
 Global RO Water Purifier Market | 2026-2036
Global RO Water Purifier Market Size, Share, and Industry Trends Forecast 2026-2036
Global RO Water Purifier Market Outlook
The gap between residential and commercial buyer archetypes is collapsing as households replace offices as the dominant volume purchasers. Kent RO Systems Ltd leverages its service-network density across Indian cities to sustain replacement-filter revenue streams. A.O. Smith Corporation anchors its position through in-house membrane manufacturing that controls input costs and quality consistency. Eureka Forbes Ltd competes via direct-to-home sales channels that bypass traditional retail markups.
A reverse osmosis water purifier forces untreated water through a semipermeable polyamide thin-film composite membrane at pressures of 40-80 psi, rejecting dissolved salts, heavy metals, and microbial contaminants to produce potable water for domestic and institutional consumption. Under-sink installations dominate value capture in mature markets where kitchen renovation cycles drive replacement demand, while countertop units lead volume growth in emerging economies with rental-heavy housing stock. Membrane filtration technology occupies the highest margin tier due to consumable replacement schedules, whereas activated carbon stages differentiate budget offerings where mineralization features command retail premiums.
The US EPA Safe Drinking Water Act and India's BIS IS 10500 standards constrain permissible contaminant levels, compelling manufacturers to certify membrane rejection rates and material safety for market access. China's SAMR enforces GB standards for water-contact materials that filter out uncertified imports from neighboring manufacturing bases. Stakeholders must monitor tightening PFAS regulations across North American and European jurisdictions, as these emerging contaminant rules will force membrane upgrades and recertification investments without guaranteed consumer willingness to absorb higher replacement costs.
Market Dynamics
Residential households in water-stressed regions are displacing commercial buyers as the dominant volume purchasers, collapsing the traditional buyer archetype gap and forcing manufacturers to reconfigure distribution networks around home installation cycles.
Growth Catalysts
- India's BIS IS 10500 Standards:Certification mandates for drinking water quality compel membrane rejection rate disclosures, accelerating certified product turnover.
- Countertop Units:Rental-heavy housing stock in emerging economies drives portable system adoption ahead of permanent fixture investment.
- PFAS Contamination Alerts:Municipal water quality deterioration across North American jurisdictions triggers preemptive household filtration purchases.
Market Restraints
- Polyamide Thin-Film Composite Supply Concentration:Membrane chemistry dependence on specialized chemical feedstock creates input cost volatility.
- China's SAMR GB Standards:Water-contact material certification requirements filter uncertified imports from neighboring manufacturing bases.
- Mineralization Stage Substitution:Activated carbon plus UV alternatives capture budget segments unwilling to absorb RO operational costs.
Strategic Opportunities
- Rural India Penetration:Direct-to-home sales channels bypass retail markups in regions with limited organized distribution.
- IoT-Enabled Predictive Maintenance:Connected membrane life monitoring converges with service-network density to lock replacement revenue.
- US EPA PFAS Rulemaking:Emerging contaminant standards create regulatory tailwind for membrane upgrade cycles without guaranteed consumer price absorption.
Industry Challenges
- Membrane Specialist Technician Scarcity:Field service capacity constraints bottleneck installation and replacement scheduling.
- Multi-Jurisdiction Recertification Timelines:BIS, GB, and EPA parallel approval processes extend product launch windows.
- Legacy Municipal Infrastructure Integration:Variable inlet pressure conditions across aging distribution systems complicate standardized product design.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global RO Water Purifier Market |
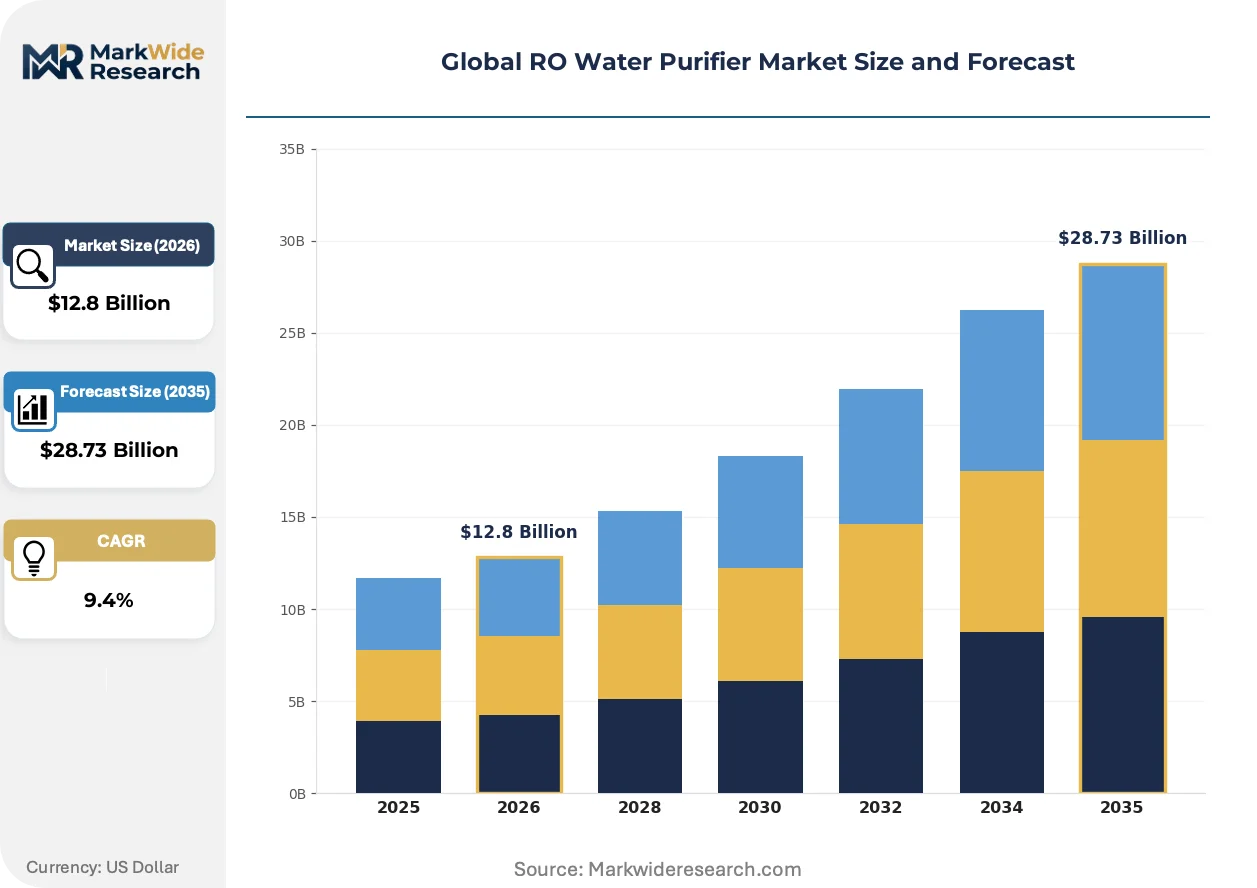
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $28.73 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Countertop, Under-Sink, Portable, Whole House End User: Residential, Commercial, Industrial, Healthcare Technology: Membrane Filtration, UV Radiation, Activated Carbon, Mineralization Distribution Channel: Online Retail, Offline Retail, Direct Sales, Distributors |
| Companies Covered | Kent RO Systems Ltd, A.O. Smith Corporation, Eureka Forbes Ltd, Coway Co., Ltd., Pentair Plc, 3M Company, LG Electronics Inc., Whirlpool Corporation, Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global RO Water Purifier Market Strategic Shifts
Membrane technology advancement and regulatory contaminant expansion are actively restructuring competitive positioning around consumable replacement schedules and certification compliance costs.
Tankless direct-flow systems are bifurcating the residential installation base. These units eliminate storage reservoir contamination risk while delivering on-demand filtration. Urban households in renovation cycles adopt them at accelerated pace. The technology is bifurcating margin capture between premium instantaneous-flow vendors and tank-based economy suppliers.
REACH PFAS restrictions across European jurisdictions are forcing membrane material reformulation. Industrial consequence includes accelerated R&D spend on alternative thin-film chemistries. Residential point-of-use systems in Germany and France face compressed certification timelines as ECHA evaluates additional substance restrictions.
Service unbundling from hardware purchase is restructuring buyer relationships. Third-party technicians and independent filter suppliers displace captive service networks in mature markets. This pattern concentrates in the United States where subscription filter delivery models bypass traditional dealer channels.
Global RO Water Purifier Market Segmentation
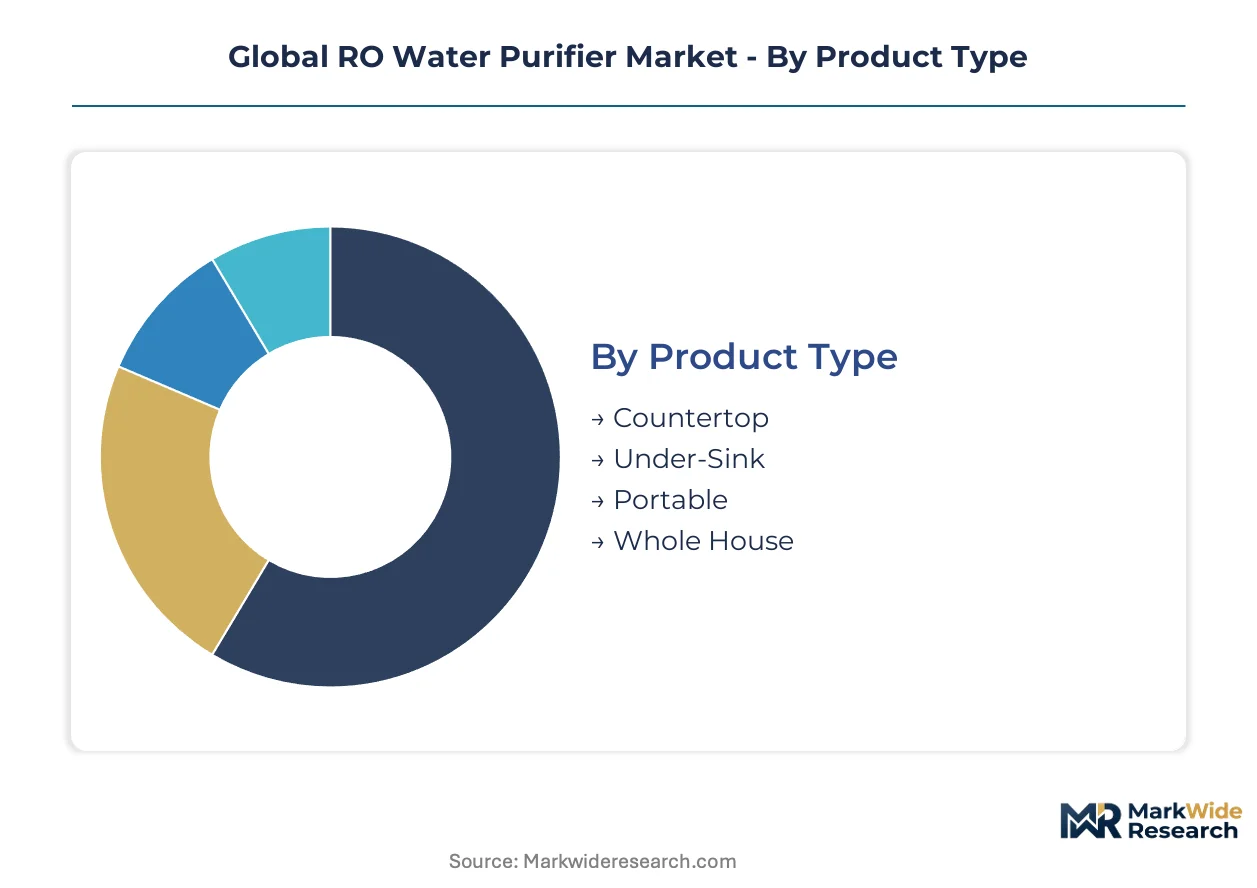
Segmentation in the RO water purifier market determines margin capture, replacement revenue cycles, and regulatory compliance burdens. Product architecture and technology choice dictate whether manufacturers compete on consumable lock-in or upfront hardware pricing. Distribution channel selection separates markets where service networks dominate from those where e-commerce disintermediation accelerates.
Product Type:
Countertop units face the most acute substitution pressure from gravity-fed and UV alternatives in price-sensitive emerging markets, while under-sink installations defend position through kitchen renovation cycle lock-in.
- Countertop:Portable units with minimal installation requirements target rental-heavy housing stock in India and China. Demand concentrates in urban apartments where permanent fixture investment is impractical. UV-plus-carbon alternatives capture budget segments unwilling to absorb RO operational costs.
- Under-Sink:Concealed installations integrate with kitchen cabinetry and plumbing infrastructure. Replacement demand in the United States tracks home renovation cycles and municipal water quality alerts. Higher upfront cost is offset by consumable replacement revenue streams.
- Portable:Battery or manually powered units serve outdoor and emergency use cases.
- Whole House:Point-of-entry systems treat all incoming water for large residential or small commercial properties.
Countertop retains volume leadership; under-sink holds the steepest expansion curve in renovation-driven mature markets.
End User:
Cost tier stratification separates residential buyers absorbing premium pricing for health assurance from commercial purchasers optimizing total cost of ownership across multi-year contracts.
- Residential:Individual households prioritize contaminant rejection rates and mineralization features. India's BIS certification mandates accelerate certified product turnover. Water-stressed regions drive replacement-filter subscription adoption.
- Commercial:Offices, restaurants, and hotels demand high-throughput systems with service-level agreements. China's GB standards for water-contact materials filter uncertified imports from neighboring manufacturing bases.
- Industrial:Manufacturing and food processing facilities require specialized pre-treatment and wastewater handling.
- Healthcare:Hospitals and clinics mandate pharmaceutical-grade water purity with redundant filtration stages.
Residential dominates absolute unit volumes; healthcare commands the highest margin per installation.
Technology:
Supply concentration in polyamide thin-film composite chemistry creates input cost volatility that reshapes competitive positioning around membrane replacement schedules.
- Membrane Filtration:Semi-permeable polyamide thin-film composite membranes operate at 40-80 psi to reject dissolved salts and heavy metals. Consumable replacement cycles generate recurring revenue. REACH PFAS restrictions across European jurisdictions force material reformulation investments.
- UV Radiation:Ultraviolet disinfection targets microbial contamination without chemical addition. Lower operational cost captures budget segments in emerging economies.
- Activated Carbon:Porous carbon stages adsorb chlorine, organic compounds, and odor.
- Mineralization:Post-RO remineralization restores beneficial calcium and magnesium for taste and health claims.
Membrane filtration anchors premium pricing; mineralization features command retail premiums in health-conscious segments.
Distribution Channel:
Customer type bifurcation separates markets where direct relationships enable service bundling from those where price transparency favors platform-based procurement.
- Online Retail:E-commerce platforms enable price comparison and subscription filter delivery. Urban India and China show accelerating adoption. Third-party technicians displace captive service networks in the United States.
- Offline Retail:Specialty stores and big-box retailers provide immediate product availability and installation referrals.
- Direct Sales:Door-to-door and telemarketing channels bypass retail markups in regions with limited organized distribution. Eureka Forbes leverages this model across Indian cities.
- Distributors:Regional wholesalers serve commercial and industrial accounts with project-based procurement.
Online retail is gaining share fastest in urban markets; direct sales defends volume leadership in rural penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ganges-Brahmaputra basin's hydrological stress and the Colorado River Basin's allocation crises frame regional demand divergence across the three dominant national markets.
United States
Municipal infrastructure decay in Flint, Michigan and Jackson, Mississippi triggers preemptive household filtration procurement. The EPA's emerging PFAS maximum contaminant levels compel membrane upgrade investments across Great Lakes manufacturing corridors. California's Central Valley agricultural communities show concentrated point-of-use system adoption where groundwater nitrate contamination exceeds federal thresholds.
India
Groundwater arsenic and fluoride contamination in the Indo-Gangetic plain accelerates rural penetration beyond tier-1 cities. BIS IS 10500 certification mandates for drinking water quality tighten product eligibility, filtering uncertified imports from Bangladesh and Nepal manufacturing bases. Gujarat's chemical belt and Maharashtra's Pune-Nashik corridor concentrate domestic membrane assembly operations serving western India distribution networks.
China
Yellow River Basin water scarcity and Yangtze Delta industrial pollution drive residential adoption in apartment-dense megacities. SAMR GB standards for water-contact materials block uncertified imports from Vietnamese and Thai assembly plants. Pearl River Delta OEM clusters around Shenzhen and Dongguan pivot toward membrane module exports as domestic market saturation intensifies price competition.
Germany
REACH PFAS restrictions and ECHA substance evaluations compress certification timelines for membrane material reformulation. The Rhine-Ruhr industrial corridor's legacy chemical contamination sustains premium point-of-entry system demand in detached housing stock. Bavaria's Munich-Stuttgart axis shows concentrated tankless direct-flow adoption linked to kitchen renovation cycles in high-income households.
Brazil
São Paulo's Cantareira reservoir stress and Rio de Janeiro's Guanabara Bay pollution elevate household health risk perception. ANVISA medical device regulations for water treatment equipment create compliance barriers for Asian import competition. The São Paulo-Minas Gerais industrial triangle concentrates domestic assembly operations serving southeast Brazil's urban concentration.
Global RO Water Purifier Market Competitive Environment
Concentration sits with diversified appliance conglomerates and specialized water treatment firms competing across membrane technology and distribution reach. The vendor base spans three tiers: integrated manufacturers controlling membrane chemistry, appliance brands leveraging retail channel density, and regional assemblers competing on price in emerging markets. Strategic moves center on service-network unbundling from hardware sales and IoT-enabled predictive maintenance subscriptions that lock replacement revenue streams.
Among India-based specialists, Kent RO Systems Ltd and Eureka Forbes Ltd occupy positions anchored by direct-to-home sales infrastructure and urban service-network density. A.O. Smith Corporation represents the integrated manufacturer archetype with captive membrane production capabilities. These three exemplify divergent competitive vectors: door-to-door penetration versus retail channel leverage versus upstream chemical process control.
| Leading Market Players |
|---|
| Kent RO Systems Ltd |
| A.O. Smith Corporation |
| Eureka Forbes Ltd |
| Coway Co., Ltd. |
| Pentair Plc |
| 3M Company |
| LG Electronics Inc. |
| Whirlpool Corporation |
| Panasonic Corporation |
| Others |
Value Chain & Pricing Dynamics
Long-term membrane supply contracts with take-or-pay clauses lock in polyamide thin-film composite access for Indian and Chinese manufacturers while freezing input cost visibility across multi-year horizons. This contract-structure pattern insulates integrated producers from spot-market volatility that squeezes regional assemblers competing on price.
Pricing Analysis
Volume-discount tiering structures stratify across certification-grade boundaries rather than simple feature bundles. BIS-certified units command 15-25% premiums over uncertified alternatives in Indian distribution channels. Pricing pressure stems from activated carbon plus UV substitutes capturing budget segments unwilling to absorb RO operational costs. Residential households in water-stressed regions show highest price sensitivity, while healthcare facilities absorb premium tiers without volume negotiation.
Supply Chain Analysis
Inbound logistics costs from Shanghai and Ningbo ports fluctuate with container availability across the Asia-Europe trade lane, compressing margins for membrane-dependent assemblers. Polyamide thin-film composite chemistry concentrates in China, Japan, and the United States. The supply chain draws from specialized chemical feedstocks including aromatic polyamides and interfacial polymerization agents. Single-source vulnerability sits with interfacial polymerization equipment suppliers. Distribution runs through captive service networks in India and direct-to-home channels that bypass retail markups.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment creates switching costs that lock replacement-filter revenue streams and extend customer lifetime value beyond hardware margins.
For Market Incumbents: Fortify membrane chemistry control through backward integration into polyamide thin-film composite production, eliminating feedstock price volatility that erodes margin consistency. Deepen service-network density in Indian tier-2 cities to preempt third-party technician displacement of captive installation channels. Counter the threat of tankless direct-flow substitutes by bundling predictive maintenance subscriptions that lock replacement revenue.
For New Entrants and Emerging Players: Rural India's direct-to-home sales infrastructure gaps present white-space entry points where organized distribution remains underdeveloped. Countertop units in Chinese rental-heavy urban apartments offer the most penetrable segment given permanent fixture investment reluctance. Pursue online retail platform partnerships with subscription filter delivery models that bypass incumbent dealer networks.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors integrated manufacturers with captive membrane production capabilities over pure-play hardware assemblers. Long-term viability centers on consumable replacement revenue visibility rather than upfront equipment sales. Monitor EPA PFAS rulemaking acceleration as the inflection signal for membrane upgrade cycle timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Membrane Chemistry | In-house polyamide thin-film composite production eliminates feedstock cost volatility from specialized chemical suppliers. |
| IoT-Enabled Predictive Maintenance Platform | Connected membrane life monitoring converges with service-network density to lock replacement revenue streams. |
| Direct-to-Home Sales Channel Expansion | Door-to-door penetration in rural India bypasses retail markups where organized distribution remains limited. |
| Multi-Jurisdiction Certification Investment | Parallel BIS, SAMR GB, and EPA approval processes extend product launch windows but filter uncertified competitors. |
| Tankless Direct-Flow Product Line Launch | Instantaneous-flow systems eliminate storage reservoir contamination risk and capture kitchen renovation cycle demand. |
Study Parameters
The analysis maps membrane filtration technology, UV radiation stages, activated carbon configurations, and mineralization features, each validated through membrane plant managers, aftermarket service heads, retail channel partners, and regulatory compliance officers. Primary interviews with these stakeholders combined with secondary validation from BIS certification registries, SAMR GB standard filings, EPA contaminant level databases, and customs trade records. Bottom-up unit shipment estimates and top-down value reconstructions triangulate across these sources.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models product architecture, technology choice, end-user type, and distribution channel segmentation dimensions. CAGRs derive from installed base growth rates, replacement cycle frequencies, and penetration curve assumptions. Industry-specific inputs include municipal water quality alert frequencies and kitchen renovation cycle timing.
Underlying assumptions cover membrane replacement schedule adherence, regulatory certification timeline stability, and logistics cost normalization, with deviation risk concentrated in PFAS rulemaking acceleration and polyamide feedstock supply disruptions. Practitioners should keep alternative scenarios live as EPA contaminant level revisions and REACH substance restrictions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water Treatment Systems
Indonesia Gravity-Based Water Purifier Market
Water Treatment Systems
Europe Water Purifier Market
Water Treatment Systems
Wastewater Recovery Systems Market
Water Treatment Systems
Water Purification Tablets Market
Water Treatment Systems
South America Residential Water Treatment Equipment Market
Water Treatment Systems
Solar Aerators Market
Water Treatment Systems
Global Residential Water Treatment Devices Market
Water Treatment Systems
Africa Zero Liquid Discharge System Market
Water Treatment Systems
Water Ionizers Market
Water Treatment Systems
Self-Cleaning Filters Market
Water Treatment Systems
Point of Entry Water Treatment Systems Market
Water Treatment Systems
Point of Use Water Treatment Systems Market
Water Treatment Systems
Shower Water Filters Market
Water Treatment Systems
Global Solar Water Desalination Plants Market
Water Treatment Systems
Commercial Water Filter Market
Water Treatment Systems
Water Treatment As a Service Market