
 Global Microbiological Testing of Water Market | 2026-2036
Global Microbiological Testing of Water Market Size, Share, and Industry Trends Forecast 2026-2036
Global Microbiological Testing of Water Market Outlook
Market Context
The gap between reference-laboratory precision and point-of-use speed is realigning procurement patterns across the water testing value chain. Thermo Fisher Scientific leverages its chromatography-mass spectrometry portfolio to dominate high-complexity environmental monitoring contracts in North America and Europe. Danaher Corporation anchors its position through Beckman Coulter's automated microbial identification systems, while IDEXX Laboratories specializes in coliform and E. coli test kits for municipal compliance workflows.
Technical Definition and Segment Structure
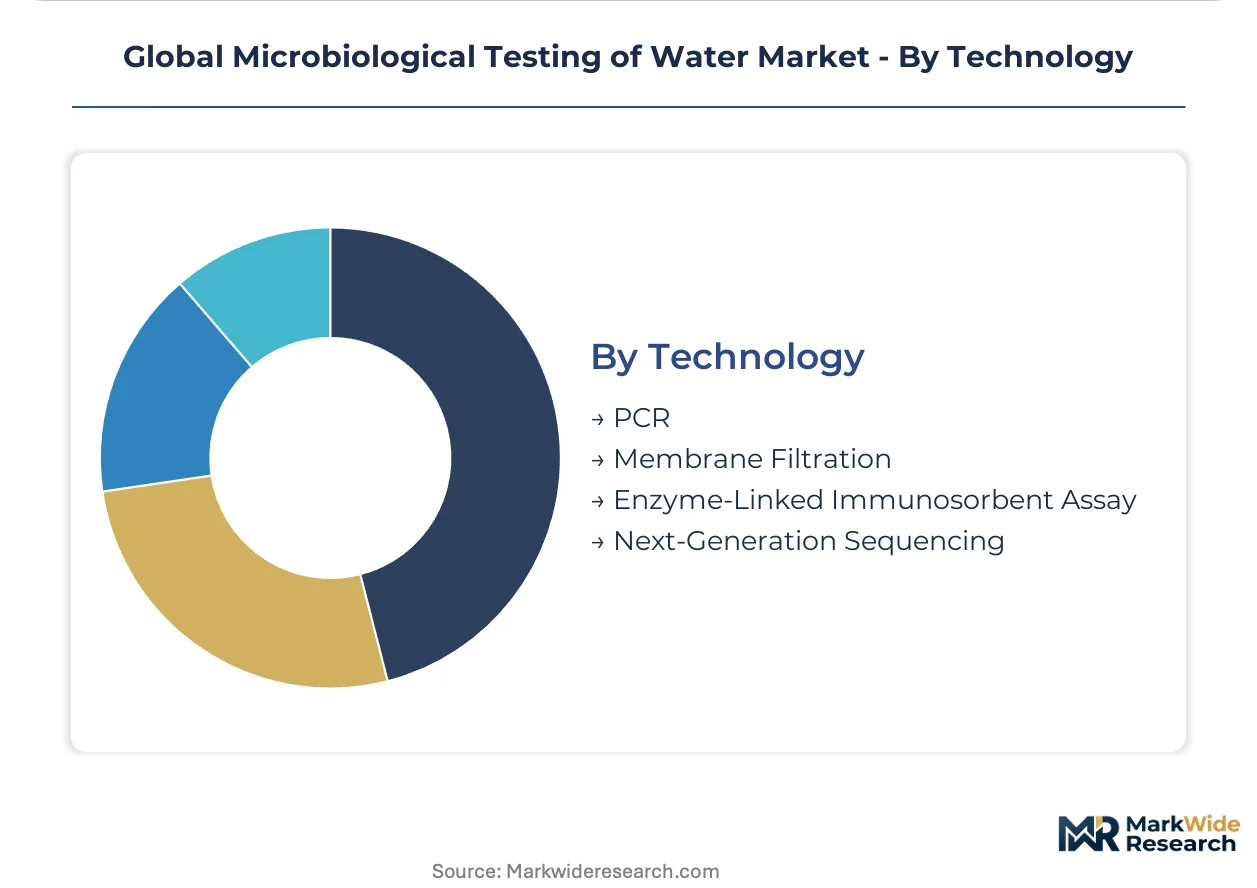
Microbiological testing of water encompasses the detection, enumeration, and identification of bacteria, viruses, protozoa, and other microorganisms in aqueous matrices using culture-based, molecular, or immunological methods with detection thresholds typically ranging from 1 CFU per 100 mL for drinking water to 10^4 CFU/mL for industrial cooling systems. The primary commercial purpose is to verify compliance with health-based standards, prevent waterborne disease outbreaks, and protect industrial process integrity. PCR technology captures premium margins in outbreak investigation and emerging pathogen surveillance, while membrane filtration sustains volume leadership in routine coliform monitoring for municipal laboratories. Test kits and reagents represent the fastest-expanding product category as decentralized testing expands beyond centralized reference labs.
Regulatory Framework and Outlook
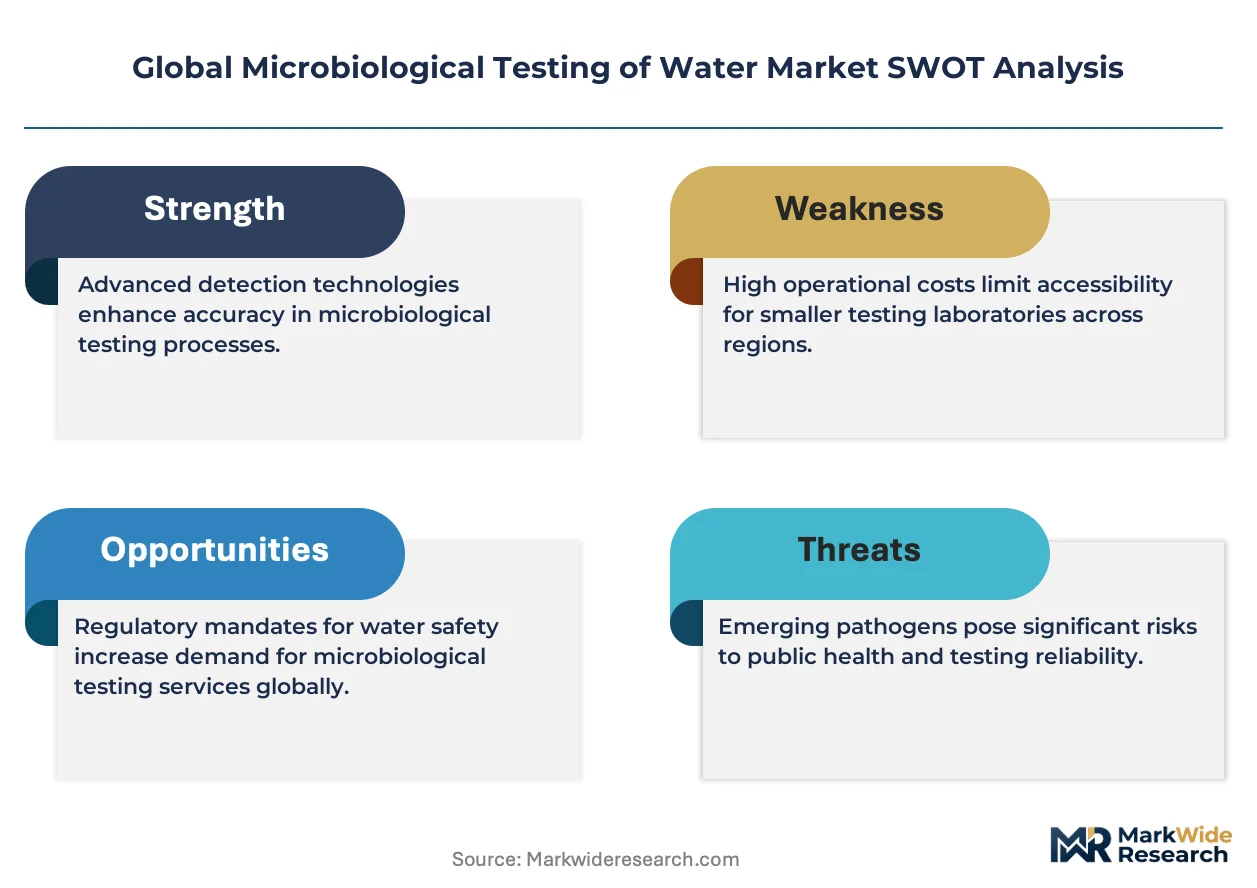
The U.S. EPA's Revised Total Coliform Rule and the EU Drinking Water Directive, enforced by national environmental agencies under ECHA coordination, mandate continuous monitoring frequencies that directly determine instrument replacement cycles and consumable demand. China's MEE enforces GB standards for drinking water quality that increasingly incorporate qPCR methods for Cryptosporidium and Giardia detection. Stakeholders must monitor how regulatory divergence between rapid molecular methods and traditional culture-based standards reshapes capital allocation across laboratory and field-deployable platforms.
Market Dynamics
The transition from culture-based methods to rapid molecular diagnostics is compressing test turnaround times from days to hours, forcing municipal laboratories and industrial facilities to rebalance capital budgets between centralized reference labs and decentralized field-deployable platforms.
Growth Catalysts
- EPA Revised Total Coliform Rule:The mandate for enhanced monitoring frequency and public notification protocols drives replacement cycles for automated enumeration systems in US municipal utilities.
- Industrial cooling water surveillance:Power generation and petrochemical facilities face escalating Legionella liability exposure, accelerating adoption of on-site qPCR screening for cooling tower discharge compliance.
- China's GB standard evolution:The Ministry of Ecology and Environment's integration of molecular methods for protozoan detection into drinking water quality standards expands the addressable market for nucleic acid extraction platforms.
Market Restraints
- Reagent supply concentration:Specialty polymerases and fluorescent probe chemistries for qPCR workflows depend on concentrated production in select manufacturing hubs, exposing test kit assemblers to input volatility.
- Culture-to-molecular regulatory lag:The EPA and EU Drinking Water Directive maintain method approval frameworks that privilege established plate-count techniques, delaying full substitution for compliance reporting.
- Skilled technician scarcity:Molecular diagnostics workflows require nucleic acid handling competencies that outpace training pipeline output in smaller municipal laboratory systems.
Strategic Opportunities
- India's urban water infrastructure:The Jal Jeevan Mission's rural piped water expansion creates demand for portable coliform detection kits suited to resource-constrained field conditions.
- ISO 13843 validation frameworks:International standardization of molecular method equivalence testing opens pathways for PCR-based kits to achieve regulatory parity with culture references.
- Building management system integration:Smart sensor networks for Legionella risk monitoring in hospitality and healthcare facilities converge IoT connectivity with automated sampling modules.
Industry Challenges
- Proficiency testing harmonization:Laboratories operating across multiple jurisdictions face divergent external quality assessment requirements from EPA, ECHA-coordinated national agencies, and China's MEE.
- Legacy LIMS integration:Automated microbial identification systems must interface with entrenched laboratory information management architectures that lack native API support for molecular data formats.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Microbiological Testing of Water Market |
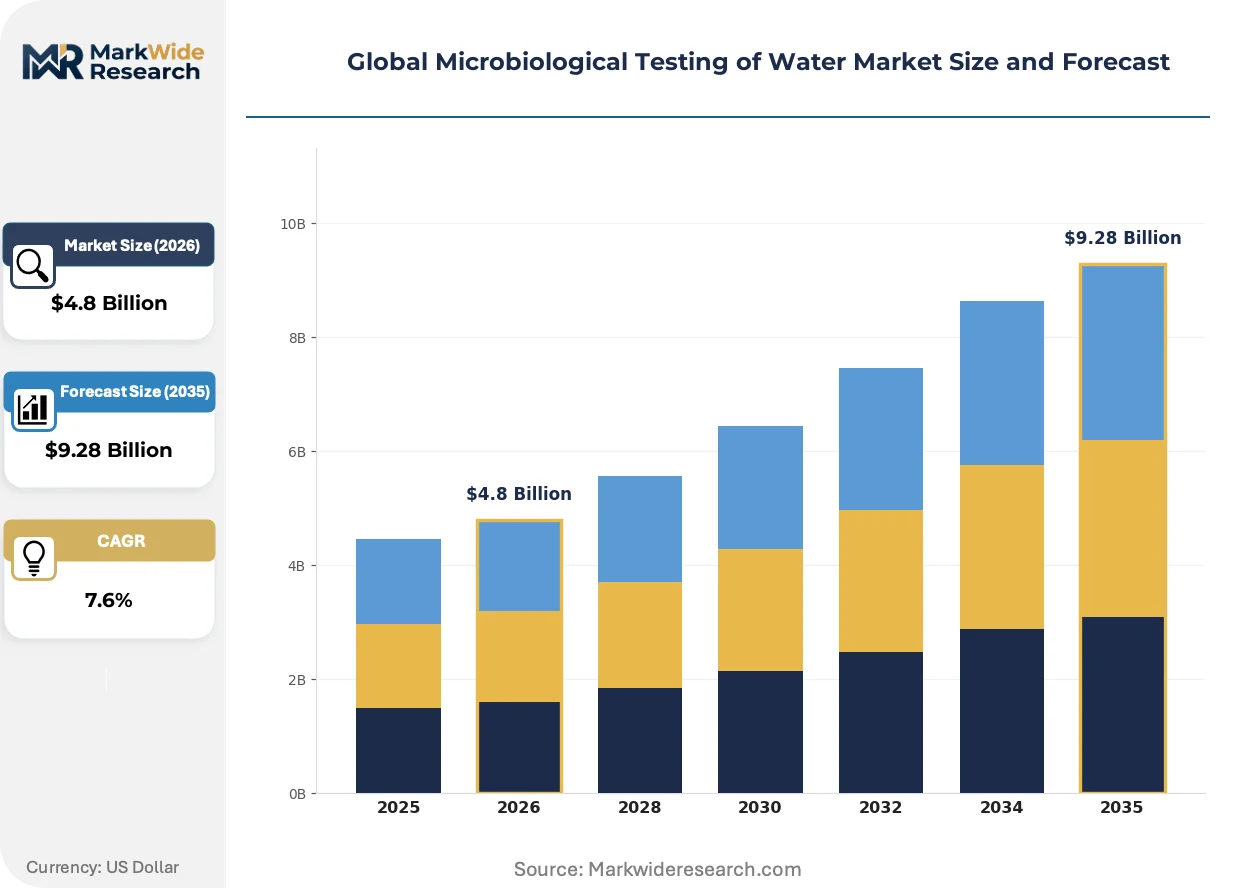
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $9.28 Billion |
| CAGR (2026 – 2036) | 7.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Culture Media, Test Kits, Reagents, Sensors Application: Drinking Water, Wastewater Management, Industrial Testing, Environmental Monitoring End User: Municipalities, Environmental Agencies, Industrial Facilities, Research Laboratories Technology: PCR, Membrane Filtration, Enzyme-Linked Immunosorbent Assay, Next-Generation Sequencing |
| Companies Covered | Thermo Fisher Scientific Inc., Danaher Corporation, 3M, Agilent Technologies Inc., IDEXX Laboratories Inc., Bio-Rad Laboratories Inc., PerkinElmer Inc., Merck KGaA, Shimadzu Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Microbiological Testing of Water Market Strategic Shifts
Digital PCR platforms are crossing from research into applied environmental monitoring, while regulatory method equivalency frameworks struggle to keep pace with technological capability gains. These developments are restructuring competitive advantage around assay sensitivity and data integrity rather than throughput scale alone.
Isothermal amplification methods, particularly LAMP chemistry, are expanding into field-deployable water screening applications where thermocycler infrastructure proves impractical. Rural utilities in Australia and distributed industrial facilities in Canada are adopting these platforms for same-shift pathogen detection. The technology is compressing the viable market for centralized reference laboratory testing of routine compliance samples.
The EU Drinking Water Directive's 2021 recast mandates risk-based monitoring plans and digital reporting infrastructure, compelling member state laboratories to upgrade data management capabilities. Germany's Federal Environment Agency and France's health inspectorate are enforcing tightened Cryptosporidium surveillance that favors continuous monitoring over grab-sample analysis. Membrane filtration equipment suppliers are responding with automated sample concentration modules that feed directly into molecular detection workflows.
Buying committees at North American municipal utilities are unbundling reagent supply contracts from instrument purchase agreements, fragmenting vendor lock-in patterns that historically bundled multi-year consumable commitments with capital equipment. This behavior is most pronounced in states with centralized procurement oversight such as California and Texas, where cooperative purchasing agreements enable smaller utilities to access pricing terms previously reserved for large metropolitan systems.
Global Microbiological Testing of Water Market Segmentation
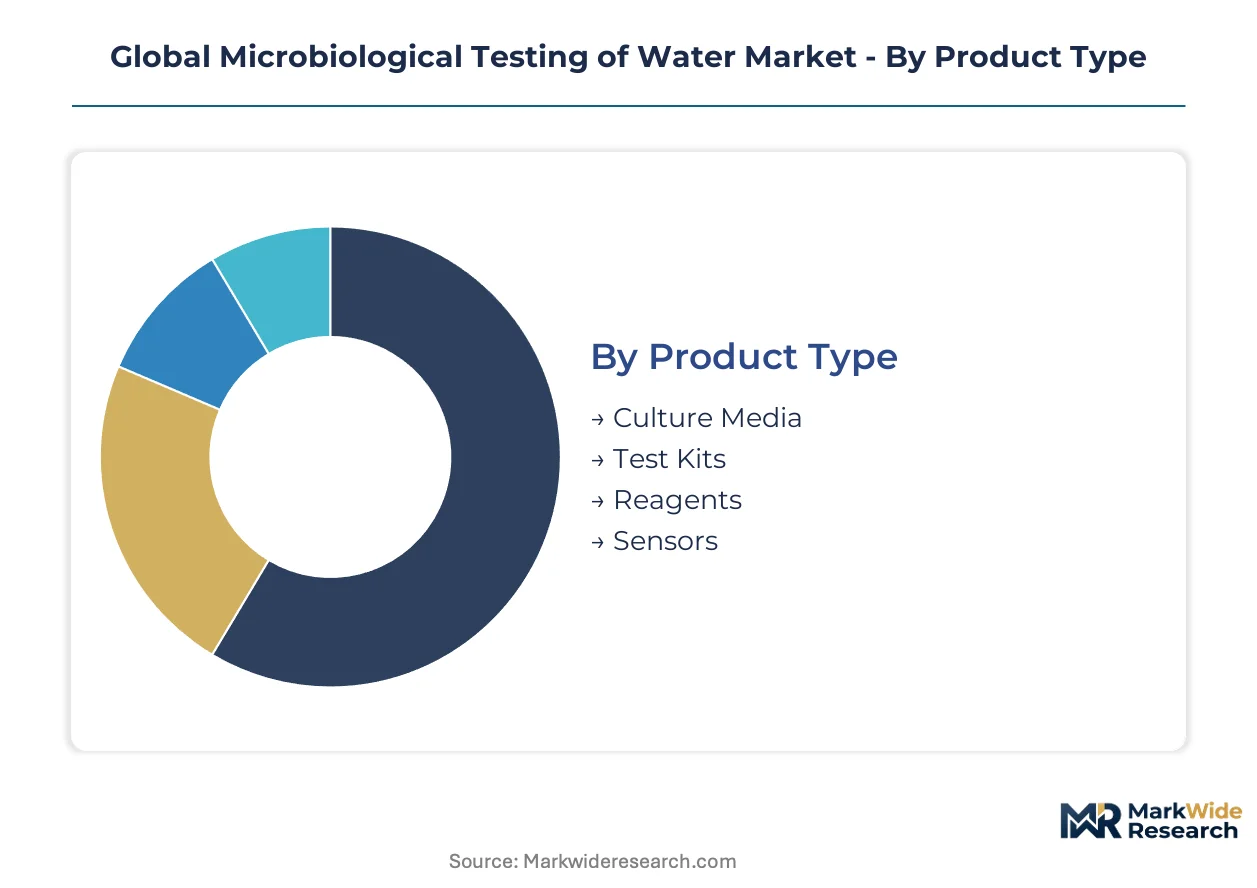
Segmentation in microbiological water testing reveals how regulatory complexity fragments procurement patterns across laboratories with divergent technical capabilities and compliance burdens. Each dimension—product, application, end user, and technology—carries distinct certification requirements that shape vendor selection criteria and replacement cycle timing.
Product Type:
Certification burdens vary sharply across this category: ISO 13843 validation governs molecular reagents in Europe, while EPA-approved methods constrain test kit formulations for US municipal compliance workflows.
- Test Kits:Pre-formulated coliform and Legionella detection systems packaged for field deployment or laboratory bench use. Demand concentrates in US municipal utilities modernizing under the Revised Total Coliform Rule, where standardized enzymatic substrates reduce technician training requirements and accelerate result turnaround.
- Reagents:Specialty polymerases, fluorescent probes, and nucleic acid extraction chemistries enabling qPCR and digital PCR workflows. German environmental laboratories and China's MEE-certified facilities drive premium consumption as GB standards and EU Drinking Water Directive recasts mandate molecular method adoption for protozoan surveillance.
- Culture Media:Dehydrated and prepared formulations supporting traditional plate-count enumeration for regulatory compliance reporting.
- Sensors:Automated optical and electrochemical detection modules integrated into continuous monitoring infrastructure for distribution network surveillance.
Leading the category by volume: Culture Media. Growing fastest: Reagents.
Application:
Cost tier segmentation separates capital-intensive continuous monitoring installations from discrete sampling workflows, with industrial facilities bearing the highest per-test cost burden due to liability-driven testing frequency.
- Drinking Water:Compliance verification for potable water treatment and distribution systems against EPA, EU Drinking Water Directive, and China's GB standards. US municipal utilities and German water associations anchor volume demand through mandated coliform, E. coli, and Cryptosporidium surveillance programs.
- Industrial Testing:Cooling tower discharge monitoring, process water validation, and Legionella risk management in power generation and petrochemical facilities. North American industrial clusters face escalating liability exposure that accelerates on-site qPCR adoption for same-shift pathogen screening.
- Wastewater Management:Effluent quality verification and reuse suitability assessment for discharge permitting and environmental protection.
- Environmental Monitoring:Surface water, groundwater, and recreational water quality surveillance for ecological protection and public health notification.
Highest capital intensity: Industrial Testing. Steepest expansion trajectory: Drinking Water.
End User:
Customer type determines procurement scale and technical sophistication, with municipalities representing the most price-sensitive volume buyers and research laboratories driving premium technology adoption.
- Municipalities:Public water utilities managing treatment and distribution infrastructure under national regulatory frameworks. Demand clusters in California and Texas cooperative purchasing agreements, where centralized procurement oversight fragments traditional vendor lock-in patterns and enables smaller utilities to access metropolitan-scale pricing.
- Industrial Facilities:Power generation, petrochemical, food and beverage, and pharmaceutical manufacturing operations with process-critical water quality requirements. Cooling tower operators in North America and distributed industrial sites in Canada adopt isothermal amplification platforms where thermocycler infrastructure proves impractical.
- Environmental Agencies:National and sub-national regulatory bodies conducting surveillance, enforcement, and standard-setting activities.
- Research Laboratories:Academic and government research institutions developing and validating emerging detection methodologies.
Dominant procurement volume: Municipalities. Technology leadership: Research Laboratories.
Technology:
Maturity gradients separate established culture-based methods with full regulatory recognition from rapid molecular platforms awaiting method equivalency approval.
- PCR:Thermocycler-based nucleic acid amplification enabling quantitative pathogen detection with high sensitivity and specificity. China's MEE-certified laboratories and Germany's Federal Environment Agency drive platform adoption as GB standards and EU directives integrate qPCR for Cryptosporidium and Giardia detection.
- Membrane Filtration:Physical separation and culture-based enumeration of microorganisms on selective media. Sustains volume leadership in routine coliform monitoring for municipal laboratories where regulatory frameworks privilege established plate-count techniques for compliance reporting.
- Enzyme-Linked Immunosorbent Assay:Antibody-based detection systems for rapid screening applications with moderate sensitivity requirements.
- Next-Generation Sequencing:Untargeted metagenomic analysis enabling comprehensive microbial community characterization and emerging pathogen discovery.
Widest regulatory recognition: Membrane Filtration. Gaining share fastest: PCR.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Houston Ship Channel petrochemical corridor drives North American demand for Legionella monitoring in industrial cooling systems. German water technology clusters and China's Yangtze River Delta manufacturing belt concentrate procurement of nucleic acid extraction platforms. India's Jal Jeevan Mission and Australia's distributed rural utilities create parallel demand vectors for portable field-deployable systems.
United States
California's Central Valley Water Quality Control Board and Texas Commission on Environmental Quality enforce the EPA's Revised Total Coliform Rule through cooperative purchasing agreements that fragment vendor lock-in. Municipal utilities across the Great Lakes region replace automated enumeration systems on accelerated cycles. The Research Triangle Park biotechnology corridor in North Carolina anchors private laboratory demand for high-complexity chromatography-mass spectrometry contracts.
Germany
The Federal Environment Agency mandates qPCR-based Cryptosporidium surveillance in drinking water distribution networks. Bavarian municipal associations and North Rhine-Westphalia's industrial water users drive premium consumption of nucleic acid extraction chemistries. Berlin-Brandenburg's environmental laboratory network validates molecular method equivalency under ISO 13843 frameworks.
China
MEE-certified facilities in Shanghai and Jiangsu province integrate qPCR methods for protozoan detection under evolving GB standards. The Pearl River Delta's electronics manufacturing clusters demand process water validation at detection thresholds below 1 CFU per 100 mL. Beijing's municipal water authority pilots continuous monitoring sensor networks for distribution network surveillance.
India
The Jal Jeevan Mission's rural piped water expansion creates demand for portable coliform detection kits in Maharashtra and Gujarat. State pollution control boards in Karnataka and Tamil Nadu enforce tightened effluent quality standards for textile and pharmaceutical discharge. The Delhi-NCR urban agglomeration faces groundwater contamination surveillance mandates that outpace laboratory capacity.
Australia
Rural utilities in Queensland and Western Australia adopt isothermal amplification platforms where thermocycler infrastructure proves impractical. Sydney Water's metropolitan network and Melbourne's catchment management authorities enforce risk-based monitoring plans under national drinking water guidelines. The Murray-Darling Basin's agricultural water reuse programs drive demand for rapid field-deployable pathogen screening.
Global Microbiological Testing of Water Market Competitive Environment
Capital-heavy producers compete with asset-light designers across the microbiological testing value chain. The market structure consolidates around three tiers: multinational analytical instrument conglomerates, specialized molecular diagnostics firms, and regional test kit assemblers. Strategic archetypes include chromatography-mass spectrometry platform providers, automated microbial identification system vendors, and field-deployable rapid assay specialists. Dominant competitive moves encompass unbundling reagent supply contracts from instrument purchase agreements and establishing method equivalency validation partnerships with national reference laboratories.
Among diversified analytical conglomerates, Thermo Fisher Scientific Inc. and Danaher Corporation occupy positions spanning high-complexity environmental monitoring and automated microbial identification. IDEXX Laboratories Inc. exemplifies the specialized diagnostics archetype with concentrated exposure to municipal compliance workflows. These three entities anchor competitive dynamics around technology platform breadth versus application-specific depth, with procurement pattern fragmentation in North American cooperative purchasing agreements eroding traditional multi-year consumable bundling arrangements.
| Leading Market Players |
|---|
| Thermo Fisher Scientific Inc. |
| Danaher Corporation |
| 3M |
| Agilent Technologies Inc. |
| IDEXX Laboratories Inc. |
| Bio-Rad Laboratories Inc. |
| PerkinElmer Inc. |
| Merck KGaA |
| Shimadzu Corporation |
| Others |
Value Chain & Pricing Dynamics
North American municipal cooperative purchasing programs concentrate procurement volume among price-sensitive public utilities, forcing vendors toward unbundled reagent supply contracts and competitive tender-based pricing models that erode traditional multi-year consumable bundling arrangements.
Pricing Analysis
Outcome-based pricing anchors premium tiers, with qPCR platform vendors tying contract value to detection sensitivity thresholds and regulatory compliance assurance rather than instrument throughput alone. Three-tier pricing structure across premium, standard, and economy levels separates ISO 13843-validated molecular reagents from EPA-approved test kits and basic culture media formulations. Cost compression in standard-grade consumables is intensifying because cooperative purchasing agreements enable smaller utilities to access metropolitan-scale pricing. Municipal laboratories exhibit the highest price sensitivity, while pharmaceutical manufacturing facilities accept premium positioning for process-critical validation.
Supply Chain Analysis
Specialized polymerase chemist shortages in Massachusetts and North Carolina constrain nucleic acid extraction platform manufacturing, while Bavaria and Shanghai maintain concentrated production of fluorescent probe reagents. Specialty polymerases, magnetic bead chemistries, and optical sensor components draw from concentrated manufacturing hubs in Germany, China, and the United States. Single-source vulnerability in fluorescent probe synthesis exposes kit assemblers to input volatility during regulatory inspection cycles. Distribution runs through authorized distributor networks serving municipal procurement offices and direct sales teams for industrial accounts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from regulatory method equivalency validation costs will force smaller test kit assemblers toward acquisition or exit, concentrating competitive position among platform providers with captive reference laboratory partnerships.
For Market Incumbents: Hedge against reagent unbundling by securing ISO 13843 validation partnerships with Germany's Federal Environment Agency and China's MEE-certified reference networks. Backward integration into specialty polymerase production reduces exposure to supply concentration in Massachusetts and Bavaria. Prioritize API-enabled LIMS integration to defend instrument replacement cycles against cloud-native entrants.
For New Entrants and Emerging Players: Enter via portable isothermal amplification platforms targeting India's Jal Jeevan Mission field deployment requirements in Maharashtra and Gujarat. Rural piped water expansion creates the most penetrable demand vector, with state pollution control board procurement channels offering direct access bypassing entrenched municipal cooperative agreements.
For Investors and Strategic Acquirers: The window for entry favors specialized molecular diagnostics firms with validated qPCR workflows for Cryptosporidium surveillance. Long-term viability centers on regulatory method equivalency achievement rather than throughput scale alone. Watch for EPA approval of digital PCR methods as the inflection signal accelerating substitution of culture-based compliance reporting.
| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Method Equivalency Partnership | ISO 13843 validation with Germany's Federal Environment Agency unlocks premium reagent positioning in EU markets. |
| Backward Integration into Polymerase Production | In-house production of specialty enzymes reduces supply vulnerability from concentrated Massachusetts manufacturing hubs. |
| API-Enabled LIMS Integration | Native connectivity with entrenched laboratory information systems defends instrument replacement cycles against cloud-native competitors. |
| Portable Isothermal Amplification Platform Launch | LAMP chemistry field deployment targets India's Jal Jeevan Mission procurement outside municipal cooperative structures. |
| Continuous Monitoring Sensor Network Deployment | Automated optical detection modules feed directly into China's MEE-mandated distribution network surveillance pilots. |
Study Parameters
EPA enforcement databases, EU Drinking Water Directive implementation reports, and China's MEE certification records formed the secondary backbone, cross-referenced with primary interviews of municipal laboratory directors, industrial water quality managers, and reagent procurement officers at German environmental agencies. Bottom-up and top-down triangulation validated segment-level estimates against instrument shipment data and consumable production volumes reported in customs records.
Bottom-up modeling anchored forecasts, with top-down macro validation against water infrastructure investment pipelines. Segmentation dimensions included product type, application vertical, end-user procurement scale, and technology maturity tier across the projection horizon. CAGRs derived from replacement cycle timing under EPA and EU regulatory mandates, calibrated against qPCR platform adoption curves in China and isothermal amplification penetration in distributed industrial facilities.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged EPA method approval delays or abrupt reagent supply disruptions. Forecasts reflect documented assumptions regarding regulatory divergence timelines and training pipeline expansion rates. Material deviation in EPA digital PCR equivalency rulings or China's GB standard revision pace warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water and Wastewater Treatment
Global Vertical Sewage Pumps Market
Water and Wastewater Treatment
Global Enhanced Water Market
Water and Wastewater Treatment
Electrocoagulation Market
Water and Wastewater Treatment
Global SCADA in Water and Wastewater Management Market
Water and Wastewater Treatment
China Water and Wastewater Treatment (WWT) Technology Market
Water and Wastewater Treatment
US Wastewater Secondary Treatment Equipment Market
Water and Wastewater Treatment
Mobile Wastewater Treatment Plant Market
Water and Wastewater Treatment
Sewage Treatment Service Market
Water and Wastewater Treatment
Global Biological Wastewater Treatment Market
Water and Wastewater Treatment
Global Wastewater Treatment Services Market
Water and Wastewater Treatment
Tertiary Water and Wastewater Treatment Equipment Market
Water and Wastewater Treatment
Ecological Wastewater Treatment Market
Water and Wastewater Treatment
Borehole Yield Testing Market
Water and Wastewater Treatment
Global Water Recycle and Reuse Market
Water and Wastewater Treatment
Sewage Pump Market
Water and Wastewater Treatment
Javelle Water Market