
 Solar Powered Sanitation Device Market | 2026-2036
Solar Powered Sanitation Device Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Powered Sanitation Device Market Outlook
India's manufacturing corridor for solar-integrated sanitation hardware is tilting toward export-oriented capacity. Ecoppia leverages its robotics heritage to automate panel-cleaning subsystems within larger sanitation stations. Karcher anchors European demand through its pressure-washing technology adapted for solar-powered water recycling. Aegeus Technologies specializes in ruggedized controllers that manage power draw across variable solar input conditions.
Solar powered sanitation devices combine photovoltaic arrays with electromechanical waste processing, UV sterilization chambers, and battery-buffered water pumps to deliver hygienic facilities without grid connection. Fixed units dominate current deployment volumes due to their structural integration with permanent infrastructure, while waste processing stations represent the fastest-expanding segment as municipalities seek closed-loop sanitation in water-scarce regions. Portable toilets retain the largest installed base but carry thinner margins owing to commoditized solar panel sourcing.
India's BIS mandates water-efficiency certification for off-grid sanitation products, while the EU Green Deal's circular economy requirements shape material recovery specifications for units sold across Europe. Kenya's energy regulator enforces solar import standards that filter substandard battery systems from entering the East African supply chain. Stakeholders must track how national renewable-energy procurement rules redirect subsidy flows between residential and commercial installation categories.
Market Dynamics
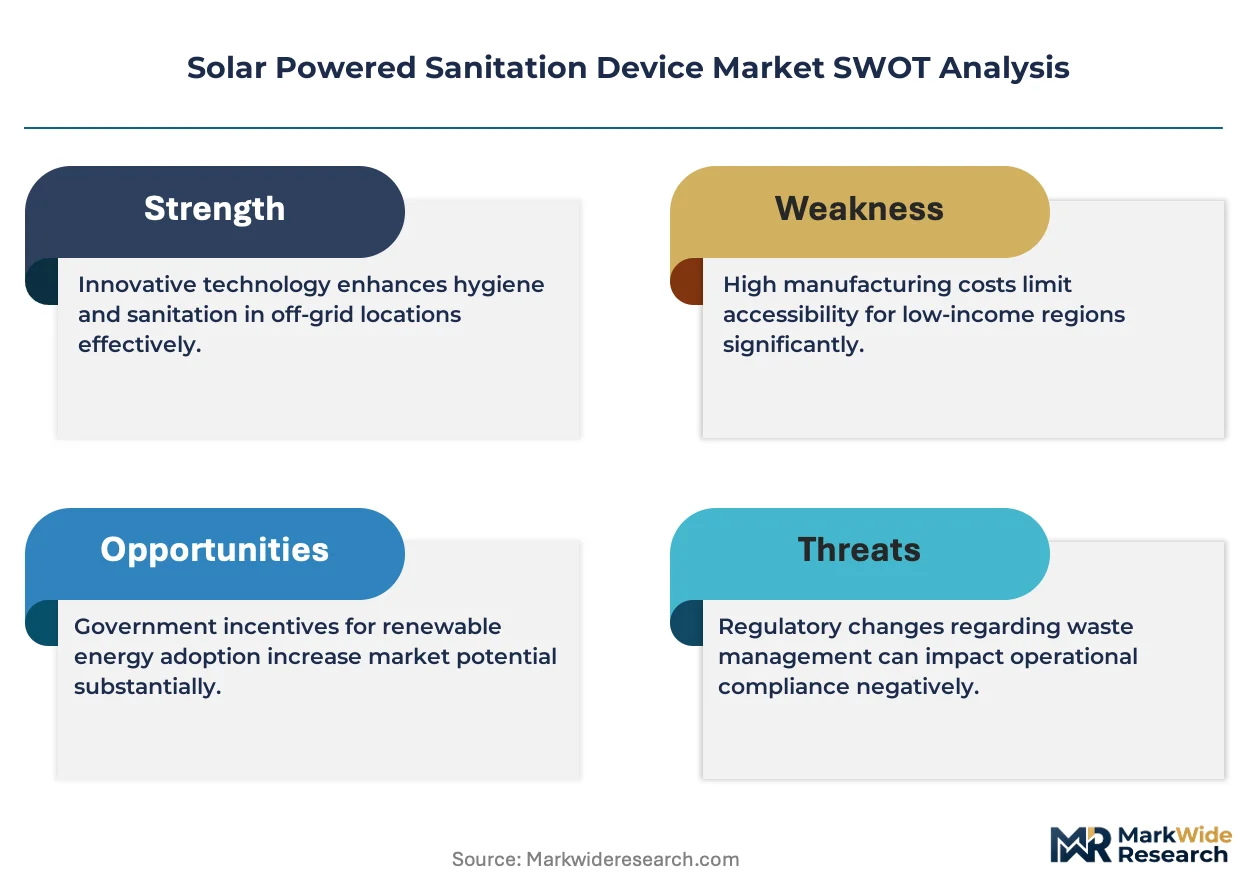
Water-efficiency mandates from India's BIS are forcing rapid product redesign cycles across the solar sanitation hardware sector, compressing development timelines while elevating technical certification barriers for market entry.
Growth Catalysts
- Arid-Zone Infrastructure Gaps:Kenya's northern counties face diesel fuel access constraints that create immediate demand pull for solar-powered alternatives in off-grid construction and municipal settings.
- BIS Water-Efficiency Mandates:India's tightened certification requirements for off-grid sanitation hardware are accelerating innovation in low-flow electromechanical processing systems.
- Photovoltaic Cost Curves:Commoditized solar panel sourcing is enabling margin expansion for waste processing stations while pressuring portable toilet manufacturers to differentiate through subsystem integration.
Market Restraints
- Battery Import Standards:Kenya's energy regulator filters substandard lithium storage systems from East African supply chains, creating procurement bottlenecks for manufacturers lacking certified supplier relationships.
- UV Chamber Material Costs:Stainless steel and specialized quartz glass for sterilization chambers face price volatility tied to energy-intensive production inputs.
- Grid-Extension Substitution:Rural electrification programs in select Sub-Saharan markets threaten standalone solar sanitation economics where grid connection timelines accelerate unexpectedly.
Strategic Opportunities
- EU Green Deal Material Recovery:Circular economy specifications for units sold across Europe create premium positioning for manufacturers engineering closed-loop component architectures.
- Robotics-Integrated Cleaning:Automated panel-cleaning subsystems represent convergence territory between photovoltaic maintenance and sanitation station uptime optimization.
- Sub-Saharan Construction Vertical:Portable solar sanitation units targeting Kenya's infrastructure build-out offer underpenetrated deployment channels distinct from municipal procurement.
Industry Challenges
- Controller Firmware Certification:Ruggedized power management systems must validate performance across variable solar input conditions, extending validation timelines for new market entrants.
- Electromechanical-Waste Processing Integration:Synchronizing battery-buffered pumps with UV sterilization chambers demands specialized systems engineering talent scarce in traditional sanitation manufacturing bases.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Powered Sanitation Device Market |
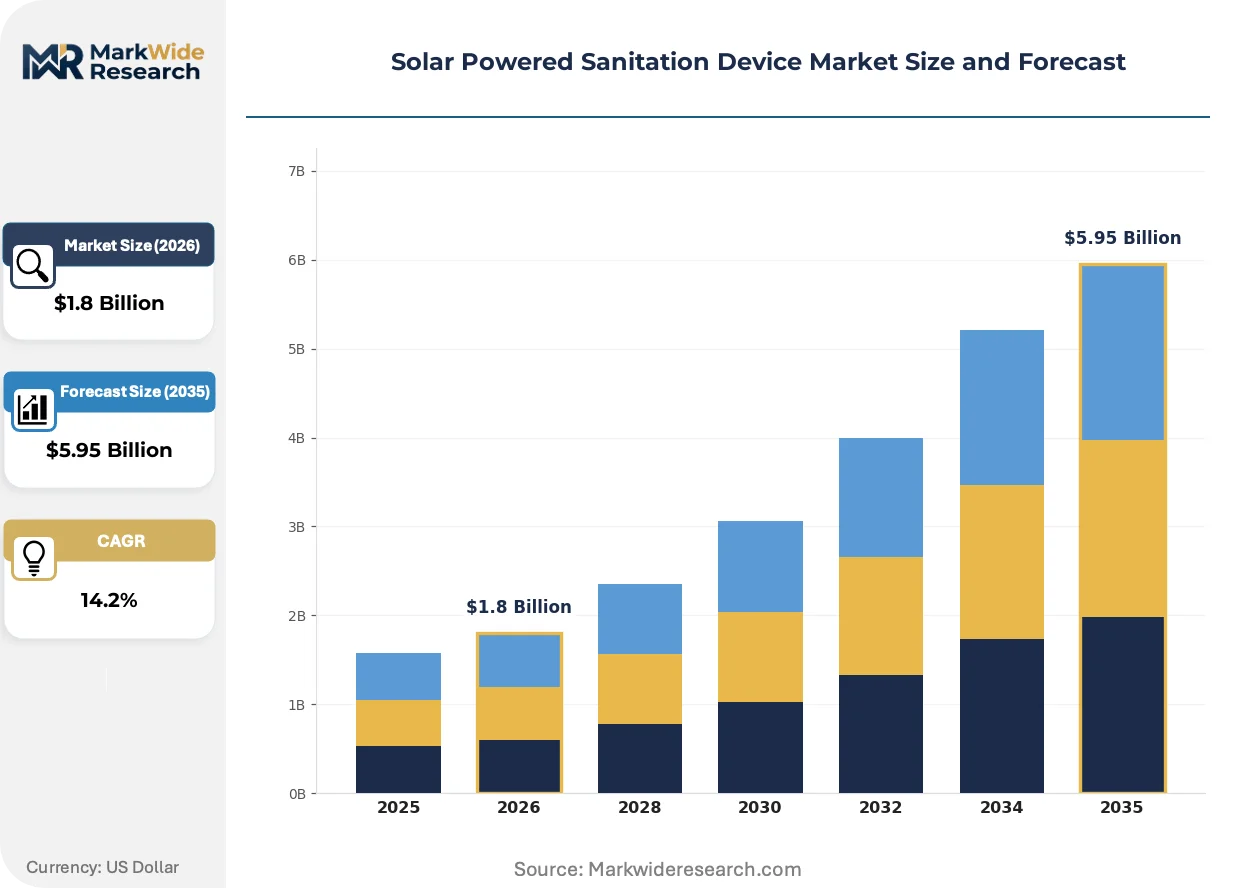
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.95 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Toilets, Fixed Units, Waste Processing Stations, Self-Cleaning Devices End User: Residential, Commercial, Government, Non-Profit Installation: Temporary, Permanent, Mobile, Stationary Application: Construction Sites, Events, Disaster Relief, Rural Areas |
| Companies Covered | Ecoppia, Karcher, BladeRanger, Boson Robotics, Aegeus Technologies, SolarCleano, Heliotex, Serbot, Clean Solar Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Powered Sanitation Device Market Strategic Shifts
Three interconnected developments are restructuring competitive positioning across solar sanitation: subsystem automation, regulatory material specifications, and procurement model compression toward equipment-as-service frameworks.
Robotic panel-cleaning technology is collapsing maintenance cost structures for fixed sanitation stations. Municipal operators in water-scarce regions are adopting automated cleaning subsystems at accelerating pace. The technology is collapsing the historical trade-off between photovoltaic output degradation and manual labor expenditure in remote deployments.
EU Green Deal circular economy requirements are reshaping material recovery specifications for sanitation hardware sold across Europe. Manufacturers must now engineer component architectures enabling end-of-life disassembly and rare earth recovery. Waste processing station categories face the steepest compliance burden, driving redesign of electromechanical housings and battery enclosure geometries.
Buyer concentration among municipal procurement authorities is compressing vendor qualification timelines. Traditional equipment sales channels are yielding to multi-year service contracts bundling hardware, maintenance, and uptime guarantees. Kenya's county-level infrastructure agencies exemplify this shift, favoring vendors offering operational responsibility over capital transfer arrangements.
Solar Powered Sanitation Device Market Segmentation
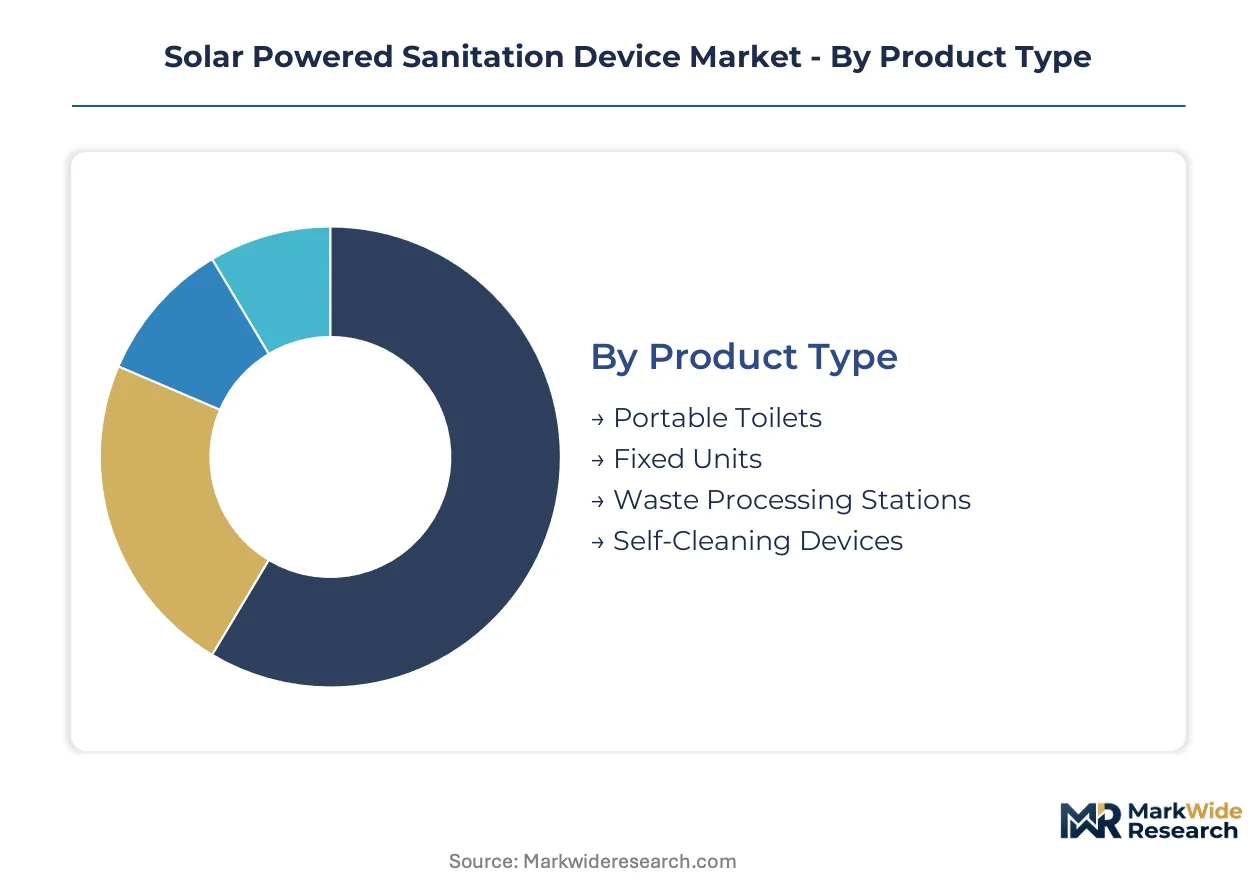
Solar powered sanitation devices serve radically different deployment contexts—from Kenya's arid construction zones to India's municipal infrastructure—making product configuration and installation flexibility decisive competitive variables. Segmentation reveals where commoditized solar hardware yields to specialized subsystem integration.
Product Type:
Maturity spreads unevenly across product categories, with established portable formats coexisting alongside emerging automated systems.
- Portable Toilets:Lightweight photovoltaic-integrated units with battery-buffered pumps and basic UV chambers dominate Kenya's northern county construction sites. Diesel fuel access constraints in these arid zones accelerate displacement of fossil-powered alternatives.
- Waste Processing Stations:Electromechanical processing systems paired with solar arrays and closed-loop water recycling deliver municipal-scale sanitation without grid connection. EU Green Deal circular economy requirements are reshaping material recovery specifications for units sold across Europe, driving redesign of component architectures.
- Fixed Units:Structural integration with permanent infrastructure supports high-capacity deployment in government facilities and commercial complexes.
- Self-Cleaning Devices:Robotic panel-cleaning subsystems automate maintenance cost reduction for fixed installations in water-scarce regions.
Portable toilets retain volume leadership; waste processing stations hold the steepest expansion curve.
End User:
Customer type determines procurement velocity and contract structure, from rapid commercial deployment to extended municipal qualification cycles.
- Government:County-level infrastructure agencies in Kenya favor multi-year service contracts bundling hardware, maintenance, and uptime guarantees over capital transfer arrangements. India's BIS water-efficiency mandates compress vendor qualification timelines while elevating technical certification barriers.
- Commercial:Construction sector procurement concentrates in Sub-Saharan Africa's off-grid build-out, where solar sanitation addresses diesel logistics failures.
- Residential:Distributed installations in rural electrification gaps face substitution risk where grid extension timelines accelerate unexpectedly.
- Non-Profit:Disaster relief deployments prioritize rapid mobilization and temporary installation flexibility over operational longevity.
Government channels dominate contract value; commercial verticals are expanding most quickly.
Installation:
Deployment duration and mobility requirements split the market between rapid-response formats and capital-intensive permanent infrastructure.
- Temporary:Rapid-deployment units serve construction timelines and event cycles without foundation requirements.
- Permanent:Foundation-anchored systems with integrated photovoltaic arrays and battery storage support continuous municipal operation.
- Mobile:Trailer-mounted configurations enable relocation across Kenya's infrastructure corridors as construction phases advance.
- Stationary:Fixed-position installations maximize structural integration and subsystem automation for waste processing stations.
Permanent installations anchor revenue stability; mobile formats gain share fastest in construction verticals.
Application:
Use-case specificity drives subsystem prioritization, from ruggedization for remote construction to rapid deployment for humanitarian response.
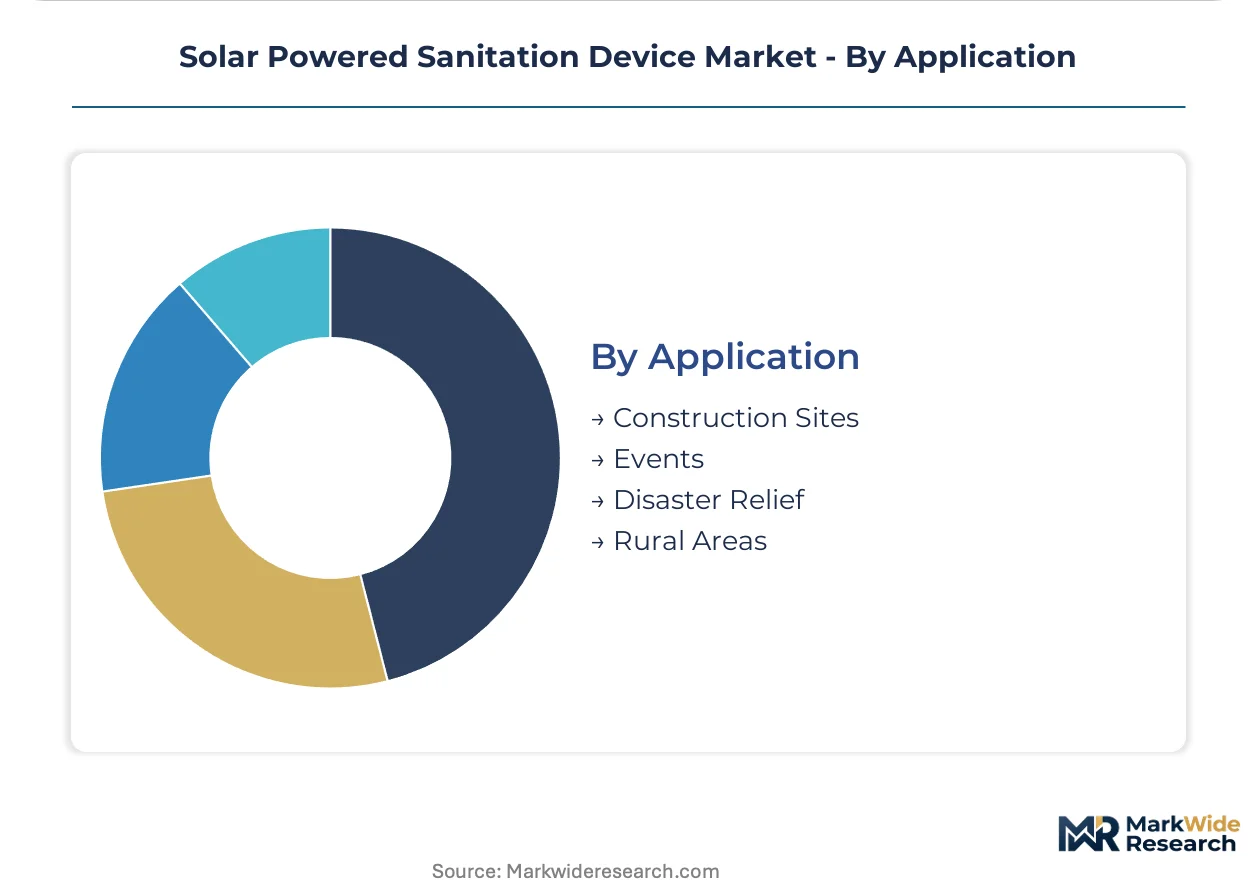
- Construction Sites:Kenya's arid northern counties generate concentrated demand for portable solar sanitation where diesel supply chains fail. Aegeus Technologies' ruggedized controllers manage power draw across variable solar input conditions critical for these deployments.
- Rural Areas:Off-grid communities in water-scarce regions require closed-loop processing and battery-buffered pumping without grid backup. India's BIS mandates accelerate innovation in low-flow electromechanical systems for these installations.
- Events:High-turnover temporary deployment favors rapid sanitation cycling and minimal maintenance overhead.
- Disaster Relief:Emergency response prioritizes immediate availability and autonomous operation independent of damaged infrastructure.
Construction applications retain the largest installed base; rural deployment shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's Bureau of Indian Standards anchors regulatory momentum for solar sanitation hardware, with water-efficiency mandates compressing product redesign cycles across multiple geographies. Kenya's northern counties and Germany's municipal procurement authorities generate concentrated demand pull from distinct infrastructure contexts.
India
BIS water-efficiency certification requirements for off-grid sanitation hardware are accelerating innovation in low-flow electromechanical processing systems. The PLI scheme for domestic manufacturing redirects subsidy flows toward export-oriented capacity expansion. Gujarat's manufacturing corridor hosts concentrated assembly operations for solar-integrated sanitation controllers and battery-buffered pumping subsystems.
Kenya
Arid northern counties face diesel fuel access constraints that create immediate substitution demand for portable solar sanitation units across construction and municipal verticals. The national energy regulator enforces solar import standards that filter substandard lithium storage systems from East African supply chains. County-level infrastructure agencies in Turkana and Marsabit favor multi-year service contracts bundling hardware, maintenance, and uptime guarantees over capital transfer arrangements.
Germany
Municipal procurement authorities prioritize closed-loop waste processing stations with circular economy-compliant material recovery architectures. EU Green Deal requirements reshape component specifications for units sold across European markets, driving redesign of electromechanical housings. Bavaria's industrial clusters concentrate engineering talent for ruggedized power management systems that validate performance across variable solar input conditions.
United States
Federal procurement guidelines for off-grid infrastructure in national parks and military installations specify autonomous sanitation with renewable power integration. EPA water-efficiency standards for temporary facilities elevate technical certification barriers for market entry. Texas and Arizona construction corridors generate demand for mobile solar sanitation units where grid extension timelines lag project schedules.
China
Dual carbon goals accelerate displacement of diesel-powered alternatives in western provinces with weak grid infrastructure. GB standards for photovoltaic system integration shape domestic product specifications that increasingly influence export markets. Yangtze River Delta manufacturing bases concentrate commoditized solar panel sourcing that enables margin expansion for integrated sanitation system assemblers.
Solar Powered Sanitation Device Market Competitive Environment
Capability concentration sits with subsystem specialists; scale advantage sits with diversified industrial equipment manufacturers. The vendor base organizes around three strategic archetypes: robotics-heritage firms automating panel-cleaning maintenance, pressure-washing technology adapters, and ruggedized controller specialists managing variable power draw. Dominant competitive moves include strategic partnerships bridging photovoltaic and sanitation engineering domains, plus geographic expansion targeting Kenya's construction corridors and India's municipal procurement channels.
Within the robotics-heritage tier, Ecoppia exemplifies automated subsystem integration, while Karcher occupies a position among European pressure-washing technology adapters. Aegeus Technologies anchors the ruggedized controller specialization segment. These three firms represent distinct capability pathways converging on solar sanitation hardware: robotic maintenance automation, industrial cleaning equipment adaptation, and power management electronics for off-grid deployment.
| Leading Market Players |
|---|
| Ecoppia |
| Karcher |
| BladeRanger |
| Boson Robotics |
| Aegeus Technologies |
| SolarCleano |
| Heliotex |
| Serbot |
| Clean Solar Solutions |
| Others |
Value Chain & Pricing Dynamics
Overcapacity in China's Yangtze River Delta photovoltaic assembly bases is compressing module pricing, enabling margin expansion for integrated sanitation system builders while forcing pure-play panel suppliers toward subsystem partnerships.
Pricing Analysis
Price spreads between German municipal procurement and Kenyan construction-site deployments exceed 40% due to EU Green Deal circular economy compliance costs and bundled service contract structures. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and after-sales bundling intensity. Cost compression in portable toilet tiers is intensifying because commoditized solar panel sourcing eliminates hardware differentiation. Government buyers in Kenya's county agencies show lowest price sensitivity due to multi-year operational responsibility contracts.
Supply Chain Analysis
Contract manufacturing for ruggedized controllers concentrates with Taiwanese EMS providers and Indian electronics manufacturing clusters in Gujarat. Battery cell supply draws from South Korean and Chinese producers, while stainless steel sterilization chamber fabrication rests on German and Italian metalworking bases. Single-source vulnerability sits with lithium iron phosphate cell suppliers facing Kenya's energy regulator import filtration. Distribution runs through municipal procurement authorities in developed markets and construction equipment rental channels in Sub-Saharan deployment zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market builds defensive moats through regulatory entrenchment: BIS water-efficiency certification and Kenya's battery import standards create multi-year qualification barriers that protect validated supplier relationships.
For Market Incumbents: Harden certification moats by accelerating BIS compliance investment ahead of India's anticipated mandate expansion. Deepen backward integration into battery-buffered pumping subsystems to offset margin pressure from commoditized photovoltaic sourcing. Threat substitution looms from grid-extension programs in select Sub-Saharan markets that could collapse standalone solar sanitation economics. For New Entrants and Emerging Players: Kenya's arid northern construction corridors offer the most penetrable white-space, with diesel logistics failures creating immediate substitution demand. Target mobile trailer-mounted configurations for infrastructure build-out phases that shift geographically. Go-to-market angle: equipment-as-service contracts bundling uptime guarantees, mirroring county-level procurement preferences already validated in Turkana and Marsabit. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across waste processing station categories as robotic panel-cleaning subsystems standardize. Long-term viability favors subsystem specialists with controller firmware and automated maintenance IP over pure hardware assemblers. Acquisition target archetype: ruggedized power management electronics firms with validated performance across variable solar input conditions. Signal to watch: BIS mandate expansion into water-efficiency tiers beyond current baselines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Battery-Buffered Pumping | Captures margin from commoditized solar panel sourcing in portable toilet tiers. |
| EU Green Deal Circular Economy Certification | Unlocks premium positioning in German municipal procurement with material recovery compliance. |
| Robotic Panel-Cleaning Subsystem Integration | Collapses maintenance cost structures for fixed waste processing stations in water-scarce regions. |
| County-Level Service Contract Bundling | Aligns with Kenya's Turkana and Marsabit infrastructure agency procurement preferences. |
| BIS Water-Efficiency Pre-Certification Investment | Accelerates vendor qualification timelines ahead of India's mandate expansion. |
Study Parameters
A standing panel of municipal procurement officers, construction project managers, solar EPC contractors, and ruggedized electronics engineers provided ongoing calibration across the study period. Primary interviews with sanitation hardware manufacturers and county-level infrastructure agencies combined with secondary validation from BIS certification databases, Kenya Energy Regulatory Commission import filings, and EU Green Deal implementation guidance. Bottom-up unit deployment estimates triangulated against top-down addressable market sizing for off-grid construction and municipal verticals.
Scenario-bracketing framed low, base, and high cases around regulatory acceleration timelines and grid-extension substitution risks across the projection horizon. Segmentation dimensions modeled include product type, end-user category, installation duration, and application context. CAGRs derived from fitted growth curves calibrated to historical deployment trajectories in comparable renewable-integrated infrastructure categories. Industry-specific inputs encompassed solar irradiance variability patterns and diesel fuel logistics failure rates in target deployment zones.
The forecast holds incumbent behavior within observed patterns; aggressive moves by Chinese photovoltaic manufacturers into integrated sanitation assembly would shift outcomes through supply-side price compression. Quarterly review of BIS mandate expansion announcements, Kenya county procurement contract awards, and EU Green Deal material specification updates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water Treatment Systems
India Desalination Systems Market
Water Treatment Systems
Residential Water Treatment Equipment Market
Water Treatment Systems
UV Water Sterilizer Market
Water Treatment Systems
Europe Water Purifier Market
Water Treatment Systems
Global RO Water Purifier Market
Water Treatment Systems
Electro-Oxidation System Market
Water Treatment Systems
US Water Purifier Market
Water Treatment Systems
Self-Cleaning Filters Market
Water Treatment Systems
Industrial Wastewater Treatment Equipment Market
Water Treatment Systems
Storm Water Cleaning Services Market
Water Treatment Systems
Wastewater Recovery Systems Market
Water Treatment Systems
Africa Zero Liquid Discharge System Market
Water Treatment Systems
Mobile Water Treatment Services Market
Water Treatment Systems
Portable Water Purifier Market
Water Treatment Systems
MENA Point of Use Water Purifiers Market
Water Treatment Systems
Global Desalination System Market