
 Home Water Softener System Market | 2026-2036
Home Water Softener System Market Size, Share, and Industry Trends Forecast 2026-2036
Home Water Softener System Market Insights
Subscription-based leasing for whole-home water softener units is narrowing the competitive field by lowering upfront capital barriers for middle-income households. Culligan International Company leverages its dealer-financing infrastructure to sustain recurring revenue streams across North American suburbs. Kinetico Incorporated anchors its position through non-electric, demand-initiated regeneration technology that reduces operating costs for rural well-water users. Pentair PLC competes via integrated filtration portfolios that bundle softeners with reverse-osmosis drinking systems.
A home water softener system is a point-of-entry treatment device that removes calcium and magnesium ions from municipal or well water through ion-exchange resin beds, typically regenerating with sodium chloride brine to prevent scale accumulation in plumbing and appliances. The primary purpose is to extend the operational lifespan of water heaters, dishwashers, and laundry equipment while improving soap and detergent efficiency in residential settings. Salt-based ion-exchange configurations still dominate installed base volumes due to proven efficacy against very hard water, though salt-free template-assisted crystallization units are gaining traction in regions with moderate hardness and sodium discharge restrictions. Dual-tank systems command premium positioning for large households with continuous water demand, as the alternating regeneration design eliminates service interruptions.
The EPA sets voluntary guidelines for drinking water quality that indirectly shape consumer awareness of hardness-related aesthetic issues, while NSF/ANSI Standard 44 certification serves as the baseline gate for product legitimacy in the United States residential channel. California's SBX7-7 water conservation mandates and local brine-discharge restrictions in Arizona and Texas are forcing manufacturers to redesign regeneration cycles for lower salt and water consumption. Stakeholders must monitor how municipal sustainability ordinances migrate from coastal states toward interior markets, as this diffusion pattern will determine which technology architectures—traditional ion exchange, salt-free conditioning, or hybrid dual-tank designs—capture incremental installation volumes.
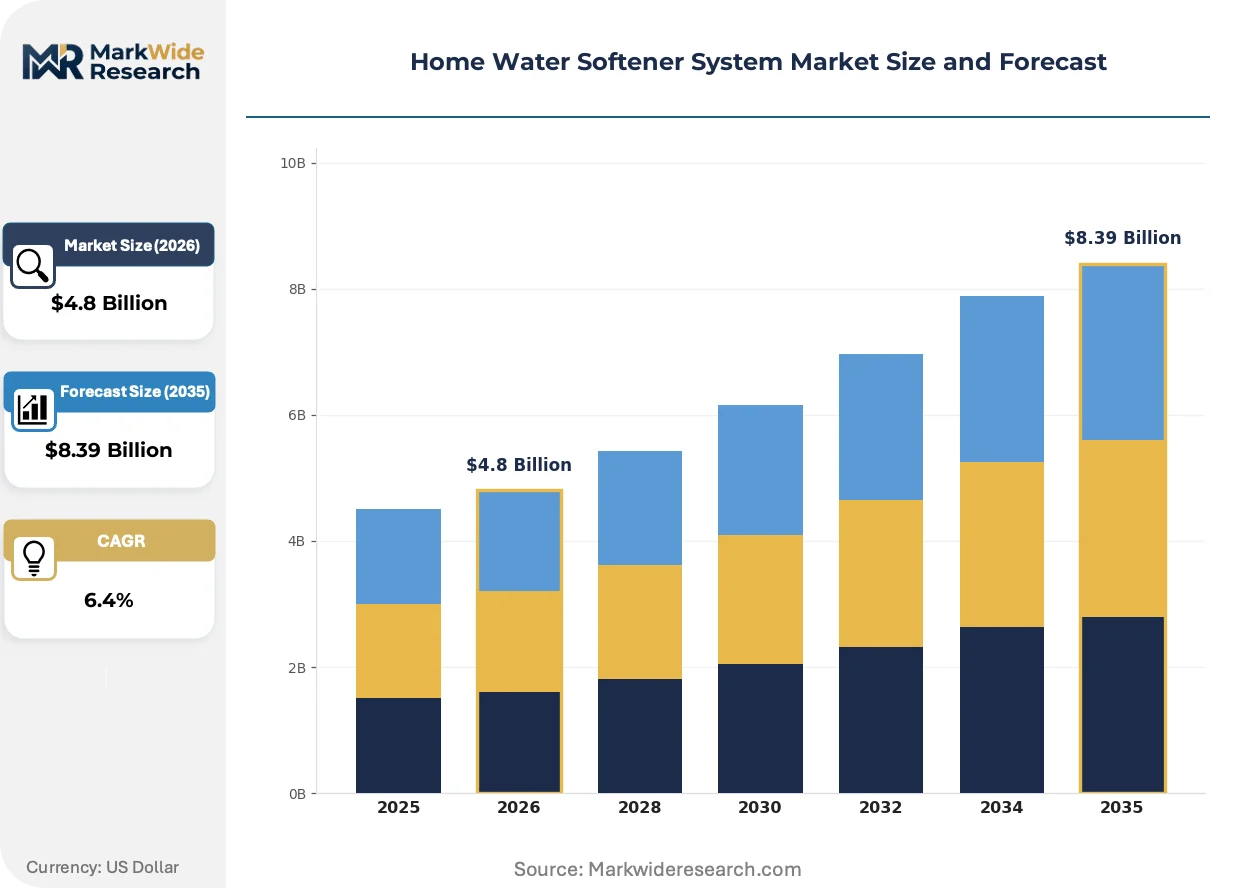
Market Dynamics
California's SBX7-7 water conservation mandates are forcing manufacturers to redesign regeneration cycles, compressing salt and water consumption benchmarks across residential product lines. This regulatory pressure is hybridizing traditional ion-exchange architectures with salt-free conditioning technologies as installers seek compliant configurations for brine-restricted municipalities.
Growth Catalysts
- Brine discharge restrictions:Arizona and Texas municipalities are banning sodium-heavy wastewater releases, accelerating demand for low-salt regeneration systems in suburban developments.
- Appliance replacement cycles:Calcium-heavy groundwater in the United States Sun Belt is shortening water heater and dishwasher lifespans, pushing homeowners toward preventive softening infrastructure.
- NSF/ANSI Standard 44:Certification requirements for residential channel legitimacy are filtering out uncertified competitors and consolidating professional installer networks.
Market Restraints
- Sodium chloride price volatility:Road salt demand spikes during winter storms divert supply from water treatment grades, squeezing operating margins for salt-based system owners.
- Template-assisted crystallization efficacy limits:Salt-free units fail below 25 grains per gallon hardness, excluding them from markets with very hard well water.
- Plastics supply concentration:Polyethylene brine tank production clusters in Gulf Coast petrochemical corridors, exposing manufacturers to hurricane-related disruption risks.
Strategic Opportunities
- Subscription leasing models:Dealer-financed programs are penetrating middle-income suburban households previously priced out of whole-home systems.
- Reverse-osmosis bundling:Integrated filtration portfolios combining softeners with point-of-use drinking systems are capturing premium positioning in kitchen remodel channels.
- Dual-tank continuous service:Alternating regeneration designs are opening large-household segments with zero-interruption water demands.
Industry Challenges
- Installer certification timelines:NSF/ANSI Standard 44 training requirements are lengthening dealer onboarding, constraining service network expansion in fast-growing Sun Belt metros.
- Legacy plumbing integration:Retrofit installations in pre-1980s housing stock require galvanized pipe replacement, inflating project complexity and customer abandonment rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Water Softener System Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Salt-Based, Salt-Free, Dual-Tank, Magnetic Technology: Ion Exchange, Reverse Osmosis, Electromagnetic, Filtration End User: Residential, Commercial, Industrial, Agricultural Distribution Channel: Online, Retail Store, Wholesale, Direct Sales |
| Companies Covered | Culligan International Company, Kinetico Incorporated, EcoWater Systems LLC, A.O. Smith Corporation, Pentair PLC, Whirlpool Corporation, Fleck Systems, SpringWell Water Filtration Systems, Leaf Home Water Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Water Softener System Market Trends and Innovations
Water softener technology is converging around resource efficiency mandates, with manufacturers embedding sensors and connectivity to optimize regeneration timing. This shift is compressing the performance gap between premium dual-tank systems and re-engineered single-tank units.
Demand-initiated regeneration technology is hybridizing with traditional time-clock systems, enabling units to meter actual water usage rather than estimating consumption patterns. Rural well-water households are adopting these configurations fastest, as erratic usage patterns make fixed-cycle regeneration wasteful. The result is squeezing market share from entry-level timer-based units while elevating expectations for operating cost transparency.
EPA voluntary guidelines for drinking water quality are indirectly tightening consumer awareness of hardness-related aesthetic issues, particularly staining and soap inefficiency. Municipal water departments in hardness-affected regions are publishing annual water quality reports that highlight calcium and magnesium levels. Residential buyers in these service areas are now entering purchase conversations with baseline technical literacy previously limited to commercial specifiers.
Service contract unbundling is fragmenting the traditional dealer-installer relationship, with third-party maintenance providers entering suburban markets through direct-to-consumer digital channels. Independent technicians certified through manufacturer programs are displacing exclusive dealer networks for routine resin bed replacement and brine tank cleaning. This pattern is most visible in Texas and Florida metro corridors where housing turnover rates accelerate system ownership transfers outside original installer relationships.
Home Water Softener System Market Segmentation
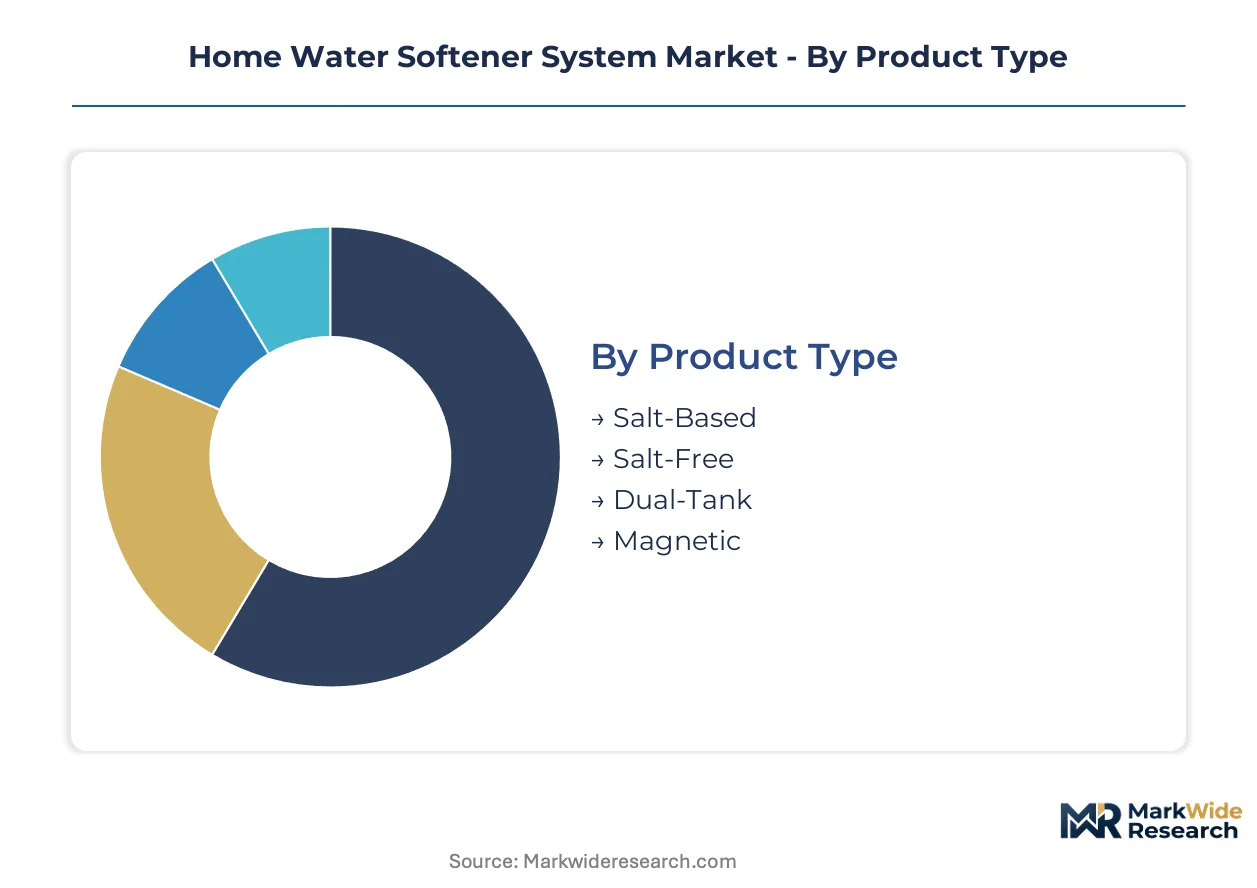
Technology architecture and regulatory compliance requirements fragment the Home Water Softener System Market into distinct competitive battlegrounds. Product configuration choices directly determine salt discharge profiles, installation complexity, and service contract economics for dealer networks.
Product Type:
Cost tier stratification separates entry-level conditioning units from premium continuous-service systems, with regeneration method and tank architecture driving lifetime ownership economics.
- Salt-Based:Ion-exchange resin beds regenerate with sodium chloride brine to strip calcium and magnesium from water flows. Municipal brine discharge restrictions in Arizona and Texas are compressing salt consumption benchmarks for new installations, pushing manufacturers toward demand-initiated regeneration controllers.
- Salt-Free:Template-assisted crystallization alters mineral structure without chemical removal, eliminating brine discharge entirely. California SBX7-7 compliance mandates are rotating this configuration up the share rankings in coastal suburban developments where sodium restrictions apply.
- Dual-Tank:Alternating regeneration design eliminates service interruptions for large households with continuous water demand.
- Magnetic:Electromagnetic field conditioning claims scale reduction without physical media replacement or salt consumption.
Salt-Based holds installed capacity. Salt-Free is rotating up the share rankings.
Technology:
Application-specific efficacy requirements determine which purification physics dominate each end-use context, with hardness level and flow rate demands filtering viable architectures.
- Ion Exchange:Resin bead chemistry swaps calcium and magnesium ions for sodium or potassium, proven effective above 25 grains per gallon hardness. Sun Belt well-water households in Texas and Florida concentrate demand here, as template-assisted crystallization fails at extreme hardness levels.
- Reverse Osmosis:Semi-permeable membrane filtration removes dissolved solids including hardness minerals, typically deployed at point-of-use for drinking water rather than whole-home softening. Kitchen remodel channels in suburban California bundle RO with salt-free conditioners for comprehensive treatment.
- Electromagnetic:Coil-generated fields claim to precipitate scale without media replacement.
- Filtration:Physical media capture of particulates and some dissolved contaminants, often paired with other technologies.
Ion Exchange holds installed capacity. Reverse Osmosis is rotating up the share rankings.
End User:
Customer type determines scale specifications, service contract structures, and regulatory exposure across residential, commercial, and productive applications.
- Residential:Single-family and multi-family dwellings requiring point-of-entry treatment for appliance protection and aesthetic water quality. Sun Belt suburban developments in the United States drive volume, with calcium-heavy groundwater shortening water heater replacement cycles and motivating preventive infrastructure investment.
- Commercial:Hospitality, healthcare, and food service operations with high-volume hot water demands and linen washing requirements. NSF/ANSI Standard 44 certification gates professional channel legitimacy for these installations.
- Industrial:Manufacturing processes requiring boiler feedwater and cooling tower treatment.
- Agricultural:Irrigation systems and livestock operations managing scale accumulation in distribution equipment.
Residential holds installed capacity. Commercial is rotating up the share rankings.
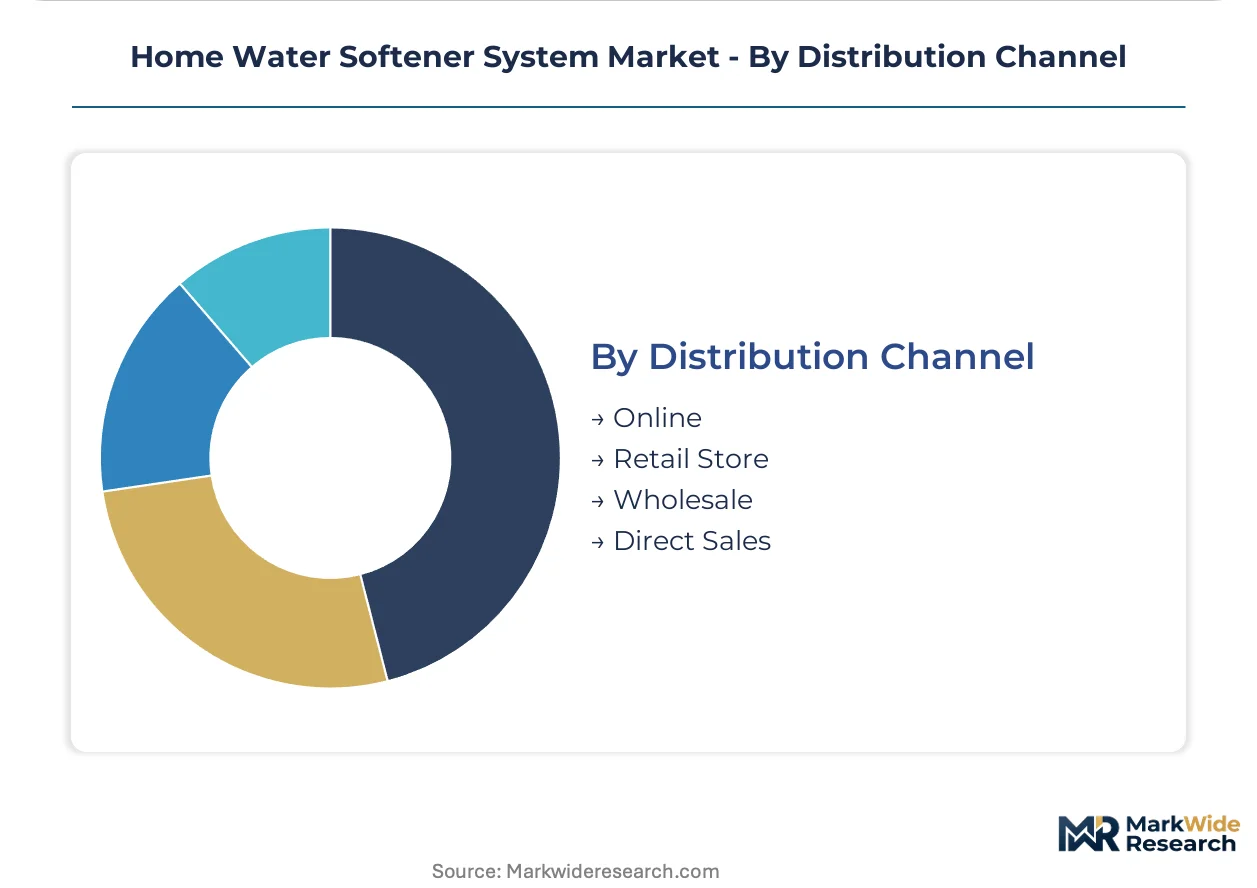
Distribution Channel:
Volume concentration and margin capture diverge across fulfillment paths, with installer certification requirements and customer acquisition economics determining channel viability.
- Online:Direct-to-consumer digital platforms enable specification comparison and third-party maintenance provider discovery. Texas and Florida metro corridors show fastest channel expansion where housing turnover accelerates system ownership transfers outside original dealer relationships.
- Retail Store:Big-box and specialty hardware channels offer immediate availability for DIY-capable homeowners. Entry-level timer-based units concentrate here, though demand-initiated regeneration is squeezing share as rural well-water households upgrade.
- Wholesale:Professional installer and contractor supply networks.
- Direct Sales:Manufacturer-employed or exclusive dealer representatives conducting in-home consultations.
Retail Store holds installed capacity. Online is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Suburban single-family homeowners in hard-water zones drive regional demand concentration. Municipal regulations and groundwater chemistry shape installation patterns across distinct national markets. Calcium-heavy aquifers and sodium discharge restrictions determine technology preferences in each geography.
United States
Sun Belt suburban developments concentrate demand as calcium-heavy groundwater shortens appliance lifespans. The EPA's voluntary drinking water guidelines heighten consumer awareness of hardness-related aesthetic issues. Texas and Florida metro corridors show fastest channel expansion where housing turnover accelerates system ownership transfers.
Germany
Municipal water hardness regulations push residential buyers toward certified ion-exchange units in single-family housing. The country's national water quality framework enforces strict discharge standards for residential treatment systems. Industrial clusters in Bavaria and North Rhine-Westphalia anchor manufacturing capacity for precision-engineered resin bed technologies.
Canada
Hard water prevalence across Prairie Provinces and Ontario drives preventive infrastructure investment among rural well-water households. Health Canada guidelines shape product certification requirements for residential channel entry. Calgary and Edmonton suburban developments concentrate installation volumes where groundwater mineral content accelerates equipment replacement cycles.
Australia
Calcium-rich groundwater in Western Australia and South Australia motivates appliance protection spending among detached housing owners. The country's national water efficiency labeling scheme influences consumer selection of low-consumption regeneration systems. Perth metropolitan expansion concentrates demand for salt-free conditioning alternatives where brine discharge restrictions apply.
India
Rising middle-class homeownership in hard-water belts drives point-of-entry treatment adoption in metropolitan suburbs. The Bureau of Indian Standards certification gates product legitimacy for residential channel penetration. Bangalore and Hyderabad tech-corridor housing developments concentrate premium system installations where groundwater hardness exceeds acceptable thresholds.
Home Water Softener System Market Competitive Landscape
Channel-controlling players compete with product-specialist players for installer network dominance and consumer mindshare. The vendor base organizes around three strategic archetypes: vertically integrated water treatment conglomerates, dealer-financed leasing specialists, and non-electric technology purists. Consolidation pressure intensifies as certification requirements and service contract economics favor scaled service networks. Dominant competitive moves include portfolio diversification into bundled filtration systems and geographic expansion through exclusive dealer financing arrangements.
Within the dealer-financed leasing tier, Culligan International Company exemplifies recurring revenue architecture through suburban installer networks. Kinetico Incorporated anchors the non-electric technology vector with demand-initiated regeneration positioning. Pentair PLC occupies the integrated filtration portfolio tier, bundling softeners with point-of-use drinking systems for kitchen remodel channels. These three entities represent distinct competitive archetypes rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Culligan International Company |
| Kinetico Incorporated |
| EcoWater Systems LLC |
| A.O. Smith Corporation |
| Pentair PLC |
| Whirlpool Corporation |
| Fleck Systems |
| SpringWell Water Filtration Systems |
| Leaf Home Water Solutions |
| Others |
Pricing and Supply Chain Analysis
Sodium chloride price volatility driven by road salt demand spikes during winter storms compresses operating margins for salt-based system owners while simultaneously widening spreads between premium demand-initiated regeneration units and entry-level timer-based configurations across North American dealer networks.
Pricing Analysis
Long-term supply agreements with sodium chloride producers indexed to agricultural salt benchmarks dominate procurement for major manufacturers, though spot market exposure persists for smaller dealers. Three-tier pricing structure across premium dual-tank systems, standard single-tank ion-exchange units, and economy timer-based models reflects NSF/ANSI Standard 44 certification grade and after-sales service bundling. Cost compression in the economy tier is intensifying because polyethylene resin price volatility feeds into brine tank production costs. DIY-capable homeowners purchasing through retail channels exhibit highest price sensitivity, while commercial hospitality operators prioritize total cost of ownership over upfront capital outlay.
Supply Chain Analysis
Contract manufacturing for ion-exchange resin beds concentrates with specialty chemical processors in Germany and the United States, while polyethylene brine tank fabrication clusters with Gulf Coast petrochemical converters. The supply chain draws from petroleum-derived resin feedstocks, ion-exchange resin precursor chemicals, and electronic control module assemblies. Single-source vulnerability concentrates in ion-exchange resin chemistry where proprietary formulation knowledge limits qualified suppliers. Distribution runs through exclusive dealer networks for premium installations, wholesale contractor channels for commercial projects, and direct-to-consumer platforms for salt-free conditioning alternatives.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market requires substitution defense against template-assisted crystallization technologies that threaten ion-exchange dominance in moderate-hardness suburban developments where sodium discharge restrictions apply.
For Market Incumbents: Build certification moats around NSF/ANSI Standard 44 dealer training infrastructure to lengthen competitor onboarding timelines in fast-growing Sun Belt metros. Deepen backward integration into ion-exchange resin production to secure supply continuity against petrochemical volatility. Salt-free conditioning entrants and municipal brine discharge mandates represent dual threats demanding preemptive hybrid product architecture investment. For New Entrants and Emerging Players: Establish a beachhead in online direct-to-consumer channels for salt-free conditioning units targeting Texas and Florida housing turnover corridors where third-party maintenance providers displace exclusive dealer relationships. The most penetrable segment comprises middle-income suburban households previously priced out of whole-home systems through subscription leasing models. Go-to-market execution should emphasize digital specification comparison tools that bypass traditional installer gatekeepers. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors scaled service networks with captive dealer financing capabilities over pure product manufacturers. Long-term viability hinges on recurring revenue streams from salt pellet replenishment and resin bed replacement contracts rather than equipment sales alone. Watch for municipal sustainability ordinance diffusion from coastal states toward interior markets as the inflection signal determining technology architecture winners.| Strategic Initiative | Industry Significance |
|---|---|
| Dealer Financing Infrastructure Expansion | Culligan's recurring revenue model demonstrates captive financing locks in suburban customer lifetime value across multi-year service contracts. |
| Demand-Initiated Regeneration Patent Development | Kinetico's non-electric technology reduces rural well-water household operating costs and defends premium positioning against timer-based alternatives. |
| Reverse Osmosis Bundling Integration | Pentair's kitchen remodel channel penetration captures premium positioning through combined softener and point-of-use drinking system portfolios. |
| Salt-Free Conditioning Certification Investment | California SBX7-7 compliance mandates rotate template-assisted crystallization configurations up share rankings in coastal suburban developments. |
| Third-Party Maintenance Platform Launch | Independent technician certification programs fragment traditional dealer-installer relationships in Texas and Florida metro corridors with high housing turnover. |
Research Methodology
Cross-validation between primary interviews with water treatment dealer principals, municipal utility planning officers, and residential plumbing contractors anchors the qualitative findings against secondary validation from EPA water quality databases, NSF/ANSI certification registries, and state-level brine discharge regulation filings. The analysis combines bottom-up installation volume estimates from regional dealer networks with top-down market sizing derived from household penetration rates in hard-water census tracts across the United States Sun Belt, German single-family housing developments, and Canadian Prairie Province rural well-water communities.
Calibration against historical salt consumption patterns and appliance replacement cycle data in calcium-heavy groundwater zones refines the projection framework across technology architecture, end-user segment, and distribution channel dimensions. CAGRs were derived from regression analysis of correlated variables including housing starts in hard-water regions, municipal regulatory adoption timelines, and sodium chloride price indices. Industry-specific forecast inputs incorporate ion-exchange resin capacity utilization rates and polyethylene brine tank production schedules from Gulf Coast petrochemical corridors.
Stress conditions across sodium chloride supply disruption, municipal brine discharge ordinance acceleration, and template-assisted crystallization efficacy breakthroughs were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory diffusion patterns and technology substitution thresholds. Quarterly review of municipal sustainability ordinance adoption rates and salt-free conditioning unit share trajectories is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water Treatment Systems
Water Desalination Equipment Market
Water Treatment Systems
Storm Water Cleaning Services Market
Water Treatment Systems
Portable Filtration System Market
Water Treatment Systems
Commercial Water Filter Market
Water Treatment Systems
Malaysia Water Purifier Market
Water Treatment Systems
Self-Cleaning Filters Market
Water Treatment Systems
Industrial Wastewater Treatment Equipment Market
Water Treatment Systems
Plant Based Water Filter Market
Water Treatment Systems
Asia-Pacific Water Purifier Market
Water Treatment Systems
Smart Water Softeners Market
Water Treatment Systems
Wastewater Recovery Systems Market
Water Treatment Systems
Solar Water Purifiers Market
Water Treatment Systems
Packaged Water Treatment System Market
Water Treatment Systems
Solar Aerators Market
Water Treatment Systems
US Water Purifier Market
Water Treatment Systems
Philippines Gravity-Based Water Purifier Market