
 Water Desalination Equipment Market | 2026-2036
Water Desalination Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Water Desalination Equipment Market Intelligence
Increased manufacturing capacity for advanced reverse osmosis membranes in South Korea and Japan is repositioning the competitive landscape for high-purity water production. Veolia Water Technologies leverages its extensive project portfolio in municipal contracts. SUEZ Group specializes in integrated water and waste management solutions for industrial clients, while IDE Technologies leads in large-scale membrane and thermal desalination projects.
Water desalination equipment refers to the integrated systems of machinery used to remove dissolved mineral salts from seawater or brackish sources. These systems typically operate using high-pressure pumps and semipermeable membranes to achieve ion separation for potable water production. Membrane filtration technologies, specifically reverse osmosis systems, command the largest market share. The municipal water supply application represents the fastest-growing segment, addressing urban water deficits.
The WHO's Guidelines for Drinking-water Quality provide a global benchmark for treated water safety. National regulations, such as those from the US EPA and China's MEE, govern brine disposal and energy efficiency standards for new plants. Equipment manufacturers must balance investments in next-generation, low-energy membranes against the development of robust hybrid systems for complex source water.
Market Dynamics
The fundamental tension between rising urban water demand and the high energy cost of conventional desalination methods is the central force shaping the market. This dynamic compels innovation in membrane technology and system design to improve the economic viability of large-scale projects.
Growth Catalysts
- Water Quality Standards:The WHO's Guidelines for Drinking-water Quality establish a global baseline, compelling municipalities to invest in advanced treatment technologies like desalination to meet safety and potability benchmarks for their populations.
- Technological Advancement:Continuous improvements in the efficiency and durability of reverse osmosis membranes lower the lifecycle cost of water production, making desalination a more competitive option against other water sourcing strategies.
- Chronic Water Scarcity:Persistent drought conditions and aquifer depletion in regions such as California, the Middle East, and North Africa create non-negotiable demand for new, climate-independent municipal water supplies.
Market Restraints
- Energy Consumption:The high electricity requirement for operating high-pressure pumps remains the largest single component of a desalination plant's operating expenditure, acting as a significant structural cost barrier.
- Brine Management:Strict environmental regulations governing the disposal of hypersaline brine concentrate, such as those enforced by the US EPA, add significant cost, complexity, and permitting hurdles to new projects.
- Membrane Fouling:The gradual degradation of membrane performance due to biological and mineral fouling necessitates costly chemical cleaning and eventual replacement, impacting long-term operational budgets and system reliability.
Strategic Opportunities
- Industrial Water Reuse:Application in closed-loop water systems for water-intensive industries like semiconductor fabrication, mining, and power generation offers a high-value, fast-growing market segment beyond municipal supply.
- Renewable Energy Pairing:Co-locating desalination facilities with solar or wind farms provides an opportunity to create low-carbon, self-sufficient water production systems, appealing to sustainability mandates and hedging against energy price volatility.
- Brackish Water Treatment:Expanding into inland regions to treat brackish groundwater sources opens a substantial new market, as these sources are often less energy-intensive to desalinate than seawater.
Industry Challenges
- Capital Intensity:The immense upfront capital investment required for constructing large-scale desalination plants creates long project timelines and significant financing hurdles, limiting the number of projects that can proceed.
- System Integration Complexity:Connecting new desalination outputs to existing, often aging, municipal water distribution networks without compromising water quality or system pressure requires sophisticated engineering and planning.
- Skilled Operator Scarcity:A shortage of technicians and engineers with the specialized skills to operate and maintain advanced membrane systems and digital control platforms poses an operational risk for plant owners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Water Desalination Equipment Market |
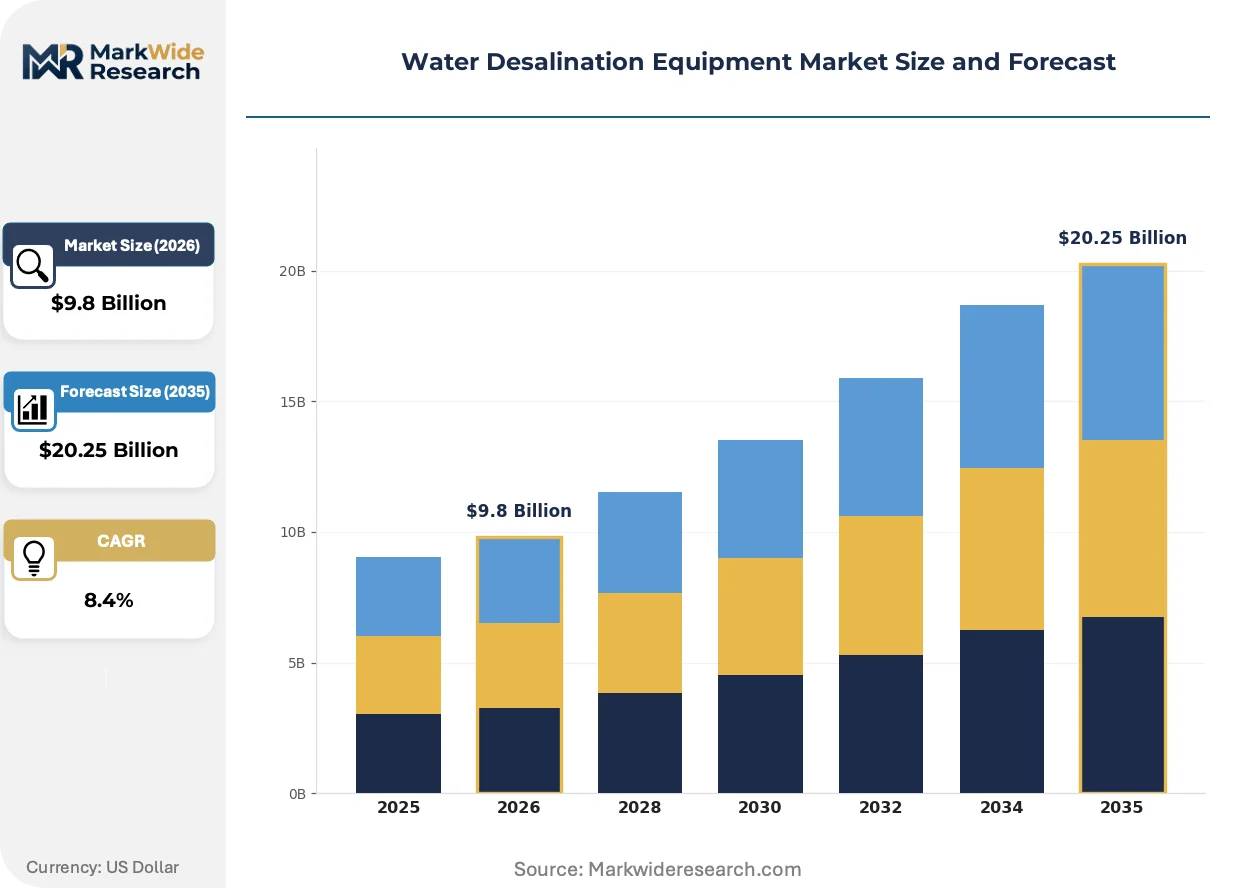
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $20.25 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Reverse Osmosis Systems, Multi-Stage Flash Distillers, Electrodialysis Units, Vapor Compression Units, Nanofiltration Systems Technology: Membrane Filtration, Thermal Distillation, Electrochemical Separation, Solar Desalination, Hybrid Technologies Application: Municipal Water Supply, Industrial Process Water, Agricultural Irrigation, Drinking Water Production, Military Operations End User: Water Utilities, Petrochemical Plants, Food & Beverage Manufacturers, Power Generation Facilities, Research Institutes |
| Companies Covered | Veolia Water Technologies, SUEZ Group, Doosan Heavy Industries & Construction, IDE Technologies, Aquatech International LLC, Xylem Inc., Acciona, Biwater Holdings Limited, Genesis Water Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Water Desalination Equipment Market Strategic Shifts & Innovations
The evolution of desalination is marked by a decisive shift toward intelligent systems that optimize energy use and operational longevity. This transition moves the industry beyond brute-force water separation to a more nuanced, data-driven approach for producing potable water from saline sources.
Advanced sensor technology embedded within membrane modules and pump systems provides real-time performance data. Industrial and municipal plant operators are adopting this technology to monitor pressure, flow, and water quality with high granularity. This instrumentation is integrating with plant-level control systems to enable automated adjustments, which optimizes chemical dosing and extends membrane life.
Regulatory frameworks are increasingly focused on the environmental footprint of desalination. The European Union's Green Deal, for example, indirectly pressures industrial water users to improve efficiency and explore recycling, creating a tailwind for industrial-scale desalination equipment. Plant manufacturers targeting the EU market must now demonstrate superior energy performance and provide clear data on the lifecycle impact of their systems.
A notable shift in asset ownership models is altering how projects are financed and operated. The traditional model of direct municipal ownership is being supplemented by build-own-operate-transfer (BOOT) arrangements with specialized infrastructure firms. This change is most prominent in the Middle East and parts of Southeast Asia, where it accelerates project deployment by transferring financing and operational risk to the private sector.
Water Desalination Equipment Market Segmentation
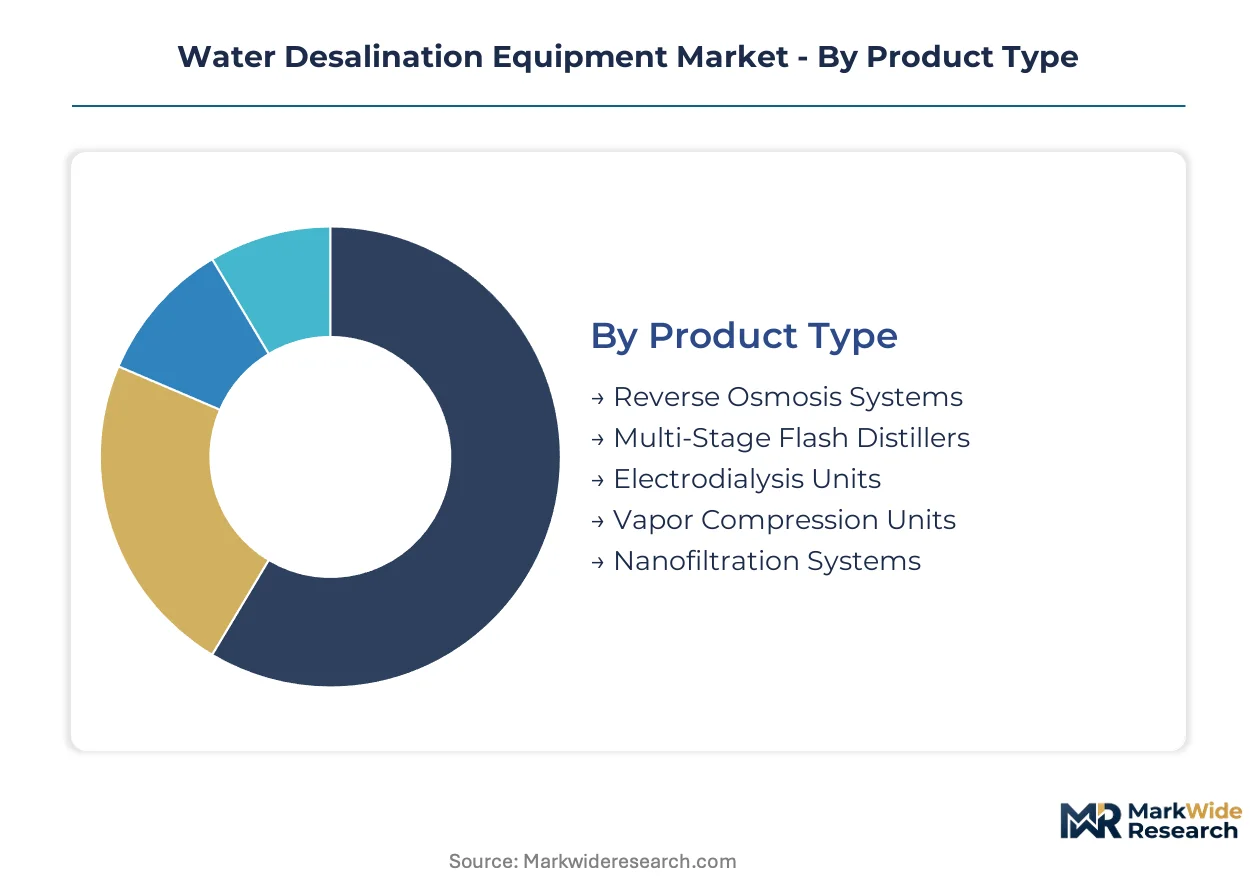
Market segmentation provides a structured view of the diverse applications and technological approaches within the water desalination equipment industry. Understanding these distinct segments helps manufacturers target specific customer needs and navigate varying regulatory environments. This detailed categorization illuminates where investment and innovation are most impactful for sustainable growth.
Product Type:
Regulatory bodies like the US EPA and China's MEE scrutinize water quality and energy efficiency across different desalination product types, influencing their market viability.
- Reverse Osmosis Systems:These systems utilize semipermeable membranes and high-pressure pumps to separate dissolved salts from water, producing high-purity permeate. Demand concentrates in arid coastal regions such as Saudi Arabia and California, driven by continuous membrane efficiency advancements.
- Multi-Stage Flash Distillers:This technology employs a series of flash evaporation stages at progressively lower pressures to distill water, making it suitable for high-salinity feedwater. Demand concentrates in regions with abundant waste heat availability, particularly in the Middle East, due to its robust performance.
- Electrodialysis Units:These units utilize an electric potential difference to move ions across ion-exchange membranes, primarily suitable for brackish water desalination.
- Vapor Compression Units:This method evaporates water using a mechanical compressor to create a vacuum, often deployed for smaller-scale or specialized industrial applications.
- Nanofiltration Systems:These systems filter particles larger than 1 nanometer, primarily removing divalent ions and organic matter, frequently serving as a pre-treatment step.
Leading the category by volume: Reverse Osmosis Systems. Growing fastest: Nanofiltration Systems.
Technology:
The cost structure for desalination technologies varies significantly, impacting both capital expenditure and operational outlays for plant developers.
- Membrane Filtration:This broad category encompasses reverse osmosis and nanofiltration, relying on semipermeable barriers for effective ion separation. Demand is high in municipal water supply projects across the United States and UAE, due to continuous efficiency improvements.
- Thermal Distillation:This technology includes multi-stage flash and multi-effect distillation, boiling and condensing water to remove impurities effectively. This technology sees significant deployment in industrial applications requiring high-purity water, especially where waste heat sources are abundant.
- Electrochemical Separation:This method uses electric fields to separate ions, primarily applied in brackish water desalination and specific industrial processes.
- Solar Desalination:This technology leverages solar energy to power distillation or membrane processes, suitable for off-grid or remote community water needs.
- Hybrid Technologies:These systems combine two or more desalination methods, such as RO with thermal, to optimize energy consumption and water recovery for complex source waters.
Supply concentration for this category heavily favors membrane-based systems. Hybrid solutions show the steepest expansion trajectory.
Application:
Application volumes for desalinated water are directly correlated with regional water stress and industrial activity levels.
- Municipal Water Supply:This application provides potable water for urban populations, directly addressing chronic water scarcity in metropolitan areas. This application represents the fastest-growing segment in regions like California and the Middle East, driven by increasing urban demand.
- Industrial Process Water:This segment supplies high-purity water for manufacturing, cooling, and boiler feed in various industrial facilities. This segment offers a high-value market in sectors such as semiconductor fabrication and petrochemicals, enhancing operational resilience.
- Agricultural Irrigation:This application uses desalinated water for crop cultivation, particularly in arid regions where freshwater sources are critically scarce.
- Drinking Water Production:This segment focuses on direct potable water generation, often for smaller communities or disaster relief scenarios, adhering to WHO guidelines.
- Military Operations:This application provides water for deployed personnel and bases, requiring robust and mobile desalination units for operational independence.
Water utilities drive the majority of demand in this category. Industrial users are gaining share fastest.
End User:
Procurement patterns among end users reflect distinct operational requirements and regulatory compliance mandates.
- Water Utilities:These public or private entities are responsible for providing potable water to communities, often through large-scale municipal projects. These entities prioritize long-term reliability and cost-effectiveness, influenced by national regulations like those from the US EPA.
- Petrochemical Plants:These facilities require substantial volumes of high-purity water for cooling, steam generation, and various process inputs, operating continuous production cycles. These industrial users focus on system uptime and water quality consistency to prevent equipment damage and ensure product integrity.
- Food & Beverage Manufacturers:These companies utilize desalinated water for product formulation, cleaning, and sanitization, meeting stringent quality standards like those from the FDA.
- Power Generation Facilities:These facilities employ desalinated water for boiler feed and cooling towers, crucial for preventing scaling and maintaining turbine efficiency.
- Research Institutes:These organizations conduct studies on new desalination technologies and processes, contributing to innovation and efficiency improvements across the industry.
Water Utilities command the largest share of equipment sales. Petrochemical Plants offer higher margin opportunities for specialized systems.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Arabian Peninsula, with its arid climate and growing urban centers, anchors substantial demand for water desalination equipment. Regions facing acute freshwater shortages increasingly rely on advanced treatment technologies to meet potable water needs. This global market sees varied adoption rates influenced by local water stress, economic development, and regulatory frameworks.
Saudi Arabia
Rapid population growth and ambitious development projects drive the need for expanded municipal water supply in Saudi Arabia. The Kingdom's national water strategy mandates investment in desalination to secure future water resources. Massive infrastructure initiatives like NEOM are developing new, large-scale desalination plants, integrating advanced membrane and thermal technologies.
United States
Persistent drought conditions and aquifer depletion in states like California create non-negotiable demand for new water sources. The US EPA’s strict regulations on brine disposal and water quality standards influence project design and permitting. Coastal communities such as San Diego continue to invest in large-scale reverse osmosis facilities to enhance water security.
United Arab Emirates
High urbanization rates and significant industrial expansion necessitate continuous investment in water infrastructure across the UAE. The Ministry of Health and Prevention (MOHAP) enforces stringent drinking water quality standards for all sources. Major cities like Dubai are expanding their desalination capacity to support both residential and commercial growth.
China
Industrial process water and urban water deficits in coastal provinces propel demand for desalination solutions in China. The Ministry of Ecology and Environment (MEE) sets energy efficiency and environmental protection standards for new desalination plants. Coastal economic zones, including those around Tianjin, are developing projects to address industrial water demands.
Japan
Industrial applications requiring high-purity water, particularly in the semiconductor and manufacturing sectors, drive demand in Japan. The Ministry of Economy, Trade and Industry (METI) supports research and development in advanced membrane technologies. Cities like Kitakyushu lead in implementing water recycling and desalination projects for industrial and municipal use.
Water Desalination Equipment Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue niche applications like industrial water reuse and renewable energy integration. The market structure exhibits a blend of large, diversified engineering firms and specialized technology providers. Strategic archetypes include integrated solution providers, membrane technology specialists, and project development consortia. Geographic expansion and technology licensing represent dominant competitive moves among market participants.
Within the integrated solution provider archetype, Veolia Water Technologies and SUEZ Group represent European-headquartered entities with diversified portfolios in water and waste management. IDE Technologies, an Israeli-based firm, anchors the large-scale membrane and thermal project segment, often specializing in complex source water challenges. These companies consistently leverage their extensive project experience across municipal and industrial clients, driving innovation in system integration and operational efficiency. Their presence underscores the market's reliance on established engineering capabilities and global project execution expertise.
| Leading Market Players |
|---|
| Veolia Water Technologies |
| SUEZ Group |
| Doosan Heavy Industries & Construction |
| IDE Technologies |
| Aquatech International LLC |
| Xylem Inc. |
| Acciona |
| Biwater Holdings Limited |
| Genesis Water Technologies |
| Others |
Cost & Logistics Intelligence
The shift towards advanced reverse osmosis membrane efficiency simultaneously reshapes system cost economics and concentrates specialized manufacturing supply. This dynamic influences overall project viability and procurement strategies for large-scale desalination plants.
Pricing Analysis
Comprehensive service bundles, including long-term maintenance contracts and performance guarantees, differentiate project pricing for desalination equipment. The dominant pricing model is project-based, reflecting the bespoke nature of large-scale plant construction. Price differentiation stems from customization levels for complex source waters and the level of after-sales support offered. Pricing softness reflects intense competition among engineering firms and the high capital intensity of projects. Municipal water utilities are highly price-sensitive due2 to public funding constraints, while industrial users prioritize system uptime and water quality consistency.
Supply Chain Analysis
High-purity reverse osmosis membrane supply rests heavily on specialized manufacturers in South Korea and Japan. Key component dependencies include these advanced membranes and high-pressure energy recovery devices. A structural risk involves the potential for single-source vulnerability for highly specialized membrane types. Distribution runs through large engineering, procurement, and construction (EPC) contractors who integrate diverse components into complete systems for end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is increasingly a consolidation play, as the immense capital intensity of large-scale projects forces out smaller, undercapitalized equipment providers. This dynamic favors established engineering firms with robust balance sheets and extensive project portfolios.
For Market Incumbents: Anticipate further tightening of environmental regulations, particularly concerning brine management and energy efficiency. Deepen vertical integration into membrane manufacturing or critical component supply to mitigate supply chain risks and control costs. Invest heavily in hybrid system development to address complex source water challenges and optimize energy consumption. Leverage existing municipal contracts to cross-sell advanced monitoring and optimization software, countering threats from specialized technology providers.
For New Entrants and Emerging Players: Renewable energy-paired desalination systems offer a technology-first wedge into the market, particularly for off-grid or remote community applications. Target industrial water reuse applications, such as semiconductor fabrication, where high-purity water commands premium pricing. Develop specialized solutions for brackish water treatment in inland regions, a less energy-intensive segment. A direct-to-industry sales model focusing on operational efficiency and reduced chemical use provides a strong go-to-market angle.
For Investors and Strategic Acquirers: Exit pathways concentrate in specialized technology providers with strong intellectual property in membrane science or advanced energy recovery systems. The long-term viability of this market remains strong, driven by persistent global water scarcity and urban growth. Identify mid-sized firms offering innovative digital twins or AI-driven plant optimization platforms. A signal to watch is the increasing adoption rate of build-own-operate-transfer (BOOT) models, indicating greater private sector involvement and project finance maturity.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Membrane Production | Secures critical supply for large-scale projects and improves cost control for integrated solution providers. |
| Advanced Sensor Integration | Enhances real-time operational efficiency and extends membrane lifespan for municipal water utilities. |
| Strategic Partnership for Renewable Energy | Reduces energy costs and improves environmental footprints for new desalination plant developments. |
| Acquisition of Digital Twin Specialists | Accelerates intelligent system optimization and predictive maintenance capabilities for plant operators. |
| Joint Venture for Brackish Water Projects | Expands market reach into inland regions with less energy-intensive desalination opportunities. |
Research Approach
WHO Guidelines for Drinking-water Quality, US EPA regulations, and China's MEE environmental standards formed the secondary backbone for this analysis. This was complemented by primary interviews with plant operators, municipal water utility executives, membrane technology R&D directors, and EPC project managers. Bottom-up data collection from individual project announcements and top-down market sizing provided robust triangulation. Trade association reports and academic research on desalination advancements further validated findings.
A combined bottom-up and top-down analytical approach established the market forecast across the analysis window. Segmentation dimensions included product type, technology, application, end-user, and regional water stress levels. Compound annual growth rates were derived from historical trends, projected technological advancements, and anticipated regulatory impacts. Key forecast inputs included projected urban water demand and energy price volatility.
Several conditions sit outside the modeled scope, including unforeseen geopolitical conflicts impacting energy supply or sudden shifts in global economic stability. Forecasts reflect documented assumptions regarding technological progression and regulatory continuity. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water Treatment Systems
Water Purification Tablets Market
Water Treatment Systems
Indonesia Gravity-Based Water Purifier Market
Water Treatment Systems
Point of Entry Water Treatment Systems Market
Water Treatment Systems
Global Residential Water Treatment Devices Market
Water Treatment Systems
Global RO Water Purifier Market
Water Treatment Systems
Self-Cleaning Filters Market
Water Treatment Systems
Africa Zero Liquid Discharge System Market
Water Treatment Systems
Water Treatment As a Service Market
Water Treatment Systems
GCC Water Purifier Market
Water Treatment Systems
Storm Water Cleaning Services Market
Water Treatment Systems
Portable Filtration System Market
Water Treatment Systems
Electro-Oxidation System Market
Water Treatment Systems
Portable Water Purifier Market
Water Treatment Systems
India Desalination Systems Market
Water Treatment Systems
Water Treatment Ozone Generator Market
Water Treatment Systems
Smart Water Softeners Market