
 Smart Water Softeners Market | 2026-2036
Smart Water Softeners Market Size, Share, and Industry Trends Forecast 2026-2036
Smart Water Softeners Market Analysis
Multi-family housing developers is rotating toward bulk smart water softener procurement as single-family residential upgrades slow in higher-interest environments. Culligan International Company leverages its direct-service technician network to sustain recurring revenue streams across commercial installations. EcoWater Systems LLC anchors its position through captive manufacturing of proprietary control valves and resin media. Pentair PLC competes on modular system architecture that allows property managers to scale capacity without full replacement.
Smart water softeners are ion-exchange or template-assisted crystallization devices equipped with flow sensors, connectivity modules, and algorithmic regeneration scheduling to reduce scale formation in plumbing and appliances; systems typically operate at 8-60 grains per gallon hardness removal capacity with resin bed lifecycles of 10-15 years under standard municipal conditions. Salt-based systems dominate installed base volume due to proven efficacy and lower upfront cost, while salt-free template-assisted crystallization is capturing fastest-growing share among environmentally regulated municipalities restricting brine discharge. IoT integration concentrates margin pools in recurring monitoring subscriptions and predictive salt-delivery logistics rather than hardware alone.
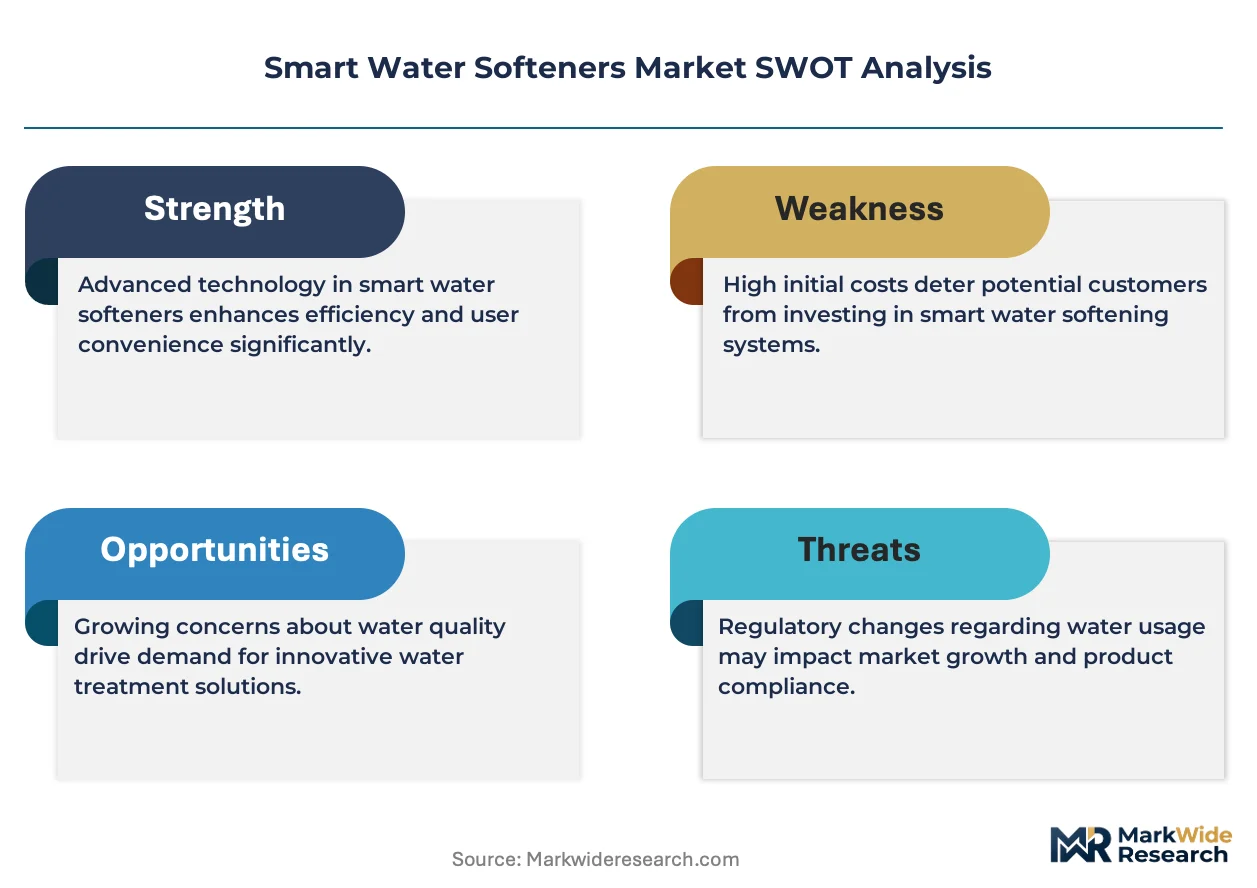
The EPA maintains voluntary water quality guidelines that influence state-level adoption of hardness thresholds, while the U.S. Department of Energy enforces efficiency standards on water treatment appliance standby power and regeneration cycle energy consumption; California's Title 22 brine disposal restrictions and Florida's building codes for coastal corrosion protection create fragmented compliance obligations that favor connected systems with automated reporting. Stakeholders must monitor evolving state-level salinity discharge rules and utility rebate programs for connected appliances to determine geographic prioritization and product certification roadmaps.
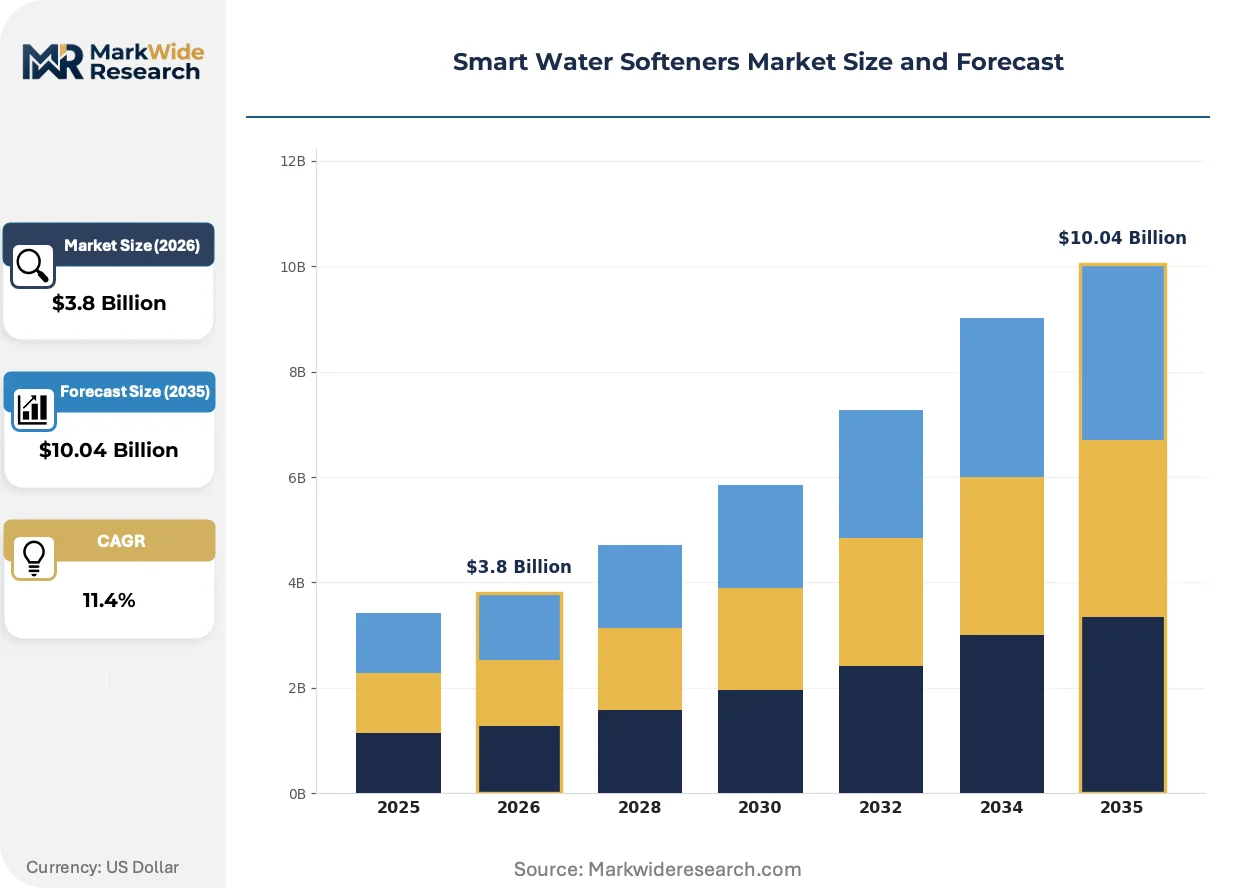
Market Dynamics
The US Sun Belt's construction boom intersects with tightening state plumbing codes to restructure demand toward connected, infrastructure-grade softening systems with automated compliance reporting.
Growth Catalysts
- California Title 22 brine discharge rules:Municipalities restricting salt discharge accelerate template-assisted crystallization adoption among environmentally regulated developers.
- Multi-family housing developers:Bulk procurement of IoT-enabled systems reduces per-unit installation costs and satisfies insurance underwriting requirements for scale properties.
- Template-assisted crystallization:Salt-free technology captures fastest-growing share where brine discharge faces municipal prohibition.
Market Restraints
- Resin media supply concentration:Specialty ion-exchange resin production clusters in Germany and China, exposing North American assemblers to freight cost volatility and customs delays.
- Florida coastal corrosion codes:Salt-based system installations face additional material certification requirements that extend permitting timelines by 4-8 weeks.
- Reverse osmosis point-of-use systems:Under-sink filtration alternatives capture kitchen-scale demand without whole-home infrastructure commitment.
Strategic Opportunities
- Texas Hill Country unpenetrated stock:Rapid Austin-San Antonio corridor expansion outpaces municipal water treatment capacity, creating private-well softening demand.
- Utility rebate programs:Connected appliance incentives in Arizona and Nevada reduce effective customer acquisition costs for smart system vendors.
- Predictive salt logistics convergence:Algorithmic consumption forecasting combined with last-mile delivery platforms enables subscription revenue models displacing transactional hardware sales.
Industry Challenges
- EPA voluntary guidance fragmentation:Absence of federal hardness mandates forces manufacturers to maintain 50-state compliance documentation matrices.
- Legacy plumbing integration:Pre-1990 residential infrastructure lacks adequate drainage for modern regeneration cycles, requiring costly retrofit assessments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Smart Water Softeners Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Salt-Based, Salt-Free, Magnetic, Dual-Tank Technology: Smart Sensors, Mobile App Control, IoT Integration, Automatic Regeneration End User: Residential, Commercial, Industrial, Agriculture Installation Type: Point-of-Entry, Point-of-Use, DIY, Professional |
| Companies Covered | 3M Company, A. O. Smith Corporation, Culligan International Company, EcoWater Systems LLC, Pentair PLC, BWT Holding GmbH, Whirlpool Corporation, Kinetico Incorporated, GE Appliances, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Smart Water Softeners Market Emerging Trajectories
Algorithmic regeneration scheduling and remote diagnostic platforms are compressing service margins while elevating hardware-software bundled offerings as the primary value capture mechanism.
Template-assisted crystallization media is supplanting conventional salt-based ion exchange in environmentally sensitive jurisdictions. Municipalities with brine discharge restrictions now specify salt-free systems for new commercial permits. This technology is supplanting legacy softening in California and Florida coastal zones where salinity regulations tighten fastest.
EPA voluntary water quality guidelines influence state-level hardness threshold adoption without creating uniform federal obligations. The Department of Energy enforces standby power and regeneration cycle efficiency standards that connected systems satisfy through automated scheduling. California, Texas, and Florida building codes now reference these efficiency benchmarks for new construction compliance.
Property managers now demand predictive maintenance subscriptions bundled with hardware rather than transactional equipment purchases. Direct-service technician networks face disintermediation by remote monitoring platforms that dispatch third-party plumbers only upon algorithmic failure prediction. This behavioral shift concentrates most visibly in Arizona and Nevada multi-family portfolios where scale economics favor centralized oversight.
Smart Water Softeners Market Segmentation
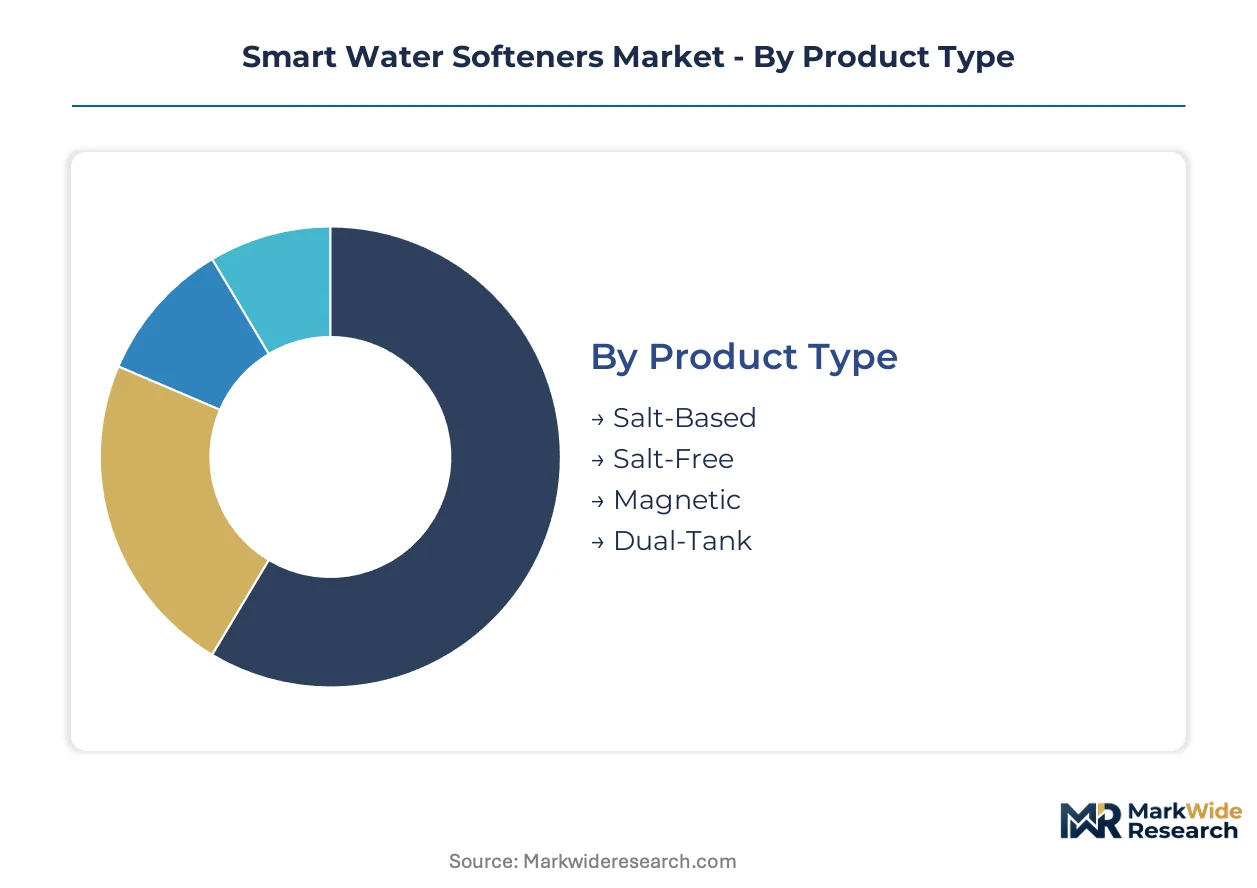
Segmentation in smart water softeners reveals how hardware margins migrate toward software-enabled services and which installation contexts justify premium pricing. Manufacturers configure product architectures around regulatory geography and infrastructure age rather than treating demand as uniform.
Product Type:
Margin pools concentrate in salt-free systems where environmental compliance commands pricing premiums and recurring media replacement revenue.
- Salt-Based:Ion-exchange systems using sodium chloride regeneration dominate installed base volume with proven efficacy across 8-60 grains per gallon hardness removal. Demand concentrates in Texas and Florida single-family retrofits where upfront cost sensitivity outweighs brine discharge concerns, though California Title 22 restrictions are compressing addressable market share in coastal municipalities.
- Salt-Free:Template-assisted crystallization media alters mineral structure without chemical exchange, eliminating brine discharge entirely. Arizona and Nevada multi-family developers specify these systems to satisfy municipal salinity caps and secure utility rebate eligibility, with media replacement cycles generating predictable recurring revenue.
- Magnetic:Electromagnetic field devices claim scale reduction without physical media replacement; uptake remains limited to experimental installations in agricultural well-water contexts.
- Dual-Tank:Continuous-flow configurations eliminate regeneration downtime for commercial laundries and hospitality operations with 24-hour hot water demand.
The dominant share belongs to Salt-Based, while Salt-Free is closing the gap fastest.
Technology:
Cost tier separation runs deepest between basic connectivity and predictive algorithm bundles that justify subscription pricing.
- Smart Sensors:Flow-rate and hardness detection modules enable condition-based regeneration rather than timer-based cycles. Residential installations in Arizona's hard-water corridor prioritize these for salt consumption reduction and appliance protection validation.
- Mobile App Control:Smartphone interfaces for manual override and consumption monitoring appeal to tech-forward single-family owners in Austin and Dallas suburbs where remote property management is normalized.
- IoT Integration:Cloud-connected platforms aggregate fleet data across multi-family portfolios, enabling centralized oversight. Las Vegas and Phoenix property managers demand these for predictive maintenance dispatch and insurance underwriting compliance.
- Automatic Regeneration:Algorithmic scheduling based on actual usage patterns rather than fixed intervals satisfies Department of Energy standby power standards. California new construction mandates reference these efficiency benchmarks.
IoT Integration commands the steepest expansion trajectory as property managers displace direct-service technician networks with centralized monitoring platforms.
End User:
Application context determines whether procurement flows through retail channels or bulk infrastructure contracts with divergent margin structures.
- Residential:Single-family and multi-family installations represent the volume anchor, with Sun Belt new construction driving specification. Bulk procurement by national developers in the Austin-San Antonio corridor reduces per-unit installation costs below retail replacement economics.
- Commercial:Hotels, hospitals, and food-service operations require continuous softening capacity with redundant tank configurations. Florida coastal corrosion codes impose additional material certification requirements that extend permitting timelines.
- Industrial:Boiler feedwater and cooling tower applications demand high-capacity systems with resin bed monitoring; procurement concentrates through MRO distributors with long-term service contracts.
- Agriculture:Private-well irrigation systems in Texas Hill Country unpenetrated stock represent emerging demand as municipal treatment capacity lags behind development pace.
Residential maintains the dominant share, though Commercial is expanding most quickly as insurance underwriters mandate connected systems for scale properties.
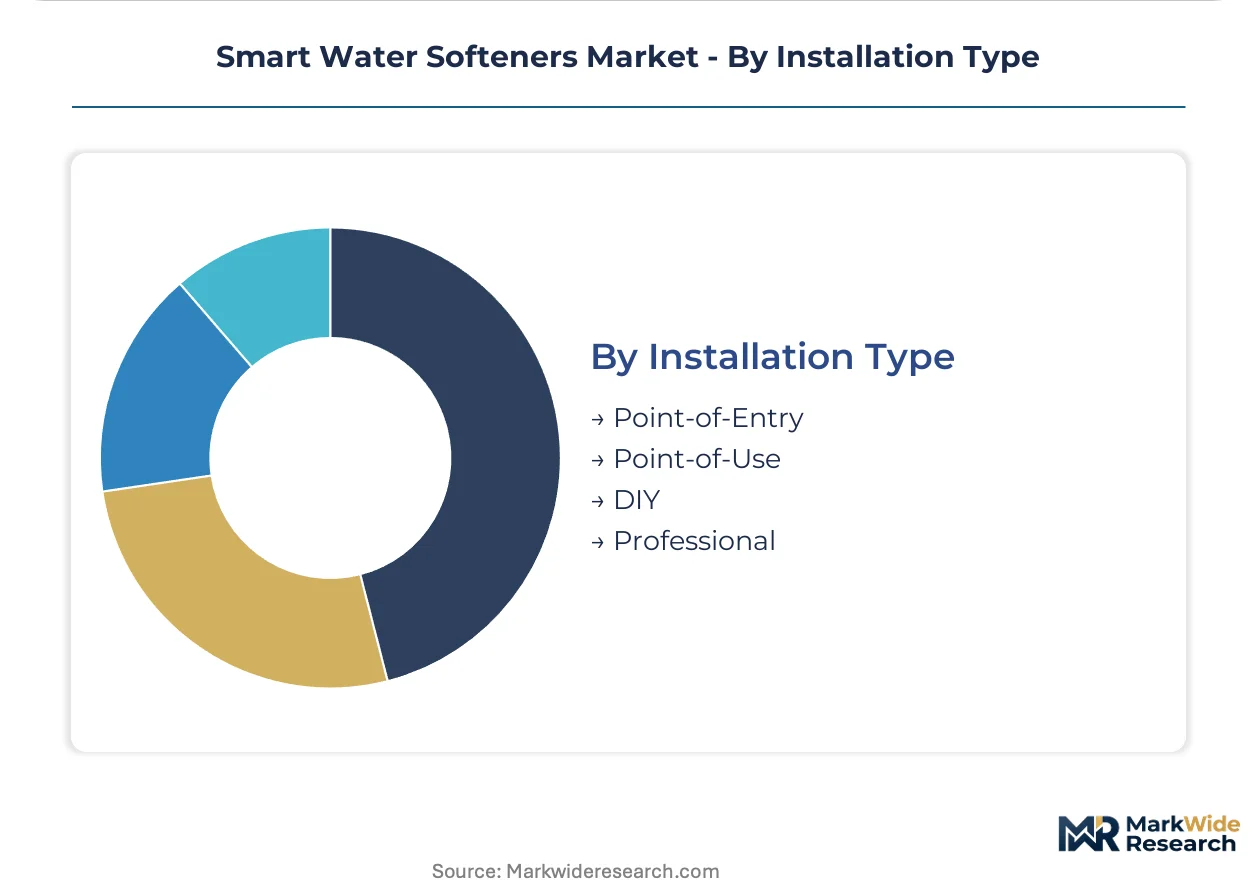
Installation Type:
Customer type stratification separates transactional retail from recurring-service infrastructure relationships with lifetime value divergence.
- Point-of-Entry:Whole-home systems installed at water main entry protect all downstream plumbing and appliances. Pre-1990 residential infrastructure in legacy Sun Belt suburbs often lacks adequate drainage for modern regeneration cycles, requiring costly retrofit assessments.
- Point-of-Use:Under-sink or appliance-dedicated units serve kitchen-scale demand without whole-home commitment; reverse osmosis alternatives capture share in this segment.
- DIY:Big-box retail channels with plug-and-play connectivity target homeowner self-installation; limited to smaller-capacity units with simplified resin bed configurations.
- Professional:Licensed plumber installation with permit compliance and warranty validation dominates commercial and multi-family contexts where liability exposure concentrates.
Professional installation holds the dominant share, while Point-of-Entry is gaining share fastest as developers standardize whole-home softening in new construction specifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German resin manufacturers supply specialty ion-exchange media to North American assemblers, while Chinese control valve fabricators export to Southeast Asian system integrators. Trade flows concentrate on component specialization rather than finished system exports.
United States
Multi-family developers in the Austin-San Antonio corridor specify connected softening systems for new construction at scale. The EPA maintains voluntary water quality guidelines that California, Texas, and Florida reference for hardness threshold adoption. Las Vegas property managers deploy IoT-enabled fleets for centralized oversight across hospitality portfolios.
Germany
Specialty ion-exchange resin production clusters around industrial chemical corridors serving global water treatment OEMs. REACH chemical registration requirements govern resin formulation disclosure and environmental safety documentation. Bavarian control valve manufacturers supply precision components to premium system assemblers across Europe.
China
Domestic hard water zones in northern provinces drive demand for cost-optimized ion-exchange systems in residential construction. The Ministry of Ecology and Environment enforces wastewater discharge standards that constrain brine output from municipal treatment facilities. Zhengzhou and Tianjin house concentrated manufacturing of resin media and electronic control modules.
India
Rapid urbanization in Delhi-NCR and Bengaluru creates demand for compact softening units in high-rise residential towers. The Bureau of Indian Standards issues water quality specifications that influence state-level municipal treatment mandates. Gujarat chemical manufacturers produce locally formulated resin media for cost-sensitive system assemblers.
Japan
Aging infrastructure in Osaka and Nagoya prefectures drives replacement demand for space-efficient softening systems. METI efficiency standards regulate standby power consumption for connected appliances. Tokyo-based property management firms pilot predictive maintenance platforms for multi-building residential portfolios.
Smart Water Softeners Market Vendor Landscape
Player mix skews toward diversified industrial conglomerates with captive water treatment divisions. Market structure concentrates around three to five integrated system providers with direct-service networks, while regional specialists compete on installation speed and local code expertise. Strategic archetypes include full-stack manufacturers controlling resin and valve production, service-intensive operators monetizing recurring maintenance contracts, and modular platform vendors enabling capacity scaling without full replacement. Dominant competitive moves span backward integration into resin media production and partnerships with utility rebate program administrators.
Among diversified industrial operators, 3M Company and A. O. Smith Corporation occupy positions spanning filtration and softening portfolios. Pentair PLC exemplifies the modular architecture approach, while Culligan International Company and EcoWater Systems LLC represent service-network-centric models. These five entities anchor the competitive structure, with BWT Holding GmbH and Whirlpool Corporation sitting within adjacent appliance and treatment ecosystems that occasionally overlap in residential specification channels.
| Leading Market Players |
|---|
| 3M Company |
| A. O. Smith Corporation |
| Culligan International Company |
| EcoWater Systems LLC |
| Pentair PLC |
| BWT Holding GmbH |
| Whirlpool Corporation |
| Kinetico Incorporated |
| GE Appliances |
| Others |
Supply Flow & Price Mechanics
Capacity utilization at German resin manufacturers shapes price floors across North American system assemblers, while bulk procurement by multi-family developers compresses per-unit installation economics below retail replacement thresholds. Scale concentration in specialty ion-exchange media production creates asymmetric pricing power that flows downstream into connected system bundles.
Pricing Analysis
Next-generation IoT-enabled systems command substantial premiums over timer-based legacy units and emerging salt-free crystallization alternatives. Pricing stratifies across premium connected platforms, standard sensor-enabled configurations, and economy-grade non-connected hardware. Cost compression in the salt-based tier is intensifying as developers negotiate volume discounts for new construction specifications. Single-family retrofits in Texas and Florida exhibit highest price sensitivity, while Arizona and Nevada multi-family portfolios prioritize total cost of ownership over upfront hardware spend.
Supply Chain Analysis
Inbound logistics costs from German chemical corridors and Chinese control valve fabricators fluctuate with transatlantic container availability and Rhine River water levels affecting barge transport. Specialty ion-exchange resin production centers on Germany and China, while electronic control module assembly concentrates in Zhengzhou and Tianjin. North American system integrators face single-source vulnerability for high-purity resin formulations certified under NSF/ANSI standards. Distribution runs through direct-service technician networks for commercial installations and big-box retail channels for residential DIY segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity in predictive maintenance algorithm development and certified resin media formulation separates viable competitors from commodity assemblers in this infrastructure-mandated demand environment.
For Market Incumbents: Fortify captive supply positions in ion-exchange resin production to offset freight cost volatility from German manufacturers. Deepen direct-service technician density across the Austin-San Antonio corridor before national developers consolidate procurement relationships with single-source vendors. Salt-free template-assisted crystallization technology from emerging competitors threatens to displace ion-exchange share in California coastal municipalities. For New Entrants and Emerging Players: Anchor in Texas Hill Country private-well installations where municipal treatment capacity lags behind residential construction velocity. The unpenetrated stock of legacy homes with pre-1990 drainage infrastructure represents the most penetrable segment for retrofit specialists offering simplified installation protocols. Pursue utility rebate program partnerships in Arizona and Nevada to reduce effective customer acquisition costs below incumbent benchmarks. For Investors and Strategic Acquirers: Regional installation specialists with certified technician networks and established municipal permitting relationships present the most defensible acquisition archetype for long-term viability. These assets compound value through recurring service contract revenue rather than transactional hardware margins. Monitor California Title 22 enforcement patterns and Florida coastal corrosion code amendments as inflection indicators for salt-free technology adoption velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Media | Captive supply of NSF-certified ion-exchange resin insulates German freight cost exposure. |
| Predictive Salt Logistics Platform | Algorithmic consumption forecasting enables subscription revenue displacing transactional hardware sales. |
| Utility Rebate Program Partnership | Arizona and Nevada incentive alignment reduces customer acquisition costs for connected system vendors. |
| Template-Assisted Crystallization Certification | California Title 22 compliance unlocks environmentally regulated municipal permit specifications. |
| Multi-Family Developer Consolidation | Bulk procurement relationships with national builders secure specification across Sun Belt new construction. |
Methodological Framework
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with multi-family property managers, licensed plumbing contractors, municipal water quality officials, and OEM procurement leads at system manufacturers. Secondary validation drew from EPA water quality guidance documents, California Title 22 brine discharge regulations, Florida building code amendments, Department of Energy efficiency standards, and customs trade data on resin media imports. Bottom-up unit economics from installation cost structures were triangulated against top-down market sizing from housing construction permits and replacement cycle assumptions.
Across the analysis window, the forecasting framework modeled volume and value outputs through segmented projections across salt-based, salt-free, magnetic, and dual-tank product architectures. Technology tiers spanning basic sensors through full IoT integration, end-user categories from residential through agricultural, and installation types from point-of-entry through professional deployment were each assigned distinct growth trajectories. CAGRs were derived from regression analysis correlating housing starts, groundwater hardness measurements, and regulatory adoption timelines. Resin bed replacement cycles and connected service subscription attach rates served as industry-specific forecast inputs.
Material uncertainties — abrupt shifts in state-level salinity discharge rules, supply disruptions in German resin production, or interest rate impacts on multi-family construction financing — sit outside the modeled envelope. Forecasts reflect documented assumptions regarding regulatory enforcement consistency and resin media pricing stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water Treatment Systems
Water Purification Tablets Market
Water Treatment Systems
Solar Water Purifiers Market
Water Treatment Systems
Home Water Softener System Market
Water Treatment Systems
Solar Aerators Market
Water Treatment Systems
Global Residential Water Treatment Devices Market
Water Treatment Systems
Solar Powered Sanitation Device Market
Water Treatment Systems
Mobile Water Treatment Services Market
Water Treatment Systems
Europe Water Purifier Market
Water Treatment Systems
Water Purifier/Filter Market
Water Treatment Systems
Africa Zero Liquid Discharge System Market
Water Treatment Systems
Industrial Wastewater Treatment Equipment Market
Water Treatment Systems
Malaysia Water Purifier Market
Water Treatment Systems
Water Treatment As a Service Market
Water Treatment Systems
South America Residential Water Treatment Equipment Market
Water Treatment Systems
Plant Based Water Filter Market
Water Treatment Systems
Residential Water Treatment Equipment Market