
 Electro-Oxidation System Market | 2026-2036
Electro-Oxidation System Market Size, Share, and Industry Trends Forecast 2026-2036
Electro-Oxidation System Market Insights
Municipal wastewater authorities are rotating procurement toward electro-oxidation systems as manufacturing plants defer capital spending on in-house treatment. Hydroleap leverages its Singapore R&D base to anchor electrochemical oxidation technology across Southeast Asian industrial zones. Industrie De Nora S.p.A. dominates dimensionally stable anode manufacturing, sustaining a captive supply of coated titanium electrodes that competitors struggle to replicate. Siemens competes through digital integration, extending its automation portfolio into real-time process control for continuous electro-oxidation trains.
Electro-oxidation systems deploy direct or indirect anodic reactions to mineralize recalcitrant organics and precipitate dissolved metals, typically operating at current densities between 10 and 200 mA per square centimeter with boron-doped diamond or mixed metal oxide anodes. The primary commercial purpose centers on destroying persistent pollutants resistant to biological treatment, particularly in industrial effluent streams containing pharmaceutical residuals, per- and polyfluoroalkyl substances, or high-salinity process water. Continuous systems lead installed base value due to throughput advantages in petrochemical and textile applications, while modular units represent the fastest-expanding category as remote oil and gas extraction sites seek containerized, deployable treatment capacity. Integrated solutions capture the deepest margin pools by bundling pretreatment, electro-oxidation, and post-polishing under single-vendor performance contracts.
China's MEE enforces Class I discharge standards that effectively mandate advanced oxidation for specific chemical oxygen demand thresholds, while the US EPA incorporates electro-oxidation into emerging contaminant roadmaps for perfluorinated compound destruction. The EU REACH framework restricts certain electrode coating chemistries, reshaping supplier qualification requirements for European water utilities. Stakeholders must monitor evolving electrode material regulations and decide whether to develop in-house anode production or lock in long-term supply agreements with specialized coaters.
Market Dynamics
Electrode coating chemistry concentration among specialized titanium anode manufacturers is compressing supplier options and forcing water utilities into long-term offtake negotiations before project financing closes.
Growth Catalysts
- China MEE Class I Standards:Municipal wastewater plants in the Yangtze River Delta must deploy advanced oxidation to meet chemical oxygen demand thresholds for heavy metal discharge.
- PFAS destruction mandates:The US EPA incorporates electro-oxidation into emerging contaminant roadmaps, creating specification pull from municipal utilities and Department of Defense remediation sites.
- Boron-doped diamond anode maturation:Synthetic diamond electrode manufacturing scales beyond laboratory quantities, reducing unit costs for high-current-density applications in pharmaceutical effluent.
Market Restraints
- Ruthenium-iridium oxide supply concentration:Dimensionally stable anode coating chemistries depend on refined platinum-group metal feedstocks concentrated in South African and Russian processing corridors.
- Capital intensity of continuous trains:Petrochemical and textile installations require multi-reactor configurations with automated rectifier banks and real-time conductivity monitoring systems.
- EU REACH coating restrictions:The framework limits certain mixed metal oxide formulations, forcing European utilities to qualify alternative electrode suppliers through extended compatibility testing.
Strategic Opportunities
- Remote oil and gas extraction:Containerized modular units address produced water treatment at shale plays and offshore platforms lacking pipeline infrastructure to centralized facilities.
- Semiconductor fab cluster expansion:Malaysia and Vietnam attract back-end packaging investment, creating demand for high-purity water recycling systems with electrochemical polishing stages.
- Digital twin integration:Real-time process control platforms converge with electro-oxidation hardware, enabling predictive anode replacement and energy optimization contracts.
Industry Challenges
- Electrochemical engineering talent scarcity:Design of bipolar electrode configurations and current distribution modeling requires specialized expertise concentrated among aging academic programs.
- Legacy SCADA integration friction:Municipal utilities operate decades-old distributed control systems that resist API connectivity with modern oxidation process analytics.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electro-Oxidation System Market |
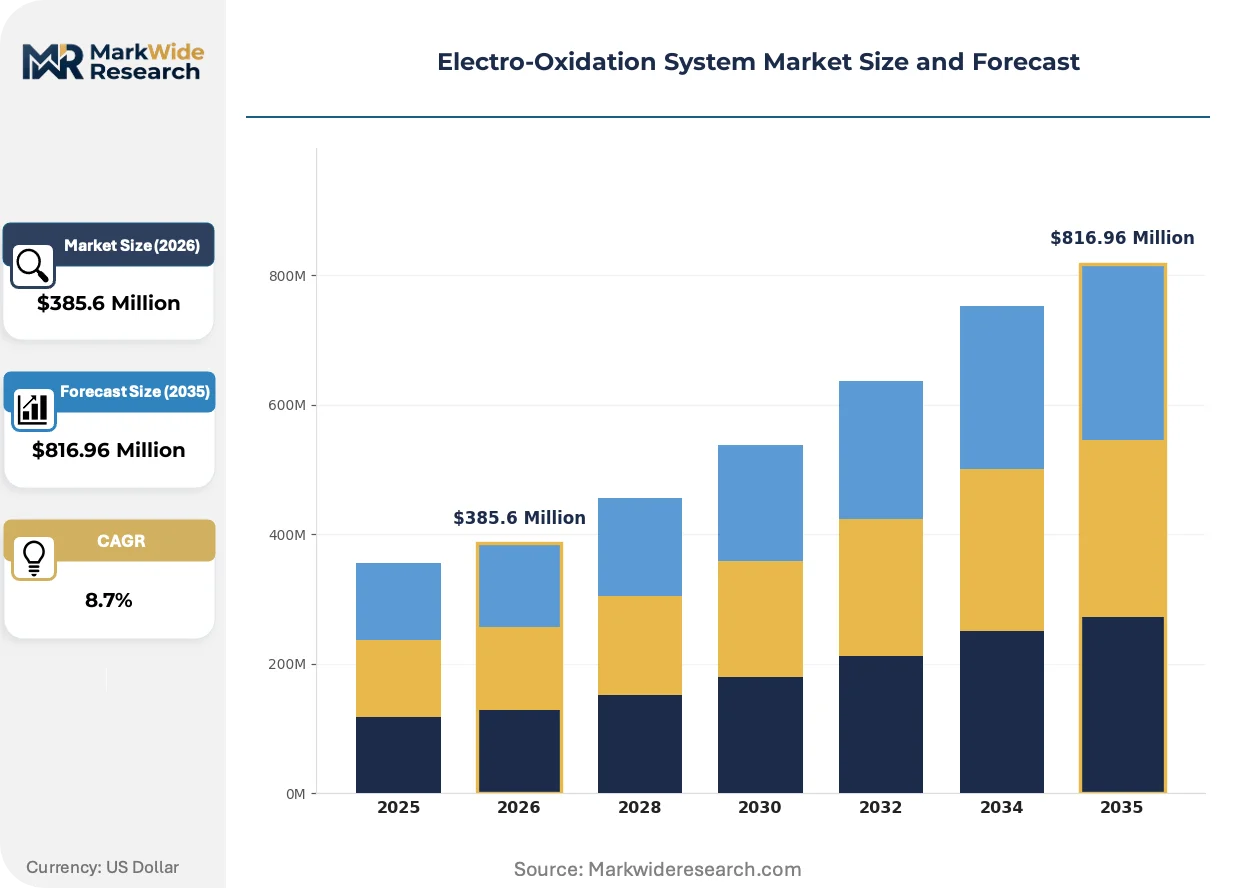
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $816.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Batch Systems, Continuous Systems, Modular Units, Integrated Solutions Application: Wastewater Treatment, Chemical Processing, Groundwater Remediation, Industrial Effluent Management End User: Municipalities, Manufacturing Plants, Oil & Gas, Food & Beverage Technology: Electrochemical Oxidation, Photoelectrochemical Oxidation, Hybrid Systems, Advanced Oxidation Processes |
| Companies Covered | Aqua Pulsar, Hydroleap, Yasa ET (Shanghai) Co., Ltd., OVIVO USA LLC, E-FLOC, Siemens, Electrolytica Technologies, Industrie De Nora S.p.A., Veolia Water Technologies & Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electro-Oxidation System Market Trends and Innovations
Electrode architecture and system packaging are converging toward deployable formats that decouple treatment capacity from permanent civil infrastructure, altering competitive dynamics between equipment vendors and engineering contractors.
Boron-doped diamond electrode fabrication is miniaturizing through chemical vapor deposition advances that reduce substrate size requirements while maintaining current distribution uniformity. Remote mining camps and military forward operating bases now specify skid-mounted units with diamond anodes for on-site leachate and graywater processing. This format compression is collapsing the traditional boundary between permanent municipal installations and temporary industrial deployment.
The EU F-Gas Regulation phases down hydrofluorocarbon refrigerants used in electrode cooling subsystems, compelling manufacturers to redesign thermal management around natural refrigerants or liquid cooling loops. Industrial effluent treatment plants in Germany and the Netherlands face retrofit deadlines that synchronize with scheduled anode replacement cycles. European water utilities now prioritize equipment vendors with demonstrated compliance documentation over lower-cost alternatives lacking certification.
Performance contracting is displacing capital purchase models as municipal authorities transfer operational risk to equipment suppliers under guaranteed effluent quality agreements. Southeast Asian industrial zone operators favor vendors offering electrode replacement and energy management as bundled service lines. This shift concentrates procurement authority among integrated solution providers with regional service footprints rather than component specialists.
Electro-Oxidation System Market Segmentation
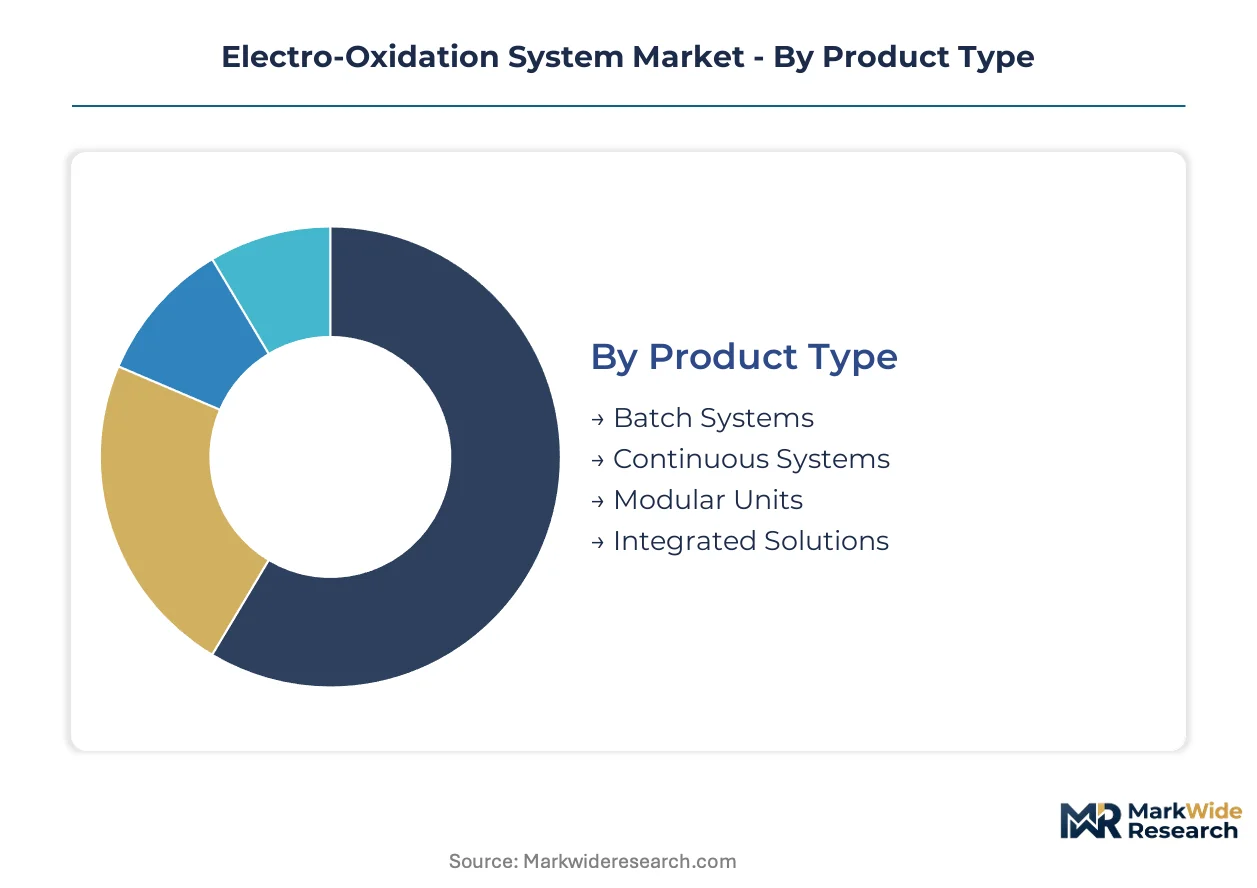
Electro-oxidation system procurement channels diverge sharply by deployment scale and operational risk allocation. Municipal authorities favor integrated solutions with performance guarantees, while industrial operators self-source modular units for rapid deployment.
Product Type:
Channel mix varies by system architecture: continuous trains flow through engineering-procurement-construction contractors, while modular units move via direct OEM sales to remote site operators.
- Continuous Systems:Multi-reactor configurations with automated rectifier banks dominate petrochemical and textile installations requiring sustained throughput. Yangtze River Delta municipal plants specify these for Class I discharge compliance, though capital intensity limits adoption among smaller utilities.
- Modular Units:Containerized, deployable formats address produced water treatment at shale plays and offshore platforms lacking pipeline infrastructure. Oil and gas extraction sites in Southeast Asia specify skid-mounted configurations with rapid commissioning timelines.
- Batch Systems:Intermittent operation suits pharmaceutical R&D facilities and pilot-scale validation before continuous train investment.
- Integrated Solutions:Bundled pretreatment, electro-oxidation, and post-polishing under single-vendor performance contracts capture municipal procurement authority.
By volume, Continuous Systems lead. By growth pace, Modular Units are expanding most quickly.
Application:
Cost tier stratification separates permanent infrastructure investments from contingent remediation spending, with industrial effluent commanding premium pricing over municipal baseline systems.
- Industrial Effluent Management:High-salinity process water and persistent pollutant streams from semiconductor fabrication require boron-doped diamond anodes operating at elevated current densities. China's MIIT discharge limits for heavy metals are rotating Yangtze River Delta manufacturing plants toward electrochemical treatment retrofits.
- Wastewater Treatment:Municipal plants deploy electro-oxidation as tertiary polishing for pharmaceutical residuals and emerging contaminants. US EPA roadmaps for PFAS destruction are pulling specification from utilities and Department of Defense remediation sites.
- Groundwater Remediation:Pump-and-treat configurations address chlorinated solvent plumes at former industrial facilities.
- Chemical Processing:On-site destruction of recalcitrant organics reduces off-site disposal liability for specialty chemical manufacturers.
Industrial Effluent Management commands the highest unit margins. Wastewater Treatment offers the largest addressable installation base.
End User:
Customer type determines procurement modality: municipalities issue performance contracts, while manufacturing plants favor capital purchase with service add-ons.
- Municipalities:Wastewater authorities under MEE Class I standards in China and EPA emerging contaminant mandates in the US are rotating procurement toward guaranteed effluent quality agreements. Southeast Asian operators increasingly bundle electrode replacement and energy management as service lines.
- Oil & Gas:Remote extraction sites lacking centralized facility access specify containerized units for produced water treatment. Malaysia and Vietnam back-end packaging investment is creating demand for high-purity water recycling with electrochemical polishing.
- Manufacturing Plants:Semiconductor fabs and textile operations self-source continuous trains, though capital deferral is shifting some demand toward municipal offtake arrangements.
- Food & Beverage:High-organic-load effluent streams employ electro-oxidation for color and odor removal before biological treatment.
Municipalities represent the largest installed base. Oil & Gas is gaining share fastest.
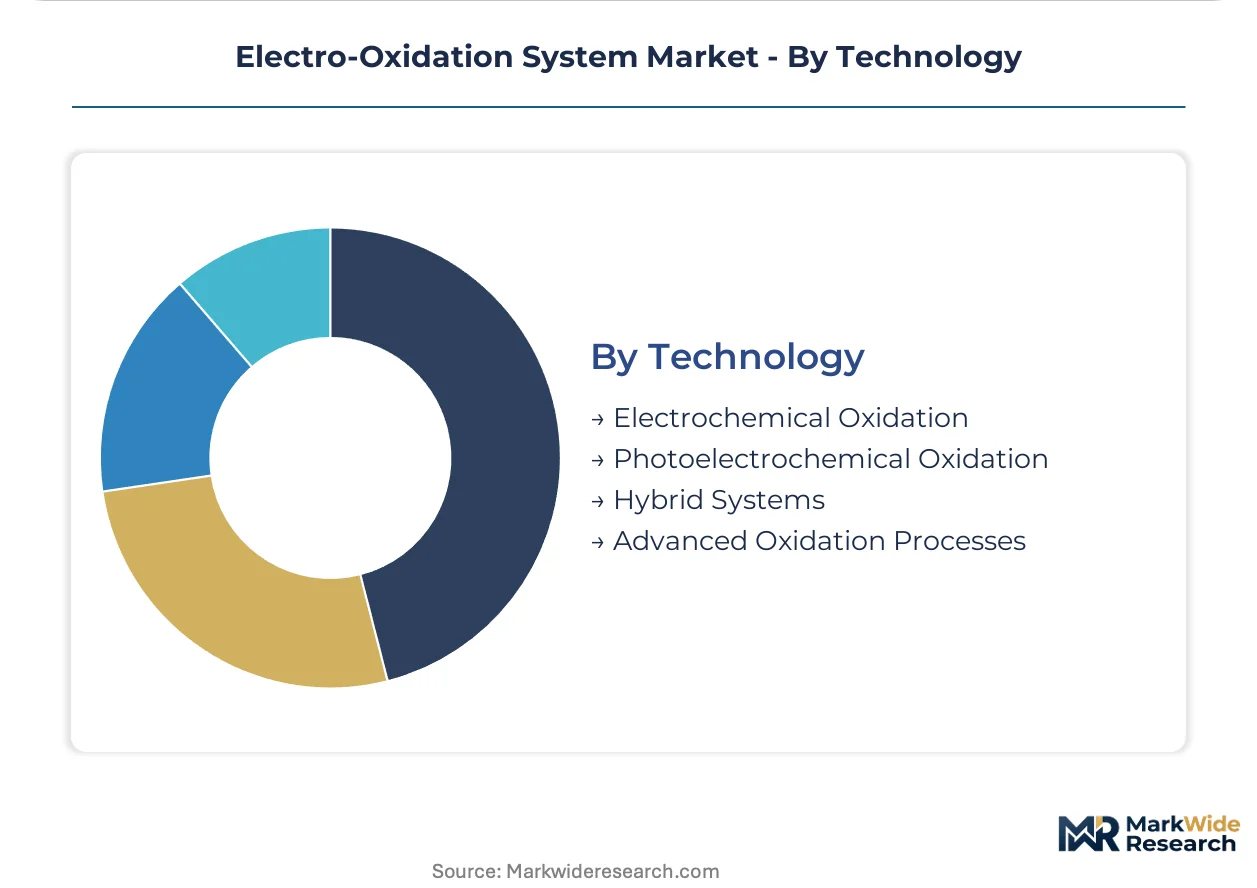
Technology:
Supply concentration in coated titanium anode manufacturing favors established electrochemical oxidation platforms over emerging photoelectrochemical alternatives.
- Electrochemical Oxidation:Direct and indirect anodic reactions mineralize recalcitrant organics at current densities between 10 and 200 mA per square centimeter. Dimensionally stable anode manufacturing concentrates among specialized titanium coaters, compressing supplier options for utilities.
- Advanced Oxidation Processes:Hybrid configurations combining electro-oxidation with ozone or UV achieve synergistic degradation rates for PFAS and pharmaceutical residuals. EU REACH restrictions on certain electrode coating chemistries are forcing qualification of alternative suppliers through extended compatibility testing.
- Photoelectrochemical Oxidation:Light-activated catalyst integration remains largely pre-commercial for industrial-scale deployment.
- Hybrid Systems:Sequential or simultaneous coupling of electrochemical and biological treatment stages optimizes energy efficiency for high-COD streams.
Electrochemical Oxidation dominates current installations. Advanced Oxidation Processes show the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Yangtze River Delta's dense waterway network underwrites China's dominance in electro-oxidation deployment, while the Rhine-Main-Danube corridor connects German industrial demand to specialized anode suppliers.
China
Semiconductor fabrication expansion and municipal wastewater retrofits drive procurement in the Yangtze River Delta. MEE Class I discharge standards mandate advanced oxidation for chemical oxygen demand thresholds. Suzhou and Wuxi municipal plants are retrofitting aging biological treatment trains with continuous electro-oxidation systems.
United States
Department of Defense remediation sites and municipal utilities pull specification for PFAS destruction systems. EPA roadmaps for perfluorinated compound treatment are creating procurement mandates. Michigan and North Carolina military installations are deploying containerized units for groundwater remediation.
Germany
Industrial effluent treatment plants face synchronized retrofit deadlines from EU F-Gas Regulation phase-downs and scheduled anode replacement cycles. REACH restrictions on mixed metal oxide formulations force extended supplier qualification. The Ruhr industrial corridor is prioritizing vendors with demonstrated compliance documentation.
Japan
High-purity water recycling requirements from semiconductor back-end packaging investment are creating demand for electrochemical polishing stages. METI efficiency standards favor integrated solutions with predictive maintenance capabilities. Kyushu's fab cluster is specifying bundled service contracts over capital purchases.
Singapore
The Jurong Island petrochemical complex and municipal NEWater facilities anchor Southeast Asian demand for advanced oxidation. PUB's stringent industrial discharge permits are rotating procurement toward performance-guaranteed systems. Hydroleap's R&D base is scaling electrochemical oxidation technology across Malaysian and Vietnamese industrial zones.
Electro-Oxidation System Market Competitive Landscape
Listed leaders compete with private specialists across electrode coating chemistry and system integration capabilities. Market structure concentrates around three tiers: diversified industrial conglomerates with automation portfolios, specialized electrochemical equipment fabricators, and regional system integrators. Strategic archetypes include captive anode manufacturers, digital-integrated solution providers, and modular deployable unit specialists. Competitive moves center on long-term electrode supply agreements and performance-based service contracting.
Within the specialized electrochemical tier, Industrie De Nora S.p.A. and Hydroleap occupy distinct geographic and technological positions. Siemens represents the automation-integrated conglomerate archetype. Veolia Water Technologies & Solutions sits within the utility-facing service provider category. Yasa ET (Shanghai) Co., Ltd. exemplifies the Asia-Pacific regional fabricator model. OVIVO USA LLC anchors the North American municipal specialist segment.
| Leading Market Players |
|---|
| Aqua Pulsar |
| Hydroleap |
| Yasa ET (Shanghai) Co., Ltd. |
| OVIVO USA LLC |
| E-FLOC |
| Siemens |
| Electrolytica Technologies |
| Industrie De Nora S.p.A. |
| Veolia Water Technologies & Solutions |
| Others |
Pricing and Supply Chain Analysis
Long-term electrode offtake contracts lock in both supply access and price visibility for water utilities navigating South African and Russian platinum-group metal volatility. Municipal authorities in the Yangtze River Delta negotiate multi-year agreements with specialized titanium coaters before project financing closes, compressing supplier options while stabilizing input costs against ruthenium-iridium oxide fluctuations.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels segments the electro-oxidation system market by anode chemistry and service bundling. Premium tiers capture boron-doped diamond configurations with predictive maintenance contracts, while economy positioning targets batch systems for pharmaceutical R&D facilities. Cost compression in the standard tier intensifies as Chinese fabricators scale mixed metal oxide production. Municipal wastewater authorities exhibit highest price sensitivity due to budget cycle constraints, whereas semiconductor fabs prioritize performance guarantees over capital expenditure minimization.
Supply Chain Analysis
Extended lead times for coated titanium substrates stretch procurement timelines to 16-24 weeks, forcing utilities into advance inventory commitments. Manufacturing concentrates in Italy, China, and Japan, with Industrie De Nora S.p.A. anchoring European supply and Yasa ET serving Asia-Pacific demand. The supply chain draws from South African platinum-group metal refiners and Japanese titanium substrate producers, creating single-source vulnerability for ruthenium-iridium oxide feedstocks. Distribution runs through engineering-procurement-construction contractors for continuous trains and direct OEM sales for modular units.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electro-oxidation system market sits at a platform-economics inflection where digital twin integration creates interoperability moats around predictive anode replacement services. Real-time process control platforms from Siemens and emerging specialists are redefining competitive boundaries between hardware vendors and software-enabled service providers.
For Market Incumbents: Shield proprietary electrode coating chemistries through captive titanium substrate supply agreements and accelerated REACH-compliant formulation R&D. De Nora's dimensionally stable anode manufacturing advantage faces erosion from Chinese coaters scaling boron-doped diamond alternatives; defensive patent thicketing around chemical vapor deposition processes preserves margin pools in high-current-density applications.
For New Entrants and Emerging Players: EU F-Gas Regulation compliance fast-tracks qualify alternative electrode suppliers for German and Dutch industrial effluent treatment retrofits. Containerized modular units for Southeast Asian oil and gas extraction represent the most penetrable white space, with direct OEM sales to remote site operators bypassing EPC contractor channel control. Target performance contracting capabilities bundled with electrode replacement service lines.
For Investors and Strategic Acquirers: Capital is best deployed toward regional system integrators with demonstrated municipal service footprints and digital twin integration capabilities. Long-term viability hinges on 5-10 year performance contract renewal rates rather than initial equipment sales. Watch for inflection when EPA PFAS destruction mandates accelerate municipal procurement beyond current pilot-scale deployment.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Anode Coating | Captive ruthenium-iridium oxide supply reduces dependency on South African refiners. |
| Digital Twin Platform Integration | Siemens extends automation portfolio into predictive anode replacement services. |
| Containerized Modular Unit Expansion | Deployable formats address produced water treatment at remote shale plays. |
| Performance Contracting Transition | Municipal authorities transfer operational risk under guaranteed effluent quality agreements. |
| REACH-Compliant Formulation Development | Alternative electrode chemistries qualify European utilities facing coating restrictions. |
Research Methodology
Desk research of customs/trade data, SEC filings from industrial conglomerates, and MEE regulatory bulletins preceded structured interviews with municipal wastewater procurement directors, semiconductor fab facility engineers, titanium anode coating specialists, and EPC contractor project managers. Primary fieldwork validated secondary estimates of electrode manufacturing capacity and pricing trajectories. Bottom-up unit economics triangulated against top-down market sizing from continuous system and modular unit shipment aggregates.
Variance decomposition across product architecture, application severity, and regional regulatory stringency shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include system format, end-use industry, anode chemistry tier, and service contract structure. CAGRs derived from installed base replacement cycles and greenfield capacity additions, with specific inputs from Yangtze River Delta municipal retrofit timelines and US Department of Defense remediation site procurement schedules.
The analysis sits within stated boundaries; outcomes outside sustained platinum-group metal price stability or accelerated EPA mandate implementation would require recalibration. Forecasts reflect assumptions regarding electrode coating chemistry concentration and digital twin adoption curves. Revision becomes warranted when boron-doped diamond manufacturing scale crosses cost-parity thresholds with mixed metal oxide alternatives.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water Treatment Systems
UV Water Sterilizer Market
Water Treatment Systems
Indonesia Gravity-Based Water Purifier Market
Water Treatment Systems
Solar Water Purifiers Market
Water Treatment Systems
Self-Cleaning Filters Market
Water Treatment Systems
Residential Water Treatment Equipment Market
Water Treatment Systems
Portable Water Purifier Market
Water Treatment Systems
Industrial Wastewater Treatment Equipment Market
Water Treatment Systems
South America Residential Water Treatment Equipment Market
Water Treatment Systems
Water Ionizers Market
Water Treatment Systems
Global Solar Water Desalination Plants Market
Water Treatment Systems
Global Residential Water Treatment Devices Market
Water Treatment Systems
Portable Filtration System Market
Water Treatment Systems
Water Purifier/Filter Market
Water Treatment Systems
Mobile Water Treatment Services Market
Water Treatment Systems
Packaged Water Treatment System Market
Water Treatment Systems
Africa Zero Liquid Discharge System Market