
 Residential Water Treatment Equipment Market | 2026-2036
Residential Water Treatment Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Residential Water Treatment Equipment Market Outlook
China is reconfiguring residential water treatment manufacturing capacity through expanded ceramic membrane and activated carbon filter production zones. Pentair plc leverages its North American distribution network to sustain dominant positioning in whole-house systems. Kent RO Systems anchors its competitive stance through deep specialization in compact reverse osmosis units engineered for hard-water geographies. Eureka Forbes competes aggressively on brand recognition and direct-to-home service infrastructure across South Asian metropolitan corridors.
Residential water treatment equipment encompasses point-of-use and point-of-entry systems designed to remove particulates, dissolved solids, biological contaminants, and chemical impurities from household water supplies, typically achieving filtration thresholds from 0.1 to 0.0001 microns depending on technology. These systems serve the essential purpose of protecting consumer health, preserving appliance longevity, and improving sensory water quality for domestic consumption. Reverse osmosis systems command the largest installed base among product types due to their proven efficacy against dissolved heavy metals and total dissolved solids, though UV purifiers represent the fastest-expanding category as consumers prioritize chemical-free disinfection. Point-of-entry installation dominates new construction channels where builders pre-integrate treatment infrastructure, while point-of-use systems capture higher margins through recurring filter replacement revenue.
The EPA Safe Drinking Water Act and NSF/ANSI standards govern contaminant thresholds and product certification requirements in the United States, directly determining which technologies qualify for consumer trust and retail placement. India's BIS drinking water specifications and China's GB standards for household water purification impose parallel compliance burdens that filter out uncertified competitors and elevate R&D investment requirements. The EU Drinking Water Directive and REACH chemical restrictions add further layers of material safety and performance transparency obligations for equipment sold across European markets. Stakeholders must monitor how fragmented municipal infrastructure investment across emerging economies will shape the relative attractiveness of centralized versus decentralized treatment solutions.
Market Dynamics
Replacement cycles for aging municipal infrastructure are compressing as EPA Safe Drinking Water Act enforcement tightens contaminant thresholds, forcing homeowners to adopt point-of-use filtration ahead of planned utility upgrades.
Growth Catalysts
- EPA Lead and Copper Rule revisions:Stricter corrosion control requirements are accelerating whole-house system installations in older single-family dwellings across the United States.
- Ceramic membrane miniaturization:Advances in compact filtration geometry are enabling countertop reverse osmosis units with reduced wastewater ratios.
- Groundwater arsenic contamination:Bengal Delta basin geology is driving sustained replacement demand for multi-stage purification in eastern Indian households.
Market Restraints
- Activated carbon supply concentration:Coconut shell charcoal sourcing clusters in Sri Lankan and Indonesian processing zones, exposing filter manufacturers to monsoon-driven raw material volatility.
- RO membrane technical limitation:Mineral stripping reduces total dissolved solids below WHO taste-preference thresholds, requiring remineralization stages that add cost and complexity.
- California Proposition 65 litigation exposure:Warning label requirements for brass and bronze components create compliance friction for point-of-entry system distributors.
Strategic Opportunities
- Vietnam urban periphery underpenetration:Ho Chi Minh City satellite districts lack centralized treatment, creating first-mover advantage for decentralized UV-RO combination systems.
- Smart home integration:IoT-enabled filter life monitoring and automatic reordering are converging with residential automation platforms.
- India PLI scheme for white goods:Production-linked incentives for component manufacturing are reducing landed costs for domestic assembly operations.
Industry Challenges
- NSF/ANSI 58 certification timeline:Third-party validation for reverse osmosis performance claims requires 12-18 month testing cycles that delay product launches.
- Legacy plumbing integration:Retrofit installations in pre-1980s housing stock encounter incompatible pipe threading and pressure specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Residential Water Treatment Equipment Market |
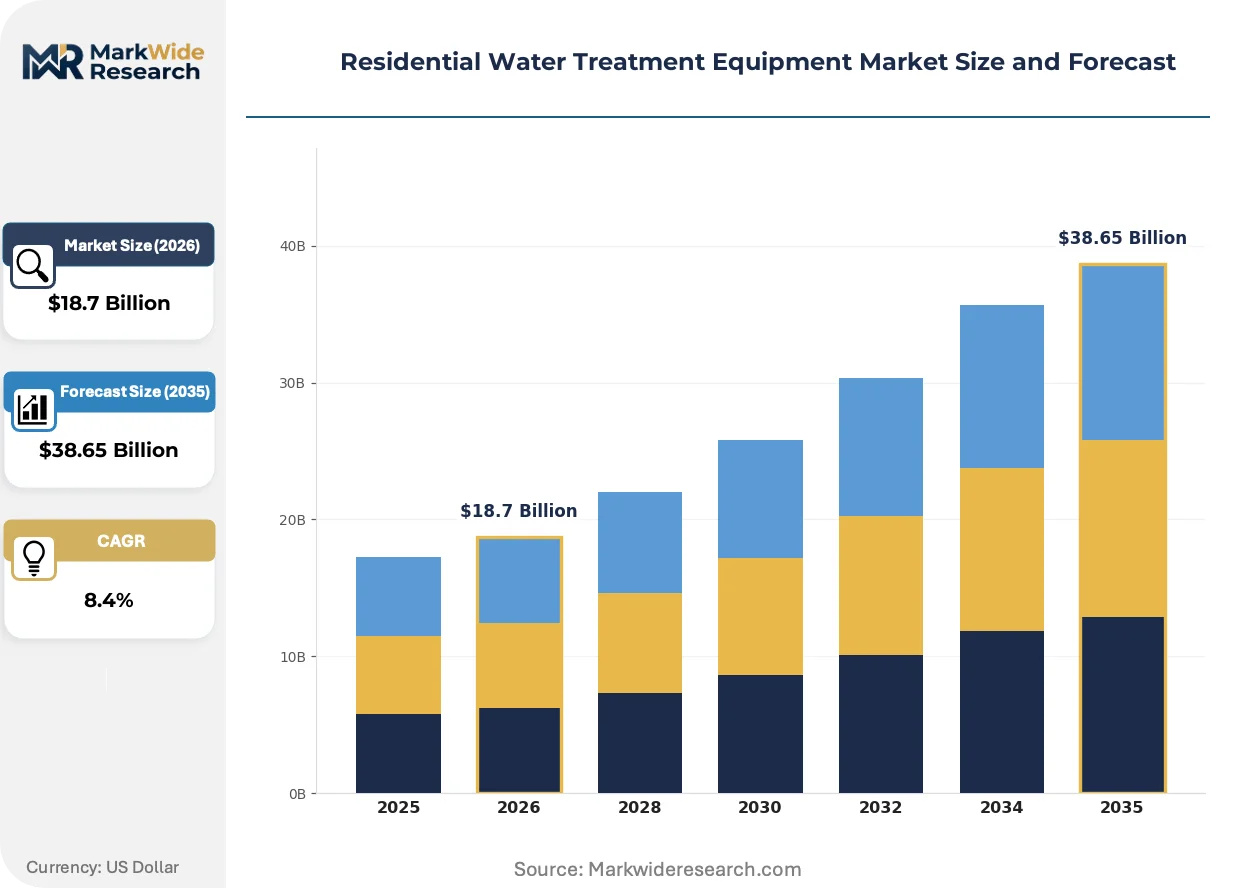
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Water Softeners, Reverse Osmosis Systems, Filtration Units, UV Purifiers Technology: Activated Carbon, Ceramic, Ion Exchange, Reverse Osmosis Installation: Point-of-Use, Point-of-Entry, Under-Sink, Whole House End User: Homeowners, Tenants, Property Managers, Builders |
| Companies Covered | A. O. Smith Corporation, Culligan International, Pentair plc, Kent RO Systems, Eureka Forbes, 3M Company, Ecolab Inc., Watts Water Technologies, Panasonic Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Residential Water Treatment Equipment Market Strategic Shifts
Equipment manufacturers are pivoting from hardware-only sales toward recurring revenue architectures, embedding connectivity and consumable logistics into core product design.
Tankless direct-flow reverse osmosis systems are eliminating storage vessel contamination risk while delivering on-demand filtration at 400-600 gallons per day capacity. Urban apartment dwellers in Shanghai and Shenzhen are adopting these units at accelerating rates. The technology is rendering obsolete traditional tank-based configurations that dominated residential installations for three decades.
REACH chemical restrictions on per- and polyfluoroalkyl substances are forcing membrane manufacturers to reformulate hydrophobic coatings and sealing gaskets. European importers now demand full material disclosure documentation upstream through Asian contract manufacturers. Countertop and under-sink categories face the steepest compliance cost escalation as re-certification cycles compress.
Homeowners are unbundling installation from equipment purchase, sourcing direct-to-consumer brands through e-commerce platforms and engaging independent plumbers for placement. This pattern disrupts traditional dealer networks that captured margin through bundled service contracts. The shift is most pronounced in United States metropolitan markets where Amazon and big-box retail have established same-day delivery infrastructure for replacement cartridges.
Residential Water Treatment Equipment Market Segmentation
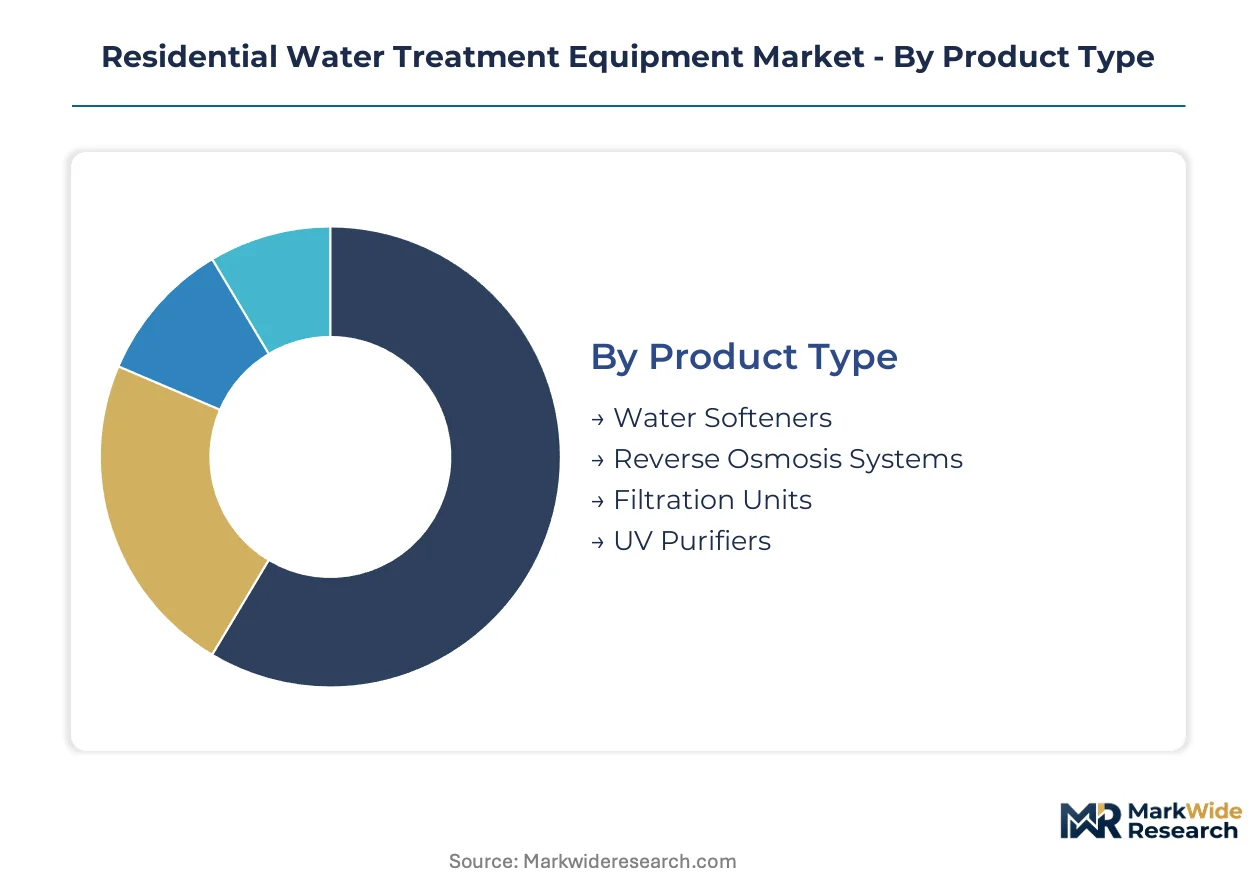
Segmentation in residential water treatment equipment reveals how technology selection, installation constraints, and buyer economics fragment demand across distinct purchasing contexts. Equipment specifications diverge sharply between retrofit replacements and new construction, while end-user sophistication determines willingness to absorb upfront capital versus operational expenditure trade-offs.
Product Type:
Cost tier stratification separates commodity filtration from premium multi-stage systems, with price elasticity varying by contaminant threat perception and household income brackets.
- Reverse Osmosis Systems:Multi-stage membrane configurations achieving 0.0001-micron filtration thresholds against dissolved heavy metals and total dissolved solids. Demand concentrates in Indian urban households confronting groundwater contamination from arsenic and fluoride geologies, with compact under-sink units displacing traditional tank-based configurations.
- UV Purifiers:Chemical-free disinfection through ultraviolet germicidal irradiation at 254 nanometers wavelength. Fastest-expanding category in Vietnamese metropolitan peripheries where centralized treatment infrastructure remains incomplete, driven by consumer preference for non-chemical purification methods.
- Water Softeners:Ion exchange resin systems targeting calcium and magnesium hardness reduction. Deployed predominantly in North American Great Lakes and Southwest regions with elevated groundwater mineral content.
- Filtration Units:Mechanical and adsorptive media configurations spanning sediment pre-filtration to activated carbon polishing. Serve as entry-level point-of-use solutions in European rental housing markets.
Reverse osmosis systems command the established base. The steepest expansion runs through UV purifiers.
Technology:
Application suitability determines technology selection, with contaminant chemistry and flow rate requirements dictating membrane versus media-based approaches.
- Reverse Osmosis:Semi-permeable thin-film composite membranes operating at 50-800 psi feed pressure, rejecting 95-99% of dissolved ionic species. Dominates in Chinese coastal cities where municipal source water carries elevated total dissolved solids from seawater intrusion.
- Activated Carbon:Coconut shell-derived granular or block configurations with 500-1500 square meter per gram surface area for organic compound adsorption. Fastest-expanding trajectory in European markets confronting pesticide and pharmaceutical trace contamination from agricultural runoff.
- Ceramic:Sintered diatomaceous earth or aluminosilicate matrices with absolute pore ratings of 0.2-1.0 microns for bacterial retention. Preferred in South Asian rural installations lacking reliable electrical supply for powered alternatives.
- Ion Exchange:Synthetic resin beads functionalized with sodium or hydrogen ions for hardness reduction and selective heavy metal capture. Standard specification for whole-house point-of-entry installations in North American suburban developments.
Reverse osmosis technology anchors the installed capacity base. Activated carbon is climbing the fastest on contaminant-specific regulatory tightening.
Installation:
Volume throughput and spatial constraints differentiate installation categories, with new construction channels enabling pre-integration that retrofit markets cannot replicate.
- Point-of-Entry:Whole-house treatment positioned at main water service entry, processing 10-20 gallons per minute for all domestic uses. Builders in United States Sun Belt metropolitan areas pre-install these systems to differentiate new construction offerings and command price premiums.
- Point-of-Use:Localized treatment at single taps or appliances, typically 0.5-2 gallons per minute capacity. Dominates replacement cycles in aging Japanese urban housing stock where legacy plumbing cannot support centralized retrofit.
- Under-Sink:Concealed installations beneath kitchen cabinetry with dedicated faucet dispensing. Standard configuration for reverse osmosis systems in Indian middle-class apartments where countertop space commands premium valuation.
- Whole House:Synonymous with point-of-entry in North American terminology, though sometimes distinguished by capacity class above 15 gallons per minute for estate-scale residences.
Point-of-entry installations capture new construction margin. Point-of-use systems are gaining share fastest through recurring filter replacement revenue models.
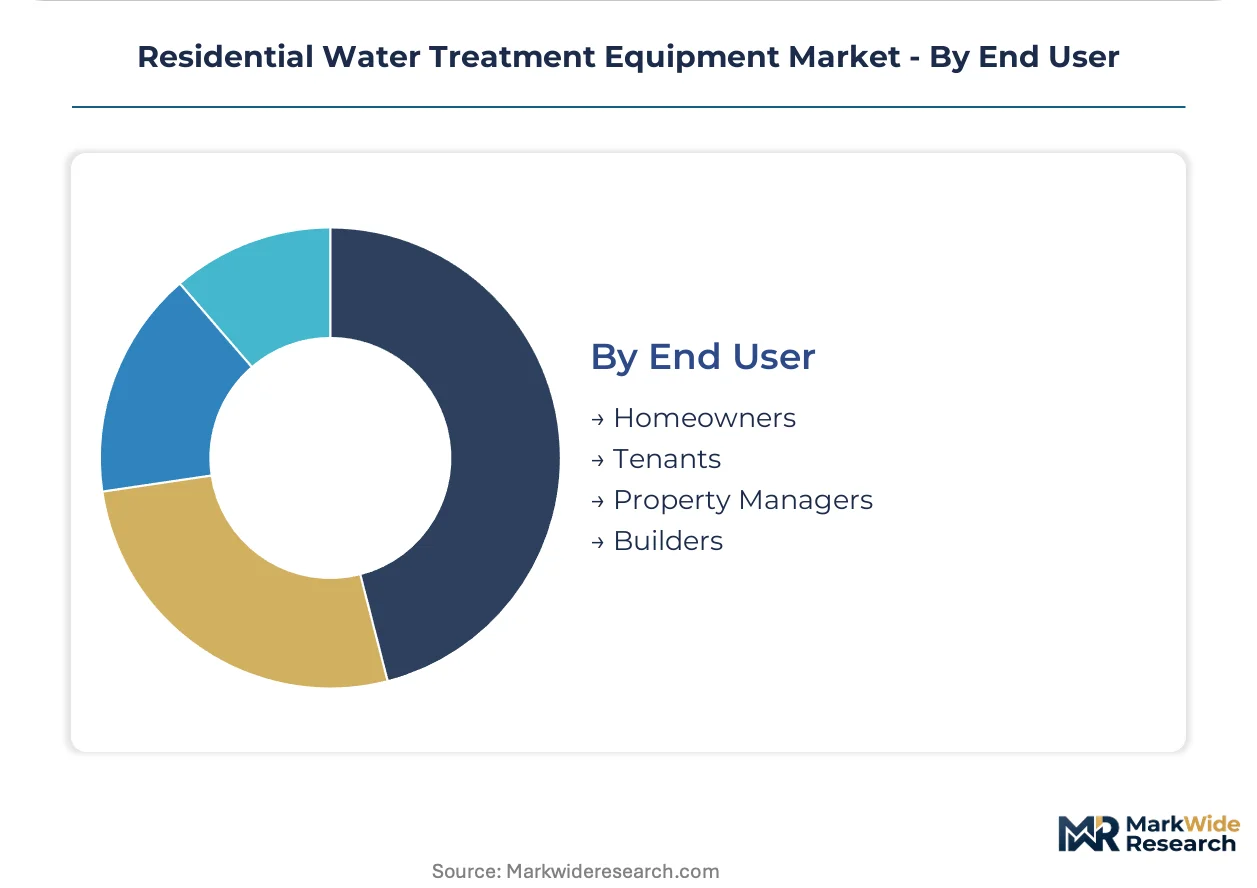
End User:
Customer type segmentation reveals divergent procurement authority, technical sophistication, and horizon preferences that reshape channel economics and service bundling requirements.
- Homeowners:Owner-occupiers with full capital decision authority and long-term residency horizons driving whole-system investments with 10-15 year depreciation expectations. Concentrated in United States single-family detached dwellings with private well dependencies.
- Builders:Production home developers and custom residential contractors specifying treatment infrastructure as standard or upgrade features. Fastest-expanding purchaser category in Chinese tier-two cities where municipal water quality variability has entered consumer consciousness.
- Property Managers:Multi-unit residential facility operators balancing capital expenditure constraints against tenant complaint mitigation. Standardize on point-of-entry systems in United States garden-style apartment complexes to reduce per-unit maintenance dispatch frequency.
- Tenants:Rental occupants with limited installation authority and mobility-driven preference for portable or non-permanent solutions. Drive countertop and faucet-mounted filtration demand in European metropolitan rental markets with strict lease modification prohibitions.
Homeowners command the established base. Builders represent the steepest expansion trajectory through pre-integration in new construction pipelines.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: Indian households prioritize compact reverse osmosis units for groundwater remediation, while North American buyers favor whole-house point-of-entry systems for municipal water conditioning.
United States
Homeowners in older single-family dwellings drive replacement demand as EPA Lead and Copper Rule revisions tighten corrosion control requirements. The EPA Safe Drinking Water Act enforcement compresses infrastructure upgrade timelines, pushing point-of-use adoption ahead of utility improvements. Sun Belt metropolitan builders pre-integrate treatment systems to command new construction premiums.
China
Coastal cities confront elevated total dissolved solids from seawater intrusion, accelerating thin-film composite membrane deployment. GB standards for household water purification impose compliance burdens that filter uncertified competitors. Shanghai and Shenzhen apartment dwellers adopt tankless direct-flow reverse osmosis configurations at accelerating rates.
India
Groundwater arsenic and fluoride contamination in the Bengal Delta basin sustains multi-stage purification replacement cycles. BIS drinking water specifications elevate R&D investment requirements for domestic assembly. Urban and semi-urban households in Delhi-NCR and Maharashtra deploy compact RO units as middle-class incomes rise.
Germany
REACH chemical restrictions on per- and polyfluoroalkyl substances force membrane coating reformulation. ECHA oversight adds material safety documentation layers for European importers. Processing zones in Baden-Württemberg concentrate activated carbon filter production for pesticide and pharmaceutical trace removal.
Vietnam
Ho Chi Minh City satellite districts lack centralized treatment infrastructure, creating first-mover openings for UV-RO combination systems. Consumer preference for chemical-free disinfection methods accelerates ultraviolet germicidal irradiation adoption. Metropolitan periphery underpenetration rewards decentralized equipment deployment.
Residential Water Treatment Equipment Market Competitive Environment
Capability concentration sits with specialized membrane and filtration technology developers; scale advantage sits with diversified industrial conglomerates with established distribution infrastructure. The vendor base separates into three strategic archetypes: integrated water technology platforms, regional purification specialists, and component-focused contract manufacturers. Consolidation pressure runs through M&A activity targeting recurring filter replacement revenue streams, while capacity expansion concentrates in Asian manufacturing zones serving cost-sensitive emerging markets.
Within the integrated platform tier, Pentair plc and 3M Company occupy positions anchored by North American distribution networks and material science portfolios respectively. Kent RO Systems exemplifies the regional specialist archetype through deep concentration in compact reverse osmosis engineering. These three entities represent divergent competitive vectors: scale-driven infrastructure access, diversified technology licensing, and geography-specific product optimization.
| Leading Market Players |
|---|
| A. O. Smith Corporation |
| Culligan International |
| Pentair plc |
| Kent RO Systems |
| Eureka Forbes |
| 3M Company |
| Ecolab Inc. |
| Watts Water Technologies |
| Panasonic Corporation |
| Others |
Value Chain & Pricing Dynamics
Coconut shell charcoal processing clusters in Sri Lanka and Indonesia concentrate activated carbon supply, anchoring margin capture with filter manufacturers who command long-term offtake contracts while spot-market buyers absorb monsoon-driven raw material volatility.
Pricing Analysis
Long-term offtake agreements dominate procurement for coconut shell activated carbon, insulating major filter manufacturers from spot price swings while smaller assemblers face commodity exposure. Three-tier pricing structure across premium NSF/ANSI-certified, standard BIS-compliant, and economy non-certified levels separates institutional buyers from cost-conscious household segments. Pricing pressure stems from ceramic membrane miniaturization reducing per-unit production costs at the premium tier. Tenants in European rental markets exhibit highest price sensitivity, preferring portable faucet-mounted units, whereas North American homeowners with private well dependencies absorb whole-house system premiums.
Supply Chain Analysis
Extended payment terms from 90 to 120 days characterize supplier-finance arrangements between Sri Lankan coconut shell processors and Chinese membrane manufacturers, compressing working capital for mid-tier assemblers. Thin-film composite membrane production concentrates in China, South Korea, and Japan, while activated carbon sourcing feeds from Southeast Asian processing zones. The supply chain draws from polyamide resin, titanium dioxide for UV lamps, and ion exchange resin beads as critical inputs. Single-source vulnerability runs through monsoon-dependent coconut harvest cycles in Sri Lanka. Distribution runs through North American dealer networks, Indian direct-to-home service infrastructure, and Chinese e-commerce platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Residential water treatment equipment is approaching a platform-economics inflection as IoT-enabled filter life monitoring converges with residential automation ecosystems, creating interoperability lock-in that favors early movers who embed consumable logistics into connected hardware.
For Market Incumbents: Insulate recurring revenue streams by backward integration into coconut shell carbon processing and ceramic membrane manufacturing, reducing exposure to Sri Lankan supply volatility. Lock in NSF/ANSI 58 certification pipelines to delay competitive entrants. Prioritize channel control through exclusive service technician networks in Indian metropolitan corridors, where Kent RO Systems and Eureka Forbes have established defensible direct-to-home infrastructure.
For New Entrants and Emerging Players: Vietnam's Ho Chi Minh City satellite districts offer the most penetrable geographic white space, with incomplete centralized treatment infrastructure and consumer preference for chemical-free UV-RO combinations. Target countertop tankless direct-flow configurations for urban apartment dwellers in Shanghai and Shenzhen, where space constraints and seawater intrusion concerns create addressable demand. Pursue e-commerce-first distribution with independent plumber partnerships to bypass entrenched dealer networks.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional purification specialists holding dense service technician networks but lacking connected product platforms. Five-to-ten year viability favors acquirers who can retrofit IoT architectures onto installed bases for recurring filter replacement monetization. Monitor EPA Safe Drinking Water Act enforcement intensity as the signal for replacement cycle acceleration in North American single-family dwellings.
| Strategic Initiative | Industry Significance |
|---|---|
| IoT Platform Integration | Enables automatic filter reordering through Amazon Alexa and Google Home ecosystems. |
| Backward Integration into Membrane Manufacturing | Captures margin from thin-film composite production in Chinese coastal zones. |
| Direct-to-Consumer Channel Expansion | Bypasses traditional dealer networks through same-day delivery infrastructure. |
| Certification Investment Pipeline | Accelerates NSF/ANSI 58 validation cycles to preempt regulatory tightening. |
| Geographic Manufacturing Footprint | Exploits India's PLI scheme for white goods to reduce landed assembly costs. |
Study Parameters
Initial hypotheses were tested against primary input from residential water treatment equipment manufacturers, municipal utility planning officers, independent plumbing contractors, and e-commerce category managers, and refined through secondary validation against EPA enforcement records, BIS certification databases, Indian customs import data, and NSF/ANSI testing protocols. Bottom-up triangulation across point-of-use and point-of-entry installation volumes converged with top-down market sizing from regional regulatory filings and trade association disclosures.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling technology selection, installation constraints, end-user procurement authority, and regional regulatory cluster as core segmentation dimensions. CAGRs were derived from fitted growth curves against historical replacement cycle data and projected infrastructure investment gaps. Forecast inputs incorporated groundwater contamination geochemistry from the Bengal Delta basin and REACH chemical restriction compliance cost escalation for European membrane coatings.
The forecast holds incumbent behavior within observed patterns; aggressive moves by connected-hardware platforms or direct-to-consumer brands would shift outcomes beyond modeled ranges. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Water Treatment Systems
South America Residential Water Treatment Equipment Market
Water Treatment Systems
Self-Cleaning Filters Market
Water Treatment Systems
Portable Filtration System Market
Water Treatment Systems
Shower Water Filters Market
Water Treatment Systems
Global RO Water Purifier Market
Water Treatment Systems
Solar Powered Sanitation Device Market
Water Treatment Systems
Global Solar Water Desalination Plants Market
Water Treatment Systems
GCC Water Purifier Market
Water Treatment Systems
Asia-Pacific Water Purifier Market
Water Treatment Systems
Solar Aerators Market
Water Treatment Systems
Commercial Water Filter Market
Water Treatment Systems
US Water Purifier Market
Water Treatment Systems
Smart Water Softeners Market
Water Treatment Systems
UV Water Sterilizer Market
Water Treatment Systems
Industrial Wastewater Treatment Equipment Market
Water Treatment Systems
Indonesia Gravity-Based Water Purifier Market