
 Rigid Plastic Packaging Market | 2026-2036
Rigid Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Rigid Plastic Packaging Market Intelligence
The gap between premium barrier-grade rigid plastic packaging and commodity-grade alternatives is expanding. Amcor Plc leverages its global manufacturing footprint to dominate high-performance bottle segments for pharmaceuticals. Berry Global Inc. anchors North American supply through vertical integration into resin conversion. Silgan Holdings Inc. specializes in metal-plastic hybrid closures that sustain margin pools in food packaging.
Rigid plastic packaging comprises formed polymer structures—typically polyethylene, polypropylene, PVC, or polystyrene—with wall thicknesses exceeding 0.010 inches, manufactured through injection molding, blow molding, or thermoforming to protect contents from mechanical damage, moisture ingress, and oxidation. Bottles lead volume across food and beverage end uses where carbonation retention and shelf stability matter. Containers represent the fastest-growing structural category as e-commerce fulfillment demands stackable, crush-resistant formats with integrated tamper evidence.
EPA guidelines on recycled content mandates and FDA food-contact notification requirements shape resin selection and migration testing protocols for domestic suppliers. EFSA's ongoing revisions to plastic regulation 10/2011 tighten specific migration limits for additives across European supply chains. REACH compliance for monomer and additive registration creates market access barriers that favor large compounders with dedicated regulatory affairs teams. Stakeholders must monitor how state-level extended producer responsibility laws in California and Maine reshape collection infrastructure economics before committing to recycled-content targets.
Market Dynamics
Extended producer responsibility laws in California and Maine are forcing resin converters to internalize collection infrastructure costs, while EFSA's tightening migration limits under Regulation 10/2011 reshape formulation choices across European supply chains.
Growth Catalysts
- EFSA Regulation 10/2011 Revisions:Tighter specific migration limits for additives are accelerating reformulation toward bio-based barrier polymers in food-contact applications.
- E-commerce Fulfillment Demands:Crush-resistant containers with integrated tamper evidence are displacing flexible alternatives in last-mile logistics.
- China and India Manufacturing Clusters:Polyethylene demand concentrates in Asia-Pacific conversion facilities serving regional beverage bottlers.
Market Restraints
- Resin Price Volatility:Naphtha feedstock fluctuations compress margins for commodity-grade blow molders without backward integration into resin production.
- Collection Infrastructure Gaps:Inadequate post-consumer sorting capacity in the United States limits FDA-compliant recycled content availability for food-contact applications.
- Aluminum Can Substitution:Beverage brands seeking carbon neutrality credentials are pivoting toward infinitely recyclable metal packaging in premium segments.
Strategic Opportunities
- Pharmaceutical Barrier Bottles:High-performance cyclic olefin polymers are penetrating injectable drug packaging where glass breakage risk drives conversion.
- California SB 54 Mandate:Recycled-content targets create first-mover advantage for compounders with FDA food-contact notification pathways.
- Digital Printing Convergence:Direct-to-object inkjet systems enable lot-level traceability without label substrates, collapsing decoration steps.
Industry Challenges
- Migration Testing Bottlenecks:EFSA notification timelines stretch 18-24 months for novel additives, delaying product launches.
- Multi-Material Separation:Metal-plastic hybrid closures complicate mechanical recycling streams, requiring infrastructure reconfiguration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rigid Plastic Packaging Market |
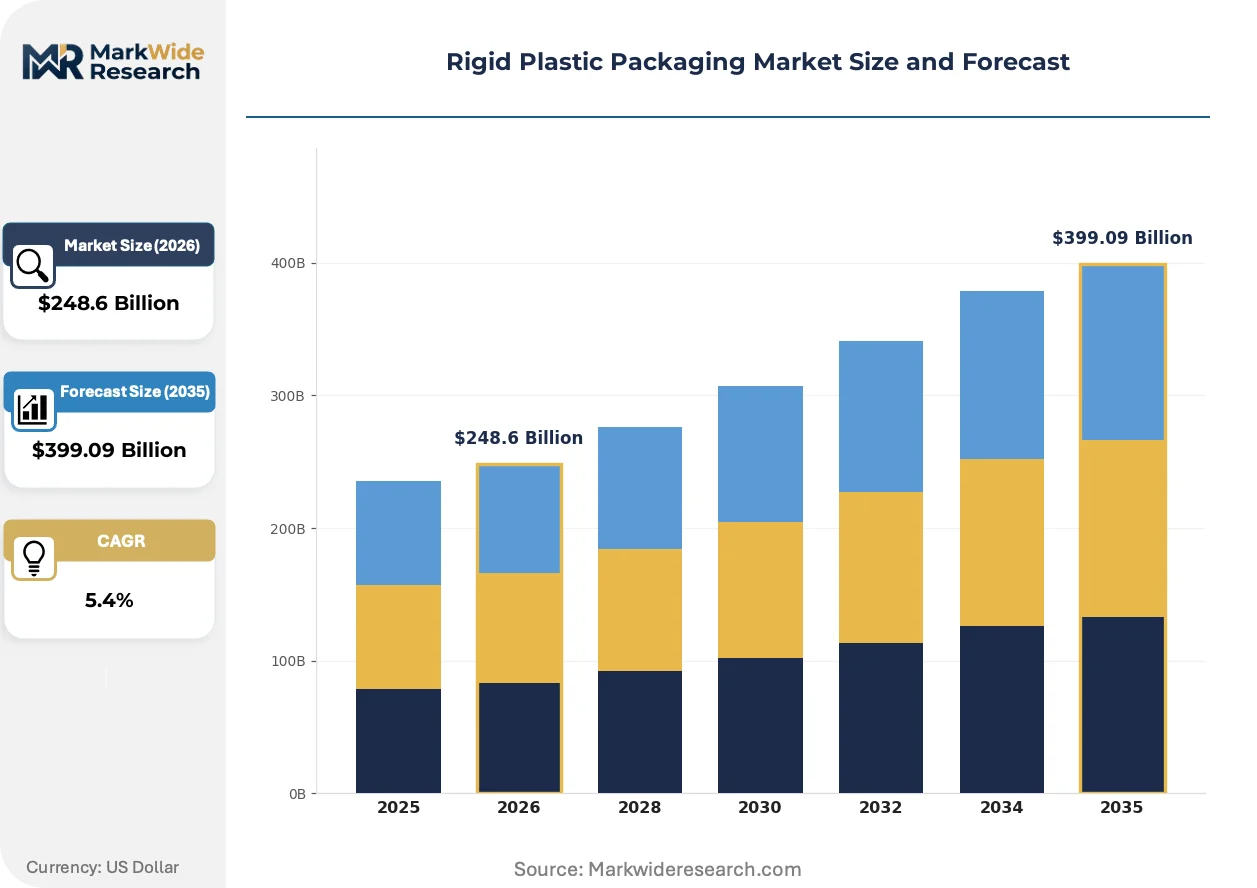
| Market Size in 2026 | $248.6 Billion |
| Market Size in 2035 | $399.09 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Containers, Jars, Trays End Use Industry: Food & Beverage, Pharmaceuticals, Personal Care, Household Products Material: Polyethylene, Polypropylene, Polyvinyl Chloride, Polystyrene Distribution Channel: Online, Supermarkets, Convenience Stores, Distributors |
| Companies Covered | Amcor Plc, Berry Global Inc., Silgan Holdings Inc., Sonoco Products Company, ALPLA Werke, DS Smith Plc, Pactiv Evergreen Inc., Graham Packaging Company Inc., Plastipak Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rigid Plastic Packaging Market Strategic Shifts & Innovations
Active and intelligent packaging systems are penetrating pharmaceutical and fresh-produce segments, while digital manufacturing tools compress development cycles for custom container geometries.
Mono-material polyethylene terephthalate barrier structures are expanding into oxygen-sensitive food categories previously reserved for multilayer laminates. Modified atmosphere protein packagers in Germany and the Netherlands are piloting these formats for case-ready meat. The technology is expanding into shelf-stable prepared meals where retort compatibility and clarity requirements once blocked polymer substitution.
REACH compliance for monomer and additive registration creates market access barriers favoring large compounders with dedicated regulatory affairs teams. European supply chains face documentation burdens for substances of very high concern that mid-scale converters cannot absorb. Pharmaceutical packaging manufacturers are responding by consolidating supplier bases to reduce audit complexity.
Brand owners are compressing packaging development cycles from 18 months to 8 weeks through digital prototyping and rapid tooling. Beverage and personal care marketers in the United States are deploying 3D-printed blow mold prototypes for shelf-testing before steel tooling commitment. This behavioral shift concentrates volume with converters possessing in-house simulation and additive manufacturing capabilities.
Rigid Plastic Packaging Market Segmentation
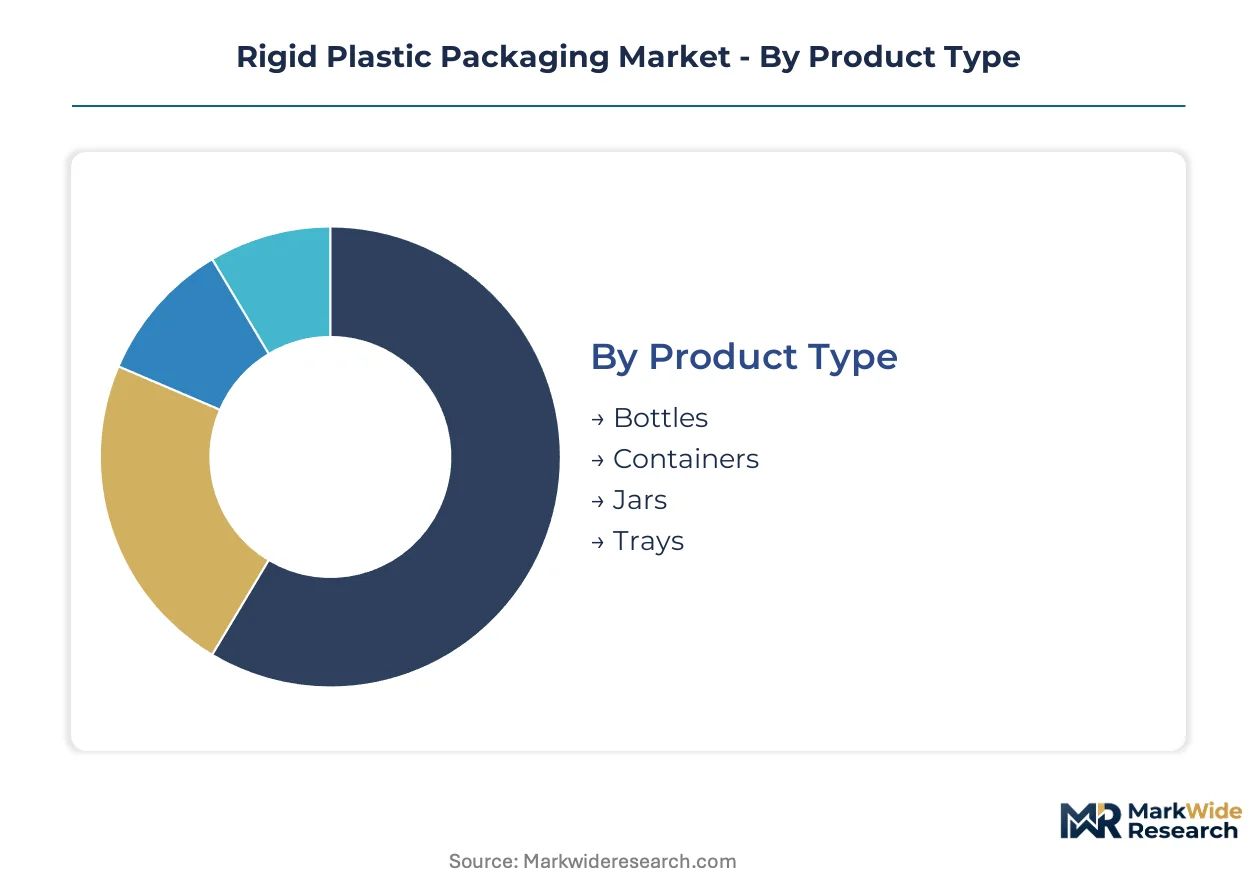
Segmentation in rigid plastic packaging separates volume-driven commodity formats from specialized barrier applications where regulatory compliance commands premium positioning. Material selection and end-use specifications dictate converter capabilities and margin structures across each category.
Product Type:
Buyers prioritize stackability, carbonation retention, and tamper evidence when selecting structural formats for their supply chains.
- Bottles:Blow-molded structures with calibrated neck finishes for closure compatibility dominate carbonated beverage and pharmaceutical liquid applications. Carbonation retention requirements in North American bottling plants sustain polyethylene terephthalate demand despite aluminum substitution pressure.
- Containers:Injection-molded or thermoformed rectangular formats with integrated handles and crush-resistant ribs serve e-commerce fulfillment and bulk food distribution. German and Dutch modified atmosphere protein packagers are piloting mono-material barrier versions for case-ready meat.
- Jars:Wide-mouth cylindrical formats with threaded closures accommodate viscous food products and personal care creams. Screw-cap compatibility and clarity requirements favor polypropylene in United States retail channels.
- Trays:Shallow thermoformed structures with compartmentalization support ready-meal and fresh-produce presentation. European supermarkets specify recyclable mono-material specifications to meet extended producer responsibility targets.
Volume sits with bottles; growth tilts toward containers.
End Use Industry:
Regulatory stringency and shelf-stability requirements create divergent qualification barriers across customer verticals.
- Food & Beverage:Oxygen barrier and migration compliance specifications dominate material selection for shelf-stable and refrigerated applications. FDA food-contact notification requirements and EFSA Regulation 10/2011 revisions force reformulation cycles in United States and European supply chains.
- Pharmaceuticals:High-performance cyclic olefin polymers are penetrating injectable drug packaging where glass breakage risk and moisture ingress protection drive conversion. United States parenteral drug manufacturers demand validated barrier performance with documented extractables profiles.
- Personal Care:Aesthetic clarity and chemical resistance specifications favor polyethylene terephthalate and polypropylene for premium cosmetic positioning. Digital printing compatibility enables lot-level traceability without label substrates.
- Household Products:Chemical resistance and child-resistant closure compatibility dominate bleach and cleaning formulation packaging. Commodity-grade high-density polyethylene serves volume applications with limited barrier requirements.
Food and beverage commands current volume; pharmaceuticals deliver the steepest expansion trajectory.
Material:
Resin selection balances cost position against barrier performance and regulatory acceptance for food-contact applications.
- Polyethylene:High-density and linear low-density grades provide chemical resistance and processability for bottles and containers. Manufacturing clusters in China and India concentrate conversion capacity for regional beverage bottlers.
- Polypropylene:Clarified grades offer glass-like transparency with retort compatibility for shelf-stable prepared meals. European supply chains favor this material for circular economy targets due to established mechanical recycling streams.
- Polyvinyl Chloride:Declining share in food-contact applications due to EFSA and FDA scrutiny of plasticizer migration limits. Remaining demand concentrates in pharmaceutical blister packaging where barrier properties are irreplaceable.
- Polystyrene:Crystal and high-impact grades serve thermoformed trays and disposable cutlery where cost minimization outweighs environmental positioning. California and Maine extended producer responsibility laws accelerate substitution pressure.
Polyethylene anchors volume; polypropylene gains share fastest.
Distribution Channel:
Channel selection determines order configuration, lead time tolerance, and technical service intensity required from converters.
- Online:Direct procurement platforms enable small-brand access to custom tooling with compressed development cycles. United States beverage marketers deploy 3D-printed blow mold prototypes sourced through digital channels before steel tooling commitment.
- Supermarkets:Private-label specification power drives standardization toward recyclable mono-material formats. German retail chains mandate recycled-content thresholds that reshape converter resin procurement.
- Convenience Stores:High-velocity replenishment demands favor regional converters with rapid turnaround capabilities. Single-serve beverage bottles dominate procurement volumes in this channel.
- Distributors:Inventory pooling and technical consultation services support mid-scale brand owners without direct converter relationships. European distributors consolidate fragmented converter bases to reduce audit complexity for pharmaceutical customers.
Distributors handle current volume; online channels are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Pearl River Delta manufacturing corridor concentrates polyethylene terephthalate conversion capacity for beverage bottlers serving domestic and export markets. FDA and EFSA migration compliance requirements reshape resin procurement decisions across four distinct national production bases.
United States
Beverage brand carbon neutrality commitments drive aluminum substitution pressure in premium segments. California SB 54 mandates recycled-content thresholds that reshape converter procurement toward post-consumer resin streams. Midwest manufacturing clusters around Chicago and Detroit anchor supply for automotive chemical and household product packaging.
Germany
Modified atmosphere protein packagers in the Netherlands and Germany pilot mono-material barrier containers for case-ready meat applications. EFSA Regulation 10/2011 revisions tighten specific migration limits for additives, forcing reformulation cycles among compounders. The Rhine-Ruhr industrial corridor concentrates thermoforming capacity for European retail private-label supply.
China
Domestic beverage consumption sustains blow-molding demand despite export market softening. SAMR food-contact material standards align with GB testing protocols for migration limits. The Yangtze River Delta cluster around Shanghai and Ningbo hosts integrated resin-to-container operations serving regional bottlers.
India
FSSAI packaging material regulations tighten notification requirements for imported resin additives. Maharashtra and Gujarat manufacturing corridors expand polyethylene conversion capacity for edible oil and dairy packaging. Mumbai-Pune industrial belt converters invest in multilayer barrier lines for shelf-stable prepared meals.
Brazil
ANVISA pharmaceutical packaging standards drive barrier validation requirements for parenteral drug containers. São Paulo state concentrates injection-molding capacity for personal care and household chemical applications. Southeast Brazilian converters face collection infrastructure gaps that limit post-consumer resin availability for food-contact applications.
Rigid Plastic Packaging Market Key Industry Players
Capital-heavy producers compete with asset-light designers across tiered capability segments. The market structure consolidates around resin-integrated compounders, specialized barrier technologists, and regional fulfillment converters. Three archetypes dominate: backward-integrated resin producers capturing margin pools, pharmaceutical barrier specialists commanding validation premiums, and e-commerce-optimized container fabricators crushing development cycles. Competitive intensity concentrates on M&A-driven geographic expansion and digital manufacturing tool deployment.
Among North American resin-integrated players, Berry Global Inc. and Pactiv Evergreen Inc. exemplify scale-driven positioning through captive supply chain control. Amcor Plc represents the multinational archetype spanning pharmaceutical barrier and beverage bottle segments with regulatory affairs depth across FDA and EFSA jurisdictions. ALPLA Werke anchors European family-owned consolidation in custom tooling and recycled-content compound development.
| Leading Market Players |
|---|
| Amcor Plc |
| Berry Global Inc. |
| Silgan Holdings Inc. |
| Sonoco Products Company |
| ALPLA Werke |
| DS Smith Plc |
| Pactiv Evergreen Inc. |
| Graham Packaging Company Inc. |
| Plastipak Holdings Inc. |
| Others |
Cost & Logistics Intelligence
Barrier-performance divergence between pharmaceutical-grade cyclic olefin polymers and commodity polyethylene formats manifests in order-magnitude price spreads and captive resin sourcing strategies. FDA food-contact notification requirements and EFSA Regulation 10/2011 compliance timelines concentrate premium pricing power with compounders possessing dedicated regulatory affairs infrastructure, while spot-market naphtha exposure erodes margins for non-integrated blow molders serving beverage and household segments.
Pricing Analysis
Outcome-based pricing anchors pharmaceutical barrier bottle contracts, with converters capturing value through validated extractables profiles and documented moisture ingress protection rather than per-unit resin weight. Three-tier pricing structure across premium barrier, standard food-grade, and economy industrial grades differentiates based on migration testing documentation and recycled-content certification under California SB 54 mandates. Pricing pressure stems from aluminum can substitution in premium beverage segments as brands pursue carbon neutrality credentials. Private-label supermarket buyers exhibit highest price sensitivity, while parenteral drug manufacturers prioritize barrier validation over unit cost.
Supply Chain Analysis
Direct-to-brand procurement channels handle pharmaceutical and premium food accounts demanding validated documentation, while distributor networks aggregate fragmented converter capacity for mid-scale household and personal care buyers. Resin supply concentrates in China, India, and the United States, with polyethylene feedstock drawing from regional naphtha crackers and ethane export terminals. Mono-material barrier container adoption and metal-plastic hybrid closure proliferation complicate mechanical recycling streams. Distribution runs through regional fulfillment converters in the Midwest United States and Rhine-Ruhr corridor serving last-mile e-commerce demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Competitive positioning in rigid plastic packaging is accelerating toward backward integration races, with resin procurement control and FDA notification pathway ownership emerging as the decisive margin levers separating compounders from converters.
For Market Incumbents: Cement barrier technology leadership through cyclic olefin polymer capacity expansion in pharmaceutical segments where glass substitution creates sustained pricing power. Deepen regulatory affairs infrastructure across FDA and EFSA jurisdictions to compress novel additive notification timelines. Aluminum can substitution in premium beverage packaging represents the most acute substitution threat requiring active portfolio rebalancing toward healthcare applications. For New Entrants and Emerging Players: Digital manufacturing tool deployment offers entry wedge into compressed development cycle segments where 3D-printed blow mold prototyping and rapid tooling reduce incumbent scale advantages. Target online procurement channels serving United States beverage marketers with prototype-to-production services before steel tooling commitment. Modified atmosphere protein packaging in Germany and the Netherlands presents the most penetrable white-space for mono-material barrier container pilots. For Investors and Strategic Acquirers: Re-rating potential sits with pharmaceutical barrier specialists given injectable drug packaging conversion tailwinds and regulatory moat depth. Long-term viability over a multi-year horizon favors compounders with integrated resin production and established FDA food-contact notification databases. Monitor EFSA Regulation 10/2011 revision implementation timelines as inflection indicator for reformulation-driven consolidation among mid-scale European converters.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Production | Captive naphtha or ethane feedstock access insulates margins from commodity volatility in beverage packaging. |
| FDA Food-Contact Notification Pathway Investment | Pre-validated additive portfolios accelerate customer product launches and command premium positioning. |
| Digital Manufacturing Tool Deployment | 3D-printed blow mold prototyping compresses development cycles from months to weeks for beverage marketers. |
| Mono-Material Barrier Format Development | Retort-compatible polyethylene terephthalate structures penetrate oxygen-sensitive food categories previously reserved for multilayer laminates. |
| Extended Producer Responsibility Compliance Infrastructure | California SB 54 and Maine EPR mandates require collection cost internalization capabilities for market access. |
Research Approach
Document review covered FDA food-contact notifications, EFSA scientific opinions on Regulation 10/2011, SAMR GB standards filings, and SEC 10-K disclosures from resin-integrated packaging producers, complemented by interviews with blow molding plant managers, pharmaceutical packaging procurement leads, supermarket private-label category buyers, and regulatory affairs directors at compounders. Secondary validation drew from customs trade data, American Chemistry Council resin production statistics, and extended producer responsibility implementation reports from California and Maine agencies. Bottom-up capacity modeling and top-down demand triangulation anchored volume estimates.
Historical production capacity expansion patterns were cross-referenced against expert panel input on resin procurement strategies and reformulation timelines. Segmentation modeling captured product type, end-use industry vertical, material grade tier, and regional regulatory cluster dimensions across the analysis window. CAGRs were derived from regression-based trend extrapolation moderated by aluminum substitution elasticity estimates and pharmaceutical glass-to-plastic conversion rate assumptions.
Several conditions sit outside the modeled scope, including unforeseen polymer technology disruptions, abrupt EFSA migration limit revisions, and state-level EPR law expansions beyond California and Maine. Forecasts reflect assumptions regarding naphtha feedstock price stability and mechanical recycling infrastructure buildout rates. Periodic stress-testing of base assumptions against actual resin procurement cost trajectories and regulatory notification approval timelines is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rigid Packaging
Morocco Rigid Plastic Packaging Market
Rigid Packaging
UAE Rigid Plastic Packaging Market
Rigid Packaging
Italy Rigid Plastic Packaging Market
Rigid Packaging
Rigid Transparent Plastic Market
Rigid Packaging
Mono-Material Trays Market
Rigid Packaging
Rigid Food Containers Market
Rigid Packaging
Global Plastic Rigid IBC Market
Rigid Packaging
GCC Rigid Plastic Packaging Market
Rigid Packaging
Luxury Rigid Box Market
Rigid Packaging
Brazil Rigid Plastic Packaging Market
Rigid Packaging
Nigeria Rigid Plastic Packaging Market
Rigid Packaging
GCC Packaging Market
Rigid Packaging
Colombia Rigid Plastic Packaging Market
Rigid Packaging
Indonesia Rigid Plastic Packaging Market
Rigid Packaging
North America Airless Packaging Market
Rigid Packaging
United Kingdom Rigid Plastic Packaging Market