
 Indonesia Rigid Plastic Packaging Market | 2026-2036
Indonesia Rigid Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Indonesia Rigid Plastic Packaging Market Foresight
Domestic resin producers across Java is repositioning their supply chains to serve rigid packaging converters more directly. PT. Indorama Ventures Indonesia leverages its integrated PET resin-to-preform operations to capture margin pools upstream. Chandra Asri Petrochemical anchors the polypropylene supply base for container molding across Greater Jakarta. PT Hokkan Deltapack competes through specialized injection-molded closures for beverage applications.
Indonesia rigid plastic packaging comprises formed polymer structures—typically PET, HDPE, or PP—with wall thickness above 0.25 mm, manufactured through injection, blow, or thermoforming processes to protect contents from moisture, oxygen, and mechanical damage during distribution. Bottles and containers dominate volume flows, though trays are gaining share in chilled ready-meal segments as modern retail cold-chain penetration deepens. Polyethylene leads material consumption for its cost-performance balance in dairy and household chemical containers, while polypropylene is displacing polystyrene in hot-fill and microwaveable jar applications due to thermal stability advantages.
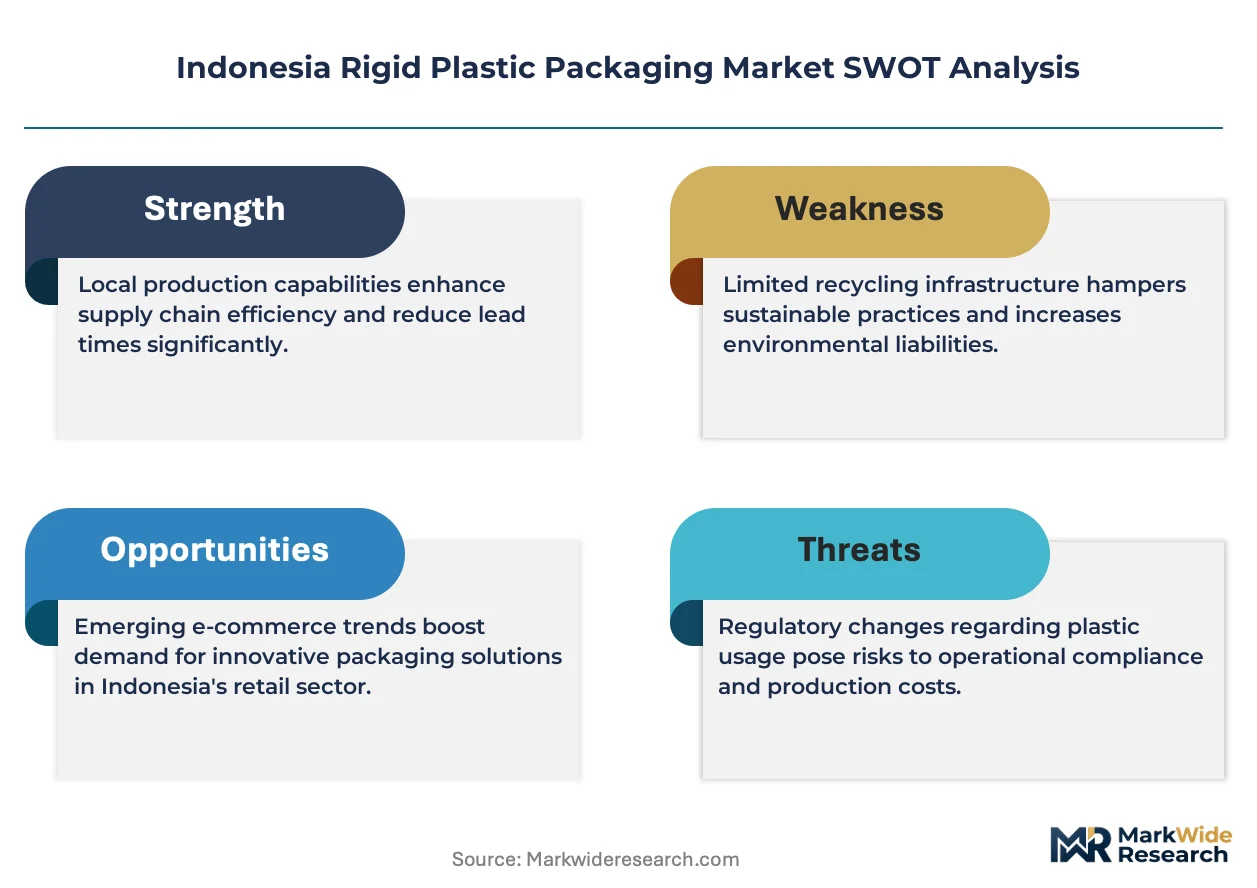
BIS-equivalent national standards and the Ministry of Environment and Forestry's waste reduction roadmaps shape product design mandates, recyclability labeling requirements, and recycled content thresholds for packaging placed on the Indonesian market. The national pharmaceutical regulator enforces material migration limits for healthcare-grade containers, creating compliance barriers for non-certified importers. Stakeholders must monitor how Indonesia's evolving EPR enforcement timeline and import tariff adjustments on virgin resin alter local versus imported packaging economics.
Market Dynamics
Indonesia's Ministry of Environment and Forestry is tightening Extended Producer Responsibility enforcement, forcing rigid packaging converters to reengineer supply chains around verified recycled content thresholds and collection infrastructure investments. This regulatory pressure layer compounds with resin import tariff volatility to compress margin structures across Java-based manufacturing clusters.
Growth Catalysts
- EPR mandate escalation:The Ministry of Environment and Forestry's waste reduction roadmaps obligate producers to fund collection networks, accelerating demand for recyclable PET and HDPE formats that simplify post-consumer sorting.
- Modern retail cold-chain expansion:Chilled ready-meal segments in Greater Jakarta and Surabaya are absorbing thermoformed PP trays as supermarket refrigeration penetration deepens beyond traditional ambient distribution.
- Integrated resin-to-preform operations:Domestic PET producers are shortening supply chains through captive preform molding, reducing working capital cycles for beverage bottlers in the manufacturing corridor.
Market Restraints
- Virgin resin import exposure:Tariff adjustments on polyethylene and polypropylene feedstock create input cost volatility that converters cannot fully pass through to price-sensitive FMCG buyers.
- Java supply concentration:Over 70 percent of rigid packaging capacity sits within 200 kilometers of Jakarta or Surabaya, exposing national supply to port congestion and island logistics bottlenecks.
- Recycled feedstock quality inconsistency:Domestic mechanical recycling yields PET flake with viscosity degradation that limits food-contact applications, constraining closed-loop compliance.
Strategic Opportunities
- Eastern Indonesia penetration:Sulawesi and Papua retail modernization lags Java by 8-10 years, creating first-mover terrain for cold-chain packaging formats in seafood and dairy distribution.
- Pharmaceutical serialization integration:The national pharmaceutical regulator's track-and-trace mandates are opening specialized HDPE container segments with embedded authentication features.
- Chemical recycling pilot scaling:Pyrolysis and depolymerization investments in Banten province could unlock food-grade rPET supply independent of mechanical recycling quality constraints.
Industry Challenges
- Migration testing capacity scarcity:Certified laboratories for FDA-equivalent and BIS-equivalent food-contact compliance are concentrated in Jakarta, creating 6-12 month bottlenecks for new product approvals.
- Legacy injection molding fleet retrofit costs:Converters face capital-intensive upgrades to electric presses and in-mold labeling systems required for thin-wall lightweighting and premium decoration.
- Informal waste picker integration:EPR collection targets depend on formalizing relationships with scavenger networks, requiring operational capabilities outside traditional manufacturing expertise.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Indonesia Rigid Plastic Packaging Market |
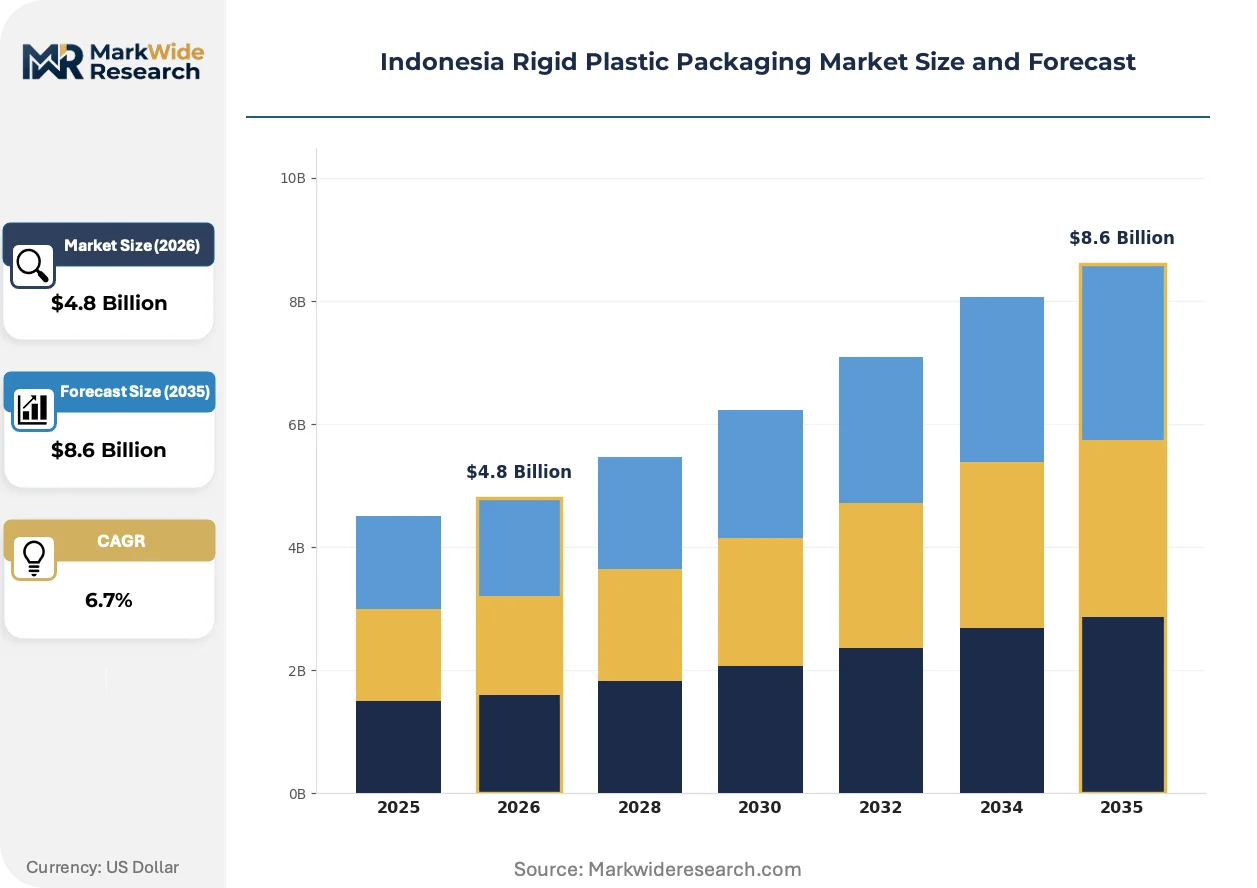
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Containers, Jars, Trays End User: Food, Beverage, Personal Care, Healthcare Material: Polyethylene, Polypropylene, PVC, Polystyrene Technology: Injection Molding, Blow Molding, Thermoforming, Extrusion |
| Companies Covered | Indo Cap Closures, PT Hokkan Deltapack, PT. Indorama Ventures Indonesia, PT Toppan Indonesia, Chandra Asri Petrochemical, PT. Berlina Tbk, PT. Solusi Prima Packaging, Primajaya Eratama, PT Indo Tirta Abadi, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Indonesia Rigid Plastic Packaging Market Shifts & Advancements
Digital printing and smart packaging technologies are collapsing minimum order quantities and enabling SKU proliferation that legacy flexographic and offset workflows cannot economically support. These capabilities are reshaping how brands manage regional flavor variants and promotional cycles.
Digital direct-to-object printing is decentralizing decoration capacity from centralized label converters to blow-molding and thermoforming plants. Beverage bottlers in Surabaya and Bandung are adopting UV-cured inkjet systems for 5,000-unit promotional runs that previously required 50,000-unit minimums. This technology is decentralizing design-to-shelf timelines from 8 weeks to 72 hours for seasonal campaigns.
The Ministry of Environment and Forestry's mandatory recyclability labeling framework is forcing redesign of multi-material laminations and pigmented containers. Mono-material PET structures are displacing PS-EVOH-PS barrier trays in fresh protein applications. Dairy processors in West Java are responding fastest, converting chilled milk bottles to transparent HDPE with compatible shrink-sleeve substrates.
Modern retail buyers are consolidating supplier panels and demanding vendor-managed inventory with scan-based replenishment. Hypermarket chains in Greater Jakarta are replacing purchase-order models with consignment stocking at distribution centers. This shift is most visible in household chemical containers, where three national retailers now control 40 percent of polyethylene jug procurement through centralized category management.
Indonesia Rigid Plastic Packaging Market Segmentation
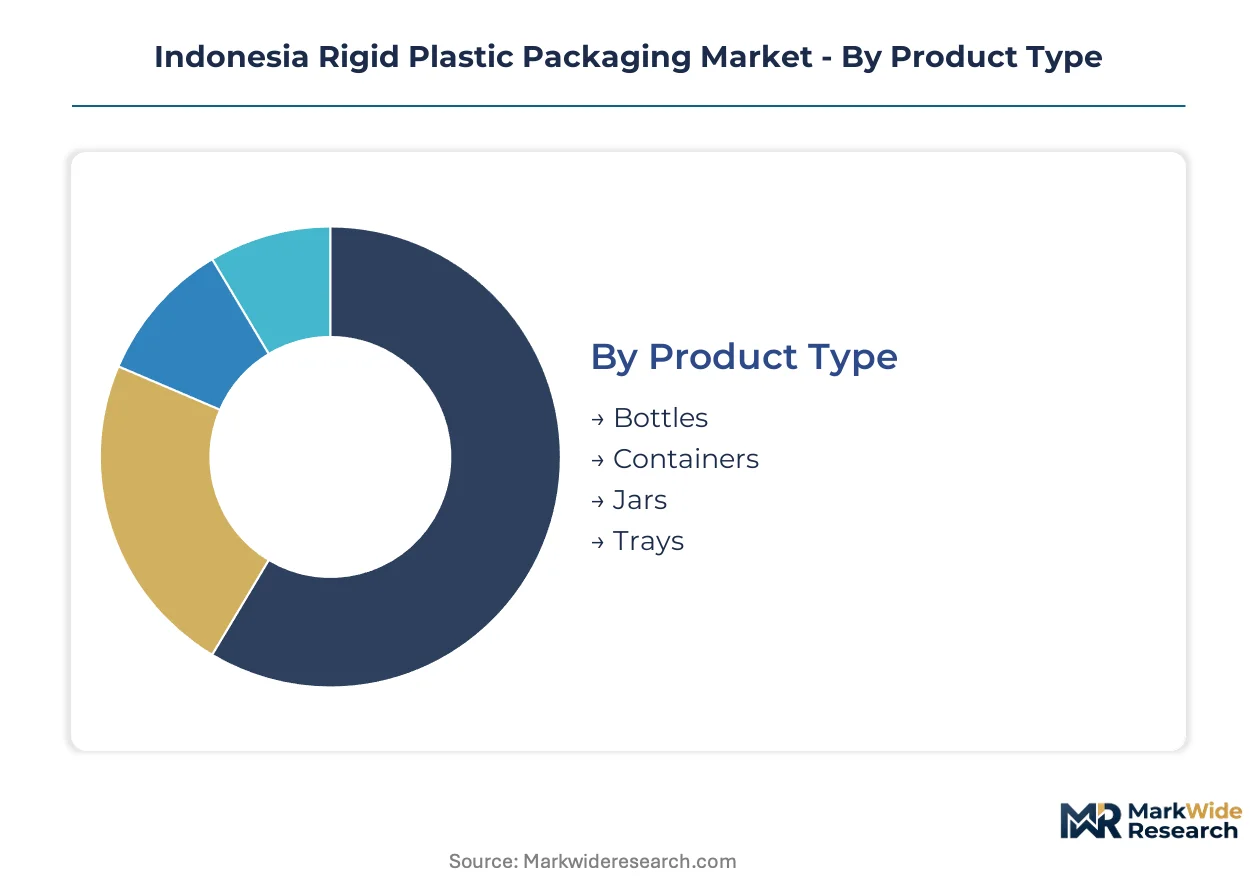
Converters in Indonesia must align equipment configurations and resin procurement strategies to distinct product-performance requirements across beverage, food, and healthcare channels. Segmentation clarity determines where capital-intensive blow-molding assets yield returns versus where flexible thermoforming lines capture chilled retail expansion.
Product Type:
Beverage bottlers prioritize cavity count and cycle speed when selecting rigid packaging formats, driving divergent tooling investments across the four structural categories.
- Bottles:PET stretch-blow formats dominate water and carbonated soft drink filling lines across West Java manufacturing corridors. Demand concentrates with multinational beverage brands expanding PET procurement for 350ml to 1.5L SKUs as ready-to-drink consumption accelerates in Greater Jakarta.
- Containers:HDPE dairy jugs and household chemical pails require barrier-enhanced designs with fluorination or multi-layer coextrusion for agrochemical clients. Processors in Surabaya absorb volume for regional distribution of cooking oil and disinfectant products.
- Jars:Wide-mouth PP structures serve hot-fill sauces and microwaveable ready-meals where thermal stability exceeds 120°C.
- Trays:Thermoformed PET and PP formats penetrate modern retail chilled meat and seafood displays as supermarket cold-chain infrastructure deepens beyond traditional ambient distribution.
Volume sits with bottles; growth tilts toward trays.
End User:
Regulatory compliance thresholds and shelf-life specifications fragment converter capabilities across four distinct buyer categories with incompatible certification requirements.
- Food:Mono-material PET trays displace PS-EVOH-PS barrier structures in fresh protein applications as the Ministry of Environment and Forestry's recyclability mandates force redesign. Dairy processors in West Java convert chilled milk packaging to transparent HDPE with compatible shrink-sleeve substrates.
- Beverage:Carbonated soft drink and bottled water producers drive PET preform demand through integrated resin-to-preform operations that shorten working capital cycles. Java-based manufacturing corridors absorb capacity for national distribution networks.
- Personal Care:HDPE bottles for shampoo and lotion require in-mold labeling compatibility and premium decoration surfaces.
- Healthcare:The national pharmaceutical regulator enforces material migration limits that create compliance barriers for non-certified importers, favoring domestic HDPE container specialists with embedded authentication features.
Food commands installed capacity; healthcare offers margin expansion.
Material:
Resin selection balances cost-performance ratios against thermal requirements and recyclability compliance under tightening Extended Producer Responsibility frameworks.
- Polyethylene:HDPE leads dairy and household chemical containers for cost-performance balance and established mechanical recycling streams. Chandra Asri Petrochemical anchors supply security for Greater Jakarta converters.
- Polypropylene:Displacing polystyrene in hot-fill and microwaveable jar applications due to thermal stability above 120°C, with random copolymer grades penetrating chilled ready-meal trays.
- PVC:Pharmaceutical blister packs and specialized chemical containers retain niche demand despite environmental pressure.
- Polystyrene:General-purpose crystal grades retreat to disposable cutlery and low-value applications as EPR enforcement accelerates format substitution.
Polyethylene dominates tonnage; polypropylene climbs fastest.
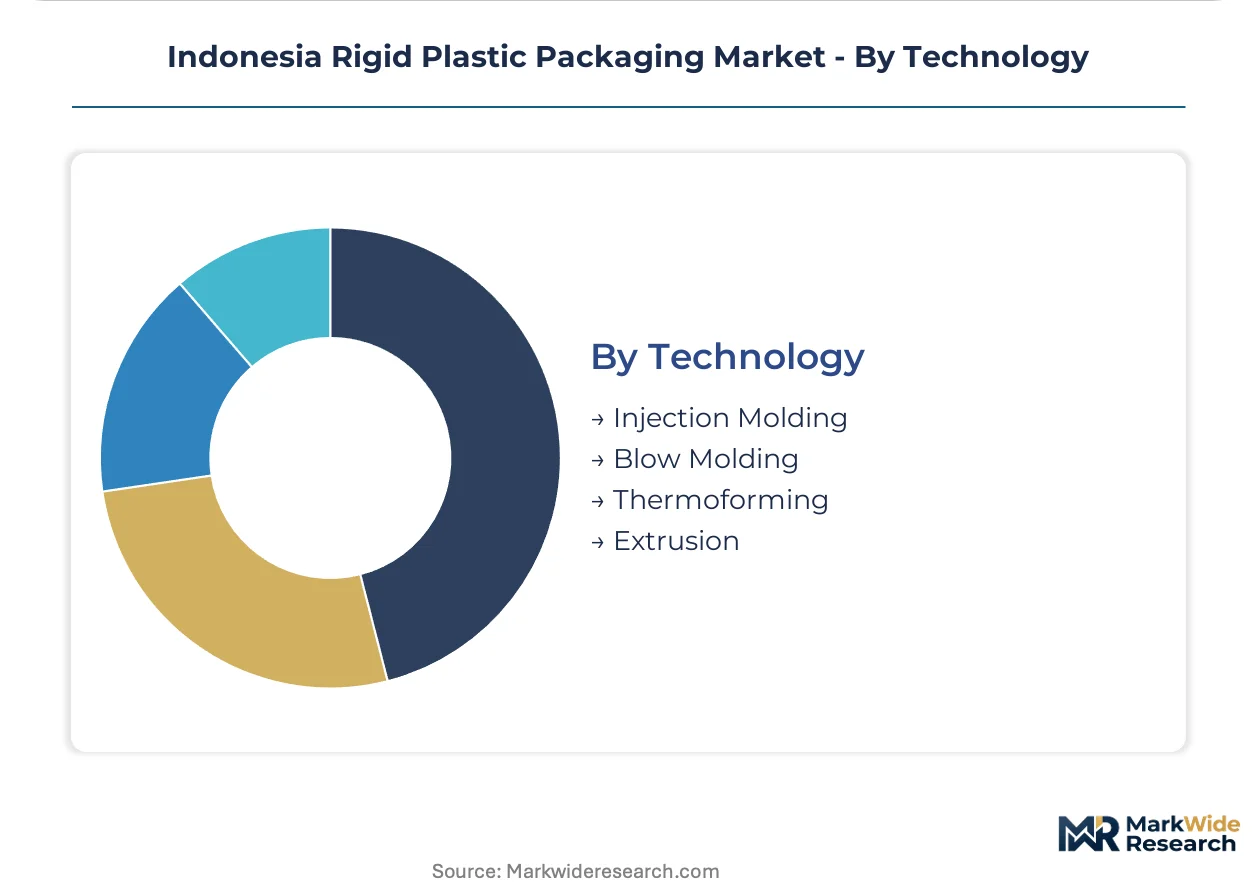
Technology:
Capital intensity and output velocity separate process technologies, with electric press retrofits and digital printing integration reshaping equipment investment priorities.
- Injection Molding:High-speed electric presses produce thin-wall containers and closures with cycle times below 3 seconds for dairy and personal care volumes. PT Hokkan Deltapack specializes in beverage closure systems with tamper-evident features.
- Blow Molding:Stretch-blow equipment for PET bottles achieves output exceeding 2,000 bottles per minute on 144-cavity rotary systems. PT. Indorama Ventures Indonesia leverages captive resin supply for preform integration.
- Thermoforming:Roll-fed and cut-sheet lines serve chilled food trays with rapid tool changeover for SKU proliferation in modern retail.
- Extrusion:Profile and sheet extrusion feeds downstream thermoforming or produces multi-layer barrier structures for extended shelf-life applications.
Blow molding captures beverage volume; thermoforming expands with retail cold-chain penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Petrochemical feedstock availability across Java and Sumatra anchors Indonesia's rigid plastic packaging geography, with resin production clustering near Cilegon and Merak industrial zones driving downstream converter placement decisions.
Java
Beverage bottlers in Bekasi and Karawang absorb PET preform volumes for national water and carbonated soft drink distribution networks. The Ministry of Environment and Forestry's Extended Producer Responsibility enforcement tightest here, forcing converters to fund collection infrastructure. Cikarang manufacturing corridors host integrated resin-to-preform operations that shorten working capital cycles for Greater Jakarta bottlers.
Sumatra
Palm oil processors in Medan and Pekanbaru drive HDPE container demand for cooking oil and shortening exports to Middle Eastern markets. The national pharmaceutical regulator's migration limits create compliance barriers for imported healthcare containers, favoring domestic converters around Batam with embedded authentication capabilities. Dumai petrochemical complexes supply virgin polyethylene feedstock to regional blow molders.
Sulawesi
Seafood exporters in Makassar and Kendari adopt thermoformed PP trays as cold-chain infrastructure penetrates chilled fish distribution. Provincial waste management regulations lag Java by several years, creating transitional windows for non-recyclable formats before EPR alignment. Bitung processing zones attract tray converters serving tuna loin export packaging.
Kalimantan
Mining chemical containers for coal and nickel operations absorb fluorinated HDPE pails from Surabaya-based suppliers shipped across the Java Sea. The Ministry of Environment and Forestry's waste reduction roadmaps exclude remote industrial zones from immediate collection mandates. Balikpapan logistics hubs consolidate chemical packaging procurement for East Kalimantan extractive operations.
Bali and Eastern Islands
Tourism-driven beverage consumption in Denpasar and Mataram generates PET bottle waste volumes disproportionate to local recycling capacity. Provincial governors negotiate EPR phase-in timelines with the Ministry of Environment and Forestry based on infrastructure gaps. Lombok emerging as a testbed for deposit-return schemes before national scaling.
Indonesia Rigid Plastic Packaging Market Competitive Landscape
Global petrochemical majors compete with domestic resin-to-packaging integrators across feedstock security and converter relationships. Market structure concentrates around three tiers: captive resin producers with downstream molding assets, independent converters sourcing spot resin, and specialized closure and decoration specialists. Strategic moves center on backward integration into preform production and forward integration into brand-direct supply contracts.
Among integrated resin-to-preform operators, PT. Indorama Ventures Indonesia and Chandra Asri Petrochemical exemplify the captive-feedstock archetype, while PT Hokkan Deltapack occupies a position within specialized closure manufacturing. These three entities represent distinct competitive positions: multinational-backed vertical integration, domestic petrochemical anchoring, and niche component specialization respectively.
| Leading Market Players |
|---|
| Indo Cap Closures |
| PT Hokkan Deltapack |
| PT. Indorama Ventures Indonesia |
| PT Toppan Indonesia |
| Chandra Asri Petrochemical |
| PT. Berlina Tbk |
| PT. Solusi Prima Packaging |
| Primajaya Eratama |
| PT Indo Tirta Abadi |
| Others |
Supply & Pricing Matrix
Hypermarket procurement consolidation in Greater Jakarta anchors contract-based pricing for polyethylene jugs and PET bottles, with three national retailers now controlling two-fifths of category volume through vendor-managed inventory programs.
Pricing Analysis
Tooling and mold maintenance warranties separate premium converter relationships from transactional spot arrangements. Pricing stratifies across premium, standard, and economy tiers based on migration testing certification grade and volume scale commitments. Cost compression in standard-tier HDPE dairy containers is intensifying because tariff volatility on virgin resin cannot be fully passed to price-sensitive FMCG buyers. Beverage bottlers exhibit lowest price sensitivity due to integrated resin-to-preform operations, while regional cooking oil distributors face highest pressure.
Supply Chain Analysis
BIS-equivalent food-contact certification and Ministry of Environment and Forestry EPR compliance documentation gate supplier qualification for rigid packaging converters. Feedstock security draws from domestic petrochemical complexes in Cilegon and Merak, with polyethylene and polypropylene resin forming the core input base. Single-source vulnerability concentrates in mechanical recycling flake supply for food-contact rPET applications. Distribution runs through Java-based manufacturing corridors serving national beverage and dairy networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Indonesia's rigid plastic packaging sector operates as a vertical-integration race where captive resin supply and preform molding assets determine margin capture across the value chain.
For Market Incumbents: Extend backward integration into chemical recycling pilots in Banten province to secure food-grade rPET supply independent of mechanical recycling quality constraints. Fortify converter relationships through vendor-managed inventory programs with scan-based replenishment to lock out spot-market competitors. The Ministry of Environment and Forestry's escalating EPR enforcement threatens non-integrated players with collection infrastructure cost burdens.
For New Entrants and Emerging Players: Enter via Sulawesi and Papua cold-chain packaging segments where retail modernization lags Java by eight to ten years, creating first-mover terrain for thermoformed PP trays in seafood distribution. Target pharmaceutical serialization-integrated HDPE containers with embedded authentication features, as the national pharmaceutical regulator's track-and-trace mandates favor domestic specialists. Pursue direct supply contracts with Bitung tuna processors bypassing Java-based distribution layers.
For Investors and Strategic Acquirers: The window for entry favors mid-cap converters with established BIS-equivalent certification and electric press fleets capable of thin-wall lightweighting. Long-term viability rests on positioning ahead of EPR enforcement maturation and chemical recycling scale-up. Monitor pyrolysis investment announcements in Banten as inflection signal for rPET supply economics.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Chemical Recycling | Pyrolysis investments in Banten unlock food-grade rPET supply beyond mechanical recycling constraints. |
| Vendor-Managed Inventory Expansion | Scan-based replenishment programs with hypermarket chains lock in polyethylene jug procurement volume. |
| Electric Press Fleet Retrofit | High-speed thin-wall molding capability captures dairy and personal care lightweighting mandates. |
| Pharmaceutical Serialization Integration | Embedded authentication features in HDPE containers align with national pharmaceutical regulator track-and-trace requirements. |
| Eastern Indonesia Geographic Expansion | Sulawesi cold-chain infrastructure gaps create transitional windows for tray converters before EPR alignment. |
Research Methodology
Independent corroboration across converter operations directors, resin procurement managers, and modern retail category buyers underwrites the qualitative findings presented in this study. Primary interviews with beverage bottler supply chain heads, thermoforming plant engineers, and Ministry of Environment and Forestry compliance officers combined with secondary validation from Indonesian customs records, petrochemical trade association disclosures, and BIS-equivalent standards documentation. Bottom-up capacity assessments across Cikarang and Surabaya manufacturing corridors triangulate against top-down demand modeling from retail channel audits.
Rate-of-change decomposition separates volume growth into packaging format substitution effects, end-use industry expansion, and material conversion trends across the projection horizon. Segmentation dimensions modeled include product type, end-use channel, resin material, and process technology, with additional granularity on EPR compliance tier. CAGRs derive from historical trajectory analysis adjusted for regulatory inflection points and infrastructure investment timelines. Forecast inputs incorporate cold-chain penetration rates in modern retail and chemical recycling pilot scale-up announcements.
Forecast precision tightens around the base case; tail outcomes carry wider variance under Ministry of Environment and Forestry EPR timeline acceleration or virgin resin tariff shock scenarios. Model assumptions reflect documented regulatory roadmaps and disclosed converter capacity expansion plans. A model refresh is warranted upon material change in Banten chemical recycling project commissioning schedules or national pharmaceutical regulator serialization mandate enforcement dates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rigid Packaging
Middle East and Africa Rigid Plastic Packaging Market
Rigid Packaging
Italy Rigid Plastic Packaging Market
Rigid Packaging
Certified-Circular Polyolefin Resins for Flexible and Rigid Packaging Market
Rigid Packaging
Australia and New Zealand Rigid Plastic Packaging Market
Rigid Packaging
Global Plastic Rigid IBC Market
Rigid Packaging
Poland Rigid Plastic Packaging Market
Rigid Packaging
GCC Rigid Plastic Packaging Market
Rigid Packaging
Europe Rigid Plastic Packaging Market
Rigid Packaging
Germany Rigid Plastic Packaging Market
Rigid Packaging
Mexico Rigid Plastic Packaging Market
Rigid Packaging
Global Rigid Paper Containers Market
Rigid Packaging
United States Rigid Plastic Packaging Market
Rigid Packaging
Saudi Arabia Rigid Plastic Packaging Market
Rigid Packaging
Japan Rigid Plastic Packaging Market
Rigid Packaging
Rigid Transparent Plastic Market
Rigid Packaging
Rigid Boxes Market