
 Insulated Corrugated Boxes Market | 2026-2036
Insulated Corrugated Boxes Market Size, Share, and Industry Trends Forecast 2026-2036
Insulated Corrugated Boxes Market Foresight
Pharmaceutical cold-chain logistics is rebalancing the insulated corrugated boxes landscape as biologics and vaccine distribution networks expand. Cryopak specializes in thermal packaging validation protocols for pharmaceutical clients. Sonoco Products dominates North American manufacturing scale for temperature-controlled fiber-based solutions. Cold Chain Technologies navigates European regulatory complexity through dedicated compliance engineering teams.
Insulated corrugated boxes combine fluted paperboard layers with thermal barrier inserts—typically polyurethane or polystyrene foam—to maintain stable internal temperatures during transit and storage. The composite structure achieves R-values between 3.5 and 7.0 per inch depending on material density and wall configuration, protecting temperature-sensitive payloads against ambient thermal excursions. Double-wall configurations lead volume shipments for mid-range pharmaceutical applications, while triple-wall variants capture premium margin pools in extreme-duration transport. Custom Size offerings represent the fastest-growing product dimension as pharmaceutical clients specify exact dimensional tolerances for automated packing lines.
The US FDA enforces strict temperature-excursion documentation through its drug distribution security framework, compelling packaging suppliers to invest in validated thermal-performance testing. REACH and the EU Green Deal constrain polystyrene-based material choices across European supply chains, redirecting R&D toward paperboard-dominant recyclable alternatives. Stakeholders must monitor evolving extended producer responsibility mandates and decide whether to anchor material strategies in polyurethane durability or paperboard circularity.
Market Dynamics
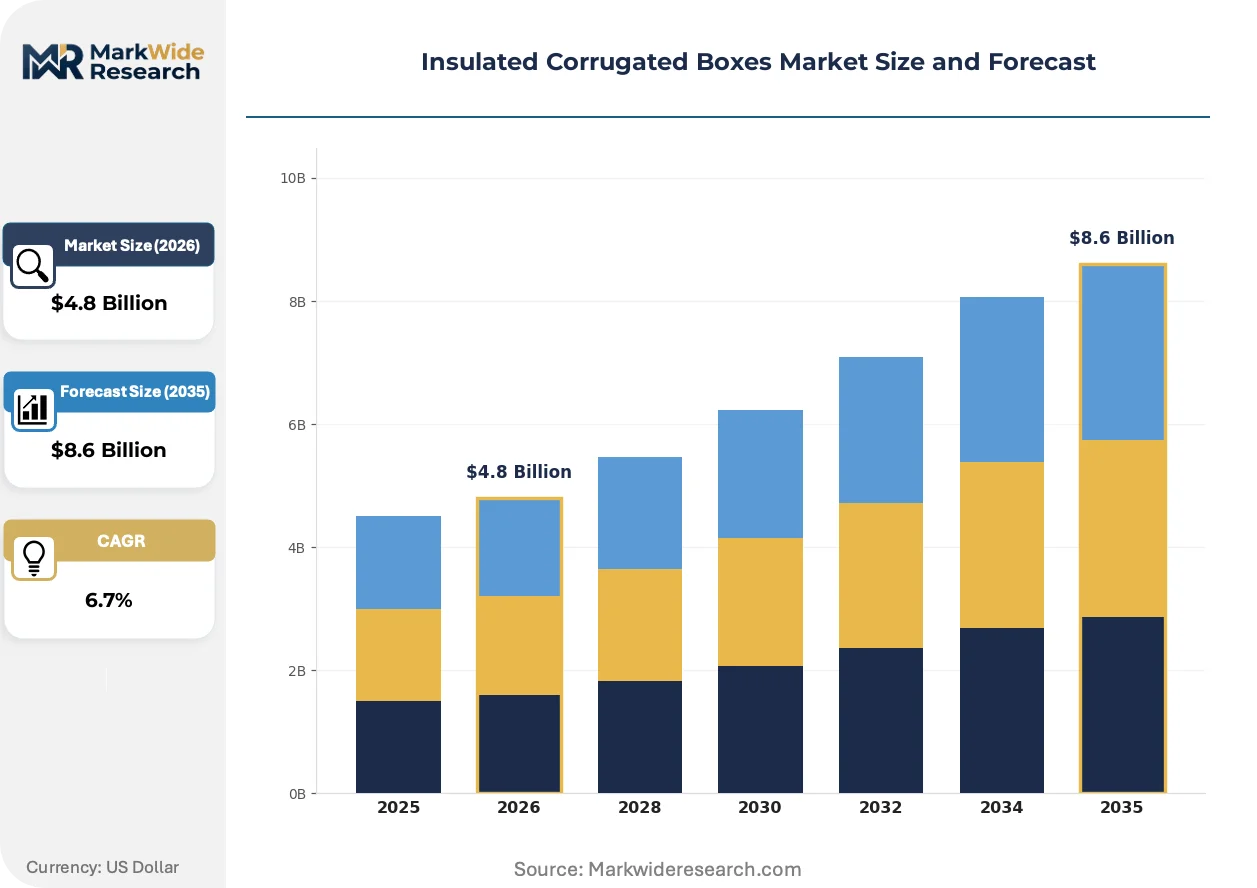
Pharmaceutical cold-chain expansion is compressing validation timelines while forcing material substitutions away from polystyrene toward paperboard-dominant thermal barriers. This structural pressure cascades through R&D priorities, capex allocation, and supplier qualification protocols across packaging value chains.
Growth Catalysts
- Biologics distribution networks:Cell and gene therapy shipments require validated 2-8°C and cryogenic protection, expanding addressable payload categories for thermal packaging.
- EU Green Deal material mandates:REACH constraints on polystyrene foam redirect formulation investment toward recyclable polyurethane and cellulose-based insulators.
- FDA temperature-excursion documentation:Enhanced drug distribution security protocols compel pharmaceutical shippers to upgrade from passive to validated active thermal packaging systems.
Market Restraints
- Polystyrene feedstock volatility:Benzene price swings compress margin predictability for foam-in-place insulation manufacturers.
- German automotive supplier dominance:Concentrated polyurethane chemical production around Ludwigshafen creates single-point vulnerability for European thermal barrier supply.
- Technical limitation in moisture resistance:Paperboard-dominant recyclable alternatives absorb humidity during multi-day ocean transit, degrading R-value performance.
Strategic Opportunities
- Indian pharmaceutical manufacturing corridor:CDSCO cold-chain expansion around Hyderabad and Ahmedabad creates underpenetrated demand for validated export packaging.
- Reusable thermal packaging systems:Reverse logistics platforms for temperature-controlled containers displace single-use corrugated in high-volume vaccine distribution.
- CSRD scope extension:Corporate sustainability reporting mandates drive Scope 3 emissions accounting, favoring suppliers with certified circular material flows.
Industry Challenges
- Thermal validation engineering talent scarcity:ISTA 7E and WHO PQS certification expertise concentrates in specialized testing laboratories, elongating supplier qualification cycles.
- Automated packing line integration:Pharmaceutical contract manufacturers require dimensional tolerances within 2 millimeters, forcing custom tooling investment for corrugated converters.
- Multi-regulatory compliance stacking:Simultaneous FDA, EMA, and WHO prequalification demands create documentation redundancy and audit fatigue.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Insulated Corrugated Boxes Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Wall, Double-Wall, Triple-Wall, Custom Size Material: Polyurethane, Polystyrene, Paperboard, Fiberglass End User: Food & Beverage, Pharmaceuticals, Electronics, Cosmetics Application: Temperature Control, Shipping, Storage, Transport |
| Companies Covered | Drew Foam Companies, Cryopak, Harwal Group, COOL Sarl, Topa Thermal, Sonoco Products, Marko Foam Products, Cold Chain Technologies, Sofrigam, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Insulated Corrugated Boxes Market Shifts & Advancements
Material science breakthroughs and regulatory disclosure mandates are converging to redefine thermal packaging performance standards. The competitive frontier is shifting from passive insulation toward intelligent, traceable, and circular systems.
Phase-change material microencapsulation is rewriting thermal mass distribution in lightweight corrugated formats. Biopharmaceutical cold-chain managers at vaccine distributors are piloting paraffin-based inserts that maintain 2-8°C stability for 96 hours at one-third the weight of traditional foam. This density reduction is rewriting freight economics on intercontinental lanes, compressing landed cost structures for temperature-sensitive payloads.
EMA's strengthened good distribution practice guidelines for ATMPs (advanced therapy medicinal products) now mandate continuous temperature monitoring with tamper-evident data loggers. Cell therapy manufacturers must demonstrate chain-of-custody integrity from apheresis center to infusion site, forcing packaging redesign around embedded IoT sensor integration. German gene therapy clusters around Cologne and Heidelberg are driving fastest adoption of connected thermal containers with real-time cloud telemetry.
Consolidated procurement by pharmaceutical third-party logistics providers is concentrating supplier relationships around performance-guarantee contracts. DHL Supply Chain and FedEx Health Solutions now require thermal packaging vendors to assume financial liability for temperature excursions, displacing traditional unit-price purchasing. This risk-transfer model is most visible in US vaccine distribution networks, where performance-based vendor selection prioritizes validated mean kinetic temperature compliance over upfront material cost.
Insulated Corrugated Boxes Market Segmentation
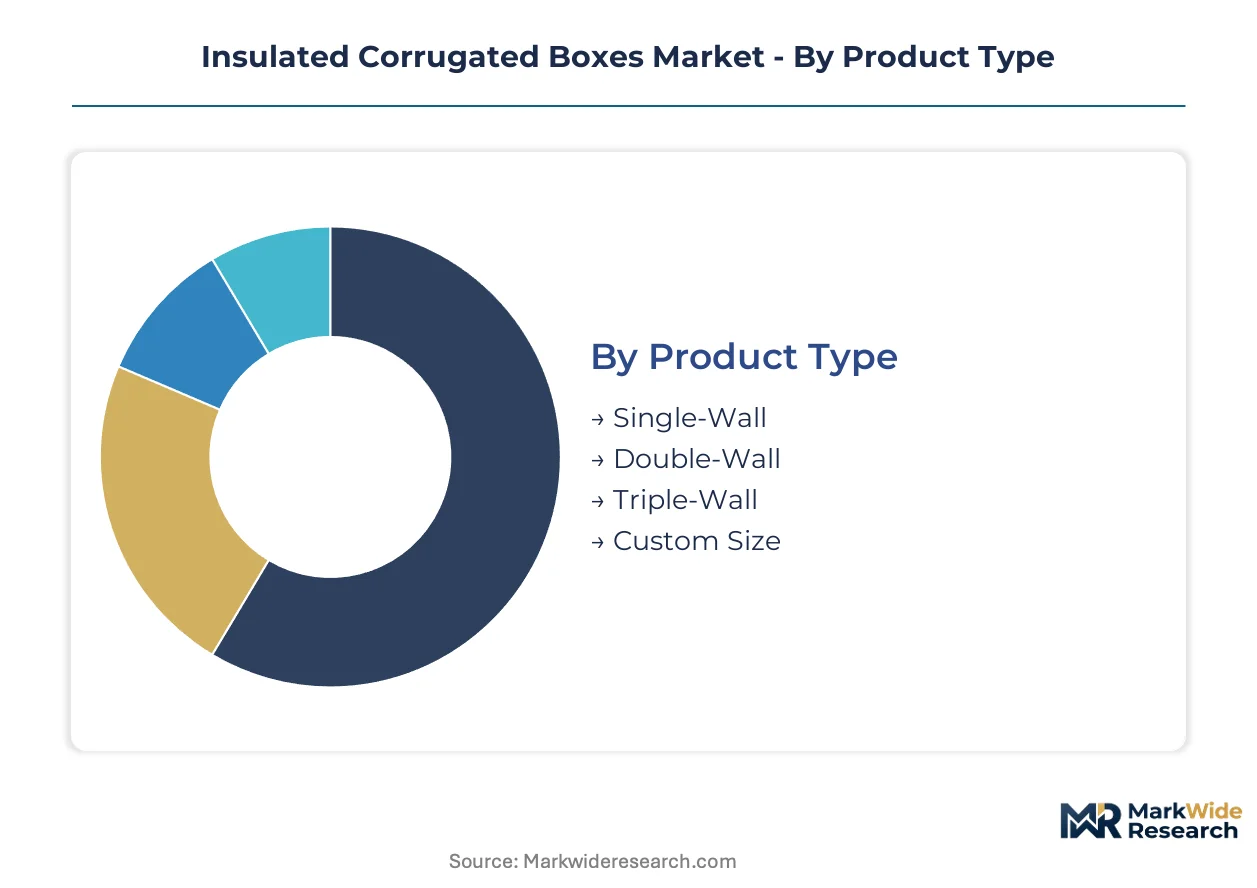
Insulated corrugated boxes fragment across thermal performance tiers, material chemistry, and payload sensitivity requirements. Pharmaceutical cold-chain validation protocols and EU material compliance mandates are compressing specification ranges while elevating premium segments.
Product Type:
Wall configuration dictates thermal resistance duration and structural load-bearing capacity for automated handling systems.
- Double-Wall:Twin fluted layers sandwiching polyurethane or polystyrene cores achieve R-values of 5.0-6.5 per inch, dominating mid-range pharmaceutical shipments requiring 48-72 hour temperature stability. German vaccine distributors around Frankfurt specify this configuration for EMA-compliant regional distribution.
- Custom Size:Dimensional tolerances within 2 millimeters accommodate robotic packing lines at pharmaceutical contract manufacturers. Hyderabad and Ahmedabad CDSCO-registered facilities are driving fastest specification growth for export-validated biologics packaging.
- Single-Wall:Lightweight construction suits short-duration food service and meal-kit applications with same-day delivery windows.
- Triple-Wall:Maximum structural rigidity and extended thermal duration target cryogenic cell therapy shipments exceeding 96 hours transit time.
Mature deployment sits with Double-Wall configurations. Newer deployment is concentrated in Custom Size specifications for automated pharmaceutical manufacturing integration.
Material:
Feedstock chemistry determines recyclability pathways, moisture resistance, and regulatory acceptance across REACH-constrained European supply chains.
- Polyurethane:Closed-cell foam structures deliver superior R-value retention under humidity stress, maintaining thermal performance through multi-day ocean transit. REACH-compliant formulations from Ludwigshafen chemical clusters supply Frankfurt-area pharmaceutical packaging converters.
- Paperboard:Fluted cellulose layers with bio-based thermal barriers satisfy EU Green Deal circularity mandates. Cologne and Heidelberg gene therapy clusters are piloting paperboard-dominant formats with embedded IoT temperature loggers for ATMP distribution.
- Polystyrene:Benzene-derived feedstock faces ECHA restriction pressures, compressing margin predictability and redirecting R&D investment toward polyurethane alternatives.
- Fiberglass:Inorganic fiber insulation targets extreme-temperature electronics shipments requiring thermal stability beyond standard foam performance envelopes.
Polyurethane retains volume leadership in validated pharmaceutical applications. Paperboard is climbing the fastest as CSRD disclosure mandates accelerate material circularity transitions.
End User:
Payload sensitivity and regulatory burden vary sharply across temperature-controlled product categories.
- Pharmaceuticals:FDA temperature-excursion documentation and WHO PQS prequalification requirements enforce validated thermal-performance testing. US vaccine distribution networks now require vendors to assume financial liability for temperature deviations, compressing supplier qualification to proven performers.
- Food & Beverage:FSSAI cold-chain expansion for dairy and frozen proteins is expanding addressable demand in Indian metropolitan distribution networks.
- Electronics:Semiconductor and battery shipments require controlled thermal environments without the validation documentation burden of pharmaceutical payloads.
- Cosmetics:Temperature-sensitive active ingredients in premium skincare formulations are adopting pharmaceutical-grade thermal protection for intercontinental e-commerce fulfillment.
Pharmaceuticals anchor premium margin pools. Cosmetics represents the steepest expansion trajectory as clean-beauty temperature sensitivity converges with direct-to-consumer cold-chain expectations.
Application:
Functional use case determines packaging lifecycle duration and reuse potential across supply chain configurations.
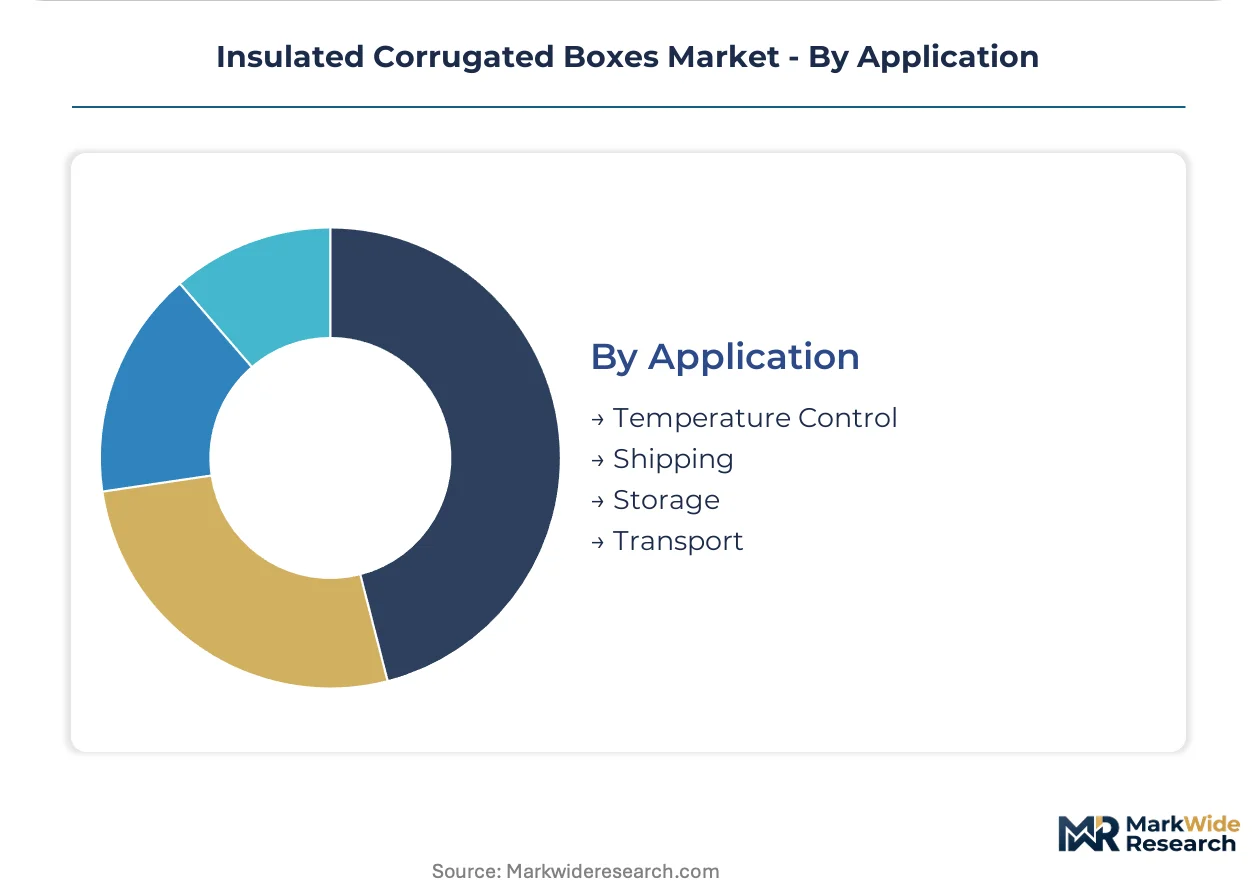
- Temperature Control:Passive and active thermal management systems protect payload integrity against ambient excursion events. German automotive supplier networks around Stuttgart are adopting temperature-controlled formats for precision electronics inbound logistics.
- Shipping:Single-use corrugated dominates intercontinental lanes where reverse logistics economics fail. DHL Supply Chain and FedEx Health Solutions are consolidating procurement around performance-guarantee contracts displacing unit-price purchasing.
- Storage:Extended-duration thermal stability supports warehouse buffer inventory and clinical trial material depots.
- Transport:Multi-modal compatibility—air, ocean, and road—drives dimensional standardization for palletized unit loads.
Shipping captures highest transaction velocity. Temperature Control is gaining share fastest as pharmaceutical validation protocols elevate technical performance requirements above commodity logistics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones for pharmaceutical manufacturing in India and concentrated chemical production clusters in Germany are redrawing supply chain maps for temperature-validated packaging. FDA enforcement in the United States and EMA guidance in Europe are tightening documentation requirements simultaneously. CDSCO expansion around Hyderabad and REACH constraints on polystyrene are forcing material substitutions across Asian and European supply bases.
United States
FDA temperature-excursion documentation mandates are compressing supplier qualification timelines for vaccine distributors. The Drug Supply Chain Security Act enforcement is elevating validation requirements for passive thermal packaging systems. Cold Chain Technologies maintains compliance engineering operations serving pharmaceutical third-party logistics providers in the Northeast corridor.
Germany
EMA strengthened good distribution practice guidelines for advanced therapy medicinal products are mandating continuous temperature monitoring. REACH restrictions on benzene-derived feedstocks are redirecting polyurethane formulation investment. The Ludwigshafen chemical cluster supplies REACH-compliant thermal barrier materials to Frankfurt-area packaging converters serving vaccine distribution networks.
India
CDSCO cold-chain expansion for biologics export validation is creating demand for custom-size specifications within two-millimeter tolerances. The Production Linked Incentive scheme for pharmaceuticals is accelerating automated manufacturing investment. Hyderabad and Ahmedabad manufacturing corridors are driving fastest specification growth for export-validated insulated corrugated formats.
China
NMPA good supply practice for vaccines is aligning domestic cold-chain standards with WHO prequalification requirements. Dual carbon goals are constraining polystyrene foam production capacity in coastal manufacturing zones. Yangtze River Delta packaging converters are piloting paperboard-dominant thermal barriers with bio-based insulating cores.
United Kingdom
MHRA post-Brexit recognition agreements with FDA and EMA are maintaining multi-regulatory compliance burdens for pharmaceutical exporters. The Medicines and Healthcare products Regulatory Agency is enforcing GDP guidelines equivalent to EU standards. Southeast England logistics hubs are consolidating procurement around performance-guarantee contracts displacing unit-price purchasing.
Insulated Corrugated Boxes Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with validation-capable suppliers capturing premium pricing in pharmaceutical applications while commodity converters serve food and beverage logistics. The vendor base concentrates around three strategic archetypes: integrated material-chemistry-to-packaging conglomerates, specialized thermal engineering boutiques, and regional corrugated converters with foam lamination capabilities. M&A activity targets validation testing laboratories to compress supplier qualification cycles, while capacity expansion concentrates in Indian pharmaceutical manufacturing corridors.
Among North American fabricators, Sonoco Products and Cold Chain Technologies occupy positions spanning material science and regulatory compliance engineering. Cryopak exemplifies the specialized thermal validation boutique archetype, anchoring pharmaceutical client relationships through ISTA 7E and WHO PQS certification expertise. These three entities represent distinct competitive vectors: scale-driven manufacturing integration, regulatory compliance depth, and specialized validation protocol mastery.
| Leading Market Players |
|---|
| Drew Foam Companies |
| Cryopak |
| Harwal Group |
| COOL Sarl |
| Topa Thermal |
| Sonoco Products |
| Marko Foam Products |
| Cold Chain Technologies |
| Sofrigam |
| Others |
Supply & Pricing Matrix
Pharmaceutical third-party logistics providers concentrate procurement authority around performance-guarantee contracts, displacing unit-price purchasing with risk-transfer pricing models that tie vendor compensation to validated thermal compliance. This buyer consolidation elevates premium tiers for ISTA 7E-certified suppliers while compressing margins for commodity corrugated converters lacking validation infrastructure.
Pricing Analysis
Lead-time-driven premiums dominate contract negotiations, with 48-hour turnaround specifications commanding substantial markups over standard four-week production windows. Three-tier pricing structure across premium, standard, and economy levels separates WHO PQS-certified systems from EMA-compliant regional formats and unvalidated food-service grades. Cost compression in polystyrene-dependent tiers is intensifying because benzene feedstock volatility erodes margin predictability. Food and beverage distributors exhibit highest price sensitivity, while cell therapy manufacturers prioritize thermal assurance over unit economics.
Supply Chain Analysis
Dual-sourcing mandates from DHL Supply Chain and FedEx Health Solutions compel pharmaceutical buyers to qualify redundant thermal barrier suppliers across Germany, India, and the United States. Raw material flows draw from Ludwigshafen polyurethane chemical clusters, Yangtze River Delta paperboard mills, and Ahmedabad foam lamination facilities. Single-source vulnerability concentrates around REACH-compliant thermal barrier formulations from the Frankfurt-Ludwigshafen corridor. Distribution runs through pharmaceutical contract manufacturing organizations with automated packing line integration requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into thermal validation testing and polyurethane formulation capabilities is becoming the decisive competitive moat as pharmaceutical buyers consolidate procurement around performance-guarantee contracts.
For Market Incumbents: Deepen backward integration into REACH-compliant polyurethane foam production to secure feedstock margin control against benzene price volatility. Expand ISTA 7E testing laboratory capacity in Hyderabad to compress supplier qualification cycles for CDSCO-registered biologics exporters. Defend against paperboard-dominant recyclable substitutes by demonstrating superior R-value retention through multi-day ocean transit. For New Entrants and Emerging Players: Cosmetics cold-chain distributors represent the most penetrable buyer archetype as clean-beauty temperature sensitivity converges with direct-to-consumer fulfillment expectations. Target Indian pharmaceutical manufacturing corridors around Ahmedabad with custom-size specifications engineered for two-millimeter dimensional tolerances on automated packing lines. Anchor go-to-market strategy through CSRD-compliant circular material flows that satisfy EU Green Deal procurement mandates. For Investors and Strategic Acquirers: The window for entry favors specialized thermal validation boutiques with WHO PQS certification expertise and established pharmaceutical client relationships. Long-term viability hinges on material science differentiation between polyurethane durability and paperboard circularity rather than commodity corrugated conversion scale. Watch for EMA enforcement actions on ATMP distribution documentation as the inflection signal for accelerated IoT-embedded packaging adoption.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polyurethane Formulation | Captures margin from Ludwigshafen chemical clusters while securing REACH compliance. |
| ISTA 7E Testing Laboratory Acquisition | Compresses pharmaceutical supplier qualification cycles from months to weeks. |
| Custom Size Specification Development | Locks in Hyderabad and Ahmedabad automated manufacturing corridors with robotic packing line integration. |
| CSRD-Compliant Circular Material Flow Certification | Qualifies suppliers for EU Green Deal procurement mandates from Cologne and Heidelberg gene therapy clusters. |
| IoT Sensor Integration Partnership | Meets EMA continuous temperature monitoring requirements for ATMP distribution integrity. |
Research Methodology
Independent corroboration across thermal packaging engineers, pharmaceutical cold-chain managers, and corrugated converter operations directors underwrites the qualitative findings presented in this study. Primary fieldwork engaged regulatory compliance specialists at DHL Supply Chain and FedEx Health Solutions alongside procurement leads at German vaccine distribution networks. Secondary validation drew from FDA temperature-excursion guidance documents, EMA good distribution practice updates, CDSCO cold-chain expansion notifications, and REACH restriction proposal dossiers. Bottom-up demand modeling from pharmaceutical shipment volumes and top-down supply assessment from polyurethane and paperboard capacity data establish analytical triangulation.
Rate-of-change decomposition separates volume growth from price-mix effects across wall configuration tiers, material chemistry categories, and end-use verticals. Segmentation modeling incorporates product type, feedstock composition, payload sensitivity requirements, and regional regulatory cluster intensity throughout the projection horizon. CAGRs derive from regression analysis against pharmaceutical cold-chain infrastructure investment trajectories and biologics distribution network expansion rates. Forecast inputs include benzene price volatility indices and EU extended producer responsibility mandate implementation schedules.
Revisions become necessary when FDA enforcement priorities shift toward active thermal systems, REACH restrictions harden against polystyrene foam, or CDSCO biologics export validation timelines accelerate materially. Deviation in pharmaceutical third-party logistics procurement consolidation patterns would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Paper & Paperboard Packaging
Asia Pacific Paper Packaging Market
Paper & Paperboard Packaging
Middle-East and Africa Corrugated Packaging Market
Paper & Paperboard Packaging
Paper Cups Market
Paper & Paperboard Packaging
Paperboard Jars Market
Paper & Paperboard Packaging
Paper Cones Market
Paper & Paperboard Packaging
Kraft Paper SOS Bag Market
Paper & Paperboard Packaging
Canada Paper Packaging Market
Paper & Paperboard Packaging
Beverage Filter Paper Market
Paper & Paperboard Packaging
Cold Seal Paper Market
Paper & Paperboard Packaging
Coated Paper Market
Paper & Paperboard Packaging
Desiccant Paper Market
Paper & Paperboard Packaging
Asia-Pacific Paper Bags Market
Paper & Paperboard Packaging
Mottled Test Liner Market
Paper & Paperboard Packaging
Testliner Market
Paper & Paperboard Packaging
Flowpack Paper Packaging Market
Paper & Paperboard Packaging
Macerated Paper Padded Mailers Market