
 Japan Rigid Plastic Packaging Market | 2026-2036
Japan Rigid Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Rigid Plastic Packaging Market Insights
Modular container systems with interchangeable caps and standardized base dimensions is realigning procurement patterns among Japanese food processors and cosmetics houses. Toyo Seiken Group Holdings Ltd leverages its integrated bottle-and-cap manufacturing to control specification drift for pharmaceutical clients. Takemoto Yohki Co Ltd anchors its position through deep specialization in custom-molded jars for premium skincare brands. Kodama Plastics Co Ltd competes on thin-wall injection molding cycles that reduce resin throughput per unit.
Japan rigid plastic packaging encompasses formed polymer structures—typically polyethylene, polypropylene, polyvinyl chloride, or polystyrene—manufactured via injection molding, blow molding, or thermoforming to provide dimensional stability, moisture barriers, and stackability for transported goods. Wall thicknesses generally range from 0.25 mm for thermoformed trays to 3 mm for industrial drums, with melt flow indices calibrated to each forming method. Polypropylene bottles lead volume due to hot-fill compatibility and clarity suited to Japanese ready-to-drink tea and sauce segments. Tamper-evident closures command margin premiums in pharmaceuticals and infant nutrition, where regulatory compliance costs deter commodity competition. Polyethylene containers sustain steady replacement demand from the bento and prepared-meal channel.
METI enforces Japan's Plastic Resource Circulation Strategy, while JIS standards govern migration limits and mechanical performance for food-contact materials; together these frameworks elevate compliance costs for imported resins and favor domestic compounders with certified recycling streams. PMDA's pharmaceutical packaging guidelines further narrow approved material grades, concentrating supplier qualification burdens on a limited pool of certified molders. Stakeholders must track PET chemical recycling scale-up and biopolymer JIS certification timelines to anticipate raw-material qualification windows.
Market Dynamics
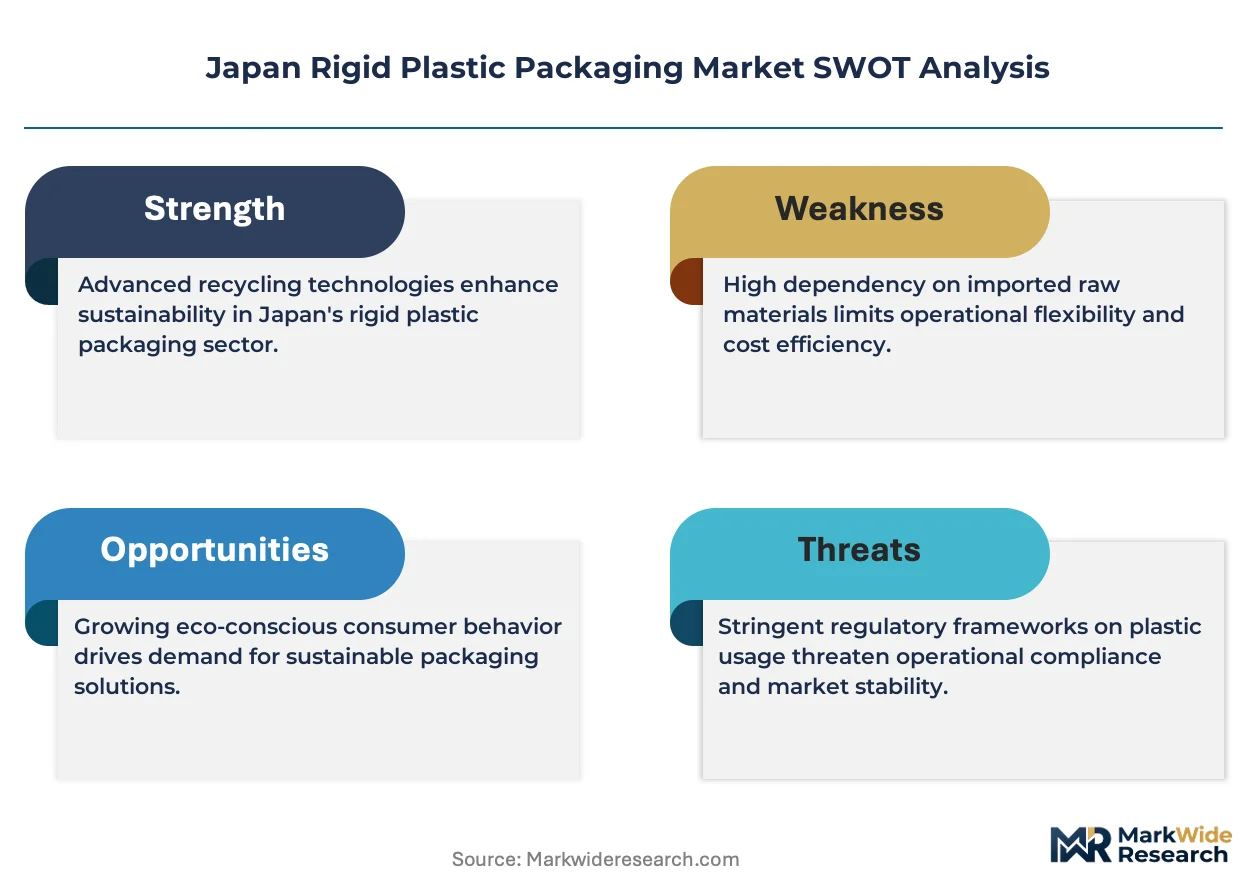
METI's Plastic Resource Circulation Strategy is forcing a structural recalibration across Japan's rigid plastic packaging value chain, as recycled-content mandates and chemical recycling scale-up timelines compress raw-material qualification windows for molders and brand owners alike.
Growth Catalysts
- Convenience store format expansion:Lawson, 7-Eleven Japan and FamilyMart are accelerating single-serve food packaging rollouts for grab-and-go bento and ready-to-drink tea segments, pulling demand for thin-wall polypropylene containers.
- METI's recycled-content mandates:The ministry's 2030 targets for post-consumer recycled plastic incorporation are redirecting procurement toward domestic compounders with certified mechanical and chemical recycling streams.
- Hot-fill compatibility requirements:Japanese ready-to-drink tea and sauce processors specify clarified polypropylene bottles that withstand 85°C filling temperatures, sustaining premium resin demand despite price differentials.
Market Restraints
- Feedstock cost volatility:Naphtha-derived polypropylene and polyethylene prices track crude oil and LNG import costs, compressing converter margins when yen depreciation amplifies import bills.
- Domestic resin supply concentration:Japan's ethylene crackers cluster in Chiba and Yamaguchi prefectures, creating geographic vulnerability to typhoon disruptions and maintenance synchronizations.
- Glass and aluminum substitution:Premium sake and craft beverage brands are reverting to glass bottles for perceived quality differentiation, eroding rigid plastic's share in alcoholic beverages.
Strategic Opportunities
- Kansai underpenetration:Osaka-Kobe industrial corridor holds lower rigid plastic packaging intensity versus Kanto, offering white space for pharmaceutical and cosmetics molders establishing secondary supply nodes.
- Pharmaceutical serialization mandates:PMDA's track-and-trace regulations for prescription drugs are creating demand for tamper-evident rigid containers with integrated RFID or 2D code authentication features.
- Chemical recycling JIS certification:Early movers achieving Japan Industrial Standards approval for pyrolysis-derived resins will secure preferred-supplier status ahead of 2027 compliance deadlines.
Industry Challenges
- Recycled resin quality consistency:Mechanical recycling of post-consumer polypropylene yields odor and color variations that disqualify batches for food-contact applications, forcing parallel virgin resin stocking.
- Mold retrofitting capex cycles:Transitioning to recycled-content or biopolymer grades requires screw and hot-runner modifications that idle production lines for 2-3 weeks per mold set.
- Cross-regional logistics reconfiguration:Kanto-based molders serving Kyushu food processors face rising freight costs and carbon accounting pressures that erode landed cost competitiveness.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Rigid Plastic Packaging Market |
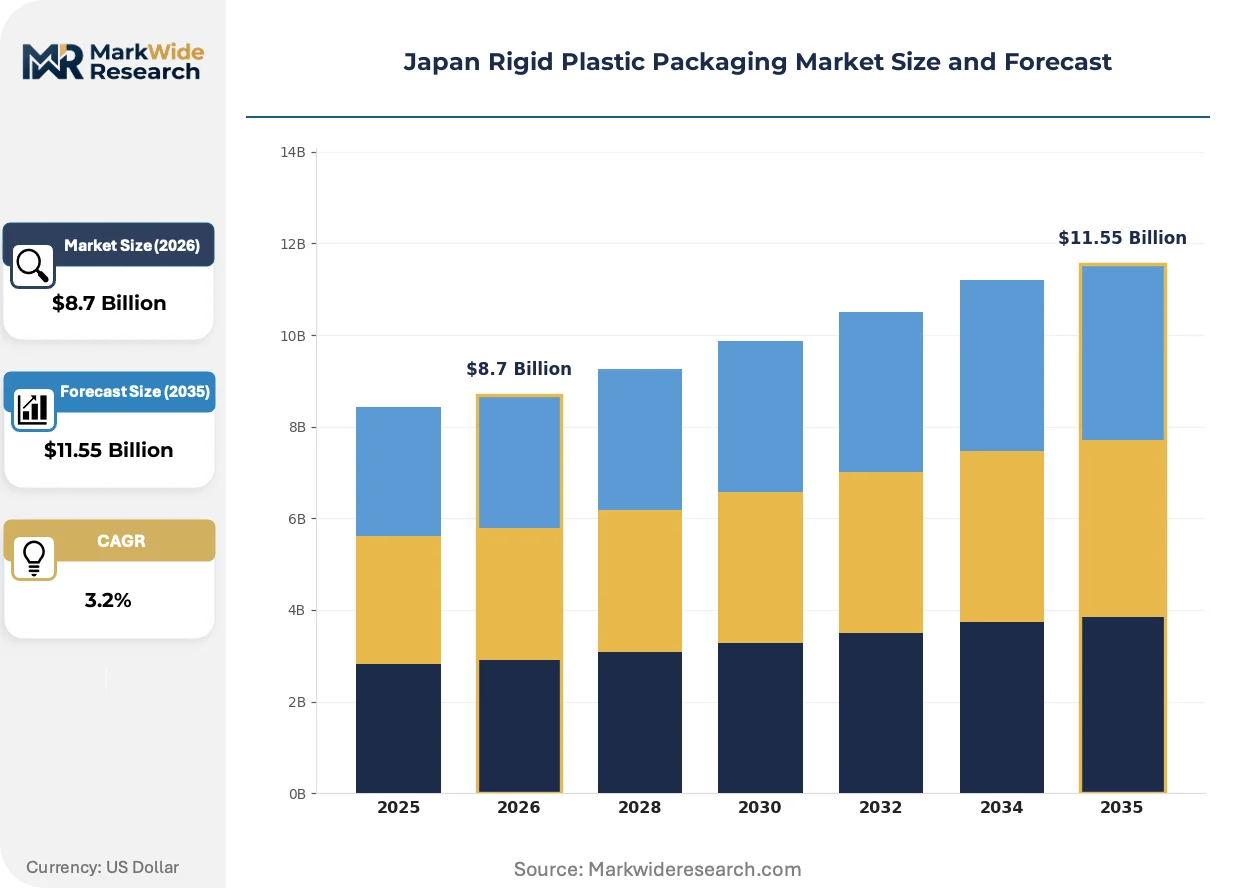
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $11.55 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Containers, Jars, Boxes Material: Polyethylene, Polypropylene, Polyvinyl Chloride, Polystyrene End User: Food & Beverage, Pharmaceuticals, Cosmetics, Electronics Packaging Type: Labelled, Printed, Tamper-Evident, Resealable |
| Companies Covered | Toyo Seiken Group Holdings Ltd, Takemoto Yohki Co Ltd, Sonoco Products Company, Sealed Air Corporation, Amcor Group GmbH, Kodama Plastics Co Ltd, Hokkan Holdings Ltd, Meiji Rubber & Chemical Co Ltd, Nihon Yamamura Glass Co Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Rigid Plastic Packaging Market Trends and Innovations
Japanese rigid plastic packaging is undergoing a technology-driven restructuring where material science advances, regulatory compliance automation, and retail format evolution are converging to redefine competitive positioning across food, pharmaceutical, and cosmetics segments.
Mono-material polypropylene structures are integrating soluble adhesive labels and compatible tamper-evident closures to achieve full-container recyclability without sorting contamination. Cosmetics houses including Shiseido and Kao are piloting these designs for premium skincare lines ahead of 2025 JIS recyclability mark requirements. The technology is integrating design-for-recycling principles into early-stage product development, compressing time-to-certification for sustainable packaging claims.
METI's Plastic Resource Circulation Strategy is mandating corporate plastic footprint disclosures and recycled-content minimums that escalate through 2030. Food-contact converters must now maintain dual supply chains—virgin for pharmaceutical and infant nutrition grades, certified recycled for general food applications. Pharmaceutical packaging bears the heaviest compliance burden, as PMDA maintains separate material-grade approvals that lag chemical recycling certification timelines by 12-18 months.
Convenience store chains are consolidating supplier bases around full-service packaging partners capable of design, molding, and in-store display integration. Lawson's specification evolution now favors molders offering modular container families with standardized 50mm neck finishes across multiple volume SKUs. This concentration pattern is most visible in Greater Tokyo, where four chains account for over sixty percent of single-serve food packaging procurement volume.
Japan Rigid Plastic Packaging Market Segmentation
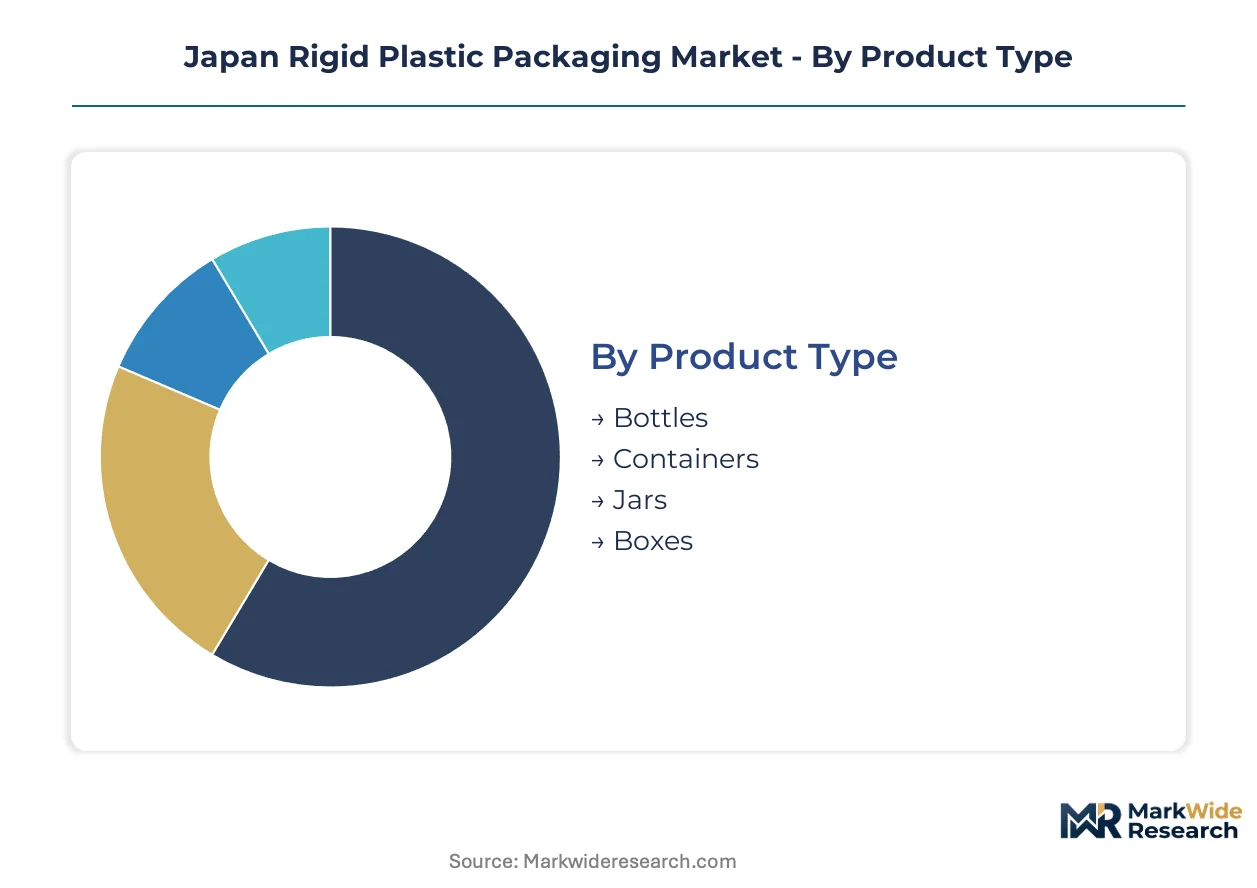
Segmentation in Japan's rigid plastic packaging market reveals how capital deployment, regulatory compliance burdens, and end-use specifications fragment manufacturing capabilities. Each dimension—product form, resin chemistry, customer industry, and functional feature—creates distinct qualification barriers that shape supplier specialization patterns.
Product Type:
Bottles and containers demand the heaviest upfront tooling investment, with multi-cavity blow molds and high-speed capping lines requiring dedicated cleanroom infrastructure for pharmaceutical and food-contact applications.
- Bottles:Blow-molded structures with calibrated neck finishes dominate ready-to-drink tea and sauce segments. Hot-fill compatibility specifications—85°C resistance thresholds—favor clarified polypropylene resins from domestic compounders with METI-certified recycling streams. Lawson and 7-Eleven Japan consolidate procurement around standardized 50mm neck formats to enable cap interchangeability across SKUs.
- Containers:Injection-molded rectangular formats with integrated stacking features serve bento and prepared-meal channels. Thin-wall designs reduce resin throughput per unit while maintaining dimensional stability for automated filling lines. Kanto-based molders capture the bulk of convenience store chain contracts through proximity to Greater Tokyo distribution hubs.
- Jars:Wide-mouth designs with threaded closures anchor premium skincare and pharmaceutical positioning. Custom-molded specifications for Shiseido and Kao require dedicated mold sets with 12-16 week lead times.
- Boxes:Thermoformed trays and hinged-lid formats target electronics and industrial components. Lower barrier requirements permit recycled-content incorporation ahead of JIS certification timelines for food-contact grades.
Most installed capacity flows through bottles. Expansion is steepest in containers.
Material:
Resin selection determines processing equipment compatibility, regulatory qualification pathways, and end-use temperature performance—locking molders into specific compounder relationships.
- Polyethylene:HDPE and LDPE grades sustain steady replacement demand from bento channels and chemical drum applications. Lower melt temperatures enable faster cycle times on refurbished injection equipment, attracting mid-cap converters serving regional food processors.
- Polypropylene:Clarified homopolymer and random copolymer grades command premium positioning for hot-fill bottles and microwaveable containers. Chiba and Yamaguchi ethylene crackers supply domestic resin with certified mechanical recycling content, though odor and color variation in post-consumer batches disqualify food-contact lots.
- Polyvinyl Chloride:Rigid PVC persists in pharmaceutical blister packs and blood collection tubes where PMDA maintains separate material-grade approvals. Plasticizer migration limits under JIS standards constrain formulation flexibility and elevate testing costs.
- Polystyrene:General-purpose and high-impact grades retreat to electronics cushioning and disposable cutlery as METI's recycled-content mandates pressure single-use applications. Chemical recycling scale-up for styrenic resins lags polyolefin timelines by 24-36 months.
Polypropylene absorbs the greatest capital deployment for hot-fill tooling. Polyethylene offers the lowest barrier to recycled-content compliance.
End User:
Customer industry determines regulatory burden intensity, with pharmaceutical and infant nutrition applications imposing the strictest material-grade segregation requirements.
- Food & Beverage:Convenience store chains and ready-meal processors drive volume through standardized container families. METI's plastic footprint disclosure mandates force dual supply chain maintenance—virgin resin for premium lines, certified recycled for mass-market SKUs.
- Pharmaceuticals:PMDA serialization regulations for prescription drugs create demand for tamper-evident rigid containers with integrated 2D code authentication. Material-grade approvals lag chemical recycling certification, compressing raw-material qualification windows for early movers.
- Cosmetics:Premium skincare brands pilot mono-material polypropylene structures with soluble adhesive labels to achieve JIS recyclability mark compliance. Custom-molded jar specifications favor molders with in-house design capabilities and deep color-matching expertise.
- Electronics:ESD-safe polystyrene trays and conductive polyethylene totes serve semiconductor and precision component logistics. Lower regulatory barriers permit faster adoption of post-industrial recycled content.
Food & Beverage channels dominate volume throughput. Pharmaceuticals concentrate margin capture.
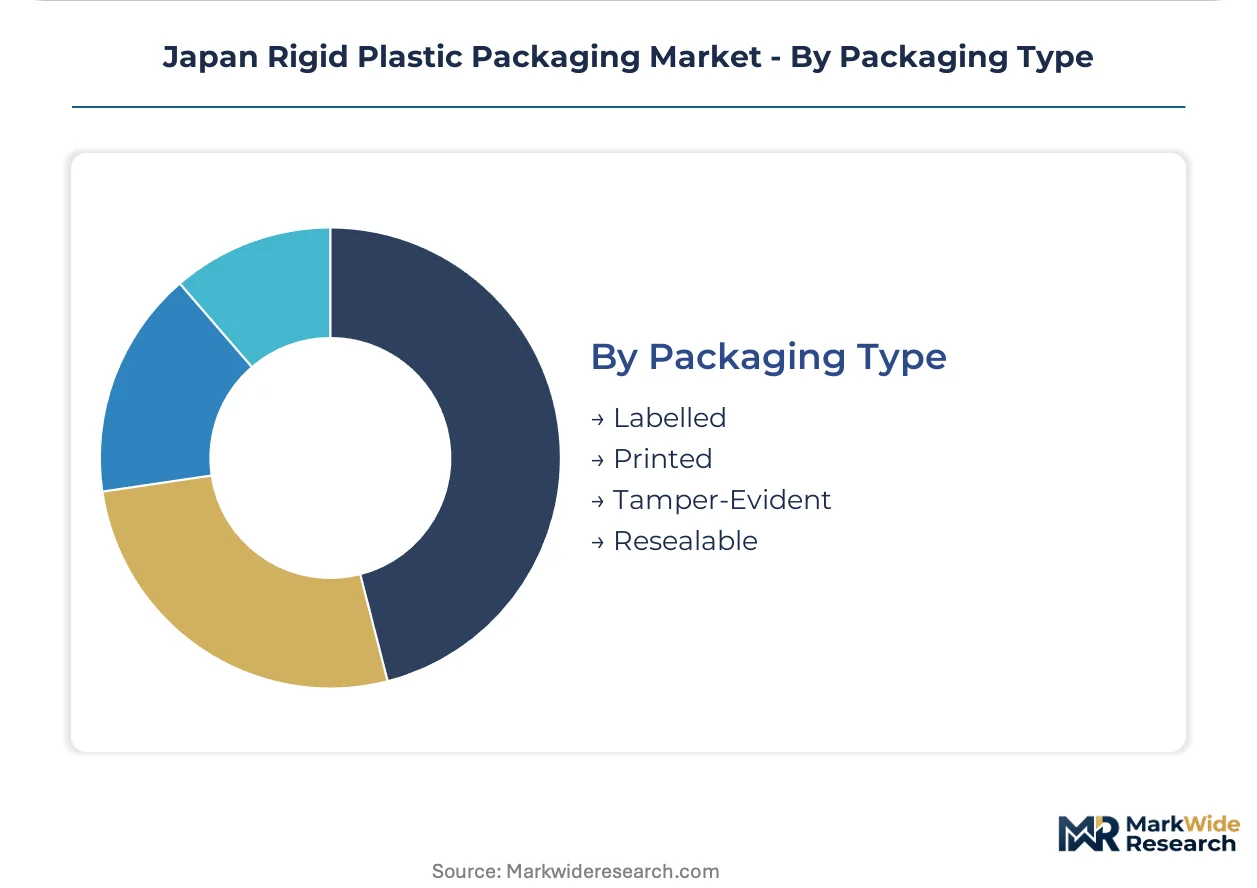
Packaging Type:
Functional feature integration determines automation compatibility and retail display performance, with tamper-evident and resealable formats commanding specification premiums.
- Labelled:Pressure-sensitive and shrink-sleeve applications face sorting contamination risks in mechanical recycling streams. Cosmetics houses accelerate soluble adhesive pilots to preserve container recyclability under 2025 JIS mark requirements.
- Printed:Direct-container printing via dry-offset or digital methods eliminates label substrate waste. High minimum order quantities favor national brand owners with centralized SKU management.
- Tamper-Evident:Break-band closures and induction-sealed membranes command margin premiums in pharmaceuticals and infant nutrition. Regulatory compliance costs deter commodity competition, concentrating supply among PMDA-qualified molders.
- Resealable:Hinged lids and snap-fit closures extend product usability for multi-serve sauces and prepared salads. Convenience store chains specify modular cap families compatible across bottle volumes to reduce in-store handling complexity.
Tamper-evident formats concentrate supplier qualification burdens. Resealable designs gain fastest share in prepared-meal segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japan's rigid plastic packaging industry traces its modern scale to post-war petrochemical investments along Tokyo Bay and Osaka Bay corridors. Domestic resin compounding and precision molding capabilities concentrated in these coastal industrial zones during the 1960s-1980s export manufacturing boom. Today regional specialization patterns reflect this inherited infrastructure.
Kanto/Tokyo
Greater Tokyo anchors Japan's rigid plastic packaging demand through convenience store headquarters and food processor clusters. METI's Plastic Resource Circulation Strategy enforcement concentrates compliance expertise in Chiba prefecture resin compounders. The Keihin industrial corridor stretching from Tokyo to Yokohama hosts the densest concentration of pharmaceutical and cosmetics molders serving Shiseido, Kao, and PMDA-regulated drug manufacturers.
Kansai/Osaka
Osaka-Kobe corridor holds lower packaging intensity versus Kanto but offers expansion white space for pharmaceutical molders. The region's sake and traditional food processors maintain stronger glass packaging loyalty, slowing rigid plastic penetration. Hyogo prefecture molders increasingly target secondary supply node status for Kyushu-bound shipments seeking freight cost relief from Tokyo-centric logistics.
Chubu/Nagoya
Toyota's automotive supply base generates specialized demand for ESD-safe polystyrene trays and conductive polyethylene totes. Aichi prefecture molders serve semiconductor logistics with lower regulatory barriers permitting faster recycled-content adoption. The region's industrial packaging segment operates somewhat decoupled from food-contact compliance cycles dominating Kanto procurement.
Kyushu
Fukuoka and Saga prefectures host food processing clusters supplying convenience store chains with prepared meals and bento. Kanto-based molders face rising freight costs and carbon accounting pressures serving these southern markets. Local resin stocking remains thin, forcing reliance on Chiba and Yamaguchi ethylene cracker shipments across the Seto Inland Sea.
Hokkaido
Dairy and seafood processing drives seasonal packaging demand spikes in Hokkaido's industrial zones. The island's geographic isolation necessitates higher safety stock levels and longer procurement lead times. Sapporo-based distributors increasingly consolidate orders to justify dedicated container shipments from Honshu resin suppliers.
Japan Rigid Plastic Packaging Market Competitive Landscape
Premium-margin players sit above commodity-margin players across regulatory qualification intensity, with PMDA-certified molders commanding specification premiums over general food-contact converters. The vendor base stratifies into three tiers: integrated resin-to-package conglomerates, specialized pharmaceutical-cosmetics molders, and regional food-container specialists. Consolidation pressure runs highest among mid-cap converters lacking certified recycling streams or in-house design capabilities. Dominant competitive moves include backward integration into resin compounding and geographic expansion toward underpenetrated Kansai pharmaceutical corridors.
Within the integrated manufacturing tier, Toyo Seiken Group Holdings Ltd exemplifies vertical control spanning bottle and closure production. Takemoto Yohki Co Ltd occupies a position among custom-molded jar specialists serving premium skincare positioning. Kodama Plastics Co Ltd represents thin-wall injection molding efficiency optimization. These three Japanese Co., Ltd. structures anchor distinct competitive archetypes: full-service integration, design-forward specialization, and process-cost minimization.
| Leading Market Players |
|---|
| Toyo Seiken Group Holdings Ltd |
| Takemoto Yohki Co Ltd |
| Sonoco Products Company |
| Sealed Air Corporation |
| Amcor Group GmbH |
| Kodama Plastics Co Ltd |
| Hokkan Holdings Ltd |
| Meiji Rubber & Chemical Co Ltd |
| Nihon Yamamura Glass Co Ltd |
| Others |
Pricing and Supply Chain Analysis
METI's recycled-content mandates gate both qualified supply and premium-tier pricing access, concentrating certified resin streams among domestic compounders while forcing dual-inventory costs onto converters seeking pharmaceutical-grade premiums. This regulatory filtering compresses margin structures for uncertified imports and elevates pricing power for Chiba and Yamaguchi-based suppliers with mechanical recycling verification.
Pricing Analysis
Three-tier pricing structure across PMDA-certified pharmaceutical, food-contact JIS-grade, and industrial non-food tiers separates margin capture by compliance burden. Price differentiation hinges on resin certification tier and mold retrofit amortization schedules. Cost compression in mass-market food containers is intensifying because thin-wall cycle-time competition erodes per-unit contribution. Convenience store chains exhibit highest price sensitivity, while pharmaceutical houses absorb premiums for serialization-ready tamper-evident formats.
Supply Chain Analysis
Freight cost differentials between Kanto and Kyushu are restructuring procurement geography, with Osaka-Kobe molders capturing secondary supply node status for southern food processors. Domestic resin compounding concentrates in Chiba and Yamaguchi prefectures, drawing from naphtha feedstocks tied to LNG import pricing. Single-source vulnerability runs through the Keihin corridor's ethylene cracker cluster, where synchronized maintenance windows disrupt regional availability. Distribution runs through consolidated logistics hubs serving Lawson, 7-Eleven Japan, and FamilyMart specification requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's rigid plastic packaging market offers geographic-arbitrage value through Kansai underpenetration, where pharmaceutical molders face lighter regulatory compliance density versus Kanto despite comparable end-user demand.
For Market Incumbents: Cement dominance in PMDA-certified pharmaceutical packaging by acquiring secondary Kansai production nodes before chemical recycling JIS deadlines compress qualification windows. Backward integration into resin compounding with METI-verified mechanical recycling streams defends margin position against imported virgin price volatility. Channel control through Lawson's consolidated supplier base specifications protects volume throughput against regional challengers. For New Entrants and Emerging Players: Convenience store distributors offer the fastest route to volume scale, with modular container families matching 50mm neck standardization requirements. White space concentrates in Kansai pharmaceutical corridors, where PMDA serialization mandates outpace local molder certification capacity. Osaka-Kobe logistics positioning captures freight savings on Kyushu-bound shipments while avoiding Kanto cracker concentration risk. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap pharmaceutical molders because PMDA qualification burdens deter new entrant competition and sustain pricing premiums through regulatory moats. Long-term viability centers on chemical recycling certification timing, with early JIS approval unlocking preferred-supplier status ahead of compliance deadlines. The signal to watch is pyrolysis-derived resin qualification velocity at domestic compounders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captures METI-certified recycling streams before import resin qualification windows close. |
| Kansai Pharmaceutical Molder Acquisition | Secures secondary supply node positioning for PMDA serialization mandate demand. |
| Chemical Recycling JIS Certification Investment | Unlocks preferred-supplier status with food-contact converters facing 2030 targets. |
| Modular Container Family Development | Matches Lawson and 7-Eleven Japan standardized neck finish procurement consolidation. |
| Thin-Wall Injection Cycle Optimization | Reduces resin throughput per unit for bento channel price-competitive positioning. |
Research Methodology
Direct dialogue with resin compounder technical directors, pharmaceutical packaging procurement managers, convenience store supply chain leads, and METI policy officers grounded qualitative findings in operational reality. Secondary validation drew from JIS standards documentation, PMDA pharmaceutical packaging guidelines, METI plastic resource circulation strategy publications, and customs trade data on polymer imports. Bottom-up triangulation across molder capacity disclosures and top-down demand modeling from convenience store format expansion plans converged on volume estimates.
Top-down macroeconomic drivers filtered through bottom-up segment granularity across product type, resin chemistry, end-use industry, and functional feature dimensions. CAGRs emerged from weighted-average growth contributions by segment, with pharmaceutical serialization mandates and convenience store single-serve format rollouts supplying demand-side elasticity parameters. Raw-material qualification windows and chemical recycling scale-up timelines informed supply-side constraint modeling.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to yen depreciation trajectories, naphtha price volatility, and JIS certification timeline shifts. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rigid Packaging
Europe Rigid Plastic Packaging Market
Rigid Packaging
Nutraceutical Rigid Packaging Market
Rigid Packaging
Spain Rigid Plastic Packaging Market
Rigid Packaging
Poland Rigid Plastic Packaging Market
Rigid Packaging
Rigid Trays Market
Rigid Packaging
Egypt Rigid Plastic Packaging Market
Rigid Packaging
United States Rigid PET Packaging Market
Rigid Packaging
Latin America Rigid Plastic Packaging Market
Rigid Packaging
India Rigid Plastic Packaging Market
Rigid Packaging
Mexico Rigid Packaging Market
Rigid Packaging
GCC Rigid Packaging Market
Rigid Packaging
North America Rigid Bulk Packaging Market
Rigid Packaging
Morocco Rigid Plastic Packaging Market
Rigid Packaging
GCC Rigid Plastic Packaging Market
Rigid Packaging
Rigid Transparent Plastic Market
Rigid Packaging
United Kingdom Rigid Plastic Packaging Market