
 Rigid Boxes Market | 2026-2036
Rigid Boxes Market Size, Share, and Industry Trends Forecast 2026-2036
Rigid Boxes Market Intelligence
European paperboard producers is restructuring capacity toward specialty grades for rigid box manufacturing. DS Smith leverages integrated pulp-to-box operations across Nordic mills to secure fiber supply. Mondi Group Plc anchors its position through kraft paper innovation for high-strength rigid applications. Smurfit Kappa Group Plc competes on corrugated-to-rigid hybrid designs that reduce material intensity.
Rigid boxes are paper-based containers constructed from thick paperboard or chipboard, typically exceeding 0.012 inch caliper, formed through cutting, scoring, and folding processes to create structurally stable enclosures that protect goods during transit and display. Folding boxes dominate volume throughput in food packaging and mass retail, while setup boxes command premium positioning in cosmetics and luxury goods where unboxing experience drives brand equity. Magnetic closure boxes represent the fastest-growing design segment, propelled by electronics brands seeking reusable packaging that extends consumer engagement beyond point of sale.
The EU Packaging and Packaging Waste Regulation and REACH chemical compliance frameworks mandate recyclability thresholds and restricted substance limits that reshape material selection across European rigid box supply chains. The US EPA and state-level extended producer responsibility laws in California and New York impose parallel compliance burdens on exporters serving North American brands. Stakeholders must monitor evolving fiber certification requirements from FSC and PEFC, as brand owners increasingly predicate supplier contracts on verified sustainable sourcing credentials.
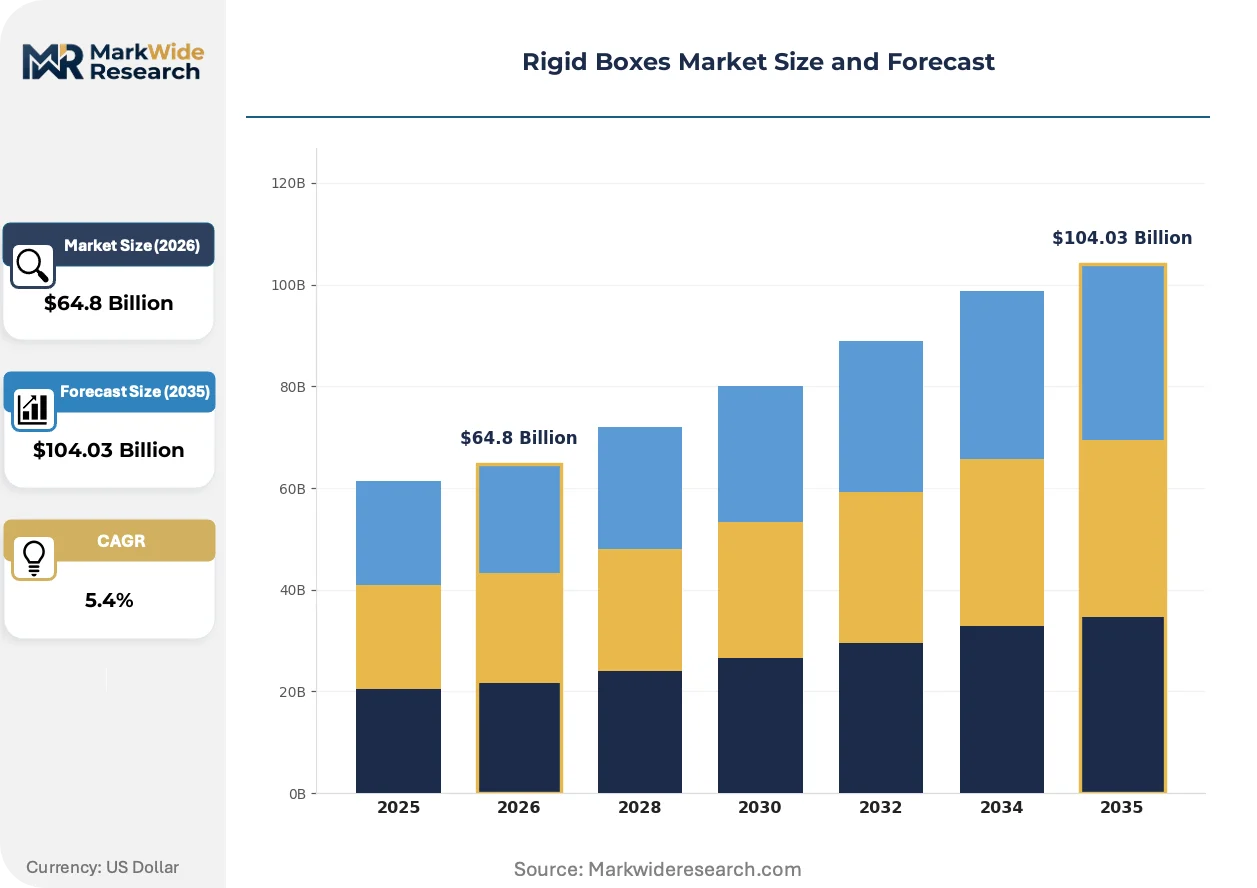
Market Dynamics
EU Packaging and Packaging Waste Regulation mandates are compressing material recovery timelines while China's Guangdong electronics cluster drives high-volume custom rigid packaging procurement, creating divergent compliance and scale pressures across supply chains.
Growth Catalysts
- REACH chemical compliance frameworks:European cosmetics brands accelerate rigid box adoption for premium unboxing experiences that signal regulatory adherence and material traceability.
- Magnetic closure design innovation:Electronics manufacturers in Shenzhen and Dongguan specify reusable rigid packaging to extend consumer brand engagement cycles.
- Kraft paper fiber innovation:Nordic pulp-to-box integration secures specialty-grade supply for high-strength rigid applications serving luxury goods.
Market Restraints
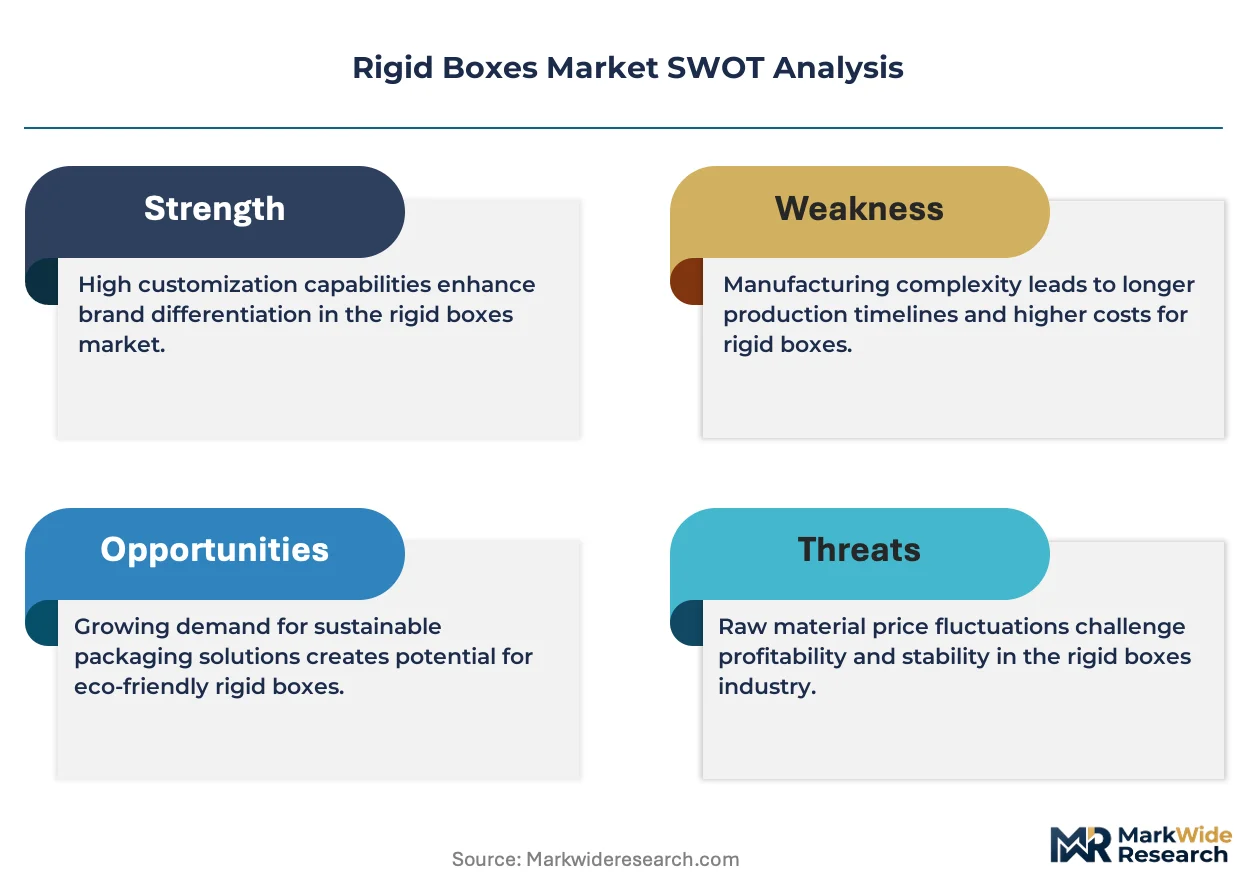
- Pulp price volatility:Northern European softwood fiber costs fluctuate with energy market instability, compressing margin structures for paperboard-dependent converters.
- Guangdong supplier concentration:Electronics OEM procurement clusters within 200 kilometers of Shenzhen, creating single-region exposure for volume-dependent rigid box manufacturers.
- Folding carton substitution:Mass retail brands in food and beverage sectors migrate to lighter-weight folding formats that reduce material intensity and shipping cube.
Strategic Opportunities
- India PLI scheme for electronics manufacturing:Smartphone and component assembly expansion in Noida and Sriperumbudur generates first-mover rigid packaging demand from domestic suppliers.
- FSC certification premium tier:Verified sustainable sourcing credentials command supplier contract preference from European luxury cosmetics and spirits brands.
- Corrugated-to-rigid hybrid formats:Material-efficient structural designs capture mid-market positioning between premium setup boxes and commodity folding cartons.
Industry Challenges
- Die-cutting precision engineering:Magnetic closure and specialty fold configurations require capital-intensive tooling investments that strain mid-cap converter balance sheets.
- Dual certification timelines:Simultaneous FSC chain-of-custody and PEFC tracking documentation extends supplier qualification cycles for multinational brand owners.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rigid Boxes Market |
| Market Size in 2026 | $64.8 Billion |
| Market Size in 2035 | $104.03 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Folding Boxes, Setup Boxes, Slide Boxes, Magnetic Closure Boxes Material: Cardboard, Chipboard, Paperboard, Plastic End User: Cosmetics, Electronics, Apparel, Food Packaging Design Type: Custom Design, Stock Design, Luxury Design, Eco-Friendly Design |
| Companies Covered | Stora Enso Oyj, DS Smith, International Paper Company, Georgia Pacific LLC, Sonoco, WestRock, Mondi Group Plc, Kwick Packaging, Smurfit Kappa Group Plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rigid Boxes Market Strategic Shifts & Innovations
Material science advances and regulatory compliance architectures are restructuring how rigid boxes deliver structural performance, brand differentiation, and circular economy credentials across divergent end-use requirements.
Digital print enhancement is converging with tactile finishing techniques to enable short-run customization for limited-edition cosmetics and spirits releases. French and German luxury houses now specify 500-unit minimum orders with holographic foil and soft-touch lamination. This capability compression collapses traditional economies of scale, fragmenting volume toward agile regional converters.
REACH restricted substance lists and RoHS material declarations are forcing reformulation of adhesives, coatings, and closure magnets across European supply chains. Electronics brands exporting to Germany and France now require full material disclosure documentation. High-value magnetic closure segments face the steepest compliance recertification burdens.
Direct-to-brand specification platforms are displacing traditional distributor relationships in North American premium packaging procurement. California and New York-based cosmetics startups now engage Guangdong manufacturers through digital sampling and virtual proofing workflows. This channel disintermediation compresses lead times but exposes smaller buyers to minimum order quantity constraints and quality assurance gaps.
Rigid Boxes Market Segmentation
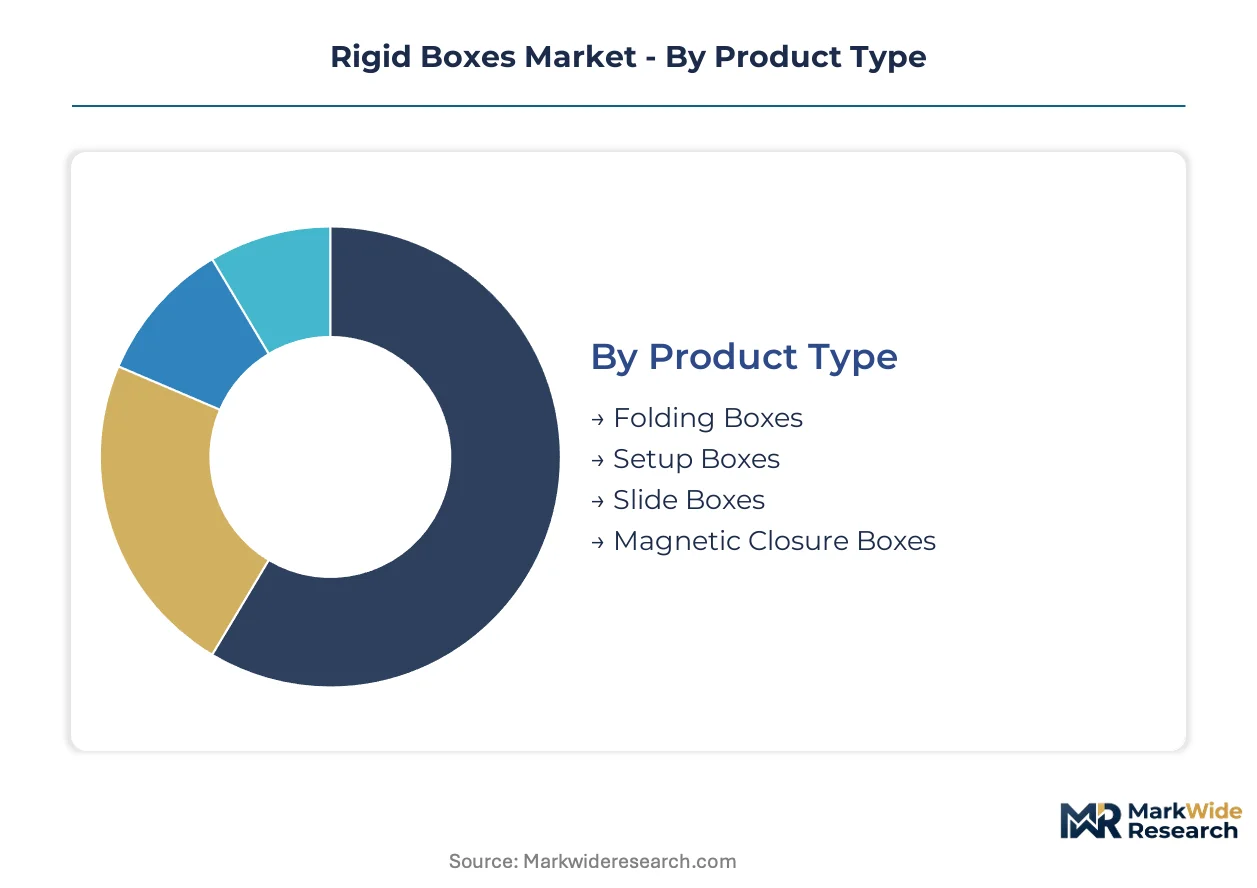
Segmentation in rigid boxes separates premium positioning from commodity throughput. Material grade and closure mechanism determine margin capture, while end-use concentration in Guangdong electronics and French luxury cosmetics creates divergent specification requirements.
Product Type:
Replacement cycles accelerate where unboxing experience drives repeat purchase behavior. Electronics brands refresh magnetic closure specifications every 18-24 months to sustain consumer engagement.
- Folding Boxes:These containers ship flat and convert on automated lines, reducing shipping cube for mass retail distribution. Food brands in Germany and the Netherlands specify folding formats for cereal and confectionery to minimize logistics spend.
- Setup Boxes:Pre-assembled rigid structures with glued corners deliver structural integrity for heavy or fragile contents. French luxury cosmetics houses in Paris and Grasse mandate setup construction for flagship fragrance launches where shelf presence determines placement.
- Slide Boxes:Drawer-style mechanisms with ribbon pulls serve jewelry and accessory segments requiring controlled product reveal. Mid-tier apparel brands specify slide formats for gift-with-purchase programs.
- Magnetic Closure Boxes:Embedded neodymium magnets enable reusable storage functionality. Shenzhen electronics OEMs specify these for smartphone and wearable packaging to extend brand visibility in consumer homes.
Folding boxes sit at the top of the volume ranking, with magnetic closure boxes climbing the fastest.
Material:
Cost tiers stratify around fiber source and caliper thickness. Nordic integrated pulp-to-box operations command premium positioning through specialty kraft grades.
- Cardboard:Single-ply recycled fiber construction serves price-sensitive mass retail applications. German discount grocery chains specify cardboard rigid formats for private-label cosmetics to hit margin targets.
- Chipboard:Multi-layered grayboard with clay coating accepts high-fidelity print for premium positioning. Spirits brands in Scotland and Cognac specify chipboard for gift sets requiring tactile lamination and foil stamping.
- Paperboard:Bleached chemical pulp delivers brightness and rigidity for luxury unboxing experiences. Swedish paperboard mills supply FSC-certified grades to Paris-based cosmetics houses under long-term contracts.
- Plastic:PET and PP rigid formats serve moisture-sensitive electronics and medical device segments. REACH compliance burdens restrict plastic adoption in European consumer packaging.
Paperboard sits at the top of the volume ranking, with chipboard gaining share fastest on sustainability credentials.
End User:
Application requirements diverge sharply on durability, print fidelity, and regulatory documentation. Electronics demands RoHS material declarations; cosmetics requires REACH full disclosure.
- Cosmetics:Premium skincare and fragrance brands specify rigid boxes with soft-touch lamination and holographic foil. L'Oréal and Estée Lauder procurement teams in France and the United States mandate FSC chain-of-custody documentation.
- Electronics:Smartphone, tablet, and wearable manufacturers in Shenzhen, Dongguan, and Noida specify magnetic closure formats with foam inserts. Apple's packaging engineering team sets specification benchmarks that Guangdong suppliers reverse-engineer.
- Apparel:Seasonal fashion cycles drive short-run custom orders with digital print enhancement. Italian luxury houses in Milan specify rigid shoe boxes with ribbon pulls for direct-to-consumer e-commerce.
- Food Packaging:Premium chocolate and confectionery brands in Belgium and Switzerland specify food-grade paperboard with grease-resistant coatings. Smaller order quantities and seasonal spikes strain converter capacity planning.
Electronics sits at the top of the volume ranking, with cosmetics climbing fastest on unboxing experience investment.
Design Type:
Customer type determines specification complexity and order quantity economics. Direct-to-brand platforms fragment volume toward agile regional converters.
- Custom Design:Bespoke structural engineering with die-cut windows and specialty folds serves limited-edition releases. California cosmetics startups specify 500-unit minimum orders through Guangdong digital sampling platforms.
- Stock Design:Standardized formats with variable print enable rapid turnaround for promotional campaigns. Mass retail brands in the United States leverage stock rigid boxes for holiday gift sets.
- Luxury Design:Multi-layer construction with velvet lining and metal hardware serves ultra-premium positioning. Swiss watchmakers and French champagne houses specify luxury formats with hand-finished details.
- Eco-Friendly Design:Unbleached kraft, soy-based inks, and water-based adhesives serve sustainability-mandated procurement. European Union Packaging and Packaging Waste Regulation compliance drives specification shifts toward mono-material recyclable formats.
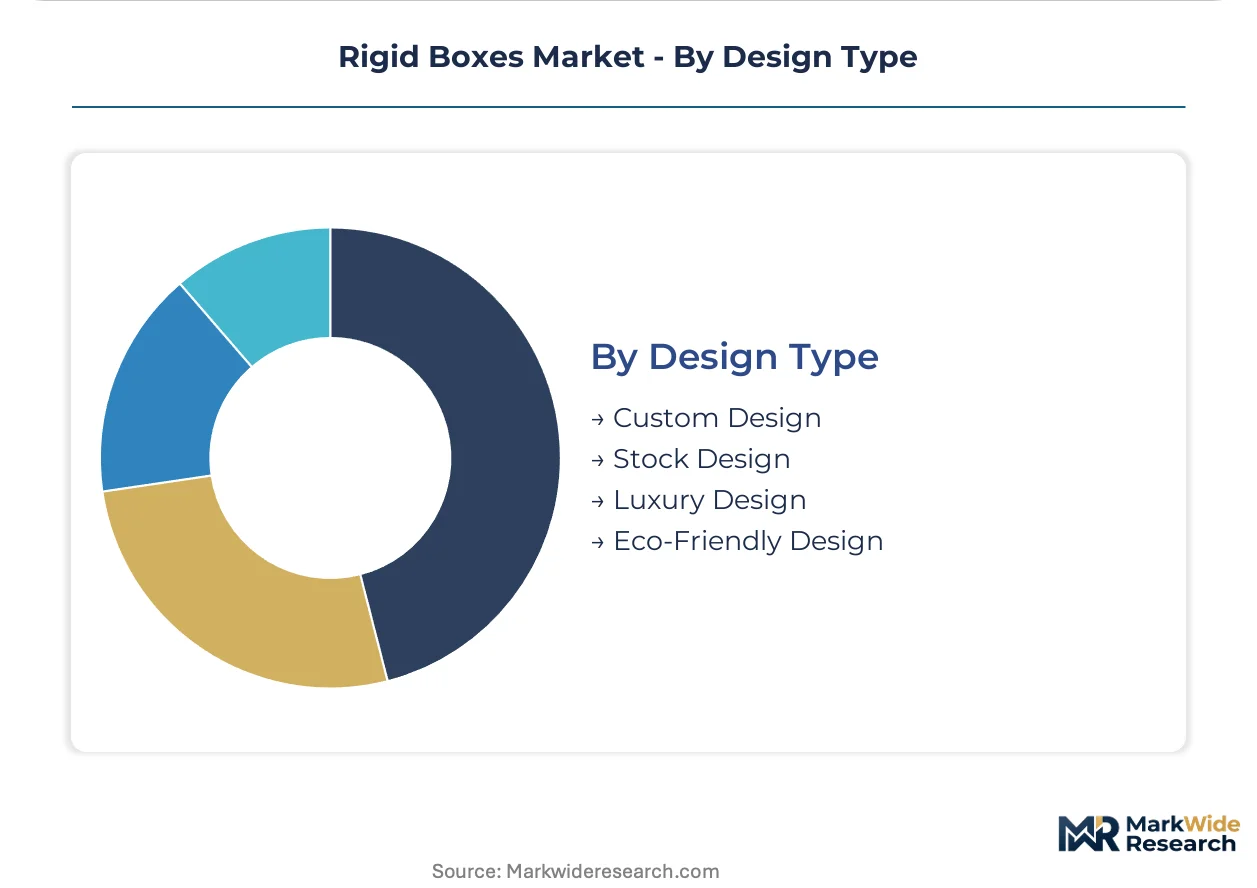
Stock design sits at the top of the volume ranking, with eco-friendly design climbing fastest on regulatory pressure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is reshaping rigid box manufacturing geography as European REACH compliance costs push volume procurement toward Asian suppliers with dual-certification capabilities. Cost-of-compliance gaps between EU and Asian fiber sourcing regimes now exceed 15 percentage points on comparable paperboard grades.
China
Shenzhen and Dongguan electronics OEMs drive magnetic closure box specifications for smartphones and wearables. MEE dual carbon goals pressure Guangdong mills to decarbonize kraft pulping operations. The Pearl River Delta cluster hosts 60 percent of global electronics rigid packaging capacity.
Germany
REACH restricted substance mandates accelerate adhesive and coating reformulation across Bavarian converter networks. KBA packaging machinery standards enforce die-cutting precision thresholds for luxury cosmetics applications. The North Rhine-Westphalia paperboard corridor supplies FSC-certified grades to Paris and Milan brand houses.
United States
California and New York extended producer responsibility laws impose parallel compliance burdens on exporters serving domestic cosmetics startups. EPA fiber sourcing guidelines intersect with state-level plastic reduction mandates. The Pacific Northwest pulp-to-box integration anchors supply for premium spirits packaging.
India
PLI scheme electronics manufacturing incentives generate first-mover rigid packaging demand from Noida and Sriperumbudur assembly clusters. BIS packaging standards for food-grade paperboard tighten import substitution requirements. Tamil Nadu converter investments target ASEAN export markets.
France
ANSM cosmetic packaging traceability rules mandate full material disclosure for Paris-based luxury houses. Grasse fragrance brands specify setup box construction with holographic foil and soft-touch lamination. The Île-de-France procurement hub consolidates specification authority for LVMH and Kering portfolios.
Rigid Boxes Market Key Industry Players
Nordic integrated pulp-to-box producers anchor the fiber-security tier; Guangdong specialists hold the high-volume custom fabrication tier. The vendor base splits between consolidated paperboard multinationals with captive fiber supply and fragmented regional converters competing on short-run agility. Three archetypes dominate: backward-integrated Nordic mills, corrugated-to-rigid hybrid designers, and magnetic closure engineering specialists. Competitive moves concentrate on M&A for specialty grade capacity and geographic expansion into India PLI electronics corridors.
Within the integrated mill tier, Stora Enso Oyj and Mondi Group Plc exemplify Nordic pulp-to-box operations securing specialty kraft supply. DS Smith occupies a position bridging European regulatory compliance expertise with Asian procurement relationships. These three anchors represent divergent strategic postures on fiber certification, geographic footprint, and premium segment positioning.
| Leading Market Players |
|---|
| Stora Enso Oyj |
| DS Smith |
| International Paper Company |
| Georgia Pacific LLC |
| Sonoco |
| WestRock |
| Mondi Group Plc |
| Kwick Packaging |
| Smurfit Kappa Group Plc |
| Others |
Cost & Logistics Intelligence
Northern European softwood fiber price indices cascade through rigid box supply chains into three distinct procurement tiers, with FSC-certified specialty grades commanding substantial premiums over recycled-content alternatives and unbleached kraft grades anchoring economy positioning.
Pricing Analysis
Distributor margins in European cosmetics procurement compress direct-to-OEM pricing by 12-18 percentage points relative to spot-market transactions. Three-tier pricing structure across premium, standard, and economy levels stratifies around certification grade and volume scale, with magnetic closure formats facing steepest cost compression due to neodymium magnet and REACH-compliant adhesive expenses. Price differentiation hinges on FSC chain-of-custody documentation and die-cutting precision thresholds. Pricing pressure stems from pulp price volatility in Nordic integrated mills, squeezing converter margins. Mass retail food brands exhibit highest price sensitivity; French luxury cosmetics houses demonstrate lowest sensitivity, prioritizing unboxing experience over unit cost.
Supply Chain Analysis
Single-source vulnerability sits with Guangdong province, where 60 percent of global electronics rigid packaging capacity clusters within 200 kilometers of Shenzhen. Raw material dependencies draw from Swedish bleached chemical pulp, German specialty kraft grades, and Chinese recycled fiber streams. Supply chain risk centers on regulatory restriction: EU Packaging and Packaging Waste Regulation mandates compress recovery timelines while REACH compliance costs exceed Asian regimes by 15 percentage points. Distribution runs through direct-to-brand digital platforms displacing traditional distributor relationships, particularly for North American cosmetics startups sourcing through Guangdong manufacturers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU REACH compliance costs push volume procurement toward Asian suppliers with dual-certification capabilities, exploiting the 15 percentage point cost-of-compliance gap between European and Asian fiber sourcing regimes.
For Market Incumbents: Extend FSC-certified specialty grade capacity in Nordic integrated mills to defend against corrugated-to-rigid hybrid substitution threatening premium positioning. Backward integration into captive kraft pulping operations secures fiber supply against Northern European softwood price volatility. Reinforce supplier qualification protocols to compress dual-certification timelines that strain multinational brand owner contracts. For New Entrants and Emerging Players: California and New York-based cosmetics startups represent an underserved buyer archetype seeking 500-unit minimum orders with holographic foil and soft-touch lamination. India's PLI scheme electronics manufacturing corridors in Noida and Sriperumbudur offer first-mover rigid packaging demand with limited domestic converter presence. Digital sampling platforms enable direct-to-brand engagement, bypassing traditional distributor relationships and capturing fragmented short-run volume. For Investors and Strategic Acquirers: Asymmetric upside sits with magnetic closure engineering specialists serving Shenzhen electronics OEMs, where 18-24 month specification refresh cycles sustain recurring revenue. Long-term viability over a 5-10 year window depends on dual-certification capabilities spanning FSC and PEFC documentation. Watch for India's BIS packaging standards tightening import substitution requirements as the inflection signal for domestic capacity investment.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Specialty Kraft Pulping | Nordic mills secure captive fiber supply against energy-market instability compressing margins. |
| Dual-Certification Capacity Investment | Converters qualify for L'Oréal and Estée Lauder contracts predicated on verified sustainable sourcing. |
| Magnetic Closure Engineering Specialization | Shenzhen electronics OEMs specify reusable formats extending consumer brand engagement cycles. |
| Digital Sampling Platform Deployment | Guangdong manufacturers compress lead times for California cosmetics startups through virtual proofing. |
| Corrugated-to-Rigid Hybrid Format Development | Smurfit Kappa captures mid-market positioning between premium setup boxes and commodity folding cartons. |
Research Approach
Bottom-up electronics and cosmetics procurement modeling reconciled against top-down paperboard production tracking forms the analytical core of this study. Primary interviews with converter operations managers, brand packaging engineers, pulp procurement leads, and FSC certification auditors combined with secondary validation from customs trade records, SEC 10-K filings of integrated paperboard multinationals, EU Packaging and Packaging Waste Regulation compliance databases, and REACH restricted substance list updates. Triangulation across these sources ensures demand-side and supply-side estimates converge.
Input-output matrices segment volume and value across product type, material grade, closure mechanism, and end-use concentration, with CAGRs derived from trend extrapolation moderated by regulatory inflection points. Segmentation dimensions span folding versus setup versus magnetic closure construction, paperboard versus chipboard versus cardboard material tiers, and electronics versus cosmetics versus food packaging end-use applications. Industry-specific forecast inputs incorporate Guangdong electronics OEM procurement cycles and French luxury cosmetics unboxing experience investment trajectories.
Underlying measurement precision varies by segment; magnetic closure and luxury design categories carry tighter precision than commodity folding box volumes due to concentrated buyer concentration and specification transparency. Forecasts reflect documented assumptions on pulp price trajectories, regulatory enforcement timelines, and substitution elasticity between rigid and folding formats. Pulp price volatility, REACH compliance recertification burdens, and folding carton substitution in mass retail present specific revision risks. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rigid Packaging
Gable Top Packaging Market
Rigid Packaging
Rigid Plastic Packaging Market
Rigid Packaging
Middle East and Africa Rigid Plastic Packaging Market
Rigid Packaging
Global Plastic Rigid IBC Market
Rigid Packaging
Latin America Rigid Plastic Packaging Market
Rigid Packaging
Egypt Rigid Plastic Packaging Market
Rigid Packaging
Nutraceutical Rigid Packaging Market
Rigid Packaging
GCC Rigid Packaging Market
Rigid Packaging
North America Rigid Plastic Packaging Market
Rigid Packaging
Asia-Pacific Rigid Bulk Packaging Market
Rigid Packaging
Saudi Arabia Rigid Plastic Packaging Market
Rigid Packaging
Spain Rigid Plastic Packaging Market
Rigid Packaging
Canada Rigid Plastic Packaging Market
Rigid Packaging
United States Rigid PET Packaging Market
Rigid Packaging
Tray Sleeve Market
Rigid Packaging
Rigid Food Containers Market