
 Italy Rigid Plastic Packaging Market | 2026-2036
Italy Rigid Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Italy Rigid Plastic Packaging Market Insights
Asset-light leasing models for injection and blow-molding equipment is tilting competitive dynamics toward mid-sized converters that previously faced capital barriers. Amcor Group GmbH leverages its European film and rigid operations to sustain integrated supply relationships with Italian food processors. Berry Global Inc anchors its position through large-scale thermoforming capacity serving pan-European dairy and prepared-meal brands. Bormioli Pharma SpA specializes in pharmaceutical-grade PET and glass-plastic hybrid solutions, occupying a defensible niche amid tightening drug-contact material standards.
Italy rigid plastic packaging encompasses bottles, containers, jars, and trays formed through extrusion blow molding, injection stretch blow molding, or thermoforming from resins including polyethylene terephthalate, polypropylene, polyvinyl chloride, and polystyrene, with wall thicknesses and barrier properties engineered to protect contents from moisture, oxygen, and mechanical damage across distribution cycles. The primary commercial purpose centers on extending shelf stability for food, beverages, pharmaceuticals, and consumer goods while enabling brand differentiation through shape, clarity, and label adhesion. Bottles dominate volume flows in beverage and personal care applications where PET clarity and lightweighting drive procurement decisions. Containers capture expanding share in prepared foods and home care segments as portion-control formats multiply. Trays represent the fastest-growing structural category, fueled by fresh-protein and ready-meal merchandising trends in Italian retail channels.
Italy's Ministry of Ecological Transition enforces the EU Single-Use Plastics Directive through national implementation measures that mandate recycled content thresholds and extended producer responsibility fees, directly elevating demand for rPET and mechanically recycled polypropylene. BIS-equivalent conformity assessments for food-contact materials, administered through Italy's Ministry of Health and ISS (Istituto Superiore di Sanità), shape formulation choices and supplier qualification protocols for converters serving export markets. Stakeholders must monitor how pending revisions to the EU Packaging and Packaging Waste Regulation recalibrate recyclability definitions and reuse targets, as these will determine which resin platforms and format designs retain economic viability in Italian manufacturing.
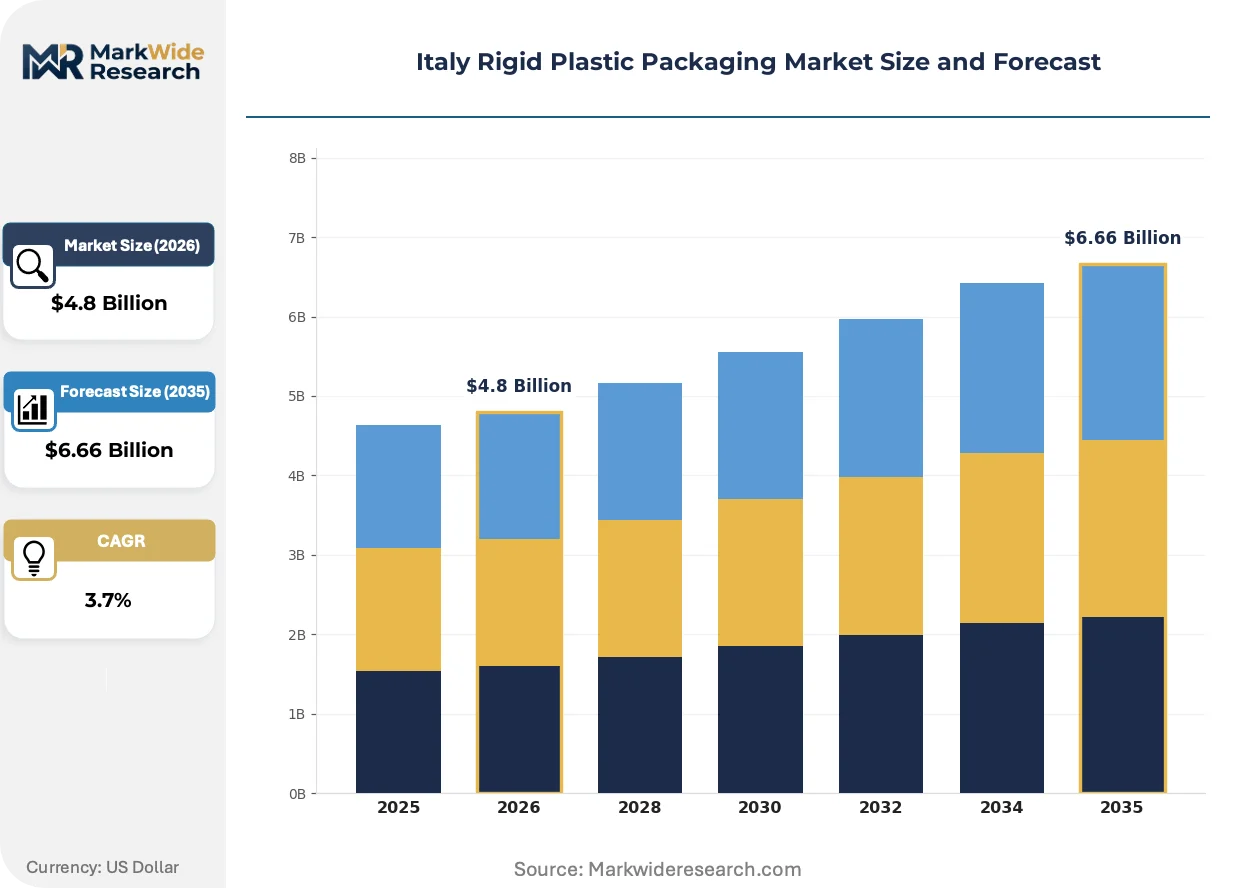
Market Dynamics
Italy's rigid plastic packaging sector is compressing around circular-economy mandates that force converters to requalify resin formulations and retrofit thermoforming lines for recycled feedstocks. The EU Single-Use Plastics Directive and Italy's national plastic tax are accelerating capital redeployment toward rPET and bio-polypropylene platforms.
Growth Catalysts
- EU Single-Use Plastics Directive:Mandatory recycled content thresholds for beverage bottles are pulling rPET capacity expansion across Emilia-Romagna's converter cluster.
- Ready-meal merchandising:Italian retailers are expanding fresh-protein and deli tray formats, driving thermoformed PP demand in Lombardy's food corridor.
- Pharmaceutical serialization:Track-and-trace requirements for drug-contact packaging are elevating demand for high-clarity, barrier-grade PET from Bormioli Pharma's specialist lines.
Market Restraints
- rPET feedstock scarcity:Collection infrastructure gaps in southern Italy constrain mechanically recycled pellet supply, forcing northern converters to import bales from Germany and France at elevated cost.
- Energy input volatility:Natural gas price exposure in extrusion and injection blow-molding operations compresses margin stability for mid-sized thermoformers.
- Glass substitution in premium pharma:Cyclic olefin polymer and glass vials are displacing PET for high-value parenteral applications amid tightening EMA extractables standards.
Strategic Opportunities
- Extended Producer Responsibility incentives:Italy's CONAI fee modulation rewards lightweight, recyclable formats, creating margin upside for converters optimizing tray-to-content ratios.
- Bio-based polypropylene scale-up:Fermentation-derived propylene from Versalis's Porto Marghera biorefinery is enabling certified renewable content claims for export-oriented food brands.
- Direct-store-delivery consolidation:Prepared-meal brands are bypassing traditional distribution layers, creating demand for unitized, retail-ready tray formats in Milan and Turin metro corridors.
Industry Challenges
- Multi-layer decontamination certification:ISS food-contact approvals for recycled-content structures require 12-18 month validation timelines, delaying product launches.
- Legacy injection mold retrofit costs:Converters face six-figure tooling modifications to process higher-viscosity rPET without clarity degradation.
- Polymer scientist scarcity:Formulation chemistry expertise for barrier-modified bio-polypropylene concentrates among a handful of Bologna-area technical consultants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Italy Rigid Plastic Packaging Market |
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Containers, Jars, Trays End Use Industry: Food, Beverages, Pharmaceuticals, Consumer Goods Material: Polyethylene Terephthalate, Polypropylene, Polyvinyl Chloride, Polystyrene Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Specialty Stores |
| Companies Covered | Amcor Group GmbH, Berry Global Inc, Aptar Group Inc, Alpla Group, Bormioli Pharma SpA, Axium Packaging, Bosisio Francesco & C SpA, Schutz (Italia) Srl, Grief Inc, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Italy Rigid Plastic Packaging Market Trends and Innovations
Digital process control and materials informatics are compressing development cycles for sustainable packaging formats. Italian converters are deploying simulation tools to optimize barrier performance before physical prototyping.
Digital twin platforms for blow-molding process optimization are virtualizing traditional trial-and-error calibration workflows. Tier-one beverage bottlers in Parma and Piacenza are adopting these tools to reduce rPET lot qualification time from weeks to days. The technology is virtualizing capital allocation decisions by enabling virtual commissioning of lightweight preform designs before mold fabrication.
Italy's Ministry of Ecological Transition is enforcing delegated acts under the EU Single-Use Plastics Directive that mandate 25% recycled content in PET bottles by 2025. This regulatory pressure is forcing resin suppliers to secure mass-balance certifications and converters to revalidate ISS food-contact dossiers. The prepared-foods segment is responding fastest, with Emilia-Romagna tray manufacturers accelerating rPP pilot lines ahead of beverage sector compliance deadlines.
Retail buyer consolidation is compressing supplier negotiation cycles and elevating format standardization requirements. Coop Italia and Conad central procurement teams are imposing unified tray dimensions and label-positioning specifications across their private-label ready-meal ranges. This concentration is most visible in Lombardy, where three retail banners control 60% of chilled prepared-food shelf space and demand interoperable secondary packaging footprints.
Italy Rigid Plastic Packaging Market Segmentation
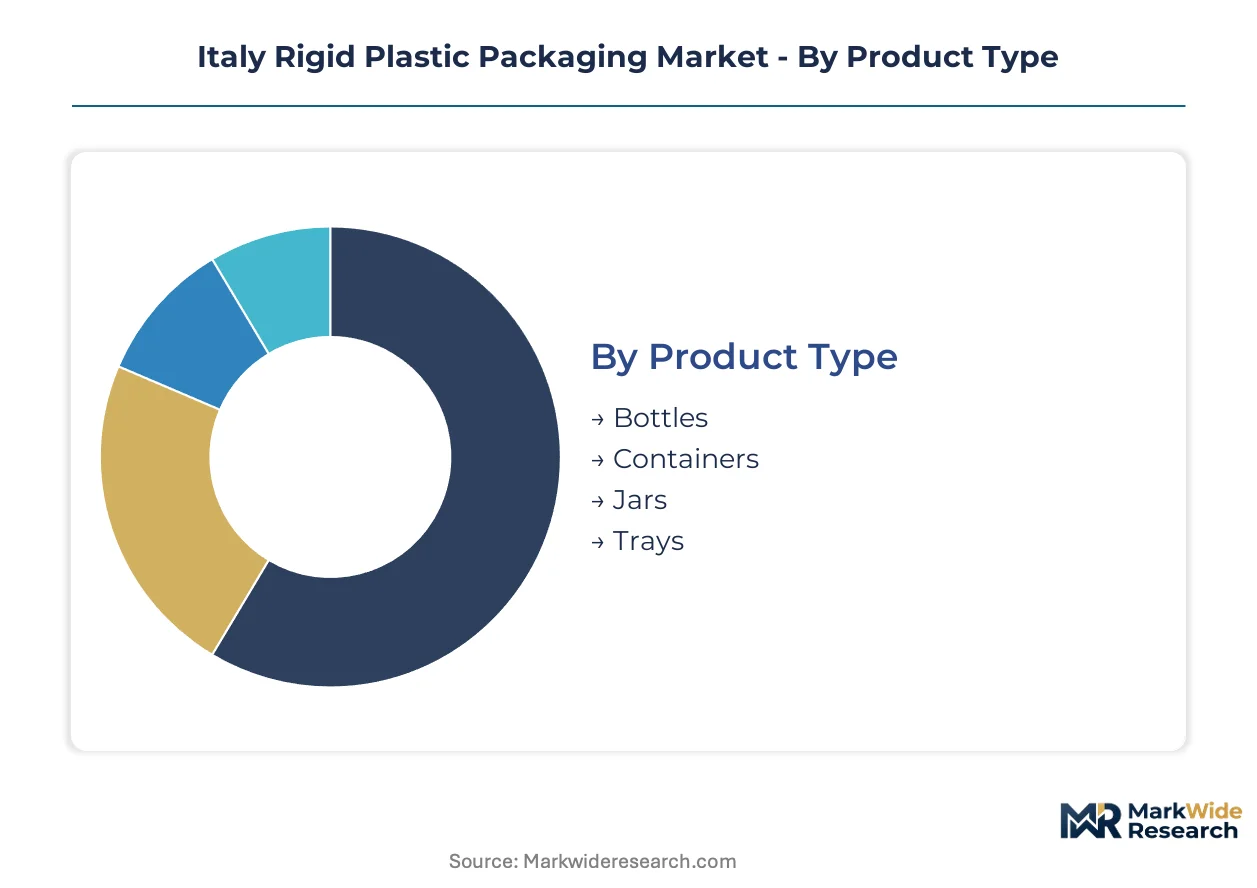
Segmentation in Italy's rigid plastic packaging sector reveals how converter capabilities and regulatory pressures concentrate across format types and resin platforms. Understanding these divisions exposes where capital deployment and technical qualification requirements diverge most sharply.
Product Type:
After-sales service intensity varies dramatically across product categories, with complex multi-cavity molds and barrier-modified formats demanding sustained technical support from equipment suppliers and resin formulators.
- Bottles:Injection stretch blow-molded PET structures dominate beverage and personal care applications, with lightweight preform designs requiring precise process control. Demand concentrates in Parma and Piacenza bottling corridors where Amcor and Berry Global maintain integrated supply relationships with mineral water and soft drink processors facing EU recycled content mandates.
- Trays:Thermoformed polypropylene and crystallized PET structures serve fresh-protein merchandising and ready-meal portion control. Lombardy's chilled prepared-food retail channels are expanding tray specifications fastest, driven by Coop Italia and Conad central procurement standardization across private-label ranges.
- Containers:Injection-molded tubs and pails with tamper-evident closures protect deli products and home care formulations.
- Jars:Wide-mouth PET and PVC formats preserve sauce viscosity and pharmaceutical cream stability.
By volume, bottles lead. By growth pace, trays are expanding most quickly.
End Use Industry:
Application-specific barrier requirements and contact-material regulations fragment converter specialization, with food and pharmaceutical segments demanding distinct ISS qualification protocols and audit trails.
- Food:Oxygen and moisture barrier specifications vary sharply between ambient shelf-stable and chilled fresh-protein applications. Emilia-Romagna's converter cluster processes the highest tray volumes for prepared-meal brands supplying northern Italian retail banners.
- Beverages:Carbonation retention and clarity standards drive PET resin selection, with rPET integration now mandatory under EU directive timelines. Mineral water bottlers in the Apennine foothills are retrofitting lines for recycled feedstock processing ahead of compliance deadlines.
- Pharmaceuticals:Bormioli Pharma's specialist PET and glass-plastic hybrid solutions serve injectable and oral solid dose formats.
- Consumer Goods:Home care and personal care applications prioritize chemical resistance and label adhesion over oxygen barrier performance.
Food commands the largest volume share. Pharmaceuticals show the steepest margin expansion trajectory.
Material:
Resin platform economics hinge on mechanical recycling infrastructure access and bio-based feedstock commercialization, with northern converters holding structural advantages in rPET supply security.
- Polyethylene Terephthalate:Clarity, lightweighting potential, and established mechanical recycling streams make PET the default for beverage and pharmaceutical visibility applications. Collection infrastructure gaps in southern Italy force northern converters to import German and French bales at cost premiums.
- Polypropylene:Versalis's Porto Marghera biorefinery is scaling fermentation-derived propylene for certified renewable content claims. Thermoformed PP trays are gaining share in fresh-protein retail formats faster than alternative resins.
- Polyvinyl Chloride:Pharmaceutical blister packs and high-clarity food jars retain niche positions amid regulatory scrutiny.
- Polystyrene:Dairy tubs and disposable foodservice applications face substitution pressure from PP alternatives.
PET dominates current volume flows. Polypropylene is climbing the fastest on bio-based and recycled formulation investments.
Distribution Channel:
Channel configuration shapes format standardization requirements, with retail banner consolidation in northern Italy driving unified secondary packaging footprints and label-positioning specifications.
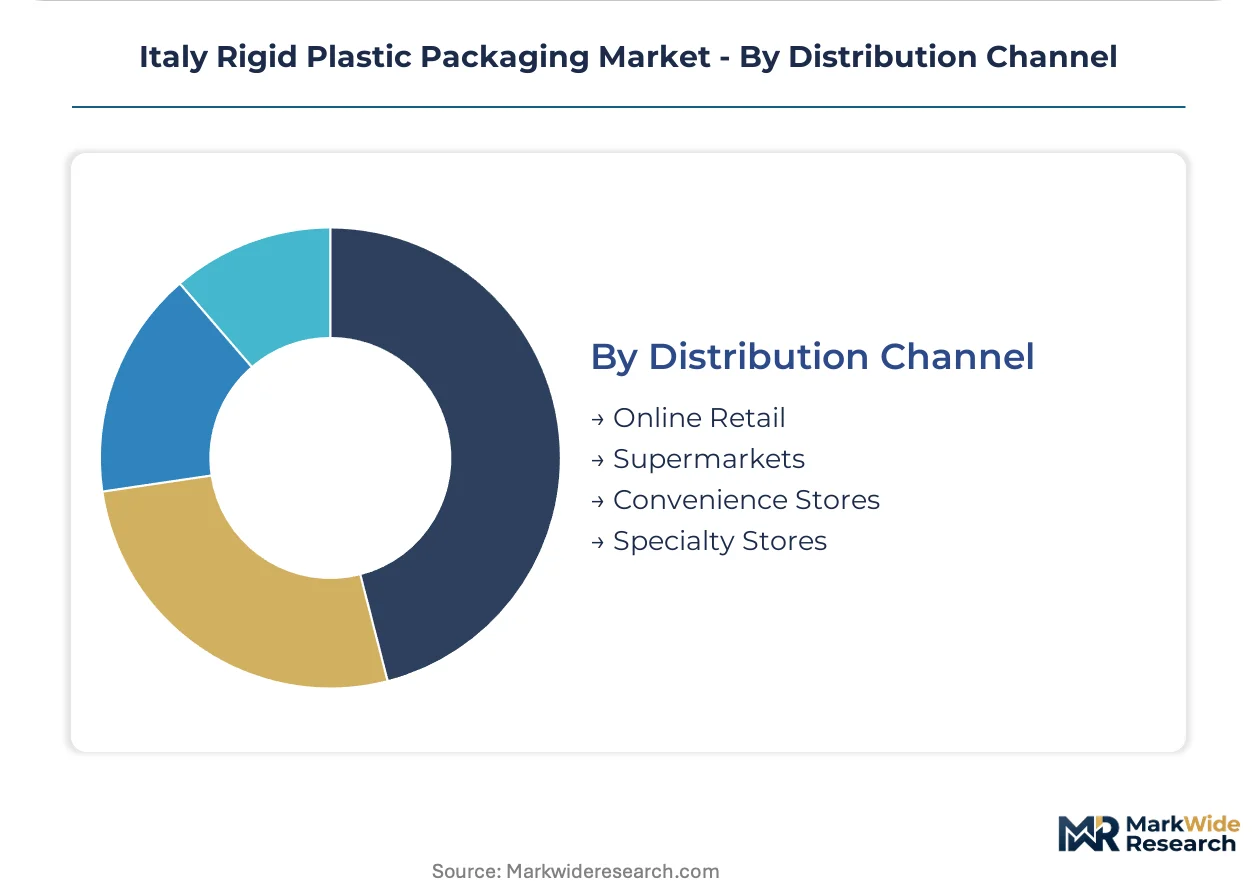
- Supermarkets:Coop Italia, Conad, and Esselunga central procurement teams impose interoperable tray dimensions and retail-ready packaging standards. Three banners control sixty percent of Lombardy chilled prepared-food shelf space.
- Online Retail:Direct-store-delivery models for prepared-meal brands are bypassing traditional distribution layers, creating demand for unitized formats optimized for last-mile handling in Milan and Turin metro corridors.
- Convenience Stores:Smaller format bottles and single-serve portions address immediate consumption occasions.
- Specialty Stores:Premium deli and pharmaceutical channels demand higher clarity grades and custom decoration.
Supermarkets anchor volume procurement. Online retail is gaining share fastest on direct-delivery consolidation trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Italy's rigid plastic packaging trade flows reflect a structural export surplus in high-value pharmaceutical and food-contact formats, offset by rPET feedstock imports from Germany and France to compensate for southern collection infrastructure gaps.
Emilia-Romagna
Tray manufacturers in this northern corridor process the highest prepared-meal packaging volumes for Coop Italia and Conad private-label ranges. The region's converters cluster near Parma's food processing plants, leveraging proximity to minimize logistics costs for chilled distribution. EU Single-Use Plastics Directive compliance deadlines are accelerating rPP pilot line investments across Bologna-area thermoforming facilities.
Lombardy
Milan and Turin metro corridors anchor demand for retail-ready tray formats as direct-store-delivery models bypass traditional distribution layers. Three retail banners control sixty percent of chilled prepared-food shelf space, imposing unified secondary packaging specifications. CONAI fee modulation rewards lightweight formats, creating margin optimization pressure for converters serving Esselunga central procurement.
Piedmont
Mineral water bottlers in the Apennine foothills are retrofitting lines for recycled feedstock processing ahead of EU recycled content mandates. The region's beverage corridor faces rPET bale import dependence from French and German mechanical recyclers. Turin-based converters specialize in carbonation-retention PET structures for premium sparkling water brands.
Veneto
Pharmaceutical packaging demand concentrates near Verona's drug formulation cluster, where barrier-grade PET requirements intersect with tightening EMA extractables standards. Bormioli Pharma's specialist lines serve injectable and oral solid dose formats from this corridor. The region's converters face displacement pressure from cyclic olefin polymer and glass vials in high-value parenteral applications.
Lazio
Rome's distribution hub function supports southern market penetration for northern-manufactured formats, though logistics costs erode margin competitiveness. The region lacks equivalent converter density, creating supply chain vulnerability for Campania and Sicily retail channels. National plastic tax administration through Italy's Ministry of Ecological Transition centralizes compliance documentation from this administrative center.
Italy Rigid Plastic Packaging Market Competitive Landscape
On the supply side, the industry is consolidating around integrated resin-to-format capabilities that satisfy EU circular-economy mandates. Tier-one converters with mass-balance certification access command procurement preference from export-oriented food brands. Three archetypes dominate: pan-European scale players with multi-country thermoforming footprints, regional specialists leveraging proximity to Emilia-Romagna food processors, and pharmaceutical-grade purity operators with ISS-validated dossiers. Competitive intensity centers on M&A-driven resin platform expansion and strategic partnerships securing rPET bale supply from German and French mechanical recyclers.
Among scale-driven operators, Amcor Group GmbH and Berry Global Inc exemplify the pan-European archetype with integrated film and rigid operations sustaining supply relationships across Italian food processing corridors. Bormioli Pharma SpA occupies a defensible niche within pharmaceutical-grade PET and glass-plastic hybrid solutions, representing the specialist purity tier amid tightening drug-contact material standards.
| Leading Market Players |
|---|
| Amcor Group GmbH |
| Berry Global Inc |
| Aptar Group Inc |
| Alpla Group |
| Bormioli Pharma SpA |
| Axium Packaging |
| Bosisio Francesco & C SpA |
| Schutz (Italia) Srl |
| Grief Inc |
| Others |
Pricing and Supply Chain Analysis
The Brenner Corridor freight routes linking northern Italy to German mechanical recyclers impose cost dynamics that concentrate supply power among Emilia-Romagna converters while forcing three-tier pricing stratification across rPET-certified, standard virgin, and economy-grade resin tiers.
Pricing Analysis
Industrial OEM buyers anchor contract structures around long-term offtake agreements indexed to virgin PET spot markets with rPET premiums negotiated separately. Price differentiation rests on ISS food-contact certification grade and volume scale commitments above 5,000 tonnes annually. Pricing pressure stems from natural gas volatility in extrusion operations compressing thermoformer margins. Private-label retail procurement teams at Coop Italia and Conad exhibit highest price sensitivity, while pharmaceutical-grade buyers accept premium positioning for barrier-validated dossiers.
Supply Chain Analysis
EU dual-use export controls on advanced barrier-coating technologies limit cross-border equipment flows, constraining Italian converters to domestic retrofit capabilities for multi-layer structures. Feedstock concentration centers on Germany, France, and Belgium as southern Italy's collection gaps force bale imports. Raw material dependencies encompass rPET flakes, bio-based propylene from Versalis's Porto Marghera facility, and specialty barrier additives. Single-source vulnerability pervades fermentation-derived propylene supply. Distribution runs through consolidated retail banner procurement hubs in Milan and Turin.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market tracks a cyclical recovery anchored to EU Packaging and Packaging Waste Regulation implementation waves forcing capital redeployment across converter tiers.
For Market Incumbents: Insulate rPET supply positions through backward integration into German and French mechanical recycling partnerships before feedstock scarcity intensifies. Secure ISS validation capacity for multi-layer structures ahead of competitor qualification backlogs. Prioritize barrier-modified bio-polypropylene R&D to defend against glass substitution in premium pharmaceutical segments.
For New Entrants and Emerging Players: Southern Italy's underpenetrated retail channels present white-space opportunity as logistics costs erode northern converter competitiveness in Campania and Sicily. Direct-store-delivery models for prepared-meal brands bypassing traditional distribution layers offer entry vectors. Target bio-based PP certification gaps among Bologna-area technical consultancy scarcity.
For Investors and Strategic Acquirers: Pending EU recycled content threshold escalations reshape the acquisition landscape toward mass-balance-certified converter assets. Five-to-ten-year viability favors specialists with validated ISS dossiers and captive rPET supply relationships. Monitor German bale export permit volumes as inflection signal for feedstock cost trajectories.
| Strategic Initiative | Industry Significance |
|---|---|
| rPET Capacity Expansion | Amcor and Berry Global investments in Emilia-Romagna thermoforming lines secure compliance headroom ahead of EU mandate deadlines. |
| Bio-based Polypropylene Scale-up | Versalis's Porto Marghera fermentation-derived propylene enables certified renewable claims for export-oriented food brands. |
| Digital Twin Platform Deployment | Parma beverage bottlers compress rPET lot qualification timelines from weeks to days through virtual commissioning. |
| Extended Producer Responsibility Optimization | CONAI fee modulation rewards tray-to-content ratio improvements for converters serving Lombardy retail banners. |
| Pharmaceutical-grade Purity Certification | Bormioli Pharma's ISS-validated barrier-grade PET dossiers defend against cyclic olefin polymer displacement in parenteral applications. |
Research Methodology
A spread of perspectives from packaging converters, retail procurement directors, resin formulators, and regulatory affairs specialists converged on the working assumptions underlying demand projections. Primary fieldwork across Emilia-Romagna and Lombardy manufacturing corridors combined with secondary validation from CONAI fee schedules, EU delegated acts under the Single-Use Plastics Directive, and Italian Ministry of Health ISS guidance documents. Bottom-up tray and bottle volume builds triangulated against top-down macroeconomic indicators.
Demand-supply balance modeling across the projection horizon segmented by format type, resin platform, end-use industry, and regional production cluster. CAGRs derived from weighted average of historical trajectory elasticity and regulatory mandate impact coefficients. Forecast inputs incorporated natural gas price volatility assumptions for extrusion energy costs and rPET bale import dependency ratios for southern versus northern converter economics.
The forecast holds incumbent behavior within observed patterns; aggressive moves by pan-European scale players acquiring Italian regional specialists would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rigid Packaging
China Rigid Plastic Packaging Market
Rigid Packaging
India Rigid Plastic Packaging Market
Rigid Packaging
Reclosable Rigid Containers Market
Rigid Packaging
Morocco Rigid Plastic Packaging Market
Rigid Packaging
Global Rigid Paper Containers Market
Rigid Packaging
Global Rigid Bulk Packaging Market
Rigid Packaging
Asia-Pacific Rigid Bulk Packaging Market
Rigid Packaging
Rigid Food Packaging Market
Rigid Packaging
Certified-Circular Polyolefin Resins for Flexible and Rigid Packaging Market
Rigid Packaging
Poland Rigid Plastic Packaging Market
Rigid Packaging
Europe Rigid Plastic Packaging Market
Rigid Packaging
Rigid Trays Market
Rigid Packaging
Japan Rigid Plastic Packaging Market
Rigid Packaging
Rigid Transparent Plastic Market
Rigid Packaging
Colombia Rigid Plastic Packaging Market
Rigid Packaging
North America Rigid Plastic Packaging Market