
 PVDC Shrink Bags Market | 2026-2036
PVDC Shrink Bags Market Size, Share, and Industry Trends Forecast 2026-2036
PVDC Shrink Bags Market Outlook
Market Context
Specialized polymer compounding expertise is reorganizing competitive dynamics as converters race to formulate PVDC alternatives with equivalent oxygen barrier performance. Amcor Plc leverages its integrated film extrusion network to secure long-term supply agreements with North American protein packers. Sealed Air Corporation sustains technology leadership through proprietary vacuum-shrink systems that reduce leaker rates in high-speed processing lines. WINPAK LTD anchors its position via backward integration into resin compounding, insulating margin pools from polyvinylidene chloride monomer volatility.
Technical Definition and Segment Structure
PVDC shrink bags are thermoplastic barrier films composed primarily of polyvinylidene chloride copolymers, typically biaxially oriented and heat-shrinkable to conform tightly to irregular meat cuts while delivering oxygen transmission rates below 5 cc/m²/day. Their primary commercial purpose is extending chilled protein shelf life by blocking moisture loss and oxidative discoloration across the distribution chain. Multi-layer constructions dominate value capture due to their ability to combine PVDC barrier layers with puncture-resistant ionomer skins for bone-in applications. Food packaging anchors volume demand, though pharmaceutical-grade specifications for sterile barrier integrity represent the fastest-expanding margin pool as biologic drug delivery formats proliferate.
Regulatory Framework and Outlook
The EPA governs residual vinyl chloride monomer thresholds in US food-contact films, while REACH restricts certain phthalate plasticizers in European PVDC formulations, forcing reformulation cycles that favor compliant suppliers with certified migration testing. China's SAMR enforces GB standards for composite food packaging that increasingly reference heavy metal limits and solvent residue controls, raising qualification barriers for imported shrink bag films. Stakeholders must monitor evolving extended producer responsibility schemes and chemical recyclate content mandates, as these will determine which barrier technologies retain access to premium retail channels.
Market Dynamics
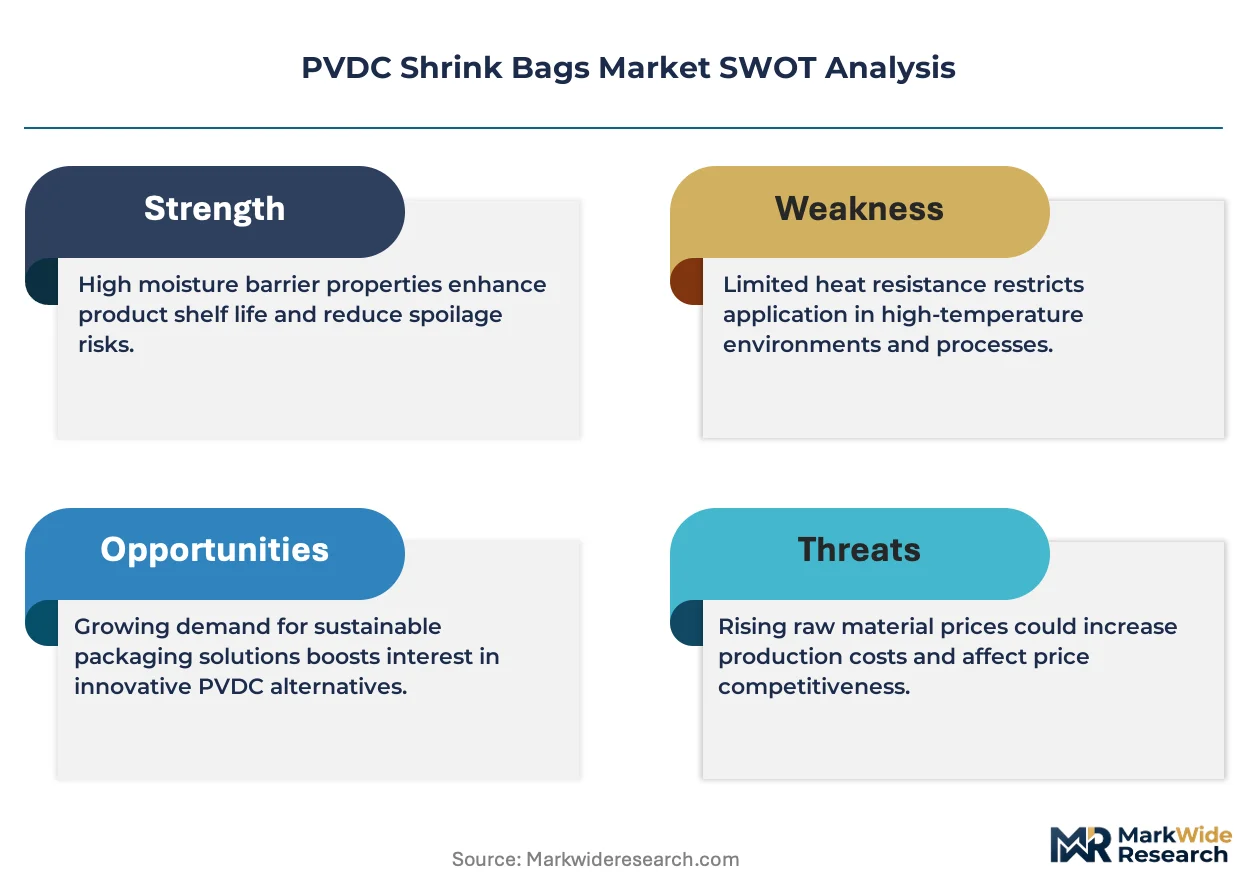
EU F-Gas Regulation and REACH chemical restrictions are forcing wholesale reformulation of barrier film architectures, as converters scramble to preserve oxygen transmission performance without chlorinated polymer layers.
Growth Catalysts
- Fresh protein export standards:Brazilian meat processors are mandating high-barrier packaging for chilled beef shipments to Middle Eastern and Asian markets.
- REACH compliance cycles:European plasticizer restrictions are accelerating qualification of migration-tested alternatives among certified compounders.
- Sterile barrier demand:Biologic drug delivery formats are expanding pharmaceutical-grade specification volumes for PVDC-based sterile integrity systems.
Market Restraints
- VCM monomer volatility:Polyvinylidene chloride resin prices swing with energy costs and chlor-alkali plant operating rates.
- Chinese supply concentration:A narrow base of domestic PVDC resin producers controls export availability to Southeast Asian converters.
- Mono-material substitution:Polyolefin barrier films with metallized or SiOx coatings are capturing shelf-ready meat applications.
Strategic Opportunities
- German premium channel:Processed meat exporters are specifying recyclable barrier structures to meet packaging waste directive targets.
- Extended producer responsibility:EU-wide EPR schemes are creating first-mover advantage for suppliers with certified chemical recyclate content.
- Vacuum-shrink automation:Convergence of vision-guided robotics and modified-atmosphere sealing is opening high-speed line retrofit demand.
Industry Challenges
- Multi-layer delamination expertise:Reformulating coextruded structures without PVDC cores demands polymer scientists with biaxial orientation process knowledge.
- Migration testing timelines:FDA and EFSA food-contact notifications now require 18-24 month validation cycles for new barrier chemistries.
Report Scope
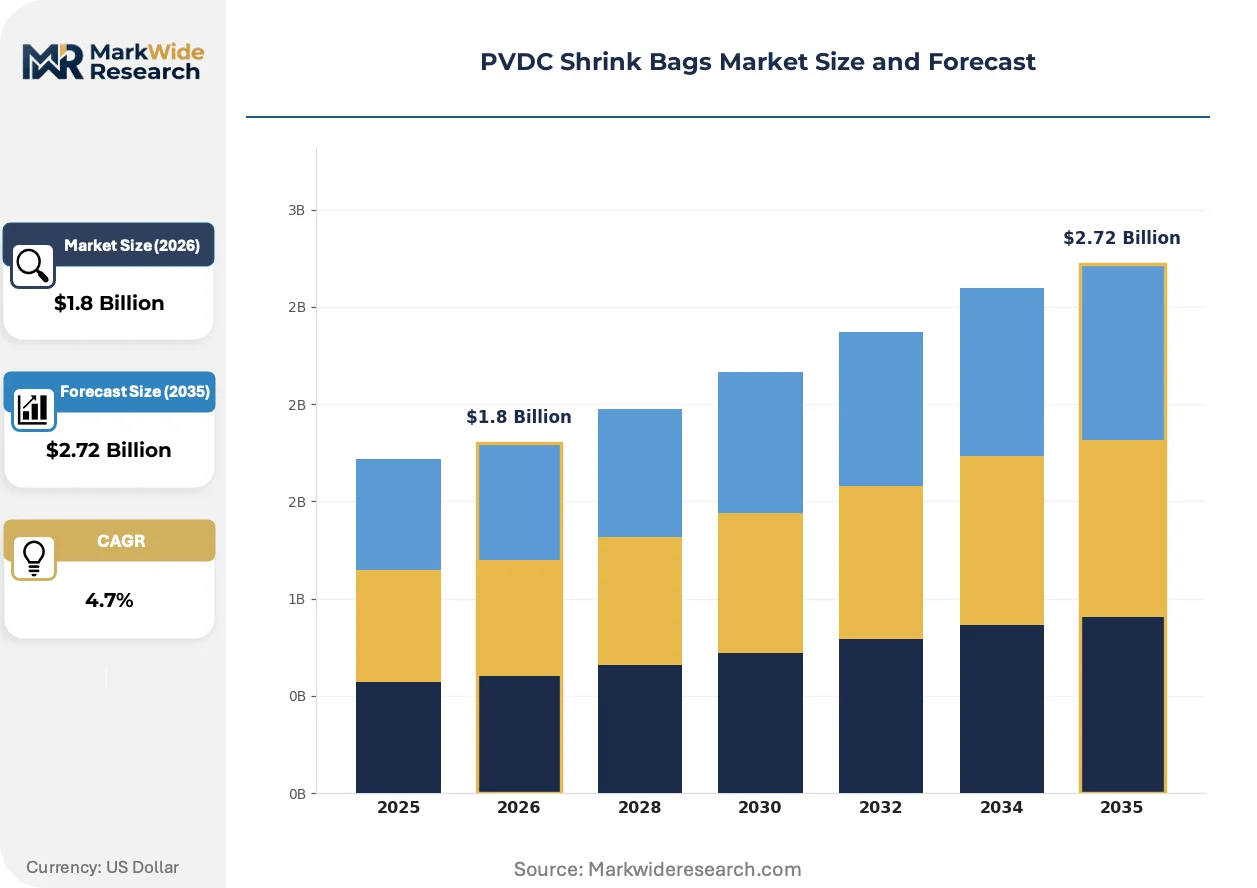
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | PVDC Shrink Bags Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Layer, Multi-Layer, Custom-Made, Laminated Application: Food Packaging, Pharmaceuticals, Electronics, Textiles Form: Rolls, Pre-formed Bags, Sheets, Pouches End User: Retail, Manufacturing, Hospitality, E-Commerce |
| Companies Covered | Amcor Plc, Sealed Air Corporation, WINPAK LTD, Suzhou Tipack (Foho) Co Ltd, Green Packaging Material (Jiangyin) Co Ltd, ALLFO GmbH & Co KG, Sunrise Packaging Material (Jiangyin) Co Ltd, PREMIUMPACK GmbH, IPE Pack Co Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
PVDC Shrink Bags Market Strategic Shifts
Barrier technology is bifurcating between incremental PVDC optimization and disruptive mono-material replacement, with regulatory chemistry restrictions acting as the forcing mechanism.
Ethylene vinyl alcohol copolymer nanolayer coextrusion is fragmenting conventional multi-layer architectures. Meat packers in Germany and the Netherlands are trialing 11-layer structures with sub-micron EVOH distribution to match PVDC oxygen barrier at reduced thickness. This is fragmenting established supply relationships as compounders without nanolayer extrusion capability lose specification access.
EU F-Gas Regulation phase-down schedules are compressing hydrofluorocarbon availability for blown film cooling. European converters are retrofitting extrusion lines with liquid nitrogen injection systems to maintain output rates. Chilled protein packaging for export markets faces the steepest cost pass-through pressure.
Retail buyer consolidation is compressing supplier qualification cycles. German discount chains and French hypermarket groups are unbundling technical service from material supply, demanding standalone barrier performance warranties. This pattern concentrates procurement leverage among three protein retail buying groups controlling cold-chain shelf space.
PVDC Shrink Bags Market Segmentation
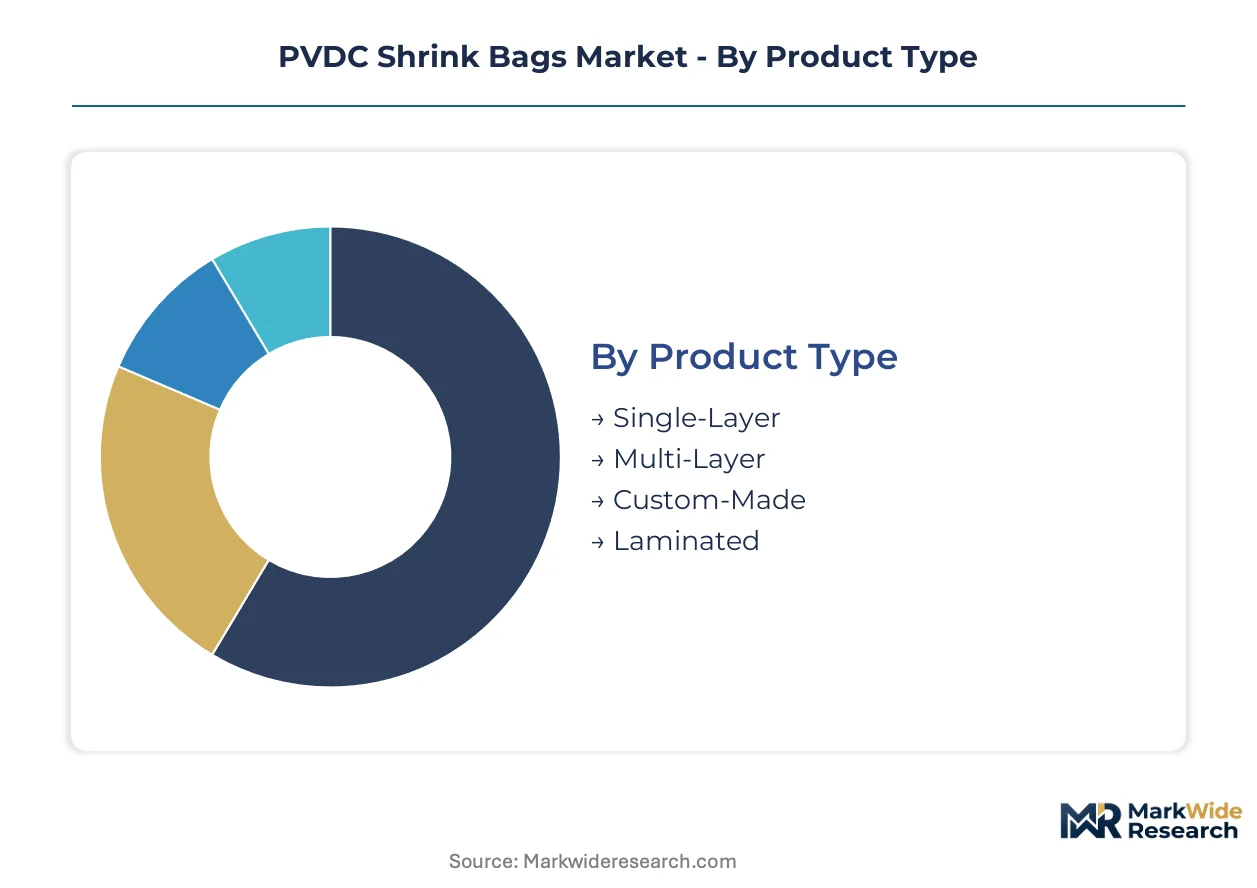
PVDC shrink bag procurement patterns diverge sharply by channel, with protein packers demanding certified barrier performance while pharmaceutical converters prioritize sterile integrity documentation. Channel-specific qualification requirements are fragmenting supplier portfolios as compounders specialize in either food-contact migration testing or medical-grade cleanroom extrusion.
Product Type:
Channel mix varies by structural complexity, with multi-layer constructions dominating branded protein exports while single-layer formats serve cost-sensitive domestic distribution.
- Multi-Layer:Coextruded architectures combining PVDC barrier cores with puncture-resistant ionomer skins deliver oxygen transmission below 5 cc/m²/day for bone-in meat applications. Brazilian beef exporters to Middle Eastern markets mandate these specifications for chilled container shipments exceeding 30 days transit time.
- Single-Layer:Homogeneous PVDC formulations offer lower unit economics for short-distribution chilled poultry and processed meat segments. German discount retailers specify single-layer formats for private-label bacon and sausage products where shelf life requirements stay under 14 days.
- Custom-Made:Tailored dimensions and seal configurations serve automated vacuum-shrink lines at protein processing facilities.
- Laminated:Adhesive-bonded constructions with printed outer webs support premium retail presentation requirements.
Multi-layer constructions dominate installed base. Custom-made formats are where expansion concentrates as automation retrofits accelerate.
Application:
Cost tier stratification separates commodity protein packaging from pharmaceutical barrier systems, with the latter commanding 3-4x material premiums.
- Food Packaging:Chilled meat and poultry distribution absorbs the majority of PVDC shrink bag volume, with oxygen barrier performance directly determining case-ready retail shelf life. EU F-Gas Regulation compliance costs are compressing margins for European converters serving this segment.
- Pharmaceuticals:Sterile barrier applications for biologic drug delivery formats demand validated seal integrity and extractables testing under USP Class VI protocols. EMA medical device regulations are tightening documentation requirements for primary packaging materials.
- Electronics:Moisture barrier protection for sensitive components in transit packaging.
- Textiles:Shrink-wrapping applications for industrial fabric rolls and garment distribution.
Food packaging anchors volume scale. Pharmaceuticals is climbing the fastest as biologic drug formats proliferate.
Form:
Volume concentration favors pre-formed bags in high-speed protein processing, while roll stock serves regional converter networks.
- Pre-formed Bags:Die-cut and side-sealed configurations integrate directly with vacuum chamber equipment, reducing line changeover downtime. North American beef packers specify pre-formed formats for consistent seal bar alignment across high-throughput operations.
- Rolls:Continuous web formats enable on-site bag fabrication by converters serving fragmented regional meat processing clusters. Southeast Asian converter networks prefer roll stock to minimize inventory SKU complexity across multiple protein species.
- Sheets:Flat film formats for manual wrapping operations in small-batch processing environments.
- Pouches:Three-side-seal configurations for modified-atmosphere retail packaging.
Pre-formed bags dominate installed base. Rolls are gaining share fastest in emerging converter markets.
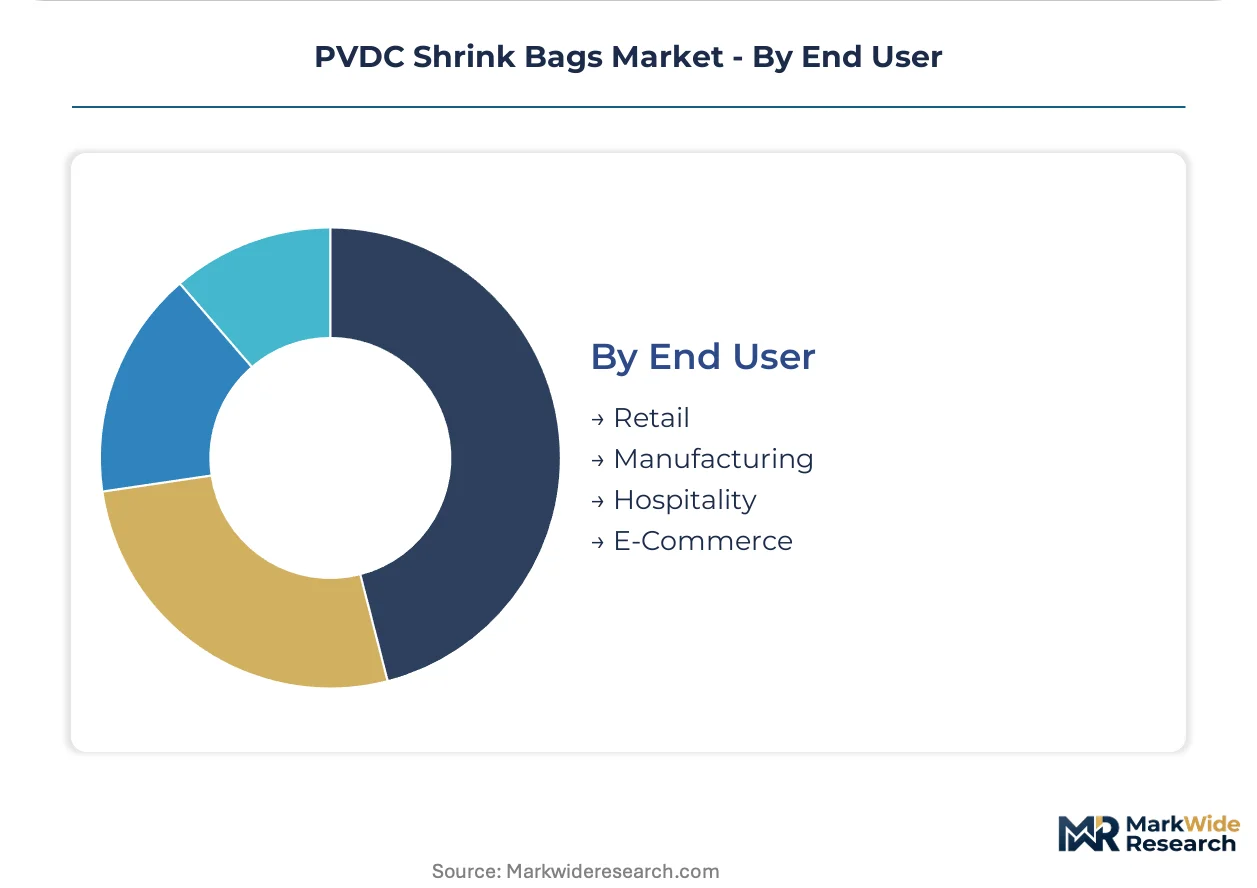
End User:
Customer type determines specification stringency, with retail-controlled supply chains imposing the most demanding barrier performance warranties.
- Retail:Supermarket and hypermarket buying groups specify certified barrier structures with standalone performance guarantees unbundled from technical service. French retail consolidation has reduced qualified supplier pools to three compounders with dedicated migration testing laboratories.
- Manufacturing:Protein processing facilities prioritize total applied cost and line speed compatibility over premium barrier specifications. Brazilian integrated meatpackers negotiate long-term resin supply agreements to insulate against VCM monomer volatility.
- Hospitality:Foodservice distributors demand puncture resistance for rough-handling distribution to restaurant chains.
- E-Commerce:Direct-to-consumer chilled protein shipments require enhanced leak resistance for last-mile logistics.
Retail channels dominate specification setting. E-commerce is where expansion concentrates as cold-chain home delivery scales.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU F-Gas Regulation anchors European demand dynamics, while Brazilian beef exports and Chinese resin supply concentration shape procurement patterns across emerging markets. Regional specifications diverge sharply between premium processed meat channels in Germany and cost-sensitive poultry distribution in Southeast Asia.
Germany
Premium processed meat exporters in Baden-Württemberg and Bavaria are specifying recyclable mono-material barrier structures to meet packaging waste directive targets. The EU Green Deal and national EPR schemes are compressing qualification timelines for compounders with certified chemical recyclate content. The Frankfurt-Rhine-Main logistics corridor concentrates cold-chain distribution infrastructure for high-barrier shrink bag demand.
Brazil
Integrated meatpackers in São Paulo state are mandating high-barrier packaging for chilled beef shipments to Middle Eastern and Asian markets. ANVISA enforces migration testing protocols for food-contact films that align with Mercosur technical regulations. The Seara and JBS processing clusters in Santa Catarina are retrofitting vacuum-shrink lines to reduce leaker rates in export-bound containers.
United States
North American protein packers are securing long-term supply agreements to insulate against vinyl chloride monomer price volatility. The EPA governs residual VCM thresholds in food-contact films, while FDA food-contact notifications require extended validation cycles for new barrier chemistries. The Nebraska-Iowa beef processing corridor represents the densest concentration of high-throughput shrink bag consumption.
China
Domestic PVDC resin producers in Jiangsu and Zhejiang provinces control export availability to Southeast Asian converter networks. SAMR enforces GB standards for composite food packaging with tightening heavy metal limits and solvent residue controls. The Yangtze River Delta film extrusion cluster is retrofitting lines with liquid nitrogen injection systems to maintain output rates amid hydrofluorocarbon phase-down pressures.
Netherlands
Rotterdam-port logistics operators are trialing 11-layer EVOH nanolayer structures to match PVDC oxygen barrier performance at reduced material thickness. ECHA REACH restrictions on phthalate plasticizers are accelerating qualification of migration-tested alternatives among certified compounders. The Eindhoven-Tilburg converter belt specializes in nanolayer coextrusion capability that fragments established supply relationships.
PVDC Shrink Bags Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes across the PVDC shrink bags competitive landscape. The vendor base organizes into three tiers: integrated multinational compounders with captive resin supply, regional specialists with nanolayer extrusion capability, and commodity converters serving cost-sensitive domestic channels. Dominant competitive moves include backward integration into resin compounding to insulate margin pools from monomer volatility, and strategic partnerships with protein packers for long-term specification lock-in.
Among integrated packaging conglomerates, Amcor Plc and Sealed Air Corporation exemplify archetypes combining film extrusion networks with vacuum-shrink system integration. WINPAK LTD anchors the North American specialist tier with in-house resin compounding capabilities. Chinese fabricators including Suzhou Tipack (Foho) Co Ltd and Green Packaging Material (Jiangyin) Co Ltd occupy positions within the Asia-Pacific supply concentration, while German mid-caps ALLFO GmbH & Co KG and PREMIUMPACK GmbH represent European premium-channel specialization.
| Leading Market Players |
|---|
| Amcor Plc |
| Sealed Air Corporation |
| WINPAK LTD |
| Suzhou Tipack (Foho) Co Ltd |
| Green Packaging Material (Jiangyin) Co Ltd |
| ALLFO GmbH & Co KG |
| Sunrise Packaging Material (Jiangyin) Co Ltd |
| PREMIUMPACK GmbH |
| IPE Pack Co Ltd |
| Others |
Value Chain & Pricing Dynamics
Sixty-day resin inventory buffers at European compounders signal supply-chain rigidity that amplifies pricing power for Chinese PVDC monomer producers. This lead-time compression concentrates procurement leverage among integrated packers with captive resin agreements, while spot-market buyers absorb volatility pass-through.
Pricing Analysis
Contract-to-spot spreads between German and Southeast Asian converters exceed 15% on equivalent multi-layer specifications. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume commitment, with pharmaceutical-grade sterile barrier films commanding material premiums over food-contact tiers. Pricing pressure stems from EVOH nanolayer substitution trials in Dutch and German meat channels. Discount retailers in Germany exhibit highest price sensitivity, while biologic drug packers prioritize seal-integrity documentation over unit cost.
Supply Chain Analysis
Forty-five day order-to-delivery cycles for custom pre-formed bags expose converter networks to VCM monomer price swings. Manufacturing concentrates in China, Germany, and Brazil, with Jiangsu province resin producers controlling export availability to Southeast Asian film extruders. Raw material flows draw from chlor-alkali plants, vinyl chloride monomer suppliers, and ionomer resin compounders. Single-source vulnerability sits with Chinese domestic PVDC resin concentration. Distribution runs through protein processor direct procurement and regional converter roll-stock networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU F-Gas Regulation phase-down schedules are disrupting incumbent barrier-film architectures faster than reformulation cycles can compensate. This regulatory inflection creates asymmetric opportunity for compounders with nanolayer extrusion capability and certified migration-testing infrastructure.
For Market Incumbents: Consolidate specification lock-in through long-term resin supply agreements with Brazilian and North American protein packers. Deepen backward integration into vinyl chloride monomer production to insulate margin pools from energy-cost volatility. Prioritize EVOH nanolayer R&D partnerships with Dutch and German converter clusters to defend against mono-material substitution threats. For New Entrants and Emerging Players: Technical service unbundling by French and German retail buying groups creates entry space for standalone barrier-performance warranty providers. Target pharmaceutical-grade sterile barrier segments where USP Class VI documentation requirements filter out commodity converters. Lead with certified chemical recyclate content to capture EU extended producer responsibility scheme premiums. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with under-monetized film extrusion assets. Five-to-ten year viability hinges on nanolayer coextrusion capability and migration-testing laboratory certification. Watch for EMA medical device regulation tightening as signal for pharmaceutical-grade specification inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Compounding | Captive VCM supply insulates margins from chlor-alkali plant operating rate volatility. |
| Nanolayer Coextrusion Capability Investment | EVOH sub-micron distribution matches PVDC barrier performance without F-Gas regulatory exposure. |
| Certified Chemical Recyclate Content Program | EU Green Deal compliance secures access to German premium processed meat export channels. |
| Long-term Supply Agreement with Protein Packers | Specification lock-in with JBS and Seara clusters reduces customer acquisition cost. |
| Migration Testing Laboratory Certification | FDA and EFSA notification capability accelerates new barrier chemistry qualification cycles. |
Study Parameters
Demand-side practitioners and supply-side operators were both consulted across primary interview programs with protein packer procurement directors, film extrusion plant managers, pharmaceutical packaging engineers, and retail category buyers. Secondary validation drew from EPA food-contact filings, ECHA REACH registration databases, ANVISA technical regulations, and customs trade flows for PVDC resin and shrink film categories. Bottom-up volume estimates triangulated against top-down polymer consumption models.
Across the analysis window, projections segmented by product architecture, application vertical, and regional regulatory cluster. CAGRs derived from elasticity-adjusted demand curves incorporating F-Gas phase-down compliance cost pass-through and biologic drug format proliferation rates. Forecast inputs included VCM monomer price band scenarios and EVOH nanolayer adoption curves in German and Dutch meat channels.
Material uncertainties — regulatory acceleration beyond modeled REACH and F-Gas schedules, Chinese export license restrictions, abrupt EVOH barrier performance breakthroughs — sit outside the modeled envelope. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bags and Containers
Bakery Bread Bag Market
Bags and Containers
Lawn and Leaf Bags Market
Bags and Containers
Crates Market
Bags and Containers
North America Retail Bags Market
Bags and Containers
Bulk Bag Unloaders Market
Bags and Containers
Global High Abuse Shrink Bags Market
Bags and Containers
Shopping Bag Market
Bags and Containers
Handle Gusseted Bags Market
Bags and Containers
Inflatable Bags Packaging Market
Bags and Containers
Wicketless Bags Market
Bags and Containers
Bag Dump Stations Market
Bags and Containers
Bulk Tote Dumpers Market
Bags and Containers
Commodity Liners Market
Bags and Containers
Volatile Corrosion Inhibitor Bags Market
Bags and Containers
Piping Bags Market
Bags and Containers
Circular Industrial Bags Market