
 APAC Rigid Plastic Packaging Market | 2026-2036
APAC Rigid Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
APAC Rigid Plastic Packaging Market Insights
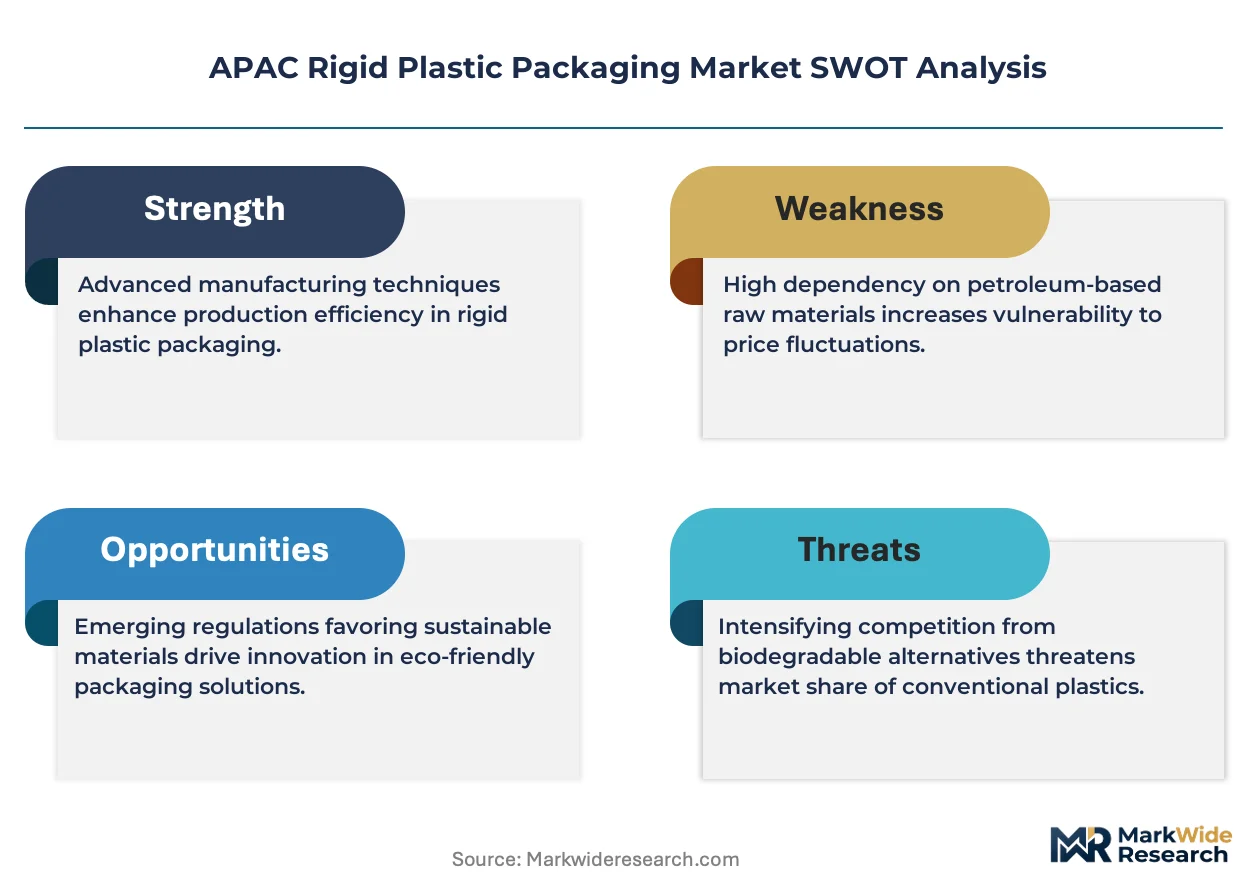
GB 4806.7 food-contact plastics compliance is redrawing supplier eligibility across the APAC Rigid Plastic Packaging landscape. Amcor Group GmbH leverages its multi-site certification network to sustain large-format beverage contracts across Australia and Thailand. Indorama Ventures Public Company Limited anchors regional PET resin supply, while Guangzhou Huaxin Plastic Products Co.,Ltd competes on injection-molded container specialization for domestic Chinese brands.
APAC Rigid Plastic Packaging comprises thermoformed or injection-molded polymer structures—typically PET, polypropylene, or high-density polyethylene—engineered to dimensional tolerances of 0.1–0.5 mm for stackability, barrier performance, and mechanical protection of filled goods. Bottles dominate volume throughput in beverage applications, while trays command premium positioning in chilled food retail display where clarity and seal integrity determine shelf appeal. Polypropylene containers are gaining structural share in microwaveable ready-meal segments across Japan and South Korea, displacing polystyrene where heat resistance thresholds exceed 120°C.
China's SAMR enforces GB standards migration limits for food-contact plastics, while India's BIS mandates IS 9845 certification for polyethylene and polypropylene articles, and Japan's METI oversees JIS S 2053 container safety protocols. These frameworks elevate testing costs for new entrants but protect incumbent suppliers with established laboratory relationships and documented compliance histories. Stakeholders must monitor evolving extended producer responsibility schemes in Thailand and Vietnam, where draft regulations threaten to impose post-consumer collection quotas on rigid packaging importers.
Market Dynamics
GB 4806.7 migration limits and India's BIS IS 9845 certification mandates are compressing supplier eligibility timelines across APAC, forcing procurement officers to revalidate sourcing networks and elevating testing documentation to contract gatekeeper status.
Growth Catalysts
- Processed food manufacturing clusters:Maharashtra and Gujarat in western India are scaling rigid container consumption as domestic brands expand shelf-stable product lines requiring PET barrier performance.
- Japan's METI container safety protocols:JIS S 2053 compliance is accelerating heat-resistant polypropylene adoption for microwaveable ready-meal segments displacing polystyrene.
- Thailand's draft EPR regulations:Post-consumer collection quota proposals are stimulating investment in rPET processing infrastructure ahead of mandate implementation.
Market Restraints
- Raw material concentration:Regional PET resin supply anchors on Indorama Ventures' integrated feedstock positions, creating vulnerability to paraxylene price volatility.
- Technical barrier thresholds:Heat resistance requirements exceeding 120°C limit polypropylene penetration in certain retort applications where metal cans retain dominance.
- Regulatory friction from SAMR:China's GB standards migration limit enforcement elevates testing costs for new entrants lacking established laboratory relationships.
Strategic Opportunities
- Vietnam's underpenetrated chilled food retail:Modern trade expansion in Ho Chi Minh City and Hanoi is creating demand for high-clarity thermoformed trays with seal integrity specifications.
- South Korea's microwaveable segment:Convenience food manufacturers are specifying polypropylene containers for dual-ovenable applications.
- Technology convergence:Digital printing integration with injection-molded containers enables batch-level traceability for pharmaceutical and nutraceutical packaging.
Industry Challenges
- Certification timeline compression:BIS IS 9845 approval cycles for polyethylene and polypropylene articles are extending procurement lead times for new product launches.
- Capex intensity for compliance:In-house migration testing laboratories require capital deployment that mid-tier converters struggle to fund.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | APAC Rigid Plastic Packaging Market |
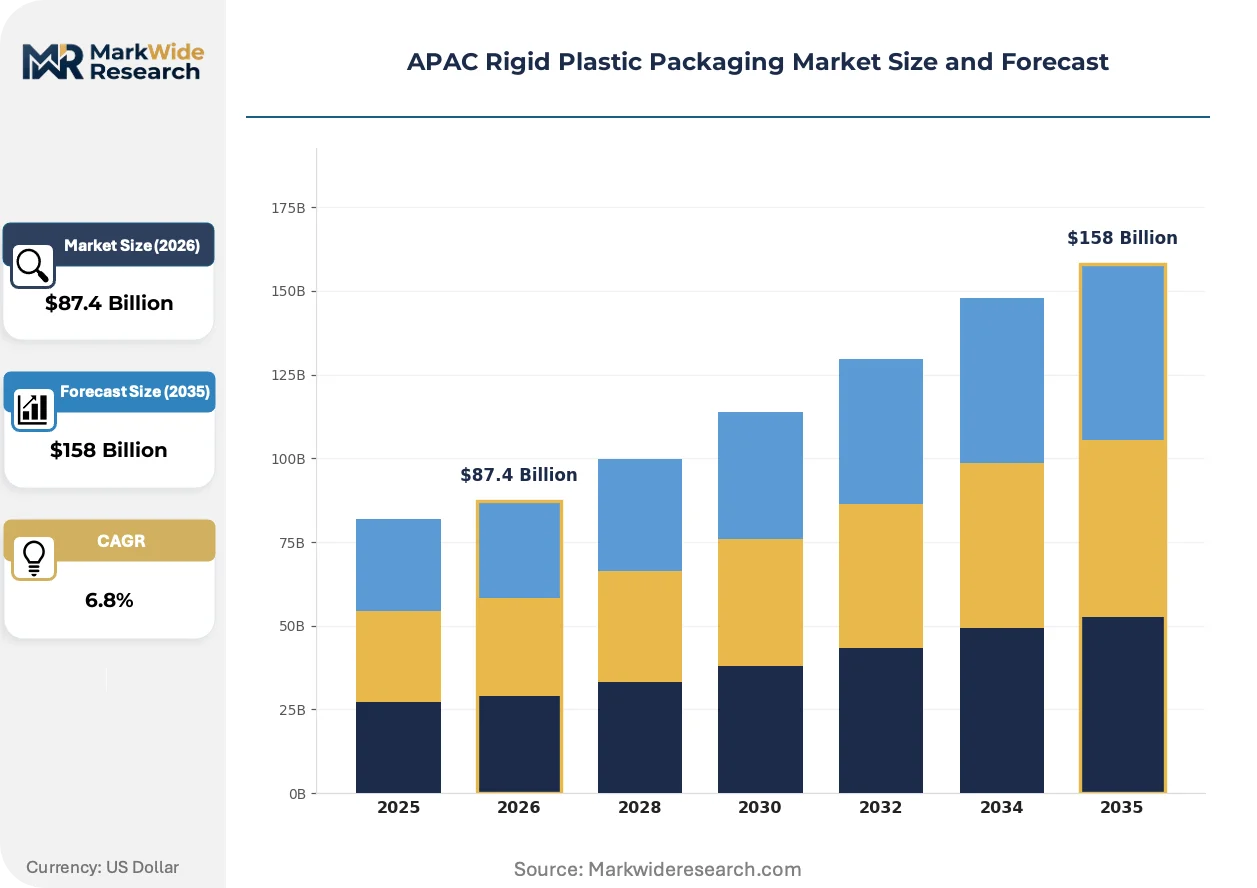
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $158 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Containers, Jars, Trays End User: Food, Beverages, Personal Care, Pharmaceuticals Material: Polyethylene, Polypropylene, PET, Polystyrene Application: Packing, Storage, Transportation, Retail Display |
| Companies Covered | Amcor Group GmbH, Berry Global Inc., Pyramid Technoplast Ltd, Silgan Holdings Inc., ALPLA, Indorama Ventures Public Company Limited, Guangzhou Huaxin Plastic Products Co.,Ltd, Sonoco Products Company, Pactiv Evergreen Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
APAC Rigid Plastic Packaging Market Trends and Innovations
Digital printing integration, regulatory tightening on food-contact migration limits, and procurement centralization by multinational beverage brands are compressing legacy supply relationships across the APAC rigid plastic packaging landscape.
Lightweighting technology for PET bottle structures is fragmenting conventional blow-molding equipment investment cycles. Southeast Asian beverage bottlers are adopting material distribution optimization software to maintain performance at reduced gram weights. This capability divergence is fragmenting competitive positioning between integrated resin-to-bottle operators and standalone converters lacking simulation expertise.
China's SAMR enforcement of GB 4806.7 migration limits is disqualifying uncertified suppliers from food-contact contracts. Testing documentation requirements now precede commercial negotiations rather than following them. Australian and Thai beverage producers with established multi-site certification networks are consolidating procurement volumes with compliant incumbents.
Centralized procurement by multinational food brands is compressing supplier rosters and elevating volume-scale requirements. Regional converters are responding by forming production consortia to meet minimum order thresholds. This consolidation pressure is most visible in Australia's retail-ready tray segment where supermarket private-label specifications demand pan-APAC supply consistency.
APAC Rigid Plastic Packaging Market Segmentation
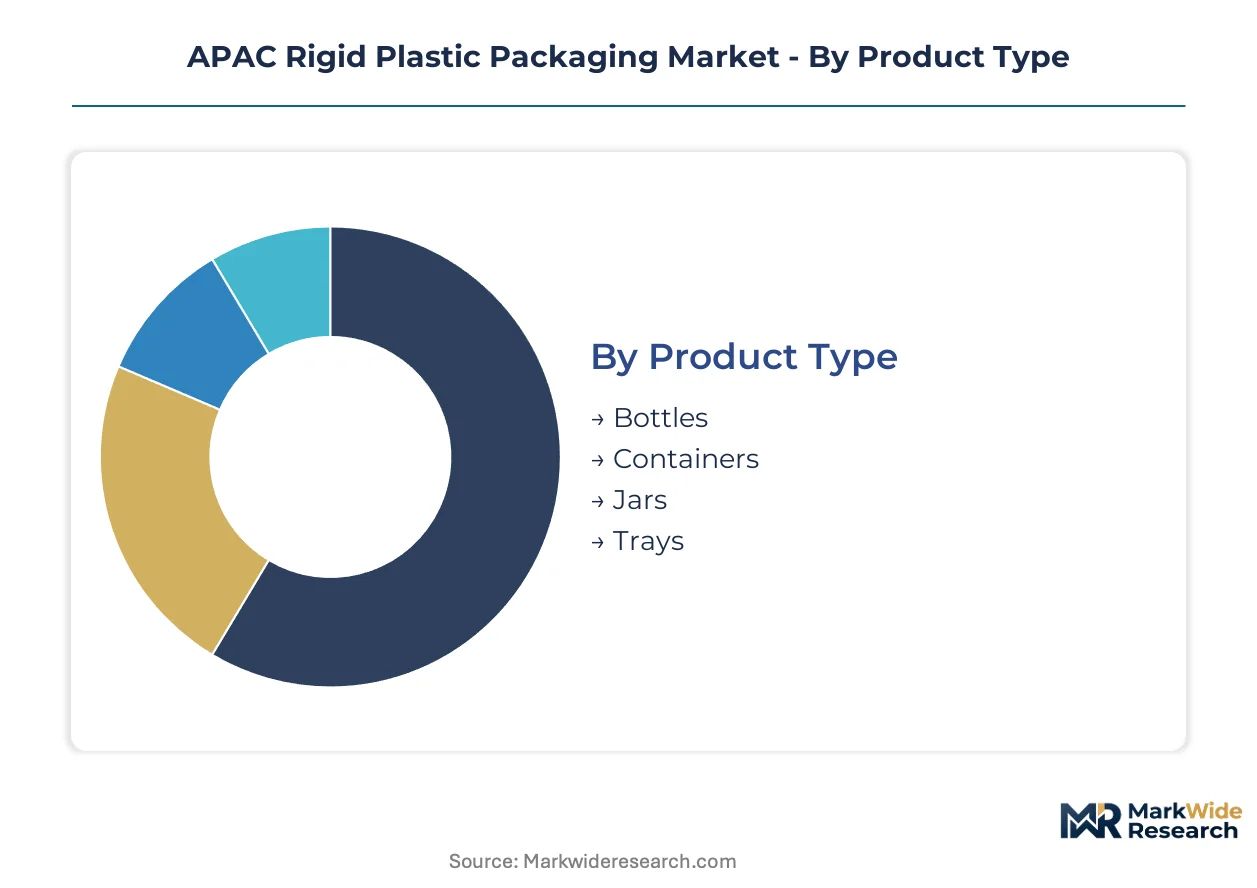
Segmentation in APAC rigid plastic packaging reveals how regulatory compliance requirements and manufacturing cluster geography reshape procurement priorities across product categories. Material certification mandates from China's SAMR and India's BIS create divergent competitive barriers that concentrate volume among pre-qualified suppliers.
Product Type:
GB 4806.7 migration limits and JIS S 2053 container safety protocols impose distinct testing burdens that favor suppliers with established laboratory networks for specific structural formats.
- Bottles:PET barrier structures dominate beverage applications across Southeast Asia, with procurement concentrating around shelf-stable product lines in Thailand and Vietnam. Maharashtra and Gujarat manufacturing clusters are scaling PET bottle consumption as domestic food brands expand distribution reach.
- Containers:Polypropylene injection-molded formats are displacing polystyrene in Japan's microwaveable ready-meal segments where METI heat resistance thresholds exceed 120°C. South Korean convenience food manufacturers specify dual-ovenable polypropylene for premium positioning.
- Jars:Wide-mouth PET and polypropylene structures serve nutraceutical and personal care applications requiring tamper-evident closure systems.
- Trays:High-clarity thermoformed formats command premium positioning in Australia's retail-ready chilled food display where seal integrity determines shelf appeal.
Established volume favors bottles; emerging adoption favors containers.
End User:
Customer procurement centralization and extended producer responsibility draft regulations in Thailand and Vietnam are elevating volume-scale requirements and compliance documentation to contract prerequisites.
- Food:Processed food manufacturing clusters in western India drive rigid container demand for shelf-stable product lines. BIS IS 9845 certification timelines compress supplier eligibility for polyethylene and polypropylene articles.
- Beverages:Southeast Asian bottlers adopt material distribution optimization software to maintain performance at reduced PET gram weights. Australia's multi-site certification networks consolidate procurement with compliant incumbents.
- Personal Care:Premium positioning requirements in South Korea and Japan drive demand for injection-molded containers with digital printing integration for batch-level traceability.
- Pharmaceuticals:Stringent migration limit enforcement from China's SAMR disqualifies uncertified suppliers from primary packaging contracts.
Procurement scale concentrates in beverages; compliance intensity peaks in pharmaceuticals.
Material:
Regional resin supply concentration and paraxylene price volatility create divergent margin structures across polymer categories.
- Polyethylene:HDPE structures serve storage and transportation applications requiring mechanical durability. India's BIS mandates IS 9845 certification for polyethylene articles, extending approval cycles for new entrants.
- Polypropylene:Heat resistance above 120°C enables microwaveable applications across Japan and South Korea. Draft EPR regulations in Thailand stimulate rPP processing infrastructure investment ahead of mandate implementation.
- PET:Regional supply anchors on integrated feedstock positions, creating vulnerability to upstream price movements. Lightweighting technology fragments competitive positioning between resin-to-bottle operators and standalone converters.
- Polystyrene:Retained in cost-sensitive applications where heat resistance requirements remain below regulatory thresholds for displacement.
PET retains volume dominance; polypropylene claims the steepest expansion trajectory.
Application:
Functional performance specifications and retail channel requirements determine material selection and dimensional tolerance priorities across use cases.
- Packing:Barrier performance and seal integrity specifications dominate food-contact applications under tightening GB standards enforcement.
- Storage:Stackability and dimensional tolerances of 0.1–0.5 mm engineer mechanical protection for filled goods in warehouse environments.
- Transportation:Impact resistance and load-bearing specifications prioritize HDPE structural formats for logistics efficiency.
- Retail Display:Clarity and aesthetic presentation requirements concentrate demand for high-clarity thermoformed trays in Vietnam's expanding modern trade channels.
Operational efficiency centers on storage; margin expansion targets retail display.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Ningbo-Zhoushan Port complex underwrites China's dominance in APAC rigid plastic packaging, handling polymer feedstock imports that supply downstream conversion clusters across the Yangtze River Delta and Pearl River Delta manufacturing corridors.
China
GB 4806.7 migration limits enforced by SAMR are disqualifying uncertified converters from food-contact contracts. The Yangtze River Delta concentrates PET bottle production for domestic beverage brands expanding shelf-stable distribution. Guangzhou Huaxin Plastic Products Co.,Ltd anchors injection-molded container supply for regional processed food manufacturers.
India
Maharashtra and Gujarat manufacturing clusters are scaling rigid container consumption as domestic food brands expand PET barrier packaging for shelf-stable product lines. BIS mandates IS 9845 certification for polyethylene and polypropylene articles, compressing supplier eligibility timelines and elevating testing documentation to contract prerequisites. Pyramid Technoplast Ltd exemplifies specialized converters navigating extended approval cycles.
Japan
METI container safety protocols under JIS S 2053 are accelerating heat-resistant polypropylene adoption for microwaveable ready-meal segments. Kansai region converters are displacing polystyrene where thermal thresholds exceed 120°C. Osaka-based manufacturers supply dual-ovenable containers to convenience food brands targeting premium retail positioning.
Thailand
Draft EPR regulations proposing post-consumer collection quotas are stimulating investment in rPET processing infrastructure ahead of mandate implementation. Eastern Economic Corridor manufacturing zones concentrate beverage bottling capacity serving export markets. Amcor Group GmbH leverages multi-site certification networks to sustain large-format contracts across Australian and Thai procurement networks.
Vietnam
Modern trade expansion in Ho Chi Minh City and Hanoi is creating demand for high-clarity thermoformed trays with seal integrity specifications. Ben Luc Industrial Park hosts emerging conversion capacity targeting chilled food retail display applications. Foreign direct investment in blow-molding equipment is fragmenting competitive positioning between integrated operators and standalone converters.
APAC Rigid Plastic Packaging Market Competitive Landscape
Listed leaders compete with private specialists across certification depth and geographic coverage, creating a tiered structure where compliance documentation serves as the primary competitive barrier. The vendor base clusters around three strategic archetypes: integrated resin-to-package operators controlling upstream feedstock positions, multi-site certified converters serving multinational beverage procurement networks, and specialized injection-molding houses targeting domestic brand requirements. Dominant competitive moves include capacity expansion in rPET processing ahead of EPR mandate implementation and strategic partnerships to meet minimum order thresholds under centralized procurement regimes.
Within the integrated feedstock tier, Indorama Ventures Public Company Limited anchors regional PET resin supply and exemplifies upstream-controlled competitive positioning. Among diversified packaging conglomerates, Amcor Group GmbH and Berry Global Inc. occupy positions defined by multi-jurisdictional certification networks that sustain volume concentration under tightening GB standards and BIS mandates. These listed entities represent the scale-driven segment where compliance infrastructure investment creates separation from mid-tier converters struggling to fund in-house migration testing laboratories.
| Leading Market Players |
|---|
| Amcor Group GmbH |
| Berry Global Inc. |
| Pyramid Technoplast Ltd |
| Silgan Holdings Inc. |
| ALPLA |
| Indorama Ventures Public Company Limited |
| Guangzhou Huaxin Plastic Products Co.,Ltd |
| Sonoco Products Company |
| Pactiv Evergreen Inc. |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at Indorama Ventures' integrated PET resin facilities sets regional price floors across APAC rigid plastic packaging, concentrating supply-side leverage among upstream-controlled operators while compressing margins for standalone converters lacking captive feedstock positions.
Pricing Analysis
Certification level under GB 4806.7 and BIS IS 9845 creates the primary spread between qualified and unqualified suppliers. Three-tier pricing structure separates multinational-certified volumes from domestic-grade contracts and spot-market transactions. Cost compression in commodity-grade PET bottles is intensifying because lightweighting technology fragments equipment investment cycles. Mid-tier converters face acute price sensitivity as procurement officers centralize volumes with pre-qualified incumbents.
Supply Chain Analysis
China and Thailand anchor regional PET resin production and downstream blow-molding conversion. Feedstock supply draws from paraxylene imports through Ningbo-Zhoushan and Map Ta Phut port complexes. Single-source vulnerability concentrates around Indorama Ventures' integrated positions. Distribution runs through beverage bottler procurement networks and modern trade retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
APAC rigid plastic packaging represents an early-cycle expansion story as EPR mandate preparation stimulates rPET infrastructure investment ahead of regulatory implementation in Thailand and Vietnam.
For Market Incumbents: Shield large-format beverage contracts by accelerating multi-site certification coverage under tightening SAMR and BIS enforcement. Prioritize backward integration into rPET flake processing to meet draft collection quotas. Defensive capacity consolidation in Maharashtra and Gujarat manufacturing clusters protects volume concentration as procurement centralization elevates minimum order thresholds. For New Entrants and Emerging Players: Anchor in Vietnam's underpenetrated chilled food retail segment where high-clarity thermoformed tray demand outpaces qualified local supply. Target Ben Luc Industrial Park conversion capacity serving Ho Chi Minh City modern trade expansion. Lead with digital printing integration for batch-level traceability in pharmaceutical and nutraceutical packaging specifications. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors specialized injection-molding houses with documented GB 4806.7 compliance histories and established laboratory relationships. Long-term viability hinges on regulatory certification depth rather than scale alone. Monitor BIS IS 9845 approval cycle extensions as an inflection indicator for supplier consolidation velocity.| Strategic Initiative | Industry Significance |
|---|---|
| rPET Processing Infrastructure Investment | Thailand's draft EPR regulations stimulate capacity buildout ahead of mandate implementation. |
| Multi-Site Certification Network Expansion | GB 4806.7 and BIS IS 9845 compliance sustains procurement access across Australian and Thai beverage networks. |
| Lightweighting Technology Adoption | Material distribution optimization software preserves performance at reduced PET gram weights. |
| Production Consortium Formation | Regional converters aggregate capacity to meet centralized procurement minimum order thresholds. |
| Digital Printing Integration | Batch-level traceability capabilities unlock pharmaceutical and nutraceutical packaging specifications. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with packaging procurement officers, regulatory compliance managers, and plant operations directors at converters across China, India, Thailand, and Vietnam; and secondary validation through SAMR GB standard filings, BIS certification registries, customs trade data, and SEC disclosures from listed packaging conglomerates. Bottom-up volume modeling triangulated against top-down resin consumption estimates.
Across the projection horizon, the analytical framework segmented demand by product format, material category, end-use vertical, and regional manufacturing cluster. CAGRs derived from trend extrapolation of PET resin throughput, thermoformed tray adoption curves, and polypropylene displacement patterns in microwaveable applications. Forecast inputs incorporated EPR regulatory timeline assumptions and lightweighting technology diffusion rates.
Material uncertainties — paraxylene price volatility, BIS certification timeline extensions, and EPR mandate implementation delays — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory enforcement consistency and feedstock supply continuity. Recalibration cycles align with material shifts in SAMR migration limit enforcement and draft EPR regulation finalization.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rigid Packaging
Colombia Rigid Plastic Packaging Market
Rigid Packaging
Rigid Sleeve Boxes Market
Rigid Packaging
Mono-Material Trays Market
Rigid Packaging
Indonesia Rigid Plastic Packaging Market
Rigid Packaging
Rigid Plastic Packaging Market
Rigid Packaging
Certified-Circular Polyolefin Resins for Flexible and Rigid Packaging Market
Rigid Packaging
Brazil Rigid Plastic Packaging Market
Rigid Packaging
Mexico Rigid Packaging Market
Rigid Packaging
Australia and New Zealand Rigid Plastic Packaging Market
Rigid Packaging
Global Rigid Bulk Packaging Market
Rigid Packaging
Asia-Pacific Rigid Bulk Packaging Market
Rigid Packaging
United States Rigid PET Packaging Market
Rigid Packaging
Latin America Rigid Bulk Packaging Market
Rigid Packaging
Nutraceutical Rigid Packaging Market
Rigid Packaging
Middle East and Africa Rigid Plastic Packaging Market
Rigid Packaging
GCC Rigid Packaging Market