
 Global Rigid Bulk Packaging Market | 2026-2036
Global Rigid Bulk Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Global Rigid Bulk Packaging Market Foresight
UN-rated hazardous material specifications is collapsing the gap between commodity drums and premium chemical packaging tiers. Greif Inc. anchors North American steel drum supply through captive reconditioning networks. SCHUTZ GmbH & Co. KGaA dominates European intermediate bulk container refurbishment with closed-loop pooling systems. Mauser Packaging Solutions extends its position in composite IBCs through multi-material bonding expertise.
Rigid bulk packaging encompasses high-capacity, returnable or single-trip containers engineered to transport solids, semi-solids, and liquids in volumes typically exceeding 20 liters, with wall thicknesses and structural ribs designed to survive forklift handling, stacking loads, and chemical exposure without deformation or permeation. Plastic intermediate bulk containers lead volume due to weight advantages in downstream logistics, while steel drums retain margin concentration in corrosive chemical and food-grade applications where UN certification commands price premiums. Fiberboard totes compete in dry agricultural and construction bulk flows where one-way economics outweigh return logistics costs.
FDA food-contact rules, EPA hazardous waste container standards, and REACH substance restrictions collectively dictate material selection, liner compatibility, and end-of-life recovery obligations across major sales corridors. The EU Green Deal's packaging waste directives are forcing reformulation of composite materials to improve recyclability. Stakeholders must weigh capital allocation between reusable pooling infrastructure and lightweight single-use designs as regulatory thresholds for recycled content and extended producer responsibility tighten across multiple jurisdictions.
Market Dynamics
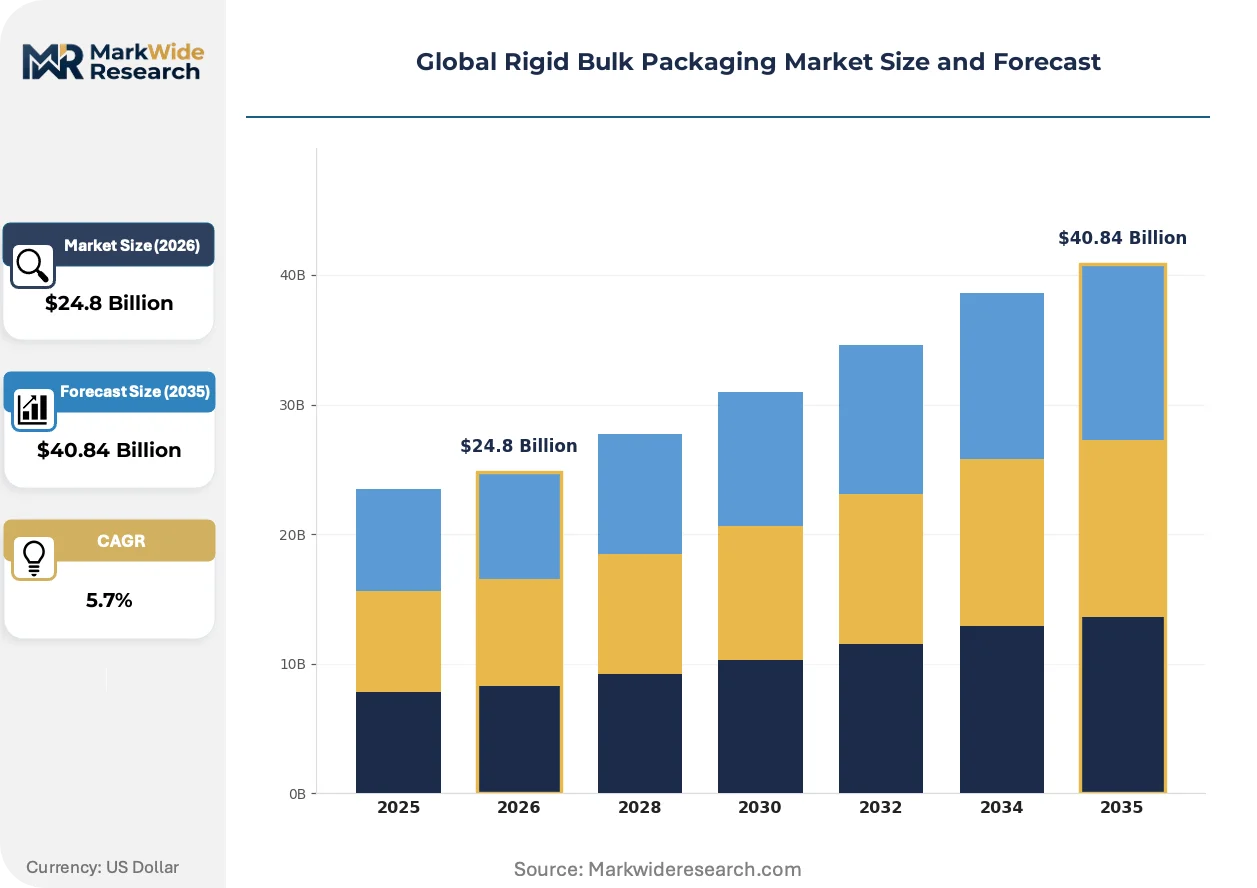
Chemical processors are consolidating purchasing power around reusable IBC pooling models while EU Green Deal mandates force material redesign, creating simultaneous pressure on capital allocation and compliance architecture across container manufacturers.
Growth Catalysts
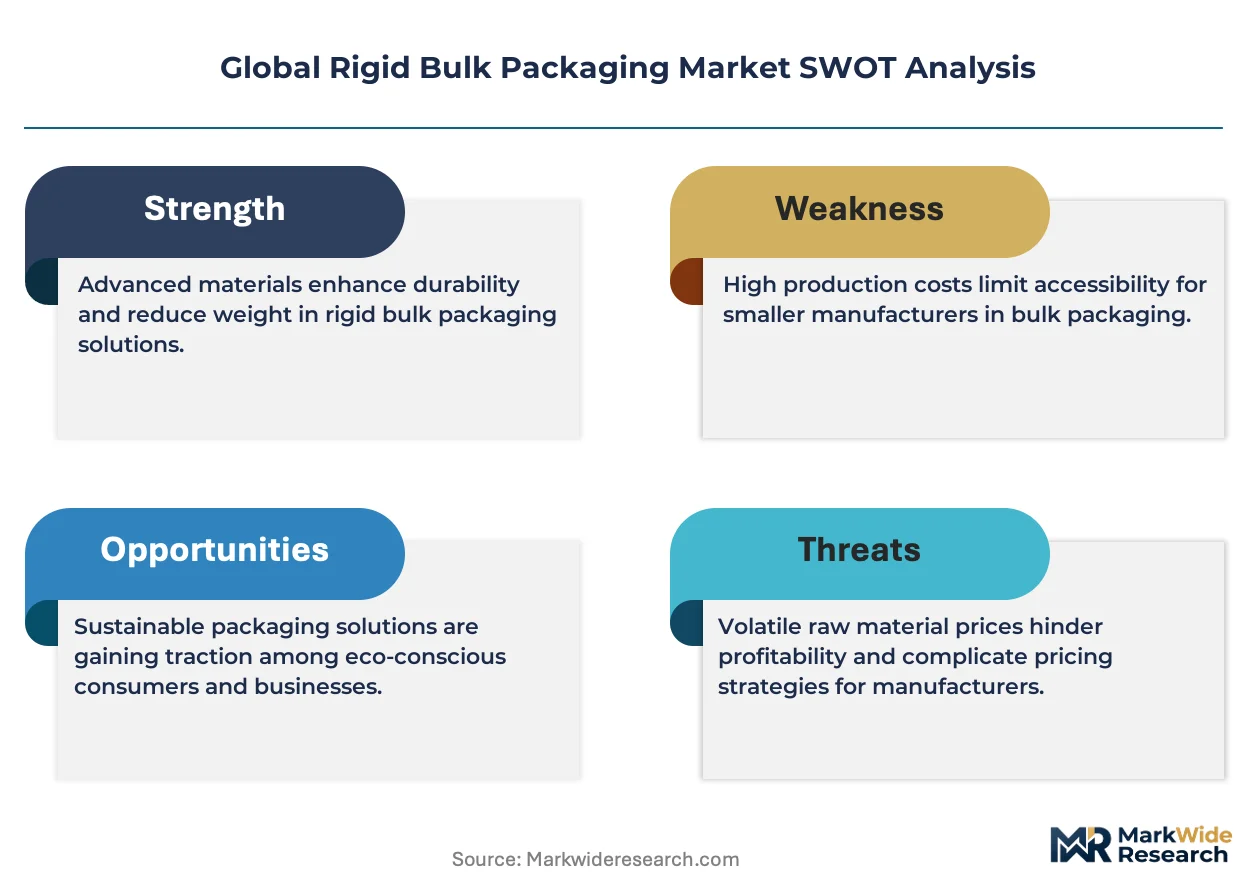
- REACH substance traceability mandates:European chemical shippers are upgrading container fleets to meet recycled content minimums, generating replacement demand for certified packaging systems.
- China export manufacturing clusters:Drum and IBC replenishment cycles concentrate in coastal industrial zones serving global chemical trade corridors.
- Lightweight composite bonding:Multi-material IBC construction reduces downstream logistics costs versus steel alternatives in non-corrosive applications.
Market Restraints
- Steel scrap price volatility:Input cost swings compress margins on UN-rated steel drum production without corresponding pricing power.
- Single-source resin supply:HDPE and polypropylene feedstock concentration among Gulf Coast petrochemical complexes creates geographic vulnerability.
- Fiberboard moisture degradation:Technical limitations exclude fiber totes from liquid chemical and humid-climate applications regardless of one-way economics.
Strategic Opportunities
- India specialty chemical expansion:Domestic formulation plants under PLI scheme incentives require virgin UN-certified packaging infrastructure.
- Digital pooling platforms:Asset-tracking IoT integration enables pay-per-use IBC models displacing capital purchase decisions.
- EU extended producer responsibility:Packaging waste directives create regulatory tailwind for closed-loop refurbishment networks over single-trip designs.
Industry Challenges
- UN certification timeline compression:Testing protocols for new composite formulations extend product development cycles beyond customer bid windows.
- Legacy ERP integration:Pooling operators struggle to synchronize container tracking data with shipper inventory management systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Rigid Bulk Packaging Market |
| Market Size in 2026 | $24.8 Billion |
| Market Size in 2035 | $40.84 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Drums, Intermediate Bulk Containers, Totes, Pallets, Barrels Material: Plastic, Steel, Fiberboard, Aluminum, Composite Application: Chemical Processing, Food & Beverage, Pharmaceuticals, Construction, Agriculture End User: Manufacturers, Distributors, Retail Packaging Companies, Logistics Providers |
| Companies Covered | Greif Inc., Berry Global Inc., SCHUTZ GmbH & Co. KGaA, Mauser Packaging Solutions, Snyder Industries, Mondi Group PLC, Core Plastech International Inc., BWAY Corporation, Packaging Corporation of America, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Rigid Bulk Packaging Market Shifts & Advancements
Container engineering is pivoting toward material hybridization and digital asset management, with regulatory chemistry restrictions and logistics cost pressures forcing simultaneous innovation across structural design and service delivery models.
Barrier-coated recycled polyethylene is miniaturizing the performance gap between virgin and post-consumer resins in chemical IBC construction. Mid-sized specialty chemical blenders are adopting these formulations fastest to preempt REACH compliance costs. The technology is miniaturizing premium virgin resin market share in non-hazardous applications where permeation tolerance permits.
EU Green Deal packaging waste directives are mandating recyclability-by-design for composite IBCs previously exempt from circular economy obligations. Manufacturers must now reformulate adhesive layers and dissimilar material bonds to enable mechanical separation at end-of-life. German chemical distributors face the steepest redesign timelines given their concentration of composite IBC fleets.
Asset-light pooling subscriptions are displacing capital purchase models among mid-market chemical shippers. Third-party logistics providers are inserting themselves between container manufacturers and end-users, capturing service revenue and utilization data. This channel shift is most advanced in Benelux and northern France where dense chemical production clusters support efficient container rotation economics.
Global Rigid Bulk Packaging Market Segmentation
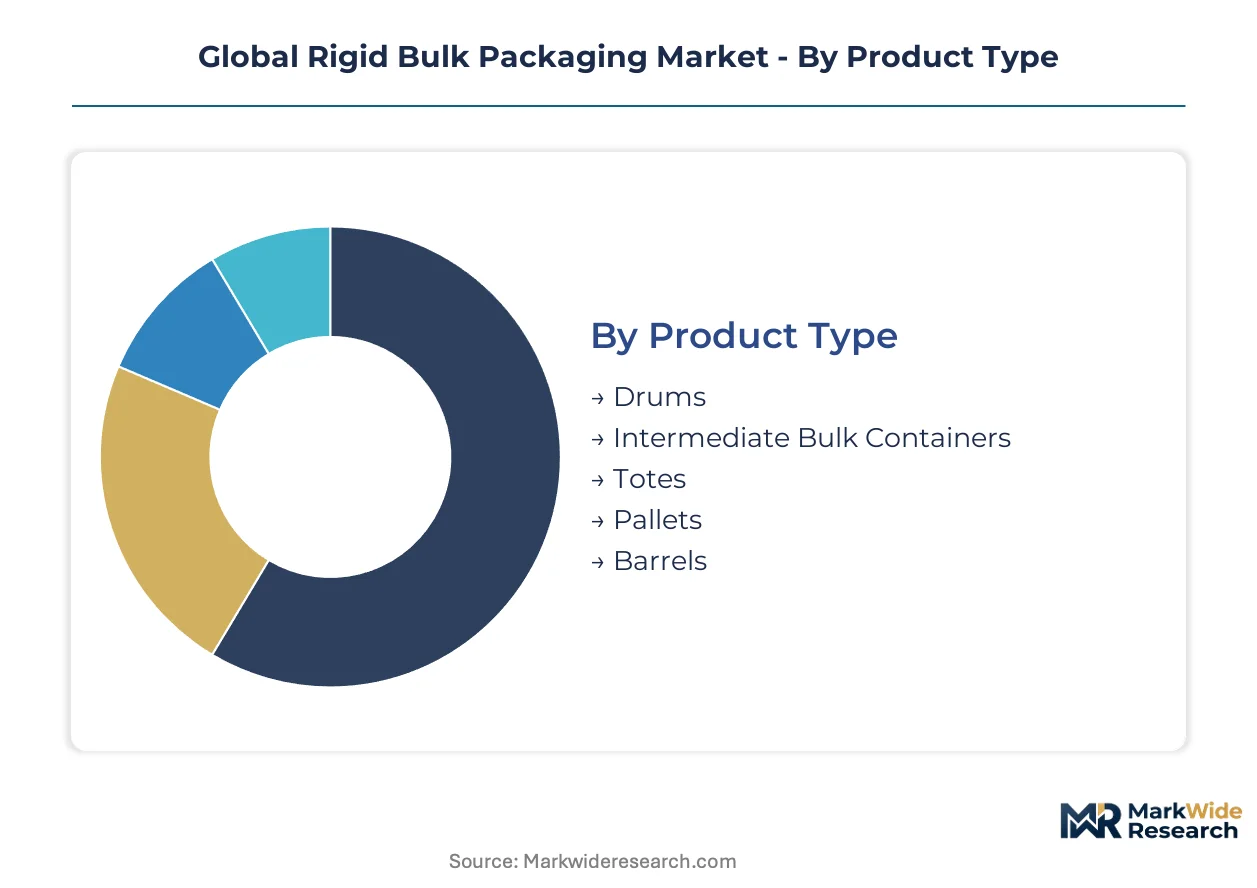
Segmentation in rigid bulk packaging reveals how substitution pressures and regulatory compliance reshape procurement patterns across material classes and container formats. Understanding these fault lines helps identify where pooling economics displace single-trip purchases and where UN certification creates pricing premiums.
Product Type:
Substitution pressure runs strongest against steel drums as composite IBCs capture chemical flows where corrosion resistance is not paramount, while fiber totes face displacement from reusable plastic alternatives in dry bulk applications.
- Drums:Cylindrical steel or plastic containers ranging from 30 to 55 gallons, engineered for UN-rated hazardous liquid transport with rolled rims and leakproof closures. Chemical processors in Germany and Texas maintain captive reconditioning networks to amortize per-trip costs across multiple rotation cycles.
- Intermediate Bulk Containers:Cubic or rectangular vessels typically holding 275 to 330 gallons, constructed from blow-molded HDPE with steel cage reinforcement or all-plastic designs. Coastal manufacturing clusters in China drive replenishment cycles for export chemical trade, with lightweight composite bonding reducing downstream logistics costs versus steel alternatives.
- Totes:Rectangular plastic containers with integrated pallet bases, designed for semi-bulk liquid and powder handling in food-grade and industrial applications. FDA food-contact rules dictate liner compatibility for dairy and beverage processors.
- Pallets:Load-bearing platforms enabling forklift handling and stacking of bulk containers, manufactured from plastic, wood, or metal depending on hygiene and durability requirements. Pharmaceutical cold chains in Switzerland specify plastic pallet formats to prevent contamination.
- Barrels:Traditional cylindrical containers with curved staves and metal hoops, now largely supplanted by drums in industrial applications but retained for specialty wine, spirits, and artisanal food aging. French cognac houses and Kentucky distilleries sustain residual demand for oak barrel maturation.
Drums anchor the volume base while intermediate bulk containers gain share at the steepest rate.
Material:
Cost tier differentiation separates virgin resin formulations commanding REACH compliance premiums from recycled-content alternatives squeezing margin in commodity chemical applications.
- Plastic:High-density polyethylene and polypropylene dominate through blow-molding and rotational forming, offering weight advantages in downstream logistics. HDPE feedstock concentration among Gulf Coast petrochemical complexes creates geographic supply vulnerability for North American converters.
- Steel:Cold-rolled carbon steel with interior linings or coatings provides UN-certified containment for corrosive chemicals and solvent-based formulations. Steel scrap price volatility compresses margins on drum production without corresponding pricing power in commodity segments.
- Fiberboard:Multi-wall corrugated constructions with moisture barriers compete in dry agricultural and construction bulk flows where one-way economics outweigh return logistics costs. Technical limitations exclude fiber totes from liquid chemical and humid-climate applications regardless of cost advantage.
- Aluminum:Lightweight metal with superior corrosion resistance for specialty pharmaceutical and food-grade applications where metallic contamination must be minimized. Swiss pharmaceutical packaging specifications favor aluminum for high-purity active ingredient transport.
- Composite:Multi-material bonding of plastic liners, steel cages, and structural reinforcements optimizing strength-to-weight ratios in IBC construction. EU Green Deal packaging waste directives mandate redesign of adhesive layers to enable mechanical separation at end-of-life.
Plastic retains the broadest installed base while composite formulations climb the fastest as chemical shippers balance lightweight logistics against circular economy obligations.
Application:
Application segmentation tracks how end-use chemistry and hygiene requirements dictate material selection, with corrosive chemical handling commanding premium specifications and food-grade applications imposing parallel FDA and EFSA compliance architectures.
- Chemical Processing:Corrosive acids, solvents, and petrochemical intermediates requiring UN-rated containment with permeation resistance and liner compatibility. REACH substance traceability mandates force European chemical shippers to upgrade container fleets to meet recycled content minimums.
- Food & Beverage:Edible oils, dairy products, and beverage concentrates requiring FDA food-contact compliance and sanitary design with clean-in-place capability. Indian dairy cooperatives under FSSAI jurisdiction drive drum demand for ghee and milk powder distribution.
- Pharmaceuticals:Active pharmaceutical ingredients and excipients demanding contamination-free transport with batch traceability and tamper-evident sealing. EMA good distribution practice rules govern container qualification for cross-border API movements within Europe.
- Construction:Cement additives, adhesives, and coatings where moisture resistance and rough handling tolerance outweigh premium material specifications. Brazilian construction chemical distributors favor fiberboard totes for one-way dry mortar packaging.
- Agriculture:Fertilizers, pesticides, and seeds requiring chemical resistance for agrochemical formulations and venting for respiring grain. Canadian PMRA pesticide container regulations mandate triple-rinse protocols and recycling infrastructure participation.
Chemical processing anchors the volume base while pharmaceuticals gains share at the steepest rate.
End User:
Customer type segmentation distinguishes capital-intensive manufacturers with captive container fleets from asset-light distributors adopting third-party pooling subscriptions.
- Manufacturers:Chemical formulators, food processors, and pharmaceutical producers owning dedicated container assets or participating in closed-loop refurbishment networks. German specialty chemical manufacturers under EU extended producer responsibility rules favor pooled IBC models over purchase decisions.
- Distributors:Third-party chemical and ingredient merchants rotating containers across multiple supplier and customer relationships, capturing utilization data through IoT asset tracking. Benelux chemical distributors lead adoption of digital pooling platforms with pay-per-use pricing.
- Retail Packaging Companies:Consumer goods converters and private label packagers sourcing bulk inputs for downstream repackaging into consumer formats. French retail packaging clusters in the Lyon corridor specify food-grade IBCs for edible oil and syrup receipt.
- Logistics Providers:Third-party transportation and warehousing operators inserting themselves between manufacturers and end-users, capturing service revenue and container rotation economics. Northern France chemical logistics hubs support efficient IBC pooling through dense production cluster proximity.
Manufacturers anchor the volume base while logistics providers gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in coastal China and the US Gulf Coast show the highest price elasticity for commodity drum purchases, while German chemical processors absorb premium pooling fees to satisfy EU compliance mandates without volume reduction.
United States
EPA hazardous waste container standards and FDA food-contact rules govern material selection across chemical and food-grade applications. Texas and Louisiana host dense petrochemical clusters where drum reconditioning networks amortize per-trip costs. Houston-area chemical distributors maintain captive steel drum fleets to serve export corridors.
Germany
REACH substance traceability mandates and EU Green Deal packaging waste directives force fleet upgrades to meet recycled content minimums. The Rhine-Ruhr industrial belt concentrates specialty chemical manufacturing requiring UN-certified composite IBCs. BASF and Bayer supplier networks in Ludwigshafen drive closed-loop refurbishment adoption.
China
Export manufacturing clusters in the Yangtze River Delta and Pearl River Delta trigger drum and IBC replenishment cycles for global chemical trade. GB standards and MIIT industrial packaging regulations govern domestic specifications. Ningbo and Shanghai port zones concentrate container manufacturing capacity serving European and North American importers.
India
PLI scheme incentives for specialty chemical formulation plants generate virgin UN-certified packaging demand. FSSAI jurisdiction governs food-grade drum specifications for dairy cooperatives distributing ghee and milk powder. Gujarat's Dahej and Mundra industrial corridors anchor domestic drum consumption growth.
Switzerland
Swissmedic pharmaceutical packaging specifications favor aluminum and plastic formats for high-purity active ingredient transport. Dense pharmaceutical production around Basel requires contamination-free containers with batch traceability. Cold chain logistics operators specify plastic pallet formats to prevent metallic contamination.
Global Rigid Bulk Packaging Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across the rigid bulk packaging sector. The market structures around three tiers: integrated multinationals with captive reconditioning networks, regional specialists with pooling expertise, and commodity converters serving price-sensitive chemical flows. Strategic moves concentrate on backward integration into reconditioning assets and geographic expansion through distributor partnerships rather than greenfield capacity.
Within the integrated multinational tier, Greif Inc. and SCHUTZ GmbH & Co. KGaA exemplify divergent regional dominance patterns—Greif anchoring North American steel drum supply through captive networks, SCHUTZ commanding European IBC refurbishment through closed-loop systems. Mauser Packaging Solutions occupies a position in composite IBC construction where multi-material bonding expertise creates defensible positioning against steel alternatives.
| Leading Market Players |
|---|
| Greif Inc. |
| Berry Global Inc. |
| SCHUTZ GmbH & Co. KGaA |
| Mauser Packaging Solutions |
| Snyder Industries |
| Mondi Group PLC |
| Core Plastech International Inc. |
| BWAY Corporation |
| Packaging Corporation of America |
| Others |
Supply & Pricing Matrix
Capacity utilization at Gulf Coast HDPE complexes sets price floors for North American plastic drum converters, while Chinese blow-molding clusters anchor global IBC cost baselines through scale economies that European REACH-compliant producers cannot match without pooling service premiums.
Pricing Analysis
UN certification tiers dictate the pricing structure across rigid bulk packaging, with virgin resin formulations commanding REACH compliance premiums and recycled-content alternatives squeezing margin in commodity chemical flows. Three-tier pricing separates UN-certified premium drums from standard industrial grades and economy fiber totes. Cost compression in steel drum production is intensifying because scrap price volatility outpaces converter pricing power. Chemical processors in Texas show highest price elasticity for commodity purchases, while German specialty blenders absorb pooling premiums to satisfy EU mandates.
Supply Chain Analysis
China, the United States, and Germany anchor global rigid bulk packaging manufacturing, with Ningbo and Shanghai port zones concentrating blow-molded IBC capacity serving European and North American importers. HDPE and polypropylene feedstock draws from Gulf Coast petrochemical complexes, while cold-rolled steel for drum construction hinges on scrap collection networks. Single-source resin concentration creates geographic vulnerability to hurricane disruption. Distribution runs through third-party logistics providers inserting themselves between manufacturers and chemical shippers with pay-per-use pooling models.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution pressure from lightweight composite IBCs displacing steel drums in non-corrosive chemical flows, requiring defensive positioning around certification barriers and refurbishment network density.
For Market Incumbents: Compound captive reconditioning network coverage to amortize per-trip costs across multiple rotation cycles, locking in chemical processor loyalty against emerging composite alternatives. Deepen backward integration into HDPE recycling streams to preempt REACH content mandates. Prioritize IoT asset-tracking deployment to capture utilization data before third-party logistics providers consolidate pooling platform control.
For New Entrants and Emerging Players: Differentiate on barrier-coated recycled polyethylene formulations that miniaturize the performance gap to virgin resins in non-hazardous IBC applications. Target mid-sized specialty chemical blenders in Benelux and northern France where dense production clusters support efficient container rotation economics. Lead with digital pooling subscriptions displacing capital purchase decisions among asset-light distributors.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among closed-loop refurbishment operators with established pooling platforms and IoT-enabled asset tracking. Long-term viability rests on regulatory tailwinds from EU extended producer responsibility rules favoring service models over single-trip manufacturing. Acquisition focus should center on regional specialists with dense geographic container rotation networks. The signal to watch is REACH recycled content threshold tightening accelerating fleet replacement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Reconditioning Assets | Greif Inc.'s captive steel drum networks in Texas demonstrate amortization economics across multiple rotation cycles. |
| Composite Material Redesign for Recyclability | EU Green Deal mandates force adhesive layer reformulation to enable mechanical separation at end-of-life. |
| Digital Pooling Platform Deployment | IoT asset-tracking integration enables pay-per-use models displacing capital purchase decisions among mid-market shippers. |
| Barrier-Coated Recycled Resin Adoption | Mid-sized specialty chemical blenders adopt post-consumer HDPE formulations fastest to preempt REACH compliance costs. |
| Geographic Expansion through Distributor Partnerships | Benelux chemical distributors capture service revenue through dense production cluster proximity supporting efficient rotation. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with chemical procurement directors, IBC pooling network managers, drum reconditioning facility operators, and regulatory compliance officers at REACH-registered chemical formulators. Secondary validation drew from ECHA substance registration databases, EU packaging waste directive implementation reports, customs trade data for HS-coded container categories, and SEC filings of listed packaging manufacturers. Bottom-up volume estimates from regional production clusters were triangulated against top-down demand models from end-use industry consumption patterns.
Across the analysis window, forecasts were constructed through segmentation by material class, container format, end-use industry, and geographic regulatory cluster. CAGRs were derived from trend extrapolation of fleet replacement cycles, regulatory compliance cost trajectories, and logistics cost optimization behaviors. Modeled inputs included REACH recycled content threshold adoption timelines, steel scrap price volatility indices, and HDPE feedstock capacity expansion announcements.
Material uncertainties — regulatory timeline slippage, feedstock supply disruption, and composite material performance validation delays — sit outside the modeled envelope. Forecasts reflect documented assumptions about pooling subscription adoption rates and refurbishment network density thresholds. Recalibration cycles align with material shifts in EU Green Deal implementation pacing and UN certification protocol revisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rigid Packaging
Global Rigid Paper Containers Market
Rigid Packaging
Morocco Rigid Plastic Packaging Market
Rigid Packaging
France Rigid Plastic Packaging Market
Rigid Packaging
Rigid Plastic Packaging Market
Rigid Packaging
Mexico Rigid Packaging Market
Rigid Packaging
GCC Rigid Plastic Packaging Market
Rigid Packaging
Rigid Boxes Market
Rigid Packaging
Rigid Industrial Packaging Market
Rigid Packaging
Italy Rigid Plastic Packaging Market
Rigid Packaging
Indonesia Rigid Plastic Packaging Market
Rigid Packaging
Germany Rigid Plastic Packaging Market
Rigid Packaging
Colombia Rigid Plastic Packaging Market
Rigid Packaging
United Kingdom Rigid Plastic Packaging Market
Rigid Packaging
Latin America Rigid Bulk Packaging Market
Rigid Packaging
Vietnam Rigid Plastic Packaging Market
Rigid Packaging
Egypt Rigid Plastic Packaging Market