
 Saudi Arabia Rigid Plastic Packaging Market | 2026-2036
Saudi Arabia Rigid Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Rigid Plastic Packaging Market Analytics
Polyethylene terephthalate (PET) is realigning rigid packaging economics across Saudi Arabia as converters substitute heavier glass and metal formats. SABIC Packaging Solutions leverages its captive resin supply to dominate upstream feedstock access. Zamil Plastic Industries Co anchors its position through large-scale blow-molding operations serving beverage clients. Packaging Product Company (PPC) differentiates via specialized barrier-layer technologies for oxygen-sensitive goods.
Saudi Arabia Rigid Plastic Packaging comprises shaped thermoplastic structures—typically two to five millimeters in wall thickness—produced through injection molding, blow molding, or thermoforming processes, designed to protect contents from mechanical damage, moisture ingress, and UV degradation during distribution and retail display. Bottles and containers command the largest volume share, while pharmaceutical-grade PET jars attract premium margins due to stringent extractables testing requirements. Polypropylene tubs expand fastest in dairy and ready-meal segments where microwave compatibility drives substitution from polystyrene.
The Saudi Food and Drug Authority (SFDA) enforces polymer migration limits that dictate resin selection and additive packages for food-contact applications, while the Saudi Standards, Metrology and Quality Organization (SASO) mandates recyclability labeling that shapes converter material strategies. The General Authority for Competition monitors pricing behavior in concentrated resin supply channels. Stakeholders must track evolving extended producer responsibility frameworks and assess whether mechanical recycling infrastructure investments outpace chemical recycling partnerships.
Market Dynamics
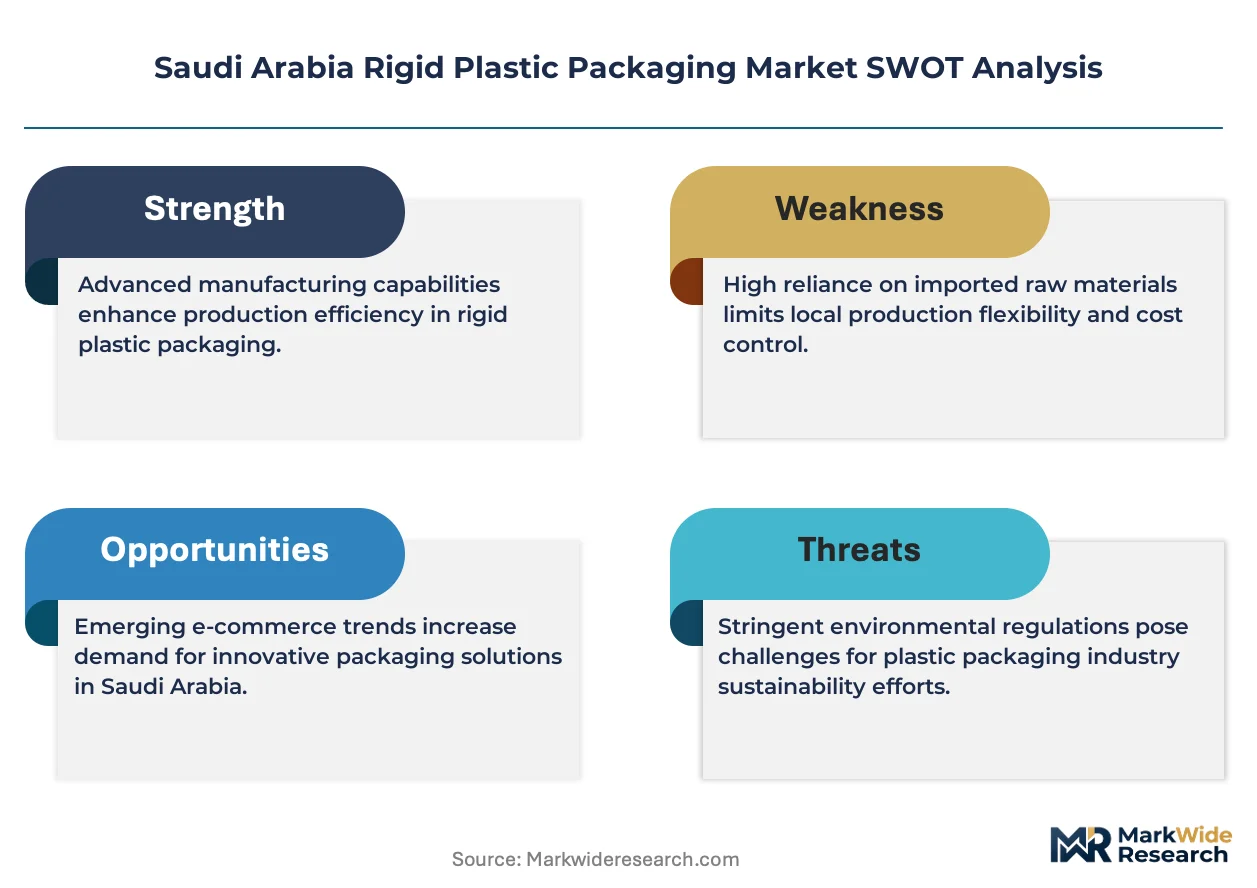
SFDA polymer migration limits are forcing converters to requalify resin formulations and additive packages, compressing development timelines while elevating compliance costs across food-contact rigid packaging production in the Kingdom.
Growth Catalysts
- Extended Shelf-Life Dairy Demand:Food processors are specifying multilayer barrier containers for ambient distribution, pulling high-performance PET and polypropylene conversions.
- SFDA Safety Protocol Updates:Tighter extractables testing requirements for pharmaceutical-grade packaging are creating premium pricing tiers for certified converters.
- Riyadh Industrial Corridor Concentration:Proximity to SABIC petrochemical feedstock sources reduces resin logistics costs and secures supply continuity for blow-molding operations.
Market Restraints
- Ethylene Feedstock Volatility:Crude-linked naphtha pricing transmits directly to polyethylene and polypropylene resin costs, squeezing converter margins during upstream spikes.
- Single-Source Resin Dependence:SABIC dominates domestic polymer supply, creating concentration risk for converters lacking alternative import channels or long-term offtake agreements.
- Mechanical Recycling Yield Limits:Contamination in post-consumer PET streams caps recycled content ratios below brand owner sustainability commitments without chemical recycling scale-up.
Strategic Opportunities
- Eastern Province Dairy Expansion:Al-Ahsa and Dammam processing clusters are underpenetrated for barrier-modified polypropylene tubs versus Riyadh supply concentration.
- SASO Recyclability Labeling Mandate:Early compliance with sorting-code standardization creates positioning advantage as retail chains enforce supplier certification.
- Barrier-Layer Thermoforming Convergence:Oxygen-scavenging EVOH coextrusion is migrating from bottles to deli containers and ready-meal trays, opening equipment upgrade cycles.
Industry Challenges
- Multilayer Coextrusion Technician Scarcity:Barrier-layer process control requires specialized extrusion expertise that outpaces vocational training pipeline output in the Kingdom.
- Pharmaceutical Extractables Documentation:USP Class VI and EP 3.1 certification timelines for new resin grades extend qualification periods beyond typical contract award windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Rigid Plastic Packaging Market |
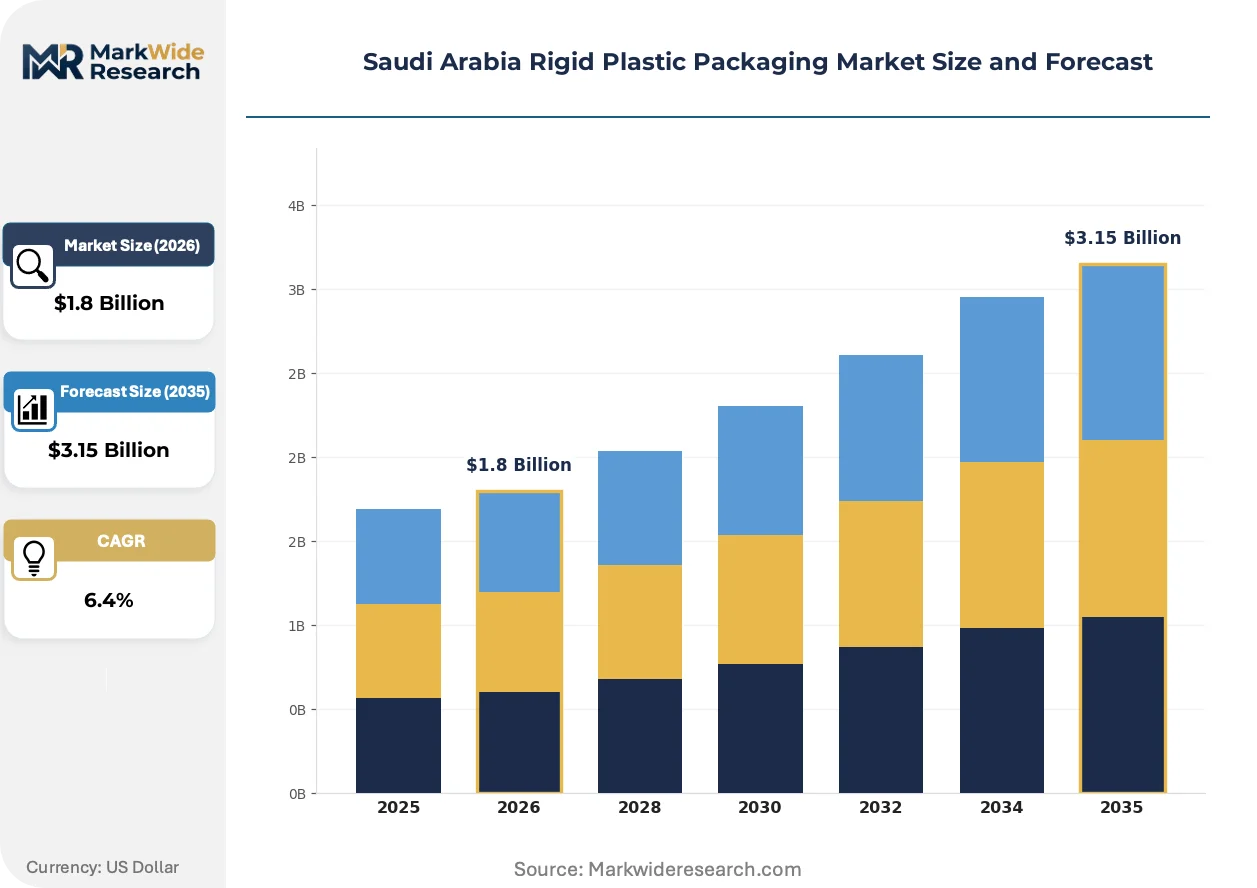
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.15 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Containers, Tubs, Jars Material: Polyethylene, Polypropylene, Polystyrene, PET Application: Food & Beverage, Personal Care, Household Products, Pharmaceuticals Distribution Channel: Retail, E-commerce, Direct Sales, Wholesalers |
| Companies Covered | Zamil Plastic Industries Co, Packaging Product Company (PPC), SABIC Packaging Solutions, ALSAD Modern and Advanced Co. Ltd., 3P Gulf Group, Obeikan Investment Group, Arabian Plastic Industrial Company Limited, Saudi Plastic Packaging Systems (SPPS), Takween Advanced Industries Company, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Rigid Plastic Packaging Market Evolving Landscape
Digital printing and smart packaging integration are disrupting traditional label economics, while regulatory pressure on circularity accelerates material science investment across Saudi converter operations.
High-speed digital inkjet decoration is converging with rigid container production lines, enabling lot-size-one customization without plate-change downtime. Beverage brands in Jeddah and Riyadh are piloting variable-data printing for regional promotional campaigns. This capability is compressing minimum order quantities and enabling direct-to-retail channel experiments previously uneconomical at blow-molding scale.
SASO recyclability labeling mandates are reshaping material selection protocols for converters serving modern retail chains. The technical specification requires resin identification codes and sorting guidance on all primary packaging. Food-contact applications face the steepest compliance burden, with dairy and bottled water segments already adapting artwork and mold-design specifications.
Retail buyer consolidation is compressing supplier qualification cycles as hypermarket chains centralize procurement under private-label strategies. Lulu, Carrefour, and Tamimi are unbundling legacy distributor relationships for direct converter contracts with volume-commitment pricing. This pattern concentrates most visibly in Riyadh and Jeddah, where retail footprint density supports logistics optimization demands.
Saudi Arabia Rigid Plastic Packaging Market Segmentation
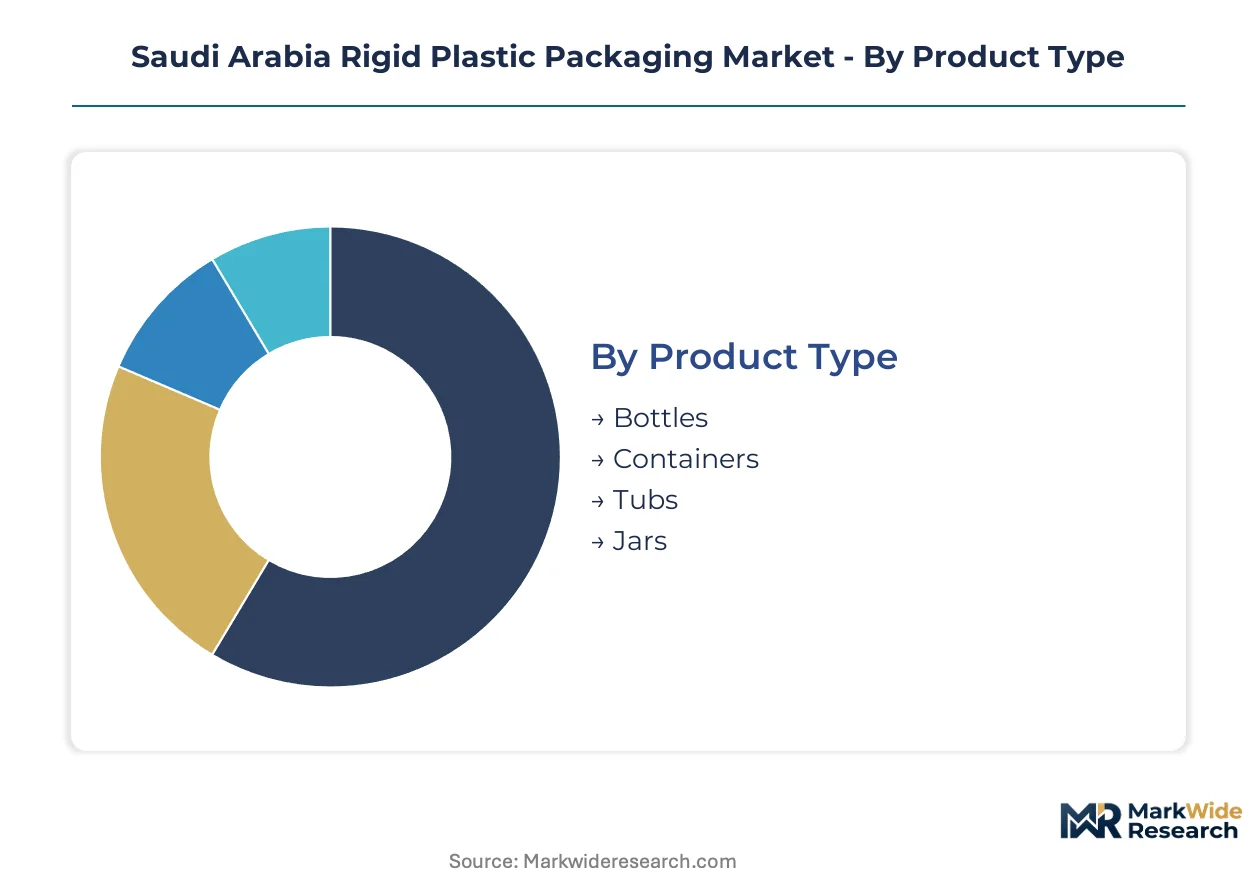
Segmentation in Saudi Arabia's rigid plastic packaging market reveals how capital deployment, regulatory exposure, and feedstock access create divergent margin profiles across converter operations. Each dimension shapes competitive positioning differently depending on proximity to SABIC resin supply and SFDA compliance intensity.
Product Type:
Blow-molding and injection-molding equipment intensity varies sharply across formats, with barrier-capable bottle lines demanding the highest upfront capital outlays for multilayer coextrusion capability.
- Bottles:High-speed reheat stretch-blow systems dominate beverage and dairy applications, with SFDA extractables testing requirements forcing pharmaceutical-grade lines to carry redundant quality infrastructure. Demand concentrates in Riyadh's industrial corridor where SABIC polyethylene terephthalate feedstock reaches converters through dedicated pipeline networks.
- Containers:Thin-wall injection molding serves ready-meal and deli segments where polypropylene microwave compatibility drives substitution from polystyrene. Eastern Province dairy processors in Al-Ahsa are expanding ambient distribution capacity, pulling barrier-modified container specifications previously concentrated in Riyadh supply bases.
- Tubs:Thermoformed polypropylene structures with oxygen-scavenging EVOH layers target extended shelf-life yogurt and cheese applications requiring modified atmosphere packaging.
- Jars:Wide-mouth PET and polypropylene formats serve nut butter, spreads, and pharmaceutical solids where wide-diameter neck finishes complicate blow-mold tooling design.
Most installed capacity flows through Bottles. Expansion is steepest in Containers.
Material:
Resin selection protocols are hardening around SASO recyclability labeling mandates and brand owner sustainability commitments, with mechanical recycling yield limits constraining post-consumer content ratios.
- Polyethylene:High-density grades dominate chemical and household product containers where stress-crack resistance outweighs clarity requirements. Jeddah converters serving industrial cleaning clients specify bimodal resins for drop-impact performance.
- Polypropylene:Random copolymer clarity improvements and nucleated fast-cycle grades are displacing polystyrene in dairy and ready-meal segments. Riyadh blow-molders are qualifying high-melt-strength grades for extrusion blow-molding of handled containers previously resin-locked to HDPE.
- Polystyrene:General-purpose crystal grades retreat to low-cost disposable applications as polypropylene and PET capture food-contact volume. Remaining demand concentrates in electronics packaging and laboratory disposables where amorphous clarity and stiffness specifications resist substitution.
- PET:Bottle-grade and thermoforming sheet specifications split demand between beverage giants and food tray converters. SFDA pharmaceutical-grade certification creates premium pricing tiers for converters with dedicated cleanroom extrusion capability.
Polyethylene holds the largest installed base. PET is climbing the fastest on barrier-layer and pharmaceutical qualification drivers.
Application:
End-use diversification strategies separate commodity converters from specialists, with pharmaceutical and personal care segments rewarding extractables documentation capability that food-grade operations rarely maintain.
- Food & Beverage:Multilayer barrier bottles and tubs for ambient dairy and bottled water absorb the largest resin volumes. Zamil Plastic Industries anchors this segment through high-volume blow-molding contracts with beverage clients.
- Personal Care:Premium cosmetic jars and dispensing bottles require thick-wall injection molding with in-mold labeling or digital decoration capability. Jeddah and Riyadh beauty brands are piloting lot-size-one customization through direct-to-shape inkjet integration.
- Household Products:HDPE bottles for detergents and cleaning chemicals prioritize stress-crack resistance and handle integration over clarity. Price pressure from private-label retail consolidation compresses converter margins in this segment.
- Pharmaceuticals:USP Class VI and EP 3.1 certification requirements extend qualification timelines and create defensive moats for incumbent suppliers. Packaging Product Company differentiates through specialized barrier-layer technologies for oxygen-sensitive drug formulations.
Food & Beverage dominates current throughput. Pharmaceuticals shows the steepest margin expansion trajectory on certification barriers.
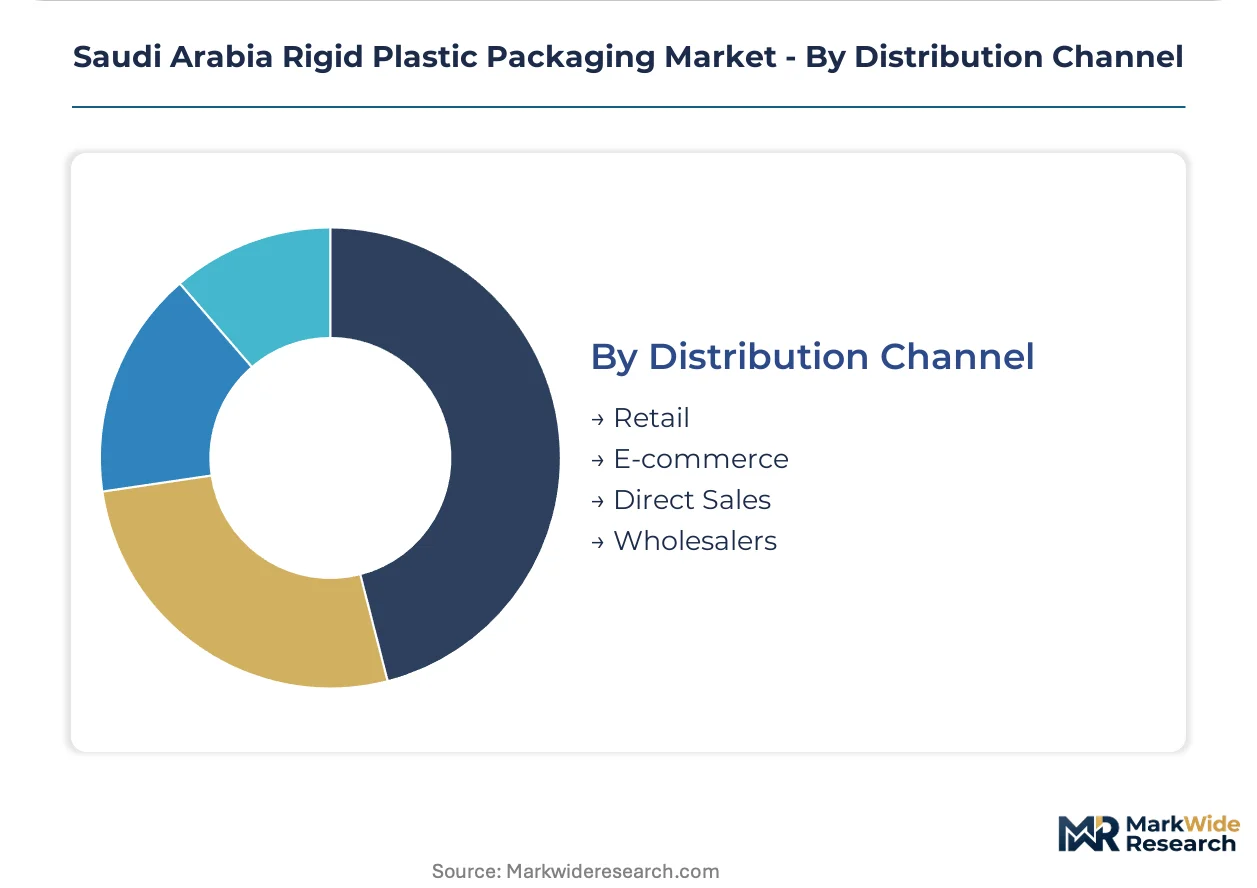
Distribution Channel:
Channel mix determines order-size economics and artwork flexibility requirements, with retail consolidation forcing converters to absorb direct procurement complexity previously handled by distributors.
- Retail:Hypermarket chains including Lulu, Carrefour, and Tamimi are unbundling legacy distributor relationships for direct converter contracts with volume-commitment pricing. SASO recyclability labeling mandates hit this channel first as retail buyers enforce supplier certification.
- E-commerce:Direct-to-consumer shipment requirements are driving secondary packaging specifications that protect primary rigid containers through last-mile handling. Smaller lot sizes and variable-data printing compatibility separate e-commerce-capable converters.
- Direct Sales:Institutional and food-service clients purchase bulk containers through converter direct relationships, bypassing retail markup structures.
- Wholesalers:Traditional distributor networks retain relevance in smaller city coverage and generic product segments where retail buyer consolidation has not yet penetrated.
Retail channels command the largest revenue share. E-commerce is gaining share fastest on fulfillment infrastructure investment.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Riyadh's industrial corridor anchors Saudi Arabia's rigid plastic packaging capacity, clustering blow-molding and injection-molding operations within pipeline reach of SABIC petrochemical feedstock sources.
Riyadh
Dairy processors and beverage bottlers drive multilayer barrier container demand across Riyadh's conversion plants. SFDA extractables testing requirements force pharmaceutical-grade lines to maintain redundant quality infrastructure. The Riyadh industrial corridor concentrates Zamil Plastic Industries and SABIC Packaging Solutions operations near dedicated resin supply networks.
Eastern Province
Al-Ahsa and Dammam dairy clusters expand ambient distribution capacity, pulling barrier-modified polypropylene tub specifications from Riyadh supply bases. The region's proximity to SABIC's Jubail petrochemical complex secures polyethylene and polypropylene logistics advantages. Eastern Province conversion plants are qualifying high-melt-strength grades for extrusion blow-molding applications.
Western Region
Jeddah converters serve industrial cleaning and household product clients with bimodal HDPE specifications for stress-crack resistance. Retail buyer consolidation at Lulu and Carrefour hypermarkets compresses supplier qualification cycles. Jeddah beauty brands pilot variable-data digital printing for lot-size-one cosmetic packaging customization.
NEOM Northwest
The giga-project's construction phase generates bulk chemical container demand for cement admixtures and industrial fluids. SFDA polymer migration limits apply to food-service packaging for project workforce catering. NEOM's circular economy mandates are accelerating chemical recycling partnership discussions with Riyadh-based converters.
Saudi Arabia Rigid Plastic Packaging Market Competitive Landscape
Global resin majors compete with regional fabrication champions across feedstock access and barrier-layer technology vectors. Market structure concentrates upstream polymer supply around SABIC while downstream conversion fragments across specialized blow-molders, thermoformers, and injection molders. Three archetypes dominate: petrochemical-integrated converters with captive resin supply, independent fabricators with long-term offtake agreements, and barrier-technology specialists serving pharmaceutical and oxygen-sensitive food segments. Capacity expansion and strategic partnerships represent the dominant competitive moves, with retail buyer consolidation forcing direct contract relationships that bypass legacy distribution channels.
Within the petrochemical-integrated tier, SABIC Packaging Solutions exemplifies upstream-downstream control through captive polyethylene terephthalate and polypropylene supply. Zamil Plastic Industries Co anchors high-volume beverage and dairy blow-molding operations from Riyadh's industrial corridor. Packaging Product Company (PPC) occupies the barrier-technology specialist position, with oxygen-scavenging EVOH coextrusion capability serving pharmaceutical-grade extractables certification requirements.
| Leading Market Players |
|---|
| Zamil Plastic Industries Co |
| Packaging Product Company (PPC) |
| SABIC Packaging Solutions |
| ALSAD Modern and Advanced Co. Ltd. |
| 3P Gulf Group |
| Obeikan Investment Group |
| Arabian Plastic Industrial Company Limited |
| Saudi Plastic Packaging Systems (SPPS) |
| Takween Advanced Industries Company |
| Others |
Value Network & Pricing Analysis
Multilayer coextrusion technician scarcity in Riyadh's industrial corridor widens labor-cost differentials between premium barrier-certified converters and commodity blow-molders, translating directly into pricing-tier spreads that separate pharmaceutical-grade from food-grade packaging supply.
Pricing Analysis
Crude-linked naphtha pricing transmits volatility directly to polyethylene and polypropylene resin costs, forcing converters to absorb margin compression during upstream spikes or pass through via contract renegotiation. Pricing stratifies across pharmaceutical-certified premium tiers, food-contact standard grades, and generic industrial economy levels, with SFDA extractables documentation creating the steepest differentiation. Price erosion runs through the household products segment as retail buyer consolidation at Lulu and Carrefour centralizes procurement under volume-commitment terms. Food and beverage clients demonstrate highest price sensitivity due to thin operating margins, while pharmaceutical buyers accept premium positioning for USP Class VI and EP 3.1 certified supply security.
Supply Chain Analysis
Post-consumer PET collection and mechanical recycling flows remain underdeveloped, constraining closed-loop material availability and forcing brand owners toward chemical recycling partnerships or virgin resin dependence. Feedstock concentration centers on Saudi Arabia's Eastern Province where SABIC's Jubail petrochemical complex anchors domestic polyethylene and polypropylene supply, with resin logistics advantages diminishing toward Jeddah and northern regions. Raw material dependencies rest on naphtha-derived ethylene, imported barrier-layer EVOH resins, and specialty additive packages for oxygen-scavenging formulations. Single-source resin vulnerability creates structural risk for converters lacking alternative import channels or long-term offtake agreements. Distribution runs through direct converter contracts with retail hypermarket chains, bypassing legacy wholesaler networks in Riyadh and Jeddah metropolitan zones.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Saudi Arabia's rigid plastic packaging market reads as a late-cycle quality story where SFDA pharmaceutical-grade certification requirements and barrier-layer technical complexity reward incumbent specialists over commodity converters. Ambient dairy distribution expansion and oxygen-sensitive food segments pull demand toward multilayer coextrusion capability that outpaces vocational training pipeline output.
For Market Incumbents: Anchor defensive positioning through captive SABIC resin offtake agreements and redundant pharmaceutical-grade quality infrastructure that emerging entrants cannot replicate within contract award windows. Deepen backward integration into barrier-layer EVOH coextrusion technology to capture margin expansion from oxygen-scavenging dairy and ready-meal specifications. Counter retail buyer consolidation pressure by qualifying as direct supplier to Lulu, Carrefour, and Tamimi centralized procurement functions. For New Entrants and Emerging Players: Digital inkjet direct-to-shape decoration capability offers entry wedge into Jeddah and Riyadh beauty brand pilot programs for lot-size-one cosmetic packaging customization. Target underpenetrated Eastern Province dairy processing clusters in Al-Ahsa and Dammam with barrier-modified polypropylene tub specifications previously concentrated in Riyadh supply bases. Pursue equipment-upgrade partnerships with regional blow-molders seeking oxygen-scavenging EVOH migration from bottles to deli containers and ready-meal trays. For Investors and Strategic Acquirers: Petrochemical-integrated converters with captive resin supply are the most active acquirer in this space, consolidating independent fabricators to secure volume-commitment pricing with retail chains. Long-term viability hinges on chemical recycling infrastructure scale-up outpacing mechanical recycling yield limits that cap post-consumer content ratios. Monitor SASO extended producer responsibility framework implementation timelines as inflection indicator for circular economy investment requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Barrier-Layer Coextrusion Capacity Expansion | Captures premium margins from SFDA pharmaceutical-grade and oxygen-sensitive food specifications. |
| Chemical Recycling Partnership Formation | Secures post-consumer feedstock supply as SASO circularity mandates tighten mechanical recycling constraints. |
| Direct Retail Channel Qualification | Bypasses distributor margin extraction under Lulu, Carrefour, and Tamimi centralized procurement consolidation. |
| Digital Inkjet Decoration Integration | Enables lot-size-one customization for Jeddah and Riyadh beauty brand promotional campaigns. |
| Eastern Province Geographic Expansion | Addresses underpenetrated Al-Ahsa and Dammam dairy clusters with barrier-modified container supply. |
Research Methodology
Bottom-up food and beverage processor demand modeling reconciled against top-down SABIC resin supply tracking forms the analytical core of this study. Primary interviews with blow-molding plant managers, dairy procurement leads, SFDA regulatory affairs specialists, retail category buyers, and pharmaceutical packaging engineers combined with secondary validation from SASO technical specifications, SFDA polymer migration protocols, customs trade data, and petrochemical feedstock pricing indices. Triangulation across converter capacity surveys and end-use consumption estimates ensures statistical integrity.
Input-output matrix framing connects resin feedstock availability through conversion capacity utilization to end-use segment absorption across the projection horizon. Segmentation dimensions modeled include product type, material grade, application vertical, and distribution channel, with regional production hub clustering as an additional industry-specific dimension. CAGRs derive from fitted growth curves applied to base-year volume estimates, incorporating ethylene feedstock cost trajectories and retail channel mix evolution as key forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to chemical recycling infrastructure deployment rates and SFDA extended producer responsibility framework finalization. Practitioners should monitor SABIC resin pricing volatility, multilayer coextrusion technician training pipeline expansion, and retail buyer consolidation pace for early signals of forecast revision triggers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rigid Packaging
Nutraceutical Rigid Packaging Market
Rigid Packaging
North America Airless Packaging Market
Rigid Packaging
Global Rigid Bulk Packaging Market
Rigid Packaging
Reclosable Rigid Containers Market
Rigid Packaging
Rigid Food Containers Market
Rigid Packaging
Asia-Pacific Rigid Bulk Packaging Market
Rigid Packaging
Collapsible Rigid Containers Market
Rigid Packaging
Europe Rigid Bulk Packaging Market
Rigid Packaging
Europe Rigid Plastic Packaging Market
Rigid Packaging
Canada Rigid Plastic Packaging Market
Rigid Packaging
Rigid Food Packaging Market
Rigid Packaging
Global Rigid Paper Containers Market
Rigid Packaging
Mexico Rigid Plastic Packaging Market
Rigid Packaging
Mono-Material Trays Market
Rigid Packaging
APAC Rigid Plastic Packaging Market
Rigid Packaging
Middle East and Africa Rigid Plastic Packaging Market