
 GCC Packaging Market | 2026-2036
GCC Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Packaging Market Insights
The gap between premium branded packaging and commodity-grade supply is shifting from a price divide into a capability divide. Tetra Pak International SA leverages its aseptic technology platform to command positions in dairy and juice segments across Saudi Arabia and the UAE. Mondi plc anchors its regional presence through kraft paper and containerboard solutions tailored to corrugated demand from e-commerce fulfillment centers. Hotpack Packaging Industries LLC dominates the foodservice disposables segment, competing on scale and proximity to Gulf hospitality and quick-service restaurant chains.
GCC packaging encompasses the design, manufacture, and supply of containment, protection, handling, and distribution materials ranging from multilayer polymer films to molded fiber and metal closures, with specifications governed by barrier properties, tensile strength, and migration limits for food contact. Flexible packaging leads volume in snack foods and personal care due to lightweighting advantages and printability on rotogravure and flexographic lines, while rigid plastic containers capture margin pools in pharmaceutical and chemical applications where child-resistance and tamper-evidence standards apply. Paperboard growth accelerates in retail-ready formats as supermarket chains across the Gulf adopt shelf-efficient merchandising standards.
Saudi Standards, Metrology and Quality Organization (SASO) technical regulations and UAE Ministry of Industry and Advanced Technology (MoIAT) conformity schemes shape material compliance pathways for imported and locally produced packaging. Gulf Cooperation Council-wide alignment on extended producer responsibility frameworks is emerging, with draft regulations expected to mandate post-consumer recycled content thresholds and labeling protocols. Stakeholders must monitor how harmonization between national standards bodies and customs authorities affects product registration timelines and raw material sourcing flexibility.
Market Dynamics
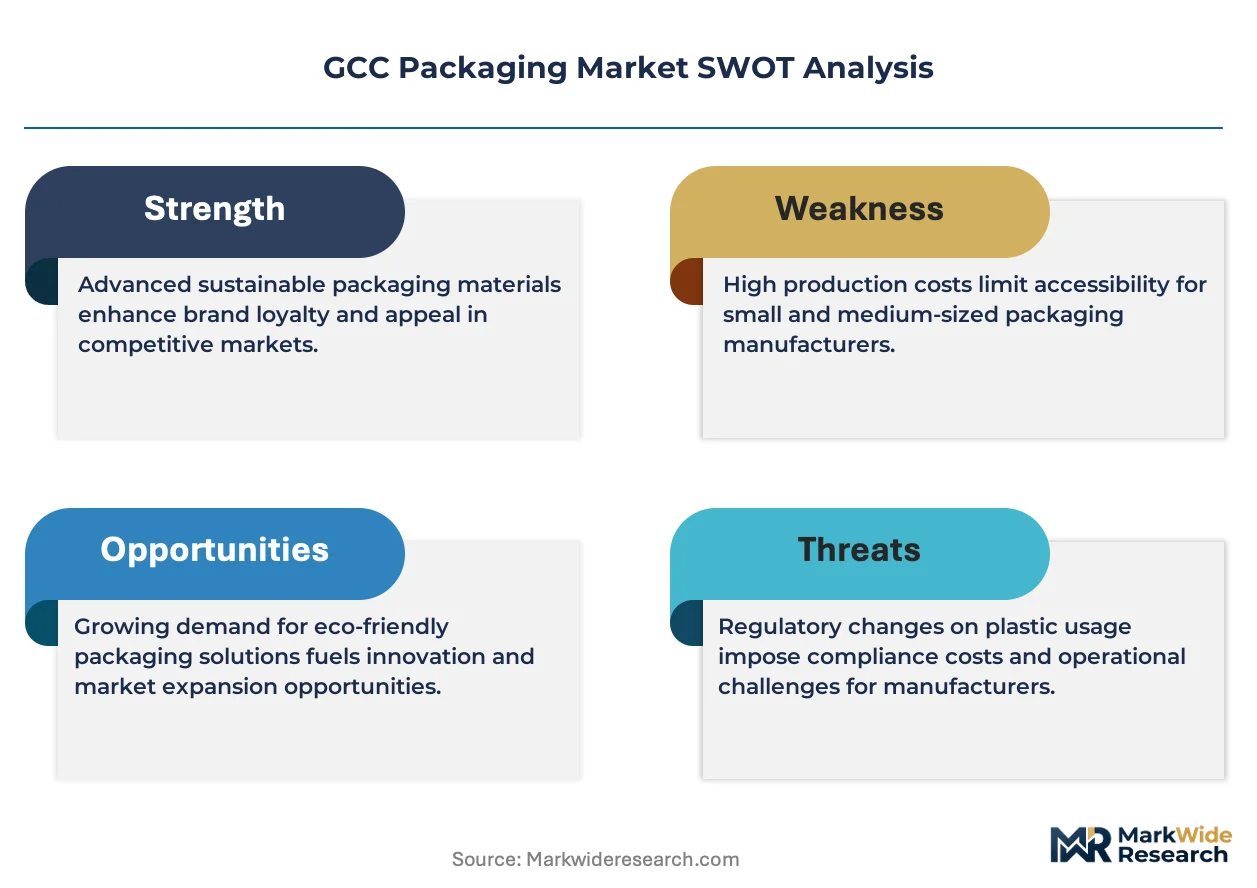
SASO technical regulations on plastic packaging recyclability are compelling converters across the Gulf to reformulate material compositions and revalidate supply chains, creating a compliance-driven restructuring of procurement priorities and converter capabilities.
Growth Catalysts
- Extended Producer Responsibility frameworks:Draft GCC-wide regulations mandating post-consumer recycled content thresholds are accelerating investment in closed-loop collection infrastructure and mechanical recycling capacity.
- E-commerce fulfillment expansion:Corrugated demand from UAE and Saudi Arabian distribution centers is pulling containerboard volumes and driving automated converting line installations.
- Aseptic technology adoption:Dairy and juice processors are migrating from chilled distribution to shelf-stable formats, expanding addressable market radius for perishable goods.
Market Restraints
- Polymer feedstock volatility:GCC converters remain exposed to naphtha and natural gas liquid pricing swings that compress margin predictability on multilayer film contracts.
- Masterbatch supply concentration:Colorant and additive sourcing concentrates among European and Asian specialty chemical suppliers, creating single-source vulnerability for custom formulations.
- Technical limitation in barrier films:Oxygen and moisture protection in mono-material structures remains below multilayer performance thresholds, constraining recyclability claims in sensitive food applications.
Strategic Opportunities
- Bahrain packaging free zone development:Underutilized industrial land and port proximity create cost arbitrage for converters serving Saudi Arabian and Kuwaiti markets with shorter lead times.
- Pharmaceutical serialization mandates:Track-and-trace requirements for drug packaging are opening specialized contract packaging services for biologics and temperature-sensitive therapies.
- Paper-film hybrid structures:Fiber-based substrates laminated with thin polymer barriers are converging sustainability positioning with functional performance in snack and confectionery segments.
Industry Challenges
- Rotogravure cylinder lead times:Skilled engraving technician shortages in the Gulf are extending pre-production schedules for high-volume flexible packaging runs.
- Legacy ERP integration:Converter migration to materials traceability systems required for SASO compliance is encountering data architecture conflicts with decade-old inventory platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Packaging Market |
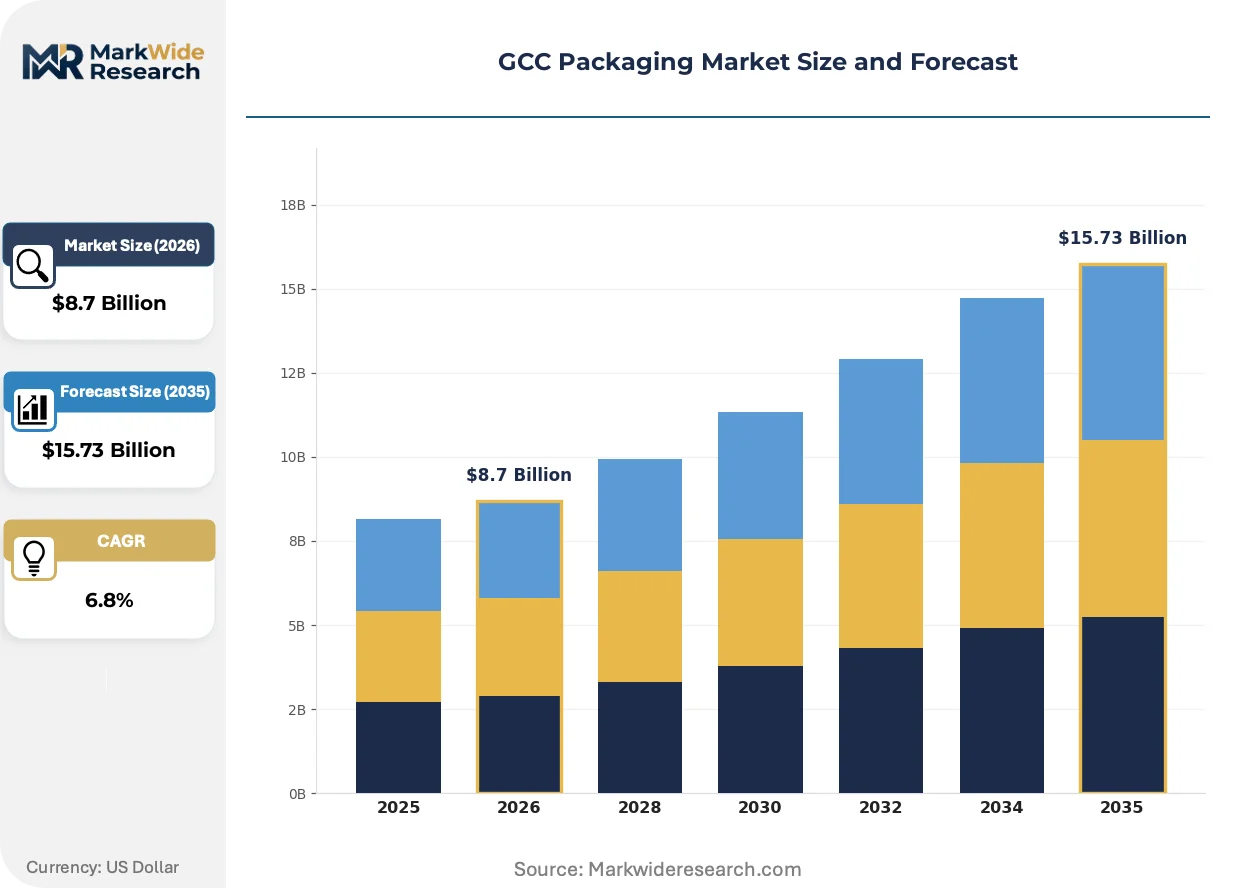
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Flexible Packaging, Rigid Packaging, Paperboard, Glass Packaging Material: Plastic, Metal, Glass, Paper, Others Application: Food & Beverage, Pharmaceuticals, Cosmetics, Electronics End User: Consumer Goods, Healthcare, Industrial, Retail |
| Companies Covered | Tetra Pak International SA, Mondi plc, AptarGroup Inc., Arabian Packaging LLC, Huhtamaki Oyj, Napco National, Najmuddin Packaging and Refilling Industry LLC, Hotpack Packaging Industries LLC, Integrated Plastics Packaging LLC, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Packaging Market Trends and Innovations
Active and intelligent packaging functionalities are migrating from premium positioning to baseline specifications, while regulatory pressure on polymer circularity is forcing material science reinvention across the value chain.
High-barrier mono-material polyethylene structures are rewriting the technical-economic tradeoff between recyclability and shelf-life extension. Saudi Arabian dairy processors are qualifying these films at commercial scale for UHT milk pouches. The shift is compressing demand for ethylene vinyl alcohol copolymer layers and forcing resin suppliers to reformulate sealant additives.
UAE Ministry of Industry and Advanced Technology conformity schemes are tightening documentation requirements for imported packaging materials. Industrial consequence includes extended product registration timelines and pre-shipment testing costs for Asian converters. Food contact migration testing is now the primary bottleneck for new supplier qualification in Dubai Industrial City.
Quick-service restaurant chains are consolidating procurement through centralized category management, displacing fragmented distributor relationships. Regional hospitality groups are mandating certified compostable disposables across outlet networks. Oman and Qatar represent the most visible geographies for this contract restructuring, with specification authority shifting from franchise operators to master franchise headquarters.
GCC Packaging Market Segmentation
Material specifications and barrier performance requirements fragment the GCC packaging landscape into distinct procurement categories. Converters must align production capabilities with end-use migration limits, mechanical stress tolerances, and recyclability mandates across Saudi Arabia, UAE, and neighboring markets.
Product Type:
Technical barriers and shelf-life extension requirements determine format selection across dairy, snack, and pharmaceutical applications.
- Flexible Packaging:Multilayer polymer films and pouches deliver oxygen transmission rates below 0.5 cc/m²/day for UHT milk distribution in Saudi Arabia. Rotogravure printability at 8-color depth supports premium branding for regional confectionery exporters.
- Rigid Packaging:Injection-molded HDPE and PET containers provide child-resistance closures for pharmaceutical serialization mandates in Dubai. The format captures margin pools where tamper-evidence and dimensional stability are non-negotiable.
- Paperboard:Folding cartons and retail-ready trays accelerate in UAE supermarket chains adopting shelf-efficient merchandising standards.
- Glass Packaging:Amber and flint glass bottles retain share in premium cosmetics and traditional food preserves where inertness and reusability signal quality.
Mature deployment sits with Rigid Packaging in pharmaceutical supply chains. Newer deployment is concentrated in Flexible Packaging as dairy processors convert from chilled to shelf-stable distribution.
Material:
Feedstock availability and SASO recyclability regulations are restructuring procurement priorities for converters across the Gulf.
- Plastic:Polyethylene and polypropylene formulations dominate volume, with mechanical recycling compatibility now a baseline specification. High-barrier mono-material structures are displacing ethylene vinyl alcohol laminates in Saudi dairy applications.
- Paper:Kraft linerboard and containerboard pull demand from UAE e-commerce fulfillment centers installing automated converting lines. Virgin fiber sourcing concentrates among Nordic and Latin American suppliers.
- Metal:Aluminum cans and steel closures retain beverage and aerosol applications where pressure resistance and infinite recyclability meet brand sustainability commitments.
- Glass:Silica-based packaging localizes production near Saudi Arabian and UAE glassworks to minimize transport costs on heavy, low-value-density shipments.
- Others:Molded fiber and bio-based polymers qualify for hospitality sector compostable mandates in Oman and Qatar.
Plastic commands current volume leadership. Paper is climbing the fastest as retail-ready formats and corrugated e-commerce demand expand.
Application:
Regulatory stringency and product shelf-life requirements create divergent specification standards across end-use sectors.
- Food & Beverage:Aseptic carton and flexible pouch adoption accelerates as processors extend distribution radius for ambient-stable dairy and juice. SASO food contact migration testing is the primary supplier qualification bottleneck.
- Pharmaceuticals:Track-and-trace serialization mandates open specialized contract packaging capacity for biologics and cold-chain therapies. Blister foil and vial containment demand precision barrier calibration.
- Cosmetics:Airless pumps and premium glass bottles support Gulf luxury retail positioning, with refillable formats gaining traction among regional beauty chains.
- Electronics:Anti-static films and molded pulp inserts protect high-value devices during re-export transit through Dubai Industrial City logistics hubs.
Food & Beverage anchors installed converter capacity. Pharmaceuticals is gaining share fastest on serialization investment and biologics growth.
End User:
Procurement centralization and sustainability mandates differentiate customer requirements across downstream sectors.
- Consumer Goods:Quick-service restaurant chains consolidate purchasing through category management, mandating certified compostable disposables across outlet networks in Oman and Qatar.
- Healthcare:Hospital systems and pharmacy chains prioritize tamper-evident and child-resistant formats with full batch traceability for patient safety compliance.
- Industrial:Chemical and lubricant manufacturers specify UN-certified drums and intermediate bulk containers for hazardous material handling across Gulf manufacturing zones.
- Retail:Supermarket operators drive retail-ready packaging specifications to minimize shelf-stocking labor and maximize linear meter productivity.
Consumer Goods represents the most fragmented procurement landscape. Retail is concentrating fastest on centralized sustainability scorecarding.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai Industrial City anchors GCC packaging demand through its co-located multinational and regional producer cluster serving re-export trade across the Gulf and broader Middle East corridor.
Saudi Arabia
UHT milk pouch conversion and aseptic carton qualification are accelerating dairy processor migration to shelf-stable formats. SASO technical regulations on plastic packaging recyclability are compelling converters to reformulate material compositions and revalidate supply chains. Jeddah's industrial corridor concentrates flexible film extrusion capacity serving domestic food manufacturers and Red Sea export routes.
United Arab Emirates
E-commerce fulfillment center expansion is pulling containerboard volumes and driving automated converting line installations in Dubai and Abu Dhabi. MoIAT conformity schemes are tightening documentation requirements for imported packaging materials and extending product registration timelines. Dubai Industrial City hosts the region's densest packaging cluster where multinational producers co-locate with regional converters.
Kuwait
Quick-service restaurant chain procurement consolidation is mandating certified compostable disposables across outlet networks. The country's national standards body is aligning with emerging GCC-wide extended producer responsibility frameworks. Shuwaikh Industrial Area concentrates foodservice packaging conversion serving domestic hospitality and cross-border trade into Iraq.
Qatar
Hospitality sector sustainability scorecarding is displacing fragmented distributor relationships with centralized category management. Draft regulations on post-consumer recycled content thresholds are accelerating supplier qualification bottlenecks. Doha's Mesaieed Industrial City hosts integrated polymer and packaging operations serving domestic consumption and event-driven demand spikes.
Oman
Retail-ready format adoption is expanding as supermarket chains implement shelf-efficient merchandising standards. The country's industrial free zone development is creating cost arbitrage for converters serving Saudi Arabian markets with shorter lead times. Sohar Port and Freezone concentrates imported substrate warehousing and secondary converting operations.
GCC Packaging Market Competitive Landscape
Premium-margin players sit above commodity-margin players across barrier technology and compliance certification dimensions. The vendor base organizes into three tiers: multinational technology licensors with proprietary aseptic platforms, regional scale converters with Gulf-wide distribution networks, and specialty fabricators serving single-country hospitality or pharmaceutical niches. Consolidation pressure intensifies as SASO compliance costs favor integrated operations with in-house testing laboratories. Capacity expansion and strategic partnerships represent the dominant competitive vectors as players secure substrate supply and regional logistics coverage.
Within the multinational technology tier, Tetra Pak International SA exemplifies premium positioning through aseptic platform control, while Mondi plc anchors regional containerboard and kraft paper supply. Hotpack Packaging Industries LLC occupies a dominant position in foodservice disposables competing on proximity to Gulf hospitality chains.
| Leading Market Players |
|---|
| Tetra Pak International SA |
| Mondi plc |
| AptarGroup Inc. |
| Arabian Packaging LLC |
| Huhtamaki Oyj |
| Napco National |
| Najmuddin Packaging and Refilling Industry LLC |
| Hotpack Packaging Industries LLC |
| Integrated Plastics Packaging LLC |
| Others |
Pricing and Supply Chain Analysis
SASO-mandated recyclability reformulation is forcing converters to requalify material compositions and absorb pre-shipment testing costs, compressing margins on legacy multilayer film contracts while creating premium capture opportunities for mono-material barrier innovators.
Pricing Analysis
Barrier performance guarantees anchor value-based pricing in UHT dairy and pharmaceutical applications, where oxygen transmission rates below 0.5 cc/m²/day command contract premiums. Three-tier pricing structure across premium, standard, and economy levels separates aseptic technology licensors from regional scale converters and commodity-grade suppliers. Cost compression in flexible film segments is intensifying because ethylene vinyl alcohol copolymer displacement requires sealant additive reformulation. Quick-service restaurant chains exhibit highest price sensitivity due to centralized category management, while pharmaceutical serialization mandates render healthcare buyers least sensitive.
Supply Chain Analysis
Dual-sourcing requirements for masterbatch colorants and additives are compelling converters to qualify European and Asian specialty chemical suppliers simultaneously, extending procurement timelines. Raw material dependencies center on naphtha and natural gas liquid feedstocks from Saudi Arabia and Qatar, virgin kraft fiber from Nordic and Latin American pulp suppliers, and aluminum coil from GCC smelters. Single-source vulnerability concentrates in custom formulation masterbatches. Distribution runs through Dubai Industrial City warehousing clusters serving re-export trade across the Gulf corridor.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mechanical recycling capacity bottlenecks across the Gulf are propping pricing for post-consumer recycled content-compliant substrates, creating supply-constrained conditions favoring integrated converters with in-house collection infrastructure.
For Market Incumbents: To counter polymer feedstock volatility, backward integration into captive resin compounding operations in Saudi Arabia's Jubail industrial corridor secures margin predictability. Certification investment in SASO-recognized testing laboratories accelerates supplier qualification timelines and locks out smaller competitors. For New Entrants and Emerging Players: The mid-tier price-point gap between Tetra Pak's aseptic platforms and commodity flexible converters opens white-space targeting of Bahrain's packaging free zone for Saudi Arabian market access with shortened lead times. Compostable foodservice disposables for Oman and Qatar hospitality chains offer the most penetrable segment, with go-to-market execution through master franchise headquarters procurement consolidation. For Investors and Strategic Acquirers: The window for entry favors regional scale converters with Gulf-wide distribution networks and existing MoIAT conformity scheme documentation. Long-term viability hinges on mechanical recycling infrastructure ownership. Watch for draft GCC extended producer responsibility framework finalization as the inflection signal triggering mandatory post-consumer recycled content threshold compliance investments.| Strategic Initiative | Industry Significance |
|---|---|
| Mechanical Recycling Capacity Expansion | Closed-loop collection infrastructure in Saudi Arabia secures SASO-compliant feedstock supply. |
| Aseptic Technology Platform Licensing | Dairy processor migration to shelf-stable formats extends Tetra Pak's addressable market radius. |
| Backward Integration into Resin Compounding | Jubail-based captive compounding insulates margins from naphtha pricing volatility. |
| MoIAT Conformity Scheme Pre-Certification | Dubai Industrial City registration acceleration captures re-export trade flow consolidation. |
| Compostable Disposables Manufacturing Scale-Up | Oman and Qatar hospitality sector mandates displace fragmented distributor relationships. |
Research Methodology
Document review covered SASO technical regulations, MoIAT conformity scheme documentation, and GCC customs trade data, complemented by interviews with flexible film extrusion plant managers, pharmaceutical packaging procurement leads, quick-service restaurant category buyers, and hospitality supply chain directors. Secondary validation drew from SEC filings of listed packaging multinationals, Dubai Industrial City tenant directories, and UN Comtrade import statistics. Bottom-up converter capacity estimates triangulated against top-down end-use demand projections.
Historical volume trajectories cross-referenced against expert panel input on SASO compliance timelines and aseptic adoption curves shaped the analytical framework across the analysis window. Segmentation dimensions modeled include material type, product format, application sector, and Gulf country regulatory cluster. CAGRs derived from elasticity-adjusted demand projections incorporating e-commerce fulfillment center expansion rates and dairy processor format conversion schedules.
Underlying measurement precision varies by segment; rigid pharmaceutical packaging carries tighter precision than fragmented foodservice disposables due to serialization mandate documentation density. Forecasts reflect assumptions on GCC regulatory harmonization pace and mechanical recycling capacity commissioning timelines. Deviation in SASO enforcement intensity or polymer feedstock price volatility would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rigid Packaging
Poland Rigid Plastic Packaging Market
Rigid Packaging
Rigid Boxes Market
Rigid Packaging
Rigid Plastic Packaging Market
Rigid Packaging
Asia-Pacific Rigid Bulk Packaging Market
Rigid Packaging
Rigid Industrial Packaging Market
Rigid Packaging
Italy Rigid Plastic Packaging Market
Rigid Packaging
Rigid Trays Market
Rigid Packaging
Indonesia Rigid Plastic Packaging Market
Rigid Packaging
Rigid Food Packaging Market
Rigid Packaging
Reclosable Rigid Containers Market
Rigid Packaging
APAC Rigid Plastic Packaging Market
Rigid Packaging
Latin America Rigid Bulk Packaging Market
Rigid Packaging
Colombia Rigid Plastic Packaging Market
Rigid Packaging
United Kingdom Rigid Plastic Packaging Market
Rigid Packaging
Rigid Packaging Containers Market
Rigid Packaging
Rigid Food Containers Market