
 Europe Rigid Plastic Packaging Market | 2026-2036
Europe Rigid Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Rigid Plastic Packaging Market Insights
The EU Green Deal is repositioning procurement criteria across European rigid plastic packaging, compelling converters to demonstrate recycled content thresholds and carbon footprint transparency. ALPLA Group leverages its in-house recycling infrastructure to secure long-term supply agreements with beverage multinationals. Greiner Packaging International GmbH anchors its competitive stance through specialized pharmaceutical-grade barrier technologies. PACCOR Packaging GmbH differentiates via lightweighting R&D programs that reduce resin intensity without compromising stack strength.
Rigid plastic packaging denotes formed polymer structures—typically blow-molded, injection-molded, or thermoformed—that retain shape under load and protect contents from mechanical damage, moisture ingress, and gas permeation. These containers commonly achieve wall thicknesses of 0.5–2.0 mm and incorporate mono- or multi-layer constructions with EVOH or PA barrier layers for oxygen-sensitive products. PET bottles command the largest volume share within the product type dimension, sustained by deposit-return scheme expansions in Germany and Scandinavia. Polypropylene containers represent the fastest-growing material category, driven by hot-fill dairy and ready-meal applications that exploit PP's thermal resistance up to 120°C. Pharmaceutical end users concentrate margin pools around serialization-compliant jars and tubs with tamper-evident closures.
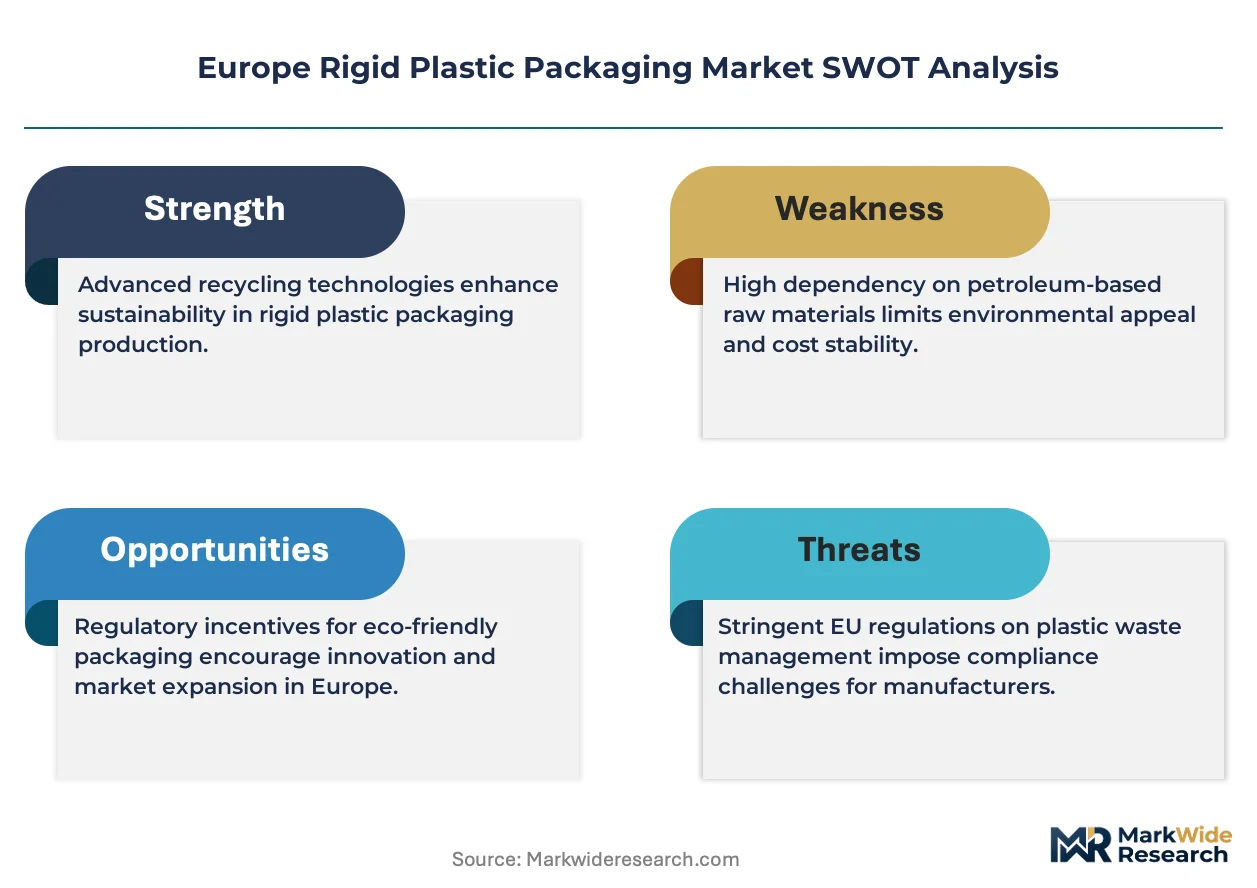
REACH and the EU Packaging and Packaging Waste Regulation shape material compliance obligations, while EFSA standards govern food-contact safety approvals that gate market access. ECHA substance restrictions on intentionally added microplastics are forcing reformulation of certain additive packages. Stakeholders must monitor PPWR implementation timelines and recycled content mandate phase-ins to calibrate capital deployment between mechanical recycling upgrades and chemical recycling pilot investments.
Market Dynamics
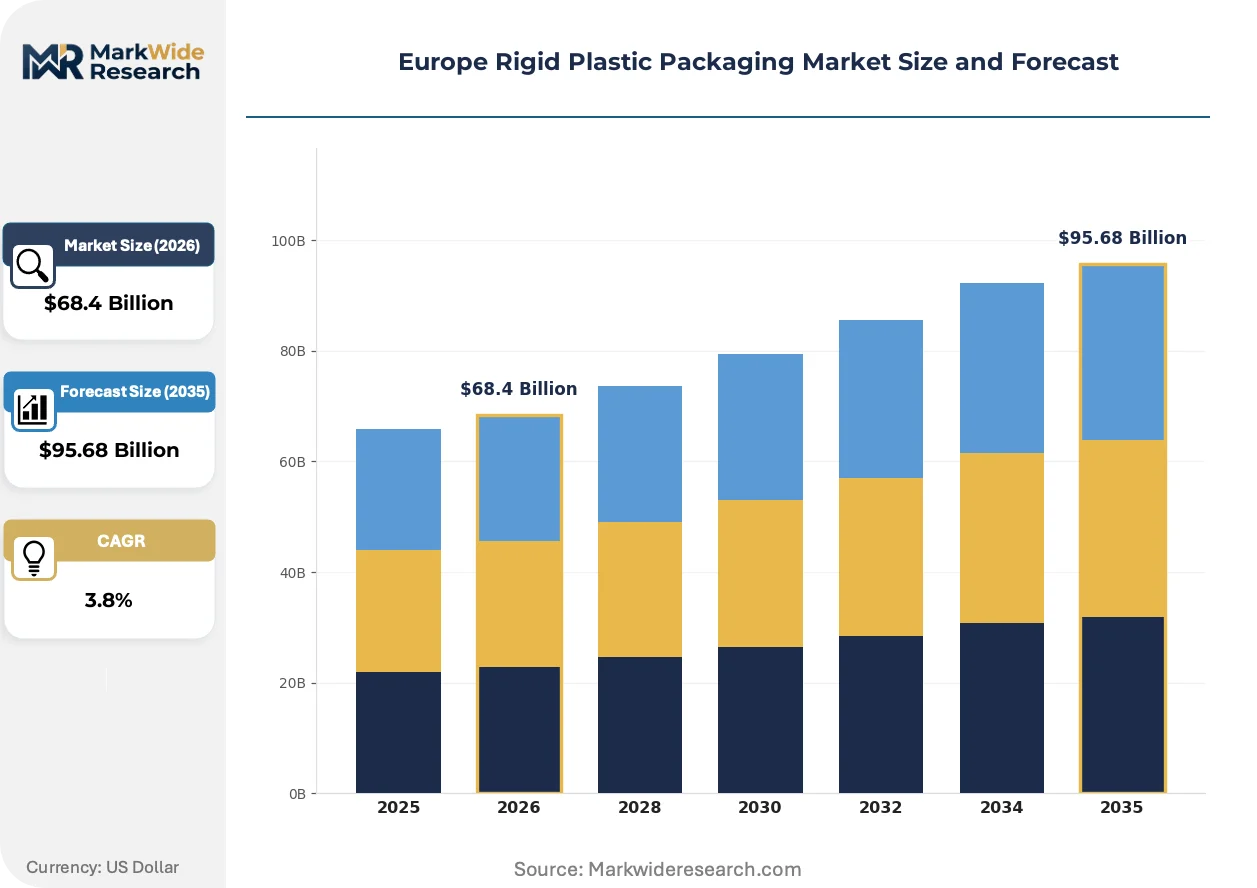
The EU Packaging and Packaging Waste Regulation is forcing converters to reengineer material specifications and recycling infrastructure ahead of phased recycled content mandates, compressing decision timelines for capital allocation between mechanical and chemical recycling pathways.
Growth Catalysts
- Deposit-return scheme expansion:Germany and Scandinavia have extended container deposit systems to cover rigid PP tubs and dairy pots, pulling additional resin volumes into closed-loop recovery systems and stabilizing post-consumer feedstock availability for converters.
- Pharmaceutical cold-chain tightening:EMA serialization requirements and temperature-controlled distribution protocols are driving specification upgrades to multi-layer barrier jars with integrated tamper-evidence, expanding addressable margins in healthcare packaging.
- EVOH barrier layer adoption:Oxygen-sensitive food applications including plant-based proteins and premium ready-meals are specifying ethylene vinyl alcohol coextrusions that extend shelf life and enable distribution radius expansion for processors.
Market Restraints
- rPET feedstock cost volatility:Deposit-return scheme competition between bottle-to-bottle and sheet applications has tightened food-grade flake availability, squeezing converter margins when virgin PET pricing diverges from recycled parity.
- Mechanical recycling yield ceilings:Sorting technology limitations and polymer degradation through reprocessing cycles cap food-contact recycled content at levels below upcoming PPWR mandates, forcing premature chemical recycling capital deployment.
- Paper-fiber substitution in secondary packaging:E-commerce shippers and retail-ready displays are shifting to molded fiber and corrugated alternatives for non-barrier applications, eroding historical HDPE and PP volume anchors in logistics packaging.
Strategic Opportunities
- Central European converter consolidation:Poland and Czechia host fragmented mid-cap blow-molding assets with limited recycling integration, creating acquisition targets for groups seeking geographic diversification beyond German wage and energy cost structures.
- Digital watermark integration:HolyGrail 2.0 pilot programs in France and Denmark are demonstrating AI-sorting compatibility for invisible marker technologies that could unlock food-contact mechanical recycling streams currently rejected by NIR sorting limitations.
- Pharmaceutical serialization-as-a-service:Contract packaging organizations with integrated track-and-trace infrastructure can capture value from mid-tier drug manufacturers seeking to outsource EU Falsified Medicines Directive compliance without dedicated line investments.
Industry Challenges
- Polymer chemist talent scarcity:Formulation expertise for compatibilizing mixed-polymer streams and stabilizing recycled-content blends is concentrating at large integrated groups, constraining independent converter R&D bandwidth.
- EFSA food-contact notification timelines:Novel recycling process approvals and additive migrations studies are extending time-to-market for sustainable packaging innovations beyond product launch windows demanded by brand owner sustainability commitments.
- Legacy injection tooling retrofit costs:Converters with installed base of single-material molds face capital-intensive upgrades to accommodate multi-layer or recycled-content specifications with modified shrinkage and processing parameters.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Rigid Plastic Packaging Market |
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $95.68 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Containers, Jars, Tubs Material: Polyethylene, Polypropylene, PVC, PET End User: Food, Beverages, Personal Care, Pharmaceuticals Packaging Type: Box, Crate, Pallet, Tray |
| Companies Covered | Schoeller Allibert Services B.V., Plastipak Holdings Inc., ALPLA Group, PACCOR Packaging GmbH, Mauser Packaging Solutions Holding Company, Amcor plc, Silgan Holdings Inc., Schutz GmbH & Co. KGaA, Greiner Packaging International GmbH, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Rigid Plastic Packaging Market Trends and Innovations
Lightweighting algorithms and barrier coextrusion advances are compressing resin intensity per functional unit while regulatory pressure on carbon footprint disclosure is transferring specification power from procurement to sustainability functions within brand owner organizations.
Mono-material polypropylene structures with integrated oxygen scavenger additives are absorbing functionality previously delivered by multi-layer PET/EVOH constructions, enabling dairy processors to meet PPWR recyclability targets without sacrificing shelf life. Adoption is accelerating among Scandinavian and Benelux dairy cooperatives with aggressive 2025 circularity commitments. This absorption is compressing demand for specialized barrier resin grades and simplifying post-consumer sorting streams.
REACH restrictions on intentionally added microplastics are forcing reformulation of certain slip agents and anti-fog additives used in food-contact films and rigid containers, compelling compounders to validate bio-based alternatives through EFSA safety assessments. The regulatory friction is most acute in Italian and Spanish fresh produce packaging sectors where optical clarity requirements have historically depended on legacy additive packages now under substance evaluation.
Retailers including French and German hard discounters are consolidating supplier panels and demanding carbon footprint transparency at SKU level, replacing transactional procurement with multi-year partnership frameworks that embed recycled content minimums and annual reduction trajectories. This concentration of buying power is marginalizing smaller converters lacking lifecycle assessment capabilities and verified Scope 3 data, with compliance gaps most visible in Southern European supply bases.
Europe Rigid Plastic Packaging Market Segmentation
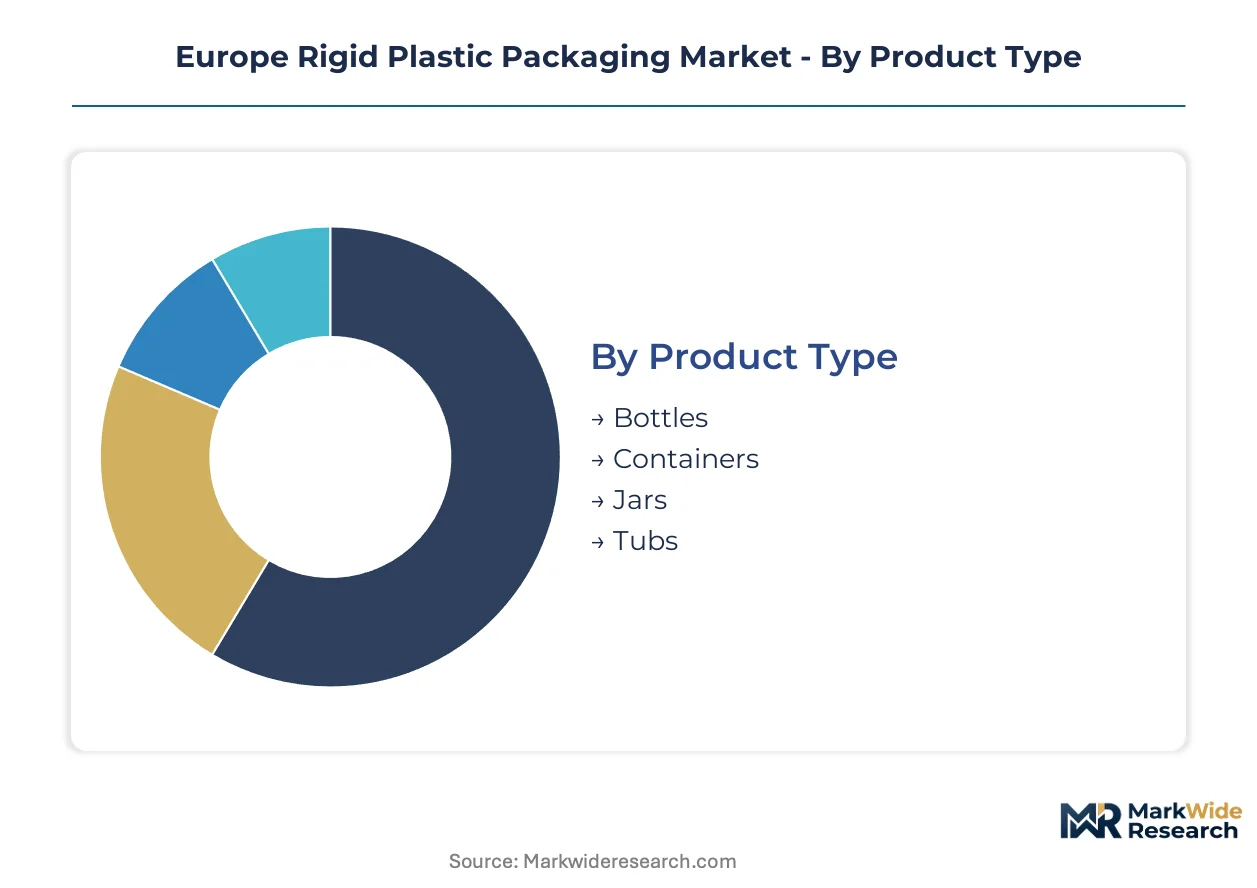
Segmentation in European rigid plastic packaging reveals how regulatory pressure and end-use performance requirements split manufacturing capabilities and margin structures. Material compliance obligations under REACH and the EU Packaging and Packaging Waste Regulation fragment converter specialization across food-contact, pharmaceutical-grade, and industrial logistics applications.
Product Type:
Bottles dominate volume throughput while jars command premium pricing through barrier complexity and closure integration.
- Bottles:Blow-molded structures with 0.5–1.2 mm wall thickness serve carbonated beverages, edible oils, and household chemicals. Deposit-return scheme expansions in Germany and Scandinavia pull PET bottle volumes into closed-loop recovery systems, stabilizing rPET feedstock access for converters with bottle-to-bottle certification.
- Containers:Rectangular or cylindrical injection-molded vessels with integrated handles target institutional food service and chemical distribution. French dairy processors specify PP containers for hot-fill applications exploiting thermal resistance to 120°C, displacing traditional glass in prepared meal logistics.
- Jars:Wide-mouth cylindrical formats with tamper-evident closures serve pharmaceutical serialization requirements and premium food preservation. EMA track-and-trace mandates concentrate demand around Italian and German contract packaging organizations with integrated aggregation infrastructure.
- Tubs:Thin-walled thermoformed or injection-molded vessels for fresh dairy, spreads, and deli products. Scandinavian retailers now include PP tubs in deposit-return systems, diverting resin from energy recovery into mechanical recycling streams.
Today's leader: Bottles. Tomorrow's challenger: Jars.
Material:
Performance temperature thresholds and barrier specifications determine material selection across end-use verticals.
- Polyethylene:HDPE delivers chemical resistance for agrochemical and cleaning product containers. Blow-molding grade demand concentrates in Benelux logistics hubs serving agricultural distribution networks.
- Polypropylene:Homopolymer and random copolymer grades enable hot-fill dairy and ready-meal applications. PP's thermal resistance and emerging mono-material recyclability positioning drive fastest share expansion among Scandinavian dairy cooperatives with circularity commitments.
- PVC:Rigid formulations persist in pharmaceutical blister packs and certain chemical containers where clarity and sterilization compatibility outweigh recyclability concerns. ECHA substance evaluations constrain additive packages in food-contact applications.
- PET:Bottle-grade and sheet-grade resins dominate beverage and fresh produce packaging. Deposit-return infrastructure investments in Germany and Czechia secure food-grade flake supply for converters with EFSA-approved super-cleaning processes.
Polyethylene holds installed base dominance. Polypropylene captures specification momentum through thermal performance and recyclability alignment.
End User:
Regulatory intensity and margin structure vary sharply across consumer-facing versus institutional demand channels.
- Food:Modified atmosphere packaging for meat, cheese, and fresh produce drives multi-layer tray and thermoformed film demand. Italian fresh produce packagers navigate REACH microplastic restrictions on legacy anti-fog additives while maintaining optical clarity specifications.
- Beverages:Carbonated soft drinks, water, and juice segments specify PET bottles with oxygen scavenger technologies or multi-layer EVOH barriers for extended shelf life. German beverage multinationals embed recycled content minimums into multi-year supply agreements.
- Personal Care:Cosmetic jars and dispensers emphasize aesthetic differentiation through color matching and surface finishing. French luxury brands demand carbon footprint transparency at SKU level, filtering supplier access to sustainability-verified converters.
- Pharmaceuticals:Serialization-compliant jars, bottles, and blister packs with integrated tamper-evidence serve EMA distribution requirements. Cold-chain tightening for biologics drives specification upgrades to multi-layer barrier structures with temperature excursion indicators.
Food and Beverages anchor volume throughput. Pharmaceuticals concentrate margin pools through compliance complexity and barrier technology premiums.
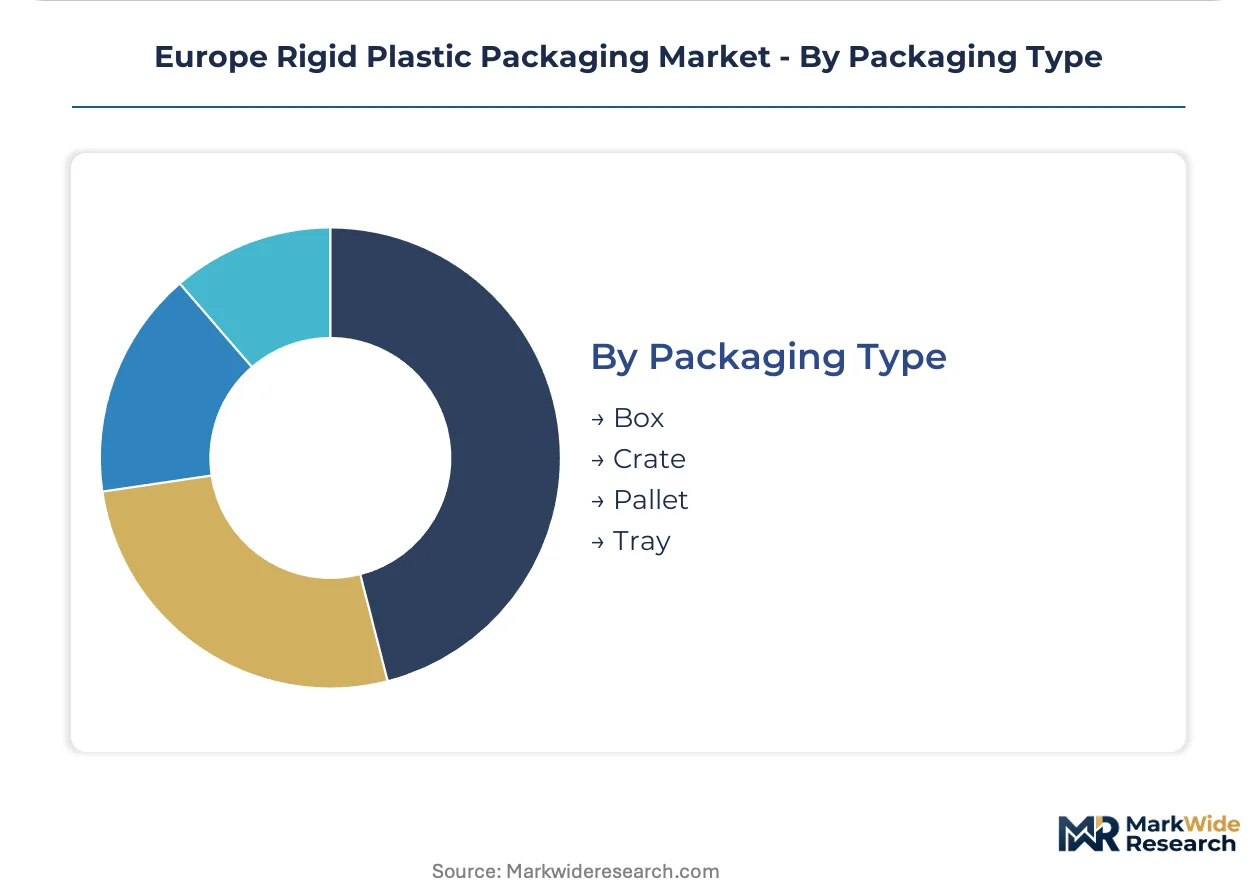
Packaging Type:
Logistics function and load-bearing requirements differentiate structural formats across distribution chain positioning.
- Box:Collapsible HDPE or PP containers for retail distribution and industrial component handling. German automotive suppliers specify returnable box systems with RFID tracking for closed-loop component logistics.
- Crate:Stackable ventilated containers for beverage bottle distribution and fresh produce handling. Deposit-return scheme operators in Denmark and Netherlands manage crate pooling systems with standardized footprint dimensions.
- Pallet:Heavy-duty platforms for unitized load handling in warehousing and transport. Lightweighting R&D programs target resin reduction without compromising rack strength for automated storage systems.
- Tray:Shallow thermoformed or injection-molded platforms for retail-ready meat, produce, and bakery presentation. Retailer consolidation of supplier panels in France and Germany demands carbon footprint disclosure for tray procurement decisions.
Trays dominate consumer-facing visibility. Crates and pallets face substitution pressure from pooled systems and alternative materials in secondary logistics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany pioneered deposit-return infrastructure for rigid plastic packaging in the 1990s, establishing closed-loop recovery systems that now serve as templates for neighboring markets. France and Italy subsequently developed specialized pharmaceutical and food-contact packaging clusters leveraging proximity to brand owner headquarters.
Germany
Deposit-return scheme expansions now cover rigid PP tubs and dairy pots, diverting additional resin volumes into mechanical recycling streams. ECHA substance restrictions on intentionally added microplastics compel reformulation of legacy additive packages. The Rhine-Ruhr industrial corridor hosts blow-molding assets supplying beverage multinationals with bottle-to-bottle certified rPET.
France
EMA serialization requirements for pharmaceutical distribution drive specification upgrades to multi-layer barrier jars with integrated tamper-evidence. Retailer consolidation demands carbon footprint transparency at SKU level, filtering supplier access. The Île-de-France region concentrates contract packaging organizations with integrated track-and-trace infrastructure.
Italy
Fresh produce packagers navigate REACH microplastic restrictions while maintaining optical clarity specifications for retail-ready displays. EFSA food-contact notification timelines extend time-to-market for sustainable innovations. Emilia-Romagna hosts injection-molding specialists serving dairy cooperatives with hot-fill PP containers.
Poland
Fragmented mid-cap blow-molding assets with limited recycling integration create acquisition targets for groups seeking geographic diversification. EU Green Deal procurement criteria reposition material sourcing priorities across the value chain. The Silesian industrial basin concentrates logistics packaging production serving German automotive component distribution.
Netherlands
HolyGrail 2.0 pilot programs demonstrate AI-sorting compatibility for digital watermark technologies that could unlock food-contact mechanical recycling streams. Crate pooling systems with standardized footprint dimensions operate nationwide under deposit-return infrastructure. Rotterdam's port logistics hub facilitates rPET flake import and export for converters with EFSA-approved super-cleaning processes.
Europe Rigid Plastic Packaging Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across divergent margin structures in European rigid plastic packaging. Integrated groups with captive recycling infrastructure capture supply security premiums, while specialized converters focus on barrier technology or pharmaceutical compliance niches. Two strategic archetypes dominate: vertically integrated resin-to-package operators and technology-focused barrier specialists. Consolidation activity concentrates in Central European mid-cap assets, while R&D partnerships target lightweighting algorithms and mono-material recyclability.
Among Austrian-headquartered integrated groups, ALPLA Group exemplifies the resin-to-package archetype through in-house recycling infrastructure securing long-term supply agreements. Greiner Packaging International GmbH, a German GmbH, occupies a position within the barrier technology tier serving pharmaceutical-grade applications. PACCOR Packaging GmbH represents the lightweighting R&D vector, with German corporate structure anchoring its competitive stance in resin reduction programs.
| Leading Market Players |
|---|
| Schoeller Allibert Services B.V. |
| Plastipak Holdings Inc. |
| ALPLA Group |
| PACCOR Packaging GmbH |
| Mauser Packaging Solutions Holding Company |
| Amcor plc |
| Silgan Holdings Inc. |
| Schutz GmbH & Co. KGaA |
| Greiner Packaging International GmbH |
| Others |
Pricing and Supply Chain Analysis
Captive in-house recycling infrastructure anchors both supply security and pricing power for integrated converters serving German beverage multinationals, while fragmented mid-cap competitors in Poland and Czechia face margin compression from feedstock volatility and limited backward integration into post-consumer flake supply.
Pricing Analysis
Contract-based long-term offtake agreements with recycled content minimums dominate procurement between converters and brand owners, with pricing stratifying across premium, standard, and economy tiers based on EFSA food-contact certification grade and volume scale commitments. Cost compression in standard-grade rPET is intensifying because deposit-return scheme competition between bottle-to-bottle and sheet applications has tightened food-grade flake availability. Mid-tier dairy processors demonstrate highest price sensitivity, while pharmaceutical contract packaging organizations with serialization infrastructure exhibit lowest sensitivity due to compliance-driven specification lock-in.
Supply Chain Analysis
Polymer chemist and formulation specialist scarcity in German and Italian manufacturing clusters constrains R&D bandwidth for independent converters attempting to compatibilize mixed-polymer recycled streams. Supply concentration centers on Germany, France, and Italy for pharmaceutical-grade barrier technologies, with Poland and Czechia hosting fragmented blow-molding assets for logistics packaging. Raw material dependencies rest on virgin PET resin from Benelux petrochemical hubs, EVOH barrier resins from Asian suppliers, and post-consumer PP feedstock from Scandinavian deposit-return systems. Single-source vulnerability to ECHA substance restrictions on intentionally added microplastics threatens additive supply continuity. Distribution runs through pooled crate systems in Netherlands and Denmark, direct-to-plant delivery for beverage bottlers, and third-party logistics for retail-ready tray consolidation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in European rigid plastic packaging hinges on lightweighting R&D programs that reduce resin intensity per functional unit and the premium-tier shift toward pharmaceutical serialization-compliant barrier structures with integrated tamper-evidence.
For Market Incumbents: To counter rPET feedstock cost volatility from deposit-return scheme competition, ALPLA Group and integrated peers should deepen backward integration into mechanical recycling infrastructure with EFSA-approved super-cleaning processes, and secure multi-year supply agreements embedding recycled content minimums that lock in volume commitments before PPWR mandate phase-ins tighten further. For New Entrants and Emerging Players: Capture white-space opportunity in Polish and Czechian mid-cap blow-molding assets with limited recycling integration, where EU Green Deal procurement criteria are repositioning material sourcing priorities. Target pharmaceutical serialization-as-a-service for mid-tier drug manufacturers seeking outsourced EU Falsified Medicines Directive compliance without dedicated line investments, leveraging HolyGrail 2.0 digital watermark pilot compatibility as a technical differentiation wedge. For Investors and Strategic Acquirers: Roll-up economics work for fragmented Central European converters because wage and energy cost differentials versus German structures create arbitrage value for groups with recycling integration capabilities. Five-to-ten year viability favors acquiring mid-cap assets with bottle-to-bottle certification pathways and hot-fill PP container specialization serving Scandinavian dairy cooperatives. Watch PPWR implementation timelines and recycled content mandate enforcement as the inflection signal distinguishing mechanical recycling upgrade ROI from premature chemical recycling capital deployment.| Strategic Initiative | Industry Significance |
|---|---|
| Mechanical Recycling Infrastructure Upgrade | EFSA-approved super-cleaning processes unlock food-contact rPET supply for German beverage bottlers. |
| Lightweighting R&D Program | Resin reduction algorithms maintain stack strength for automated storage systems in French retail logistics. |
| Pharmaceutical Serialization Integration | EMA track-and-trace compliance captures margin pools from biologics cold-chain tightening in Italian contract packaging. |
| Digital Watermark Pilot Participation | HolyGrail 2.0 AI-sorting compatibility enables food-contact mechanical recycling streams rejected by NIR limitations. |
| Central European Geographic Expansion | Polish and Czechian mid-cap acquisition targets offer diversification beyond German wage and energy cost structures. |
Research Methodology
Direct dialogue with converter operations directors, brand owner sustainability procurement leads, EFSA regulatory affairs specialists, and pharmaceutical contract packaging executives grounded qualitative insights, validated against EU Packaging and Packaging Waste Regulation implementation documents, ECHA substance restriction evaluations, Cefic plastics industry statistics, and national deposit-return scheme operator disclosures. Bottom-up triangulation across primary interview findings and secondary source validation established segment-level demand estimates.
Bottom-up volume modeling by material grade, product type, end-use vertical, and country-level regulatory cluster intersected with top-down macroeconomic sensitivity testing across the projection horizon. Segmentation dimensions included food-contact versus pharmaceutical-grade compliance tiers, mono-material versus multi-layer barrier constructions, and mechanical versus chemical recycling feedstock pathways. CAGRs were derived from regression analysis of historical resin consumption patterns against regulatory mandate implementation schedules and brand owner circularity commitment trajectories.
PPWR recycled content mandate delays, EFSA food-contact notification timeline extensions, and rPET feedstock availability shocks from deposit-return scheme competition are the dominant revision risks to demand forecasts. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rigid Packaging
North America Rigid Bulk Packaging Market
Rigid Packaging
Australia and New Zealand Rigid Plastic Packaging Market
Rigid Packaging
Rigid Trays Market
Rigid Packaging
Rigid Packaging Containers Market
Rigid Packaging
Colombia Rigid Plastic Packaging Market
Rigid Packaging
India Rigid Plastic Packaging Market
Rigid Packaging
North America Airless Packaging Market
Rigid Packaging
Rigid Transparent Plastic Market
Rigid Packaging
Canada Rigid Plastic Packaging Market
Rigid Packaging
Reclosable Rigid Containers Market
Rigid Packaging
Rigid Food Containers Market
Rigid Packaging
Tray Sleeve Market
Rigid Packaging
GCC Rigid Plastic Packaging Market
Rigid Packaging
Spain Rigid Plastic Packaging Market
Rigid Packaging
North America Rigid Plastic Packaging Market
Rigid Packaging
Mexico Rigid Packaging Market