
 Frozen Seafood Packaging Market | 2026-2036
Frozen Seafood Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Frozen Seafood Packaging Market Foresight
Subscription-based packaging asset management is rebalancing how frozen seafood processors procure materials, shifting capital expenditure into operational contracts. Amcor leverages its global film manufacturing footprint to supply multilayer barrier solutions for North Atlantic whitefish exports. Sealed Air anchors cryogenic packaging automation through its IntelliVue tracking-enabled systems. Berry Global Inc. specializes in thermoformed polystyrene trays calibrated for blast-freezer compatibility.
Frozen seafood packaging comprises engineered barrier systems designed to maintain sub-zero temperature integrity, prevent oxidative rancidity, and control moisture migration during storage and distribution, typically incorporating ethylene-vinyl alcohol copolymers or metallized polyethylene terephthalate layers with specified oxygen transmission rates below 0.5 cc per square meter per day. Vacuum packs dominate high-value species segments where shelf-life extension of twelve to eighteen months justifies premium material costs, while corrugated boxes represent the mature volume layer serving bulk export logistics with thinner margin pools. Biodegradable films are capturing R&D investment as European retail chains impose plastic reduction mandates, though polyethylene retains cost advantages in emerging market foodservice channels.
The EU F-Gas Regulation and REACH framework restrict hydrofluorocarbon use in insulated shipping containers, compelling material suppliers to certify alternative blowing agents for expanded polystyrene. FDA hazard analysis requirements under the Seafood HACCP program mandate lot-traceable packaging substrates for all US-bound shipments, elevating demand for printed bar-code-ready films. Stakeholders must monitor evolving extended producer responsibility schemes in multiple jurisdictions to anticipate redesign obligations and recycling infrastructure investments.
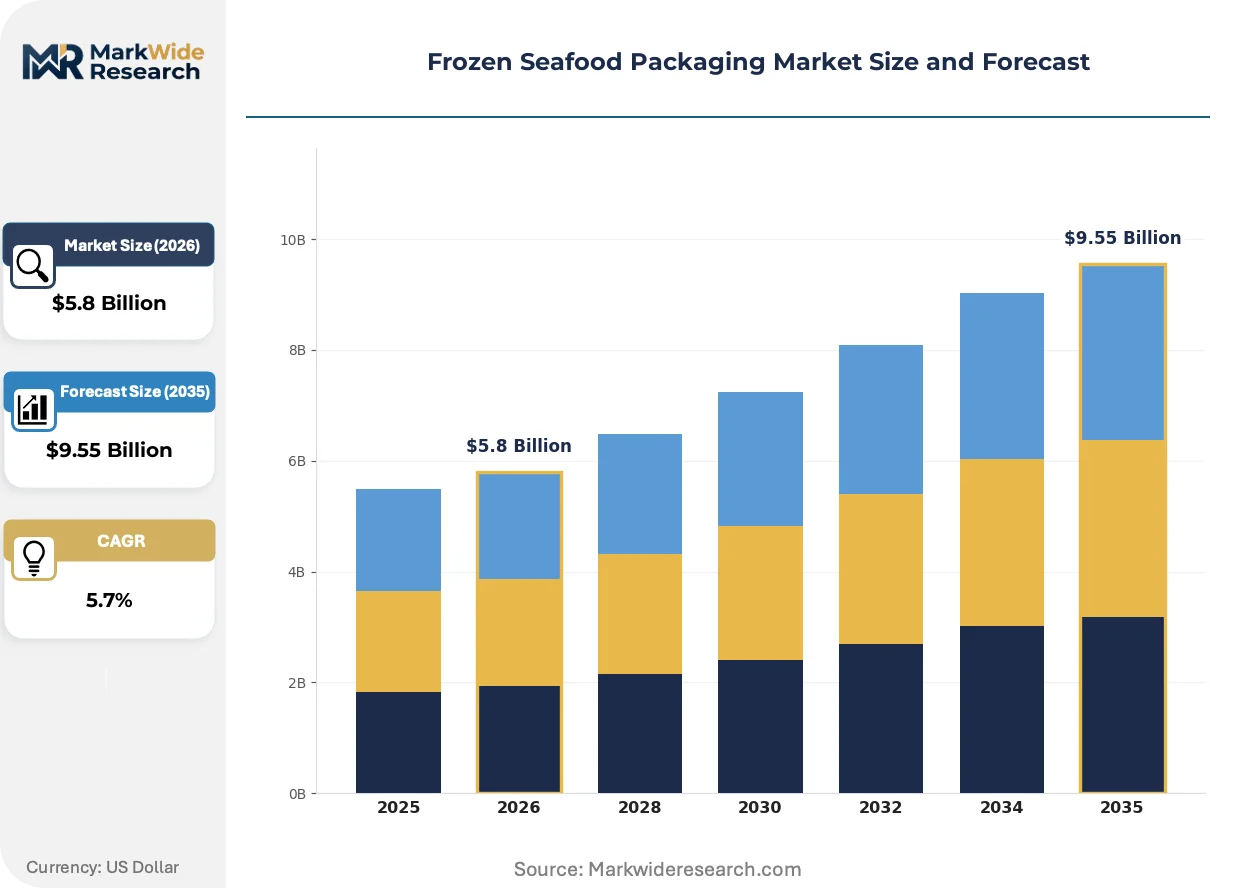
Market Dynamics
The EU F-Gas Regulation and REACH framework are compressing material options for insulated shipping containers, forcing suppliers to certify alternative blowing agents while cold-chain e-commerce standards simultaneously escalate barrier performance requirements.
Growth Catalysts
- EU Green Deal mandates:Retail chains across Germany, France, and the Netherlands are accelerating procurement of biodegradable films to meet plastic reduction targets, creating pull-through demand for certified compostable barrier materials.
- Blast-freezer compatibility standards:Norwegian salmon exporters require thermoformed trays rated to minus forty degrees Celsius, expanding the addressable market for polystyrene alternatives with equivalent thermal shock resistance.
- E-commerce fulfillment protocols:Direct-to-consumer seafood subscription services in the United States demand lot-traceable, bar-code-ready films compliant with FDA Seafood HACCP requirements.
Market Restraints
- Ethylene-vinyl alcohol copolymer supply concentration:Production of EVOH barrier layers clusters in East Asian petrochemical corridors, exposing converters to feedstock volatility and shipping cost spikes.
- Metallized polyethylene terephthalate technical ceiling:Oxygen transmission rates below 0.1 cc per square meter per day remain commercially unachievable without aluminum foil laminates that conflict with microwaveable packaging trends.
- Extended producer responsibility friction:Divergent recycling infrastructure investments across EU member states create compliance fragmentation for multinational packaging suppliers.
Strategic Opportunities
- Underpenetrated Japanese retail channels:Convenience store chains in Tokyo and Osaka lack dedicated frozen seafood sections with premium barrier packaging, representing whitespace for vacuum-packed sashimi-grade products.
- Cryogenic automation convergence:Integration of liquid nitrogen injection systems with RFID-enabled tracking is opening subscription-based asset management contracts for insulated container fleets.
- India FSSAI cold-chain mandates:New regulations for temperature-controlled seafood distribution are creating first-mover advantages for barrier film suppliers establishing local converting partnerships.
Industry Challenges
- Multilayer film delamination expertise:Shortage of polymer scientists capable of optimizing adhesion between EVOH, tie layers, and sealant films is constraining R&D velocity at mid-tier converters.
- Blast-freezer capex intensity:Validating new tray formulations requires capital-intensive testing chambers that smaller packaging firms cannot access without third-party laboratory partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Frozen Seafood Packaging Market |
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $9.55 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Packaging Type: Vacuum Packs, Clamshell Containers, Shrink Wrap, Corrugated Boxes, Foam Trays Material: Polyethylene, Polypropylene, Polystyrene, Biodegradable Films, Aluminum Foil End User: Food Processing Units, Wholesale Distributors, Retail Chains, Foodservice Operators, Exporters Distribution Channel: Supermarkets, Online Retailers, Specialty Stores, Hypermarkets, Convenience Stores |
| Companies Covered | Amcor, Sealed Air, Berry Global Inc., Crown Holdings, DS Smith, Sonoco Products Company, Smurfit Kappa, Huhtamaki Oyj, Winpak Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Frozen Seafood Packaging Market Shifts & Advancements
Active and intelligent packaging systems are penetrating frozen seafood logistics, with sensor-enabled films and automated cold-chain monitoring compressing spoilage windows and redefining liability allocation between processors and distributors.
Smart barrier films incorporating time-temperature indicators and freshness sensors are electrifying supply chain transparency. Norwegian cod exporters are piloting these materials for trans-Atlantic shipments. The technology is compressing insurance premiums and enabling dynamic pricing based on verified cold-chain integrity.
REACH restrictions on hydrofluorocarbon blowing agents are restructuring expanded polystyrene production. ECHA compliance deadlines are forcing insulation manufacturers to reformulate with hydrocarbon or carbon dioxide alternatives. Nordic shipping container suppliers are absorbing certification costs fastest due to aquaculture export dependency.
Subscription-based packaging procurement is displacing spot purchasing among North American whitefish processors. Asset-light contracts for insulated container fleets are replacing capital-intensive owned equipment. This shift concentrates most visibly in Pacific Northwest salmon processing clusters where seasonal volume volatility favors operational flexibility over balance-sheet ownership.
Frozen Seafood Packaging Market Segmentation
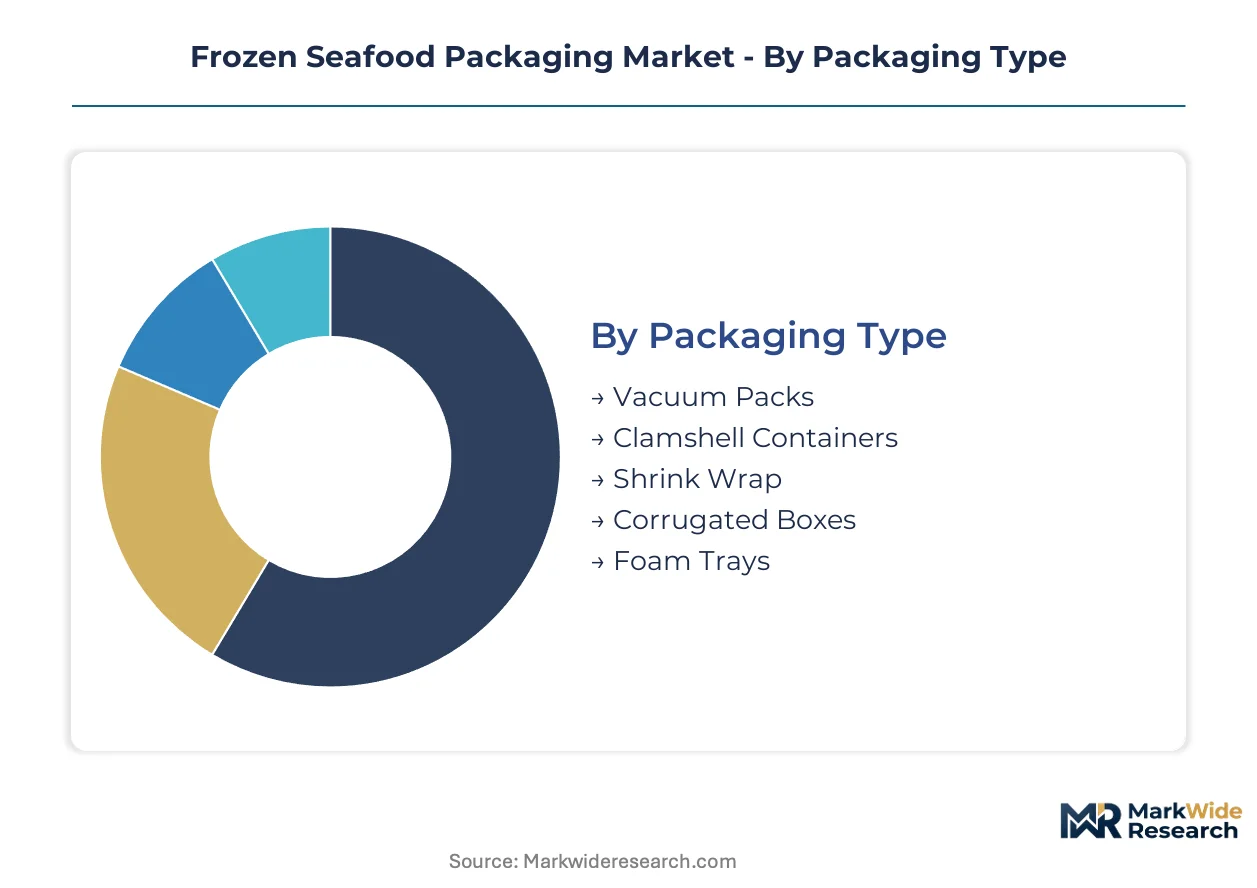
Frozen seafood packaging segments reflect divergent technical requirements across cold-chain touchpoints. Material selection and format design vary sharply between bulk export logistics and direct-to-consumer fulfillment channels.
Packaging Type:
Integration depth varies from standalone primary packaging to embedded secondary systems requiring pallet-level coordination.
- Vacuum Packs:Multilayer barrier films incorporating EVOH copolymers achieve oxygen transmission rates below 0.5 cc per square meter per day. Norwegian salmon processors deploy these for twelve-to-eighteen-month shelf-life extension in trans-Atlantic export corridors.
- Corrugated Boxes:Double-wall fluted structures with moisture-resistant coatings dominate bulk whitefish logistics. Demand concentrates in Pacific Northwest processing clusters serving foodservice distributors with high-volume, thinner-margin procurement protocols.
- Clamshell Containers:Thermoformed PET or PP shells with hinged lids suit retail-ready portion control. German supermarket chains specify these for private-label seafood counters.
- Shrink Wrap:Polyolefin films applied via heat tunnels bundle multi-unit retail packs. Convenience stores in Tokyo favor this format for frozen sashimi-grade tuna portions.
- Foam Trays:Expanded polystyrene platforms with absorbent pads manage drip loss in blast-freezer environments. REACH F-Gas restrictions are forcing hydrocarbon blowing-agent transitions.
Vacuum packs lead volumes today; biodegradable alternatives are gaining share fastest.
Material:
Cost stratification separates commodity polymers from certified compostable barrier films with premium positioning.
- Polyethylene:Linear low-density grades provide seal integrity and puncture resistance at lowest unit cost. Indian foodservice channels under FSSAI cold-chain mandates favor PE for price-sensitive institutional procurement.
- Biodegradable Films:PLA-PHA blends certified to EN 13432 composting standards command three-to-five-x premiums over conventional polymers. EU Green Deal plastic reduction targets in France and the Netherlands are accelerating retail chain adoption.
- Polypropylene:Oriented PP films deliver clarity and moisture barrier for retail display applications. Japanese convenience store chains specify biaxially oriented grades for frozen seafood visibility.
- Polystyrene:High-impact and expanded variants maintain rigidity at minus forty degrees Celsius. Norwegian blast-freezer standards validate thermal shock resistance for salmon export trays.
- Aluminum Foil:Seven-to-nine-micron laminates achieve sub-0.1 cc oxygen transmission for premium species. Microwaveability conflicts constrain growth in ready-meal segments.
Polyethylene dominates installed base; biodegradable films are expanding most quickly.
End User:
Customer type determines order fragmentation, with food processing units demanding bulk formats and retail chains specifying SKU-differentiated packaging.
- Food Processing Units:High-volume procurement of standard corrugated and vacuum formats with minimal customization. Pacific Northwest salmon canneries operate on seasonal volume contracts.
- Retail Chains:Private-label specifications drive clamshell and modified-atmosphere tray demand. German and Dutch supermarket groups impose plastic reduction mandates on suppliers.
- Exporters:FDA Seafood HACCP lot-traceability requirements elevate bar-code-ready film specifications. Norwegian aquaculture volumes dominate trans-Atlantic whitefish shipments.
- Wholesale Distributors:Intermediate handling favors shrink-wrapped bulk packs with pallet-level identification. US foodservice redistribution centers prioritize logistics efficiency over shelf appeal.
- Foodservice Operators:Portion-controlled vacuum packs reduce labor in commercial kitchen environments. Institutional buyers in India favor PE-based economy formats.
Food processing units anchor volume demand; exporters are climbing the fastest.
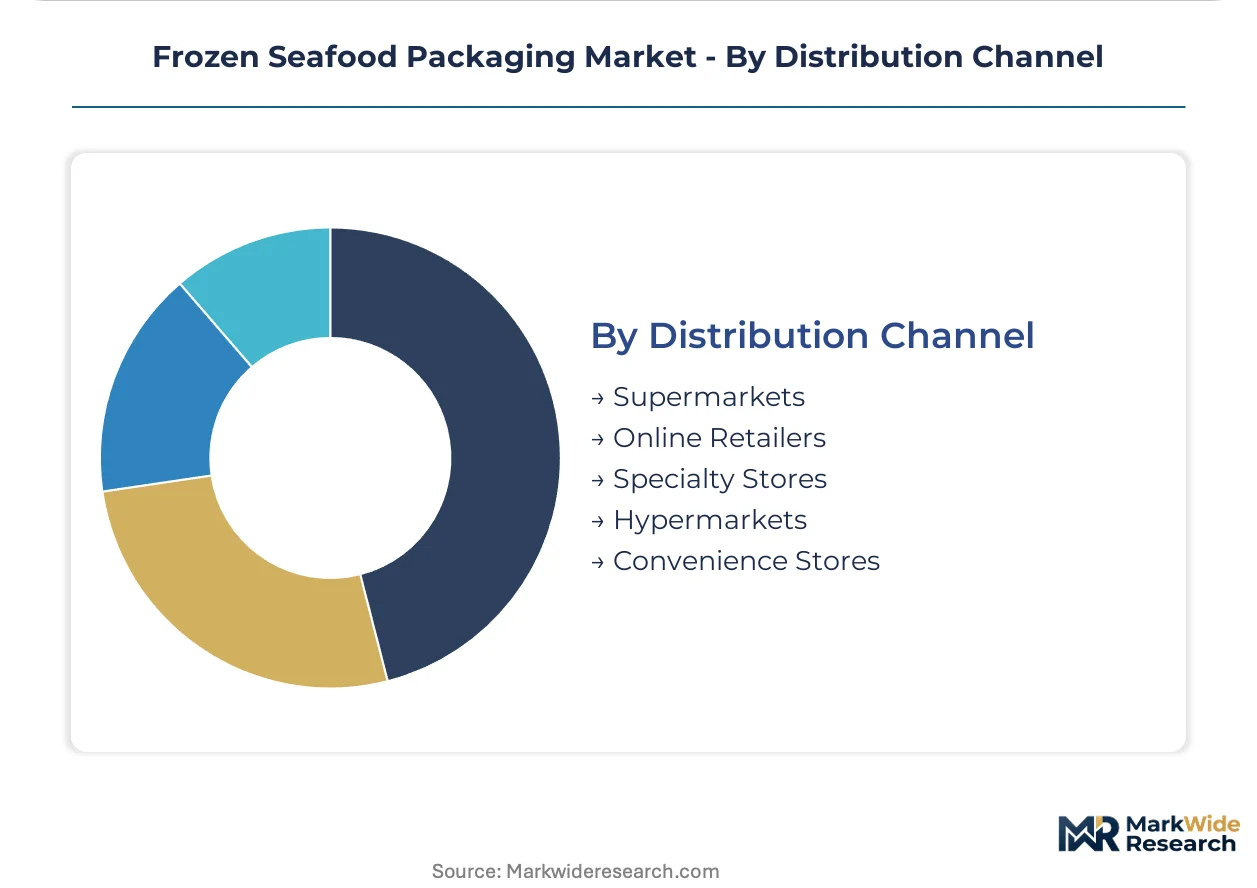
Distribution Channel:
Channel selection dictates pack size, labeling complexity, and cold-chain integrity requirements from warehouse to final handoff.
- Supermarkets:Full-service seafood counters require retail-ready clamshells with consumer-facing graphics. French and German chains lead biodegradable film procurement.
- Online Retailers:Direct-to-consumer fulfillment demands insulated shipper compatibility and lot-traceable films. US subscription seafood services specify FDA-compliant bar-code substrates.
- Hypermarkets:High-volume self-service frozen sections favor shrink-wrapped multi-packs with club-store pricing. Tokyo-Osaka corridors represent whitespace for premium barrier expansion.
- Specialty Stores:Sashimi-grade and organic certifications command vacuum-pack premiums with extended oxygen barrier. Norwegian cod exporters pilot sensor-enabled smart films for these channels.
- Convenience Stores:Limited freezer space drives small-format, high-turnover SKUs. Japanese chains lack dedicated frozen seafood sections, creating entry opportunities.
Supermarkets maintain volume leadership; online retailers show steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Norwegian aquaculture exports drive specialized barrier film demand in Scandinavia, while US processors grapple with FDA Seafood HACCP lot-traceability mandates for trans-Pacific shipments.
Norway
Atlantic salmon and whitefish exports require thermoformed trays rated to minus forty degrees Celsius for blast-freezer compatibility. The EU F-Gas Regulation compels domestic converters to certify hydrocarbon blowing agents for expanded polystyrene insulation. Bergen and Trondheim processing clusters anchor specialized barrier film consumption for trans-Atlantic logistics.
United States
Direct-to-consumer seafood subscription services demand lot-traceable, bar-code-ready films compliant with FDA Seafood HACCP requirements. EPA and FDA joint enforcement on cold-chain documentation elevates specification standards for Pacific Northwest salmon exporters. Seattle processing hubs concentrate procurement of RFID-enabled tracking systems for insulated container fleets.
Germany
Retail chains accelerate biodegradable film procurement to meet EU Green Deal plastic reduction targets. ECHA REACH framework restricts hydrofluorocarbon use in insulated shipping containers, forcing material reformulation. Hamburg and Bremen logistics corridors concentrate demand for certified compostable barrier materials in frozen seafood distribution.
India
FSSAI cold-chain mandates for temperature-controlled seafood distribution create first-mover advantages for barrier film suppliers establishing local partnerships. Central government PLI scheme incentives support domestic converting capacity expansion. Mumbai and Kochi processing clusters drive polyethylene-based economy format procurement for institutional foodservice channels.
Japan
Convenience store chains in Tokyo and Osaka lack dedicated frozen seafood sections with premium barrier packaging, representing whitespace for vacuum-packed sashimi-grade products. METI standards govern food contact material safety for imported packaging substrates. Nagoya logistics hubs concentrate demand for biaxially oriented polypropylene films with retail display clarity.
Frozen Seafood Packaging Market Competitive Landscape
Top-tier vendors anchor global multilayer barrier supply, while regional converters occupy specialized thermal shock resistance niches. The vendor base stratifies across integrated film manufacturers, thermoforming specialists, and insulation fabricators with distinct cold-chain expertise. Three archetypes dominate: multinational material science conglomerates, mid-tier packaging converters with blast-freezer validation capabilities, and regional insulation suppliers absorbing ECHA certification costs. Capacity expansion and strategic partnerships represent the dominant competitive vectors as stakeholders reposition for EU Green Deal compliance deadlines.
Among integrated film and rigid packaging conglomerates, Amcor, Sealed Air, and Berry Global Inc. exemplify the scale-driven tier. Amcor leverages global manufacturing footprints to supply multilayer barrier solutions. Sealed Air anchors cryogenic packaging automation through tracking-enabled systems. Berry Global Inc. occupies a position within thermoformed polystyrene tray fabrication calibrated for extreme temperature environments. These entities collectively represent how material science capabilities, geographic reach, and regulatory compliance infrastructure concentrate competitive positioning in frozen seafood logistics.
| Leading Market Players |
|---|
| Amcor |
| Sealed Air |
| Berry Global Inc. |
| Crown Holdings |
| DS Smith |
| Sonoco Products Company |
| Smurfit Kappa |
| Huhtamaki Oyj |
| Winpak Ltd. |
| Others |
Supply & Pricing Matrix
Retail chain procurement concentration in Germany, France, and the Netherlands anchors the dominant contract-based long-term offtake model for biodegradable barrier films, with EU Green Deal compliance deadlines compressing supplier pricing power into volume-commitment negotiations.
Pricing Analysis
Capacity additions in Southeast Asian EVOH copolymer corridors are reshaping price floors for multilayer barrier films. Three-tier pricing structure across premium sensor-enabled smart films, standard vacuum packs, and economy polyethylene formats stratifies the market. Cost compression in the biodegradable segment is intensifying because PLA-PHA blend suppliers compete for limited composting certification capacity. Foodservice distributors in India exhibit highest price sensitivity, while Norwegian salmon exporters prioritize thermal shock resistance over unit cost.
Supply Chain Analysis
Trans-Pacific freight rate volatility directly impacts landed costs for East Asian EVOH barrier layer shipments to North Atlantic converters. Raw material sourcing draws from South Korean petrochemical corridors for EVOH copolymers, Chinese metallized film production, and Nordic expanded polystyrene insulation fabrication. Single-source vulnerability clusters in East Asian EVOH manufacturing expose converters to feedstock disruption. Distribution runs through cold-chain logistics operators with blast-freezer validation capabilities serving Norwegian aquaculture export corridors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Frozen seafood packaging has matured into a late-cycle quality story as EU retail chains shift procurement toward EN 13432-certified compostable barrier materials with premium specification requirements.
For Market Incumbents: Extend certification infrastructure for alternative blowing agents under REACH F-Gas deadlines before Nordic competitors absorb compliance costs. Backward integration into EVOH copolymer supply through East Asian joint ventures mitigates feedstock volatility exposure. Channel control over refrigerated logistics partnerships in Pacific Northwest salmon processing clusters defends margin position against subscription-based packaging asset management entrants. For New Entrants and Emerging Players: Japanese convenience store chains lack dedicated frozen seafood sections with premium barrier packaging, representing immediate whitespace for vacuum-packed sashimi-grade formats. Local converting partnerships under India FSSAI cold-chain mandates offer first-mover positioning in polyethylene-based economy formats for institutional foodservice. Direct technical sales teams with blast-freezer validation expertise accelerate adoption in Norwegian salmon export processing clusters. For Investors and Strategic Acquirers: Integrated material science conglomerates are the most active acquirer in this space, targeting mid-tier converters with blast-freezer chamber access and ECHA certification completion. The five-to-ten-year viability window favors asset-light packaging procurement platforms over capital-intensive owned equipment models. Watch for EU extended producer responsibility scheme harmonization as the signal indicating consolidation acceleration across fragmented national recycling infrastructures.| Strategic Initiative | Industry Significance |
|---|---|
| Alternative Blowing Agent Certification | REACH F-Gas compliance enables continued expanded polystyrene supply to Nordic aquaculture exporters. |
| Sensor-Enabled Smart Film Launch | Norwegian cod exporters pilot time-temperature indicators for trans-Atlantic insurance premium compression. |
| Local Converting Partnership in India | FSSAI cold-chain mandates create captive supply positioning for polyethylene economy formats. |
| Subscription-Based Asset Management Platform | Pacific Northwest processors shift capital expenditure into operational contracts for seasonal volume flexibility. |
| Biodegradable Film Manufacturing Scale-Up | EU Green Deal plastic reduction targets in France and Netherlands accelerate certified compostable demand. |
Research Methodology
Multiple input streams — primary interviews with packaging procurement managers at retail chains, technical directors at barrier film converters, and cold-chain logistics operators — were reconciled against secondary validation from ECHA regulatory filings, EU customs trade data, and FSSAI mandate documentation. Conversations with Norwegian salmon processing executives, German supermarket category buyers, and Indian foodservice distributors informed demand-side assumptions. Bottom-up volume modeling across packaging formats and top-down value reconciliation anchored the analytical framework.
Data-stream reconciliation applied segmentation across packaging type, material grade, end-user vertical, and distribution channel throughout the forecast period. CAGRs were derived from trend extrapolation of biodegradable film adoption curves, EVOH supply expansion timelines, and cold-chain infrastructure investment patterns. Modeled inputs incorporated EU Green Deal compliance deadline impacts, FDA Seafood HACCP lot-traceability mandate enforcement intensity, and blast-freezer compatibility standard evolution.
Inputs from regulatory filing databases and customs trade repositories were available through the study window; gaps in real-time converter capacity utilization data introduce uncertainty bands around near-term supply elasticity assumptions. Forecasts reflect documented assumptions about ECHA certification completion rates and FSSAI enforcement trajectories. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Food Packaging
Flexible Frozen Food Packaging Market
Food Packaging
Self-Heating Food Packaging Market
Food Packaging
Spreads and Toppings Packaging Market
Food Packaging
On the Go Food Packaging Market
Food Packaging
North America Frozen Food Packaging Market
Food Packaging
Mushroom Packaging Market
Food Packaging
Food and Beverage Packaging Market
Food Packaging
Food Packaging Market
Food Packaging
PCR Packaging for Food and Beverages Applications Market
Food Packaging
Ambient Food Products Packaging Market
Food Packaging
Cupcake Containers Market
Food Packaging
North America Canned Food Packaging Market
Food Packaging
Europe Food Packaging Market
Food Packaging
Probiotics Packaging Market
Food Packaging
Produce Packaging Market
Food Packaging
Food Partition Trays Market