
 France Rigid Plastic Packaging Market | 2026-2036
France Rigid Plastic Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
France Rigid Plastic Packaging Market Insights
Asset-light leasing arrangements for injection and blow-molding equipment is tilting competitive dynamics toward mid-sized converters that previously faced capital barriers. Alpla France SAS leverages its captive resin compounding network to secure material cost advantages across bottle production. Berry Global Inc sustains scale economics through multi-site manufacturing footprints serving pan-European personal care brands. ActiPack SAS specializes in technical jars for pharmaceutical applications, occupying a defensible niche against commodity competitors.
France rigid plastic packaging encompasses thermoformed, injection-molded, and extrusion-blown structures fabricated from polyethylene, polypropylene, polystyrene, or PVC, engineered to provide dimensional stability, barrier protection, and stackability for shelf-ready goods. Bottles dominate volume flows into beverage and personal care lines, while containers capture expanding share from pharmaceutical compliance packs and household concentrate refills. Polypropylene grades are gaining formulation preference where heat resistance and clarified aesthetics command premium positioning against standard polyethylene specifications.
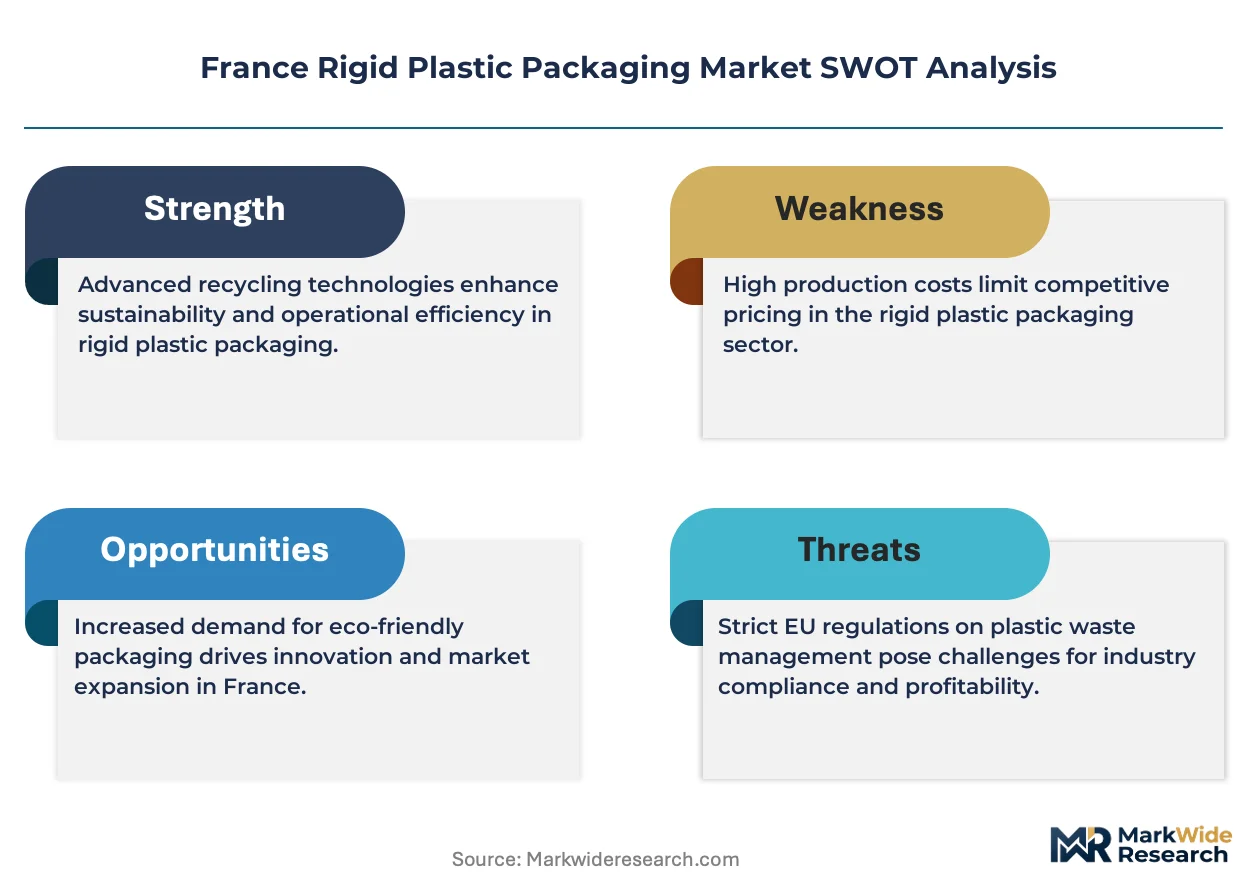
France's AGEC anti-waste statute and EU REACH chemical registration protocols jointly constrain virgin material pathways while mandating recycled content traceability. ANSM pharmaceutical packaging standards enforce child-resistance and barrier integrity thresholds that elevate technical qualification costs for new entrants. Stakeholders must monitor forthcoming Ecodesign for Sustainable Products Regulation implementation timelines to calibrate capital allocation between mechanical recycling integration and bio-based polymer development pipelines.
Market Dynamics
France's AGEC law mandates recycled content thresholds that force converters to reengineer material specifications and sourcing networks simultaneously.
Growth Catalysts
- Pharmaceutical compliance packaging:Dose-protection requirements under ANSM standards drive rigid container adoption for prescription adherence programs.
- Île-de-France industrial clustering:Food processing concentration around Paris generates procurement pull for thermoformed trays and barrier bottles.
- Polypropylene formulation advances:Clarified heat-resistant grades displace standard polyethylene in premium cosmetic and dairy applications.
Market Restraints
- Virgin resin cost volatility:Naphtha-linked polyethylene and polypropylene pricing squeezes converter margins during upstream petrochemical swings.
- Mechanical recycling feedstock scarcity:Post-consumer rigid flake supply concentrates in northern European collection zones, creating geographic dependency.
- EuPIA migration limits:Ink and coating restrictions on recycled substrates constrain decorative flexibility for brand owners.
Strategic Opportunities
- Auvergne-Rhône-Alpes pharma corridor:Underdeveloped local compounding capacity creates white space for technical jar specialists near Lyon formulation clusters.
- Bio-based polymer convergence:Drop-in polypropylene from renewable feedstocks aligns with AGEC circular economy credits and brand sustainability commitments.
- Direct-to-manufacturer digital procurement:B2B platforms bypass traditional distributor layers for mid-sized cosmetic brands seeking shorter lead times.
Industry Challenges
- Multi-material separation expertise:Sorting technology operators face skill gaps in distinguishing near-infrared signatures of complex barrier laminates.
- ANSM certification timelines:Child-resistance testing protocols extend qualification periods for new pharmaceutical container designs.
- Legacy blow-molding asset retrofit:Reconfiguring existing equipment for post-consumer resin processing demands capital outlays many mid-tier converters cannot absorb.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Rigid Plastic Packaging Market |
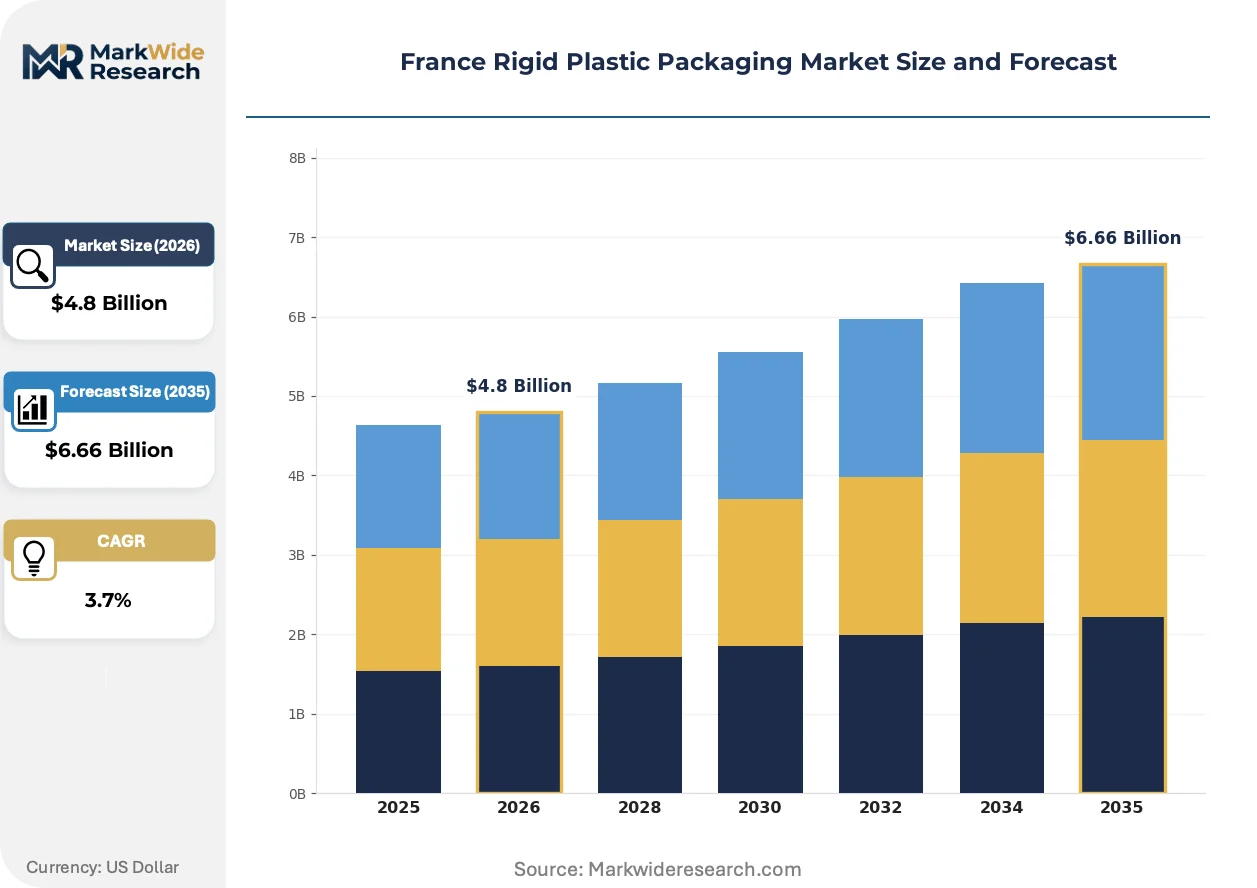
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $6.66 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Containers, Tubs Material: Polyethylene, Polypropylene, Polystyrene, PVC End Use Industry: Food & Beverage, Personal Care, Household, Pharmaceuticals Distribution Channel: Online Retail, Supermarkets, Convenience Stores, Direct Sales |
| Companies Covered | Amcor Group GmbH, Berry Global Inc, Aptar Group Inc, Alpla France SAS, Axium Packaging, Frapak Packaging, Retal Group, PDG Plastiques, ActiPack SAS, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Rigid Plastic Packaging Market Trends and Innovations
Material science breakthroughs and regulatory tightening are compressing traditional specification cycles while opening premium positioning for certified sustainable alternatives.
Digital watermarking is migrating from pilot trials to production-scale deployment across French retail packaging streams. Consortiums including major supermarket chains are embedding invisible markers into rigid trays and bottles. This technology is enabling automated sorting precision that mechanical recycling infrastructure previously could not achieve.
Ecodesign for Sustainable Products Regulation implementation timelines are forcing converters to front-load lifecycle assessment documentation. The delegated act covering packaging categories will mandate recycled content verification systems traceable to batch level. Pharmaceutical and cosmetic brands with pan-European distribution are pre-qualifying suppliers against these protocols ahead of enforcement dates.
Refill concentrate formats are disrupting traditional bottle economics in household and personal care segments. Auvergne-Rhône-Alpes formulation houses are specifying smaller rigid containers designed for dilution at point of use. This pattern concentrates procurement volumes toward technical injection-molded closures and dosing caps rather than standard blow-molded bottles.
France Rigid Plastic Packaging Market Segmentation
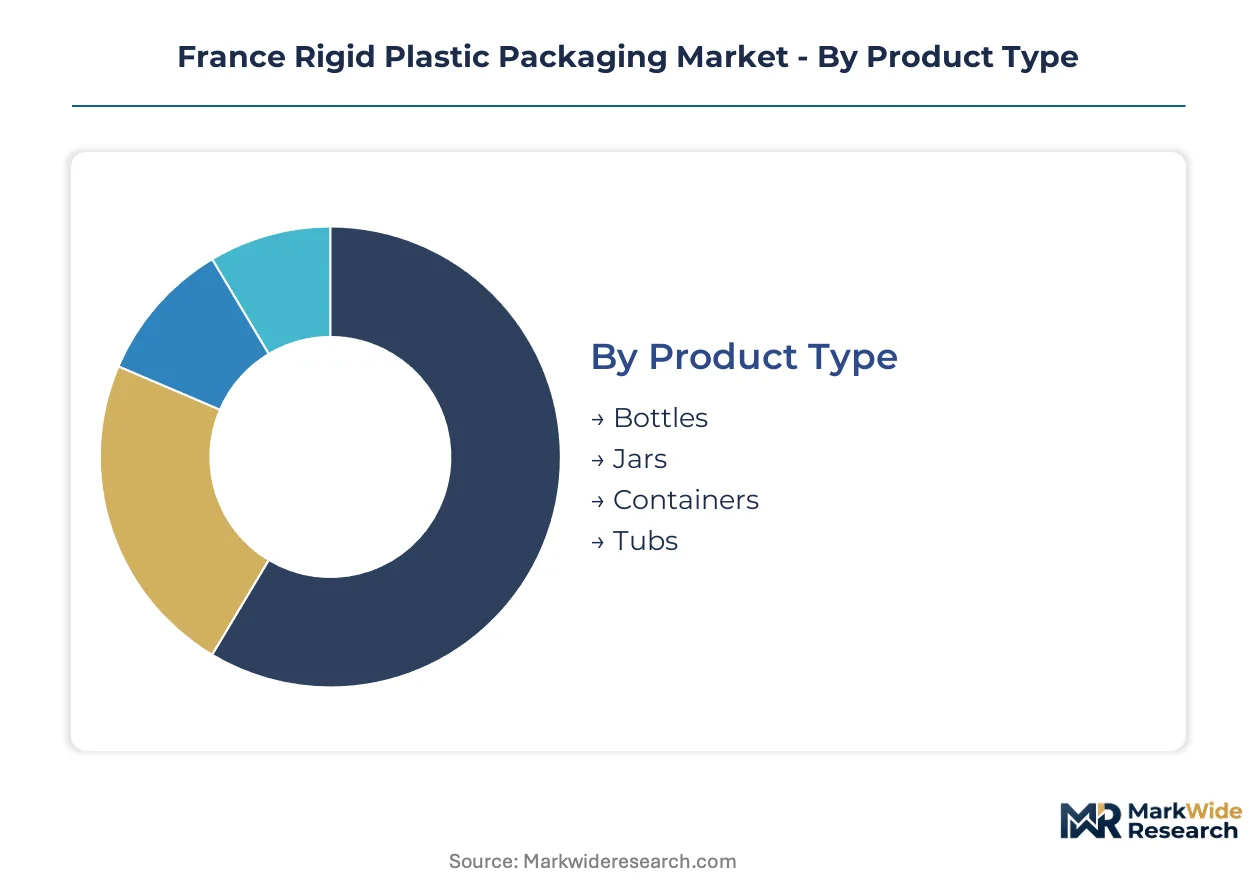
France rigid plastic packaging exhibits divergent growth velocities across product architectures and material specifications. Pharmaceutical and food-grade applications command premium positioning against commodity household formats. Understanding segment-level dynamics illuminates where converters must deploy capital versus where asset-light strategies suffice.
Product Type:
Mature blow-molding infrastructure dominates high-volume throughput, while injection-molded technical formats capture expanding share in compliance-driven end uses.
- Bottles:Extrusion and injection blow-molded structures fabricated from HDPE and PET-grade polymers deliver dimensional stability for carbonated beverages and personal care liquids. Île-de-France beverage bottlers and Auvergne-Rhône-Alpes cosmetic formulators anchor procurement volumes for standard and handled variants. AGEC recycled content mandates are forcing requalification of post-consumer resin grades for food-contact approvals.
- Jars:Wide-mouth injection-molded containers with threaded or snap-fit closures provide access convenience for viscous products. Pharmaceutical manufacturers around Lyon specify child-resistant jar configurations under ANSM protocols, creating technical barriers that filter out commodity converters. Clarified polypropylene grades are displacing polystyrene where shelf aesthetics command premium positioning.
- Containers:Rectangular and oval thermoformed or injection-molded formats serve concentrate refills and dry goods. Household product brands in northern France are downsizing container volumes to align with refill economics.
- Tubs:Thin-wall injection-molded dairy and deli formats compete against flexible alternatives on total system cost. French dairy cooperatives favor tubs with tamper-evident lidding for retail distribution.
Bottles handle the majority of throughput; jars are gaining share fastest on pharmaceutical compliance demand.
Material:
Cost tier differentiation separates commodity polyethylene from engineered polypropylene specifications serving heat-stability requirements.
- Polyethylene:HDPE and LDPE grades dominate blow-molded bottle production for beverage and household applications. Virgin resin cost volatility linked to naphtha pricing squeezes converter margins during upstream petrochemical swings.
- Polypropylene:Homopolymer and random copolymer formulations deliver clarified aesthetics and hot-fill tolerance for dairy and cosmetic segments. Clarified heat-resistant grades are displacing standard polyethylene in premium cosmetic applications across Paris formulation clusters.
- Polystyrene:Crystal and high-impact grades persist in thermoformed trays and disposable cutlery despite regulatory pressure on single-use formats. Ecodesign for Sustainable Products Regulation timelines are accelerating substitution toward polypropylene alternatives.
- PVC:Rigid calendered and blow-molded specifications retain niche position in pharmaceutical blister packs and construction applications. REACH chemical registration protocols constrain vinyl chloride monomer pathways while mandating migration testing documentation.
Polyethylene commands the volume base; polypropylene is climbing the fastest on premium formulation demand.
End Use Industry:
Application-driven specification divergence separates high-barrier pharmaceutical formats from commodity household packaging.
- Food & Beverage:Barrier bottles, thermoformed trays, and dairy tubs serve processed food manufacturers and beverage bottlers. Île-de-France industrial clustering generates concentrated procurement pull for shelf-ready formats.
- Personal Care:Clarified jars and bottles with decorative finishing support cosmetic brands' premium positioning. Auvergne-Rhône-Alpes formulation houses specify smaller rigid containers designed for dilution at point of use.
- Household:Standard blow-molded bottles and concentrate containers face margin compression from private-label competition. Refill economics are disrupting traditional bottle specifications in cleaning product lines.
- Pharmaceuticals:Child-resistant jars, compliance packs, and barrier bottles meet ANSM dose-protection standards. Technical qualification costs and extended certification timelines filter out commodity competitors.
Food & Beverage anchors procurement volume; Pharmaceuticals shows the steepest expansion trajectory on compliance packaging adoption.
Distribution Channel:
Customer type stratification separates bulk direct procurement from fragmented retail replenishment.
- Online Retail:E-commerce-optimized packaging with damage-resistant geometries serves direct-to-consumer fulfillment networks. Secondary packaging reduction pressures are migrating upstream to primary rigid format specifications.
- Supermarkets:High-volume replenishment of standard bottles and containers through centralized distribution centers. Major French retail chains are embedding digital watermarking into rigid trays for automated sorting infrastructure.
- Convenience Stores:Smaller pack sizes and impulse-oriented formats with grab-and-go handling features. Urban density around Paris and Lyon concentrates replenishment frequency.
- Direct Sales:Manufacturer-to-converter relationships for custom technical formats bypass distributor margins. Mid-sized cosmetic brands are migrating toward digital procurement platforms for shorter lead times.
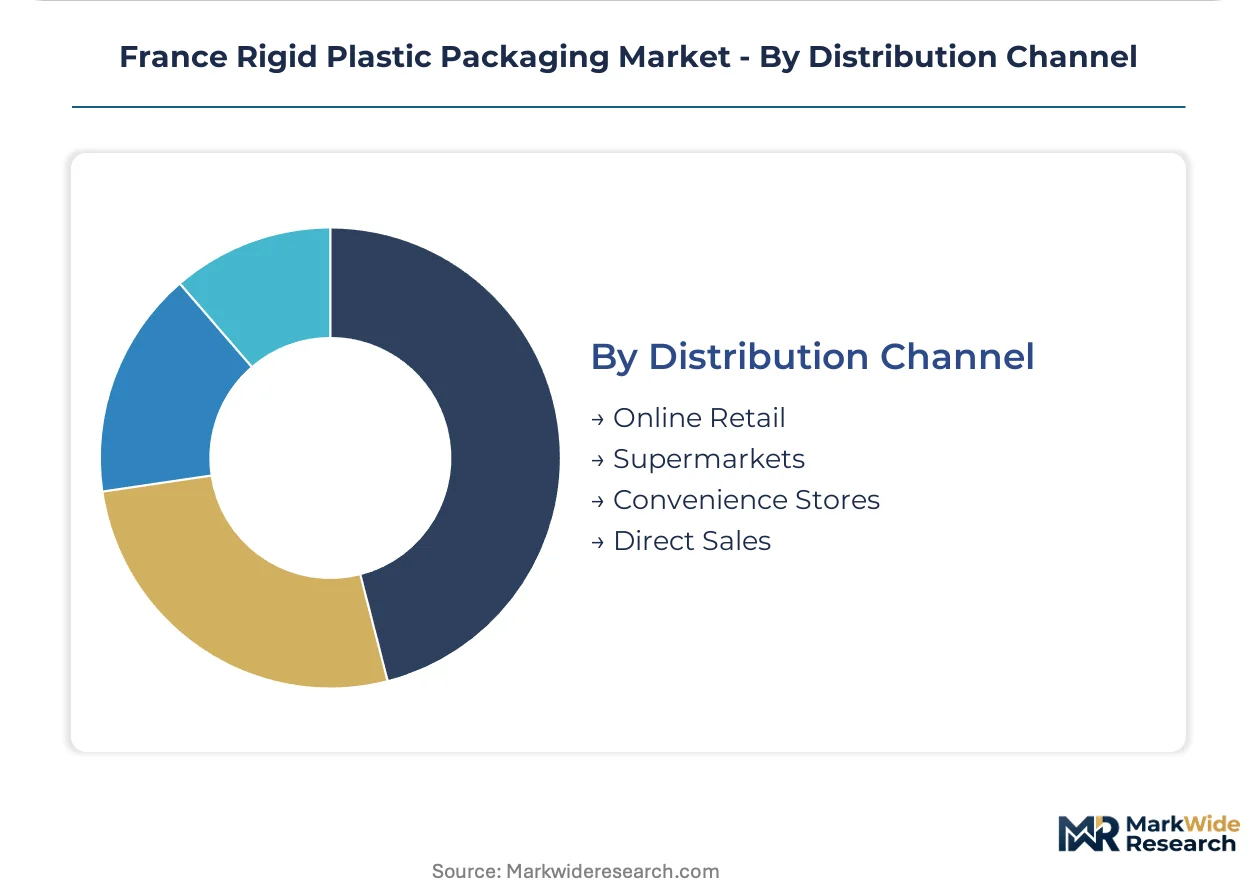
Supermarkets move the largest unit volumes; Direct Sales is expanding most quickly on B2B platform adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's AGEC law and extended producer responsibility framework are reshaping material sourcing decisions across regional industrial corridors, with recycled content mandates concentrating procurement pull around established formulation clusters.
Île-de-France
Beverage bottlers and food processors around Paris generate concentrated demand for thermoformed trays and barrier bottles. ANSM pharmaceutical packaging standards enforce child-resistance thresholds that elevate technical qualification costs for converters serving the region's dose-protection packaging needs. The metropolitan industrial belt anchors procurement volumes for shelf-ready formats with clarified polypropylene specifications.
Auvergne-Rhône-Alpes
Cosmetic formulation houses and pharmaceutical manufacturers near Lyon specify technical jars and compliance packs under strict barrier integrity protocols. The AGEC anti-waste statute tightens recycled content mandates that force converters to reengineer material specifications for this corridor's premium applications. Local compounding capacity scarcity creates white space for specialists positioned near formulation clusters.
Hauts-de-France
Household product brands and cleaning concentrate formulators drive demand for smaller rigid containers designed for dilution economics. REACH chemical registration protocols constrain virgin material pathways while mandating traceability documentation. The northern collection infrastructure concentrates post-consumer rigid flake supply, creating geographic dependency for mechanical recycling feedstock.
Provence-Alpes-Côte d'Azur
Personal care brands with premium positioning requirements source clarified heat-resistant polypropylene grades for shelf aesthetics. The Ecodesign for Sustainable Products Regulation implementation timelines force converters to front-load lifecycle assessment documentation. Regional formulation activity supports procurement for decorative-finished jars displacing standard polyethylene specifications.
France Rigid Plastic Packaging Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base organizes around three strategic archetypes: multi-site manufacturers with scale economics, captive resin compounders with material cost advantages, and technical specialists occupying defensible niches. M&A activity concentrates among pan-European packaging groups consolidating converter networks, while asset-light equipment leasing arrangements tilt dynamics toward mid-sized players previously facing capital barriers.
Among France-based specialists, Alpla France SAS and ActiPack SAS exemplify contrasting positioning strategies. Alpla occupies a position anchored by captive resin compounding infrastructure, while ActiPack represents the technical jar specialist archetype serving pharmaceutical compliance applications. Berry Global Inc and Aptar Group Inc sit within the scale-driven tier, with multi-site manufacturing footprints serving brand owners across pan-European distribution networks.
| Leading Market Players |
|---|
| Amcor Group GmbH |
| Berry Global Inc |
| Aptar Group Inc |
| Alpla France SAS |
| Axium Packaging |
| Frapak Packaging |
| Retal Group |
| PDG Plastiques |
| ActiPack SAS |
| Others |
Pricing and Supply Chain Analysis
The Rhine-Rhône freight corridor carries virgin resin shipments from Antwerp petrochemical hubs to French converter plants, with its cost dynamics amplifying supply concentration effects around Île-de-France and Auvergne-Rhône-Alpes while forcing downstream price differentiation between AGEC-compliant certified grades and standard specifications.
Pricing Analysis
Certification level under AGEC recycled content mandates and ANSM pharmaceutical standards creates the primary spread between premium technical jars and commodity blow-molded bottles. Three-tier pricing structure across premium, standard, and economy levels reflects material qualification costs, with pharmaceutical-grade containers commanding substantial premiums over household formats. Price erosion runs through standard polyethylene bottles as private-label competition intensifies and naphtha-linked resin volatility squeezes converter margins. Mid-sized cosmetic brands show highest price sensitivity, while pharmaceutical manufacturers prioritize barrier integrity over unit cost.
Supply Chain Analysis
Contract manufacturing concentration sits with Alpla France SAS, Berry Global Inc, and ActiPack SAS holding dominant thermoforming and injection-molding capacity across French industrial corridors. Geographic supply concentration draws from Belgium, Germany, and the Netherlands for virgin resin feedstocks, with post-consumer flake sourcing tethered to northern European collection infrastructure. Raw material dependencies rest on naphtha-derived polyethylene, polypropylene homopolymers, and clarified random copolymers for premium applications. Single-source vulnerability emerges from mechanical recycling feedstock scarcity concentrated in Hauts-de-France collection zones. Distribution runs through direct manufacturer relationships for technical formats and supermarket centralized procurement for standard bottles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France rigid plastic packaging is approaching a platform-economics inflection where digital procurement platforms and batch-level traceability systems will determine competitive access, driven by the Ecodesign for Sustainable Products Regulation's interoperability requirements for recycled content verification.
For Market Incumbents: Insulate pharmaceutical market share by accelerating ANSM certification pipelines for post-consumer resin grades before enforcement timelines tighten. Deepen backward integration into captive compounding capacity near Lyon formulation clusters to offset virgin resin cost volatility and defend margin position against asset-light mid-tier competitors leasing blow-molding equipment. For New Entrants and Emerging Players: Technical jar production for pharmaceutical compliance applications around Auvergne-Rhône-Alpes represents the most penetrable entry point given local compounding capacity scarcity and ANSM qualification barriers filtering commodity competitors. Bio-based polypropylene drop-in formulations for cosmetic brands seeking AGEC circular economy credits offer a second white-space target. A direct-to-manufacturer digital procurement angle bypasses traditional distributor layers and captures mid-sized cosmetic brands demanding shorter lead times. For Investors and Strategic Acquirers: Carve-out targets emerge from pan-European packaging groups consolidating French converter networks, particularly technical specialists with ANSM-certified pharmaceutical jar capacity. Long-term viability favors assets positioned at the intersection of mechanical recycling integration and bio-based polymer development pipelines. The signal to watch is Ecodesign for Sustainable Products Regulation delegated act implementation timelines, which will accelerate supplier pre-qualification activity and concentrate procurement volumes toward certified converters.| Strategic Initiative | Industry Significance |
|---|---|
| Mechanical Recycling Integration | AGEC mandates force converters to secure post-consumer flake supply chains traceable to batch level. |
| Bio-based Polymer Development | Drop-in polypropylene from renewable feedstocks aligns with circular economy credits and brand sustainability commitments. |
| Digital Watermarking Deployment | Major French retail chains embed invisible markers enabling automated sorting precision for rigid trays and bottles. |
| ANSM Certification Pipeline Expansion | Child-resistance testing protocols extend qualification periods, creating defensive moats for certified pharmaceutical container suppliers. |
| Asset-light Equipment Leasing | Mid-sized converters bypass capital barriers for injection and blow-molding capacity, tilting competitive dynamics toward specialized players. |
Research Methodology
The analysis maps blow-molded bottles, injection-molded jars, thermoformed containers, and thin-wall tubs, each validated through converter operations directors, pharmaceutical packaging procurement managers, cosmetic brand supply chain leads, and resin compounding technical officers. Primary interviews with these stakeholders combined with secondary validation against ANSM regulatory filings, EU Ecodesign implementation documentation, AGEC law compliance reports, and French customs trade data. Bottom-up capacity assessments and top-down demand modeling triangulate volume estimates across material grades and end-use applications.
Assumptions held AGEC recycled content thresholds and Ecodesign delegated act timelines fixed at announced regulatory positions, while naphtha pricing volatility and post-consumer flake availability varied across sensitivity scenarios. Segmentation dimensions modeled include product architecture, material specification, end-use industry, and regional industrial corridor concentration. CAGRs derive from weighted average growth across these segments, with pharmaceutical compliance packaging adoption curves and refill concentrate format penetration serving as key industry-specific forecast inputs across the projection horizon.
Macroeconomic conditions sit as an overlay; deviation in naphtha pricing spreads, eurozone industrial output, or consumer packaged goods demand would shift the trajectory. Forecasts reflect documented assumptions regarding regulatory enforcement timelines and recycling infrastructure buildout rates. Quarterly review of ANSM certification queue lengths, post-consumer resin price spreads, and digital watermarking deployment milestones is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rigid Packaging
Latin America Rigid Plastic Packaging Market
Rigid Packaging
Reclosable Rigid Containers Market
Rigid Packaging
United States Rigid Plastic Packaging Market
Rigid Packaging
Spain Rigid Plastic Packaging Market
Rigid Packaging
GCC Rigid Packaging Market
Rigid Packaging
Rigid Food Containers Market
Rigid Packaging
Morocco Rigid Plastic Packaging Market
Rigid Packaging
China Rigid Plastic Packaging Market
Rigid Packaging
GCC Packaging Market
Rigid Packaging
Global Rigid Paper Containers Market
Rigid Packaging
Rigid Transparent Plastic Market
Rigid Packaging
APAC Rigid Plastic Packaging Market
Rigid Packaging
Gable Top Packaging Market
Rigid Packaging
Rigid Food Packaging Market
Rigid Packaging
Rigid Plastic Packaging Market
Rigid Packaging
North America Airless Packaging Market