
 Europe Rigid Bulk Packaging Market | 2026-2036
Europe Rigid Bulk Packaging Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Rigid Bulk Packaging Market Insights
The European rigid bulk packaging sector is repositioning around a widening gap between premium engineered containers and commodity-grade alternatives. Basca Srl leverages its Italian manufacturing base to dominate high-performance plastic drum exports across Southern Europe. Schoeller Allibert Services B.V. sustains leadership in reusable folding bulk containers through dense service networks in Benelux and Germany. Greif Inc. anchors its position with integrated steel drum production and closed-loop recycling infrastructure spanning multiple European countries.
Rigid bulk packaging encompasses durable, stackable containers—typically constructed from high-density polyethylene, steel, or plywood—engineered to transport and store goods in volumes generally exceeding twenty liters without flexible walls. These units withstand mechanical handling, resist chemical permeation, and maintain dimensional stability through repeated use cycles in industrial supply chains. Plastic drums lead material substitution trends as converters replace coated steel in corrosive chemical applications, while totes capture expanding food-grade liquid logistics in dairy and edible oil distribution. Metal containers retain defensive share in solvent and hazardous waste segments where UN-certified performance remains non-negotiable.
REACH and the EU Green Deal shape material choices by restricting hazardous substances and mandating recyclability disclosures across packaging placed on European markets. ECHA substance evaluations and national extended producer responsibility schemes tighten compliance costs for imported containers. The F-Gas Regulation indirectly influences insulated bulk packaging specifications in temperature-sensitive pharmaceutical distribution. Stakeholders must monitor upcoming Packaging and Packaging Waste Regulation revisions to calibrate material portfolios and reuse service investments against shifting compliance thresholds.
Market Dynamics
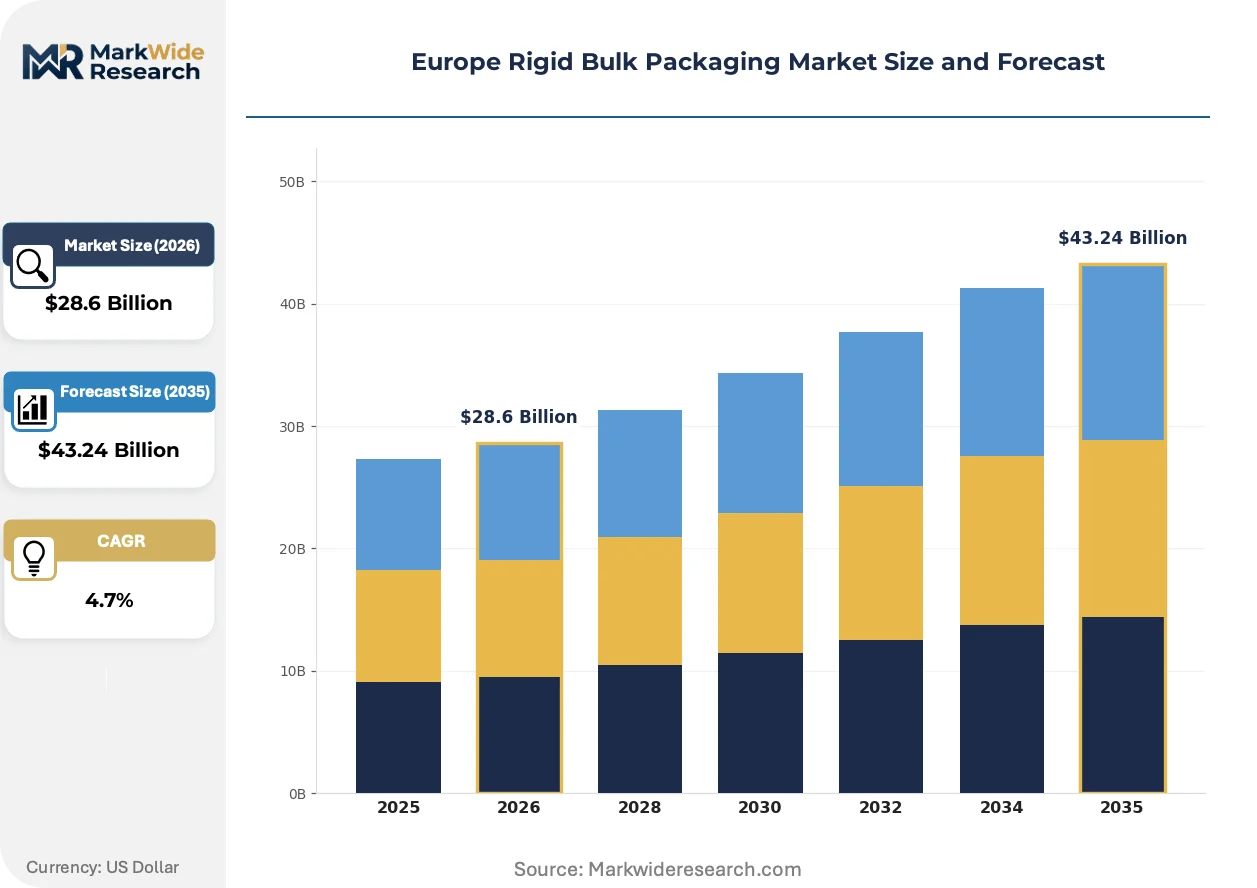
The European rigid bulk packaging market is restructuring around regulatory compression on material recyclability and the operational economics of reusable container fleets versus single-use alternatives. Chemical producers in the Rhine-Ruhr corridor are recalibrating procurement around total cost of ownership models that internalize reverse logistics and washing cycles.
Growth Catalysts
- REACH substance restrictions:Hazardous substance limitations under ECHA evaluations are phasing out coated steel drums in corrosive chemical applications. Polymer alternatives gain volume as converters reformulate resins for compliance.
- Food-grade liquid logistics:Dairy and edible oil distributors across Benelux are adopting intermediate bulk containers with multi-trip certification. Temperature stability requirements favor insulated polymer totes over traditional steel.
- Extended producer responsibility schemes:National EPR frameworks in France and Germany mandate recyclability disclosures and deposit systems. Packaging producers invest in closed-loop collection infrastructure to recover container assets.
Market Restraints
- HDPE resin cost volatility:Feedstock price swings tied to naphtha and natural gas markets compress converter margins. Long-term supply agreements with petrochemical suppliers remain difficult to secure at fixed rates.
- Steel drum supply concentration:UN-certified steel container production clusters in Eastern European manufacturing zones. Geopolitical friction and energy cost disparities create supply vulnerability for Western European buyers.
- Recyclate quality limitations:Post-consumer recycled polymer lacks consistent mechanical properties for hazardous goods certification. ECHA substance evaluations restrict certain recyclate streams from food-contact applications.
Strategic Opportunities
- Pharmaceutical cold chain expansion:Insulated bulk packaging for temperature-sensitive biologics remains underpenetrated in Southern European markets. F-Gas Regulation compliance creates specification barriers that favor specialized regional producers.
- Digital fleet tracking integration:Convergence of RFID tagging and blockchain-based custody records enables asset-light pooling models. Third-party logistics providers in Germany pilot subscription-based container availability guarantees.
- EU Green Deal packaging revisions:Upcoming Packaging and Packaging Waste Regulation mandates reuse targets for industrial transport packaging. Early compliance investments position service networks for preferential supplier status.
Industry Challenges
- Multi-material separation expertise:Composite containers combining polymer liners with steel cages require specialized dismantling capabilities. Recycling infrastructure capacity for these hybrid formats lags behind pure-material alternatives.
- UN certification timeline compression:Design validation for new container geometries faces extended testing protocols. Certification backlogs at notified bodies delay product launches for twelve to eighteen months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Rigid Bulk Packaging Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.24 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Containers, Crates, Drums, Totes Material: Plastic, Glass, Metal, Wood End User: Food & Beverage, Chemicals, Pharmaceuticals, Agriculture Size: Small, Medium, Large, Extra Large |
| Companies Covered | Basca Srl, Martin Contenedores Para Logística S.L., ORBIS Corporation, ALPLA Group, Schutz GmbH & Co., Schoeller Allibert Services B.V., Obal Centrum S.R.O., Tank International S.R.L., Greif Inc., Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Rigid Bulk Packaging Market Trends and Innovations
Material science advances and digital asset tracking are converging to redefine container lifecycle economics. Producers are repositioning around performance guarantees rather than unit sales.
Co-extruded multi-layer HDPE is absorbing barrier functions previously requiring metal or fluoropolymer linings. Specialty chemical distributors in the Netherlands are specifying these constructions for solvent transport at scale. The technology is absorbing market share from composite drums by eliminating liner replacement costs and simplifying end-of-life recycling.
EU Green Deal implementation timelines are compressing permissible carbon intensity thresholds for packaging production. Industrial buyers in Germany now require Environmental Product Declarations as standard tender documentation. Steel drum producers are responding with electric arc furnace feedstock sourcing and renewable energy power purchase agreements to maintain specification eligibility.
Asset pooling models are displacing outright purchase for high-turnover container categories. Chemical manufacturers in the Rhine-Ruhr corridor are contracting with third-party fleet operators for per-use pricing with guaranteed availability. This shift concentrates procurement influence with logistics integrators and reduces brand loyalty to original equipment manufacturers.
Europe Rigid Bulk Packaging Market Segmentation
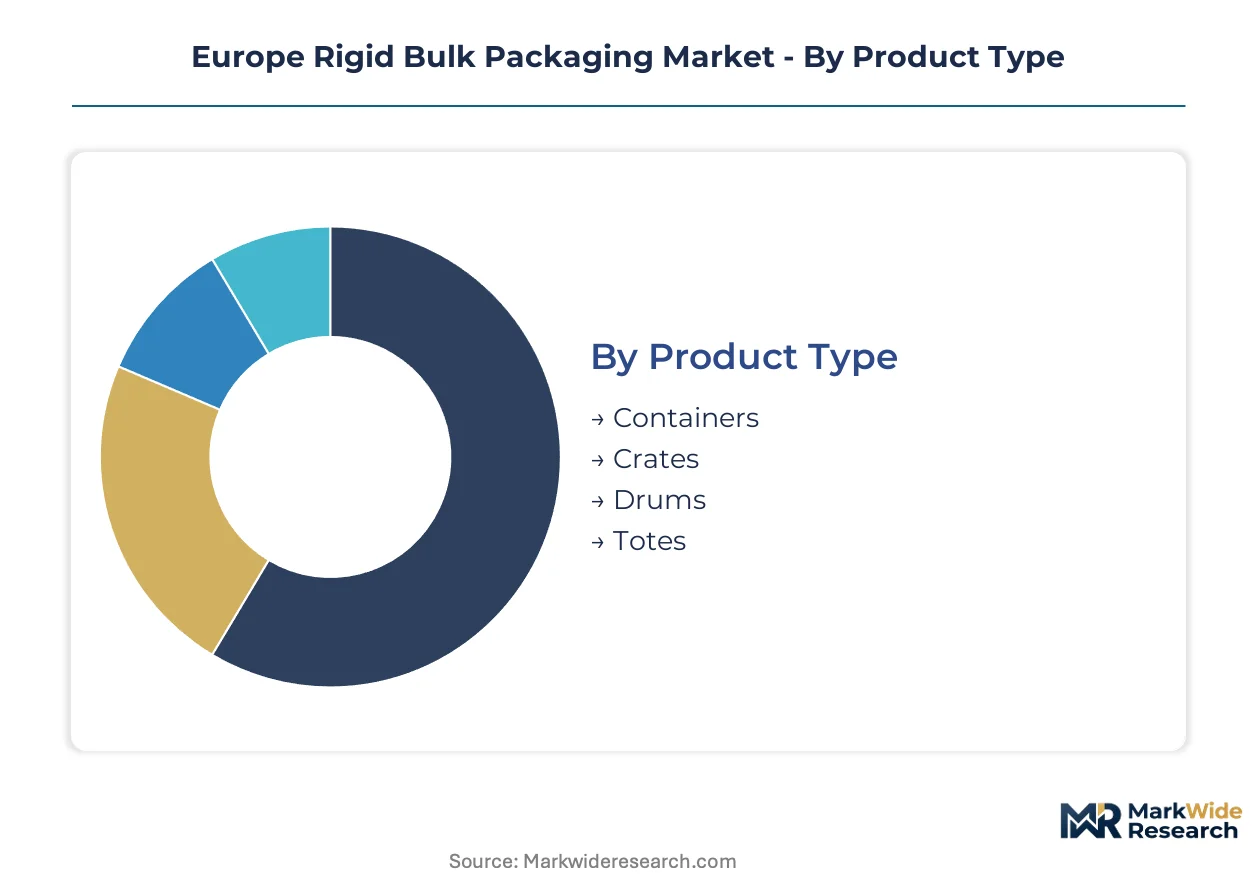
Segmentation in European rigid bulk packaging reveals how material specifications and container geometries align with distinct regulatory and operational requirements across industrial supply chains. Chemical handlers, food processors, and pharmaceutical distributors each impose non-negotiable performance thresholds that reshape procurement patterns.
Product Type:
Container geometry determines mechanical handling compatibility and stacking efficiency in automated warehouse environments.
- Containers:Rectangular or cylindrical vessels engineered for palletized transport and forklift engagement. Rhine-Ruhr chemical clusters specify UN-certified polymer containers for solvent distribution, driven by REACH substance restrictions on coated metal alternatives.
- Crates:Ventilated or solid-walled enclosures for agricultural produce and processed food logistics. Dutch horticulture exporters dominate demand, prioritizing collapsible designs that minimize return freight costs in closed-loop distribution.
- Drums:Cylindrical vessels with tight-head or open-head configurations for liquid and semi-solid containment. Steel drums retain defensive share in hazardous waste segments where UN-certified performance remains mandatory.
- Totes:Intermediate bulk containers with integrated pallet bases for liquid and granular materials. Dairy and edible oil distributors across Benelux adopt insulated polymer totes for temperature-stable logistics.
Containers lead on scale; totes lead on momentum.
Material:
Material selection balances chemical resistance, recyclability compliance, and total cost of ownership across reuse cycles.
- Plastic:High-density polyethylene and co-extruded multi-layer constructions dominate corrosive chemical applications. ECHA substance evaluations accelerate substitution of coated steel in Germany and France.
- Glass:Borosilicate and soda-lime formulations for pharmaceutical and high-purity chemical containment. Limited penetration reflects fragility constraints in mechanized handling environments.
- Metal:Cold-rolled steel with interior coatings for solvent and flammable liquid transport. Eastern European production concentration creates supply vulnerability for Western buyers.
- Wood:Plywood and timber constructions for agricultural bulk and export crating. EU Green Deal carbon intensity thresholds pressure producers toward certified sustainable sourcing.
Plastic dominates volume; metal retains premium positioning in hazardous segments.
End User:
End-use specifications fragment around hygiene standards, chemical compatibility, and traceability requirements.
- Food & Beverage:Dairy processors and edible oil distributors specify food-grade polymer totes with multi-trip certification. Temperature stability requirements favor insulated constructions over traditional steel.
- Chemicals:Specialty chemical producers in the Netherlands and Germany drive demand for co-extruded barrier containers. REACH compliance mandates accelerate material substitution away from coated metal drums.
- Pharmaceuticals:Temperature-sensitive biologics distribution requires insulated bulk packaging with F-Gas Regulation-compliant specifications. Southern European markets remain underpenetrated relative to Northern corridors.
- Agriculture:Horticulture and grain logistics favor collapsible crates and ventilated containers. Dutch export clusters concentrate demand for returnable packaging systems.
Chemicals anchor procurement volume; pharmaceuticals climb the fastest.
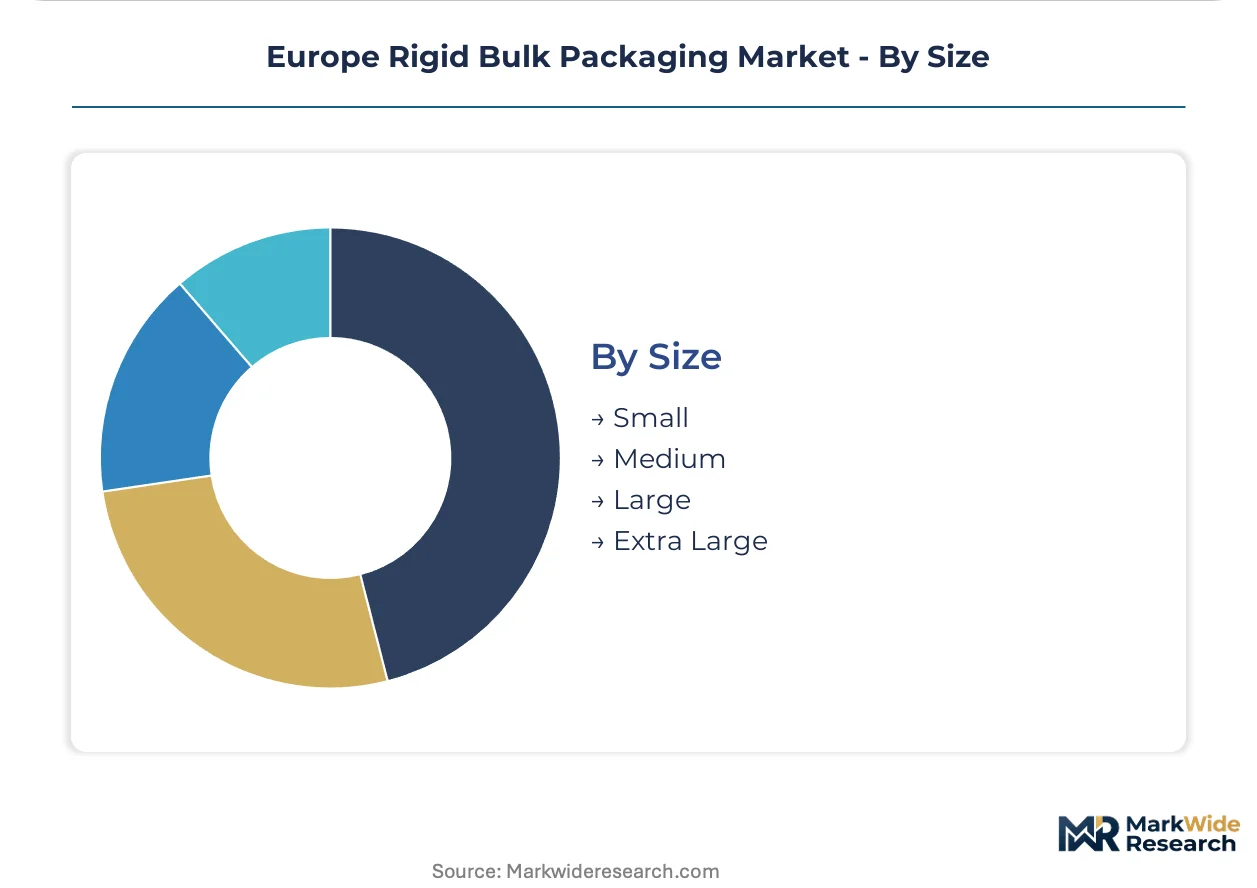
Size:
Capacity tiers align with handling equipment specifications and modal transport economics.
- Small:Sub-50-liter vessels for specialty chemical samples and pharmaceutical intermediates. Laboratory and pilot-scale production facilities in Switzerland and Germany concentrate demand.
- Medium:50-200 liter containers for batch chemical processing and food ingredient distribution. Standard pallet dimensions govern geometry optimization.
- Large:200-1000 liter intermediate bulk containers for bulk liquid logistics. Rhine-Ruhr industrial corridors specify these for chemical and edible oil transport.
- Extra Large:Above-1000 liter vessels for grain, feed, and bulk powder handling. Agricultural cooperatives in France and Germany favor these for harvest collection and storage.
Large formats dominate industrial procurement; extra large gains share in agricultural consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent pools in polymer science and container design concentrate in the Rhine-Ruhr corridor and Benelux manufacturing zones. These workforce clusters anchor Europe's rigid bulk packaging production networks and drive innovation in reusable container systems.
Germany
REACH substance restrictions are phasing out coated steel drums in corrosive chemical applications across German chemical parks. ECHA evaluations accelerate polymer substitution in the Rhine-Ruhr corridor, where BASF and Bayer facilities specify multi-trip intermediate bulk containers. Extended producer responsibility frameworks mandate recyclability disclosures, tightening compliance costs for container suppliers.
France
Dairy processors and edible oil distributors in Normandy and Brittany drive food-grade polymer tote adoption. National EPR schemes require deposit systems and closed-loop collection infrastructure. Lyon-based chemical clusters specify insulated containers for temperature-sensitive logistics, favoring regional producers with F-Gas Regulation compliance capabilities.
Netherlands
Dutch horticulture exporters dominate demand for collapsible crates in agricultural produce logistics. Rotterdam port infrastructure enables efficient return freight in closed-loop distribution systems. Specialty chemical distributors in the Amsterdam-Rotterdam-Antwerp corridor specify co-extruded barrier containers for solvent transport at scale.
Italy
Food processing clusters in Emilia-Romagna and Lombardy drive container turnover for pasta, olive oil, and wine logistics. EU Green Deal carbon intensity thresholds pressure producers toward certified sustainable sourcing for plywood and timber constructions. Basca Srl leverages its Italian manufacturing base to dominate high-performance plastic drum exports across Southern Europe.
United Kingdom
Pharmaceutical distributors in the Southeast and Midlands require insulated bulk packaging for temperature-sensitive biologics. Post-Brexit regulatory divergence from REACH creates compliance complexity for container imports. Steel drum producers respond with electric arc furnace feedstock sourcing and renewable energy power purchase agreements to maintain specification eligibility.
Europe Rigid Bulk Packaging Market Competitive Landscape
Top-tier vendors anchor integrated production and closed-loop recycling infrastructure, while mid-tier specialists focus on regional service density and material science differentiation. The vendor base stratifies across three tiers: multinational integrators with cross-border asset networks, national champions with dense service territories, and niche converters targeting certified hazardous goods segments. Two strategic archetypes dominate: fleet operators monetizing per-use pricing models, and material specialists capturing premium margins through barrier technology. Competitive moves concentrate on M&A for geographic coverage and capacity expansion in Eastern European manufacturing zones.
Within the multinational integrator tier, Greif Inc. and Schoeller Allibert Services B.V. exemplify divergent strategic positions. Greif anchors its European presence with integrated steel drum production spanning multiple countries. Schoeller Allibert Services B.V. sustains leadership in reusable folding bulk containers through dense service networks in Benelux and Germany. Basca Srl occupies a specialist position, leveraging its Italian manufacturing base to capture high-performance plastic drum exports across Southern Europe.
| Leading Market Players |
|---|
| Basca Srl |
| Martin Contenedores Para Logística S.L. |
| ORBIS Corporation |
| ALPLA Group |
| Schutz GmbH & Co. |
| Schoeller Allibert Services B.V. |
| Obal Centrum S.R.O. |
| Tank International S.R.L. |
| Greif Inc. |
| Others |
Pricing and Supply Chain Analysis
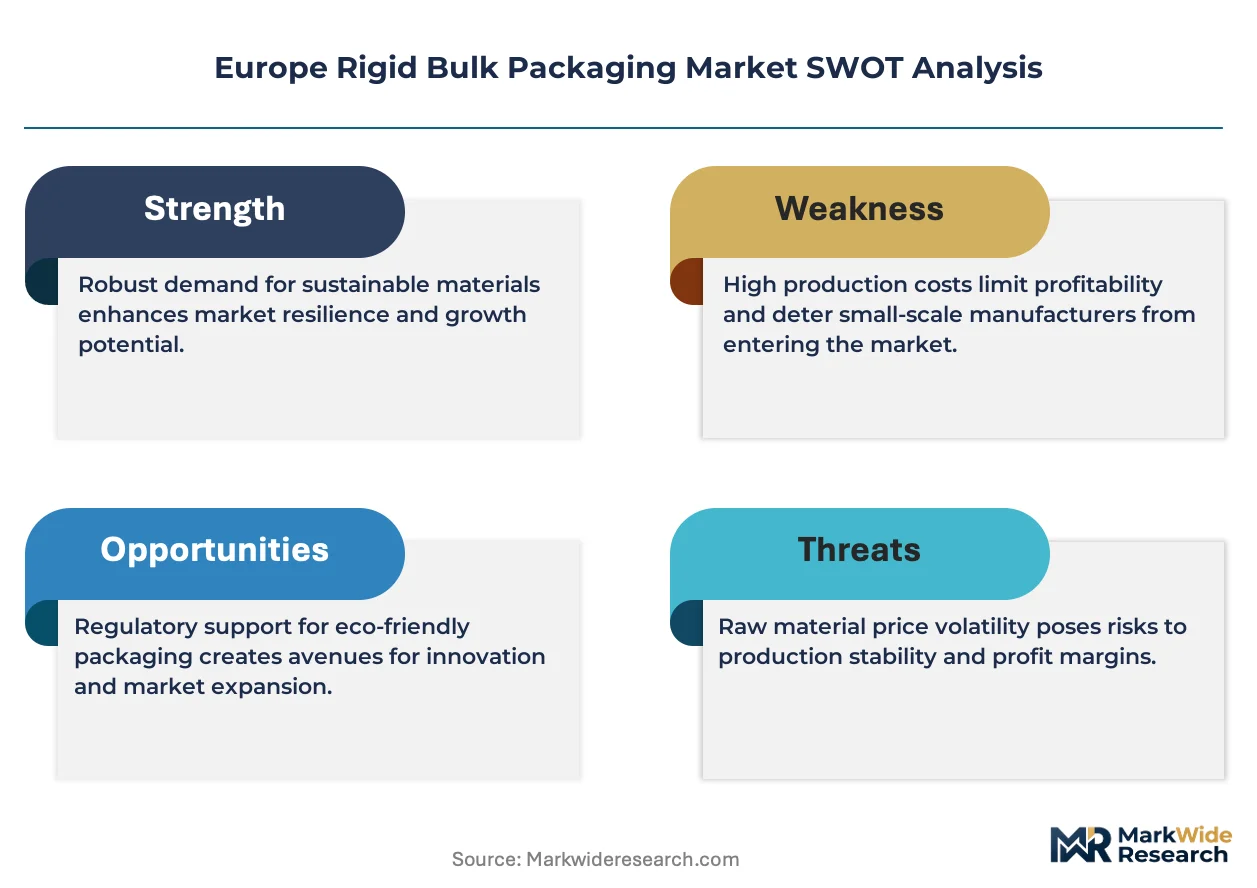
EU Green Deal carbon intensity thresholds gate qualified supply and premium-tier pricing access for rigid bulk packaging producers. REACH substance restrictions and ECHA evaluations further stratify the market, with compliant polymer alternatives commanding price premiums over legacy coated steel drums in German and French chemical corridors.
Pricing Analysis
The bundled-vs-unbundled service split defines pricing architecture across the European rigid bulk packaging sector. Container-as-a-service models with reverse logistics and washing cycles command 15-25% premiums over transactional unit sales, with price differentiation anchored in certification grade and geographic service density. Cost compression in commodity-grade steel drums intensifies as Eastern European producers absorb energy cost disparities. Small-scale agricultural buyers in France and Italy exhibit highest price sensitivity, while pharmaceutical distributors in Germany and the United Kingdom prioritize performance guarantees over unit economics.
Supply Chain Analysis
Workforce availability in polymer science and container engineering concentrates manufacturing gravity in the Rhine-Ruhr corridor and Benelux zones. HDPE resin supply draws from naphtha and natural gas feedstock markets centered on Rotterdam and Antwerp petrochemical complexes. Single-source vulnerability permeates UN-certified steel drum production clustered in Eastern European manufacturing zones. Distribution runs through third-party logistics integrators operating dense service networks across Germany, France, and the Netherlands.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The European rigid bulk packaging market functions as a regulatory compounder, with Packaging and Packaging Waste Regulation reuse targets driving demand concentration among early-compliant service networks.
For Market Incumbents: Cement defensive positioning through captive recycling infrastructure investments in Germany and France. ECHA substance evaluation timelines threaten coated steel drum incumbents; backward integration into post-consumer polymer sorting and reprocessing secures qualified feedstock access. Capacity expansion in Benelux service territories captures chemical producer procurement consolidation around per-use pricing models. For New Entrants and Emerging Players: RFID-enabled fleet tracking platforms offer technology-first wedge into asset-light pooling models. Southern European pharmaceutical cold chain segments remain penetrable due to F-Gas Regulation compliance barriers favoring specialized regional producers. Direct contracting with Dutch horticulture exporters for collapsible crate subscriptions bypasses incumbent OEM relationships. For Investors and Strategic Acquirers: Roll-up economics work for mid-tier fleet operators because fragmented national service networks lack scale to meet EU Green Deal reuse mandates. Five-to-ten year viability hinges on EPR scheme consolidation and carbon border adjustment implementation. Watch ECHA substance evaluation backlogs as inflection indicator for polymer substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Recyclate Sourcing | Captive HDPE feedstock secures REACH-compliant resin supply for German chemical container producers. |
| Digital Fleet Tracking Platform Launch | RFID and blockchain custody records enable subscription pricing models with logistics integrators in Benelux. |
| Southern European Service Network Expansion | Underpenetrated pharmaceutical cold chain markets in Italy and Spain offer first-mover reuse service advantages. |
| Electric Arc Furnace Feedstock Transition | Steel drum producers source scrap-based inputs to meet EU Green Deal carbon intensity thresholds for UK buyers. |
| Co-extruded Barrier Technology Licensing | Dutch specialty chemical distributors adopt multi-layer HDPE constructions eliminating liner replacement costs. |
Research Methodology
Coverage spans Western, Central, and Southern Europe, with primary inputs from each regional cluster. The research combines structured interviews with container fleet managers, chemical procurement leads, third-party logistics operators, and ECHA regulatory affairs specialists with secondary validation from customs trade data, Cefic chemical industry reports, SEC filings of listed packaging producers, and EU regulatory databases. Bottom-up volume modeling triangulates against top-down macroeconomic indicators.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions include material type, container geometry, end-use industry, and regional regulatory cluster. CAGRs derive from historical trajectory analysis adjusted for policy intervention intensity and technology substitution curves. Forecast inputs incorporate REACH substance evaluation timelines and EPR scheme implementation schedules.
The model holds under stable regulatory enforcement and feedstock supply continuity; deviation in ECHA evaluation acceleration or HDPE resin cost volatility would shift volume and value trajectories. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Rigid Packaging
France Rigid Plastic Packaging Market
Rigid Packaging
Indonesia Rigid Plastic Packaging Market
Rigid Packaging
Reclosable Rigid Containers Market
Rigid Packaging
Mexico Rigid Plastic Packaging Market
Rigid Packaging
Poland Rigid Plastic Packaging Market
Rigid Packaging
Latin America Rigid Plastic Packaging Market
Rigid Packaging
North America Airless Packaging Market
Rigid Packaging
Morocco Rigid Plastic Packaging Market
Rigid Packaging
Mexico Rigid Packaging Market
Rigid Packaging
Rigid Plastic Packaging Market
Rigid Packaging
India Rigid Plastic Packaging Market
Rigid Packaging
Mono-Material Trays Market
Rigid Packaging
Europe Rigid Plastic Packaging Market
Rigid Packaging
Nutraceutical Rigid Packaging Market
Rigid Packaging
Luxury Rigid Box Market
Rigid Packaging
Australia and New Zealand Rigid Plastic Packaging Market