
 HDPE Containers Market | 2026-2036
HDPE Containers Market Size, Share, and Industry Trends Forecast 2026-2036
HDPE Containers Market Outlook
Direct procurement channels between resin converters and end-use brand owners is rewriting how HDPE container contracts are negotiated and fulfilled. Berry Global Inc. leverages its North American blow-molding footprint to sustain long-term supply agreements with beverage multinationals. Graham Packaging Company anchors its position through captive recycling operations that lower virgin resin exposure. Alpla Group competes by specializing in lightweighting technologies that reduce material intensity per container.
HDPE containers are blow-molded or injection-molded vessels fabricated from high-density polyethylene resin, typically graded between 0.941 and 0.965 g/cm³ density, engineered to resist chemical permeation and mechanical stress across temperatures from -50°C to 110°C. Their primary commercial purpose is the safe containment, transport, and shelf-stable storage of liquid and semi-solid products in industrial and consumer supply chains. Bottles command the largest volume share within product type segmentation, though totes generate superior margin pools per unit in chemical and agricultural bulk applications. Food and Beverage end-use demand leads absolute consumption, while Pharmaceuticals applications exhibit the fastest structural growth due to stringent barrier-property requirements and serialization compliance.
FDA food-contact regulations and EPA hazardous materials packaging standards govern HDPE container specifications in the United States, with California's SB 54 extended producer responsibility law adding state-level recycled-content mandates that reshape converter procurement. The EU REACH regulation and F-Gas Regulation indirectly influence HDPE demand by restricting alternative container materials in certain chemical and refrigerant applications. Stakeholders must monitor evolving extended producer responsibility frameworks and resin recycling certification schemes to secure compliant feedstock access and defend market positioning.
Market Dynamics
The EU Single-Use Plastics Directive is compressing virgin resin demand and forcing converters to reengineer supply chains around mechanically recycled feedstock. This regulatory compression is reshaping contract structures, capital allocation, and competitive positioning across the entire HDPE container value chain.
Growth Catalysts
- Extended Producer Responsibility Mandates:California's SB 54 and the EU Single-Use Plastics Directive are creating legal pull-through for post-consumer recycled HDPE. Brand owners must now secure certified recycled content to maintain shelf access.
- Dairy and Juice Packagers:Food and beverage processors are specifying HDPE for extended-shelf-life applications. Barrier-enhanced grades now compete with multilayer PET in cold-chain distribution.
- Lightweighting Technologies:Advanced blow-molding controls are reducing wall thickness without sacrificing top-load strength. Material intensity per container is falling 8-12% in leading converter operations.
Market Restraints
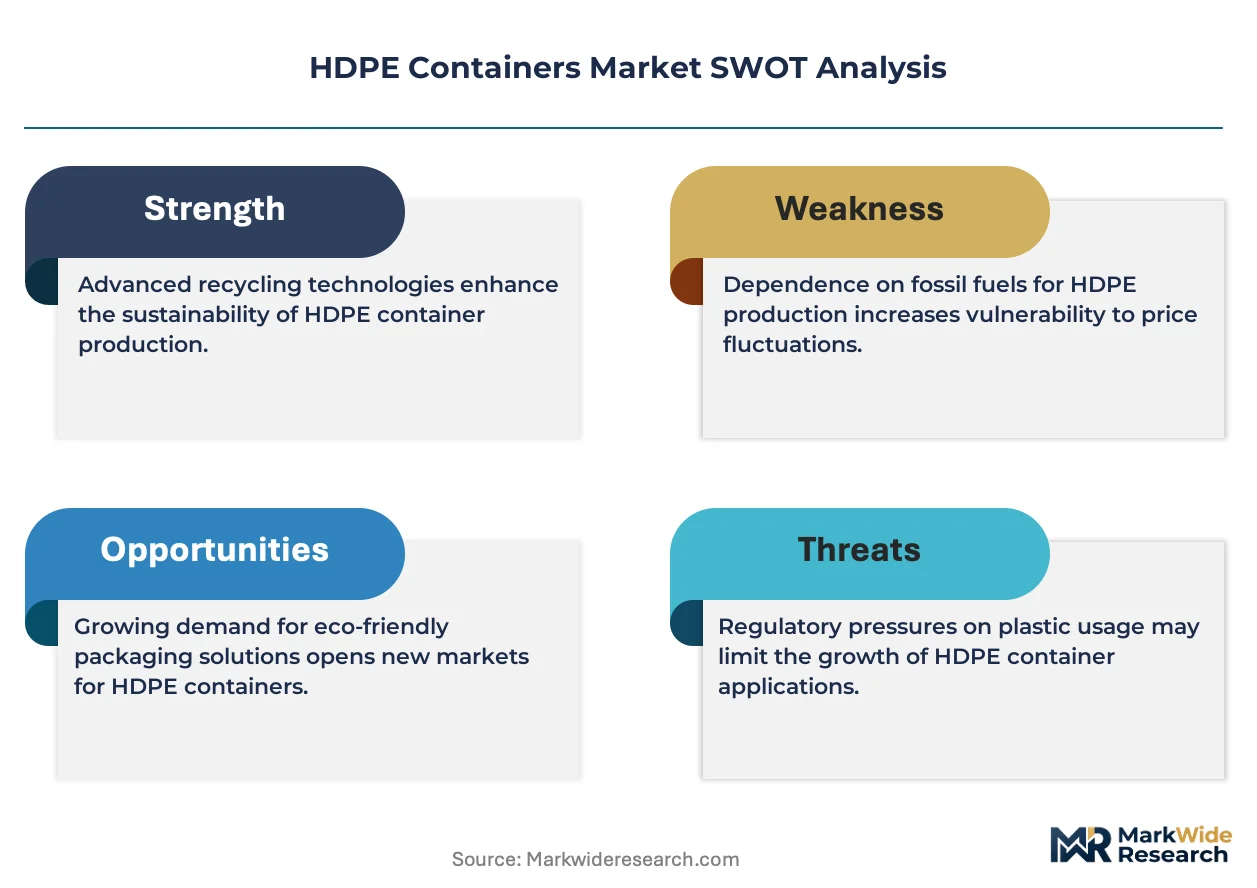
- Feedstock Cost Volatility:Naphtha and natural gas liquids pricing swings directly compress converter margins. Virgin HDPE resin contracts remain indexed to ethylene spot markets with limited hedge availability.
- Mechanical Recycling Yield Loss:Contamination in post-consumer bales reduces usable flake output by 15-25%. Sorting infrastructure gaps in North American municipal systems constrain rHDPE availability.
- Multilayer Barrier Substitution:High-barrier EVOH and nylon co-injected containers are displacing monolayer HDPE in oxygen-sensitive pharmaceutical applications. FDA barrier testing protocols favor these alternatives.
Strategic Opportunities
- Chemical Recycling Scale-Up:Pyrolysis and depolymerization investments are creating food-grade recycled resin streams. Converters with offtake agreements will bypass mechanical recycling quality constraints.
- Pharmaceutical Serialization Compliance:EU Falsified Medicines Directive and US DSCSA deadlines are driving demand for HDPE bottles with integrated RFID and tamper-evident closures. This application commands 40-60% premium pricing over commodity food packaging.
- Industrial Bulk Tote Expansion:Agricultural chemical and lubricant distributors are consolidating from drums to IBC totes. HDPE's chemical resistance and UN certification compatibility position it against steel and composite alternatives.
Industry Challenges
- Recycling Certification Complexity:Multiple competing standards—EuCertPlast, RecyClass, and APR Design Guide—create compliance fragmentation. Converters must maintain parallel certification systems to serve different brand owner requirements.
- Blow-Molding Technical Talent Scarcity:Parison programming and multilayer die head maintenance require specialized skills. The workforce pipeline from vocational programs has not kept pace with equipment sophistication.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | HDPE Containers Market |
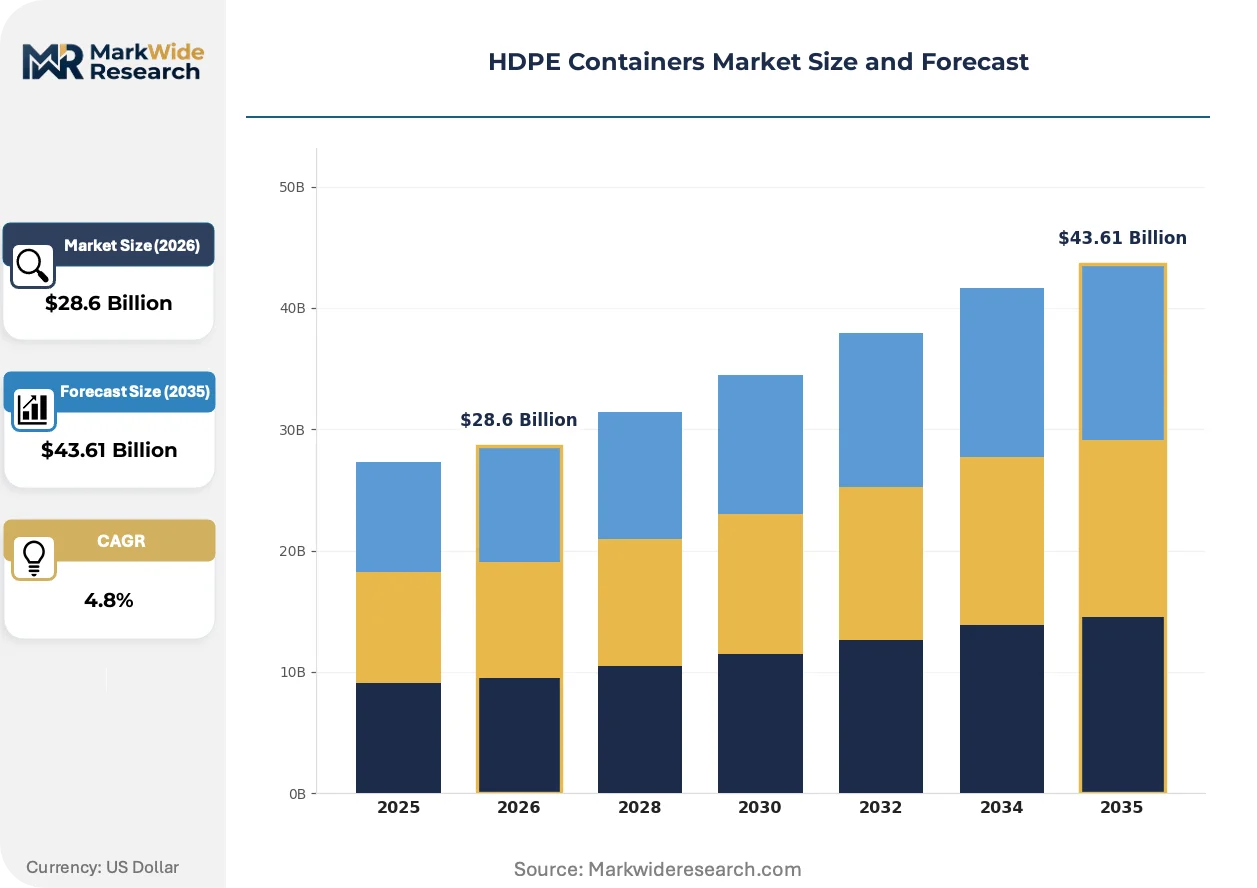
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $43.61 Billion |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Bottles, Jars, Drums, Totes End Use Industry: Food & Beverage, Pharmaceuticals, Chemicals, Agriculture Size: 1L, 5L, 10L, 20L Distribution Channel: Online Retail, Wholesale, Direct Sales, Supermarkets |
| Companies Covered | Amcor Plc, Berry Global Inc., Graham Packaging Company, Alpla Group, Greif Inc., Silgan Holdings Inc., Mauser Packaging Solutions, Sonoco Products Company, Plastipak Holdings Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
HDPE Containers Market Strategic Shifts
Digital manufacturing controls and regulatory pressure on carbon intensity are converging to transform how HDPE containers are specified, produced, and recovered. Three distinct vectors are compressing legacy operational models.
All-electric blow-molding machinery is collapsing energy consumption per unit while tightening dimensional tolerances. Beverage and dairy packagers in Germany and the Netherlands are replacing hydraulic presses at end-of-life with servo-electric systems. The technology is collapsing the historical trade-off between production speed and wall-thickness consistency.
REACH substance restrictions on per- and polyfluoroalkyl substances are eliminating fluorinated HDPE barrier treatments from EU food-contact applications. Converters must pivot to plasma coating or multilayer coextrusion to maintain oxygen and moisture barriers. Pharmaceutical and agrochemical segments are most affected, with reformulation timelines compressed by the 2025 enforcement horizon.
Direct resin converter-to-brand-owner contracting is fragmenting the distributor channel. Large beverage and personal care multinationals are establishing multi-year volume commitments in exchange offtake priority and price caps. This behavior is most visible in North America and Western Europe, where procurement functions have consolidated supplier panels to fewer than five approved converters per region.
HDPE Containers Market Segmentation
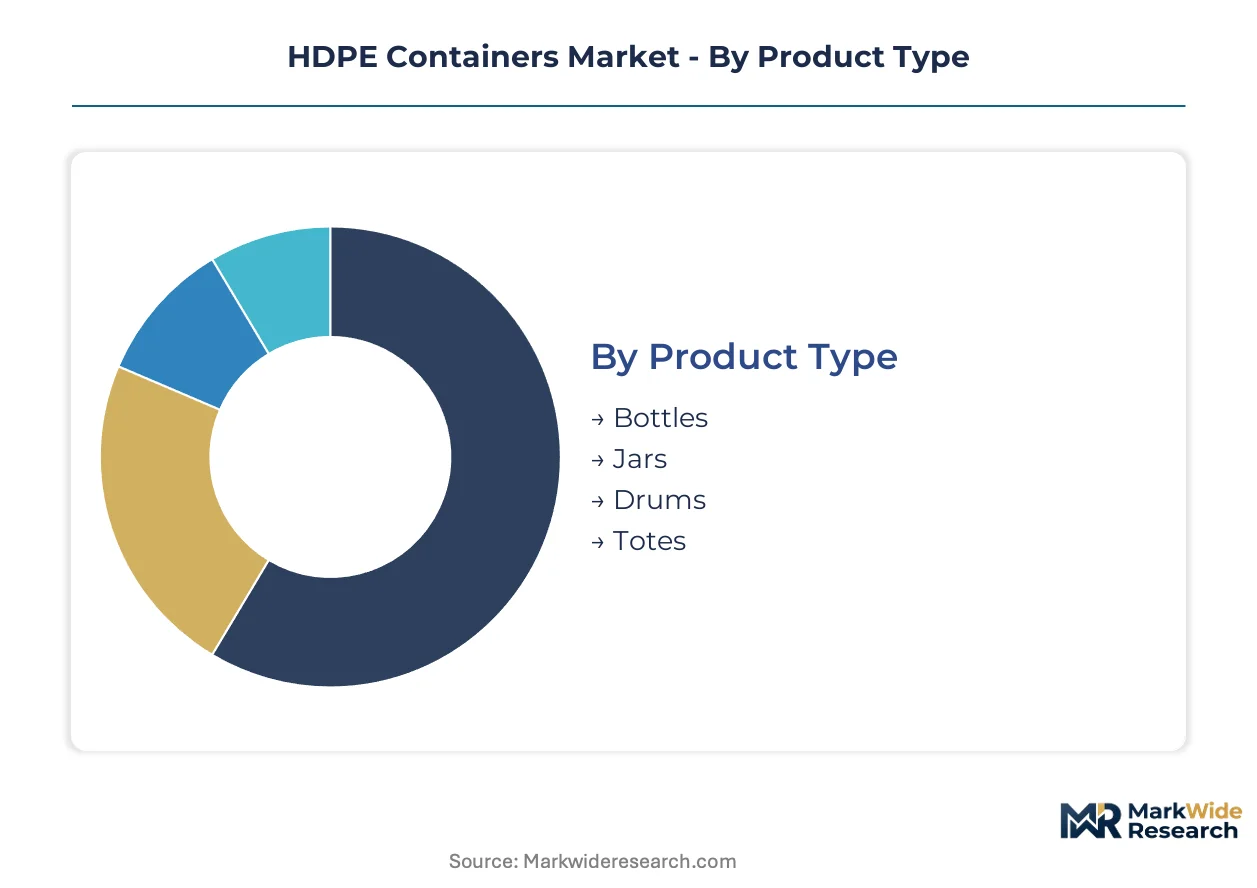
HDPE container procurement decisions cascade through multiple technical and commercial dimensions. Product geometry, end-use regulatory exposure, volume scale, and channel economics each reshape converter capabilities and margin structures differently.
Product Type:
Mature blow-molding formats dominate absolute volume, while emerging tote configurations are capturing value share in bulk chemical handling.
- Bottles:Narrow-neck blow-molded vessels ranging from 100ml to 5 liters, engineered with controlled wall thickness for top-load compression resistance. Dairy and juice packagers in Germany's industrial corridor around Cologne specify these for extended-shelf-life applications requiring oxygen barrier compliance.
- Totes:Intermediate bulk containers from 500 to 1,500 liters, fabricated via rotational or blow molding with UN certification for hazardous material transport. Agricultural chemical distributors in the Netherlands are consolidating drum fleets into these formats for reduced handling cost per liter.
- Jars:Wide-mouth containers with threaded closures, typically 250ml to 4 liters, serving personal care and food spreads. French cosmetics brand owners specify these for cream and gel formulations requiring finger-access scooping.
- Drums:Cylindrical vessels from 30 to 220 liters, produced via extrusion blow molding with reinforced chime rings for stacking strength. German lubricant blenders specify these for factory-to-workshop bulk distribution.
Bottles retain volume leadership; totes hold the steepest expansion curve.
End Use Industry:
Regulatory intensity separates cost-tier positioning across applications, with compliance burden directly mapping to pricing power.
- Food & Beverage:Cold-chain dairy and juice applications specify barrier-enhanced HDPE grades competing with multilayer PET. FDA food-contact regulations and EU REACH substance restrictions govern resin selection and additive packages.
- Pharmaceuticals:Serialization-compliant bottles with tamper-evident closures and RFID integration for EU Falsified Medicines Directive compliance. This segment commands substantial premium pricing over commodity packaging due to validation documentation requirements.
- Chemicals:Industrial solvents and agrochemical formulations requiring UN-certified containment and chemical permeation resistance. EPA hazardous materials packaging standards and EU CLP regulation dictate wall thickness and closure specifications.
- Agriculture:Fertilizer and pesticide containers exposed to UV degradation and mechanical field handling. Italian and Spanish distributors specify these for olive oil and vineyard chemical applications.
Food & Beverage retains volume leadership; Pharmaceuticals holds the steepest expansion curve.
Size:
Volume scale determines manufacturing process selection and logistics economics across the specification range.
- 1L:Single-serve beverage and personal care applications, blow-molded on high-cavity all-electric machinery. German dairy processors specify these for on-the-go consumption formats.
- 5L:Household cleaning and automotive fluid containers, balancing retail shelf presence with handling ergonomics. French hypermarket chains stock these as private-label standards.
- 10L:Professional-grade chemical and food service applications, requiring reinforced handles and stacking geometry. Dutch industrial cleaning suppliers specify these for commercial kitchen contracts.
- 20L:Bulk institutional and light industrial use, produced via accumulator head blow molding for thicker wall sections. German automotive workshops specify these for coolant and washer fluid dispensing.
1L retains volume leadership; 20L holds the steepest expansion curve.
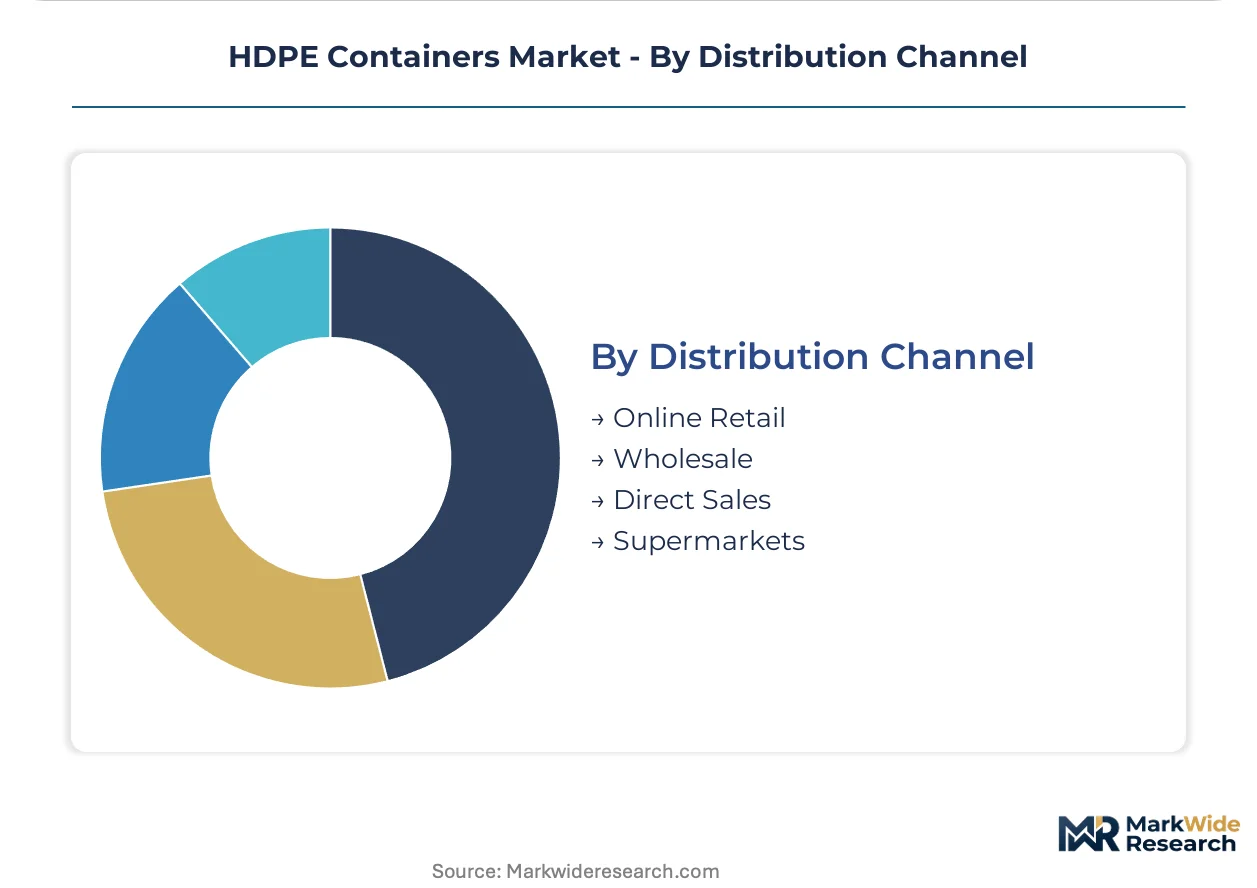
Distribution Channel:
Channel configuration determines converter customer intimacy requirements and working capital intensity.
- Direct Sales:Long-term supply agreements between resin converters and beverage multinationals, bypassing distributor margins. Berry Global leverages this channel for North American beverage contracts with volume commitments and price caps.
- Wholesale:Industrial packaging distributors serving fragmented chemical and agricultural end-users. German distributors around Düsseldorf maintain regional stockholding for just-in-time drum and tote delivery.
- Online Retail:E-commerce platforms for small-batch specialty and replacement container procurement. Italian pharmaceutical contract manufacturers source serialized bottles through validated digital channels.
- Supermarkets:Mass retail shelf placement for consumer-facing food, beverage, and household product containers. French and German retail consolidation has reduced approved supplier panels to fewer than five converters per region.
Wholesale retains volume leadership; Direct Sales holds the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Extended producer responsibility mandates across multiple jurisdictions are redirecting converter investment toward post-consumer recycled feedstock infrastructure and certified recycling certification schemes.
United States
California's SB 54 recycled-content mandates are forcing beverage and personal care brand owners to secure certified rHDPE supply chains. FDA food-contact regulations and EPA hazardous materials packaging standards govern container specifications, with state-level EPR laws adding compliance fragmentation. The Midwest industrial corridor around Chicago anchors blow-molding capacity serving dairy processors and automotive fluid packagers.
Germany
The EU Single-Use Plastics Directive is compressing virgin resin demand and accelerating mechanical recycling infrastructure deployment. REACH substance restrictions on per- and polyfluoroalkyl substances are eliminating fluorinated barrier treatments from food-contact applications by 2025. The industrial packaging corridor around Cologne and Düsseldorf concentrates converter operations serving chemical distributors and lubricant blenders.
China
Dual carbon goals and provincial plastic pollution action plans are tightening virgin resin utilization in packaging applications. SAMR national standards and GB food-contact material regulations govern HDPE container specifications for domestic and export markets. The Yangtze River Delta manufacturing cluster around Shanghai anchors blow-molding capacity serving beverage multinationals and agrochemical exporters.
India
Extended producer responsibility frameworks under PWM Rules are creating compliance obligations for plastic packaging producers. FSSAI food-contact regulations and BIS standards govern container specifications for domestic dairy and edible oil applications. The Gujarat industrial corridor around Ahmedabad concentrates converter operations serving pharmaceutical contract manufacturers and agrochemical formulators.
Brazil
National solid waste policy implementations are establishing post-consumer collection targets for rigid plastic packaging. ANVISA pharmaceutical packaging regulations and CONAMA environmental standards govern container specifications for healthcare and chemical applications. The São Paulo state manufacturing belt anchors blow-molding capacity serving personal care multinationals and agricultural chemical distributors.
HDPE Containers Market Competitive Environment
On the supply side, the industry is consolidating around integrated converters with captive recycling operations and long-term resin offtake agreements. The vendor base stratifies into three tiers: multinational packaging conglomerates with continental manufacturing footprints, regional specialists with vertical integration into recycling streams, and contract manufacturers serving niche pharmaceutical and agrochemical specifications. Dominant competitive moves include strategic partnerships for chemical recycling offtake and geographic expansion through distributor channel acquisition.
Among North American packaging conglomerates, Berry Global Inc. and Graham Packaging Company exemplify scale-driven positioning through continental blow-molding footprints. Alpla Group represents the European specialist archetype with concentrated technical capabilities in lightweighting and barrier engineering. These three entities anchor the competitive structure by demonstrating how converter scale and recycling integration reshape contract negotiation leverage with beverage and personal care multinationals.
| Leading Market Players |
|---|
| Amcor Plc |
| Berry Global Inc. |
| Graham Packaging Company |
| Alpla Group |
| Greif Inc. |
| Silgan Holdings Inc. |
| Mauser Packaging Solutions |
| Sonoco Products Company |
| Plastipak Holdings Inc. |
| Others |
Value Chain & Pricing Dynamics
Feedstock cost volatility in ethylene and naphtha markets compresses converter margins while simultaneously widening spreads between virgin and recycled-content HDPE tiers, forcing procurement functions to restructure long-term contracting around indexed resin clauses and certified recycling certification schemes.
Pricing Analysis
Certification level (EuCertPlast/RecyClass/ISCC-PLUS) creates the primary spread between premium and commodity HDPE containers. Three-tier pricing structure across pharmaceutical-grade, food-contact certified, and industrial-standard levels dominates contract negotiations. Cost compression in food-contact grades is intensifying because mechanical recycling yield losses constrain rHDPE availability. Pharmaceutical packagers exhibit lowest price sensitivity due to validation documentation requirements, while agricultural distributors face acute margin pressure from spot resin exposure.
Supply Chain Analysis
Upstream naphtha and natural gas liquids pricing draws from Gulf Coast petrochemical complexes, Middle Eastern feedstock exporters, and European refinery output. Virgin HDPE resin production rests on ethylene cracker operations concentrated in the United States, Germany, and China. Single-source vulnerability in post-consumer bale supply constrains rHDPE scale-up. Distribution runs through direct converter-to-brand-owner channels for beverage multinationals and wholesale industrial distributors for fragmented chemical end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
HDPE container procurement is approaching a platform-economics inflection where recycling certification interoperability between EuCertPlast, RecyClass, and APR standards will determine converter access to multinational brand owner supplier panels.
For Market Incumbents: Pre-empt mechanical recycling quality constraints by securing chemical recycling offtake agreements with pyrolysis operators before feedstock competition intensifies. Backward integration into post-consumer collection infrastructure in Germany's industrial corridor around Cologne and Düsseldorf anchors long-term rHDPE supply security against emerging entrant disruption. For New Entrants and Emerging Players: Pharmaceutical serialization-compliant bottles with integrated RFID and tamper-evident closures represent the most penetrable entry point, commanding substantial premium pricing over commodity packaging. Targeting Indian pharmaceutical contract manufacturers through validated digital procurement channels offers lower incumbent saturation than North American or Western European markets. For Investors and Strategic Acquirers: California's SB 54 and EU Single-Use Plastics Directive enforcement horizons reshape the acquisition landscape toward converters with captive recycling operations and multi-certification compliance systems. Five-to-ten-year viability favors regional specialists with demonstrated mechanical recycling yield optimization and established brand owner offtake relationships. The signal to watch is chemical recycling project FID announcements altering rHDPE supply-demand balance.| Strategic Initiative | Industry Significance |
|---|---|
| Chemical Recycling Offtake Agreement | Secures food-grade rHDPE streams bypassing mechanical yield constraints for EU compliance. |
| Lightweighting Technology Investment | Reduces material intensity per container by 8-12% while maintaining UN certification standards. |
| Multi-Certification Compliance System | Enables parallel EuCertPlast, RecyClass, and APR qualification for diverse brand owner requirements. |
| Direct Brand Owner Contracting | Bypasses distributor margins through multi-year volume commitments with price caps. |
| All-Electric Blow-Molding Conversion | Collapses energy consumption per unit while tightening dimensional tolerances for dairy applications. |
Study Parameters
The analysis maps blow-molded bottles, intermediate bulk totes, wide-mouth jars, and industrial drums, each validated through procurement directors at beverage multinationals, sustainability officers at personal care brand owners, technical managers at resin converters, and regulatory affairs leads at pharmaceutical packagers. Primary interview findings triangulate against customs and trade data, SEC 10-K filings, EuCertPlast certification registries, and extended producer responsibility compliance reports. Bottom-up unit economics and top-down sector sizing converge through iterative stakeholder cross-checking.
Assumptions held fixed include current EU Single-Use Plastics Directive enforcement timelines and existing mechanical recycling yield parameters, while chemical recycling commercialization rates and naphtha price volatility scenarios were varied across sensitivity runs. Segmentation modeling spans product geometry, end-use regulatory intensity, volume scale tiers, and distribution channel configuration. CAGRs derive from weighted average growth across these dimensions, with resin price indexing and recycling infrastructure deployment pace as key HDPE-specific forecast inputs.
Practitioners should monitor pyrolysis project commissioning delays and post-consumer bale contamination rate trends for early signals requiring forecast revision. Cross-checking against EuCertPlast and RecyClass certification issuance volumes is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Jug Shipper Market
Containers
Reconditioned IBC Market
Containers
USA and Canada Packer Bottle Market
Containers
Mini Spray Bottles Market
Containers
Wet Wipes Canister Market
Containers
Slide Top Tins Market
Containers
ISO Container Market
Containers
Wide Mouth Jars Market
Containers
EPS Container Market
Containers
Container Stacking Machine Market
Containers
Trays Market
Containers
Multi-Layer Blow Molded Containers Market
Containers
Global Styrene Compartment Boxes Market
Containers
High Density Polyethylene (HDPE) Bottles Market
Containers
Clear Hinged Container Market
Containers
Packaging Bins Market