
 Disposable Lids Market | 2026-2036
Disposable Lids Market Size, Share, and Industry Trends Forecast 2026-2036
Disposable Lids Market Outlook
Chinese molded-fiber capacity expansion is recalibrating competitive dynamics across Asian supply chains. Huhtamäki leverages its European fiber-forming expertise to anchor premium sustainable lid positions in Western markets. Berry Global sustains polymer-based economies of scale while navigating biopolymer transitions across North American dairy and beverage accounts.
Disposable lids are thermoformed or injection-molded closures manufactured from polypropylene, polystyrene, molded fiber, or coated paperboard, designed to seal beverage cups and food containers against spillage and thermal loss while enabling straw or sip-port functionality. Plastic lids still occupy the largest volume share due to cost parity and existing thermoforming infrastructure, though biodegradable segments are gaining fastest as composting certification becomes a procurement gate for national foodservice chains. Medium and large sizes dominate quick-service and delivery applications, while small lids retain niche strength in specialty coffee shops.
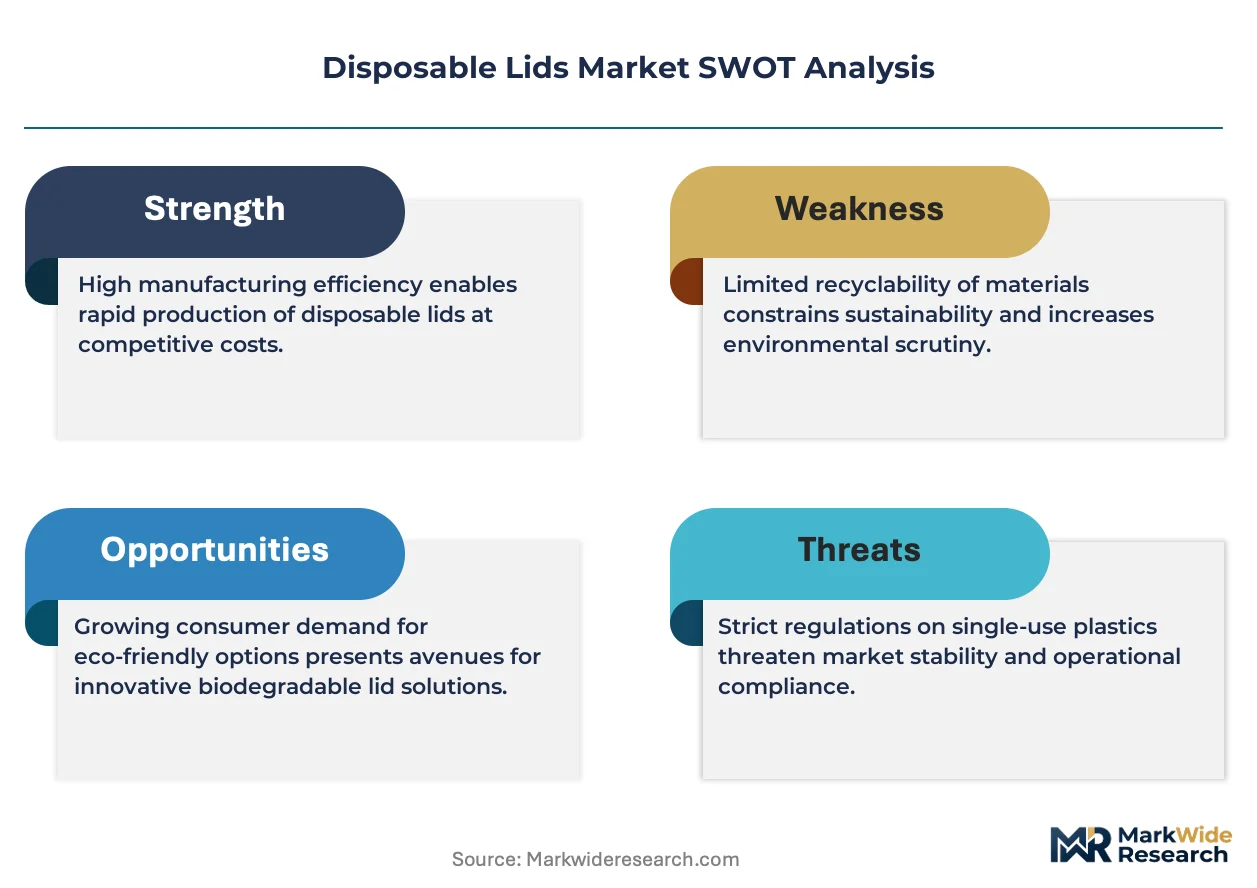
FDA food-contact regulations govern polymer migration limits in the United States, while EFSA and the EU Single-Use Plastics Directive constrain conventional plastic deployment across European foodservice. BIS certification requirements in India and China's GB standards for food-contact materials create layered compliance thresholds for exporters entering these markets. Stakeholders must monitor evolving extended producer responsibility frameworks and substrate-specific composting standards to align capacity investments with regulatory trajectories.
Market Dynamics
The EU Single-Use Plastics Directive is compressing polymer lid margins while redirecting capital toward molded-fiber thermoforming lines across European converting facilities.
Growth Catalysts
- Delivery-format proliferation:Quick-service restaurants in India are scaling lid procurement as organized chains penetrate tier-two cities and cloud kitchens multiply.
- Composting certification mandates:National foodservice chains in Western Europe now require BPI or OK Compost certification as a procurement gate, accelerating fiber-based substrate adoption.
- Polypropylene cost parity:Existing thermoforming infrastructure for PP lids sustains volume share in North American dairy and beverage accounts despite sustainability pressures.
Market Restraints
- Pulp input cost volatility:Bleached kraft pulp prices swing with energy and logistics costs, compressing molded-fiber lid margins unpredictably.
- Chinese supply concentration:Molded-fiber capacity expansion in Zhejiang and Guangdong provinces creates dependency risk for Western converters sourcing finished lids or semi-finished fiber blanks.
- Polymer migration limits:FDA food-contact regulations and EFSA thresholds constrain formulation flexibility for conventional plastic lids, extending R&D timelines.
Strategic Opportunities
- Indian tier-two penetration:Organized foodservice chains expanding into secondary Indian cities generate fresh demand for medium-format lids with sip-port functionality.
- Extended producer responsibility frameworks:EPR schemes rolling out across EU member states create first-mover advantage for fiber-lid producers with verified end-of-life pathways.
- Barrier coating convergence:Integration of aqueous and PLA barrier coatings with fiber-forming lines enables hot-beverage applications previously reserved for plastic lids.
Industry Challenges
- Composting infrastructure gaps:Industrial composting facility scarcity in the United States and parts of Asia-Pacific undermines the value proposition of certified fiber lids.
- Thermoformer retooling costs:Converting legacy PS and PP lines to fiber-compatible presses demands capex outlays that mid-tier converters struggle to finance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Disposable Lids Market |
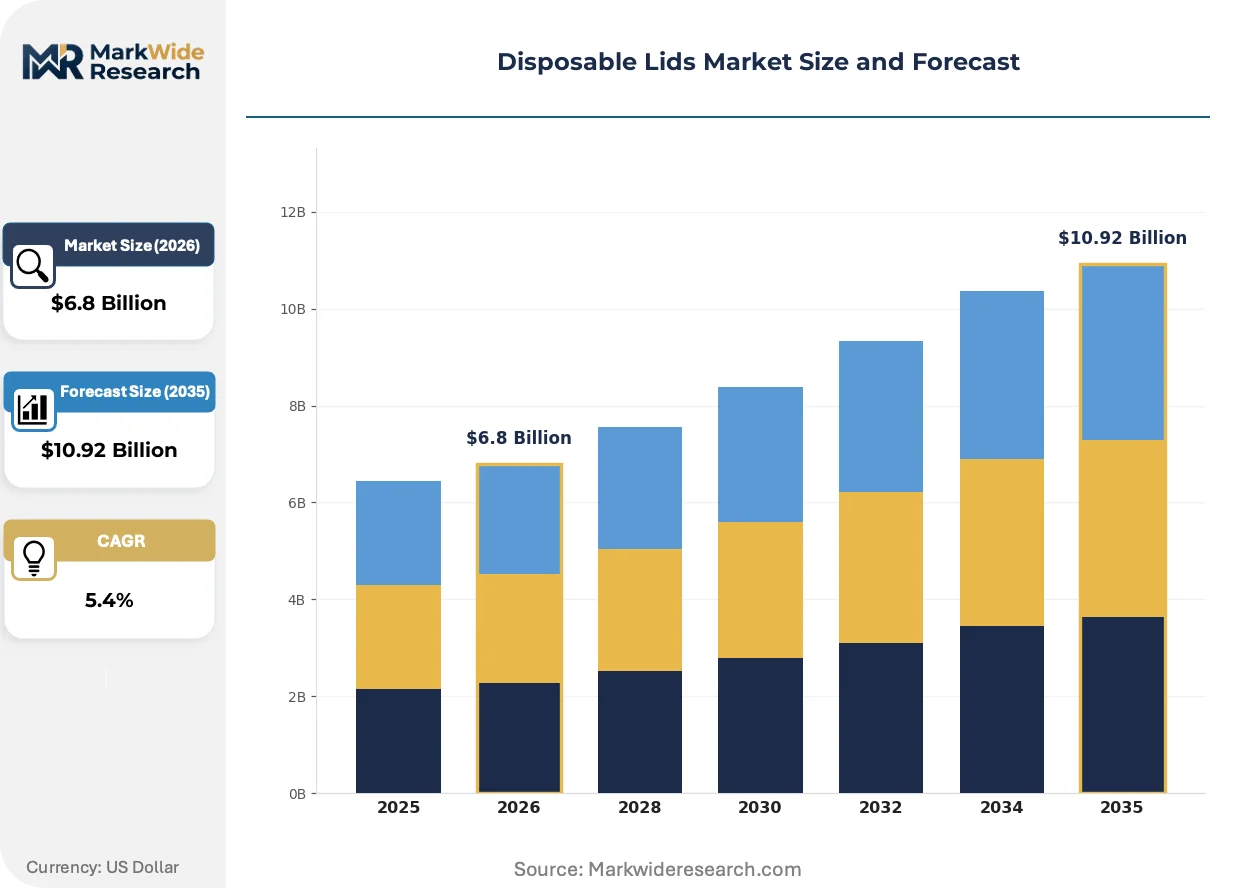
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.92 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: Plastic, Paper, Foam, Biodegradable Size: Small, Medium, Large, Extra Large End User: Restaurants, Cafes, Fast Food Chains, Catering Services Shape: Round, Square, Oval, Rectangle |
| Companies Covered | Berry Global, Huhtamäki, Dart Container Corporation, Pactiv Evergreen, Genpak, Sabert Corporation, Amcor, Greiner Packaging India Pvt Ltd, Airlite Plastics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Disposable Lids Market Strategic Shifts
Material science advances and regulatory compression are converging to redefine lid performance standards and manufacturing economics across foodservice supply chains.
Molded-fiber thermoforming with integrated aqueous barrier coatings is rewriting the competitive map for hot-beverage lid applications. Quick-service chains in Germany and France are piloting these lids at scale for coffee and tea programs. The technology is compressing the addressable market for conventional polypropylene lids in premium beverage segments where heat retention and leak resistance matter.
REACH restrictions on microplastics and the EU Single-Use Plastics Directive are forcing reformulation across European lid supply chains. Conventional polystyrene lids face phase-out timelines in multiple member states, redirecting R&D spend toward fiber and biopolymer alternatives. Dairy and ready-meal segments in the Netherlands and Belgium are responding fastest, with private-label retailers demanding substrate switches ahead of regulatory deadlines.
Consolidated procurement by national foodservice chains is squeezing regional converter margins and favoring suppliers with multi-plant fiber capacity. Large buyers in the United States and United Kingdom are unbundling lid sourcing from cup contracts, creating standalone bidding events that reward scale and certification depth. This pattern concentrates volume with thermoformers capable of delivering BPI-certified fiber lids at million-unit weekly scale.
Disposable Lids Market Segmentation
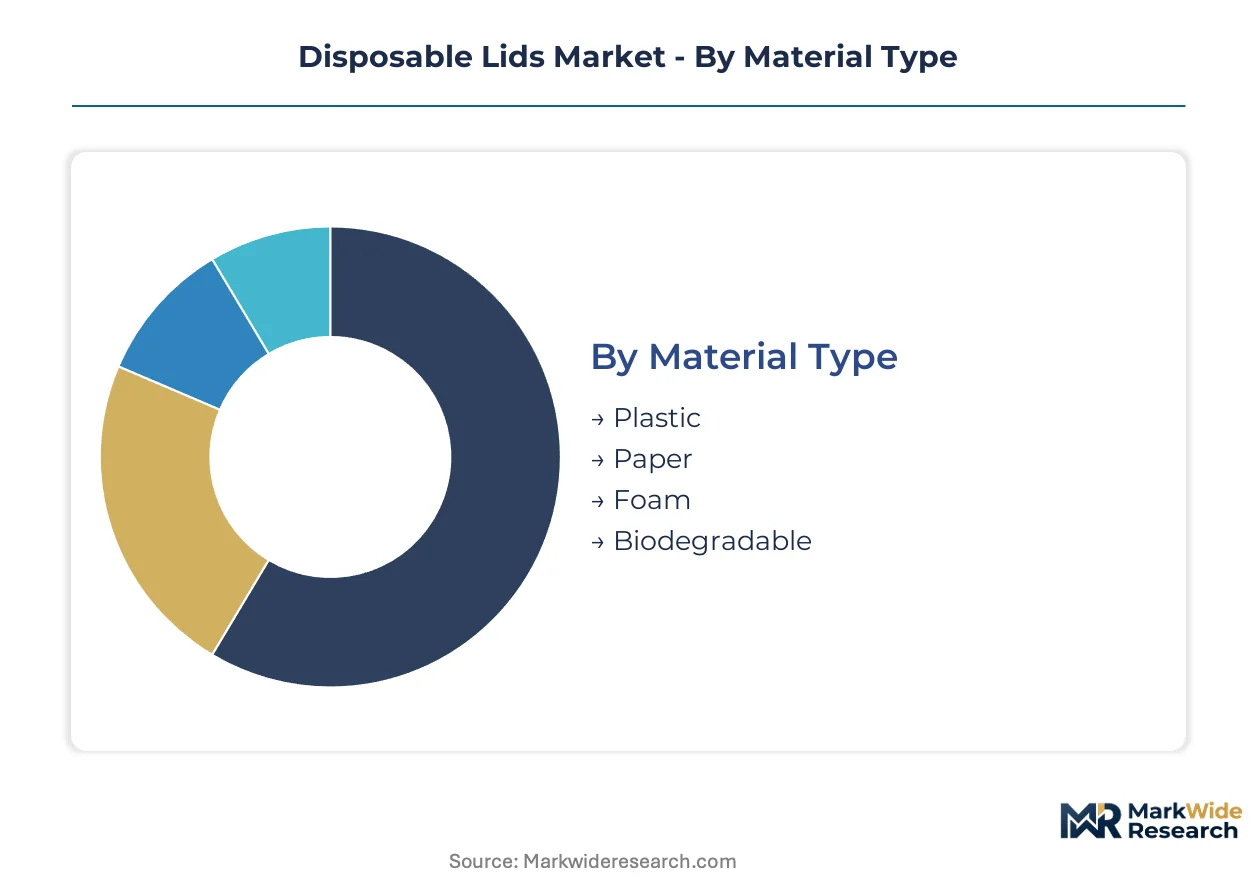
Segmentation in disposable lids reveals how material science, format specifications, and end-use requirements create distinct procurement clusters. Each dimension carries different margin profiles and regulatory exposure, shaping where converters invest capacity and how buyers consolidate sourcing.
Material Type:
Upgrade cycles from conventional polymers to fiber-based and certified compostable substrates are compressing legacy material margins while rewarding early movers with compliant capacity.
- Plastic:Polypropylene and polystyrene formulations dominate existing thermoforming infrastructure across North American dairy and beverage accounts. FDA migration limits constrain formulation flexibility, extending R&D timelines for converters serving quick-service chains.
- Biodegradable:PLA and PHA variants are gaining procurement traction where BPI or OK Compost certification serves as a gate for national foodservice contracts. Demand concentrates in Western European markets where EPR schemes and the EU Single-Use Plastics Directive accelerate substrate switching.
- Paper:Coated paperboard lids serve specialty coffee and premium beverage segments requiring printability and tactile differentiation.
- Foam:Expanded polystyrene retains niche strength in insulated applications despite regulatory phase-out pressures across multiple jurisdictions.
Plastic sits at the top of the volume ranking, with biodegradable climbing the fastest.
Size:
Format dimensions align with beverage category conventions and thermal retention requirements across quick-service and specialty coffee channels.
- Medium:The workhorse specification for quick-service restaurant coffee and fountain beverages, balancing material efficiency with spillage resistance. Procurement scales most aggressively in India as organized chains penetrate tier-two cities.
- Large:Cold-beverage and smoothie applications drive demand where straw-port functionality and structural rigidity matter. Cloud kitchen proliferation in urban India and Southeast Asia expands addressable volume.
- Small:Espresso and specialty coffee formats retain premium positioning in independent cafe channels.
- Extra Large:Bulk beverage and catering formats serve institutional and event-based foodservice with lower frequency but higher per-unit material consumption.
Medium formats command the highest procurement volumes, while large formats are expanding most quickly alongside cold-beverage program growth.
End User:
Customer-type segmentation exposes diverging certification requirements and contract structures across fragmented versus consolidated buying channels.
- Fast Food Chains:Consolidated procurement by national operators creates standalone bidding events for lids unbundled from cup contracts. BPI-certified fiber capacity at million-unit weekly scale wins share as EPR frameworks roll out across EU member states.
- Restaurants:Full-service operators prioritize leak resistance and brand presentation over substrate certification, sustaining polymer lid demand in markets with immature composting infrastructure.
- Cafes:Specialty coffee chains drive sip-port innovation and premium fiber-lid adoption where consumer-facing sustainability credentials support pricing power.
- Catering Services:Event and institutional foodservice favors cost-optimized formats with reliable supply over certification depth.
Fast food chains sit at the top of the volume ranking, with cafes climbing the fastest on sustainability-driven premiumization.
Shape:
Geometric configurations map to cup-mouth standards, stacking efficiency, and brand differentiation requirements across beverage categories.
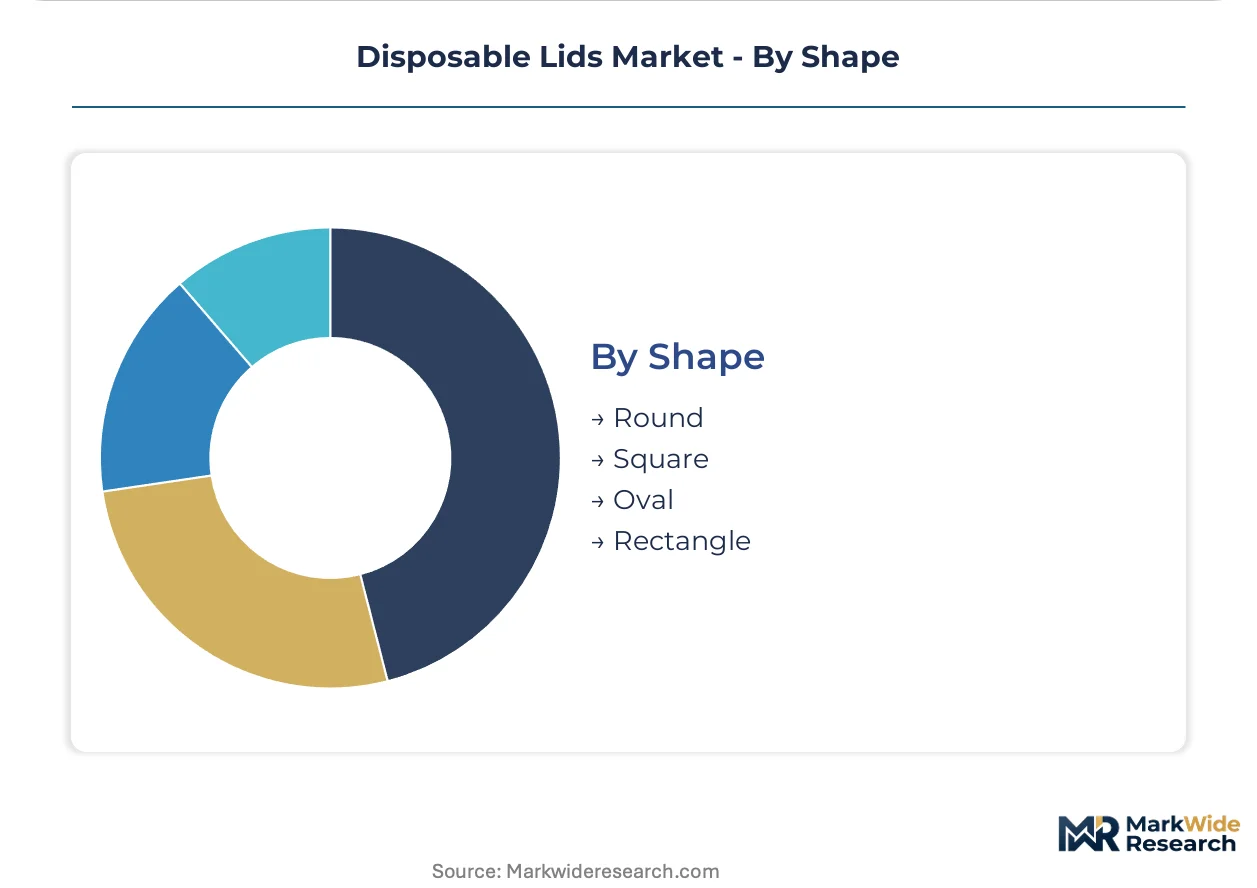
- Round:Universal compatibility with standardized cup diameters makes this the default specification across quick-service and convenience channels. Chinese molded-fiber capacity expansion in Zhejiang and Guangdong provinces supplies Western converters with round-format fiber blanks.
- Square:Differentiated positioning in premium ready-meal and specialty beverage applications where shelf presence and brand blocking matter.
- Oval:Niche strength in frozen dessert and specialty drink formats requiring elongated straw placement.
- Rectangle:Food-container closures for ready-meal and deli applications where lid-cup integration differs from beverage conventions.
Round formats dominate procurement volumes, with square formats gaining share fastest on premium packaging differentiation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are redirecting molded-fiber capacity toward jurisdictions with lower compliance costs while polymer lid production defends legacy positions in markets with mature thermoforming infrastructure. Production migration patterns track divergent EPR implementation timelines and composting certification requirements across national boundaries.
United States
Quick-service restaurant chains unbundle lid procurement from cup contracts, creating standalone bidding events that reward million-unit weekly scale. FDA food-contact regulations constrain polymer migration limits, extending R&D timelines for conventional plastic formulations. Thermoforming clusters in Ohio and Indiana defend polypropylene economies of scale for dairy and beverage accounts.
Germany
REACH restrictions on microplastics and the EU Single-Use Plastics Directive compress polystyrene lid margins while accelerating fiber-substrate adoption. National foodservice chains mandate BPI or OK Compost certification as procurement gates. Converting facilities in Bavaria and North Rhine-Westphalia retool toward molded-fiber thermoforming lines with integrated aqueous barrier coatings.
China
Molded-fiber capacity expansion in Zhejiang and Guangdong provinces recalibrates competitive dynamics across Asian supply chains. GB standards for food-contact materials create layered compliance thresholds for exporters. Fiber-forming clusters in the Yangtze River Delta supply semi-finished blanks to Western converters seeking cost-competitive sustainable substrates.
India
Organized foodservice chains penetrate tier-two cities, scaling procurement for medium-format lids with sip-port functionality. BIS certification requirements govern food-contact material imports, creating compliance barriers for unverified suppliers. Cloud kitchen proliferation in Bangalore and Hyderabad expands addressable volume for large-format cold-beverage applications.
France
EPR schemes rolling out across EU member states create first-mover advantage for fiber-lid producers with verified end-of-life pathways. Dairy and ready-meal segments in the Netherlands and Belgium respond fastest to substrate-switch mandates. Industrial composting infrastructure in the Île-de-France region supports pilot programs for hot-beverage fiber lids at scale.
Disposable Lids Market Competitive Environment
Established producers occupy the standard tier; emerging entrants pursue certified-compostable positioning and barrier-coating integration. The vendor base stratifies across three maturity levels: multinational converters with multi-plant fiber capacity, regional thermoformers defending polymer economies of scale, and specialty entrants commercializing aqueous-coated fiber technologies. Two dominant competitive moves define current dynamics: capacity expansion in molded-fiber thermoforming and strategic partnerships securing pulp supply agreements.
Among diversified packaging conglomerates, Berry Global and Huhtamäki exemplify contrasting strategic archetypes. Berry Global anchors polymer-based scale positions across North American dairy and beverage accounts. Huhtamäki leverages European fiber-forming expertise to secure premium sustainable lid positions in Western markets. Dart Container Corporation occupies a position within the mid-tier thermoforming segment, representing regional converters navigating biopolymer transitions.
| Leading Market Players |
|---|
| Berry Global |
| Huhtamäki |
| Dart Container Corporation |
| Pactiv Evergreen |
| Genpak |
| Sabert Corporation |
| Amcor |
| Greiner Packaging India Pvt Ltd |
| Airlite Plastics |
| Others |
Value Chain & Pricing Dynamics
Molded-fiber thermoforming specialists concentrated in Zhejiang province command wage differentials that widen the spread between premium certified-fiber lids and commodity polypropylene alternatives. Labor-cost arbitrage across Asian converting clusters feeds directly into three-tier pricing structures that separate BPI-certified sustainable grades from standard fiber and legacy plastic formats.
Pricing Analysis
Distributor margins compress most acutely at the mid-tier standard-fiber level where Chinese blank imports compete with European-formed finished goods. Pricing stratifies across premium, standard, and economy tiers based on certification depth and pulp sourcing transparency, with polypropylene formats facing downward pressure from EU Single-Use Plastics Directive compliance deadlines. Quick-service restaurant chains exhibit lowest price sensitivity for certified fiber grades, while institutional catering buyers prioritize unit economics over substrate credentials.
Supply Chain Analysis
Regional distribution centers in Ohio and Bavaria anchor hub-and-spoke patterns that serve quick-service restaurant networks with weekly million-unit replenishment cycles. Supply concentrates in China for molded-fiber blanks, Germany for barrier-coating integration, and the United States for polypropylene thermoforming. Bleached kraft pulp, aqueous barrier coatings, and PLA resin constitute critical input dependencies. Single-source vulnerability runs through Zhejiang fiber-forming clusters where capacity expansion outpaces Western converter retooling. Distribution runs through foodservice broadline distributors and direct OEM contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The disposable lids market functions as a geographic-arbitrage play where EU regulatory compression creates premium pricing power for compliant fiber capacity while Asian manufacturing cost bases defend margin structures. Extended producer responsibility implementation gaps between member states generate sourcing-location advantages.
For Market Incumbents: Extend fiber-forming capacity into Central European converting corridors ahead of EPR scheme full implementation. Anchor polymer-based positions through backward integration into recycled PP feedstock streams. Defend against Chinese blank import erosion by securing exclusive BPI certification pathways with national foodservice chains.
For New Entrants and Emerging Players: Launch via direct-to-cloud-kitchen distribution models bypassing legacy broadline channels. Target Indian tier-two cities where organized chain penetration outpaces local converter capacity. Penetrate the aqueous-coated hot-beverage lid segment where barrier-performance gaps still exclude fiber alternatives from premium coffee applications.
For Investors and Strategic Acquirers: Packaging conglomerates with multi-plant fiber capacity are the most active acquirer in this space, consolidating regional thermoformers to achieve million-unit weekly scale. Long-term viability hinges on composting infrastructure buildout trajectories across target geographies. Monitor industrial composting facility permitting velocity in the United States as the critical inflection signal for certified-fiber lid value proposition durability.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Molded-Fiber Thermoforming | Chinese Zhejiang and Guangdong clusters supply Western converters with cost-competitive sustainable blanks. |
| Backward Integration into Pulp Supply | Bleached kraft pulp agreements with Nordic mills insulate margin compression from energy price volatility. |
| Barrier Coating Technology Licensing | Aqueous and PLA coating integration enables hot-beverage fiber lids previously reserved for polypropylene. |
| Extended Producer Responsibility Compliance | Verified end-of-life pathways create first-mover advantage in EU member states with active EPR frameworks. |
| Direct OEM Contracting | Unbundled lid procurement from cup contracts rewards standalone suppliers with certification depth and scale. |
Study Parameters
Quantitative tracking and qualitative interviews ran in parallel throughout the study window. Primary fieldwork engaged thermoforming plant managers, quick-service restaurant procurement directors, foodservice distributor category buyers, pulp supply specialists, and composting facility operators. Secondary validation drew from FDA food-contact guidance documents, EU Single-Use Plastics Directive implementation reports, BPI certification databases, GB standards filings, and trade customs records for molded-fiber blank movements. Bottom-up capacity assessments and top-down demand modeling were cross-referenced for triangulation.
Segment-weighting applied material type, size format, end-user channel, and regional regulatory cluster as core dimensions across the projection horizon. CAGRs were derived from installed thermoforming capacity trajectories, chain penetration rates in emerging markets, and substrate-switch elasticity coefficients tied to composting infrastructure development. Forecast inputs included pulp price volatility indices, EPR scheme rollout schedules, and cloud kitchen format proliferation metrics.
Forecast precision tightens around the base case; tail outcomes carry wider variance under abrupt composting infrastructure delays or accelerated polymer phase-out timelines. Outputs reflect documented assumptions on regulatory implementation velocity and fiber-forming yield rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Containers
Stainless Steel Cask Market
Containers
Disposable Cups and Lids Market
Containers
Injection Molding Containers Market
Containers
Bulk Container Packaging Market
Containers
Wooden Barrels Market
Containers
EPS Container Market
Containers
Packaging Bins Market
Containers
Laminated Bulk Bins Market
Containers
Pail Lids Market
Containers
Essential Oil Containers Market
Containers
USA and Canada Packer Bottle Market
Containers
Twist Up Stick Container Market
Containers
PVC Container Market
Containers
Middle East and Africa Plastic Bottles and Containers Market
Containers
Global Flexitanks Market
Containers
Laboratory Sample Container Market