
 Coherent Optical Equipment Market | 2026-2036
Coherent Optical Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Coherent Optical Equipment Market Intelligence
Software-defined coherent line cards are repositioning vendor-customer relationships toward programmable bandwidth contracts. Nokia Corporation leverages its Bell Labs R&D heritage to sustain technology leadership in high-baud-rate silicon photonics. Fujitsu Limited anchors its position through integrated optical-electrical subsystems for submarine cable systems. Ciena Corporation differentiates via Blue Planet automation software layered across its WaveLogic coherent modem portfolio.
Coherent optical equipment employs phase and amplitude modulation of laser light combined with digital signal processing to transmit data across single-mode fiber at terabit-per-second aggregate rates. These systems use polarization multiplexing and advanced forward error correction to maximize spectral efficiency over distances exceeding 3,000 kilometers. Transceivers dominate product-level revenue as pluggable form factors displace embedded line systems in metro and data center interconnect routes. Coherent detection technology leads the technology dimension due to its compatibility with real-time DSP compensation for fiber impairments. Telecom operators remain the largest end-user category, though data center providers represent the fastest-expanding procurement segment.
FCC open access rules in the United States, EU Green Deal energy-efficiency mandates under ETSI standards, and China's MIIT fiber infrastructure targets collectively shape equipment certification and deployment timelines. NMPA-type equipment registration in China and REACH substance restrictions in Europe further constrain component sourcing for transceiver manufacturing. Stakeholders must monitor standardization timelines at the IEEE 802.3 working group and OIF implementation agreements to anticipate the next pluggable form factor transition.
Market Dynamics
The coherent optical equipment sector is restructuring around open line system architectures that decouple transceivers from proprietary chassis, forcing incumbent vendors to defend installed bases through software differentiation rather than hardware lock-in.
Growth Catalysts
- Hyperscale data center buildouts:Cloud operators in the United States, China, and Germany are deploying 400G and 800G coherent pluggables for campus interconnects and metro fiber backbones.
- EU Green Deal mandates:ETSI energy-efficiency standards for network equipment are accelerating replacement cycles of legacy DWDM systems with lower-power coherent alternatives.
- Open optical networking standards:OIF implementation agreements and IEEE 802.3 interoperability specifications are reducing switching costs for telecom operators procuring multi-vendor networks.
Market Restraints
- Indium phosphide supply concentration:High-performance laser chip fabrication depends on a limited supplier base concentrated in East Asian foundries, creating input cost volatility.
- REACH substance restrictions:European chemical regulations constrain sourcing of gallium arsenide and other III-V semiconductor materials used in coherent transmitter assemblies.
- Silicon photonics yield limitations:Manufacturing complexity for integrated coherent optical subassemblies limits cost reduction trajectories below certain port density thresholds.
Strategic Opportunities
- Submarine cable upgrades:Trans-Pacific and trans-Atlantic routes require new coherent modem generations capable of 2.4 Tbps per fiber pair, creating demand for integrated optical-electrical subsystems.
- China MIIT fiber targets:National broadband infrastructure mandates under the 14th Five-Year Plan specify gigabit access coverage expansion that feeds metro aggregation layer investment.
- Edge computing interconnects:Distributed AI inference clusters are emerging as a new application category requiring low-latency coherent links between metropolitan data centers and baseband processing units.
Industry Challenges
- DSP algorithm engineering scarcity:Real-time digital signal processing for high-baud-rate coherent detection requires specialized expertise in mixed-signal design that outpaces university pipeline output.
- Multi-vendor integration complexity:Open line system deployments demand extensive interoperability testing between transceivers from different suppliers and host equipment, extending deployment timelines.
- China NMPA equipment registration:Network product certification requirements create procedural friction for foreign vendors seeking access to state-owned carrier procurement programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coherent Optical Equipment Market |
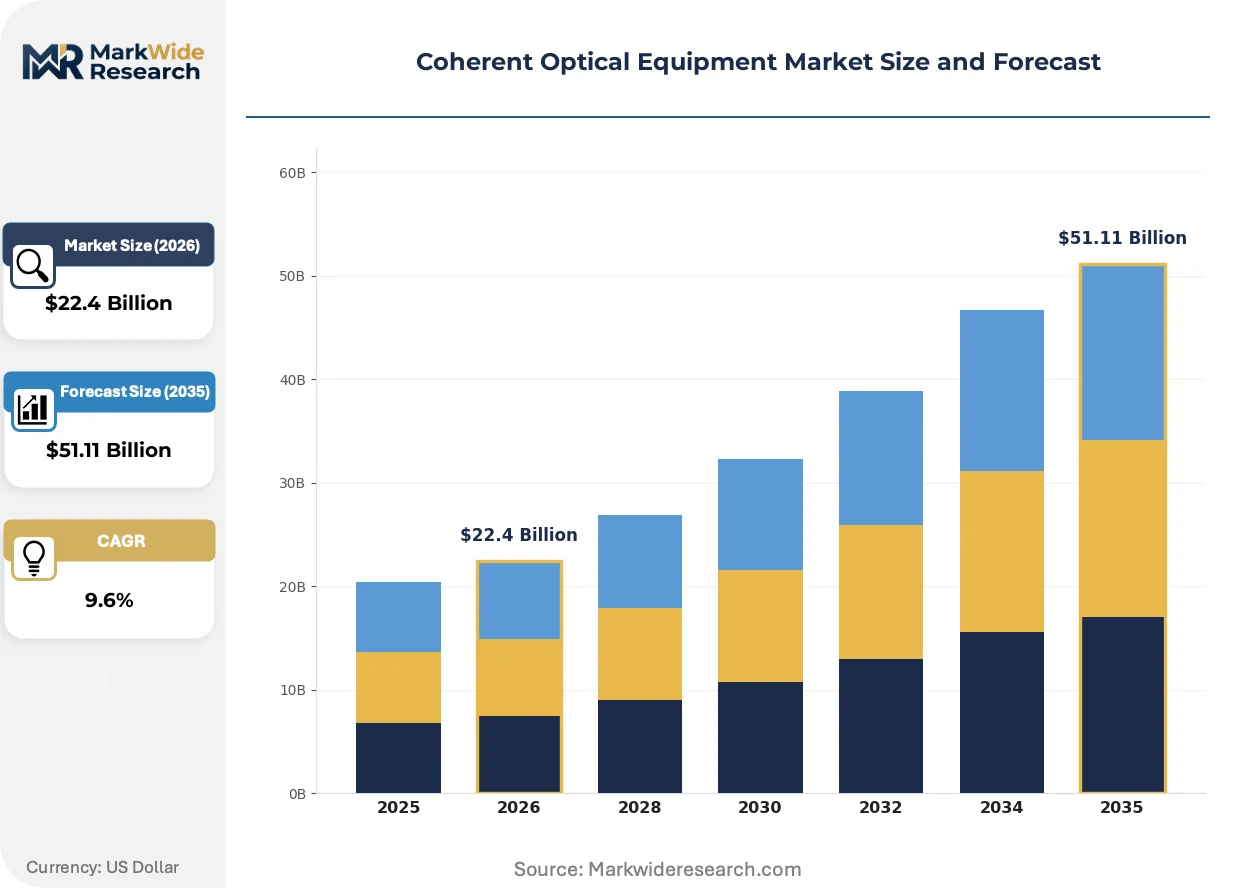
| Market Size in 2026 | $22.4 Billion |
| Market Size in 2035 | $51.11 Billion |
| CAGR (2026 – 2036) | 9.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lasers, Amplifiers, Transceivers, Modulators Technology: Polarization Multiplexing, Frequency Domain Multiplexing, Phase Shift Keying, Coherent Detection Application: Telecommunications, Data Center Interconnect, Research & Development, Aerospace End User: Telecom Operators, Data Center Providers, Research Institutions, Government Agencies |
| Companies Covered | Nokia Corporation, Fujitsu Limited, Huawei Technologies Co., Ltd., ZTE Corporation, NEC Corporation, Ciena Corporation, Infinera Corporation, Telefonaktiebolaget LM Ericsson, Cisco Systems, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coherent Optical Equipment Market Strategic Shifts & Innovations
Silicon photonics is consolidating coherent optical functions onto single chips, collapsing the traditional separation between optical and electrical subsystems that defined vendor specialization for two decades.
Pluggable coherent transceivers are consolidating metro and data center interconnect markets by absorbing functions previously performed by embedded line systems, compressing the addressable market for chassis-based DWDM platforms. Data center operators are adopting QSFP-DD and OSFP form factors at pace, enabling pay-as-you-grow capacity scaling without forklift upgrades. The structural consequence is vendor margin compression in hardware and forced migration toward software-defined control plane revenues.
EU Green Deal energy-efficiency mandates under ETSI standards are reshaping equipment design priorities toward power-per-gigabit metrics. Network operators now specify thermal envelopes and idle power consumption in procurement tenders, disqualifying legacy coherent platforms from consideration. Metro aggregation segments in Germany and France are responding fastest, embedding sustainability scoring into vendor selection criteria alongside traditional performance benchmarks.
Buying patterns among telecom operators are fragmenting as procurement teams disaggregate optical layer decisions from transport architecture planning. Traditional system integrators are losing influence to specialized optical engineering consultants who specify multi-vendor configurations. This behavioral shift is most visible in the United States, where FCC open access rules for middle-mile networks encourage equipment diversity rather than single-source deployments.
Coherent Optical Equipment Market Segmentation
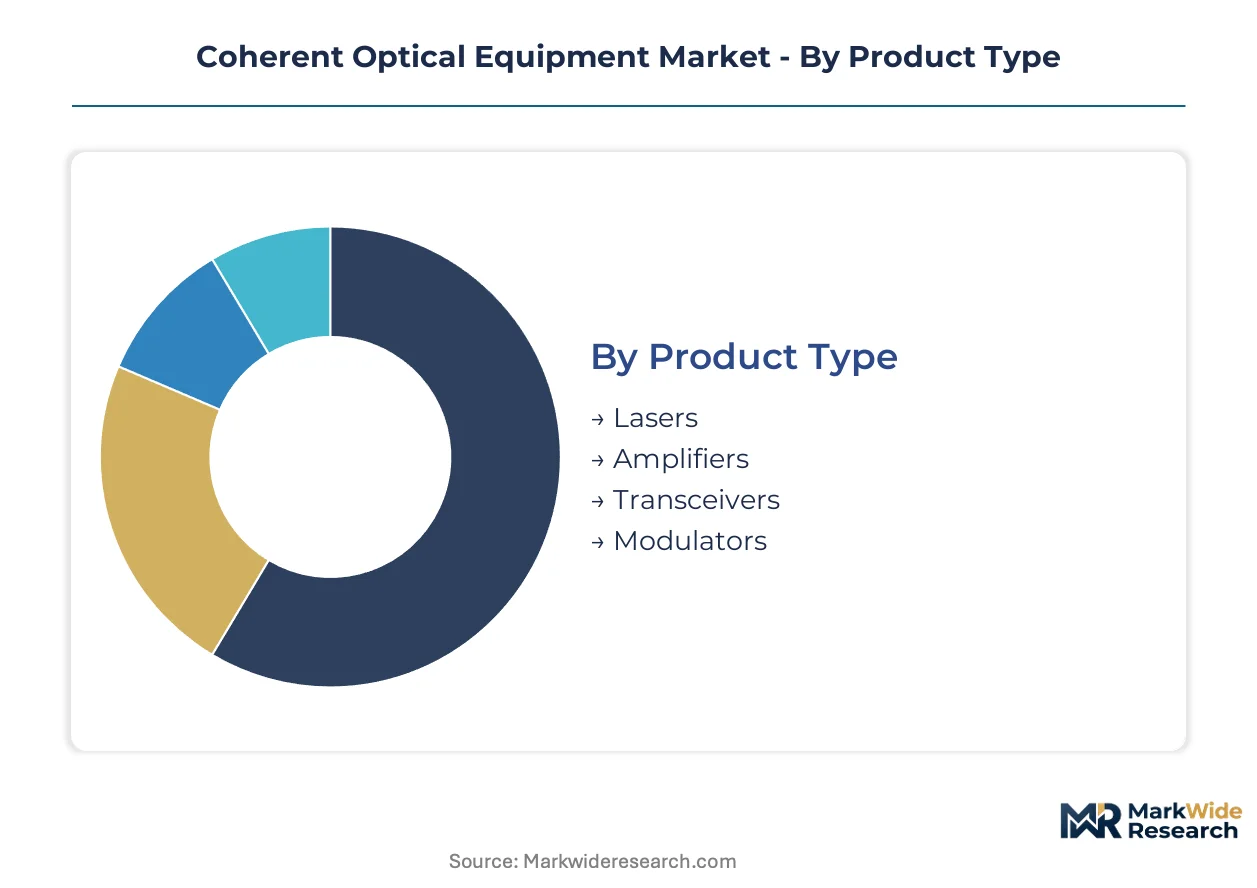
Coherent optical equipment segmentation reveals how procurement priorities diverge across deployment contexts. Buyers in submarine cable systems prioritize integrated optical-electrical subsystems over discrete components, while hyperscale data center operators favor pluggable form factors for pay-as-you-grow scaling.
Product Type:
Cost tier separates buyers seeking commodity photonic components from those requiring integrated subsystem performance.
- Transceivers:Pluggable QSFP-DD and OSFP form factors integrate lasers, modulators, and coherent receivers into single packages. Hyperscale operators in the United States and China specify these for metro data center interconnects to enable rapid capacity scaling without chassis replacement. QSFP-DD dominates current procurement volumes.
- Amplifiers:Erbium-doped fiber amplifiers and semiconductor optical amplifiers boost signal power across long-haul routes. Submarine cable operators deploying trans-Atlantic and trans-Pacific routes specify ultra-low-noise variants to maximize reach without electrical regeneration. EDFA technology anchors installed base economics.
- Lasers:External cavity and distributed feedback lasers provide narrow-linewidth optical carriers for coherent modulation. Foundries in East Asia concentrate high-volume production for pluggable transceiver integration.
- Modulators:Lithium niobate and silicon photonics-based modulators impose data onto optical carriers through phase and amplitude manipulation. Indium phosphide platforms serve performance-intensive long-haul applications.
Transceivers lead volumes today; amplifiers are gaining share fastest in submarine upgrade cycles.
Technology:
Application requirements determine whether buyers prioritize spectral efficiency maximization or implementation simplicity.
- Coherent Detection:Homodyne and intradyne detection architectures employ local oscillator lasers and digital signal processing to recover phase-modulated signals. Telecom operators across Germany, France, and Japan mandate this technology for 400G+ metro aggregation to enable real-time fiber impairment compensation. DSP integration complexity limits supplier base breadth.
- Polarization Multiplexing:Dual-polarization transmission doubles spectral efficiency by encoding independent data streams on orthogonal polarization states. Submarine cable operators leverage this for 2.4 Tbps per fiber pair on trans-Pacific routes where fiber count constraints dominate economics. Receiver DSP algorithms must track rapid polarization state changes.
- Phase Shift Keying:QPSK, 8QAM, and 16QAM constellations trade off spectral efficiency against optical signal-to-noise ratio requirements. Long-haul network designers select modulation formats based on specific route characteristics.
- Frequency Domain Multiplexing:Subcarrier multiplexing techniques aggregate multiple optical carriers within superchannel architectures. Research institutions pilot these approaches for next-generation terabit-class interfaces.
Coherent detection leads volumes today; polarization multiplexing is climbing the fastest in submarine cable deployments.
Application:
Volume concentration and margin structure separate infrastructure-scale buyers from specialized niche purchasers.
- Telecommunications:National backbone and metro aggregation networks constitute the foundational demand base. Incumbent operators in the United States, China, and Germany execute multi-year DWDM modernization programs replacing 100G embedded systems with 400G coherent pluggables. FCC open access rules and EU Green Deal mandates accelerate replacement timelines.
- Data Center Interconnect:Campus and metro fiber links between hyperscale facilities represent the steepest expansion trajectory. Cloud operators specify 400G and 800G coherent optics for distances under 120 kilometers, collapsing the addressable market for traditional chassis-based platforms. Power-per-gigabit metrics dominate procurement scoring.
- Research & Development:National laboratories and university consortia prototype next-generation modulation formats and optical switching architectures. Funding cycles from NSF, EU Horizon programs, and China's Ministry of Science and Technology drive irregular procurement patterns.
- Aerospace:Satellite optical inter-satellite links and high-altitude platform systems demand radiation-hardened coherent terminals. Volume constraints limit supplier participation to specialized defense contractors.
Telecommunications leads volumes today; data center interconnect is expanding most quickly.
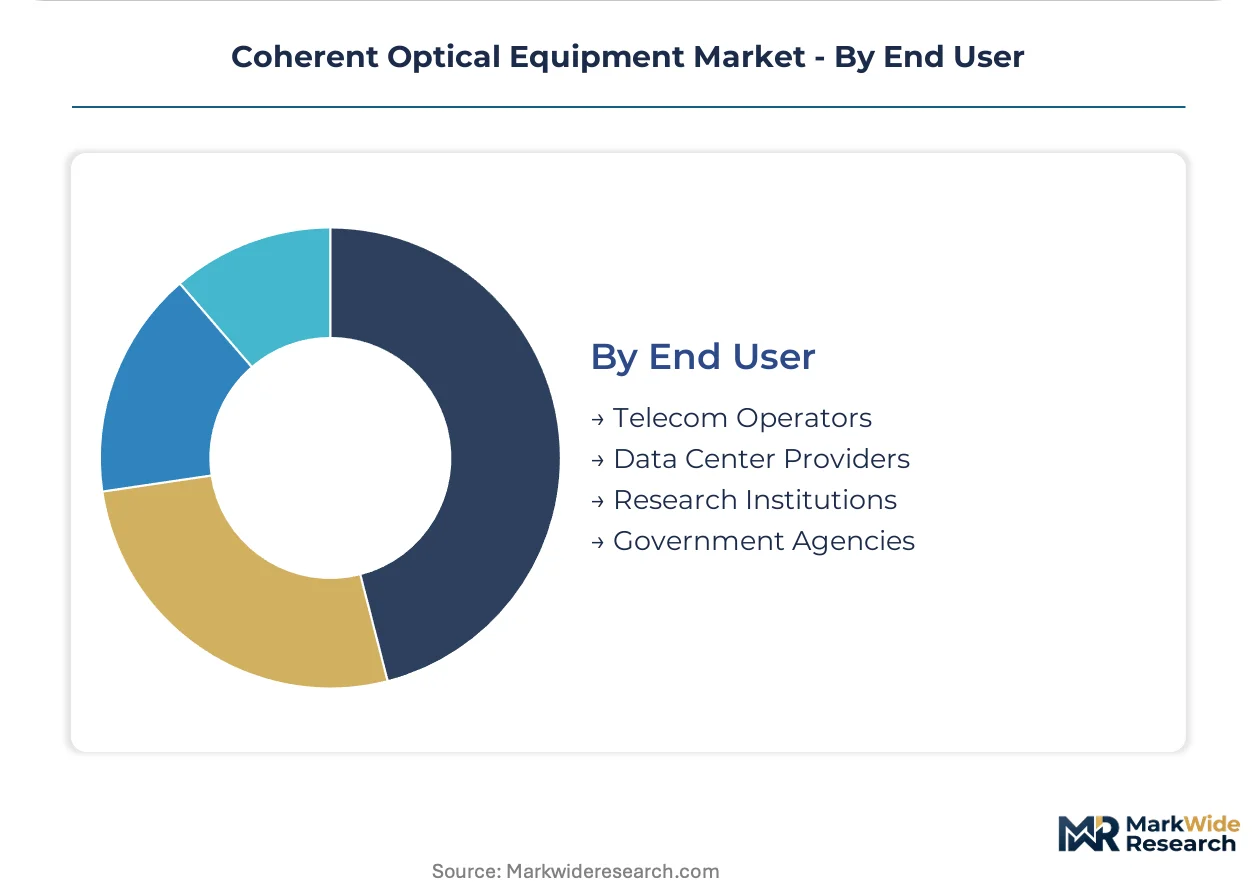
End User:
Procurement sophistication and technical specification authority distinguish institutional buyer categories.
- Telecom Operators:Incumbent carriers and competitive network operators deploy coherent equipment across access, aggregation, and core network tiers. Verizon, Deutsche Telekom, and China Mobile execute centralized procurement with multi-vendor interoperability requirements. OIF implementation agreements and IEEE 802.3 standards compliance are mandatory bid preconditions.
- Data Center Providers:Hyperscale cloud operators and colocation specialists specify optical layer equipment independently from traditional telecom vendors. Amazon Web Services, Microsoft Azure, and Alibaba Cloud employ internal optical engineering teams that disaggregate transceiver procurement from transport system decisions. Direct sourcing from Asian ODMs compresses vendor margins.
- Research Institutions:CERN, national laboratories, and university optical communications groups acquire coherent equipment for experimental network testbeds. Non-standard specifications and extended support requirements limit commercial supplier interest.
- Government Agencies:Defense and intelligence community networks procure secure coherent terminals through classified acquisition channels. ITAR and national security certification requirements constrain vendor eligibility.
Telecom operators lead volumes today; data center providers are climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's MIIT fiber infrastructure targets and the United States FCC open access rules are pulling investment in divergent regulatory directions, while Germany's ETSI compliance deadlines compress replacement cycles for legacy equipment.
United States
Hyperscale operators in Northern Virginia and Dallas-Fort Worth are deploying 800G coherent pluggables for campus interconnects. FCC open access rules for middle-mile networks encourage multi-vendor procurement rather than single-source deployments. Seattle and San Jose host engineering clusters where cloud providers operate internal optical teams disaggregated from traditional telecom vendors.
China
State-owned carriers execute centralized procurement for 400G metro aggregation under MIIT gigabit coverage mandates. NMPA equipment registration creates procedural barriers for foreign suppliers seeking access to China Mobile and China Telecom programs. Shenzhen and Wuhan concentrate silicon photonics foundry capacity serving domestic transceiver manufacturing.
Germany
Deutsche Telekom and Vodafone specify EU Green Deal energy-efficiency thresholds disqualifying high-power legacy DWDM systems. ETSI standards for network equipment idle consumption accelerate coherent platform replacement in Frankfurt and Munich metro rings. Bavaria hosts submarine cable landing stations driving demand for integrated optical-electrical subsystems.
Japan
NTT and KDDI deploy coherent detection architectures for 400G+ aggregation layers requiring real-time DSP compensation. METI funding programs support domestic silicon photonics R&D to reduce reliance on imported indium phosphide components. Yokohama and Osaka house optical subsystem integrators serving trans-Pacific cable upgrade cycles.
United Kingdom
BT Openreach and CityFibre procure QSFP-DD form factors for metro fiber backbones connecting London data centers. Ofcom wholesale access regulations shape equipment interoperability requirements for multi-operator fiber sharing. Slough and Manchester clusters concentrate hyperscale facility construction driving coherent interconnect demand.
Coherent Optical Equipment Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, with integrated subsystem vendors defending position in submarine cable upgrades while pluggable transceiver specialists capture hyperscale data center volumes. The vendor base organizes around three archetypes: diversified telecom equipment conglomerates with Bell Labs-scale R&D heritage, Japanese integrated optical-electrical subsystem specialists, and Silicon Valley-based automation software layers. Competitive moves concentrate on strategic partnerships for open line system interoperability and backward integration into indium phosphide laser fabrication.
Among diversified telecom equipment conglomerates, Nokia Corporation and Ciena Corporation exemplify archetypes diverging on hardware-versus-software differentiation. Fujitsu Limited occupies a position within the integrated subsystem tier serving submarine cable operators. Huawei Technologies Co., Ltd. represents state-affiliated vertical integration spanning DSP design through transceiver manufacturing. These three anchors illustrate how geographic origin and corporate structure shape competitive positioning without determining specific strategic outcomes.
| Leading Market Players |
|---|
| Nokia Corporation |
| Fujitsu Limited |
| Huawei Technologies Co., Ltd. |
| ZTE Corporation |
| NEC Corporation |
| Ciena Corporation |
| Infinera Corporation |
| Telefonaktiebolaget LM Ericsson |
| Cisco Systems, Inc. |
| Others |
Cost & Logistics Intelligence
DSP algorithm engineering clusters in Silicon Valley and Yokohama anchor labor-cost differentials that widen pricing-tier spreads between premium coherent subsystems and commodity transceiver modules. Cost compression in pluggable form factors intensifies as Asian ODMs absorb functions previously performed by branded chassis vendors.
Pricing Analysis
Capacity additions in China's silicon photonics foundries are reshaping price floors for QSFP-DD transceivers serving hyperscale data center interconnects. Three-tier pricing structure across premium, standard, and economy levels separates submarine cable-integrated subsystems from metro pluggables and campus interconnect commodities. Price differentiation hinges on DSP integration complexity and OIF interoperability certification. Margins are tightening in standard-tier metro aggregation as direct procurement from Asian ODMs bypasses traditional vendor channels. Data center providers exhibit highest price sensitivity; submarine cable operators prioritize performance over unit cost.
Supply Chain Analysis
ETSI energy-efficiency certification and OIF implementation agreement compliance gate access to European and North American carrier procurement programs. Manufacturing concentrates in China, Japan, and the United States, with Shenzhen and Wuhan hosting silicon photonics foundry capacity. Raw material dependencies include indium phosphide laser chips, lithium niobate modulator substrates, and erbium-doped fiber amplifier components. Single-source vulnerability in East Asian III-V semiconductor foundries creates input cost volatility. Distribution runs through direct OEM relationships for hyperscale operators and systems integrator channels for telecom carriers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicon photonics yield improvements and pluggable form factor standardization create margin-expansion headroom for vendors mastering DSP software differentiation. Premium-tier demand from submarine cable upgrades offsets commodity compression in metro aggregation.
For Market Incumbents: Lock in proprietary DSP algorithm advantages through Bell Labs-scale R&D investment and backward integration into indium phosphide laser fabrication. Defend installed base relationships by embedding Blue Planet-style automation layers that increase switching costs for open line system deployments. Threaten hyperscale direct procurement from Asian ODMs demands channel control through certification investment and field engineering support density. For New Entrants and Emerging Players: Edge computing interconnect specialists between metropolitan data centers and baseband processing units represent an underserved buyer archetype with limited incumbent attention. Penetration concentrates in Germany and Japan where distributed AI inference clusters require low-latency coherent links outside traditional telecom procurement frameworks. Go-to-market leverage rests on QSFP-DD interoperability pre-certification and pay-as-you-grow financing structures. For Investors and Strategic Acquirers: Hyperscale cloud operators are the most active acquirer in this space, seeking captive optical engineering capabilities to disaggregate from traditional telecom vendors. Long-term viability favors vertically integrated specialists controlling DSP design through transceiver manufacturing. Acquisition target archetypes include silicon photonics foundries with coherent subsystem integration expertise and OIF-certified interoperability testing laboratories. Signal to watch: MIIT procurement policy shifts opening China Mobile and China Telecom programs to foreign NMPA-registered suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Open Line System Interoperability Certification | OIF implementation agreement compliance reduces switching costs for Deutsche Telekom multi-vendor deployments. |
| Silicon Photonics Foundry Scale-Up | Domestic capacity in Wuhan serves China MIIT fiber infrastructure targets with reduced indium phosphide dependency. |
| DSP Software Platform Integration | Blue Planet-style automation layers differentiate Ciena from commodity transceiver competitors in Verizon procurement. |
| Submarine Cable Subsystem Partnership | Integrated optical-electrical offerings capture Fujitsu share in trans-Pacific 2.4 Tbps fiber pair upgrades. |
| Energy-Efficiency Certification Program | ETSI idle power compliance qualifies Nokia for EU Green Deal-mandated replacement cycles in Germany. |
Research Approach
Direct dialogue with optical network architects at hyperscale operators, DSP engineering leads at transceiver manufacturers, procurement directors at state-owned carriers, and submarine cable system integrators grounded qualitative findings. Secondary validation drew from IEEE 802.3 working group documentation, OIF implementation agreements, FCC open access rulemaking dockets, ETSI network equipment standards, and MIIT fiber infrastructure policy circulars. Bottom-up and top-down triangulation reconciled vendor shipment data with carrier capex disclosure patterns.
Bottom-up modeling aggregated product-level volume assumptions across transceiver, amplifier, and subsystem categories; top-down verification cross-checked against national fiber backbone investment programs. Segmentation dimensions included product form factor, detection technology, application context, and end-user procurement sophistication. CAGRs were derived from installed base replacement cycles, hyperscale data center buildout trajectories, and regulatory-mandated efficiency upgrade timelines. Industry-specific inputs encompassed silicon photonics yield curves, indium phosphide foundry capacity utilization, and open line system interoperability testing duration.
Underlying measurement precision varies by segment; data center interconnect volumes carry tighter precision than aerospace satellite terminal forecasts due to hyperscaler disclosure practices. Forecasts reflect assumptions regarding OIF standardization timelines, REACH substance restriction enforcement, and China NMPA registration procedural friction. A model refresh is warranted upon material change in MIIT procurement policy or FCC open access rule implementation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Optical Isolator Market
Optical Components
Laser Module Market
Optical Components
Optical Spectrum Analyzer (OSA) Market
Optical Components
Electro-Optic Modulators Market
Optical Components
Global Fiber Bragg Grating Amplifier Market
Optical Components
Global Optical Coating Equipment Market
Optical Components
Faraday Rotator Market
Optical Components
Optical Sensor Market
Optical Components
LGP (Light Guide Plate) for TV Market
Optical Components
Mexico Extreme Ultraviolet Lithography (EUVL) Systems Market
Optical Components
Global Hybrid Photonic Integrated Circuit Market
Optical Components
Pancake Optical Module Market
Optical Components
Global Transparent Quartz Tube Market
Optical Components
Global Tunable Filter Market
Optical Components
Global Optical Connectivity Solutions Market
Optical Components
Ring Panel Filters Market