
 Faraday Rotator Market | 2026-2036
Faraday Rotator Market Size, Share, and Industry Trends Forecast 2026-2036
Faraday Rotator Market Insights
Defense contractors and classified laser system integrators are redrawing procurement priorities for Faraday rotators, pulling volume away from general industrial buyers. Thorlabs leverages its vertically integrated crystal growth and polishing operations to control terbium gallium garnet supply chains. Kohoku Kogyo anchors Japanese domestic demand through METI-backed quantum technology programs. Electro-Optics Technology specializes in high-power handling designs for directed-energy applications.
A Faraday rotator is a magneto-optic device that rotates the plane of polarized light passing through it by an angle proportional to the applied magnetic field strength and crystal path length, typically constructed from terbium gallium garnet or yttrium iron garnet crystals with Verdet constants measured in rad/T·m, and serves primarily to block back-reflected light in laser cavities and optical amplifiers. Crystal-based technology dominates current manufacturing due to mature TGG boule growth and established polishing protocols, while semiconductor-based approaches are gaining traction for chip-scale integration in coherent transceivers. Optical rotators command the largest product category share, though active rotators with tunable magnetic bias coils are capturing margin in research lab environments requiring real-time polarization control.
The US FDA regulates medical laser systems incorporating Faraday isolators, while FCC spectrum management shapes telecom deployment timelines that drive component demand; China's MIIT and GB standards enforce domestic content ratios in state-funded fiber backbone projects. ISO 10110 surface quality specifications and REACH substance restrictions on rare-earth processing chemicals jointly determine supplier qualification thresholds. Stakeholders must monitor divergence between US export control classifications for high-power isolators and EU dual-use regulations to anticipate channel fragmentation.
Market Dynamics
Defense procurement priorities are redrawing Faraday rotator demand allocation, pulling volume toward classified directed-energy programs and away from general industrial buyers. This structural shift concentrates purchasing power among cleared contractors with security-cleared supply chains.
Growth Catalysts
- Telecom Amplifier Deployment:Fiber backbone operators are scaling isolator-protected erbium-doped fiber amplifier chains. China's MIIT mandates domestic optical component ratios in state-funded projects.
- Quantum Technology Funding:METI-backed programs in Japan are anchoring domestic demand for precision magneto-optic devices. Research labs require real-time polarization control capabilities.
- Terbium Gallium Garnet Supply Maturity:Established boule growth and polishing protocols enable cost-efficient manufacturing. German precision photonics clusters around Jena provide specialized finishing expertise.
Market Restraints
- Rare-Earth Processing Constraints:REACH substance restrictions on terbium and gallium refining chemicals limit European supplier qualification. Qualified chemical processors concentrate in China.
- High-Power Thermal Limitations:Crystal-based TGG devices face heat dissipation ceilings above kilowatt-class continuous-wave operation. Semiconductor alternatives remain immature for these power levels.
- Export Control Fragmentation:Divergence between US Commerce Department high-power isolator classifications and EU dual-use regulations creates channel compliance complexity. Cross-border shipments require dual licensing.
Strategic Opportunities
- Coherent Transceiver Integration:Semiconductor-based Faraday rotators are miniaturizing for silicon photonics chip-scale packaging. Datacom module vendors seek integrated isolator solutions.
- Medical Laser Certification Path:US FDA 510(k) clearance requirements for surgical laser systems create captive demand for qualified isolator suppliers. Device OEMs prefer pre-certified component sources.
- Domestic Manufacturing Incentives:China's dual carbon goals and MIIT localization push redirect procurement toward indigenous TGG crystal growth capabilities. State-backed foundries absorb capital intensity.
Industry Challenges
- Magneto-Optic Crystal Polishing Expertise:Specialized opticians capable of achieving ISO 10110 surface quality on TGG substrates are scarce. Training cycles extend 18-24 months.
- Dual-Use Compliance Documentation:Defense contractors require extensive provenance records for rare-earth supply chains. Audit preparation consumes engineering resources.
- Legacy System Interface Standards:New rotator designs must maintain mechanical compatibility with existing optical bench configurations. Retrofit markets resist form-factor changes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Faraday Rotator Market |
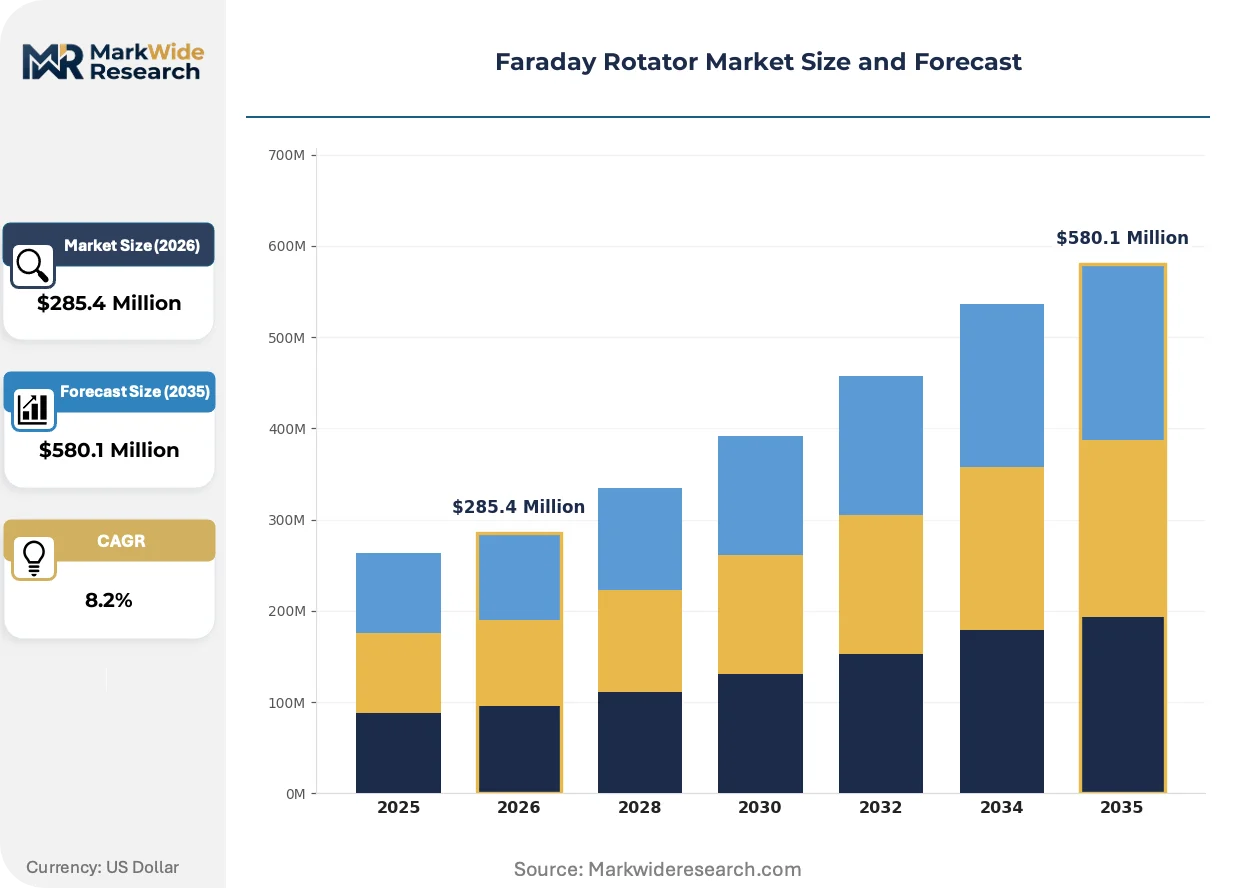
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $580.1 Million |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Rotators, Magnetic Rotators, Passive Rotators, Active Rotators Technology: Fiber Optic, Crystal-Based, Semiconductor-Based, Optical Waveguide End User: Telecommunications, Defense, Aerospace, Industrial Application: Laser Systems, Optical Communication, Research Labs, Imaging Systems |
| Companies Covered | Thorlabs, Newport, Kohoku Kogyo, Leysop, Electro-Optics Technology, DK Photonics, AFW Technologies, Haphit, GRANOPT, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Faraday Rotator Market Trends and Innovations
Magneto-optic device architecture is compressing toward chip-scale formats while regulatory frameworks fragment across major economies. These forces are reshaping supplier qualification requirements and buyer procurement criteria simultaneously.
Semiconductor Faraday rotators fabricated from magneto-optic thin films on silicon nitride platforms are miniaturizing isolation functions for coherent optical transceivers. Cloud datacenter operators are adopting these devices for 400G and 800G modules. The technology is compressing isolator footprints from discrete crystal assemblies to waveguide-integrated elements.
EU REACH restrictions on heavy rare-earth processing chemicals are tightening supplier environmental qualification thresholds. European TGG vendors must demonstrate closed-loop chemical recovery or face market exclusion. Medical device OEMs sourcing EU-manufactured isolators absorb compliance documentation costs into procurement specifications.
Defense procurement offices are consolidating Faraday isolator purchasing through security-cleared prime contractors. General industrial distributors lose access to high-power device categories. The pattern concentrates most visibly in US directed-energy program supply chains where facility clearance requirements filter vendor pools.
Faraday Rotator Market Segmentation
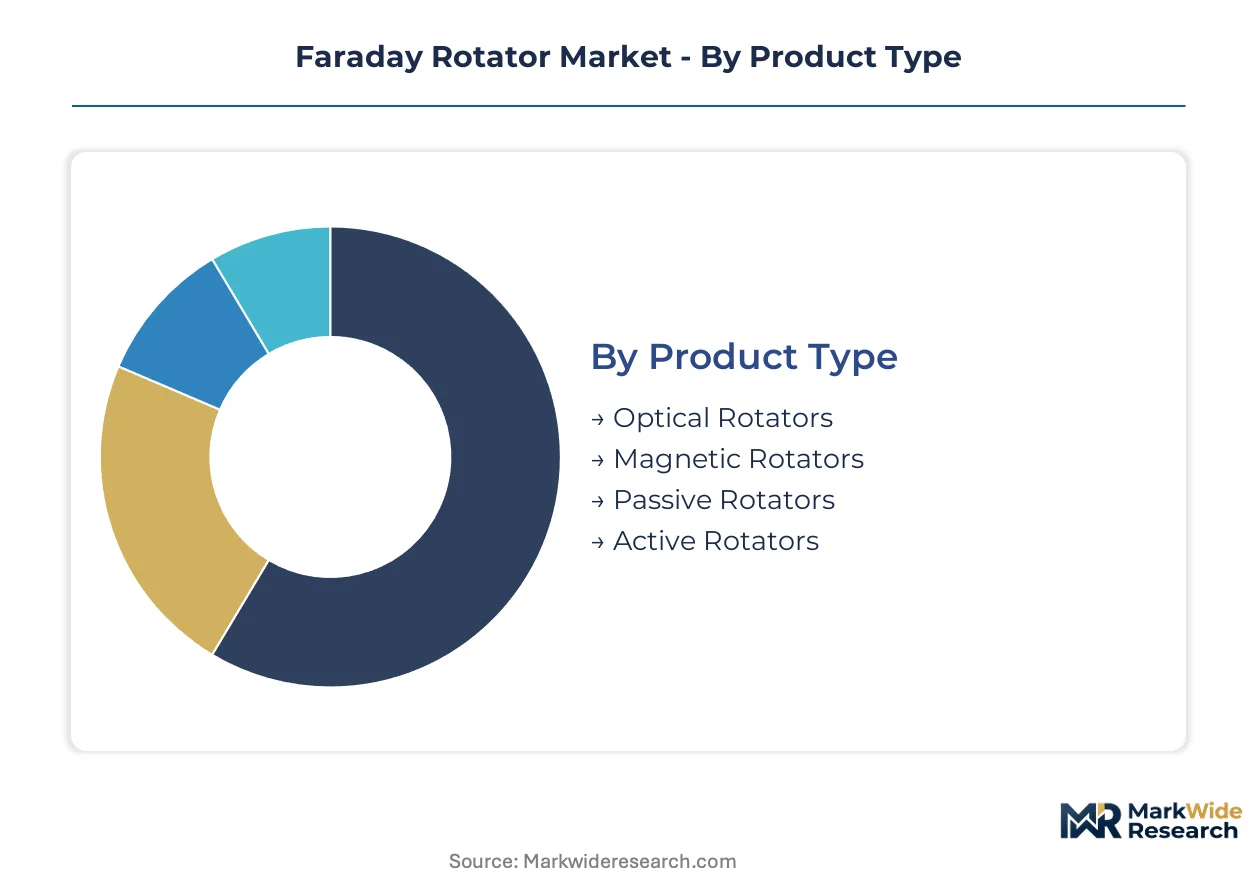
Faraday rotator procurement patterns diverge sharply across product architectures and end-use certifications. Crystal-based isolators command premium pricing in defense-directed energy programs, while semiconductor formats are compressing unit economics for datacom module vendors.
Product Type:
Margin pools concentrate in active rotator configurations where tunable magnetic bias coils enable real-time polarization control for research laboratories.
- Optical Rotators:These devices rotate polarized light through magneto-optic crystals without external power, constructed from terbium gallium garnet boules with Verdet constants measured in rad/T·m. Demand concentrates in Germany's precision photonics cluster around Jena, where ISO 10110 surface quality specifications filter supplier qualification.
- Active Rotators:Magnetic bias coils enable dynamic rotation angle adjustment during operation. Research labs in Japan's METI-backed quantum technology programs absorb volume for real-time polarization control experiments.
- Magnetic Rotators:Permanent magnet assemblies provide fixed rotation angles for stable laser cavity isolation.
- Passive Rotators:Unpowered crystal devices serve cost-sensitive industrial cutting and welding applications.
Optical rotators hold installed capacity. Active rotators are rotating up the share rankings.
Technology:
Cost tier stratification separates mature boule-growth processes from emerging thin-film deposition methods.
- Crystal-Based:Terbium gallium garnet boule growth and polishing protocols dominate current manufacturing, with established supply chains anchored by vertically integrated crystal growers. China's MIIT mandates domestic content ratios in state-funded fiber backbone projects, redirecting procurement toward indigenous TGG capabilities.
- Semiconductor-Based:Magneto-optic thin films on silicon nitride platforms enable chip-scale integration for coherent optical transceivers. Cloud datacenter operators in the US are adopting these devices for 400G and 800G modules.
- Fiber Optic:All-fiber isolator designs serve telecom amplifier chains requiring minimal insertion loss.
- Optical Waveguide:Planar waveguide structures integrate isolation functions with photonic integrated circuits.
Crystal-based technology anchors volume shipments. Semiconductor-based formats are climbing the fastest.
End User:
Application-specific certification requirements create captive demand pools with divergent procurement timelines.
- Defense:Classified directed-energy programs require security-cleared supply chains with extensive rare-earth provenance documentation. US Commerce Department export controls and EU dual-use regulations create channel compliance complexity for cross-border shipments.
- Telecommunications:Fiber backbone operators scale isolator-protected erbium-doped fiber amplifier chains. China's MIIT localization push redirects component sourcing toward domestic optical device manufacturers.
- Aerospace:Satellite laser communication terminals demand radiation-hardened isolator designs.
- Industrial:General manufacturing applications face purchasing power concentration among cleared contractors.
Defense holds installed capacity. Telecommunications is gaining share fastest.
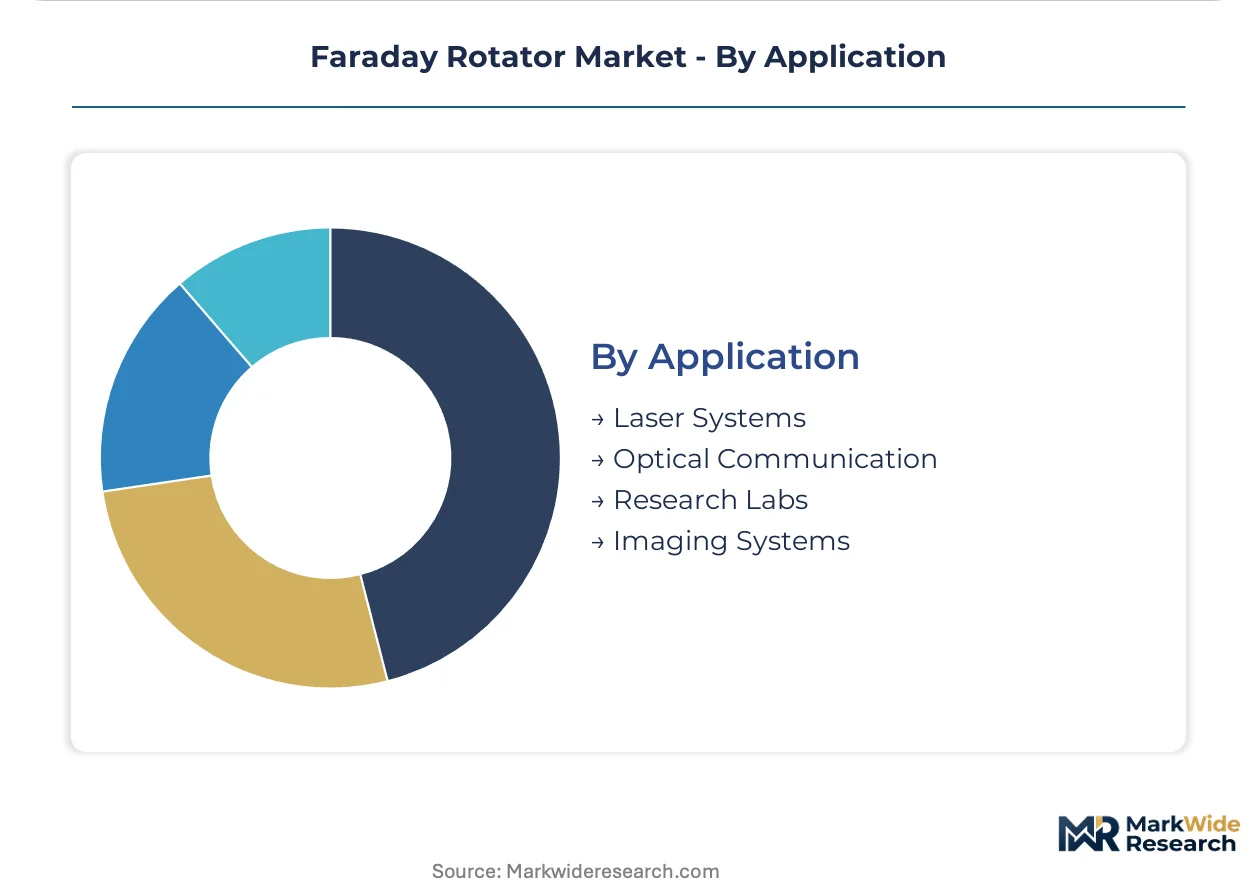
Application:
Customer type differentiation separates FDA-regulated medical device OEMs from research procurement offices with flexible specification tolerance.
- Laser Systems:Medical surgical platforms require US FDA 510(k) cleared isolator subassemblies, creating captive demand for pre-certified component suppliers. Device OEMs absorb compliance documentation costs into procurement specifications.
- Optical Communication:Datacom module vendors seek integrated isolator solutions with compressed footprints for coherent transceiver packaging. FCC spectrum management shapes deployment timelines that drive component demand cycles.
- Research Labs:Academic and government laboratories purchase active rotators for polarization control experiments.
- Imaging Systems:Microscopy and metrology instruments require low-wavefront-distortion isolator designs.
Laser systems hold installed capacity. Optical communication is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Qinghai-Tibet Railway's freight corridors and the Trans-European Transport Network's fiber trunk lines underpin Faraday rotator demand corridors across Asia and Europe. These infrastructure arteries channel optical component procurement toward precision manufacturing clusters in Germany, China, Japan, and the United States.
United States
Directed-energy weapons programs at Kirtland Air Force Base and Lawrence Livermore National Laboratory absorb high-power isolator volume. The US Commerce Department maintains export control classifications for terbium gallium garnet devices above specified power thresholds. Boston's Route 128 photonics corridor hosts specialized opticians serving FDA-cleared medical laser OEMs.
Germany
Precision photonics manufacturing concentrates around Jena's historic optical cluster and Berlin's research infrastructure. ECHA REACH restrictions on rare-earth processing chemicals filter supplier environmental qualification. The Fraunhofer Institute for Applied Optics and Precision Engineering anchors TGG polishing expertise development in Thuringia.
China
MIIT mandates domestic content ratios in state-funded fiber backbone projects spanning the Beijing-Shanghai and Guangzhou-Shenzhen trunk lines. GB standards enforce optical component performance specifications for 400G and 800G coherent transmission systems. Yangtze River Delta foundries absorb capital intensity for indigenous TGG boule growth capacity.
Japan
METI-backed quantum technology programs anchor domestic demand for active rotators with tunable magnetic bias. The Kansai region's Osaka-Kobe manufacturing belt supplies precision magneto-optic devices for research laboratories. PMDA regulatory pathways shape medical laser system component certification timelines.
United Kingdom
Defense Science and Technology Laboratory procurement consolidates isolator purchasing through security-cleared prime contractors. The Cambridge photonics cluster specializes in semiconductor-based waveguide-integrated designs for datacom applications. UK Research and Innovation funding redirects toward silicon photonics foundry capabilities.
Faraday Rotator Market Competitive Landscape
Concentration sits with vertically integrated crystal growers and specialized defense contractors. The vendor base splits between established TGG boule producers and emerging semiconductor thin-film specialists. Two strategic archetypes dominate: precision opticians with ISO 10110 surface quality capabilities, and chip-scale integration players targeting coherent transceiver modules. Competitive moves center on backward integration into terbium supply chains and geographic expansion toward China's state-funded fiber projects.
Among US-based suppliers, Thorlabs and Electro-Optics Technology exemplify divergent positioning strategies. Thorlabs represents the vertically integrated archetype with captive crystal growth operations. Electro-Optics Technology occupies a position within the high-power defense-specialist tier. Kohoku Kogyo anchors Japanese domestic demand through METI program relationships. These three companies illustrate how procurement consolidation around cleared contractors and state technology funding creates divergent market access patterns.
| Leading Market Players |
|---|
| Thorlabs |
| Newport |
| Kohoku Kogyo |
| Leysop |
| Electro-Optics Technology |
| DK Photonics |
| AFW Technologies |
| Haphit |
| GRANOPT |
| Others |
Pricing and Supply Chain Analysis
Boule-growth economies in China's Yangtze River Delta and Thuringia's Jena corridor concentrate TGG crystal production, compressing unit costs for high-volume defense contractors while ISO 10110-qualified opticians command premium pricing for precision finishing. This scale asymmetry stratifies the market between commodity crystal supply and specialized polishing services.
Pricing Analysis
Volume-discount tiering separates cleared defense contractors purchasing kilowatt-class isolator assemblies from research labs acquiring single active rotator units. Pricing stratifies across premium, standard, and economy tiers based on ISO 10110 surface quality grade and FDA 510(k) certification status. Cost compression in the standard tier is intensifying because China's MIIT-backed foundries are absorbing capital intensity for indigenous TGG growth. General industrial buyers exhibit highest price sensitivity; defense-directed energy programs show lowest sensitivity due to security-cleared supply chain requirements.
Supply Chain Analysis
Shanghai port congestion and transpacific container availability shape inbound logistics costs for terbium oxide feedstock arriving from Bayan Obo mining complexes. Supply concentrates in China, Germany, and Japan for TGG boule growth, magnet assembly fabrication, and precision polishing respectively. The chain draws from terbium rare-earth concentrates, gallium metal, and specialized polishing compounds. Single-source vulnerability sits with China's dominance in heavy rare-earth chemical processing under REACH-compliant standards. Distribution runs through security-cleared prime contractors for defense tiers and specialized photonics distributors for research segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized opticians capable of achieving ISO 10110 surface quality on magneto-optic crystals require 18-24 month training cycles, creating a persistent capability gap that constrains supplier expansion and defends incumbent positioning.
For Market Incumbents: Fortify backward integration into terbium supply chains to offset China's rare-earth processing dominance and REACH chemical restriction exposure. Expand captive polishing capacity in Thuringia's Jena cluster to capture margin from defense contractors consolidating procurement through cleared channels. Semiconductor-based rotator entrants threaten crystal-based volume in datacom modules. For New Entrants and Emerging Players: Lead with semiconductor-based waveguide-integrated designs targeting cloud datacenter 400G and 800G coherent transceiver modules, the most penetrable segment given footprint compression requirements. Avoid defense-tier competition where facility clearance requirements filter vendor pools. Pursue foundry partnerships with silicon photonics capabilities for rapid scale. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertically integrated crystal growers with captive TGG boule production and established defense contractor relationships. Long-term viability favors suppliers with dual-use compliance documentation capabilities and MIIT-qualification for China's state-funded fiber projects. Watch for inflection in semiconductor-based rotator yield rates at commercial foundries.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Terbium Supply | Captive rare-earth sourcing mitigates REACH chemical restriction exposure and China's export quota volatility. |
| ISO 10110 Polishing Capacity Expansion | Thuringia's Jena cluster offers specialized optician training pipelines for defense-tier surface quality qualification. |
| Semiconductor Foundry Partnership | Silicon photonics integration enables 400G/800G datacom module packaging for cloud operator procurement cycles. |
| MIIT Qualification Pathway | China's domestic content mandates in state-funded fiber projects redirect procurement toward indigenous TGG capabilities. |
| FDA 510(k) Certification Investment | Pre-certified isolator subassemblies create captive demand from surgical laser OEMs absorbing compliance costs. |
Research Methodology
A standing panel of defense procurement officers, laser system integrators, TGG crystal growth engineers, and photonics distribution specialists provided ongoing calibration throughout the study period. This primary fieldwork combined with secondary validation from SEC filings of listed optical component manufacturers, MIIT optical device standard disclosures, FDA 510(k) clearance databases, and ECHA REACH substance restriction updates. Bottom-up shipment data triangulated against top-down defense budget allocation analysis.
Consistency checks validated volume and value outputs against hyperscaler datacom capex disclosures and fiber backbone operator amplifier deployment schedules across the analysis window. The analytical framework modeled product type, technology architecture, end-user certification tier, and application-specific performance requirements. CAGRs derived from segmented growth rate reconciliation with macroeconomic indicators and regulatory timeline assumptions. Forecast inputs incorporated terbium spot price trajectories and semiconductor foundry yield improvement curves.
The analysis sits within stated boundaries; outcomes outside sustained defense-directed energy funding levels, MIIT localization policy continuity, or REACH chemical restriction enforcement would require recalibration. Forecasts reflect documented assumptions regarding rare-earth supply chain stability and coherent transceiver adoption velocity. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Optical Position Sensors Market
Optical Components
Raman Amplifier Market
Optical Components
Ring Laser Gyroscope Market
Optical Components
Mid-Infrared Laser Market
Optical Components
Integrated Quantum Optical Circuits Market
Optical Components
Passive Optical Component Market
Optical Components
Diode Laser Module Market
Optical Components
Japan Lithium Niobate Modulator Market
Optical Components
Global Mask Alignment Systems Market
Optical Components
Global Optical Fiber Preform Market
Optical Components
Asia-Pacific Optical Film Market
Optical Components
Optical Amplifier Market
Optical Components
Erbium-Doped Fiber Amplifier Market
Optical Components
Co-Packaged Optics Market
Optical Components
Silicon Focus Ring Market
Optical Components
Europe Optical Imaging Market