
 Global Optical Connectivity Solutions Market | 2026-2036
Global Optical Connectivity Solutions Market Size, Share, and Industry Trends Forecast 2026-2036
Global Optical Connectivity Solutions Market Foresight
Chinese fiber producers is restructuring capacity toward higher-grade preform and specialty cable, tightening supply for Western system integrators. Corning Incorporated leverages its captive glass science portfolio to dominate premium low-loss fiber segments. Prysmian Group anchors European supply through deep manufacturing presence in Italy and France. Sumitomo Electric Industries sustains Japanese technical leadership in ribbon cable and fusion splicing ecosystems.
Optical connectivity solutions encompass photonic components, fiber infrastructure, and transmission systems engineered to carry data as light pulses across silica or plastic waveguides, typically operating at wavelengths between 1260 nm and 1625 nm with attenuation below 0.2 dB/km for single-mode fiber. These systems serve as the physical backbone for modern digital infrastructure, enabling terabit-scale throughput across distances from meters in data centers to thousands of kilometers in submarine networks. Optical transceivers capture the dominant margin pool as form factors shift from QSFP-DD to OSFP and CPO architectures, while fiber optic cables remain the volume foundation driven by data center interconnect and 5G fronthaul builds. Dense Wavelength Division Multiplexing technology leads carrier long-haul deployments, though Passive Optical Network architectures accelerate in broadband access where cost-per-subscriber dominates procurement decisions.
The FCC in the United States mandates open access and interoperability standards for federally subsidized rural broadband deployments, directly shaping supplier qualification requirements and product roadmaps. ETSI and the EU AI Act impose energy efficiency and cybersecurity conformity pressures on optical transport equipment sold across European member states. China's MIIT enforces domestic GB standards and dual carbon compliance that filter market access for foreign component vendors. Stakeholders must monitor how divergent national certification regimes fragment procurement specifications and force parallel product development tracks.
Market Dynamics
Data center interconnect buildouts are compressing upgrade cycles from 100G to 400G and 800G, forcing component suppliers to accelerate coherent DSP development while managing thermal constraints from higher port densities.
Growth Catalysts
- Hyperscale cloud expansion:Amazon Web Services, Microsoft Azure, and Google Cloud are deploying fiber-rich architectures across Virginia, Oregon, and Iowa facilities, consuming ribbon cable and MPO connectors at volumes that reshape supplier allocation priorities.
- F-Gas Regulation compliance pressure:The EU mandate on fluorinated greenhouse gases is accelerating replacement of refrigerant-cooled optical transport with liquid-cooled and ambient-tolerant designs, creating pull-through demand for thermally optimized transceivers.
- Coherent pluggable modules:400G ZR and 800G ZR+ standards are collapsing traditional optical line system hierarchies, allowing router vendors to integrate optical transport functions and bypass incumbent subsystem suppliers.
Market Restraints
- Preform supply concentration:Chinese producers control approximately 60 percent of optical fiber preform capacity, exposing Western cable manufacturers to export license unpredictability and input cost volatility during trade friction episodes.
- Raw material scarcity:Germanium and erbium dopants for fiber amplification face extraction bottlenecks from Chinese and Russian supply chains, constraining specialty fiber output for submarine and long-haul applications.
- Technical limitation in hollow-core fiber:Photonic bandgap structures promise lower latency and nonlinear distortion but remain confined to sub-10 kilometer distances, blocking data center interconnect deployment at scale.
Strategic Opportunities
- Rural broadband subsidy programs:The FCC's Rural Digital Opportunity Fund and comparable programs in India and Brazil are unlocking greenfield fiber-to-the-home deployments where passive optical network equipment can capture first-mover positions.
- Convergence of silicon photonics and electronic packaging:Co-packaged optics integration with switch ASICs is eliminating retimer power and PCB trace losses, enabling 51.2 Tbps switch capacities that redefine rack-scale architecture.
- Submarine cable system renewal cycle:Trans-Pacific and trans-Atlantic routes installed during the 2001-2003 buildout are reaching end-of-life, creating replacement demand for space-division multiplexing cables with 24+ fiber pairs.
Industry Challenges
- Coherent DSP engineering talent scarcity:The intersection of analog circuit design, forward error correction algorithms, and high-speed packaging requires skill sets concentrated at fewer than ten institutions globally, constraining vendor expansion.
- Interoperability certification timelines:Open ROADM and OpenZR+ compliance testing at University of New Hampshire InterOperability Laboratory and EANTC extends product launch schedules by 6-12 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Optical Connectivity Solutions Market |
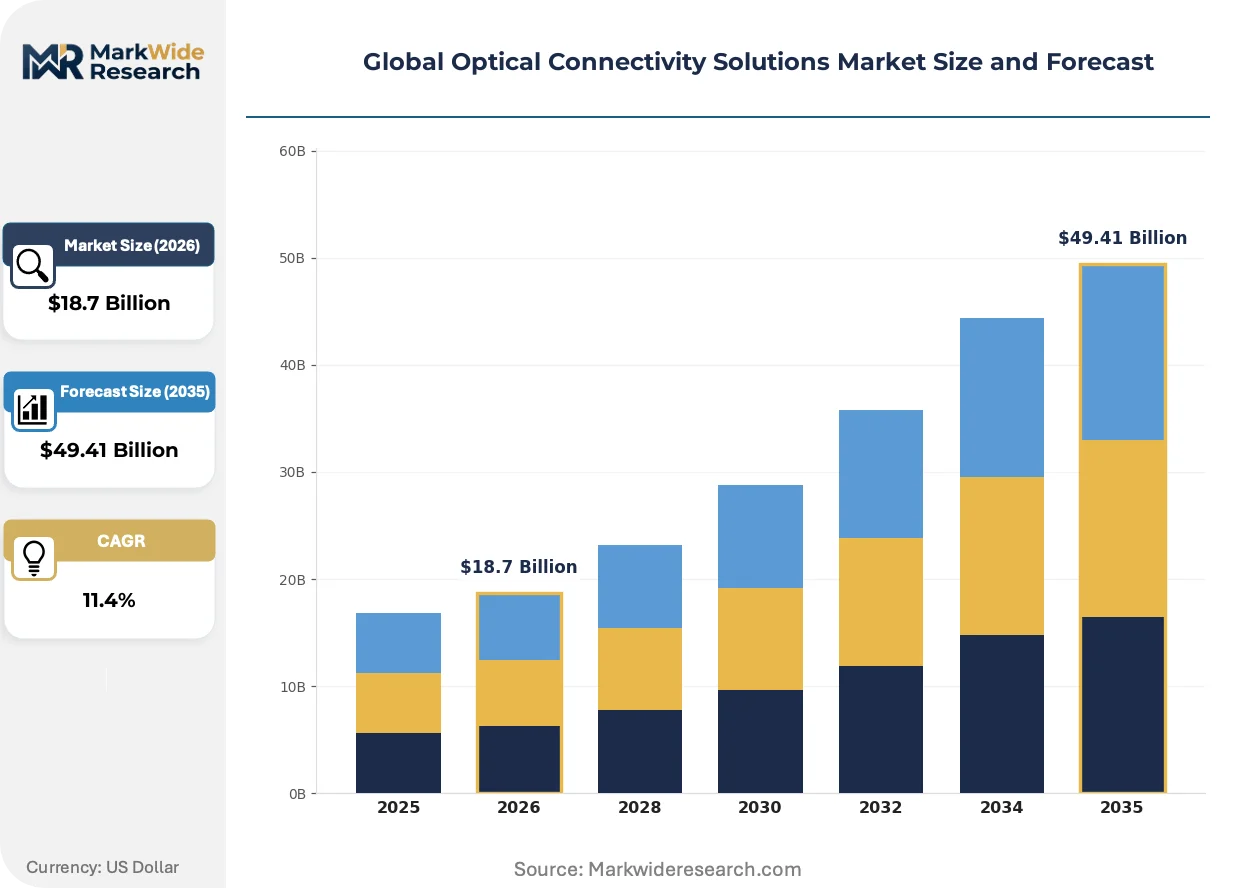
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $49.41 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Transceivers, Fiber Optic Cables, Optical Switches, Optical Amplifiers, Optical Connectors Technology: Dense Wavelength Division Multiplexing, Coarse Wavelength Division Multiplexing, Passive Optical Network, Fiber to the Home, Optical Transport Network Application: Telecommunication Networks, Data Centers, Military Communications, Enterprise Networks, Broadcast Networks End User: Internet Service Providers, Cloud Service Providers, Government Agencies, Defense Organizations, Media & Entertainment Firms |
| Companies Covered | Corning Incorporated, Prysmian Group, Sumitomo Electric Industries, Ltd., Furukawa Electric Co., Ltd., Amphenol Corporation, TE Connectivity Ltd., Huawei Technologies Co., Ltd., CommScope Holding Company, Inc., Ciena Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Optical Connectivity Solutions Market Shifts & Advancements
Optical transport architecture is undergoing fundamental restructuring as pluggable coherent optics displace embedded line systems and artificial intelligence workloads reshape traffic patterns between compute clusters.
Co-packaged optics is automating the elimination of retimers and re-timers between switch ASICs and front-panel pluggable modules. Hyperscale operators in California and Singapore are piloting 51.2 Tbps switches with integrated silicon photonics engines. This convergence is automating the compression of power-per-bit metrics by 30-40 percent compared to discrete pluggable alternatives.
The EU F-Gas Regulation is mandating phase-down of hydrofluorocarbon refrigerants in network equipment cooling systems. Equipment vendors are redesigning thermal architectures around liquid cooling and ambient air economization. Long-haul transport platforms sold into Germany, France, and Netherlands face the most stringent compliance deadlines and are driving supplier roadmaps.
Hyperscale procurement patterns are consolidating optical transceiver sourcing through direct long-term agreements with module manufacturers, bypassing traditional systems integrator channels. Cloud operators in Virginia and Oregon now specify custom firmware and hardware revision locks that lock out secondary distribution. This disintermediation is most visible in 400G and 800G datacenter interconnect deployments where volume concentration enables vertical negotiation leverage.
Global Optical Connectivity Solutions Market Segmentation
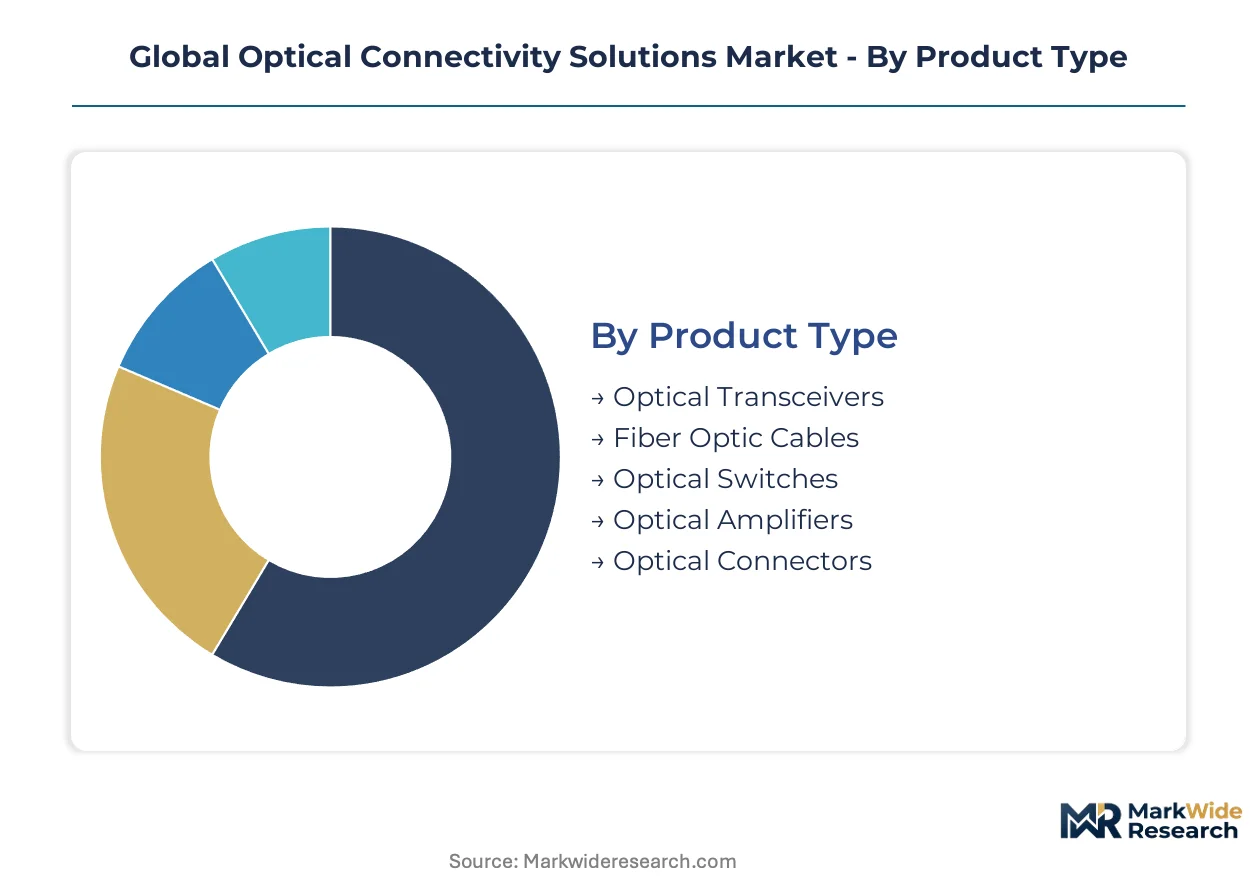
Optical connectivity solutions fragment across multiple technical and commercial axes. Each segmentation layer reveals distinct procurement patterns, margin structures, and vendor qualification requirements that shape competitive positioning.
Product Type:
Form factor evolution and thermal engineering intensity separate margin tiers across hardware categories.
- Optical Transceivers:Pluggable modules converting electrical signals to optical wavelengths through laser diodes and photodetectors. Hyperscale data centers in Virginia and Oregon specify 400G ZR+ and 800G coherent variants, driving coherent DSP development roadmaps while compressing supplier margins through direct procurement consolidation.
- Fiber Optic Cables:Silica waveguide bundles with single-mode attenuation below 0.2 dB/km, sheathed for duct, aerial, or submarine deployment. Ribbon cable configurations dominate data center interconnect builds, while loose-tube designs anchor long-haul terrestrial routes across Germany and France.
- Optical Switches:All-optical cross-connects enabling wavelength-level routing without O-E-O conversion. Metro core networks in Japan deploy these for traffic engineering flexibility.
- Optical Amplifiers:Erbium-doped fiber amplifiers and Raman pumps extending unrepeatered reach. Submarine cable systems spanning trans-Pacific routes represent the most demanding application.
- Optical Connectors:Physical terminations including MPO, LC, and SC variants with alignment tolerances below 1 micron. Data center fiber densification consumes MPO-16 and MPO-32 variants at volumes reshaping manufacturing allocation.
Mature deployment sits with Fiber Optic Cables. Newer deployment is concentrated in Optical Transceivers.
Technology:
Spectral efficiency targets and cost-per-bit economics determine architecture selection across network layers.
- Dense Wavelength Division Multiplexing:Multiplexing 80+ channels at 100 GHz spacing onto single fiber pairs. Carrier long-haul routes across the United States deploy C-band and L-band systems with coherent 800G per wave.
- Coarse Wavelength Division Multiplexing:Lower-density multiplexing at 20 nm channel spacing using uncooled lasers. Enterprise campus and mobile fronthaul applications in India prioritize cost over spectral efficiency.
- Passive Optical Network:Point-to-multipoint fiber architecture splitting optical signals to 32-64 subscribers. Rural broadband subsidy programs in Brazil and India drive GPON and XGS-PON equipment procurement.
- Fiber to the Home:Last-mile fiber termination delivering gigabit symmetrical services. Municipal builds in France and Italy accelerate as copper retirement deadlines approach.
- Optical Transport Network:ITU-standardized digital wrapper technology ensuring interoperability across vendor boundaries. European incumbent carriers mandate OTN switching for cross-border capacity exchanges.
Legacy architectures concentrate in Coarse Wavelength Division Multiplexing. Steepest expansion trajectory belongs to Passive Optical Network.
Application:
Traffic pattern diversity and latency requirements create distinct equipment specifications across verticals.
- Telecommunication Networks:National backbone and metro aggregation infrastructure serving residential and business subscribers. Incumbent operators in Germany and Japan upgrade to 400G coherent metro to manage video traffic growth.
- Data Centers:Internal fiber plant and external interconnects enabling compute cluster communication. Cloud operators in Iowa and Singapore specify MPO-32 trunk cables and 800G OSFP transceivers for AI training clusters.
- Military Communications:Hardened optical transport for tactical and strategic networks. Defense procurement in the United States requires TEMPEST shielding and anti-jamming waveforms.
- Enterprise Networks:Campus and data center interconnect for private infrastructure. Financial services firms in London and New York deploy dark fiber for trading latency minimization.
- Broadcast Networks:Contribution and distribution fiber for uncompressed video transport. Sports production networks across Europe adopt 12G-SDI over fiber for 4K remote production.
Established infrastructure concentrates in Telecommunication Networks. Gaining share fastest is Data Centers.
End User:
Procurement scale and technical specification authority vary sharply across buyer categories.
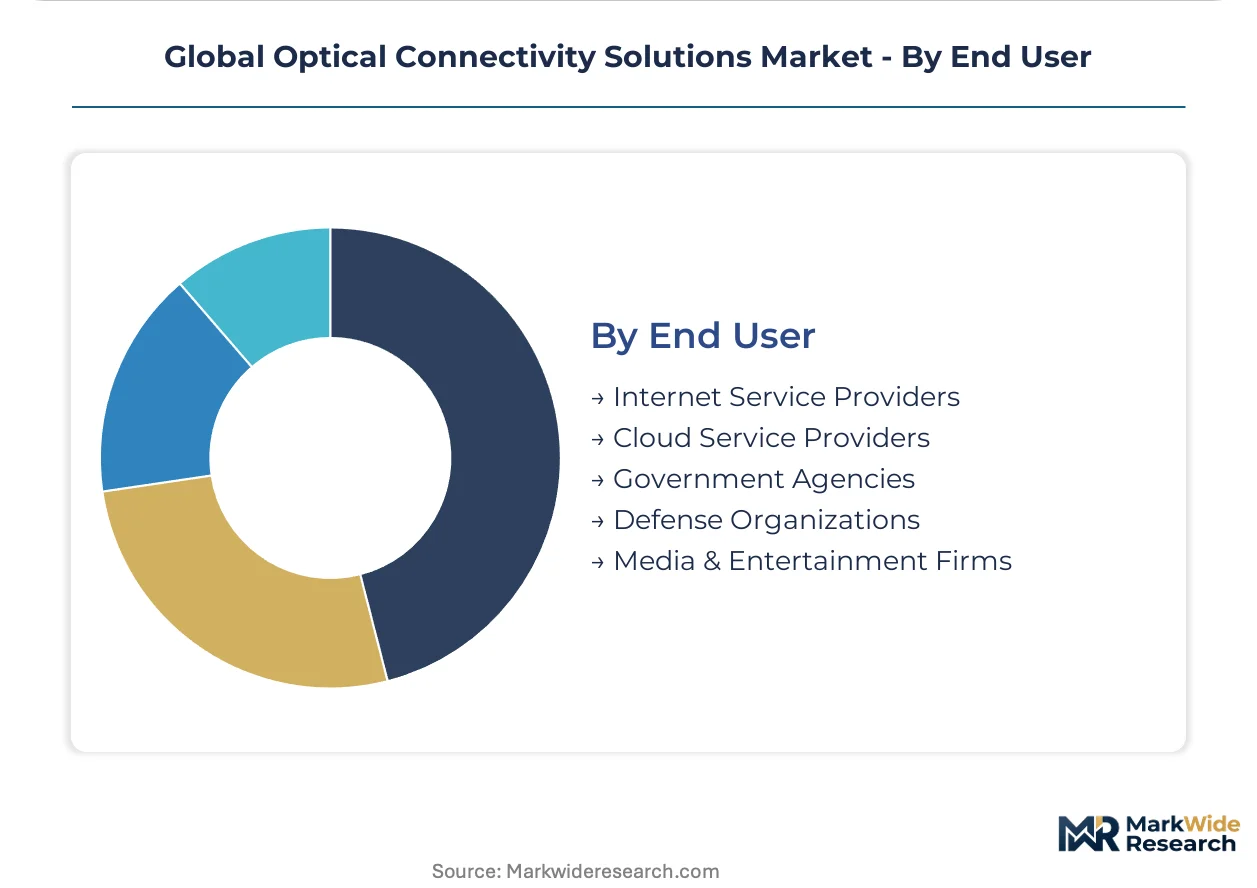
- Internet Service Providers:Fixed and mobile network operators purchasing access and aggregation equipment. Tier-1 ISPs in the United States negotiate multi-year transceiver supply agreements with direct manufacturer engagement.
- Cloud Service Providers:Hyperscale operators designing custom optical hardware for internal data center fabrics. Amazon Web Services, Microsoft Azure, and Google Cloud specify firmware-locked modules bypassing distribution channels.
- Government Agencies:National broadband authorities and rural connectivity programs. The FCC's Rural Digital Opportunity Fund shapes supplier qualification through open access mandates.
- Defense Organizations:Military procurement commands with security-cleared supply chain requirements. Program offices in the United States and United Kingdom specify ruggedized connectors and classified encryption modules.
- Media & Entertainment Firms:Broadcasters and content distributors deploying contribution fiber networks. Live sports rights holders in Europe and North America drive low-latency optical circuit procurement.
Volume concentration sits with Internet Service Providers. Procurement innovation is concentrated in Cloud Service Providers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germanium and erbium extraction from Chinese and Russian supply chains shapes regional production capabilities across optical amplification and specialty fiber manufacturing.
United States
Hyperscale cloud buildouts in Virginia and Oregon strain interconnection capacity, driving ribbon cable and MPO connector procurement at volumes reshaping supplier allocation. The FCC mandates open access standards for federally subsidized rural broadband deployments through the Rural Digital Opportunity Fund. Data center clusters in Iowa and the Pacific Northwest specify 800G OSFP transceivers for AI training infrastructure.
Germany
Incumbent carriers upgrade metro aggregation to 400G coherent systems managing video traffic growth across residential and business subscribers. The EU F-Gas Regulation imposes stringent phase-down deadlines for hydrofluorocarbon refrigerants in network equipment cooling. Manufacturing presence in the Eindhoven-adjacent corridor and domestic production facilities anchor European supply for thermally optimized transport platforms.
China
Domestic producers control approximately sixty percent of optical fiber preform capacity, restructuring output toward higher-grade preform and specialty cable. The Ministry of Industry and Information Technology enforces GB standards and dual carbon compliance filtering market access for foreign component vendors. Yangtze River Delta manufacturing clusters concentrate output for data center interconnect and 5G fronthaul builds.
Japan
Technical leadership in ribbon cable and fusion splicing ecosystems sustains competitive positioning in high-precision connectivity components. METI standards and procurement guidelines shape domestic equipment qualification requirements for carrier and enterprise deployments. Kanto and Kansai industrial corridors host concentrated R&D activity for next-generation coherent DSP development.
India
Rural broadband subsidy programs unlock greenfield fiber-to-the-home deployments where passive optical network equipment captures first-mover positions. TRAI regulations and national broadband authority frameworks govern supplier qualification for federally supported connectivity expansion. Metropolitan clusters in Maharashtra and Karnataka concentrate system integration capacity for GPON and XGS-PON equipment deployment.
Global Optical Connectivity Solutions Market Competitive Landscape
Global majors compete with regional champions across captive material science capabilities and geographic manufacturing footprint. Market structure consolidates around three tiers: integrated glass science specialists, cable and connectivity fabricators, and coherent transport subsystem vendors. Strategic archetypes include captive preform producers, assembly-scale system integrators, and DSP-focused transport technology developers. Dominant competitive moves center on backward integration into preform manufacturing and direct procurement relationships bypassing traditional distribution channels.
Among integrated material science specialists, Corning Incorporated and Prysmian Group exemplify archetypes defined by captive glass portfolios and deep European manufacturing presence. Sumitomo Electric Industries occupies a position representing Japanese technical leadership in precision connectivity ecosystems. These three entities anchor tier-one supply relationships with hyperscale operators and incumbent carriers across North America, Europe, and Asia-Pacific respectively.
| Leading Market Players |
|---|
| Corning Incorporated |
| Prysmian Group |
| Sumitomo Electric Industries, Ltd. |
| Furukawa Electric Co., Ltd. |
| Amphenol Corporation |
| TE Connectivity Ltd. |
| Huawei Technologies Co., Ltd. |
| CommScope Holding Company, Inc. |
| Ciena Corporation |
| Others |
Supply & Pricing Matrix
Coherent DSP engineering talent concentrated in Kanto and Kansai industrial corridors creates labor-cost differentials that widen pricing-tier spreads between premium coherent modules and standard pluggable transceivers. European F-Gas Regulation compliance investments further stratify cost structures, forcing buyers to absorb thermal-architecture premiums or accept shortened warranty terms.
Pricing Analysis
Warranty bundling separates premium-tier coherent transceivers from economy alternatives, with 400G ZR+ modules including field-replacement guarantees and firmware-update entitlements while standard pluggables carry depot-only service. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation—OpenZR+ compliance at University of New Hampshire InterOperability Laboratory commands measurable premiums over non-certified alternatives. Pricing pressure stems from hyperscale direct procurement consolidation in Virginia and Oregon, where cloud operators negotiate volume locks that bypass distribution markups. Cloud service providers exhibit lowest price sensitivity given total-cost-of-ownership framing, while rural broadband ISPs operating under FCC subsidy programs face stringent cost-per-subscriber constraints.
Supply Chain Analysis
Reverse-logistics flows for failed transceiver modules concentrate refurbishment capacity in Shenzhen and Dongguan manufacturing clusters, creating secondary supply channels for warranty-replacement inventory. Raw material sourcing draws from Chinese preform production, Japanese specialty-dopant refining, and German precision-connector machining. Germanium and erbium extraction bottlenecks from Chinese and Russian supply chains expose amplification-component manufacturers to input scarcity. Distribution runs through direct long-term agreements between hyperscale operators and module manufacturers, disintermediating traditional systems integrator channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The EU F-Gas Regulation functions as a cost-of-compliance moat, elevating capital requirements for thermal-architecture redesign and filtering non-compliant vendors from European long-haul transport procurement.
For Market Incumbents: Acquire captive preform manufacturing capacity to offset Chinese export-license unpredictability threatening Western cable manufacturers. Consolidate coherent DSP engineering teams through targeted recruitment from Kanto and Kansai R&D corridors, reinforcing technical differentiation against router-vendor optical integration threats. Expand liquid-cooled transport platform production in Eindhoven-adjacent manufacturing corridors to capture F-Gas Regulation-driven replacement cycles. For New Entrants and Emerging Players: Begin with rural broadband subsidy programs in India and Brazil, where passive optical network equipment procurement lacks entrenched incumbent relationships and qualification timelines favor agile responders. Target GPON and XGS-PON deployment in Maharashtra and Karnataka metropolitan clusters, leveraging local system integration partnerships to bypass direct-hyperscale channel consolidation. Position through open-access interoperability certification to qualify for FCC Rural Digital Opportunity Fund mandates. For Investors and Strategic Acquirers: Re-rating potential sits with silicon photonics specialists given co-packaged optics integration catalysts compressing power-per-bit metrics by 30-40 percent. Long-term viability favors vendors with backward integration into glass science and captive preform supply, insulating against raw-material scarcity and trade-friction volatility. Monitor hyperscale capex disclosure patterns for AI training cluster buildouts as inflection signals for 800G OSFP and CPO architecture demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Preform Manufacturing | Captive glass science insulates Prysmian and Corning from Chinese export-license unpredictability. |
| Co-Packaged Optics Platform Development | Silicon photonics integration with switch ASICs enables 51.2 Tbps capacities for AI clusters in Singapore. |
| OpenZR+ Interoperability Certification | University of New Hampshire testing qualifies vendors for hyperscale direct procurement bypassing distribution. |
| Liquid-Cooled Transport Architecture Redesign | F-Gas Regulation deadlines in Germany and France mandate thermal redesign for long-haul platform sales. |
| Rural Broadband Subsystem Partnership | FCC Rural Digital Opportunity Fund unlocks greenfield GPON deployment with first-mover positioning. |
Research Methodology
Document review covered SEC 10-K filings from optical component vendors, ETSI technical specifications, FCC Rural Digital Opportunity Fund disbursement records, and MIIT GB standards documentation, complemented by interviews with data center procurement officers at hyperscale operators, coherent DSP engineering directors, fiber cable plant managers, and optical transport equipment product managers. Secondary validation drew from hyperscaler capex disclosure analysis, submarine cable system installation databases, and customs trade data for preform and specialty fiber flows. Bottom-up segment sizing triangulated against top-down macroeconomic demand modeling.
Output modeling produced volume and value trajectories across the projection horizon by segmenting across product type, technology architecture, application vertical, and end-user procurement authority. CAGRs derived from regression analysis against hyperscale facility buildout announcements, carrier coherent upgrade disclosed pipelines, and rural broadband subsidy program appropriation schedules. Forecast inputs incorporated thermal-design roadmaps responding to F-Gas Regulation phase-down deadlines and coherent pluggable standards evolution timelines.
Underlying measurement precision varies by segment; data center interconnect and hyperscale transceiver procurement carry tighter precision than military communications and broadcast network verticals given disclosure transparency differentials. Forecasts reflect assumptions regarding trade-friction stability, germanium/erbium supply continuity, and coherent DSP engineering talent pipeline expansion. Practitioners should monitor Chinese preform export-license policy shifts and hyperscale AI cluster capex acceleration for early signals warranting forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Pancake Optical Module Market
Optical Components
Planar Lightwave Circuit Splitter Market
Optical Components
Objective Lens Market
Optical Components
UAE Lithium Niobate Modulator Market
Optical Components
Optical Image Stabilization (OIS) Actuators Market
Optical Components
Diode Laser Module Market
Optical Components
CW Fiber Amplifier Market
Optical Components
Optical Waveguide Market
Optical Components
Electro Optical System Market
Optical Components
Liquid Light Guides Market
Optical Components
Optical Interconnect Market
Optical Components
Terbium Gallium Garnet Market
Optical Components
ROADM WSS Component Market
Optical Components
Mobile Optical Pluggable Market
Optical Components
Global Fiber Optic Gyroscope Market
Optical Components
Picosecond and Femtosecond Fiber Lasers Market