
 Laser Module Market | 2026-2036
Laser Module Market Size, Share, and Industry Trends Forecast 2026-2036
Laser Module Market Analytics
Aftermarket service revenue for laser module recalibration and fiber replacement is rewriting profit allocation across the value chain. IPG Photonics Corporation leverages its captive fiber production to sustain premium positioning in high-power industrial installations. Trumpf SE + Co. KG anchors European demand through integrated beam source-to-system architectures. Coherent Corp. competes across medical, industrial, and semiconductor lithography wavelengths with broad portfolio coverage.
A laser module integrates a gain medium, optical resonator, and pump source into a self-contained unit that emits coherent light at specified wavelengths, output powers, and beam quality parameters measured by M-squared values; industrial systems typically operate at 1,064 nm for metals processing or 1,070 nm for reflective alloys, while medical variants target 2,940 nm for soft-tissue ablation. Fiber lasers now lead power ratings above six kilowatts where wall-plug efficiency exceeds forty percent, diode lasers dominate low-power marking and sensing applications with smallest form factors, and solid-state architectures retain share in ultra-short-pulse scientific and micromachining segments where picosecond stability commands margin premiums. Electronics manufacturing applications for microsoldering and wafer dicing are expanding fastest among end-user verticals as miniaturization requirements intensify.
FDA device classification rules, the EU MDR CE marking pathway, and China's NMPA technical review standards for medical laser products each impose distinct clinical validation and electromagnetic compatibility testing burdens that shape product development roadmaps. OSHA laser safety standards in the United States and IEC 60825 international classifications dictate enclosure engineering, interlock design, and operator training protocols for industrial installations. Stakeholders must monitor divergence between regional wavelength-specific exposure limits and emerging semiconductor process requirements as next-generation node transitions redefine source specifications.
Market Dynamics
Fiber laser architectures above six kilowatts are compressing solid-state and CO₂ alternatives across metal fabrication, while FDA 21 CFR Part 820 and EU MDR traceability mandates are restructuring supplier qualification protocols for clinical-grade modules.
Growth Catalysts
- Automotive lightweighting:Stuttgart and Munich manufacturing clusters are scaling fiber laser welding for aluminum-intensive electric vehicle architectures, pulling demand for kilowatt-class modules with active beam shaping.
- FDA 21 CFR Part 820:Quality system regulations for surgical laser devices are mandating documented beam stability validation, creating captive demand for recalibration service contracts among US medical device OEMs.
- Silicon carbide pump diodes:Advances in wide-bandgap semiconductor pumps are extending fiber laser wall-plug efficiency above forty percent in industrial cutting applications above six kilowatts.
Market Restraints
- Rare-earth fiber supply:Ytterbium-doped fiber preform production concentrates among a handful of specialty glass manufacturers, creating input cost volatility and qualification bottlenecks for new module entrants.
- EU MDR clinical validation:The CE marking pathway for medical laser products now requires extended electromagnetic compatibility testing and post-market surveillance infrastructure, extending product development timelines.
- Ultrafast laser substitution:Picosecond and femtosecond solid-state systems retain performance advantages in cold ablation micromachining, limiting fiber laser penetration in semiconductor wafer dicing applications.
Strategic Opportunities
- India electronics manufacturing:PLI scheme incentives for semiconductor and mobile device production are creating greenfield demand for precision marking and microsoldering laser modules in Noida and Chennai clusters.
- Battery cell welding:Tab-to-busbar laser joining for cylindrical and prismatic lithium-ion cells represents an emerging application with distinct beam parameter requirements from traditional metal cutting.
- OSHA laser safety standard updates:Revised enclosure and interlock specifications for Class 4 industrial installations are creating retrofit demand for legacy CO₂ and Nd:YAG system replacements.
Industry Challenges
- Optical engineer scarcity:Specialized expertise in resonator design and beam quality characterization (M-squared metrology) concentrates among aging workforces in Germany and the United States, constraining module development velocity.
- Multi-jurisdiction certification:Simultaneous FDA 510(k), EU MDR, and China NMPA technical reviews for medical laser products require parallel documentation streams and divergent clinical evidence standards.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laser Module Market |
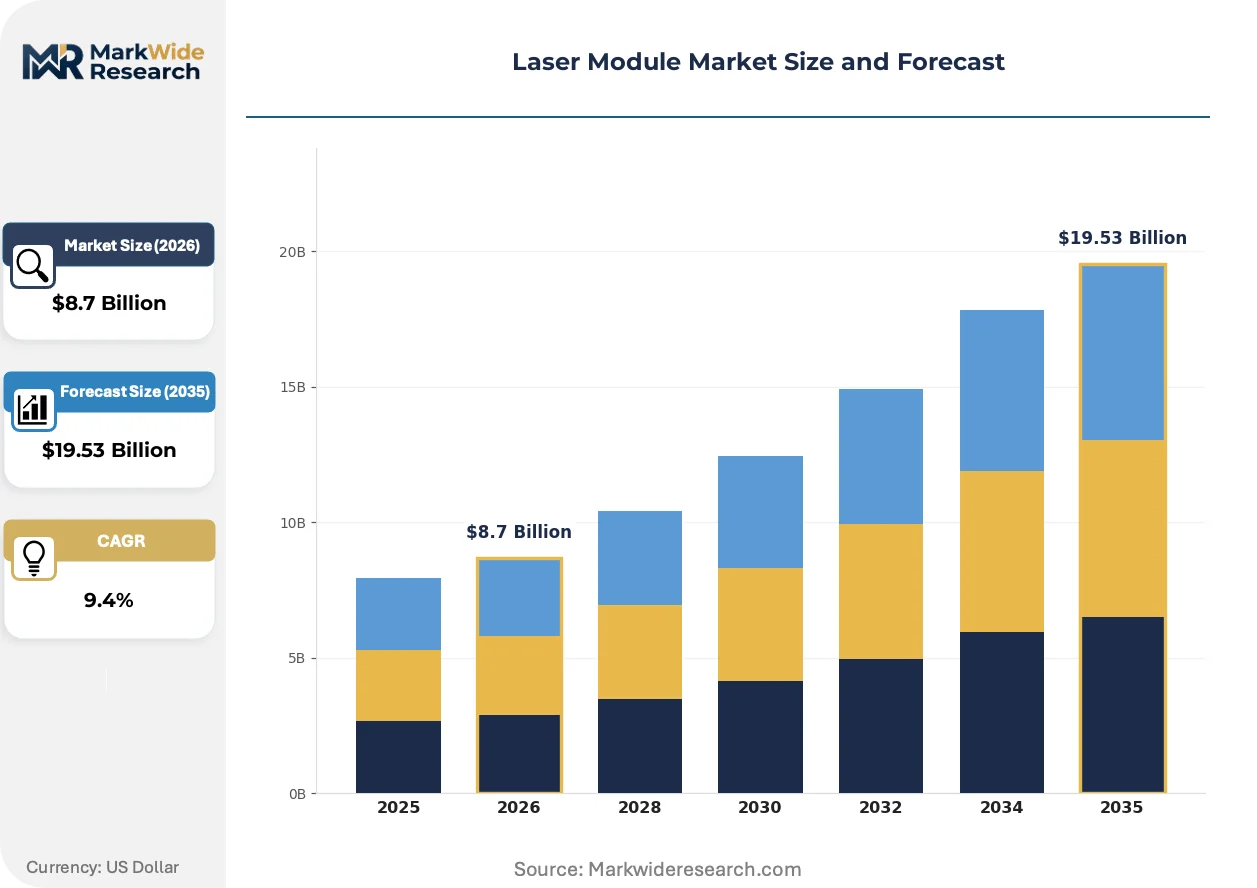
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Diode Lasers, Fiber Lasers, Solid-State Lasers, Gas Lasers Application: Cutting, Welding, Marking, Medical Procedures End User: Aerospace, Automotive OEMs, Electronics Manufacturing, Healthcare Facilities Power Rating: Low Power, Medium Power, High Power, Ultra High Power |
| Companies Covered | Coherent Corp., IPG Photonics Corporation, Jenoptik AG, Lumentum Holdings Inc., ams-OSRAM AG, MKS Instruments, ROHM Co., Ltd., Hamamatsu Photonics K.K., Trumpf SE + Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laser Module Market Evolving Landscape
Beam delivery architectures and wavelength conversion technologies are restructuring competitive boundaries between fiber, solid-state, and direct-diode platforms across industrial and medical applications.
Single-mode fiber laser platforms with beam quality factors below 1.3 are collapsing the performance gap with solid-state sources in precision micromachining below fifty microns. Electronics manufacturers in Japan and South Korea are adopting these systems for flexible circuit trimming at speeds previously requiring picosecond lasers. The technology is collapsing margin premiums historically commanded by scientific-grade ultrafast systems in mid-precision applications.
EU MDR Article 10 and Annex I general safety requirements are mandating Unique Device Identification and enhanced post-market surveillance for active implantable and surgical laser equipment. German and Swiss medical technology manufacturers are restructuring supplier qualification to capture full beam source traceability from preform to finished module. Clinical-grade product development roadmaps now integrate regulatory affairs resources earlier in concept phase.
Aftermarket service unbundling is separating hardware procurement from lifetime recalibration and fiber replacement contracts in industrial installations. German automotive OEMs and their tier suppliers are negotiating outcome-based uptime agreements rather than capital purchase models. This pattern concentrates in high-volume welding cells where unplanned downtime costs exceed module replacement value.
Laser Module Market Segmentation
Laser module procurement cycles vary dramatically by technology maturity and application criticality. Replacement intervals for consumable pump diodes compress to months, while capital-intensive fiber laser installations stretch across years. Understanding these velocity differentials shapes inventory strategies and service revenue forecasting.
Type:
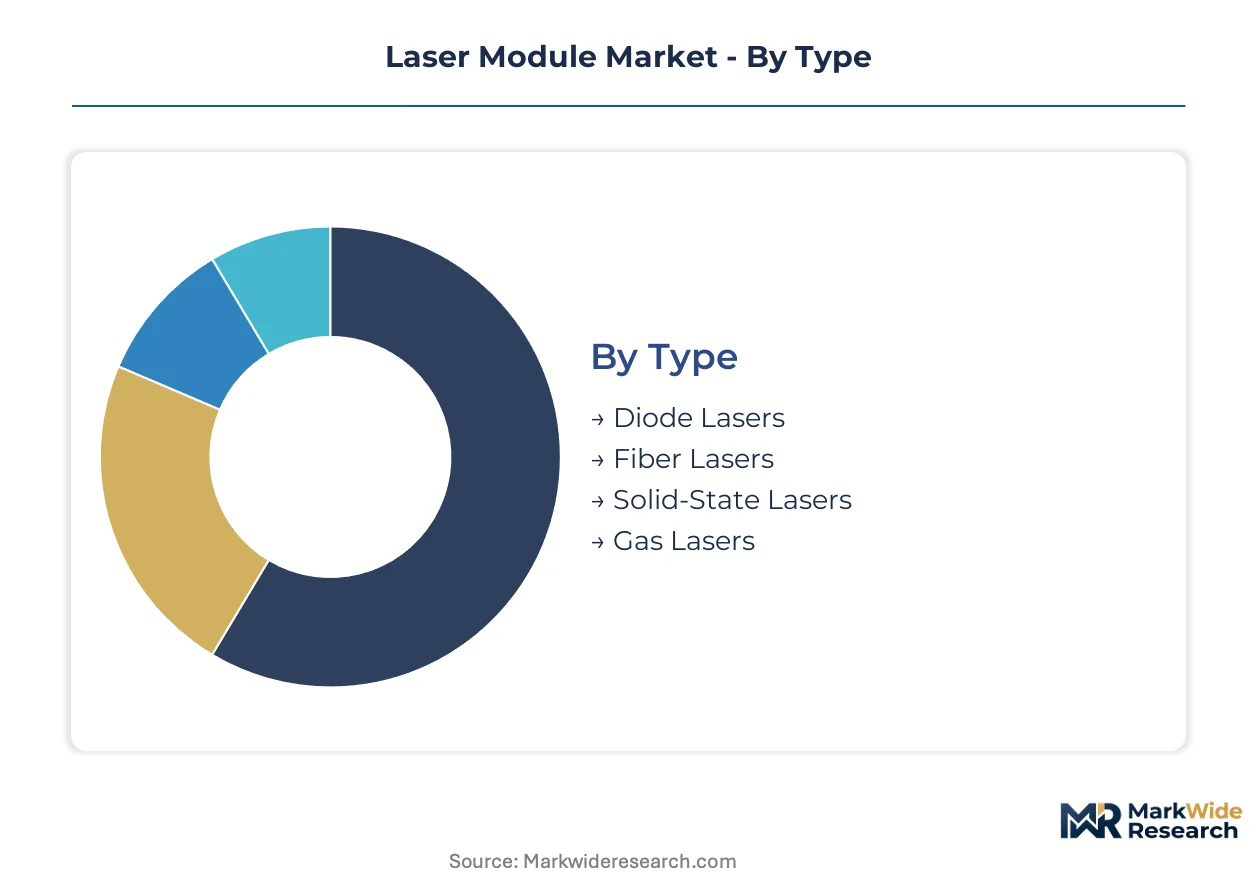
Cycle times separate dramatically here—diode modules turn over fastest due to pump degradation, while gas laser tubes require multi-year replacement schedules.
- Fiber Lasers:Ytterbium-doped fiber architectures dominate installations above six kilowatts with wall-plug efficiency exceeding forty percent. Stuttgart and Munich automotive clusters are standardizing on these systems for aluminum-intensive electric vehicle welding, though rare-earth fiber preform supply concentration creates qualification bottlenecks for new entrants.
- Diode Lasers:Compact form factors and direct electrical-to-optical conversion make these the default for low-power marking and sensing applications. Electronics manufacturers in Japan and South Korea are adopting single-mode platforms with beam quality factors below 1.3 for flexible circuit trimming at speeds previously requiring solid-state systems.
- Solid-State Lasers:Nd:YAG and vanadate crystals retain dominance in picosecond and femtosecond ultrafast segments where cold ablation micromachining commands margin premiums. Scientific and semiconductor wafer dicing applications favor these architectures for pulse stability.
- Gas Lasers:CO₂ molecular gas discharge tubes continue serving legacy cutting installations despite fiber laser displacement, with longest replacement cycles in the category. OSHA laser safety standard updates for Class 4 enclosures are accelerating retrofit demand.
Diode lasers anchor the volume base while fiber lasers gain share at the steepest rate.
Application:
Cost tier stratification separates capital-intensive welding cells from consumable-heavy marking operations.
- Cutting:High-power fiber platforms above six kilowatts have compressed CO₂ alternatives across metal fabrication. German precision manufacturing belts around Stuttgart and Munich are driving demand for active beam shaping capabilities in thick-section processing.
- Welding:Battery cell tab-to-busbar joining for cylindrical and prismatic lithium-ion cells represents emerging demand with distinct beam parameter requirements. Automotive OEMs are negotiating outcome-based uptime agreements rather than capital purchase models.
- Marking:Low-power diode systems dominate product identification and traceability applications with smallest form factors. India PLI scheme incentives for semiconductor and mobile device production are creating greenfield demand in Noida and Chennai clusters.
- Medical Procedures:Soft-tissue ablation at 2,940 nm and surgical precision applications require FDA 21 CFR Part 820 documented beam stability validation. EU MDR CE marking pathways now mandate extended electromagnetic compatibility testing and post-market surveillance infrastructure.
Cutting commands the installed value base while medical procedures expand most quickly on regulatory-driven replacement cycles.
End User:
Customer type determines procurement sophistication and service contract attachment rates.
- Automotive OEMs:Integrated beam source-to-system architectures anchor European demand through captive qualification protocols. Tier suppliers are unbundling aftermarket service contracts for lifetime recalibration and fiber replacement.
- Electronics Manufacturing:Microsoldering and wafer dicing applications are expanding fastest among verticals as miniaturization requirements intensify. Japan and South Korea manufacturers are collapsing margin premiums historically commanded by scientific-grade ultrafast systems.
- Healthcare Facilities:FDA device classification rules and EU MDR clinical validation requirements impose distinct development roadmaps. Multi-jurisdiction certification demands parallel documentation streams for simultaneous FDA 510(k), EU MDR, and China NMPA technical reviews.
- Aerospace:Stringent traceability and qualification protocols favor established suppliers with documented beam source provenance from preform to finished module. German and Swiss medical technology manufacturers are restructuring supplier qualification to capture full provenance chains.
Automotive OEMs anchor the volume base while electronics manufacturing climbs the fastest on semiconductor process transitions.
Power Rating:
Supply concentration intensifies at the upper extreme where silicon carbide pump diode advances are extending efficiency boundaries.
- High Power:Fiber laser architectures above six kilowatts are displacing solid-state and CO₂ alternatives across metal fabrication. Wide-bandgap semiconductor pumps are extending wall-plug efficiency above forty percent in industrial cutting applications.
- Ultra High Power:Emerging battery cell welding and heavy-section processing applications are defining beam parameter requirements distinct from traditional cutting. Active beam shaping capabilities are becoming standard specification elements.
- Medium Power:Precision marking and microsoldering applications in electronics manufacturing concentrate demand here. Single-mode platforms with beam quality factors below 1.3 are penetrating mid-precision segments.
- Low Power:Smallest form factor diode lasers dominate sensing and identification applications with shortest replacement cycles. India PLI scheme incentives are stimulating greenfield procurement in emerging manufacturing clusters.
High power anchors the revenue base while ultra high power shows the steepest expansion trajectory on battery welding adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply by geography: Germany and China favor high-power industrial fiber lasers for metal fabrication, while the United States concentrates medical-grade procurement under stringent FDA validation protocols, and Japan prioritizes precision electronics manufacturing with single-mode platforms.
United States
FDA 21 CFR Part 820 quality system regulations are mandating documented beam stability validation for surgical laser devices, creating captive demand for recalibration service contracts among medical device OEMs. Boston and Minneapolis medical technology clusters are scaling purchases of fiber laser modules for precision surgical applications. OSHA laser safety standards dictate enclosure engineering and interlock design protocols for industrial installations.
Germany
Stuttgart and Munich manufacturing clusters are scaling fiber laser welding for aluminum-intensive electric vehicle architectures, pulling demand for kilowatt-class modules with active beam shaping. EU MDR CE marking pathways now require extended electromagnetic compatibility testing and post-market surveillance infrastructure for clinical-grade modules. Baden-Württemberg precision manufacturing belts anchor European demand through integrated beam source-to-system architectures.
China
NMPA technical review standards for medical laser products impose distinct clinical validation burdens that shape product development roadmaps alongside electromagnetic compatibility testing requirements. Yangtze River Delta electronics manufacturing hubs are adopting single-mode fiber laser platforms for flexible circuit trimming applications. The country's dual carbon goals are accelerating displacement of CO₂ laser tubes with wall-plug-efficient fiber alternatives.
Japan
METI industrial policy is supporting precision manufacturing upgrades that favor beam quality factors below 1.3 in mid-precision micromachining segments. Kanto and Kansai electronics manufacturers are collapsing margin premiums historically commanded by scientific-grade ultrafast systems through adoption of advanced fiber platforms. JIS standards govern optical performance characterization in domestic procurement specifications.
India
PLI scheme incentives for semiconductor and mobile device production are creating greenfield demand for precision marking and microsoldering laser modules. Noida and Chennai manufacturing clusters represent emerging procurement centers as miniaturization requirements intensify across electronics verticals. BIS certification requirements are structuring supplier qualification protocols for imported beam sources.
Laser Module Market Competitive Landscape
Capability concentration sits with one tier; scale advantage sits with another. The vendor base separates between integrated beam source-to-system architects and specialized component suppliers. Three archetypes dominate: captive fiber producers controlling rare-earth preform supply, broad-wavelength portfolio players spanning medical-industrial-semiconductor applications, and precision medical specialists with regulatory affairs integration. M&A activity targets beam delivery technology assets, while capacity expansion concentrates in wide-bandgap pump diode fabrication.
Within the integrated architecture tier, Trumpf SE + Co. KG anchors European demand through its German GmbH structure, while IPG Photonics Corporation exemplifies the captive fiber production archetype with in-house control over ytterbium-doped preform supply. Coherent Corp. occupies a position across multiple wavelength segments with portfolio breadth spanning clinical, industrial, and lithography applications. These three represent distinct competitive vectors: system integration, upstream supply control, and diversification across end-use verticals.
| Leading Market Players |
|---|
| Coherent Corp. |
| IPG Photonics Corporation |
| Jenoptik AG |
| Lumentum Holdings Inc. |
| ams-OSRAM AG |
| MKS Instruments |
| ROHM Co., Ltd. |
| Hamamatsu Photonics K.K. |
| Trumpf SE + Co. KG |
| Others |
Value Network & Pricing Analysis
Rare-earth fiber preform supply concentration among German and Japanese specialty glass manufacturers determines both three-tier pricing stratification across clinical, industrial, and economy-grade modules and the geographic shape of qualification-dependent procurement networks. This input bottleneck compresses margins for non-integrated assemblers while amplifying pricing power for captive fiber producers serving FDA-validated medical device OEMs.
Pricing Analysis
Long-term offtake contracts dominate procurement for kilowatt-class fiber laser modules in Stuttgart automotive clusters, while spot purchasing persists for consumable pump diodes with degradation-driven replacement cycles. Three-tier pricing structure across premium, standard, and economy levels separates FDA 21 CFR Part 820-validated surgical modules from industrial cutting systems and unmarked economy-grade alternatives. Cost compression in standard-tier industrial modules is intensifying because silicon carbide pump diode advances are extending efficiency boundaries and eroding historical performance premiums. Tier suppliers in German automotive welding cells exhibit highest price sensitivity due to outcome-based uptime agreements, while medical device OEMs absorbing captive recalibration contracts show lowest sensitivity to hardware unit pricing.
Supply Chain Analysis
Tariff exposure between United States and China dominates risk planning for electronics manufacturers sourcing precision marking modules through Yangtze River Delta distribution channels. Ytterbium-doped fiber preform production concentrates in Germany, Japan, and the United States, while silicon carbide pump diodes and rare-earth refining capacity cluster in China and the United States. Module assembly draws from specialty glass preforms, wide-bandgap semiconductor pumps, and precision optical components with single-source vulnerability in ytterbium fiber qualification protocols. Distribution runs through integrated beam source-to-system architects in European industrial clusters and specialized component distributors serving medical technology OEMs in Boston and Minneapolis.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Aftermarket service revenue for fiber replacement and beam recalibration is expanding faster than hardware procurement across German automotive welding cells, repositioning lifetime contract attach rates as the central value capture mechanism. This service-layer acceleration favors suppliers restructuring from capital sales to outcome-based uptime agreements.
For Market Incumbents: Build captive fiber production moats through backward integration into ytterbium-doped preform supply, mirroring IPG Photonics Corporation's architecture. Add capacity in wide-bandgap pump diode fabrication to capture efficiency gains above forty percent wall-plug performance. Defend against single-mode fiber platforms collapsing margin premiums in mid-precision micromachining by accelerating FDA 510(k) and EU MDR certification pipelines for clinical-grade modules. For New Entrants and Emerging Players: India's PLI scheme electronics manufacturing clusters in Noida and Chennai offer the most penetrable geographic entry point, with greenfield demand for precision marking and microsoldering modules outpacing established supplier presence. Target battery cell tab-to-busbar welding applications with distinct beam parameter requirements from saturated metal cutting segments. Pursue partnership-based go-to-market models with German automotive tier suppliers unbundling aftermarket service contracts from hardware procurement. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors acquisition of beam delivery technology assets and specialized regulatory affairs capabilities over pure hardware scale. Long-term viability across the projection horizon rests on service contract attach rates and multi-jurisdiction certification infrastructure rather than unit volume growth. Signal to watch: divergence between regional wavelength-specific exposure limits and semiconductor process node transitions redefining source specifications.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Fiber Preform Integration | Backward integration into ytterbium-doped fiber supply secures qualification protocols for FDA-validated surgical modules. |
| Wide-Bandgap Pump Diode Capacity Expansion | Silicon carbide fabrication investments extend wall-plug efficiency above forty percent in industrial cutting applications. |
| Multi-Jurisdiction Certification Infrastructure | Parallel FDA 510(k), EU MDR, and China NMPA documentation streams accelerate clinical-grade product development velocity. |
| Outcome-Based Service Contract Unbundling | Uptime agreements in German automotive welding cells separate hardware procurement from lifetime recalibration revenue. |
| Single-Mode Platform Development | Beam quality factors below 1.3 penetrate mid-precision micromachining previously requiring scientific-grade ultrafast systems. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through primary interviews with fiber laser module procurement directors at Stuttgart automotive OEMs, biomedical engineers at Boston medical technology clusters, aftermarket service heads at German tier suppliers, and optical resonator design specialists. Secondary validation incorporated FDA 510(k) device classification filings, EU MDR technical documentation databases, SEC 10-K disclosures from captive fiber producers, and IEC 60825 laser safety standard revision records. Bottom-up module shipment estimates triangulated against top-down industrial laser system installation data across the analysis window.
Calibration against historical replacement cycle data and pump diode degradation curves shaped the analytical framework across technology type, power rating tier, application vertical, and end-user procurement sophistication dimensions. CAGRs were derived from segment-level growth rate differentials weighted by installed base velocity and regulatory-driven replacement cycle compression. Forecast inputs incorporated silicon carbide pump efficiency trajectories, rare-earth fiber preform supply elasticity, and multi-jurisdiction certification timeline divergences.
Practitioners should monitor rare-earth fiber preform supply disruptions, EU MDR post-market surveillance infrastructure requirements, and OSHA laser safety standard enclosure specification updates for early signals of forecast revision. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Optical Cross Connect Market
Optical Components
Waveguide Phase Shifter Market
Optical Components
Portable Lenses Market
Optical Components
Global Optical Fiber Preform Market
Optical Components
Global Electrochromic Glass and Devices Market
Optical Components
Fluorophore Market
Optical Components
Low-E Glass Magnetron Sputtering Coating Line Market
Optical Components
Bio-Optics Market
Optical Components
Digital Optical Transmitter Market
Optical Components
Global Optical Measurement Market
Optical Components
Spectroradiometers Market
Optical Components
CW Fiber Amplifier Market
Optical Components
Electronic Digital Magnifiers Market
Optical Components
Infrared Filter Market
Optical Components
Optical Isolator Market
Optical Components
Silicon Photonics Market