
 LGP (Light Guide Plate) for TV Market | 2026-2036
LGP (Light Guide Plate) for TV Market Size, Share, and Industry Trends Forecast 2026-2036
LGP (Light Guide Plate) for TV Market Insights
ISO 9001 quality management certification is rotating as a baseline gate for Tier-1 TV panel supply chains, filtering out sub-scale molders. Mitsubishi Chemical Corporation leverages captive methacrylate resin production to sustain cost discipline across optical-grade PMMA output. LG Innotek anchors its position through backward integration into LED package and LGP module assembly. Sumitomo Chemical differentiates via high-purity polymer synthesis tailored to quantum-dot color-conversion layers.
A light guide plate is an optically engineered polymer sheet—typically PMMA or MS resin, 1.0–3.0 mm thick—fabricated through injection molding or hot-embossing with micro-patterned V-cut or dot-matrix surfaces to distribute LED backlight uniformly across LCD and mini-LED television displays. Edge-lit LGP configurations retain volume dominance in mid-size TV segments where thickness reduction commands priority, while direct-lit LGP variants capture premium share in large-format screens requiring zoned dimming precision. Ultra-thin thickness grades are gaining fastest traction as OEMs race to sub-5 millimeter panel assemblies.
REACH and RoHS frameworks in Europe restrict halogenated flame retardants and heavy-metal stabilizers in optical polymers, forcing reformulation of LGP substrate chemistry. EPA energy-efficiency guidelines and California Title 20 appliance standards in the United States tighten backlight power budgets, indirectly elevating LGP optical-extraction efficiency requirements. Stakeholders must monitor how Korea's KC certification and China's GB standards for display energy consumption reshape qualification protocols for cross-border component supply.
Market Dynamics
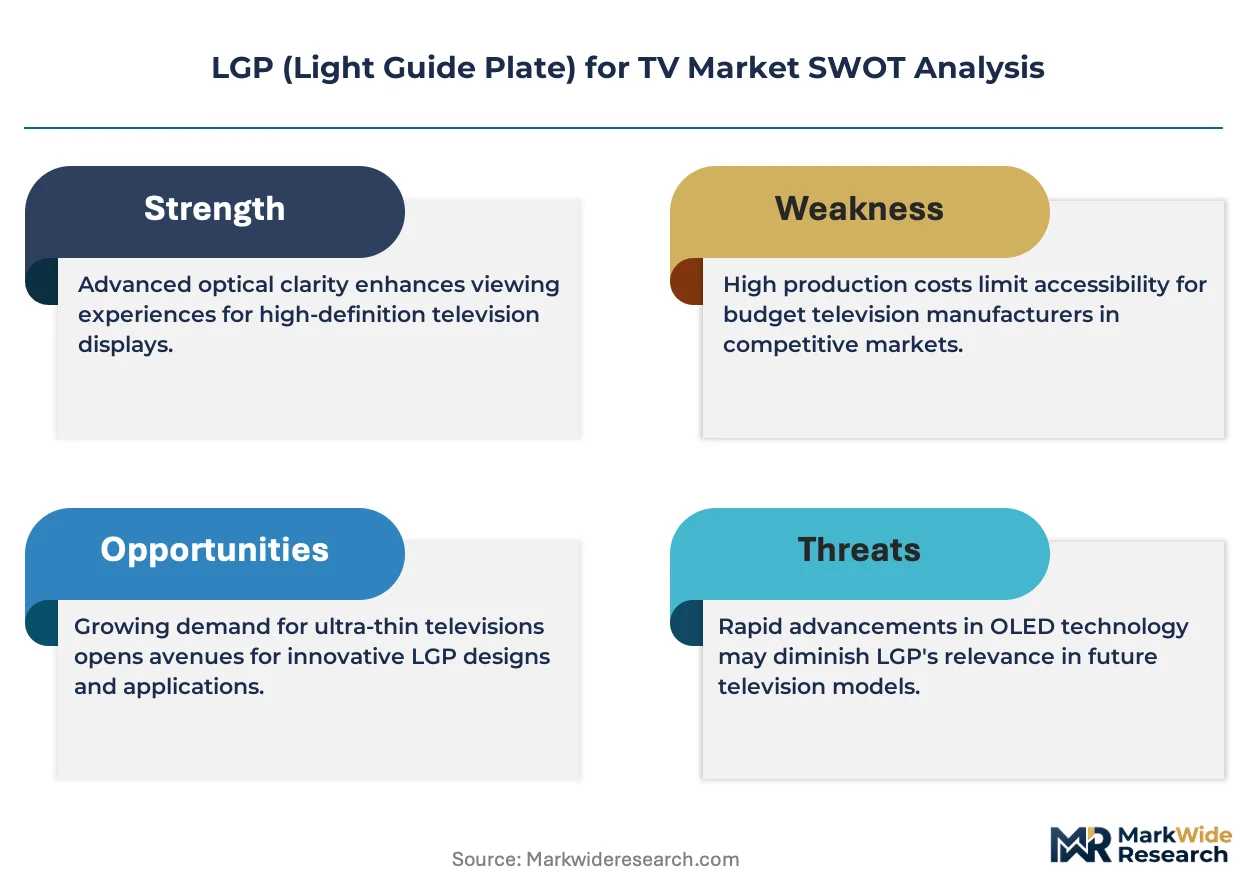
Ultra-thin television panel specifications are compressing LGP thickness targets below 1.5 millimeters, forcing molders to retool for micro-V-cut precision at scale while maintaining optical extraction efficiency. This dimensional squeeze is redrawing the competitive map around hot-embossing capability and captive resin synthesis.
Growth Catalysts
- REACH compliance deadlines:European ECHA enforcement of halogen-free optical polymer mandates is accelerating qualified supplier consolidation among molders with reformulated PMMA substrates.
- Mini-LED backlight diffusion:Television OEMs in South Korea and Japan are integrating zoned-dimming LGP architectures that demand higher-pattern-density microstructures.
- China's dual carbon goals:Provincial energy-efficiency targets for display manufacturing are pulling demand toward low-power edge-lit configurations with optimized light-extraction films.
Market Restraints
- Methacrylate monomer volatility:Crude-linked MMA feedstock costs swing optical-grade PMMA margins unpredictably for non-integrated molders.
- Precision-molding concentration:Three East Asian economies control over 80 percent of hot-embossing capacity for sub-2.0 millimeter grades, creating single-source exposure.
- QD-OLED substitution:Self-emissive quantum-dot panels eliminate backlight units entirely in premium television segments above 75 inches.
Strategic Opportunities
- India PLI scheme:Display manufacturing incentives under the country's production-linked initiative are attracting LGP module assembly investments for domestic television brands.
- Automotive display convergence:Curved LGP architectures developed for dashboard screens represent a transferable technology stack for Tier-1 automotive suppliers.
- EU Ecodesign expansion:Upcoming European Commission regulations on repairability and energy labeling will favor modular, replaceable LGP designs in commercial signage.
Industry Challenges
- Micro-pattern metrology talent:Scarce process engineers capable of calibrating sub-50-micron V-cut uniformity across 85-inch formats are commanding premium compensation in Suzhou and Gumi industrial clusters.
- ISO 9001-to-14001 dual certification timelines:Television panel OEMs now require 18-month environmental management qualification cycles that freeze new molder onboarding.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | LGP (Light Guide Plate) for TV Market |
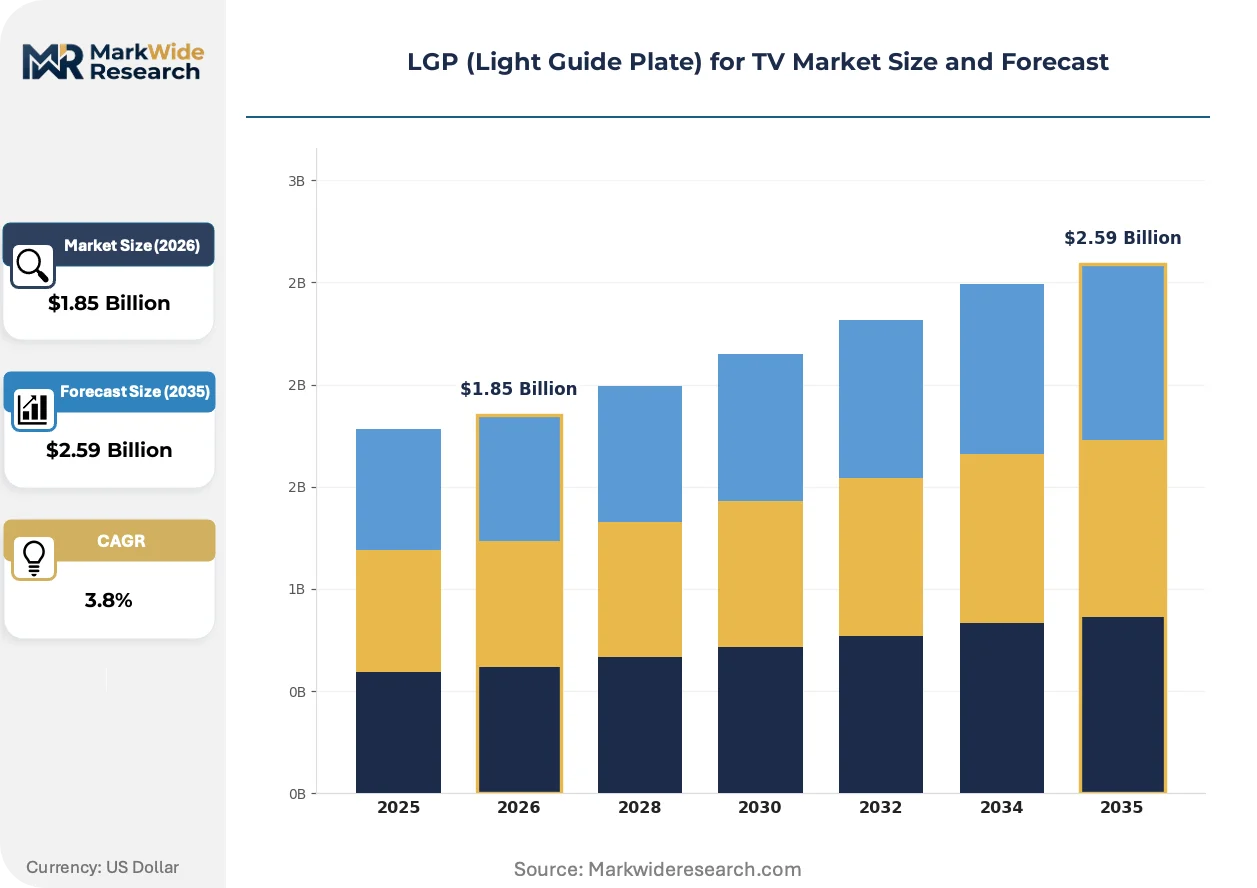
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $2.59 Billion |
| CAGR (2026 – 2036) | 3.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Edge-lit LGP, Direct-lit LGP, Flexible LGP, Standard LGP Technology: LED, LCD, OLED, Quantum Dot Thickness: Thin, Medium, Thick, Ultra-thin Surface Treatment: Anti-glare, Textured, Glossy, Matte |
| Companies Covered | Mitsubishi Chemical Corporation, Sumitomo Chemical, LG Innotek, Chi Mei, Asahi Kasei, Nitto Denko Corporation, 3M, Kuraray, Global Lighting Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
LGP (Light Guide Plate) for TV Market Trends and Innovations
Manufacturing process convergence is compressing the traditional separation between resin synthesis, sheet extrusion, and micro-patterning into continuous production lines. This integration is rewriting capital deployment strategies and supplier qualification protocols across the value chain.
MS resin (methyl styrene copolymer) is supplanting conventional PMMA in mid-range television LGP applications where moisture resistance and dimensional stability outweigh pure optical clarity. Chinese panel assemblers are specifying MS grades for 55-65 inch models destined for humid climates. This substitution is compressing the addressable premium for optical-grade PMMA and forcing Mitsubishi Chemical and Sumitomo Chemical to defend position through captive monomer supply.
REACH Annex XVII restrictions on persistent organic pollutants are compelling reformulation of optical polymer stabilizer packages across European-bound LGP shipments. ECHA substance-of-very-high-concern listings for certain phosphite antioxidants have triggered 12-month material requalification cycles at major molders. Television brands exporting to Germany and France are now demanding full material disclosure documentation that exceeds RoHS baseline requirements.
Television OEM sourcing committees are consolidating qualified LGP suppliers from 6-8 per panel size to 2-3 strategic partners with full backward integration into LED package and driver IC procurement. This concentration is displacing spot-market volume purchasing and locking molders into multi-year cost-down roadmaps. The shift is most visible in South Korea, where Samsung Display and LG Display have implemented vendor reduction programs since 2022.
LGP (Light Guide Plate) for TV Market Segmentation
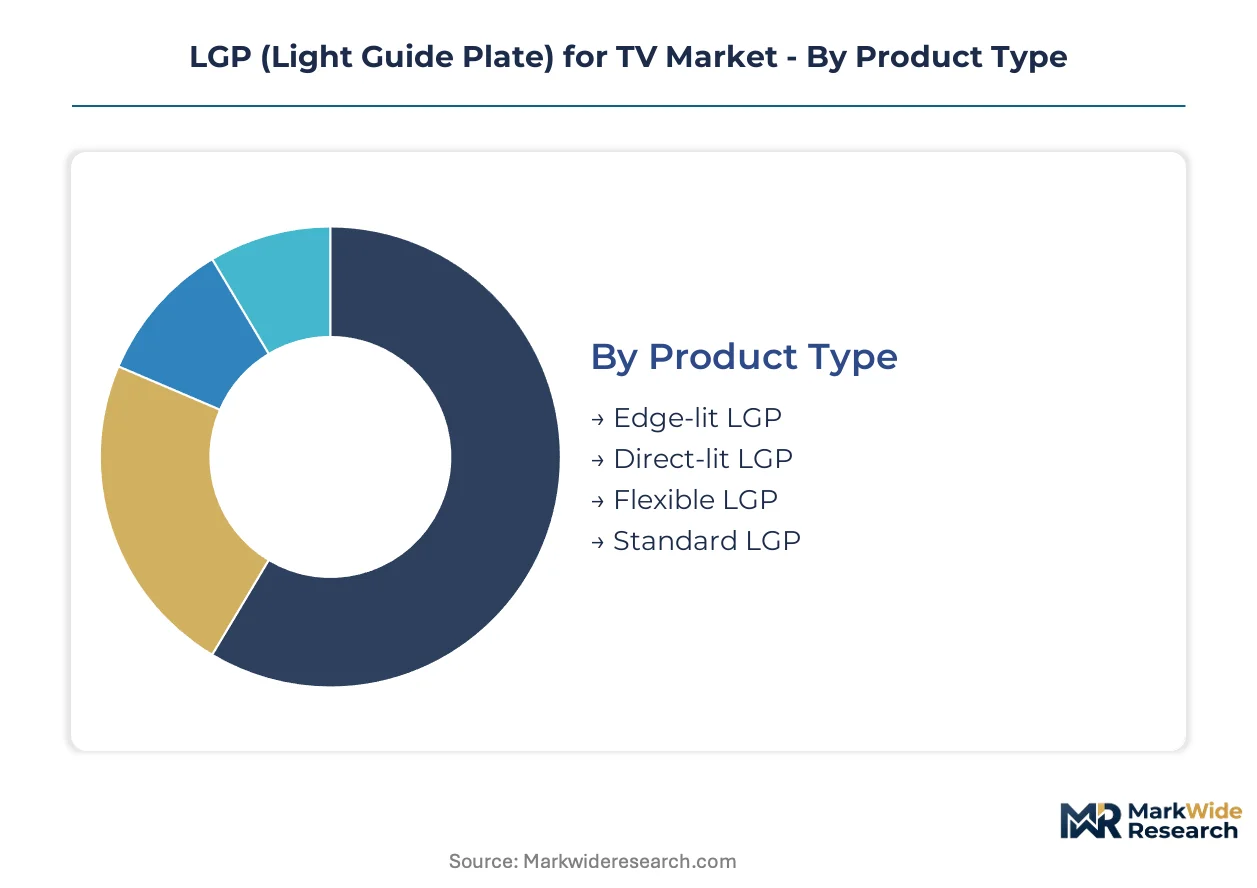
Segmentation in the LGP for TV market tracks how display architecture choices translate into polymer specifications. Each dimension—optical configuration, display technology, thickness grade, and surface engineering—carries distinct qualification protocols and margin structures that reshape supplier competitiveness.
Product Type:
QD-OLED self-emissive panels are eliminating backlight units entirely in premium television segments, pressuring LGP product types most exposed to large-format substitution.
- Edge-lit LGP:PMMA or MS resin sheets with micro-patterned V-cut surfaces distribute LED input from one or two edges across mid-size television panels. South Korean OEMs specify these configurations for sub-5 millimeter assemblies where thickness reduction commands priority over zoned dimming precision.
- Direct-lit LGP:Thicker optical-grade substrates with higher-density dot-matrix patterns enable local dimming zones for HDR performance in 75-inch and larger televisions. Japanese panel assemblers integrate these architectures where contrast ratio differentiation justifies backlight complexity.
- Flexible LGP:Curved polymer formulations for convex or concave television designs, typically 2.0–3.0 mm thickness grades with stress-relief pattern geometries.
- Standard LGP:Conventional flat-sheet configurations for entry-level television segments where cost minimization outweighs optical optimization.
Edge-lit LGP anchors the volume base while direct-lit LGP gains share at the steepest rate.
Technology:
Cost tier separation between display backplane technologies is fragmenting LGP demand into distinct specification bands.
- LED:Conventional edge-lit and direct-lit configurations using blue-LED plus phosphor conversion dominate mass-market television production. Chinese panel assemblers specify these for domestic brands under provincial energy-efficiency targets.
- LCD:Cold-cathode and LED-backlit LCD panels retain volume in commercial signage and hospitality television segments where replacement cycles stretch beyond consumer norms.
- OLED:Self-emissive organic panels eliminate LGP requirements entirely; this technology functions as a demand destructor rather than a segment for LGP suppliers.
- Quantum Dot:QD-enhanced LED backlights with color-conversion films demand higher-purity PMMA substrates to minimize optical interference with nanocrystal layers.
LED-backlit configurations command the installed base while quantum dot architectures expand most quickly among premium tier specifications.
Thickness:
Television OEM sourcing committees are consolidating suppliers around demonstrated capability at specific thickness grades, creating qualification moats.
- Ultra-thin:Sub-1.5 millimeter grades requiring hot-embossing precision at scale; Suzhou and Gumi industrial clusters concentrate process engineers capable of calibrating sub-50-micron V-cut uniformity.
- Thin:1.5–2.0 millimeter specifications balancing optical extraction efficiency with mechanical handling robustness for high-volume television assembly.
- Medium:2.0–2.5 millimeter grades for commercial displays and outdoor television applications where thermal cycling resistance outweighs slimness priorities.
- Thick:Above 2.5 millimeter legacy specifications for industrial and replacement markets with minimal new design activity.
Thin grades anchor current volume while ultra-thin specifications climb the fastest as OEMs race to sub-5 millimeter panel assemblies.
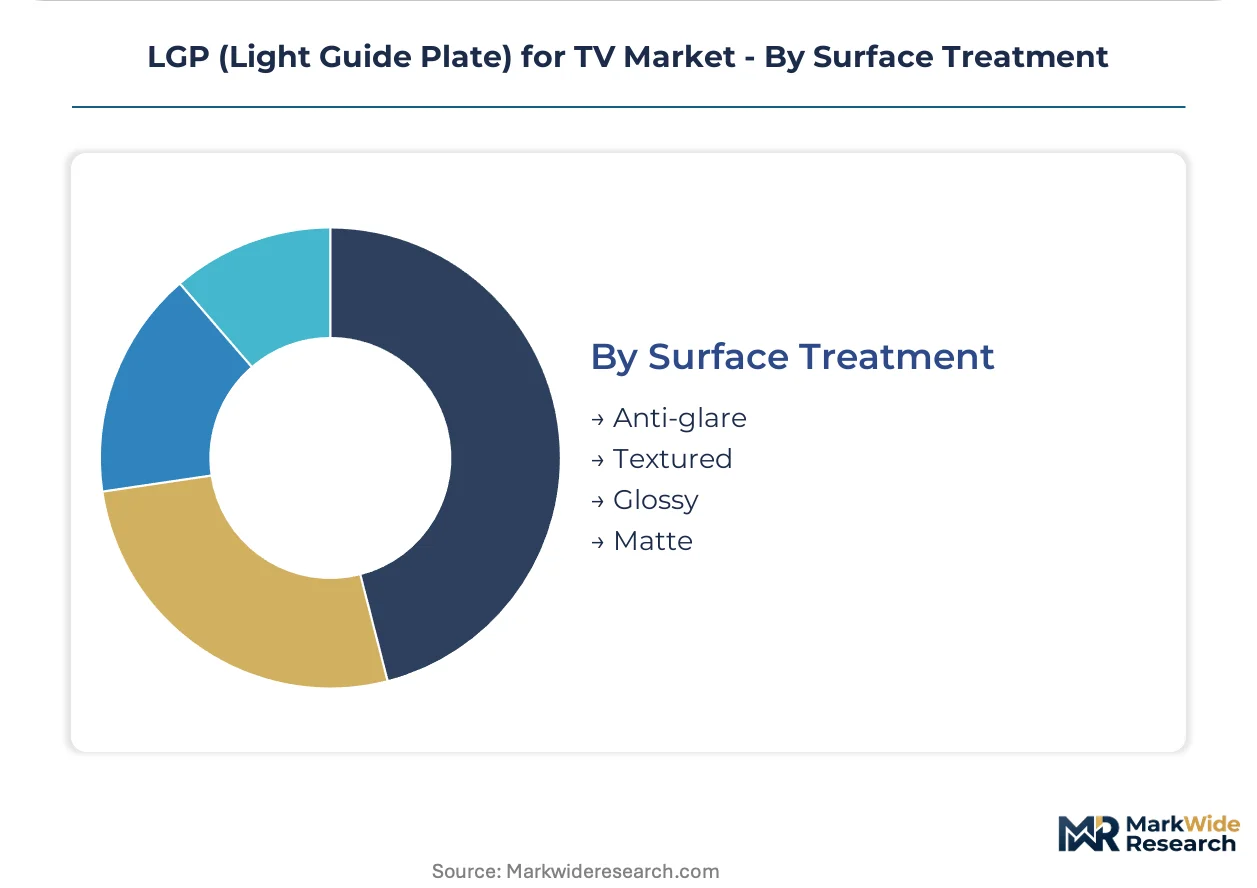
Surface Treatment:
REACH Annex XVII restrictions on optical polymer additives are reformulating surface treatment chemistry for European-bound shipments.
- Anti-glare:Micro-roughened surfaces scatter ambient reflection for living-room television installations; ECHA substance-of-very-high-concern listings for certain phosphite antioxidants have triggered 12-month requalification cycles.
- Matte:Controlled diffuse scattering for professional monitor and commercial signage applications where viewing angle consistency matters more than peak brightness.
- Textured:Engineered micro-patterns for light-extraction optimization in edge-lit configurations.
- Glossy:High-clarity finishes for premium television segments where black-level perception and color saturation drive consumer preference.
Matte treatments anchor commercial volume while anti-glare specifications gain share fastest among consumer television qualifications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Provincial energy-efficiency targets and production-linked incentives are redrawing manufacturing footprints across major television assembly hubs. Display panel OEMs are consolidating supply chains around jurisdictions offering dual carbon compliance pathways and precision-molding talent pools.
China
Provincial dual carbon goals in Jiangsu and Guangdong are accelerating demand for low-power edge-lit configurations. GB standards for display energy consumption administered by SAMR are tightening qualification protocols for cross-border component supply. Suzhou industrial clusters concentrate hot-embossing capacity for sub-1.5 millimeter grades, with process engineers commanding premium compensation for sub-50-micron V-cut calibration.
South Korea
Samsung Display and LG Display vendor reduction programs since 2022 are consolidating qualified LGP suppliers from 6-8 per panel size to 2-3 strategic partners. KC certification requirements are reshaping qualification protocols for domestic television brands. Gumi industrial clusters anchor precision-molding capacity for zoned-dimming LGP architectures in mini-LED backlight diffusion.
Japan
METI energy-efficiency directives are elevating optical-extraction efficiency requirements for backlight power budgets. JIS standards for display components are filtering sub-scale molders from Tier-1 supply chains. Chubu-Nagoya industrial corridors concentrate high-purity polymer synthesis capabilities tailored to quantum-dot color-conversion layers.
United States
EPA energy-efficiency guidelines and California Title 20 appliance standards are tightening backlight power budgets for television imports. Domestic assembly operations remain limited, with procurement shifting toward East Asian integrated suppliers. Mexico City Metro and Nuevo León maquiladora zones are absorbing module assembly investments for North American market access.
India
Display manufacturing incentives under the PLI scheme are attracting LGP module assembly investments for domestic television brands. BIS certification timelines are extending supplier qualification cycles to 18 months for environmental management standards. Maharashtra and Gujarat industrial corridors are concentrating downstream panel assembly capacity for regional consumer brands.
LGP (Light Guide Plate) for TV Market Competitive Landscape
Player mix skews toward integrated chemical conglomerates with captive resin synthesis and specialized optical component fabricators with precision-patterning capabilities. The competitive map divides between backward-integrated PMMA producers defending margin through monomer supply control and independent molders competing on hot-embossing yield rates. Strategic archetypes include captive resin synthesizers, precision-molding specialists, and module-integrators with LED package procurement leverage. Dominant competitive moves involve multi-year cost-down roadmaps locking strategic partners and geographic expansion into PLI-subsidized manufacturing zones.
Among East Asian chemical conglomerates, Mitsubishi Chemical Corporation, Sumitomo Chemical, and LG Innotek occupy positions that exemplify distinct strategic archetypes. Mitsubishi Chemical represents the captive methacrylate resin producer defending cost discipline through upstream chemical integration. Sumitomo Chemical sits within the high-purity polymer synthesis tier targeting quantum-dot display applications. LG Innotek anchors the module-integrator archetype with backward integration into LED package procurement. These three entities collectively illustrate how qualification moats form around demonstrated capability at specific thickness grades and pattern densities.
| Leading Market Players |
|---|
| Mitsubishi Chemical Corporation |
| Sumitomo Chemical |
| LG Innotek |
| Chi Mei |
| Asahi Kasei |
| Nitto Denko Corporation |
| 3M |
| Kuraray |
| Global Lighting Technologies |
| Others |
Pricing and Supply Chain Analysis
Eighteen-month qualification cycles for ISO 14001 environmental management certification concentrate pricing power among incumbent molders with established TV panel OEM relationships, while compressing spot-market opportunities for non-integrated suppliers. This lead-time rigidity in supplier onboarding reinforces cost-plus contract structures indexed to methacrylate monomer feedstock costs, binding LGP pricing to crude-linked MMA volatility.
Pricing Analysis
Cost-plus contracts with MMA feedstock indexation dominate long-term supply agreements between optical-grade PMMA producers and television panel OEMs. Three-tier pricing structure across premium, standard, and economy levels separates ultra-thin hot-embossed grades from conventional injection-molded specifications. Pricing pressure stems from MS resin substitution in mid-range 55-65 inch television segments where moisture resistance outweighs optical clarity demands. Chinese domestic brands exhibit highest price sensitivity, while South Korean OEMs prioritize optical extraction efficiency over unit cost.
Supply Chain Analysis
Inbound logistics costs through Shanghai and Busan port corridors fluctuate with container availability for optical-grade polymer resin shipments from Japan and South Korea. China, South Korea, and Japan concentrate over 80 percent of hot-embossing capacity for sub-2.0 millimeter grades. Raw material dependencies center on methyl methacrylate monomer, phosphite antioxidant stabilizers, and LED package components. Single-source exposure in precision-molding talent clusters creates vulnerability. Distribution runs through integrated module assemblers with captive LED procurement leverage.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Television display architecture is approaching a platform-economics inflection as mini-LED zoned-dimming ecosystems and quantum-dot color-conversion layers demand interoperable LGP specifications. This interoperability shift rewards suppliers with demonstrated pattern-density calibration across multiple backlight technologies.
For Market Incumbents: Consolidate supplier qualification moats by deepening backward integration into methacrylate monomer production and expanding hot-embossing capacity in Suzhou and Gumi clusters. QD-OLED substitution in premium segments above 75 inches threatens direct-lit LGP volumes, requiring incumbents to defend position through captive resin synthesis and multi-year cost-down roadmaps with strategic panel OEM partners.
For New Entrants and Emerging Players: Anchor in India's PLI-subsidized display manufacturing corridors where 18-month BIS qualification timelines have frozen incumbent onboarding and created white-space for module assembly specialists. The most penetrable entry point lies in curved LGP architectures for automotive dashboard displays, leveraging transferable hot-embossing expertise toward Tier-1 automotive supplier qualification. A joint-venture route with domestic Indian television brands offers fastest path to volume scale.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underutilized optical-grade polymer synthesis assets and stranded PMMA capacity outside East Asian demand clusters. Long-term viability hinges on five-to-ten year positioning toward quantum-dot display material integration rather than commodity LGP sheet production. The signal to watch is ECHA substance-of-very-high-concern listing velocity for phosphite antioxidants, which would trigger accelerated material requalification cycles favoring integrated suppliers with reformulation capabilities.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Methacrylate Monomer | Mitsubishi Chemical's captive MMA production sustains margin discipline against feedstock volatility. |
| Hot-Embossing Capacity Expansion | Sub-50-micron V-cut precision at scale separates qualified suppliers from commodity molders. |
| MS Resin Formulation Investment | Moisture-resistant grades capture 55-65 inch television demand in humid climate markets. |
| Quantum-Dot Material Qualification | High-purity PMMA synthesis tailored to nanocrystal color-conversion layers opens premium tier access. |
| India PLI Corridor Manufacturing | Domestic module assembly investments align with Maharashtra and Gujarat panel assembly concentration. |
Research Methodology
The analysis maps edge-lit, direct-lit, flexible, and standard LGP product configurations, each validated through procurement directors at television panel OEMs, optical polymer R&D leads, hot-embossing process engineers, and LED package integration specialists. Primary fieldwork combined structured interviews with secondary validation against SEC 10-K filings from chemical conglomerates, customs and trade data for optical-grade polymer shipments, SAMR GB standard disclosure documents, and ECHA REACH Annex XVII regulatory updates. Bottom-up volume builds triangulated against top-down industry absorption estimates.
Consistency checks validated volume and value outputs against external benchmarks including regional television production databases and display panel shipment trackers. The analytical framework models product type, display technology, thickness grade, and surface treatment segmentation across the projection horizon. CAGRs derive from polynomial trend fitting of historical volume trajectories adjusted for technology substitution elasticities. Forecast inputs include mini-LED backlight diffusion rates and QD-OLED penetration in premium size classes.
Decision-makers should treat outputs as directional under assumptions of sustained REACH enforcement continuity and stable East Asian precision-molding capacity concentration; material deviation in either dimension would warrant model refresh. Specific risk factors include ECHA substance-of-very-high-concern listing acceleration and abrupt QD-OLED cost reduction in 75-inch segments. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Optical Frequency Domain Reflectometer Market
Optical Components
Low-E Glass Magnetron Sputtering Coating Line Market
Optical Components
Ring Laser Gyroscope Market
Optical Components
Europe Eye Tracking Solutions Market
Optical Components
Fluorophore Market
Optical Components
Optical Isolator Market
Optical Components
Digital Optical Transmitter Market
Optical Components
100G Optical Transceivers Market
Optical Components
High Speed Fiber Optic Sensor Market
Optical Components
High Power Double-Clad Fiber Bragg Grating Market
Optical Components
Optical Position Sensors Market
Optical Components
Flexible Glass for Flexible Electronics Market
Optical Components
Electro-Optic Modulators Market
Optical Components
Nonlinear Optical Crystals Market
Optical Components
China Lithium Niobate Modulator Market
Optical Components
Europe Tunable Laser Market