
 Electro-Optic Modulators Market | 2026-2036
Electro-Optic Modulators Market Size, Share, and Industry Trends Forecast 2026-2036
Electro-Optic Modulators Market Analysis
The EU Green Deal is repositioning electro-optic modulator procurement criteria across European telecom infrastructure. Lumentum Holdings Inc leverages vertical integration in indium phosphide fabrication to sustain cost advantages in high-speed modulators. Jenoptik AG anchors its competitive stance through specialized lithium niobate waveguide manufacturing for defense and research end users. Coherent Inc dominates the telecom provider channel with integrated optics platforms that reduce power consumption in data center interconnects.
An electro-optic modulator converts electrical signals into optical intensity or phase variations using materials whose refractive index changes under applied electric fields, typically operating at wavelengths between 1310 nm and 1550 nm for fiber-optic compatibility. Mach-Zehnder interferometer architectures lead volume shipments for telecommunications, while electro-absorption variants capture margin in compact, high-speed data transmission modules. Bulk optics technology retains niche demand in research institutions requiring free-space beam manipulation, whereas integrated optics platforms attract the fastest-growing share from hyperscale data center operators.
FCC broadband infrastructure mandates in the United States, combined with EU F-Gas Regulation restrictions on refrigerants used in laser cooling systems, shape component qualification requirements and supply chain compliance burdens. Japan's METI carbon neutrality roadmap for information and communications technology infrastructure adds a third regulatory layer affecting modulator efficiency specifications. Stakeholders must monitor evolving interoperability standards between coherent DSP engines and modulator interfaces to anticipate procurement specification shifts.
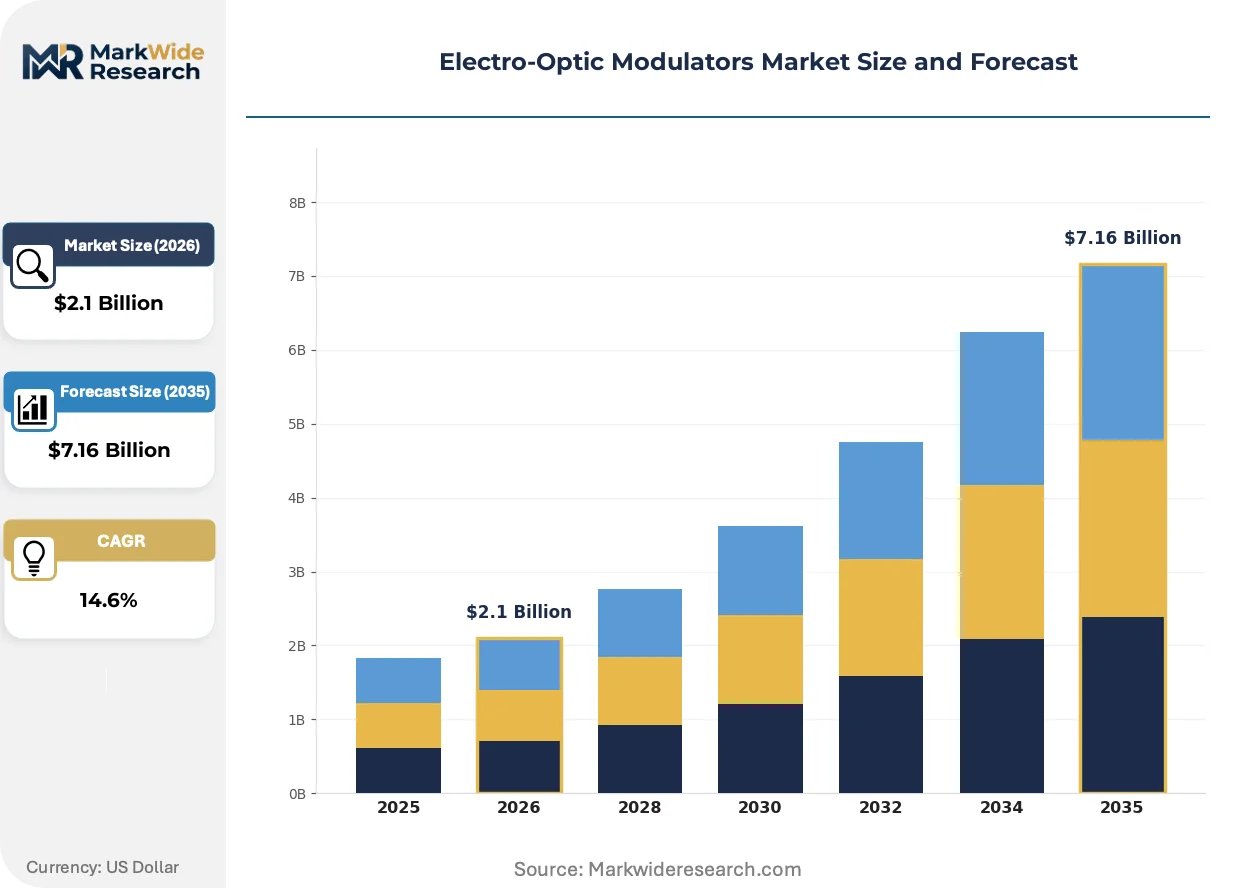
Market Dynamics
The coherent optical transmission buildout by telecom providers is compressing modulator qualification cycles while amplifying pressure on power efficiency metrics and thermal management specifications.
Growth Catalysts
- Telecom infrastructure mandates:FCC broadband deployment requirements in the United States are accelerating coherent optical system procurement by tier-one carriers.
- EU Green Deal:Energy-efficiency procurement criteria are repositioning supplier priorities toward low-power photonic components across European infrastructure buildouts.
- Hyperscale data center expansion:Cloud operators in the United States, Germany, and Japan are driving volume demand for integrated optics platforms.
Market Restraints
- Indium phosphide supply concentration:Foundry capacity for compound semiconductor substrates remains concentrated among a limited set of merchant suppliers.
- F-Gas Regulation compliance costs:EU restrictions on refrigerants used in laser cooling systems add qualification burden and extend component validation timelines.
- Silicon photonics substitution threat:CMOS-compatible modulator architectures are capturing share in cost-sensitive, moderate-speed applications.
Strategic Opportunities
- Defense and research verticals:Specialized lithium niobate waveguide manufacturing for free-space applications retains premium pricing power.
- METI carbon neutrality roadmap:Japan's ICT infrastructure efficiency targets create specification pull for low-thermal-dissipation modulator designs.
- Coherent DSP-modulator convergence:Tight integration between digital signal processors and electro-optic interfaces is opening new architectural possibilities.
Industry Challenges
- Compound semiconductor fabrication talent scarcity:Indium phosphide process engineering expertise pools remain shallow relative to demand acceleration.
- Interoperability certification complexity:Evolving interface standards between coherent engines and modulator subsystems extend validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Electro-Optic Modulators Market |
| Market Size in 2026 | $2.1 Billion |
| Market Size in 2035 | $7.16 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LiNbO3, Polymer, Lithium Tantalate, InP Application: Telecommunications, Data Transmission, Optical Signal Processing, Sensing End User: Telecom Providers, Research Institutions, Defense, Industrial Technology: Mach-Zehnder, Electro-Absorption, Integrated Optics, Bulk Optics |
| Companies Covered | Gooch & Housego PLC, Conoptics Inc, Lumentum Holdings Inc, Jenoptik AG, iXBlue Inc, Thorlabs Inc, Coherent Inc, AA Opto-Electronic, Fujitsu Optical Components Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Electro-Optic Modulators Market Emerging Trajectories
Photonic integration architectures are displacing discrete component assemblies across high-speed transmission applications, compressing form factors while amplifying thermal management complexity.
Thin-film lithium niobate modulators are expanding into telecommunications infrastructure. These devices deliver superior electro-optic coefficients compared to legacy bulk crystal architectures. Tier-one carriers in Germany and Japan are piloting deployments for 800G coherent transmission. The technology is expanding into volume applications previously dominated by indium phosphide alternatives.
The EU F-Gas Regulation is reshaping thermal management requirements for high-power optical components. Restrictions on hydrofluorocarbon refrigerants are forcing redesign of laser cooling subsystems. Telecom equipment manufacturers are responding by specifying thermoelectric cooling alternatives and revising thermal budgets for outdoor cabinet deployments.
Hyperscale operators are consolidating procurement around vertically integrated photonics platforms. Cloud providers in the United States are bypassing traditional component distributors to source directly from integrated device manufacturers. This channel compression is most pronounced in data center interconnect applications where standardization enables specification simplification.
Electro-Optic Modulators Market Segmentation
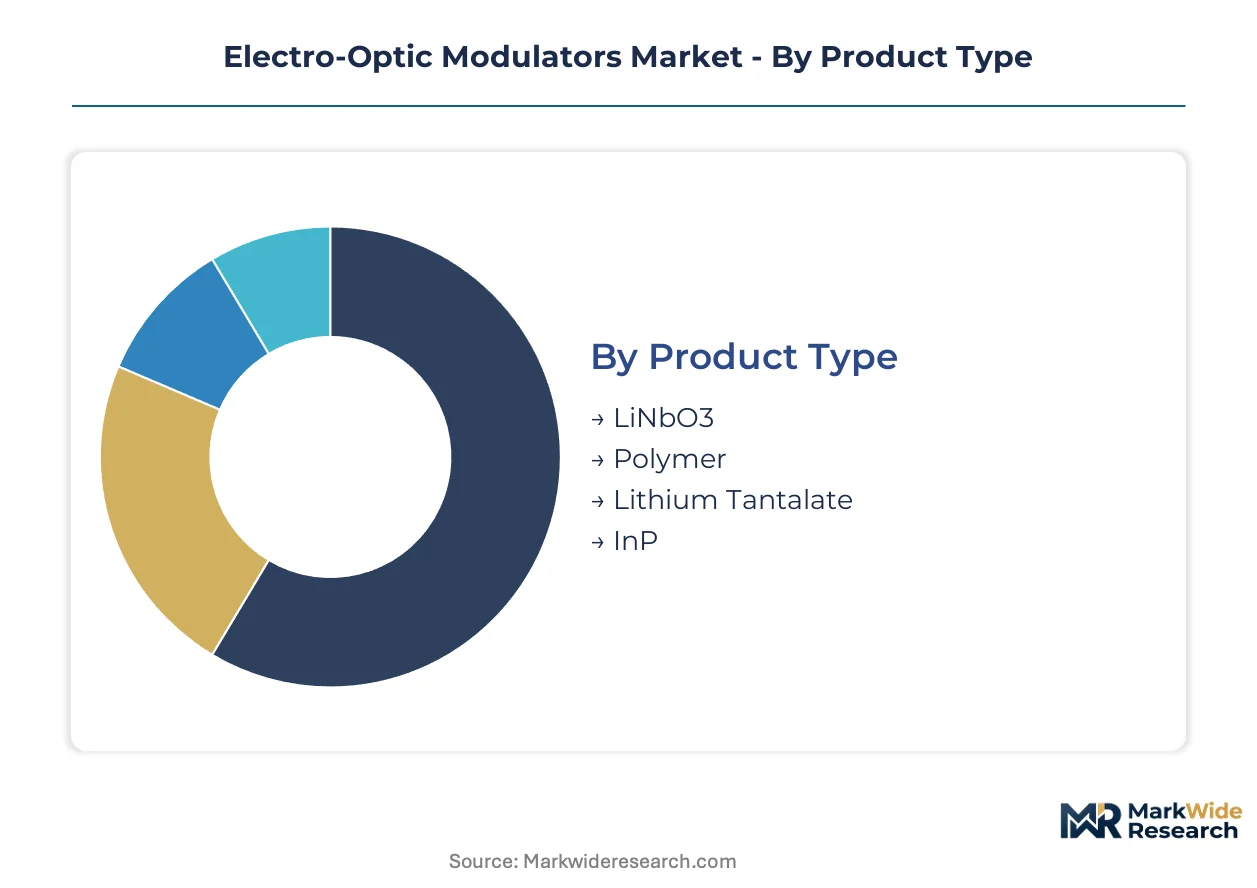
Electro-optic modulator procurement patterns diverge sharply across material platforms, with indium phosphide and thin-film lithium niobate architectures commanding premium positioning in coherent transmission systems while polymer alternatives capture cost-sensitive volume applications.
Product Type:
Material composition dictates electro-optic coefficient performance, thermal stability thresholds, and foundry compatibility—factors that cascade into qualification timelines and supply chain concentration.
- InP:Compound semiconductor substrates deliver the highest electro-optic coefficients for 800G coherent transmission. Telecom providers in the United States and Japan specify InP modulators for data center interconnects where power efficiency metrics determine procurement awards.
- LiNbO3:Thin-film lithium niobate waveguides achieve modulation bandwidths exceeding 100 GHz with lower drive voltages than bulk crystal predecessors. Germany's precision optics corridor is piloting deployments for next-generation coherent systems.
- Polymer:Organic electro-optic materials enable low-cost, flexible form factors for short-reach interconnects.
- Lithium Tantalate:Pyroelectric stability suits sensing applications requiring thermal drift resistance.
InP leads on scale; LiNbO3 leads on momentum.
Application:
End-use requirements fragment across bandwidth demands, environmental tolerances, and signal fidelity specifications—with telecommunications infrastructure consuming the dominant procurement volume.
- Telecommunications:Coherent optical transmission systems in North America and Europe absorb the majority of high-speed modulator shipments. FCC broadband mandates and EU Green Deal efficiency criteria compress qualification cycles while amplifying thermal management specifications.
- Data Transmission:Hyperscale data center operators in the United States and Japan are consolidating procurement around integrated optics platforms. Cloud providers bypass traditional distributors to source directly from device manufacturers.
- Optical Signal Processing:Research institutions deploy free-space modulator arrays for beam steering and pulse shaping.
- Sensing:Lidar and interferometric measurement systems specify compact, low-power modulator variants.
Telecommunications dominates procurement volume; data transmission is climbing the fastest.
End User:
Customer archetypes impose divergent validation protocols—defense programs demand traceability documentation while industrial buyers prioritize total cost of ownership.
- Telecom Providers:Tier-one carriers in Germany and Japan are compressing supplier qualification timelines to match coherent DSP engine roadmaps. Procurement specifications increasingly mandate integrated photonics platforms over discrete component assemblies.
- Defense:Specialized lithium niobate manufacturing for free-space applications retains premium pricing power. Defense contractors require extended environmental testing and supply chain security documentation.
- Research Institutions:Bulk optics modulators serve laboratories requiring customizable free-space beam paths.
- Industrial:Factory automation and process control systems specify ruggedized packaging for electromagnetic interference resistance.
Telecom providers anchor procurement volume; defense programs sustain margin premiums.
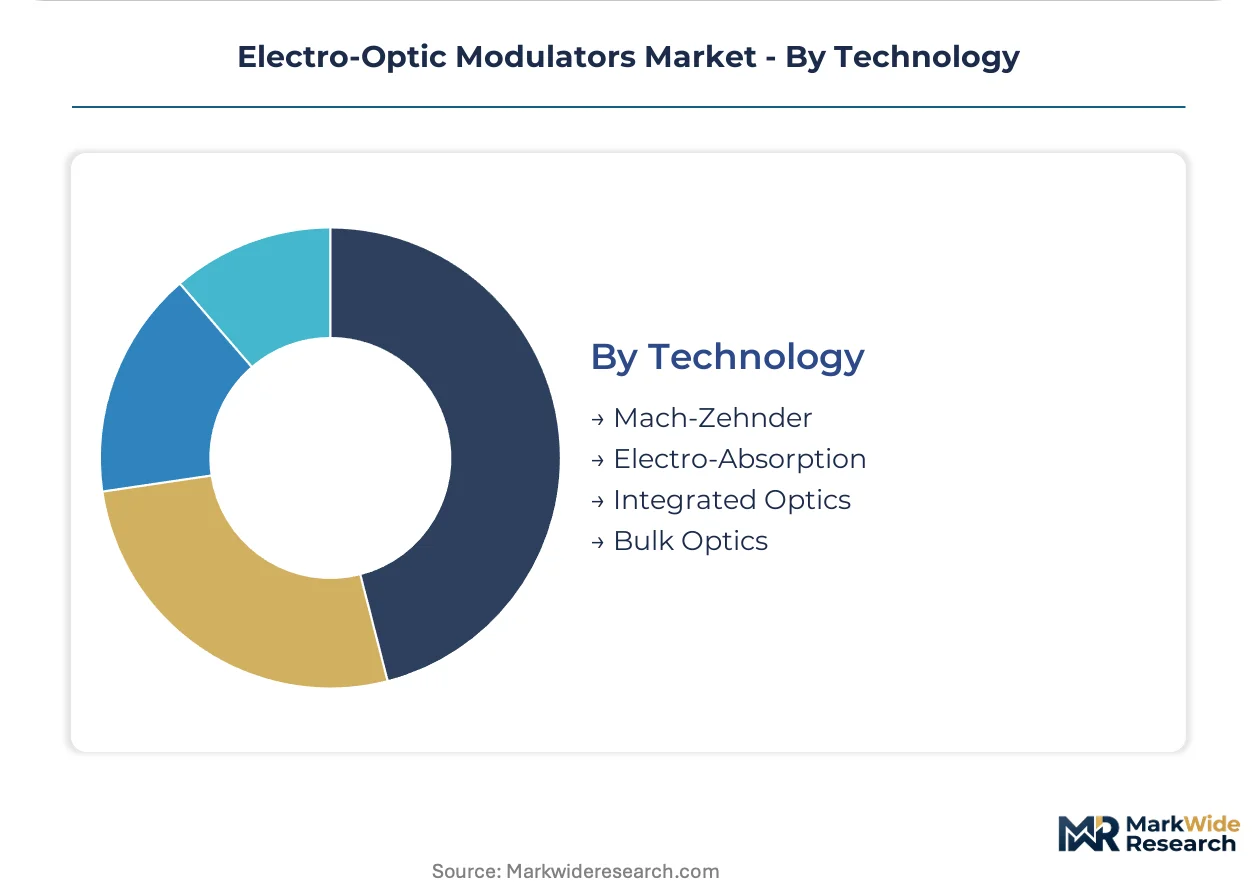
Technology:
Architectural choices between interferometric and absorption-based modulation determine power budgets, footprint constraints, and compatibility with CMOS fabrication flows.
- Mach-Zehnder:Interferometer architectures modulate optical phase through differential refractive index changes in parallel waveguide arms. Volume shipments concentrate in telecommunications infrastructure where extinction ratio specifications exceed 20 dB.
- Integrated Optics:Photonic integration platforms displace discrete assemblies across high-speed applications. Hyperscale operators in the United States are driving fastest adoption through direct sourcing relationships with foundries.
- Electro-Absorption:Quantum-confined Stark effect devices capture margin in compact, high-speed modules.
- Bulk Optics:Free-space crystal modulators retain niche demand in research settings requiring large aperture diameters.
Mach-Zehnder leads on installed base; integrated optics shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Electro-optic modulator manufacturing traces its industrial lineage to Bell Laboratories breakthroughs in the 1960s, establishing the United States as the foundational geography before German precision optics and Japanese compound semiconductor expertise developed parallel specializations.
United States
FCC broadband infrastructure mandates accelerate coherent optical system procurement by tier-one carriers. EPA regulations on electronic waste disposal shape component qualification requirements for telecom infrastructure deployments. The Greater Boston photonics corridor anchors precision manufacturing for defense and research end users requiring free-space modulator arrays.
Germany
EU Green Deal energy-efficiency criteria reposition supplier priorities toward low-power photonic components across European infrastructure buildouts. ECHA REACH compliance requirements extend validation timelines for compound semiconductor substrates. The Jena precision optics manufacturing cluster pilots thin-film lithium niobate deployments for next-generation coherent transmission systems.
Japan
METI carbon neutrality roadmap for ICT infrastructure creates specification pull for low-thermal-dissipation modulator designs. JIS standards for optical components establish interoperability benchmarks for coherent DSP engine interfaces. The Yokohama-Kawasaki industrial belt concentrates foundry capacity for indium phosphide fabrication serving data center interconnect demand.
China
MIIT dual carbon goals for telecommunications infrastructure amplify procurement emphasis on power efficiency metrics in optical transmission equipment. GB standards for fiber-optic components mandate domestic certification for network infrastructure deployments. The Wuhan Optics Valley anchors integrated photonics manufacturing clusters supplying hyperscale data center operators.
United Kingdom
UK Research and Innovation funding programs accelerate pilot deployments of thin-film lithium niobate modulators for quantum communication applications. HSE regulations on compound semiconductor manufacturing shape workplace safety protocols for indium phosphide foundries. The Cambridge photonics cluster specializes in Mach-Zehnder interferometer architectures for telecommunications infrastructure.
Electro-Optic Modulators Market Vendor Landscape
Capital-heavy producers compete with asset-light designers across divergent process technology requirements. Indium phosphide foundry ownership separates integrated device manufacturers from fabless modulator specialists dependent on merchant wafer supply. Three archetypes dominate: vertically integrated compound semiconductor fabricators, precision optics specialists leveraging lithium niobate waveguide expertise, and photonic integration platform providers. Capacity expansion in thin-film lithium niobate manufacturing and strategic partnerships between coherent DSP engine developers and modulator subsystem suppliers constitute the dominant competitive moves.
Among compound semiconductor fabricators, Lumentum Holdings Inc and Coherent Inc exemplify the vertically integrated archetype through captive indium phosphide production. Jenoptik AG occupies a position within the precision optics specialist tier, representing German manufacturing expertise in lithium niobate waveguide processing. These three anchors illustrate the geographic and technological bifurcation shaping procurement patterns across telecommunications and defense verticals.
| Leading Market Players |
|---|
| Gooch & Housego PLC |
| Conoptics Inc |
| Lumentum Holdings Inc |
| Jenoptik AG |
| iXBlue Inc |
| Thorlabs Inc |
| Coherent Inc |
| AA Opto-Electronic |
| Fujitsu Optical Components Limited |
| Others |
Supply Flow & Price Mechanics
FCC broadband infrastructure mandates are compressing procurement timelines for coherent optical systems, forcing suppliers to absorb qualification cost acceleration while hyperscale operators consolidate direct-sourcing relationships that compress distributor margins.
Pricing Analysis
Three-tier pricing structure across defense-grade, telecom-qualified, and research-laboratory levels dominates procurement negotiations, with defense-grade lithium niobate modulators commanding substantial premiums over volume telecom variants. Price differentiation rests on thermal stability certification and coherent DSP engine interoperability validation. Cost compression in telecom-qualified tiers is intensifying because silicon photonics substitutes capture moderate-speed applications. Research laboratories exhibit lowest price sensitivity; hyperscale data center operators drive hardest bargain consolidation.
Supply Chain Analysis
GB standards for fiber-optic components and domestic certification mandates in China's network infrastructure are reshaping sourcing patterns for compound semiconductor substrates. Indium phosphide foundry capacity concentrates in Japan, the United States, and Germany's precision optics corridor. Raw material dependencies draw from high-purity indium metal, lithium niobate crystal boules, and specialized photoresists. Single-source vulnerability in merchant indium phosphide wafer supply constitutes primary structural risk. Distribution runs through integrated device manufacturers serving hyperscale operators directly, bypassing traditional component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The electro-optic modulator market reads as a late-cycle quality story where 800G coherent transmission specifications and METI carbon neutrality efficiency targets are concentrating procurement awards toward premium thermal-dissipation designs.
For Market Incumbents: Lock in captive indium phosphide foundry capacity and accelerate thin-film lithium niobate pilot certifications before silicon photonics substitutes capture additional share in data center interconnects. Prioritize backward integration into compound semiconductor substrate supply and deepen direct-sourcing relationships with tier-one carriers in Germany and Japan. For New Entrants and Emerging Players: Enter via polymer electro-optic modulators for short-reach hyperscale interconnects where qualification barriers remain lowest and price sensitivity runs highest. Target research institution procurement for free-space bulk optics applications requiring customizable beam paths. Pursue foundry partnerships rather than capital-intensive fabrication buildouts. For Investors and Strategic Acquirers: Asymmetric upside sits with precision optics specialists possessing lithium niobate waveguide expertise and established defense program relationships. Long-term viability hinges on coherent DSP-modulator convergence roadmaps and thermal management specification tightening. Watch for inflection signals in 800G deployment acceleration by tier-one Japanese carriers.| Strategic Initiative | Industry Significance |
|---|---|
| Thin-Film Lithium Niobate Scale-Up | Jena precision optics cluster pilots next-generation coherent transmission deployments. |
| Coherent DSP-Modulator Integration | Tight coupling between signal processors and electro-optic interfaces opens architectural possibilities. |
| Defense Program Certification Investment | Extended environmental testing and supply chain security documentation sustain premium pricing. |
| Direct Hyperscale Sourcing Relationships | Cloud operators in the United States bypass distributors for integrated photonics platforms. |
| Thermoelectric Cooling Redesign | EU F-Gas Regulation restrictions force laser cooling subsystem specification revisions. |
Methodological Framework
Direct dialogue with telecom procurement officers, compound semiconductor foundry engineers, defense contractor supply chain managers, and coherent DSP platform architects grounded qualitative assessment, validated against SEC filings from Lumentum and Coherent, FCC broadband deployment databases, METI ICT efficiency roadmaps, and EU Green Deal implementation tracking. Bottom-up shipment estimates triangulated with top-down infrastructure spend analysis across the analysis window.
Segmentation-level outputs across material platform, application vertical, end-user archetype, and technology architecture were modeled throughout the forecast period, with CAGRs derived from regression against coherent optical transmission deployment trajectories and hyperscale data center capex cycles. Indium phosphide foundry utilization rates and thin-film lithium niobate manufacturing yield curves served as industry-specific forecast inputs.
Inputs from tier-one carrier procurement specifications and defense program documentation were available through the study window; gaps in emerging polymer modulator shipment data introduce uncertainty bands around short-reach interconnect projections. Forecasts reflect documented assumptions regarding coherent DSP engine interoperability standardization and F-Gas Regulation compliance timeline adherence. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Mobile Optical Pluggable Market
Optical Components
Raman Amplifier Market
Optical Components
Electronic Digital Magnifiers Market
Optical Components
Picosecond and Femtosecond Fiber Lasers Market
Optical Components
Asia Pacific Optical Sensors Market
Optical Components
Europe Optical Film Market
Optical Components
Microchannel Plates Market
Optical Components
LGP (Light Guide Plate) for TV Market
Optical Components
Optical Modulators Market
Optical Components
North America Photonic Sensors Market
Optical Components
Optical Sensor Market
Optical Components
Electro Optical System Market
Optical Components
Objective Lens Market
Optical Components
Optical Frequency Domain Reflectometer Market
Optical Components
VCSEL for Data Communication Market
Optical Components
Italy Lithium Niobate Modulator Market