
 Global Fiber Bragg Grating Amplifier Market | 2026-2036
Global Fiber Bragg Grating Amplifier Market Size, Share, and Industry Trends Forecast 2026-2036
Global Fiber Bragg Grating Amplifier Market Intelligence
The integration of advanced optical signal processing directly within amplifier modules is narrowing the physical footprint and power consumption of network equipment. TeraXion Inc. leverages its expertise in dispersion compensation components to offer highly integrated amplifier solutions. Luna Innovations Inc. sustains its market position through a focus on high-precision sensing and instrumentation applications. These specializations create distinct competitive lanes within the broader market.
A Fiber Bragg Grating amplifier is an optical device that selectively amplifies light signals at specific wavelengths determined by a periodic variation in the refractive index of a fiber core. Its primary purpose is to boost signal strength in long-haul telecommunications and high-precision sensing systems without introducing significant noise. The telecommunications application segment commands the largest share, driven by network upgrades. Among product types, Erbium-Doped Fiber Amplifiers integrated with FBG filters remain the dominant architecture for C-band and L-band amplification.
Component and system performance are governed by international standards from the IEC and specific telecommunication protocols. In the United States, the FCC sets requirements for network equipment, while in Europe, CE marking and RoHS directives dictate material composition and safety for electronic components. Stakeholders must decide whether to invest in developing amplifiers for emerging O-band and E-band applications or to optimize existing C-band and L-band product lines for higher efficiency.
Market Dynamics
The market's central tension lies in the strategic allocation of R&D investment. Stakeholders must balance optimizing mature C-band and L-band product lines for efficiency against pioneering development for emerging O-band and E-band telecommunication windows.
Growth Catalysts
- WDM System Density:The increasing channel count in Wavelength Division Multiplexing networks requires advanced FBG amplifiers to manage signal-to-noise ratio and prevent crosstalk, particularly in long-haul and metro networks.
- Chinese Infrastructure Investment:Massive public and private investment in China's optical network backbone, guided by MIIT directives for 5G and F5G (Fifth Generation Fixed Network), creates sustained demand for high-performance amplifiers.
- Industrial Sensing Expansion:Adoption in high-precision sensing for structural health monitoring in civil engineering and temperature or strain sensing in the energy sector provides a key diversification driver beyond telecommunications.
Market Restraints
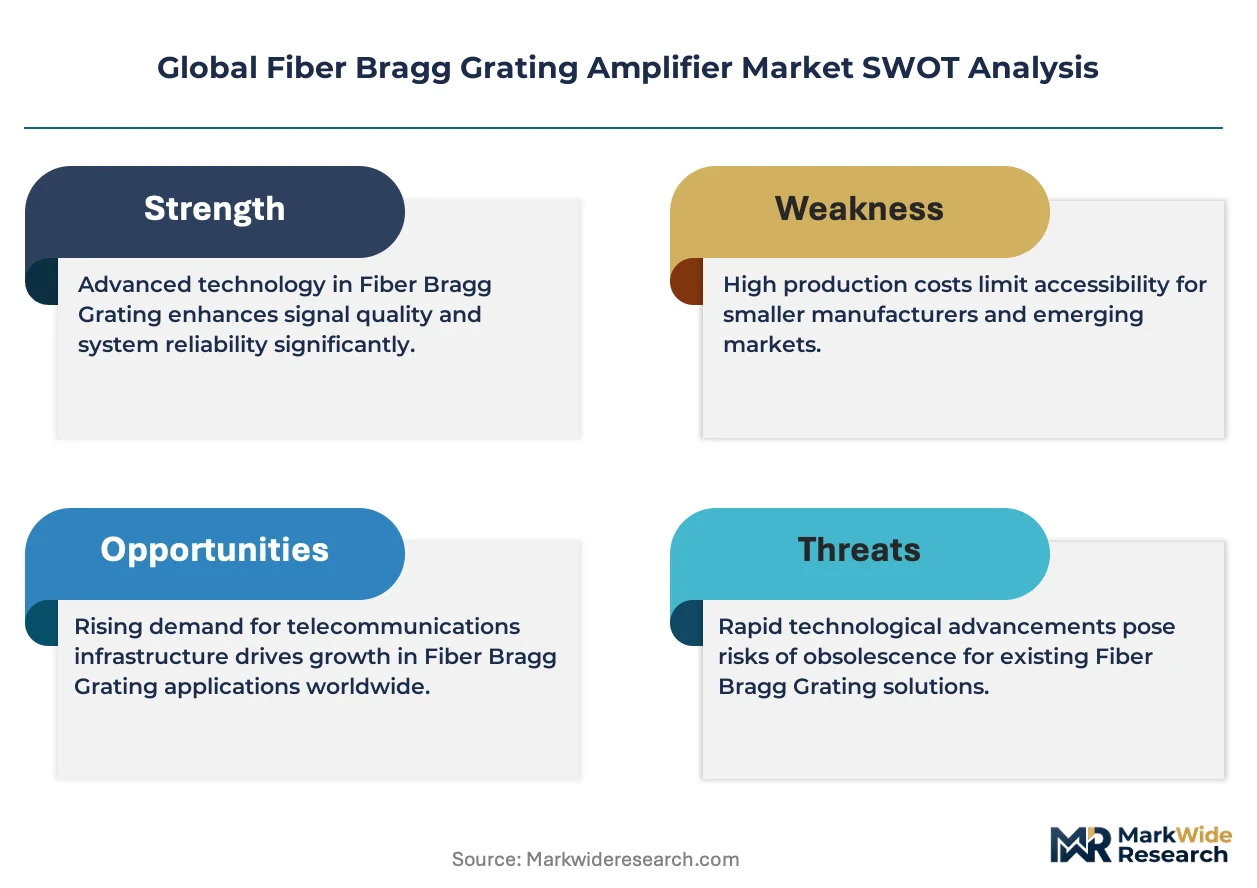
- High Fabrication Cost:The manufacturing process, involving specialized photosensitive fibers and high-precision UV laser inscription, results in a high unit cost that can limit adoption in price-sensitive applications.
- Alternative Amplification Technologies:Raman amplifiers and Semiconductor Optical Amplifiers (SOAs) present viable substitutes in specific network scenarios, such as distributed amplification or short-reach, low-cost links.
- Performance at Power Extremes:Thermal effects and nonlinearities can degrade the performance and stability of FBG amplifiers at very high optical power levels, posing a constraint for certain directed energy or industrial applications.
Strategic Opportunities
- Emerging Transmission Bands:Developing amplifiers for the O-band and E-band opens new avenues for growth, addressing capacity demands in short-reach data center interconnects and access networks.
- Integrated Photonic Modules:Converging amplification with monitoring and dispersion compensation functions onto a single photonic integrated circuit creates value by reducing equipment size and power consumption.
- Fiber Optic Gyroscope Systems:The aerospace and defense sector offers a high-value opportunity for specialized, radiation-hardened FBG amplifiers used within sophisticated fiber optic gyroscope navigation systems.
Industry Challenges
- Interoperability Standardization:Achieving consensus through bodies like the IEC on performance and interface standards for multi-band, integrated amplifiers is critical to ensure multi-vendor compatibility in complex networks.
- Legacy System Integration:Ensuring new, sophisticated FBG amplifiers can be deployed into existing fiber networks without introducing penalties or requiring extensive re-engineering of legacy infrastructure remains a persistent operational hurdle.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Fiber Bragg Grating Amplifier Market |
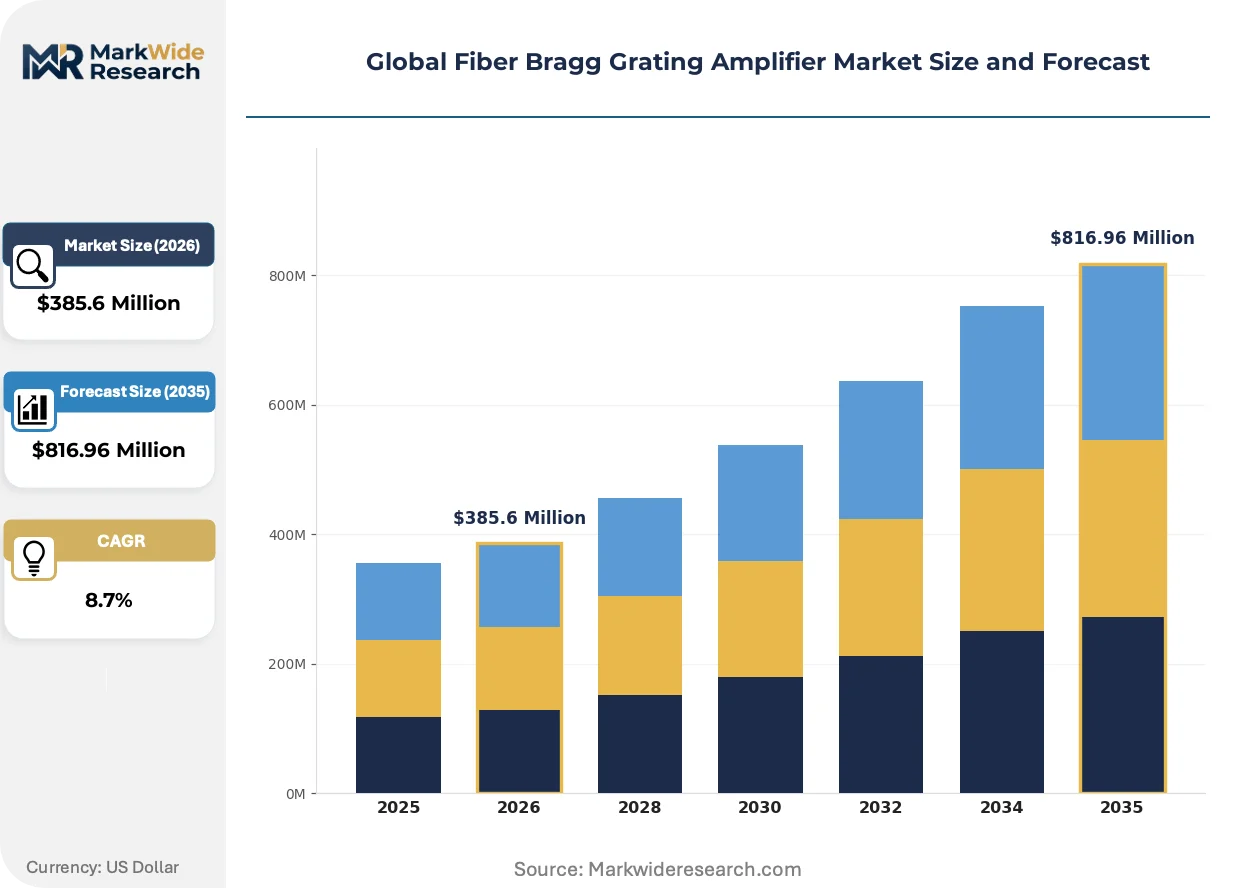
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $816.96 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Erbium-Doped Fiber Amplifier, Raman Fiber Amplifier, Semiconductor Optical Amplifier, Fiber Bragg Grating-Based Amplifier Technology: Wavelength Division Multiplexing, Coherent Detection, Dispersion Compensation, Optical Signal Processing Application: Telecommunications, Data Center Interconnects, Military Communications, Sensing and Instrumentation End User: Network Operators, Data Center Facilities, Government Agencies, Research Institutions |
| Companies Covered | FBGS Technologies GmbH, Com&Sens bvba, Femto Sensing International, iXBlue Photonics, TeraXion Inc., Optical Fiber Solutions, QPS Photronics, Smart Fibers Ltd., Luna Innovations Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Fiber Bragg Grating Amplifier Market Strategic Shifts & Innovations
A drive toward higher functional density and multi-band capability is redefining the FBG amplifier landscape. This evolution is a direct response to the physical and spectral constraints of next-generation optical networks, demanding more intelligence within smaller footprints.
Advanced amplifier modules that co-package FBG filters, gain media, and pump lasers are becoming the standard. Network equipment manufacturers are quickly adopting these integrated solutions for new data center and 5G backhaul deployments. This high level of integration is rendering obsolete the traditional approach of assembling systems from discrete optical components.
European Union RoHS directives place stringent restrictions on hazardous substances in electronic equipment, including optical amplifiers. This regulation forces manufacturers to re-engineer designs and qualify new materials for solder and other components to maintain market access. The entire supply chain for C-band and L-band products sold in Europe is directly impacted by these material composition rules.
Buying behavior now involves large-scale network operators specifying custom performance parameters for amplifier modules. This moves away from off-the-shelf product procurement and disrupts the standard product catalog model for vendors. The practice is most visible among hyperscale data center operators in the United States seeking to optimize network performance for specific workloads.
Global Fiber Bragg Grating Amplifier Market Segmentation
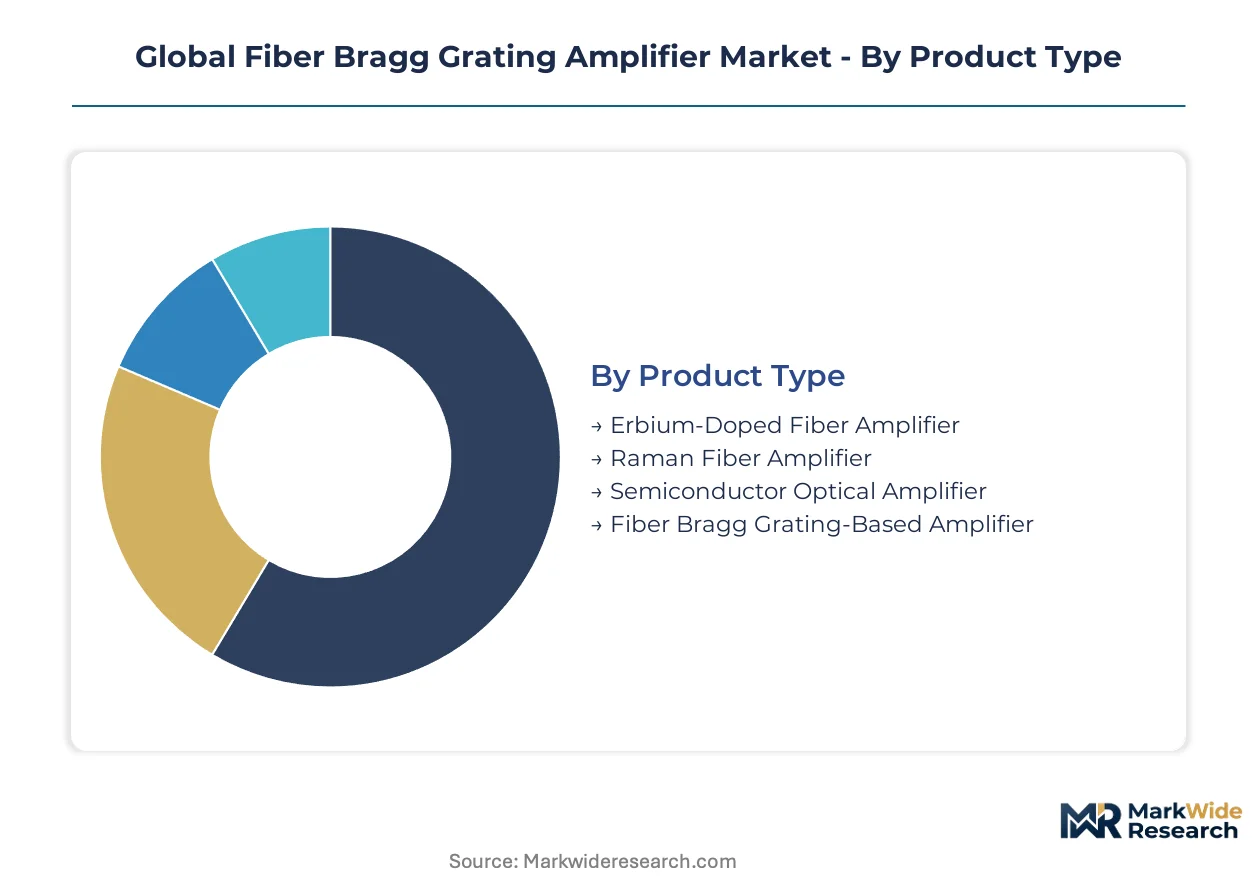
Understanding the segmentation of the Fiber Bragg Grating amplifier market clarifies where innovation and investment converge. This detailed breakdown reveals distinct value propositions for different product architectures and application scenarios. Analyzing these segments helps stakeholders prioritize development efforts and market penetration strategies.
Product Type:
Product type segmentation highlights the varying development cycles and commercial maturity across FBG amplifier designs.
- Erbium-Doped Fiber Amplifier:These amplifiers utilize erbium-doped fiber as the gain medium, pumped by laser diodes, and are highly optimized for C-band and L-band amplification. Demand concentrates in long-haul telecommunications networks, driven by the need for high signal-to-noise ratios over vast distances.
- Fiber Bragg Grating-Based Amplifier:These devices integrate FBG filters directly into the amplifier design to achieve wavelength-selective gain and noise suppression. Hyperscale data centers in the United States increasingly deploy these for precise channel management in dense WDM systems.
- Raman Fiber Amplifier:Raman amplifiers provide distributed gain and operate at various wavelengths, offering flexibility for specialized network configurations.
- Semiconductor Optical Amplifier:SOAs offer compact size and low power consumption, finding use in metro networks and optical switching applications.
Erbium-Doped Fiber Amplifiers dominate the installed base. Fiber Bragg Grating-Based Amplifiers are where expansion concentrates.
Technology:
Technology segmentation reveals the core functional capabilities that address specific challenges in optical signal management.
- Wavelength Division Multiplexing:WDM technology enables multiple optical signals at different wavelengths to be transmitted over a single fiber, drastically increasing network capacity. Telecommunications network operators globally prioritize WDM integration for 5G backhaul and fixed broadband expansion.
- Optical Signal Processing:This involves manipulating optical signals directly, offering advanced functionalities like reconfigurable add-drop multiplexing and dynamic gain equalization. Data center interconnects in Europe are increasingly adopting these for flexible and high-speed data transfer.
- Dispersion Compensation:Dispersion compensation techniques mitigate signal distortion over long fiber spans, crucial for maintaining data integrity in high-speed links.
- Coherent Detection:Coherent detection enhances receiver sensitivity and spectral efficiency, supporting ultra-high-speed data transmission in long-haul systems.
Wavelength Division Multiplexing is fundamental for increasing network capacity, while Optical Signal Processing unlocks new capabilities for dynamic network management.
Application:
Application segments delineate the primary end-use cases that drive significant volume and revenue for FBG amplifier solutions.
- Telecommunications:This segment encompasses long-haul, metro, and access networks, where FBG amplifiers boost signal strength for voice, video, and data transmission. China's MIIT directives for 5G and F5G infrastructure heavily influence demand in this sector.
- Sensing and Instrumentation:FBG amplifiers enhance the performance of optical sensors for precise measurements in structural health monitoring and industrial process control. The energy sector in the United States utilizes these for critical infrastructure monitoring.
- Data Center Interconnects:These applications connect data centers over short to medium distances, requiring high-bandwidth and low-latency amplification solutions.
- Military Communications:Military applications demand robust and secure optical communication links, often in harsh environments, leveraging specialized FBG amplifier designs.
The largest revenue contribution comes from Telecommunications, with Sensing and Instrumentation showing the steepest expansion trajectory.
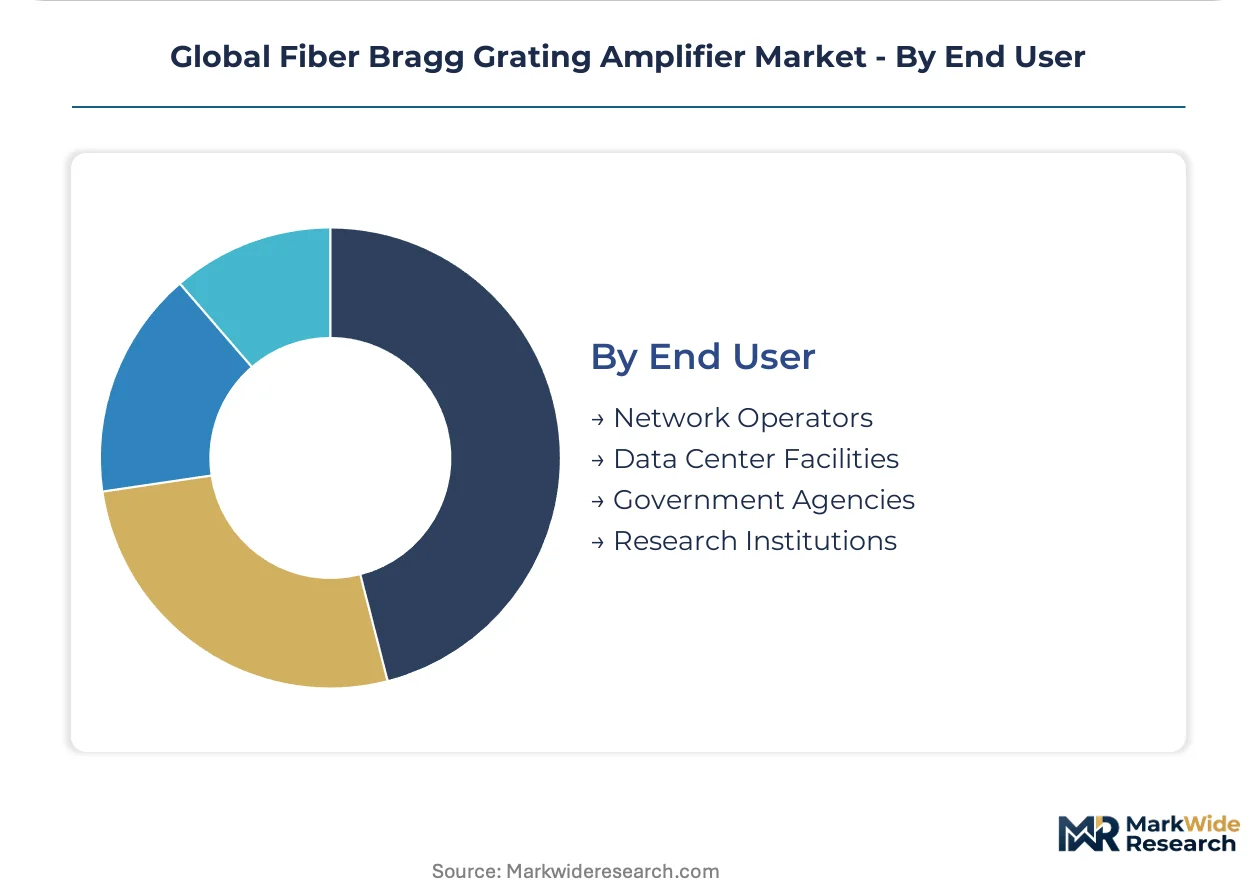
End User:
End user segmentation reflects the varying levels of technical sophistication and procurement processes among different customer groups.
- Network Operators:These entities manage large-scale optical networks, requiring custom-specified, high-performance FBG amplifiers for their infrastructure. Hyperscale operators in North America often dictate specific performance parameters for their deployments.
- Data Center Facilities:Data centers deploy FBG amplifiers for high-speed interconnects and internal network optimization, prioritizing integration and power efficiency. European data centers are increasingly focused on energy-efficient amplifier solutions to meet sustainability goals.
- Government Agencies:Government agencies procure FBG amplifiers for secure communication networks and specialized sensing applications, often with stringent security and reliability requirements.
- Research Institutions:Research institutions utilize FBG amplifiers for experimental setups, advanced optical communication studies, and sensor development, driving demand for flexible and high-precision devices.
Procurement patterns for Network Operators are highly standardized. Data Center Facilities often require bespoke solutions.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Hyperscale operators and network providers primarily drive demand for Fiber Bragg Grating amplifiers. These key buyers concentrate their investments in regions with robust digital infrastructure and ambitious network expansion plans. This concentration shapes the regional market dynamics for FBG amplifier solutions.
China
China's massive investment in 5G and F5G network infrastructure heavily drives Fiber Bragg Grating amplifier demand. The Ministry of Industry and Information Technology (MIIT) directives guide significant public and private sector spending on optical network backbone. Major telecommunication hubs like Shenzhen are seeing widespread deployment of high-performance FBG amplifiers for dense WDM systems.
United States
Demand in the United States stems from hyperscale data center operators and expanding industrial sensing applications. The Federal Communications Commission (FCC) sets requirements for network equipment, influencing amplifier design. Silicon Valley is a key innovation center, developing advanced FBG amplifier solutions for high-bandwidth data center interconnects.
Germany
Germany's market for FBG amplifiers benefits from its strong industrial base and focus on high-precision manufacturing. European CE marking and RoHS directives significantly impact material composition for electronic components. Industrial regions such as Bavaria integrate FBG amplifiers into advanced sensing systems for automation and structural health monitoring.
Japan
Japan's market is characterized by advanced telecommunications infrastructure and innovation in optical technologies. The Ministry of Economy, Trade and Industry (METI) supports research and development in next-generation optical networking components. Tokyo is a primary center for deploying FBG amplifiers in high-capacity WDM systems for urban and long-haul networks.
India
India presents a significant growth opportunity due to its rapid telecommunications expansion and digital transformation initiatives. The Telecom Regulatory Authority of India (TRAI) oversees network infrastructure development, encouraging upgrades. Major metropolitan areas like Bangalore are experiencing increased demand for FBG amplifiers in 5G backhaul and data center interconnects.
Global Fiber Bragg Grating Amplifier Market Key Industry Players
Channel-controlling players compete with product-specialist players for market share in the Fiber Bragg Grating amplifier sector. The market exhibits a tiered structure, with a few large integrated optical component manufacturers alongside numerous niche technology providers. Strategic archetypes include vertically integrated solution providers and focused component innovators. Companies primarily engage in strategic partnerships and technology licensing to expand their market reach and product portfolios.
Specialists in high-precision optical components such as FBGS Technologies GmbH exemplify the segment of firms focused on advanced Fiber Bragg Grating manufacturing techniques and specialized designs. TeraXion Inc. represents a player leveraging expertise in dispersion compensation to offer highly integrated amplifier solutions, catering to complex network requirements for high-speed data transmission. Luna Innovations Inc. further anchors the market with its focus on high-precision sensing and instrumentation applications, demonstrating diversification beyond core telecommunications into industrial and infrastructure monitoring. These companies collectively illustrate the blend of specialized component development and integrated solution delivery that defines the competitive landscape.
| Leading Market Players |
|---|
| FBGS Technologies GmbH |
| Com&Sens bvba |
| Femto Sensing International |
| iXBlue Photonics |
| TeraXion Inc. |
| Optical Fiber Solutions |
| QPS Photronics |
| Smart Fibers Ltd. |
| Luna Innovations Inc. |
| Others |
Cost & Logistics Intelligence
Shenzhen's manufacturing capacity for optical components significantly influences downstream pricing power for Fiber Bragg Grating amplifiers. This concentration allows key suppliers to dictate terms for specialized FBG amplifier modules.
Pricing Analysis
Contract-based pricing for FBG amplifiers often follows a cost-plus model, indexed to specialized fiber and laser diode input costs. Price differentiation stems from custom performance parameters specified by network operators and the level of integration within amplifier modules. Pricing pressure arises from the viability of alternative amplification technologies, particularly for short-reach applications. Hyperscale data center operators exhibit lower price sensitivity due to their demand for highly customized, performance-optimized solutions, while research institutions are more price-sensitive.
Supply Chain Analysis
Upstream feedstock for FBG amplifiers, including specialized photosensitive fibers and high-power UV lasers, primarily originates from Japan and the United States. Geographic supply concentration for these critical components creates single-source vulnerability for manufacturers. Rare earth elements for Erbium-Doped Fiber Amplifiers further contribute to raw material dependencies, mainly drawing from China. Distribution runs through direct sales channels to large network operators and specialized system integrators for sensing applications.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Fiber Bragg Grating amplifier market is experiencing a shift in buyer power, driven by the consolidation of demand from hyperscale data center operators and large telecommunications network providers.
For Market Incumbents: Entrench market position by accelerating R&D into multi-band amplifier solutions for O-band and E-band applications. This counters the threat from alternative amplification technologies and addresses emerging capacity demands. Deepen vertical integration into specialized component manufacturing to mitigate supply chain risks and control costs. Strategic partnerships with key component suppliers in Japan can also secure critical inputs.
For New Entrants and Emerging Players: Specialized radiation-hardened FBG amplifiers for aerospace and defense represent a high-value, underpenetrated segment. Targeting specific industrial sensing applications, such as structural health monitoring in civil infrastructure, offers another viable entry point. Focus on delivering integrated photonic modules that combine amplification with dispersion compensation and monitoring functions, offering a compact and power-efficient go-to-market angle.
For Investors and Strategic Acquirers: Long-term, this sits as a foundational technology play because optical communication underpins all digital infrastructure expansion. Target niche technology providers specializing in O-band/E-band amplifier development or integrated photonic solutions for acquisition. The signal to watch is the progress in interoperability standardization by bodies like the IEC for multi-band, integrated amplifiers, indicating broader market readiness and adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in O-band/E-band R&D | Expands market reach into emerging telecommunication windows for future capacity. |
| Develop integrated photonic modules | Reduces physical footprint and power consumption for data center deployments. |
| Secure specialized fiber supply agreements | Mitigates single-source vulnerability for critical upstream components. |
| Pursue aerospace/defense certifications | Unlocks high-value markets requiring robust and reliable amplifier designs. |
| Form partnerships for WDM system integration | Ensures seamless deployment of advanced FBG amplifiers into complex networks. |
Research Approach
Findings reconcile primary fieldwork against secondary review of IEC standards, ITU recommendations, and national telecommunication regulations. Primary interviews engaged optical engineers, network planners, procurement managers, and regulatory body representatives to gather qualitative insights. This approach facilitated bottom-up data aggregation and top-down market validation, ensuring comprehensive data coverage.
Forecast inputs considered include 5G deployment timelines, WDM channel density, and data center expansion rates across the analysis window. The analytical framework modeled segmentations by product type, technology, application, end-user, and transmission band. Compound Annual Growth Rates were derived from historical data analysis and projected market dynamics, reflecting anticipated technological advancements and infrastructure investments.
Macroeconomic conditions sit as an overlay; deviation in global economic growth or trade policy stability would shift the trajectory of market expansion. Forecasts reflect assumptions regarding technological adoption and regulatory frameworks. Cross-checking against ITU recommendations and regional telecommunication authority reports is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Bio-Optics Market
Optical Components
Global Fiber Optic Gyroscope Market
Optical Components
High Power Double-Clad Fiber Bragg Grating Market
Optical Components
Europe Eye Tracking Solutions Market
Optical Components
Optical Isolator Market
Optical Components
Lithium Niobate Modulator Market
Optical Components
Optical Fiber and Plastic Conduit Market
Optical Components
Flexible Glass for Flexible Electronics Market
Optical Components
Global Optical Imaging System Market
Optical Components
North America Laser Diode Market
Optical Components
Ring Panel Filters Market
Optical Components
Liquid Light Guides Market
Optical Components
Planar Lightwave Circuit Splitter Market
Optical Components
Global Electrochromic Glass and Devices Market
Optical Components
Silicon Photonics Wafer Market
Optical Components
Global Wavelength Division Multiplexing (WDM) Equipment Market