
 Global Optical Coating Equipment Market | 2026-2036
Global Optical Coating Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Optical Coating Equipment Market Intelligence
Specialized equipment manufacturing capacity in Germany and Japan is expanding to meet demand for high-precision deposition systems. The Bühler Group leverages its extensive engineering heritage to serve high-volume consumer electronics applications. In contrast, Veeco Instruments specializes in complex systems for semiconductor and data storage markets. ULVAC sustains a strong position through its broad portfolio of vacuum technologies catering to diverse industrial clients.
Optical coating equipment comprises specialized machinery designed to deposit single or multiple thin-film layers onto substrates. These systems precisely control material deposition to achieve specific optical properties, such as anti-reflection or high-reflectivity, with layer thickness uniformity measured in angstroms. Physical Vapor Deposition (PVD) technologies, including sputtering systems, command the largest market share due to their versatility and cost-effectiveness. Demand from camera lens and eyewear applications provides a stable volume base, while semiconductor devices represent a high-margin growth frontier.
Material selection and process safety are governed by a complex web of international and national standards. Regulations such as the EU's REACH and RoHS directives restrict hazardous substances in coatings, influencing the development of deposition materials. Concurrently, ISO 9001 standards are critical for qualifying equipment suppliers in the medical and aerospace sectors. Stakeholder success will depend on developing equipment compatible with emerging eco-friendly materials and advanced deposition techniques like atomic layer deposition.
Market Dynamics
The optical coating equipment market is defined by the dual pressures of high-volume, cost-sensitive consumer electronics applications and low-volume, high-precision semiconductor requirements. This dynamic forces equipment manufacturers to balance platforms optimized for throughput against those designed for atomic-scale precision and material purity.
Growth Catalysts
- Next-Generation Semiconductors:Demand for atomic layer deposition (ALD) and advanced physical vapor deposition (PVD) systems is rising from semiconductor foundries to produce 3D NAND memory and gate-all-around transistors requiring ultra-thin, conformal films.
- Automotive Sensor Proliferation:The integration of LiDAR, advanced driver-assistance systems (ADAS) cameras, and in-cabin monitoring requires complex optical coatings for anti-reflection, filtering, and environmental protection, creating a significant volume driver for deposition equipment.
- National Industrial Policies:Government initiatives in the United States, China, and the European Union to bolster domestic semiconductor manufacturing directly stimulate capital investment in new fabrication facilities and the associated optical coating and lithography equipment.
Market Restraints
- High Capital Costs:The initial investment for high-precision deposition systems, particularly multi-chamber cluster tools and EUV-compatible equipment, is substantial, creating a high barrier to entry for new firms and smaller research institutions.
- Process Qualification Complexity:Qualifying a new coating process for critical applications in aerospace or medical devices is a time-consuming and expensive endeavor, often taking many months and slowing the adoption of new materials or equipment.
- Material Use Restrictions:Environmental regulations like the EU's REACH directive constrain the use of certain heavy metals and chemical compounds historically used in high-performance optical coatings, forcing costly research into viable alternatives.
Strategic Opportunities
- AR and VR Optics:The emerging market for augmented and virtual reality headsets presents a significant opportunity, as the complex waveguides and micro-displays used in these devices require novel and precisely deposited optical coatings.
- Flexible and Conformal Coatings:Developing deposition equipment capable of uniformly coating non-planar or flexible substrates opens new applications in wearable sensors, foldable displays, and advanced medical implants, moving beyond traditional rigid optics.
- Biomedical and Life Sciences:Equipment tailored for coating implantable medical devices, diagnostic tools, and microfluidic chips represents an underpenetrated, high-margin segment where precision and biocompatibility are paramount.
Industry Challenges
- Specialized Talent Scarcity:A persistent shortage of process engineers and technicians with the expertise to develop, operate, and maintain sophisticated vacuum deposition systems hampers production scalability and innovation across the industry.
- IP Protection:Safeguarding proprietary process recipes and equipment configurations is a constant challenge, particularly as manufacturing and supply chains become more geographically distributed and involve multiple partners.
- Standardization Gaps:A lack of universal standards for new material characterization and process control in emerging fields like quantum computing and advanced photonics creates integration challenges for equipment suppliers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Optical Coating Equipment Market |
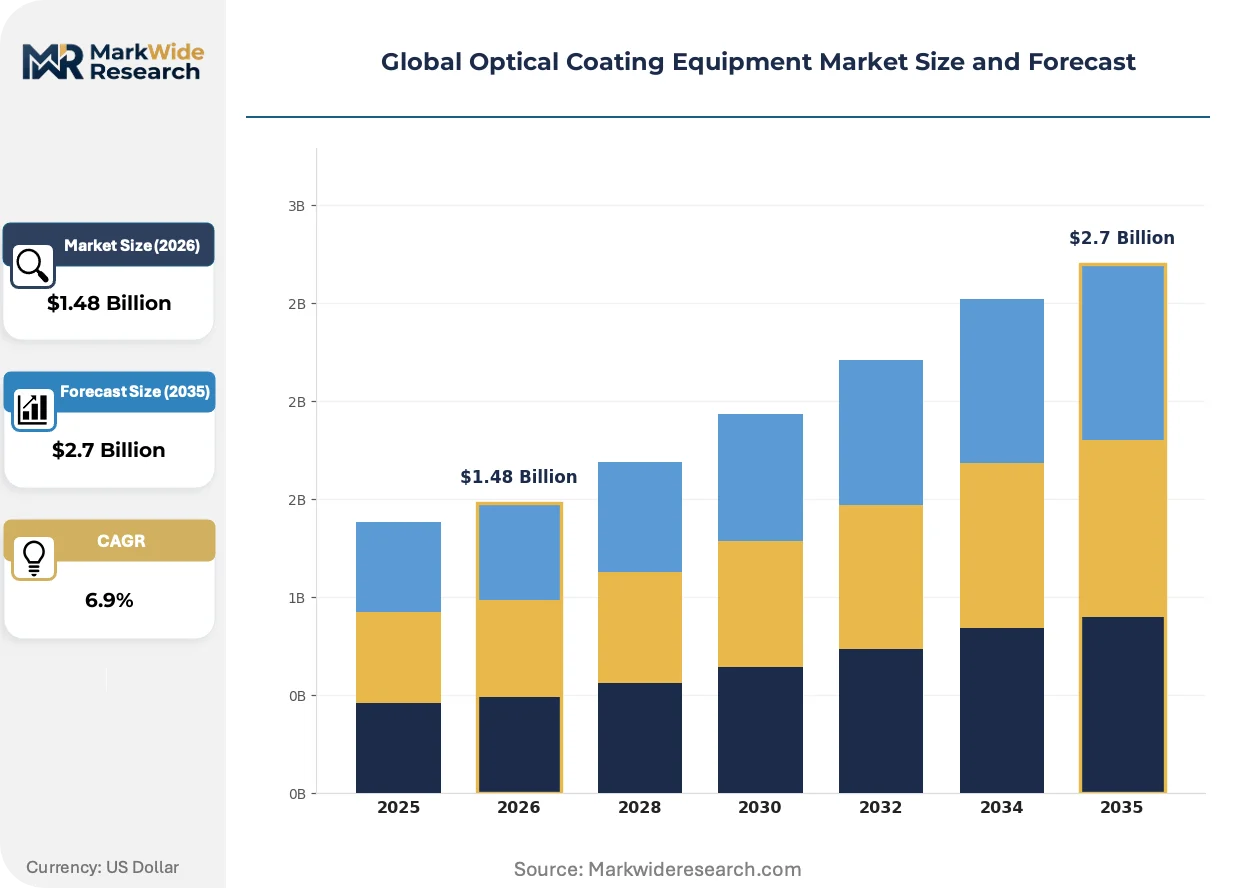
| Market Size in 2026 | $1.48 Billion |
| Market Size in 2035 | $2.7 Billion |
| CAGR (2026 – 2036) | 6.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vacuum Coaters, Sputtering Systems, Evaporation Equipment, Ion Beam Coaters Technology: Physical Vapor Deposition, Chemical Vapor Deposition, Atomic Layer Deposition, Plasma-Enhanced Deposition Application: Camera Lenses, Eyewear, Display Panels, Solar Panels, Semiconductor Devices End User: Consumer Electronics Manufacturers, Optical Component Fabricators, Semiconductor Foundries, Research Laboratories |
| Companies Covered | Buhler Leybold Optics, Shincron, Bühler Group, Veeco Instruments, Evatec, ULVAC, CANON ANELVA, IHI, Applied Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Optical Coating Equipment Market Strategic Shifts & Innovations
The push for atomic-level process control is reshaping equipment design, favoring platforms that integrate advanced metrology and machine learning. This trend enables the production of optical components with previously unattainable performance, driving innovation in semiconductors, displays, and sensing technologies.
Atomic Layer Deposition (ALD) technology provides unparalleled control for depositing uniform, conformal films one atomic layer at a time. Semiconductor manufacturers are the primary adopters, using ALD for critical gate oxide and barrier layers in advanced logic and memory devices. This adoption is modularizing equipment architecture, where specialized ALD process chambers are integrated into large, versatile cluster tool platforms alongside other deposition and etch technologies.
The European Union's RoHS directive, which restricts hazardous substances in electronics, continues to influence material science for optical coatings. The regulation compels equipment and material suppliers to develop and validate lead-free and cadmium-free compounds that can replicate the optical properties of traditional materials. This shift most directly affects suppliers to the consumer electronics and automotive lighting sectors, which must certify their entire supply chains for compliance.
A notable behavioral shift is the move by large original equipment manufacturers (OEMs) to establish in-house coating capabilities for critical components. This disrupts the traditional outsourcing model, as OEMs in the smartphone and automotive display sectors seek greater control over performance, intellectual property, and supply chain resilience by purchasing equipment directly. This trend is most pronounced in manufacturing hubs across South Korea and Taiwan, where vertical integration is a key competitive strategy.
Global Optical Coating Equipment Market Segmentation
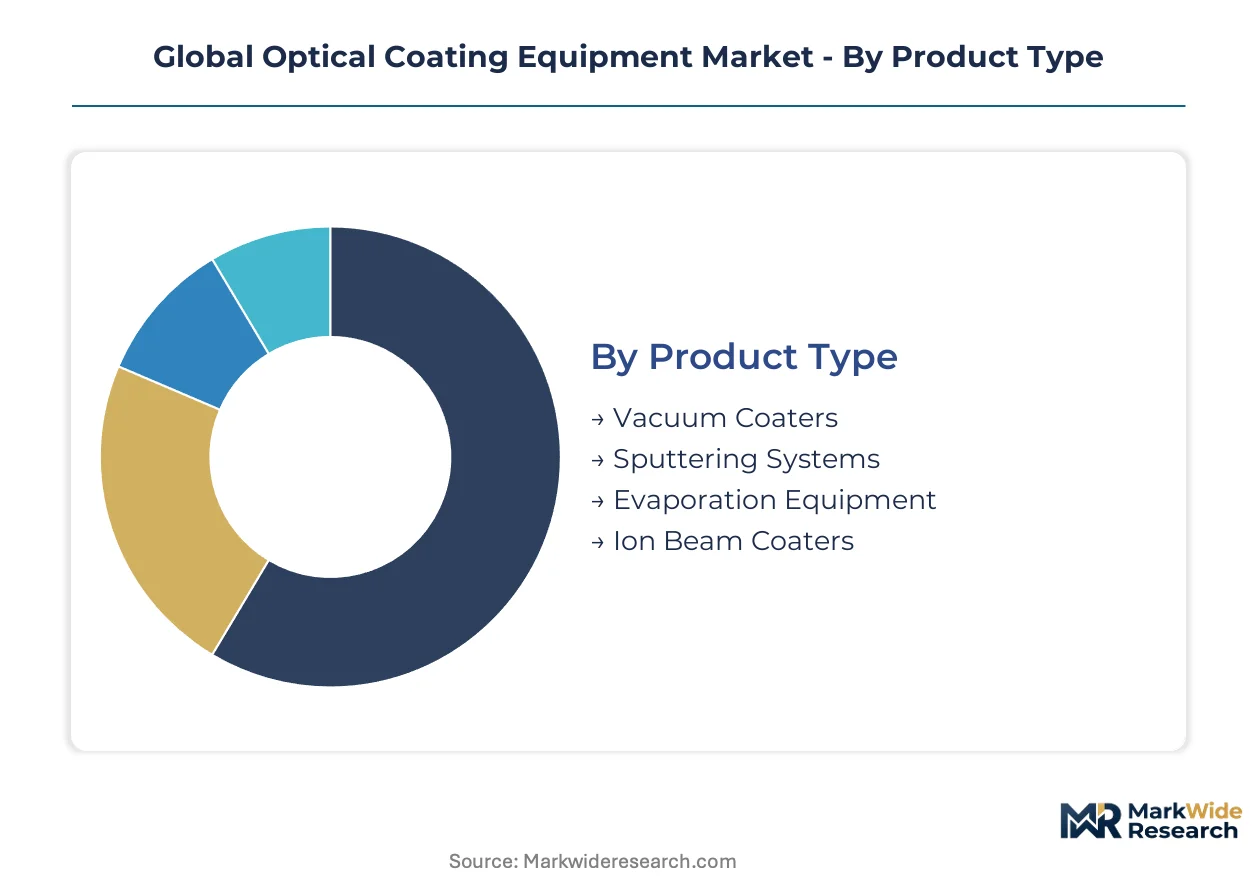
The optical coating equipment market addresses a wide spectrum of industrial requirements, necessitating a granular understanding of distinct product types, underlying technologies, diverse applications, and varied end-user profiles. This segmentation provides clarity on where specific market demands originate and how equipment manufacturers tailor their offerings.
Product Type:
Certain product types within optical coating equipment face stringent certification requirements, particularly for medical devices and aerospace components, demanding compliance with ISO 9001 and specific national aviation standards like those from the FAA or EASA.
- Sputtering Systems:These systems utilize plasma to deposit thin films from a target material onto a substrate, offering excellent adhesion and density for optical coatings. Semiconductor foundries in Taiwan and South Korea drive demand for sputtering systems to produce high-performance integrated circuits.
- Vacuum Coaters:These are fundamental platforms for depositing various optical films under controlled vacuum conditions, enabling precise layer thickness. Consumer electronics manufacturers in China and Vietnam utilize vacuum coaters for high-volume production of display panels and camera optics.
- Evaporation Equipment:Thermal or e-beam evaporation deposits materials in a vacuum, commonly used for anti-reflection coatings on eyewear and decorative applications.
- Ion Beam Coaters:These systems offer highly precise thickness control and film density, critical for advanced optical filters in scientific instruments and defense applications.
Sputtering Systems sits at the top of the volume ranking, with Ion Beam Coaters climbing the fastest due to precision requirements.
Technology:
The cost structure for optical coating technologies varies significantly, influencing adoption based on desired precision, throughput, and material efficiency across different industries.
- Physical Vapor Deposition:PVD encompasses various techniques like sputtering and evaporation, depositing thin films by physical means in a vacuum environment. This technology commands the largest market share due to its versatility and cost-effectiveness in camera lens production for smartphones.
- Atomic Layer Deposition:ALD deposits films one atomic layer at a time through sequential self-limiting gas-phase reactions, providing unparalleled uniformity and conformality. Semiconductor manufacturers in the US and Japan are rapidly adopting ALD for advanced logic and memory devices.
- Chemical Vapor Deposition:CVD uses chemical reactions to deposit thin films, often employed for harder coatings and specialized semiconductor applications requiring specific material properties.
- Plasma-Enhanced Deposition:This technique utilizes plasma to enhance deposition rates and film quality, finding use in display panel manufacturing and optical component fabrication.
Physical Vapor Deposition technologies represent the largest segment by installed base, while Atomic Layer Deposition exhibits the fastest-growing trajectory.
Application:
Application segments for optical coating equipment exhibit diverse volume requirements, ranging from mass-produced consumer goods to highly specialized industrial components.
- Semiconductor Devices:Optical coatings are critical for advanced lithography, anti-reflection, and passivation layers in integrated circuits, enabling smaller and more powerful chips. Demand from leading foundries in Taiwan and South Korea drives innovation in this high-margin segment.
- Display Panels:Anti-reflection, anti-glare, and hard coatings enhance the performance and durability of screens for smartphones, tablets, and televisions. Manufacturers in China and Vietnam require high-throughput equipment for large-scale display production.
- Camera Lenses:Anti-reflection coatings improve light transmission and reduce glare in smartphone cameras and advanced driver-assistance systems.
- Eyewear:Scratch-resistant and anti-reflective coatings are standard features for corrective and protective lenses, enhancing visual clarity for consumers.
- Solar Panels:Anti-reflective coatings improve light absorption efficiency in photovoltaic cells, increasing power generation for renewable energy projects.
Semiconductor Devices command the highest revenue share, with Solar Panels gaining significant traction due to clean energy initiatives.
End User:
The customer base for optical coating equipment spans various industrial and research entities, each with distinct procurement processes and technical specifications.
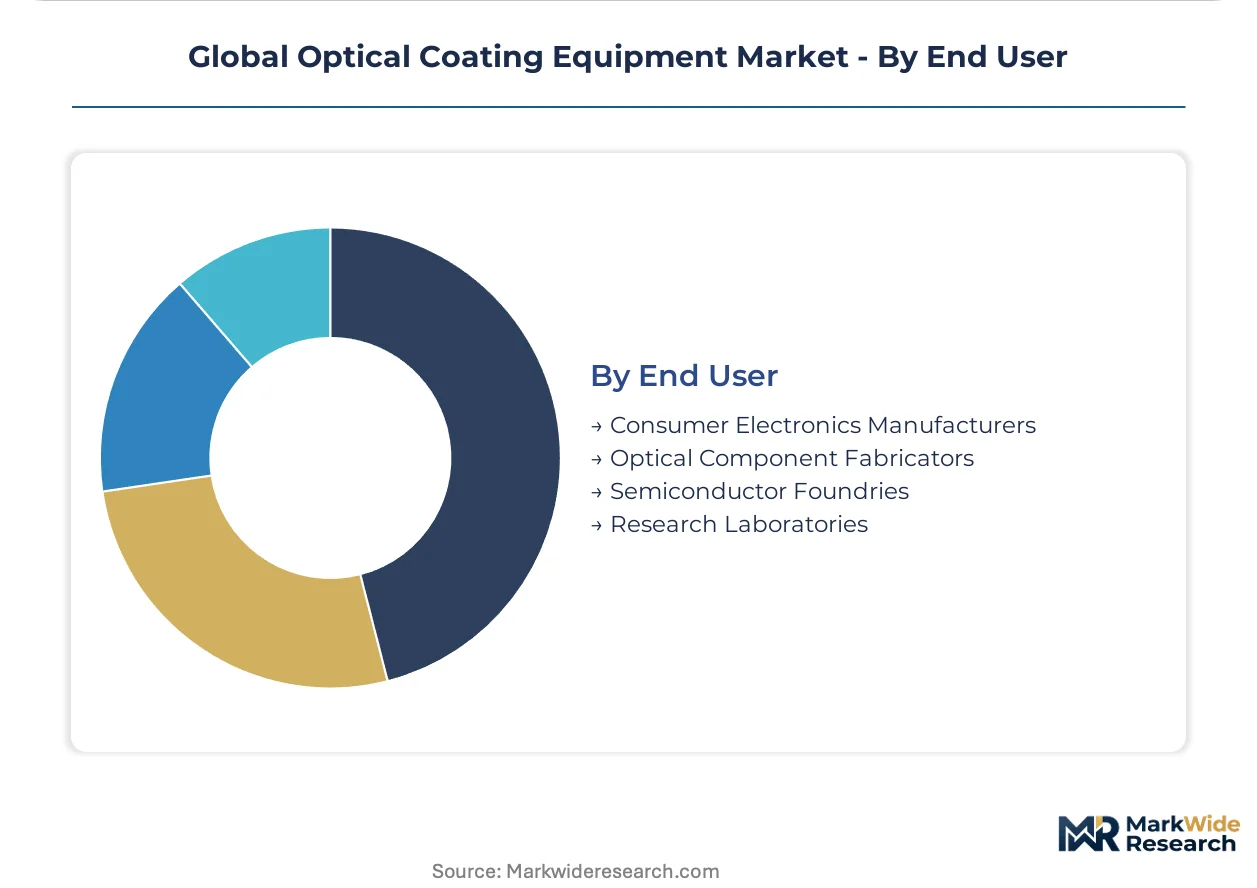
- Semiconductor Foundries:These entities require ultra-high precision, high-throughput systems for depositing critical layers in microprocessors, memory, and sensors. Major foundries in the US, Taiwan, and South Korea invest heavily in advanced deposition equipment.
- Consumer Electronics Manufacturers:These companies demand reliable, cost-effective equipment for mass production of components like camera modules, display screens, and wearable device optics. Production hubs in China and Vietnam are key procurement centers.
- Optical Component Fabricators:These specialized firms produce lenses, filters, and mirrors for diverse industries, requiring versatile coating solutions for custom specifications.
- Research Laboratories:Academic and corporate research facilities use coating equipment for material science studies, prototype development, and advanced photonics research.
Semiconductor Foundries represent the highest value segment, while Research Laboratories demonstrate consistent, specialized demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage significantly influences the global optical coating equipment market, as manufacturers strategically locate production facilities to balance environmental compliance costs and market access. Stringent environmental regulations in some developed economies often encourage production migration to regions offering different cost structures for adherence, reshaping the supply chain for specialized equipment.
China
China's vast electronics production ecosystem drives substantial demand for optical coating equipment, particularly for display panels and high-volume consumer electronics. Government initiatives through the MIIT actively promote domestic manufacturing capabilities and self-sufficiency in critical technologies. Cities like Shenzhen and Shanghai host major electronics manufacturing clusters, necessitating advanced vacuum coaters and sputtering systems.
United States
The United States market for optical coating equipment concentrates on advanced semiconductor fabrication and high-precision defense and aerospace applications. The Inflation Reduction Act (IRA) supports domestic manufacturing and supply chain resilience, stimulating investment in advanced deposition technologies. Silicon Valley and Austin serve as prominent hubs for semiconductor foundries and research institutions, requiring state-of-the-art ALD and PVD systems.
Japan
Japan exhibits strong demand for optical coating equipment driven by its precision optics industry, advanced materials research, and automotive sensor manufacturing. METI industrial policies foster innovation in high-tech manufacturing sectors, ensuring adherence to stringent quality standards like JIS. The Tokyo and Osaka regions are critical centers for optical component fabricators and advanced research laboratories, specializing in ion beam coaters.
Germany
Germany's market for optical coating equipment is characterized by demand for high-precision deposition systems used in industrial machinery, automotive components, and scientific instruments. Compliance with the EU's REACH and RoHS directives is mandatory for equipment and materials, influencing product development. Bavaria and Baden-Württemberg are home to specialized equipment manufacturers and automotive suppliers, focusing on advanced PVD solutions.
South Korea
South Korea's robust semiconductor and display industries generate significant demand for optical coating equipment, especially for memory semiconductors and innovative display technologies. The national government actively supports the semiconductor industry, promoting investment in cutting-edge fabrication facilities. Gyeonggi Province is a major center for semiconductor foundries and display manufacturers, requiring high-throughput ALD and sputtering systems.
Global Optical Coating Equipment Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue high-precision semiconductor and advanced optics applications, creating a tiered market structure. This market balances the need for high-volume, cost-effective solutions with specialized, atomic-scale precision requirements. Strategic archetypes include integrated system providers, specialized technology developers, and regional niche players. Capacity expansion in key manufacturing hubs and strategic partnerships for technology co-development represent dominant competitive moves.
Among the established equipment providers, the Switzerland-based Bühler Group exemplifies suppliers catering to high-volume consumer electronics applications. The US-based Veeco Instruments Inc. represents specialists in complex systems for semiconductor and data storage markets. Japan-based ULVAC, Inc. maintains a strong position through its broad portfolio of vacuum technologies, serving diverse industrial clients globally.
| Leading Market Players |
|---|
| Buhler Leybold Optics |
| Shincron |
| Bühler Group |
| Veeco Instruments |
| Evatec |
| ULVAC |
| CANON ANELVA |
| IHI |
| Applied Materials |
| Others |
Cost & Logistics Intelligence
High-purity material commodity indices directly influence the cost of target materials for deposition equipment, cascading through the supply chain into distinct pricing tiers for optical coating systems. This cost structure differentiates equipment based on precision, throughput, and material purity requirements across end-user segments.
Pricing Analysis
Direct-to-OEM discounts significantly shape the final cost of optical coating equipment, with project-based and value-based pricing models dominating. Price differentiation stems from the rigorous certification level required for medical and aerospace applications (ISO 9001) and the extensive customization level for advanced semiconductor tools. Pricing softness reflects intense competition for high-volume consumer electronics applications. Consumer Electronics Manufacturers exhibit high price sensitivity, whereas Semiconductor Foundries prioritize performance and precision over initial capital expenditure.
Supply Chain Analysis
Dual-sourcing requirements are becoming standard practice for critical optical coating equipment components, particularly in semiconductor manufacturing. Geographic supply concentration centers on China, Taiwan, and Japan for manufacturing and assembly. The supply chain draws from high-purity target materials and specialized vacuum components, creating dependencies on a limited number of suppliers. Single-source vulnerability for niche precision parts presents a structural risk. Distribution runs through direct sales channels and specialized system integrators, especially for complex, high-precision systems.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global optical coating equipment market presents a compelling margin-expansion story, driven by the increasing demand for high-precision systems in semiconductor and advanced optics applications. This shift towards premium-tier segments allows for higher value capture and improved profitability for specialized equipment manufacturers.
For Market Incumbents:Anchor existing market share in high-volume segments through continuous process optimization and cost leadership. Incumbents should acquire specialized ALD technology firms to counter emerging entrant archetypes offering niche, high-precision solutions. Investing in advanced R&D for next-generation deposition techniques, particularly for EUV-compatible systems, is a critical lever. Protecting intellectual property through robust patent portfolios remains essential against technology replication.
For New Entrants and Emerging Players:Begin with specialized, high-margin white-space targets like AR/VR optics and bespoke biomedical devices, where precision outweighs volume. The most penetrable segment lies within research laboratories and specialized optical component fabricators, who require custom, high-performance solutions. A specific go-to-market angle involves developing deposition equipment compatible with emerging eco-friendly materials, addressing stricter environmental regulations like REACH. Focus on rapid prototyping and flexible manufacturing to serve these evolving needs.
For Investors and Strategic Acquirers:Asymmetric upside sits with mid-cap specialists possessing proprietary atomic layer deposition or ion beam coater technology. The market exhibits robust long-term viability over the next decade, driven by foundational demand from semiconductors and advanced optics. Acquisition targets should include firms with strong intellectual property in flexible or biocompatible coating solutions. A key signal to watch for inflection is increased capital expenditure by automotive OEMs for in-house sensor coating capabilities, indicating broader market adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Acquire ALD Technology Specialist | Secures leadership in advanced semiconductor and display applications. |
| Expand Manufacturing in US/EU | Mitigates supply chain risks and aligns with national industrial policies. |
| Invest in Eco-Friendly Material R&D | Addresses regulatory compliance and opens new market segments. |
| Form Strategic Partnerships for AR/VR | Captures early market share in emerging high-growth optics. |
| Develop In-Situ Metrology Integration | Enhances process control and equipment performance for critical components. |
Research Approach
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region informing the analysis. This involved combining in-depth interviews with industry stakeholders such as process engineers, R&D directors, and procurement managers, validated by secondary research. Key secondary data sources included SEC filings of public companies, patent databases, industry association reports, and peer-reviewed academic journals. Bottom-up and top-down triangulation ensured data consistency and accuracy.
Rate-of-change decomposition formed the analytical framework, dissecting market expansion into volume growth, price evolution, and product mix shifts across the analysis window. Segmentation dimensions modeled included product type, underlying technology, diverse applications, end-user profiles, and substrate material. Compound Annual Growth Rates were derived from historical trends and projected future demand. Key forecast inputs included global semiconductor capital expenditure and projected AR/VR device shipments.
Caveats apply where geopolitical trade tensions or rapid material science breakthroughs could materially shift the outlook. Forecasts reflect assumptions regarding technological development and regulatory stability. Deviation in semiconductor capital expenditure would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Japan Lithium Niobate Modulator Market
Optical Components
Fiber-Optic Attenuator Market
Optical Components
Waveguide Phase Shifter Market
Optical Components
Lithium Niobate Modulator Market
Optical Components
Asia-Pacific Optical Film Market
Optical Components
Liquid Lenses Market
Optical Components
Global Optical Diode Market
Optical Components
Portable Lenses Market
Optical Components
Terbium Gallium Garnet Market
Optical Components
Global Fiber Bragg Grating Amplifier Market
Optical Components
Optical Spectrum Analyzer (OSA) Market
Optical Components
Electro Optical System Market
Optical Components
Optical Film Market
Optical Components
North America Photonic Sensors Market
Optical Components
Mid-Infrared Laser Market
Optical Components
Fiber Optic Collimating Lens Market