
 MBE Components Market | 2026-2036
MBE Components Market Size, Share, and Industry Trends Forecast 2026-2036
MBE Components Market Insights
Modular source configuration is broadening buyer choice in MBE Components procurement. Veeco leverages its integrated effusion cell and electron source portfolios to sustain technology leadership across compound semiconductor lines. Riber anchors European supply through specialized III-V growth systems for research and production fabs. Scienta Omicron differentiates via ultra-high vacuum chamber architectures that compete on base pressure performance.
Molecular beam epitaxy components comprise precision-engineered subsystems including effusion cells, electron beam sources, substrate heaters, and cryopanels that deposit single-crystal thin films layer-by-layer in ultra-high vacuum conditions below 10^-10 torr. These components enable atomic-scale control essential for manufacturing high-electron-mobility transistors, laser diodes, and quantum structures. Electron sources and substrates lead current revenue pools given their consumable nature and critical role in film quality, while ion guns and vacuum chambers capture expanding share as process complexity rises in quantum computing and space electronics applications. Thin films and masks represent mature segments where price competition intensifies and margin pools shift toward custom engineering services.
The EPA enforces vacuum equipment emissions standards that shape component material selection and pump system design, while REACH compliance in Europe restricts hazardous substances in effusion cell construction and chamber coatings. Japan's METI coordinates national semiconductor strategies that direct procurement toward domestic MBE component suppliers. ISO 9001 and ISO 14001 certifications function as baseline market access requirements for vendor qualification at tier-one semiconductor manufacturers. Stakeholders must monitor evolving export control classifications for epitaxial growth equipment and assess supply chain exposure to specialty refractory metal sources.
Market Dynamics
Semiconductor foundries are compressing node geometries below 3nm, forcing MBE component suppliers to deliver atomic-scale precision at production-scale throughput. This technical tension between research-grade accuracy and fab economics is restructuring procurement priorities across Taiwan, South Korea, and the United States.
Growth Catalysts
- EPA vacuum purity mandates:Stricter emissions standards for ultra-high vacuum equipment are compelling fabs in the United States to upgrade effusion cell and cryopanel systems, creating replacement demand across installed bases.
- Quantum computing substrate requirements:Superconducting qubit fabrication demands defect-free III-V heterostructures that only advanced molecular beam epitaxy can deliver, pulling specialized electron sources and substrate heaters into volume production.
- GaN-on-SiC RF device proliferation:Defense and telecommunications applications for high-electron-mobility transistors are expanding compound semiconductor foundry capacity in Taiwan and the United States.
Market Restraints
- Tantalum and tungsten supply concentration:Specialty refractory metals for effusion cell crucibles and heater filaments concentrate in Chinese and Russian mining operations, exposing component manufacturers to price volatility and export restriction risk.
- Technical limitation in throughput scaling:MBE's layer-by-layer deposition rate remains orders of magnitude slower than metal-organic chemical vapor deposition, constraining adoption beyond niche high-performance applications.
- REACH substance restrictions:European regulations on hazardous materials in vacuum chamber coatings and cell construction are forcing reformulation of established component designs, extending qualification timelines.
Strategic Opportunities
- Space-qualified component certification:Satellite constellation operators in the United States are specifying radiation-hardened MBE-grown solar cells and sensors, opening premium pricing tiers for vacuum chambers meeting MIL-STD-1540.
- Modular source retrofit kits:Fabs are extending legacy system lifespans through upgradeable effusion cell and electron source modules rather than full chamber replacement, creating recurring aftermarket revenue streams.
- Photonic integrated circuit convergence:Silicon photonics foundries are adopting III-V integration via selective area MBE, bridging compound semiconductor performance with silicon manufacturing scale.
Industry Challenges
- Cryogenic engineering talent scarcity:Design of sub-10^-10 torr vacuum systems requires specialized expertise in thermal management and materials science that outpaces university pipeline output.
- ISO 9001 and ISO 14001 certification burden:Tier-one semiconductor manufacturers mandate dual certification for vendor qualification, imposing documentation and audit costs that disadvantage smaller component suppliers.
- Legacy system integration complexity:New effusion cell architectures must interface with 15-20 year old chamber designs prevalent in research institutions, constraining innovation in source geometry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | MBE Components Market |
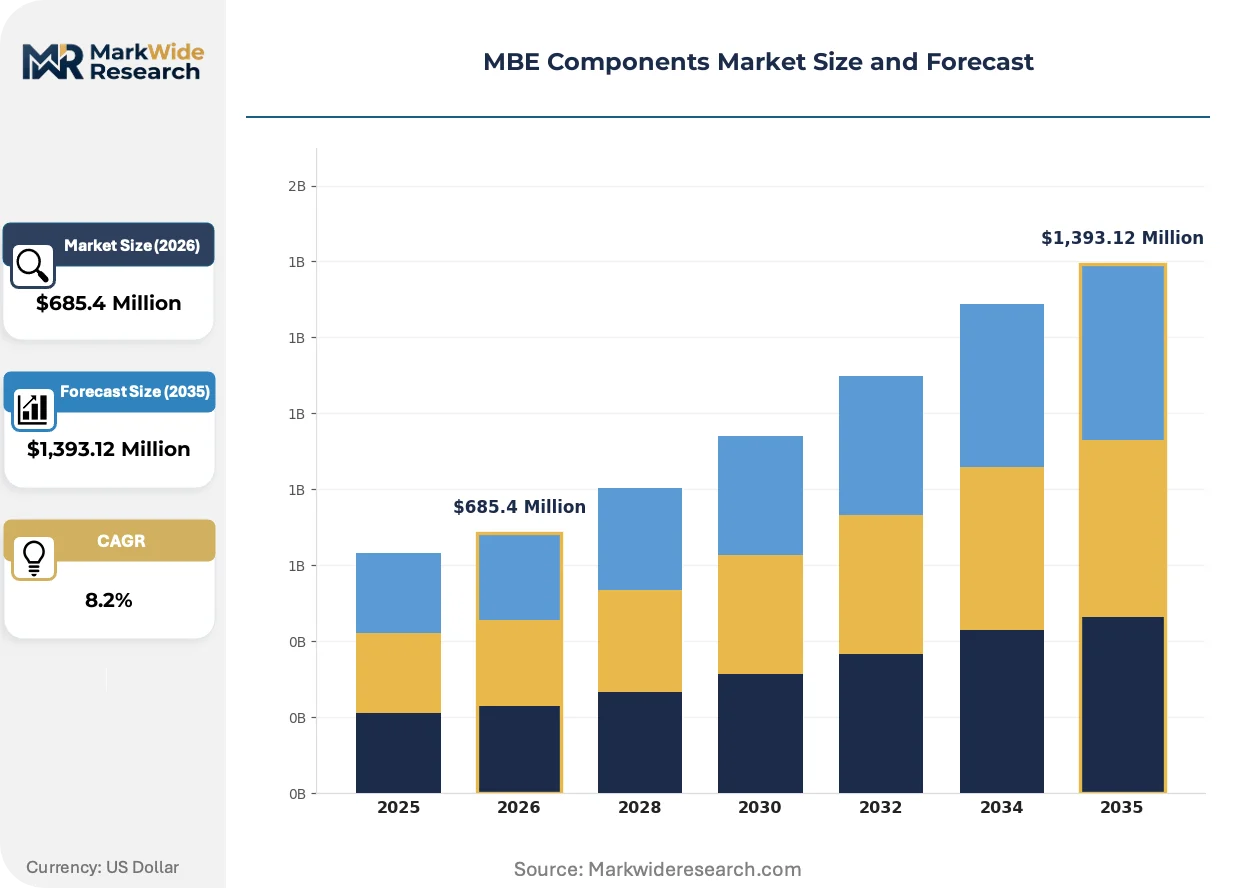
| Market Size in 2026 | $685.4 Million |
| Market Size in 2035 | $1,393.12 Million |
| CAGR (2026 – 2036) | 8.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electron Sources, Substrates, Thin Films, Ion Guns, Vacuum Chambers, Masks Technology: Molecular Beam Epitaxy, Metalorganic Chemical Vapor Deposition, Atomic Layer Deposition, Pulsed Laser Deposition, Molecular Beam Scattering, Epitaxial Growth Application: Semiconductor Fabrication, Optoelectronics, Quantum Computing, Photovoltaics, Sensors, Space Electronics End User: Semiconductor Manufacturers, Research Institutes, Defense Contractors, Consumer Electronics Makers, Nanotechnology Firms |
| Companies Covered | Veeco, Riber, Scienta Omicron, DCA Instruments, Dr. Eberl MBE-Komponenten, Pascal, SVT Associates, CreaTec Fischer & Co., Prevac, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
MBE Components Market Trends and Innovations
Atomic-scale process control is migrating from laboratory curiosity to production imperative as compound semiconductor applications multiply. Equipment architectures are fragmenting between maximum purity configurations for quantum devices and throughput-optimized designs for photonics.
Cluster tool integration is unifying deposition, metrology, and annealing functions within single vacuum envelopes. Leading-edge foundries in Taiwan are adopting these unified platforms to reduce atmospheric contamination between process steps. This consolidation is compressing the market for standalone measurement instruments while expanding demand for integrated sensor modules.
REACH compliance deadlines in Europe are accelerating material substitution in effusion cell construction. Ceramic crucible coatings and alternative heater alloys are displacing legacy formulations containing restricted substances. German and French research fabs are prioritizing suppliers with pre-qualified green material portfolios, creating first-mover advantages for compliant component vendors.
Buying patterns are consolidating around turnkey source replacement programs rather than individual component procurement. Foundry maintenance teams in South Korea are outsourcing effusion cell refurbishment and electron source regeneration to original equipment manufacturers. This service bundling is concentrating aftermarket revenue with integrated suppliers possessing regional technical support infrastructure.
MBE Components Market Segmentation
Component selection in molecular beam epitaxy systems follows distinct procurement logics across product categories, deposition technologies, and end-use applications. Understanding these segmentation boundaries reveals where specification requirements diverge and where standardization pressures converge.
Product Type:
Buyer budgets concentrate on consumable subsystems requiring frequent replacement versus capital-intensive chamber infrastructure.
- Electron Sources:Thermionic and field-emission filaments generate the molecular beams for atomic-layer deposition precision. Taiwan-based foundries are expanding orders for high-stability sources as they scale GaN-on-SiC production for 5G base stations.
- Substrates:Silicon, sapphire, and SiC wafers provide the crystalline foundation for epitaxial growth with surface roughness below 0.1 nm. Demand clusters in South Korea where Samsung and SK Hynix are qualifying next-generation memory substrates.
- Thin Films:Pre-deposited template layers accelerate process development cycles in research settings. German and French university consortia are the primary volume purchasers for III-V material stacks.
- Ion Guns:Low-energy sources enable substrate cleaning and assisted deposition modes. Space electronics manufacturers in the United States are specifying radiation-hardened variants for satellite solar cell fabrication.
- Vacuum Chambers:Stainless steel and aluminum alloy vessels maintain base pressures below 10^-10 torr. Japanese METI-directed semiconductor investments are pulling orders for cluster-compatible chamber architectures.
- Masks:Shadow masks define selective growth patterns for photonic integrated circuits. European photonics foundries are driving incremental demand for sub-micron feature resolution.
Volume sits with electron sources and substrates given their consumable nature; growth tilts toward vacuum chambers as cluster tool adoption accelerates.
Technology:
Process selection hinges on the tension between atomic-scale precision and wafer-per-hour throughput economics.
- Molecular Beam Epitaxy:Ultra-high vacuum deposition achieves monolayer control through Knudsen cell evaporation. Quantum computing startups in the United States are pulling specialized MBE systems for superconducting qubit heterostructure fabrication.
- Metalorganic Chemical Vapor Deposition:Precursor gas delivery enables higher deposition rates for LED and power device manufacturing. Taiwanese compound semiconductor foundries dominate equipment procurement for GaN RF applications.
- Atomic Layer Deposition:Self-limiting surface reactions deposit conformal films on complex topographies. South Korean memory manufacturers are integrating ALD for high-k gate dielectric stacks.
- Pulsed Laser Deposition:Ablation targets enable stoichiometric transfer of complex oxide materials. Research institutes in Germany and Japan are the primary installed base for correlated electron system studies.
- Molecular Beam Scattering:Surface science techniques characterize growth kinetics without film deposition. Academic tool purchases in France and the United Kingdom sustain this niche segment.
- Epitaxial Growth:Generic category captures hybrid and emerging deposition modalities. Chinese semiconductor investments are expanding share for domestic equipment variants.
Metalorganic chemical vapor deposition commands the largest installed base; molecular beam epitaxy carries the steepest expansion trajectory as quantum applications mature.
Application:
End-use requirements fragment between commodity-scale semiconductor manufacturing and precision-constrained emerging technologies.
- Semiconductor Fabrication:Logic and memory foundries employ MBE for specialized channel materials and interface engineering. Taiwan and South Korea account for the dominant share of production-scale tool deployment.
- Optoelectronics:Laser diodes and photodetectors demand precise III-V heterostructure control. United States defense contractors are specifying MBE-grown components for directed energy systems.
- Quantum Computing:Superconducting and semiconductor qubits require defect-free interfaces at the atomic scale. IBM and Google supplier ecosystems in New York and California are qualifying dedicated MBE lines.
- Photovoltaics:Multi-junction solar cells for space applications use lattice-matched III-V layers. Satellite constellation operators in the United States are expanding radiation-hardened cell procurement.
- Sensors:Infrared focal plane arrays and MEMS devices leverage MBE for active material deposition. German automotive suppliers are evaluating MBE-grown infrared detectors for autonomous driving systems.
- Space Electronics:Radiation tolerance and thermal cycling resistance mandate specialized growth protocols. NASA and ESA qualification programs in the United States and France drive premium component specifications.
Semiconductor fabrication absorbs the greatest component volume; quantum computing applications are climbing the fastest as commercial qubit systems approach pilot production.
End User:
Procurement authority separates between integrated device manufacturers with captive epitaxy and outsourced research services.
- Semiconductor Manufacturers:Foundries and IDMs operate internal epitaxy departments or contract with dedicated houses. TSMC and Intel capital expenditure plans in Taiwan and Arizona dictate regional component demand cycles.
- Research Institutes:University and national laboratory facilities prioritize flexibility over throughput for materials discovery. Max Planck and CNRS facilities in Germany and France sustain European source manufacturer order books.
- Defense Contractors:Classified programs mandate domestic supply chains and radiation-hardened specifications. Raytheon and Northrop Grumman supplier networks in the United States require ITAR-compliant component sourcing.
- Consumer Electronics Makers:Apple and Samsung vertical integration strategies are pulling select optical component manufacturing in-house. VCSEL arrays for facial recognition drive MBE requirements for specific device tiers.
- Nanotechnology Firms:Emerging companies commercializing 2D materials and topological insulators represent fragmented demand. Startup clusters in Boston and Shenzhen are qualifying small-batch MBE services.
Semiconductor manufacturers dominate current procurement volumes; defense contractors are gaining share fastest as classified compound semiconductor programs expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Special economic zones in Taiwan and South Korea concentrate MBE component demand through tax incentives for semiconductor fabrication. Foundry clusters in Hsinchu and Yongin anchor procurement volumes for effusion cells and electron sources. Government-backed semiconductor initiatives in Germany, Japan, and the United States are reshaping regional supply patterns.
Taiwan
TSMC's advanced node expansion in Hsinchu Science Park drives effusion cell replacement cycles at unprecedented scale. The National Development Council's chip industry subsidies under the Taiwan Chip Implementation Act direct capital toward molecular beam epitaxy infrastructure. Southern Taiwan Science Park in Tainan hosts emerging compound semiconductor foundries qualifying new substrate heater specifications.
South Korea
Samsung Foundry and SK Hynix are scaling GaN-on-SiC capacity for 5G RF applications, pulling specialized electron sources into volume production. METI-coordinated investments through the K-Semiconductor Belt program channel procurement toward domestic MBE component vendors. Yongin's semiconductor cluster represents the densest concentration of installed MBE systems outside Taiwan.
United States
Intel's Arizona and Ohio fab investments are qualifying new effusion cell architectures for sub-3nm production. EPA vacuum purity mandates under the Clean Air Act compel upgrades across legacy equipment bases in California and Texas. IBM and Google supplier ecosystems in New York and California are commissioning dedicated MBE lines for superconducting qubit fabrication.
Germany
Fraunhofer and Max Planck institutes sustain European demand for research-grade MBE components through federal excellence initiatives. REACH substance restrictions from ECHA are forcing reformulation of effusion cell crucible coatings, extending qualification timelines. Dresden's Silicon Saxony cluster anchors production-scale procurement for automotive sensor applications.
Japan
Tokyo Electron and Shin-Etsu Chemical are expanding internal MBE capacity for power device epitaxy under METI's semiconductor strategy. JIS standards for ultra-high vacuum equipment shape component specifications for domestic and export markets. Tsukuba's research corridor hosts national laboratory facilities driving next-generation source development.
MBE Components Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the MBE components landscape. The vendor base organizes into three tiers: integrated equipment manufacturers with full-system portfolios, specialized source suppliers with deep effusion cell expertise, and regional fabricators serving research institutions. Consolidation pressures favor players with captive vacuum technology and aftermarket service infrastructure. Strategic moves center on modular source retrofit programs and cluster tool integration partnerships.
Among integrated equipment manufacturers, Veeco Instruments and Riber exemplify divergent geographic anchoring strategies. Veeco occupies a position within the North American compound semiconductor supply chain, while Riber represents European specialization in III-V growth systems. Scienta Omicron sits within the ultra-high vacuum instrumentation tier, anchoring Scandinavian precision engineering capabilities. These three entities collectively illustrate how technology leadership fragments across regional innovation ecosystems rather than concentrating under single corporate umbrellas.
| Leading Market Players |
|---|
| Veeco |
| Riber |
| Scienta Omicron |
| DCA Instruments |
| Dr. Eberl MBE-Komponenten |
| Pascal |
| SVT Associates |
| CreaTec Fischer & Co. |
| Prevac |
| Others |
Pricing and Supply Chain Analysis
EPA vacuum purity mandates gate qualified supply for effusion cells and cryopanels, restricting premium-tier pricing access to vendors with certified low-emission architectures. Foundries in Taiwan and South Korea now demand ISO 14001-compliant documentation as a baseline for procurement, compressing margins for uncertified suppliers while enabling price premiums for green-qualified component manufacturers.
Pricing Analysis
Margin tightening in standard-grade effusion cells reflects ceramic crucible reformulation costs driven by REACH substance restrictions. Three-tier pricing structure across premium, standard, and economy levels separates MIL-STD-1540 space-qualified chambers from research-grade configurations. Cost-down pressure on electron sources accelerates because foundries are consolidating procurement through turnkey replacement programs. Defense contractors exhibit the lowest price sensitivity given ITAR compliance requirements, while research institutes negotiate aggressively on volume discounts.
Supply Chain Analysis
ISO 9001 certification functions as the primary gating mechanism for vendor qualification at tier-one semiconductor manufacturers. Component manufacturing concentrates in the United States, Germany, and Japan where precision vacuum engineering capabilities cluster. Supply chains draw from tantalum and tungsten mining operations in China and Russia for heater filaments and crucible materials. Single-source vulnerability in specialty refractory metals exposes manufacturers to export restriction risk. Distribution runs through original equipment manufacturer service networks with regional technical support infrastructure.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
MBE component supply is consolidating around integrated suppliers with captive vacuum technology and aftermarket service infrastructure. REACH compliance deadlines and EPA vacuum purity mandates are forcing smaller component vendors to exit or seek acquisition.
For Market Incumbents: Anchor technology leadership through cluster tool integration partnerships with Taiwanese foundries scaling GaN-on-SiC production. Defend against modular source retrofit competitors by capturing aftermarket revenue through regional refurbishment facilities in South Korea and Arizona. Prioritize ceramic crucible coating reformulation to preempt REACH qualification timeline extensions. For New Entrants and Emerging Players: Research institutes operating 15-20 year old chamber designs represent an underserved buyer archetype with legacy system integration requirements. Photonic integrated circuit foundries in Europe offer the most penetrable segment for selective area MBE source modules. Pursue go-to-market positioning through university consortium procurement channels in Germany and France. For Investors and Strategic Acquirers: IBM and Google commissioning dedicated MBE lines for superconducting qubit fabrication is the leading indicator that quantum computing substrate requirements will drive specialized electron source demand. Position acquisition targets around pure-play source suppliers with pre-qualified green material portfolios. Monitor METI-directed procurement patterns for inflection signals on domestic Japanese vendor preference.| Strategic Initiative | Industry Significance |
|---|---|
| Cluster Tool Integration Partnership | Taiwanese foundries adopt unified deposition-metrology-annealing platforms to reduce atmospheric contamination. |
| Green Material Portfolio Pre-qualification | German and French research fabs prioritize REACH-compliant ceramic crucible coatings for first-mover advantage. |
| Regional Refurbishment Facility Expansion | South Korean foundry maintenance teams outsource effusion cell regeneration to OEM technical support networks. |
| Space-qualified Component Certification | Satellite constellation operators specify MIL-STD-1540 vacuum chambers for radiation-hardened solar cells. |
| Modular Source Retrofit Program Launch | Legacy system lifespan extension creates recurring aftermarket revenue streams beyond full chamber replacement. |
Research Methodology
Independent corroboration across semiconductor fabrication executives, vacuum equipment procurement managers, and compound semiconductor R&D directors underwrites the qualitative findings. Primary fieldwork combined with secondary validation from EPA emissions filings, METI semiconductor strategy documents, and ISO certification registries anchors supply-side assessments. SEC 10-K disclosures from integrated equipment manufacturers and customs data on refractory metal imports support demand quantification. Bottom-up component shipment analysis triangulates against top-down foundry capital expenditure tracking.
Historical reference periods spanning equipment replacement cycles and regulatory compliance deadlines anchor the projection horizon. The analytical framework segments by product type, technology modality, end-use application, and geographic production cluster. CAGRs derive from fitted growth curves calibrated to compound semiconductor foundry capacity announcements and quantum computing pilot production timelines. Forecast inputs incorporate tantalum price volatility indices and cluster tool adoption rates from Taiwanese tool integration partnerships.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to export control reclassifications for epitaxial growth equipment and Chinese refractory metal supply disruptions. Model assumptions reflect EPA enforcement intensity and METI procurement direction. A model refresh is warranted upon material change in REACH substance restriction scope or superconducting qubit fabrication yield thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Semiconductor Devices
Global Automotive Mosfets Market
Semiconductor Devices
Global Small Signal Diode Market
Semiconductor Devices
Temperature-Controlled Semiconductor Market
Semiconductor Devices
Multi-Junction Solar Cell Market
Semiconductor Devices
Japan Power Transistor Market
Semiconductor Devices
High Speed Data Converters Market
Semiconductor Devices
Reachers Market
Semiconductor Devices
North America Ultra-Low-Power Microcontroller Market
Semiconductor Devices
TC-SAW Filter Market
Semiconductor Devices
Global Cryptocurrency Mining Hardware Market
Semiconductor Devices
Asia-Pacific Silicon Carbide Wafers Market
Semiconductor Devices
Field Effect Transistor Market
Semiconductor Devices
SLD Market
Semiconductor Devices
Home Appliance MCU Market
Semiconductor Devices
Large-Size PV Silicon Wafer Market
Semiconductor Devices
Field Effect General Purpose Transistors Market