
 Laser Transmitter Market | 2026-2036
Laser Transmitter Market Size, Share, and Industry Trends Forecast 2026-2036
Laser Transmitter Market Foresight
Defense and telecommunications is restructuring demand composition across the laser transmitter landscape. Lumentum Operations LLC leverages its optical communications heritage to anchor supply relationships with major fiber network operators. IPG Photonics Corporation sustains manufacturing scale in high-power fiber laser systems for industrial cutting and welding. Focuslight Technologies Inc. specializes in diode laser components, positioning itself at the upstream end of transmitter assembly chains.
A laser transmitter converts electrical energy into coherent light through stimulated emission, typically achieving output powers from milliwatts to multi-kilowatt depending on gain medium and pump architecture, for downstream use in optical data links, precision machining, or target designation. Fiber lasers now dominate industrial material processing due to superior wall-plug efficiency and beam quality, while quantum cascade technology captures emerging share in infrared sensing and spectroscopy where wavelength tunability proves critical. Semiconductor-based diode lasers concentrate volume in telecommunications data transmission, though margin pools remain thinner than in specialized solid-state systems for medical procedures.
FDA device classifications and ISO 13485 quality mandates shape healthcare laser transmitter entry pathways in the United States, while CE marking under the EU MDR and REACH substance restrictions govern European market access for surgical and industrial equipment. China's NMPA and GB standards enforce separate testing protocols for imported medical laser systems, fragmenting compliance burdens across jurisdictions. Stakeholders must monitor divergence between regional wavelength exposure limits and emerging export control classifications for high-power military-grade transmitters.
Market Dynamics
Defense procurement programs in the United States and allied nations are accelerating laser transmitter deployment for rangefinding and directed-energy weapons, while China's MIIT standards tighten industrial performance benchmarks and reshape supplier qualification pathways.
Growth Catalysts
- Directed-energy weapons programs:Pentagon procurement for high-power fiber laser systems in counter-drone and missile defense applications is pulling volume through specialized defense contractors. These programs mandate multi-kilowatt output with beam quality specifications that filter supplier pools.
- REACH substance restrictions:European RoHS and REACH compliance deadlines are forcing replacement of legacy gain media with rare-earth-doped fiber architectures, indirectly benefiting transmitter manufacturers with cleaner material stacks.
- Semiconductor fabrication clusters:East Asian precision electronics manufacturing in Japan and South Korea is consuming ultraviolet and deep-ultraviolet laser transmitters for lithography and wafer inspection at rates outpacing other industrial verticals.
Market Restraints
- Rare-earth supply concentration:Neodymium and ytterbium feedstock processing concentrates in Chinese refining facilities, exposing fiber laser manufacturers to export quota volatility and price swings in pump diode components.
- Technical wavelength limitations:Quantum cascade lasers face thermal management constraints that cap continuous-wave output power below levels required for industrial material processing, restricting them to sensing and spectroscopy niches.
- FDA device classification friction:510(k) clearance pathways for surgical laser transmitters impose 18-24 month timelines that deter mid-scale entrants from healthcare verticals, consolidating share among established device manufacturers.
Strategic Opportunities
- LiDAR automotive penetration:Autonomous vehicle programs in Germany and California are qualifying 1550-nanometer fiber laser transmitters for long-range object detection, opening volume contracts previously dominated by mechanical scanning systems.
- EU Green Deal industrial retrofit:Carbon reduction mandates for European metal fabrication are subsidizing fiber laser adoption over CO2 systems, creating replacement demand cycles for transmitter suppliers with efficient wall-plug architectures.
- Quantum key distribution infrastructure:National quantum communication networks in China and Switzerland are deploying specialized single-photon laser sources, establishing new specification categories outside traditional telecom standards.
Industry Challenges
- Specialized optical engineering talent:Design of stable resonator cavities and thermal lensing compensation requires expertise concentrated in German and Japanese research institutions, constraining workforce scalability for new market entrants.
- Cleanroom certification timelines:ISO 14644 Class 7 compliance for semiconductor-grade transmitter assembly extends facility commissioning by 8-14 months, delaying revenue recognition for capacity expansion projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Laser Transmitter Market |
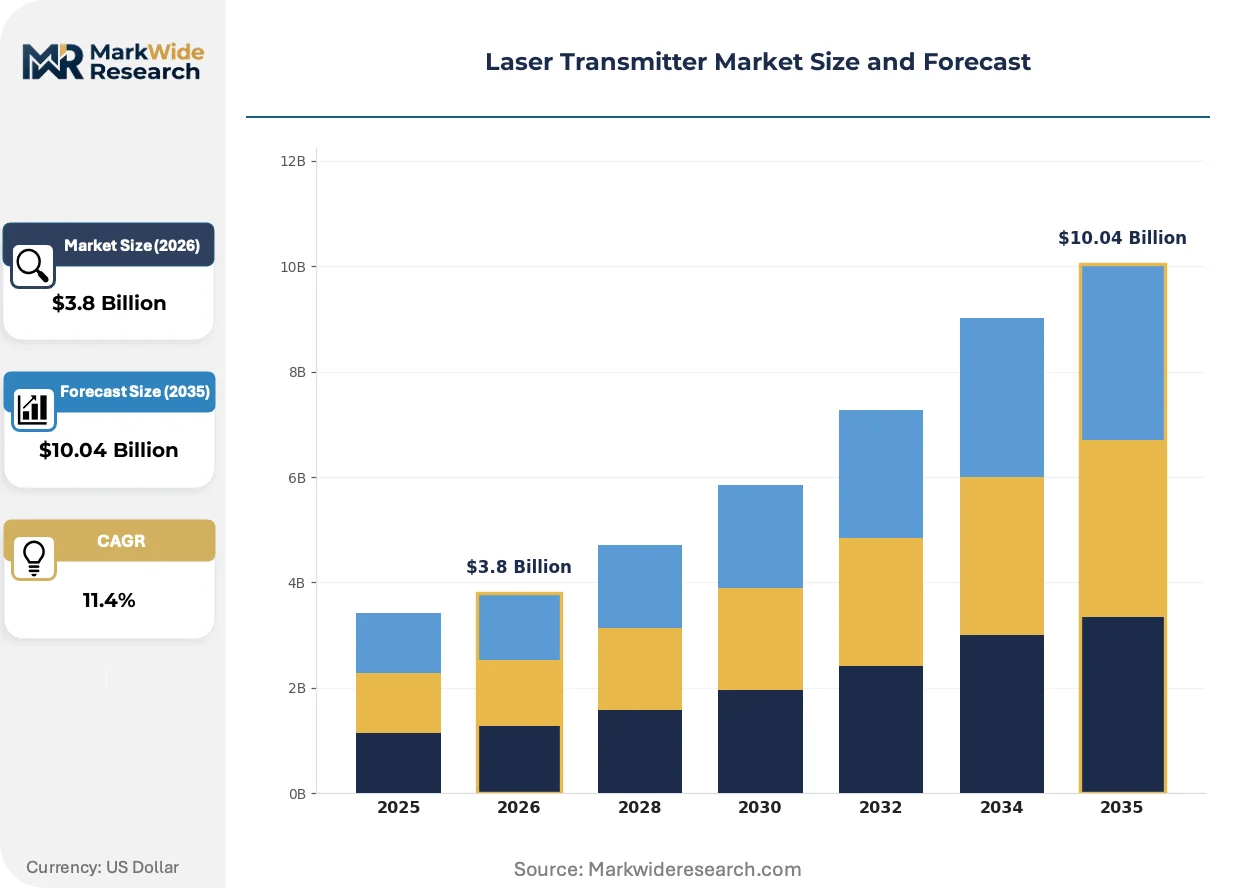
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fiber Lasers, Diode Lasers, Solid-State Lasers, Gas Lasers Technology: Optical Fiber Technology, Semiconductor Technology, Plasma Technology, Quantum Cascade Technology End User: Telecommunications, Industrial Manufacturing, Healthcare, Defense Application: Data Transmission, Material Processing, Medical Procedures, Sensing |
| Companies Covered | RPMC Lasers, ABB Ltd, Hawk Measurement Systems, Easy-Laser AB, Focuslight Technologies Inc., Robert Bosch GmbH, Honeywell Process Solutions, Lumentum Operations LLC, IPG Photonics Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Laser Transmitter Market Shifts & Advancements
Beam combining architectures and wavelength stabilization protocols are compressing the performance gap between single-emitter and consolidated multi-kilowatt systems, reshaping competitive positioning across industrial and defense applications.
Coherent beam combining of fiber laser arrays is integrating phase-locking electronics with distributed gain modules to scale output without thermal damage thresholds that constrain monolithic designs. Automotive LiDAR manufacturers in Germany and California are adopting these architectures for 1550-nanometer long-range sensors. The approach is integrating photonic integrated circuits that reduce form factors and assembly labor content.
China's MIIT standards for industrial laser equipment are mandating real-time power monitoring and interlock redundancy that exceed IEC 60825-1 baselines. Domestic manufacturers must recertify existing product lines by 2026, creating compliance-driven replacement cycles. Foreign suppliers face parallel GB standard testing protocols that fragment technical documentation requirements.
Defense procurement offices are compressing supplier qualification cycles from 36 months to 18 months for directed-energy subsystems, pressuring transmitter manufacturers to front-load reliability testing. This pattern concentrates contract awards among vendors with captive environmental stress screening facilities. The shift is most visible in Pentagon programs where fielding velocity now outweighs unit cost optimization in source selection criteria.
Laser Transmitter Market Segmentation
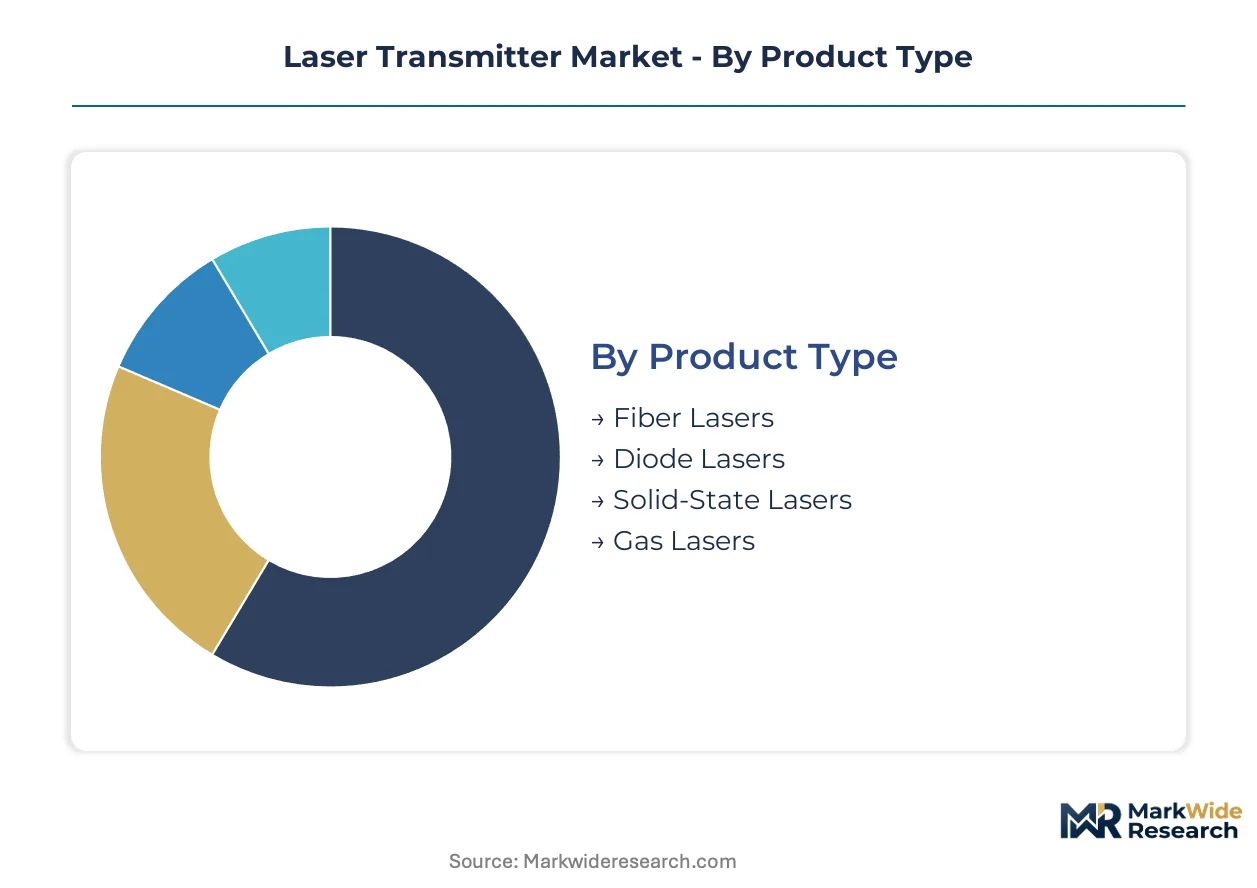
Laser transmitter architectures diverge sharply across power thresholds, wavelength precision, and thermal management requirements. Understanding these divisions reveals where margin pools concentrate versus where volume commoditization erodes returns.
Product Type:
Fiber lasers dominate high-value industrial contracts while diode lasers capture telecommunications volume at thinner margins.
- Fiber Lasers:Rare-earth-doped silica gain fibers pumped by semiconductor diodes achieve wall-plug efficiencies exceeding 30% with near-diffraction-limited beam quality. Demand concentrates in German automotive sheet-metal fabrication and Pentagon-directed energy programs where multi-kilowatt output justifies premium pricing.
- Diode Lasers:Direct electrical-to-optical conversion through III-V semiconductor junctions enables compact form factors at the cost of beam quality. East Asian fiber-optic network deployments in Japan and South Korea consume billions of units annually for 1310-nanometer and 1550-nanometer data transmission.
- Solid-State Lasers:Crystalline or glass hosts doped with neodymium or ytterbium deliver nanosecond pulse widths for medical dermatology and ophthalmology procedures.
- Gas Lasers:CO2 discharge tubes remain entrenched in legacy cutting applications despite fiber laser displacement, sustained by installed base maintenance revenue.
Today's leader: Fiber Lasers. Tomorrow's challenger: Diode Lasers.
Technology:
Semiconductor fabrication maturity separates deployable-at-scale architectures from laboratory-bound innovations.
- Optical Fiber Technology:Double-clad fiber geometries with inner core diameters of 10-50 micrometers confine signal propagation while outer pump cladding enables efficient energy transfer. Industrial metal processing in Japan's precision manufacturing clusters and Swiss watchmaking component fabrication represent concentrated demand.
- Semiconductor Technology:Epitaxial growth of aluminum gallium arsenide or indium phosphide heterostructures on gallium arsenide substrates yields edge-emitting or vertical-cavity surface-emitting geometries. Chinese 5G base station deployments and Indian fiber-to-the-home infrastructure expansion drive procurement volume.
- Plasma Technology:Gas discharge excitation of argon or krypton produces visible wavelengths for scientific instrumentation and entertainment projection systems.
- Quantum Cascade Technology:Intersubband transitions in semiconductor superlattices enable mid-infrared emission tunable across 3-25 micrometers for chemical sensing and spectroscopy.
Semiconductor Technology anchors present revenue. Optical Fiber Technology climbs the fastest.
End User:
Defense procurement cycles and healthcare reimbursement pathways create divergent customer economics.
- Telecommunications:Carrier-grade optical transport networks require transmitter reliability exceeding 25-year lifespans with mean-time-between-failures above 500,000 hours. Submarine cable landing stations in Portugal and terrestrial long-haul routes across Australia impose stringent qualification protocols.
- Industrial Manufacturing:Automotive OEMs in Michigan and Bavaria specify fiber laser cutting systems with automated nozzle changing and real-time pierce detection for high-mix, low-volume production.
- Healthcare:FDA 510(k) and EU MDR compliance timelines filter supplier participation in surgical laser markets.
- Defense:Pentagon counter-UAS programs and Israeli border security systems mandate ruggedized packaging with shock and vibration tolerance per MIL-STD-810.
Industrial Manufacturing commands the largest addressable spend. Defense exhibits the steepest expansion trajectory.
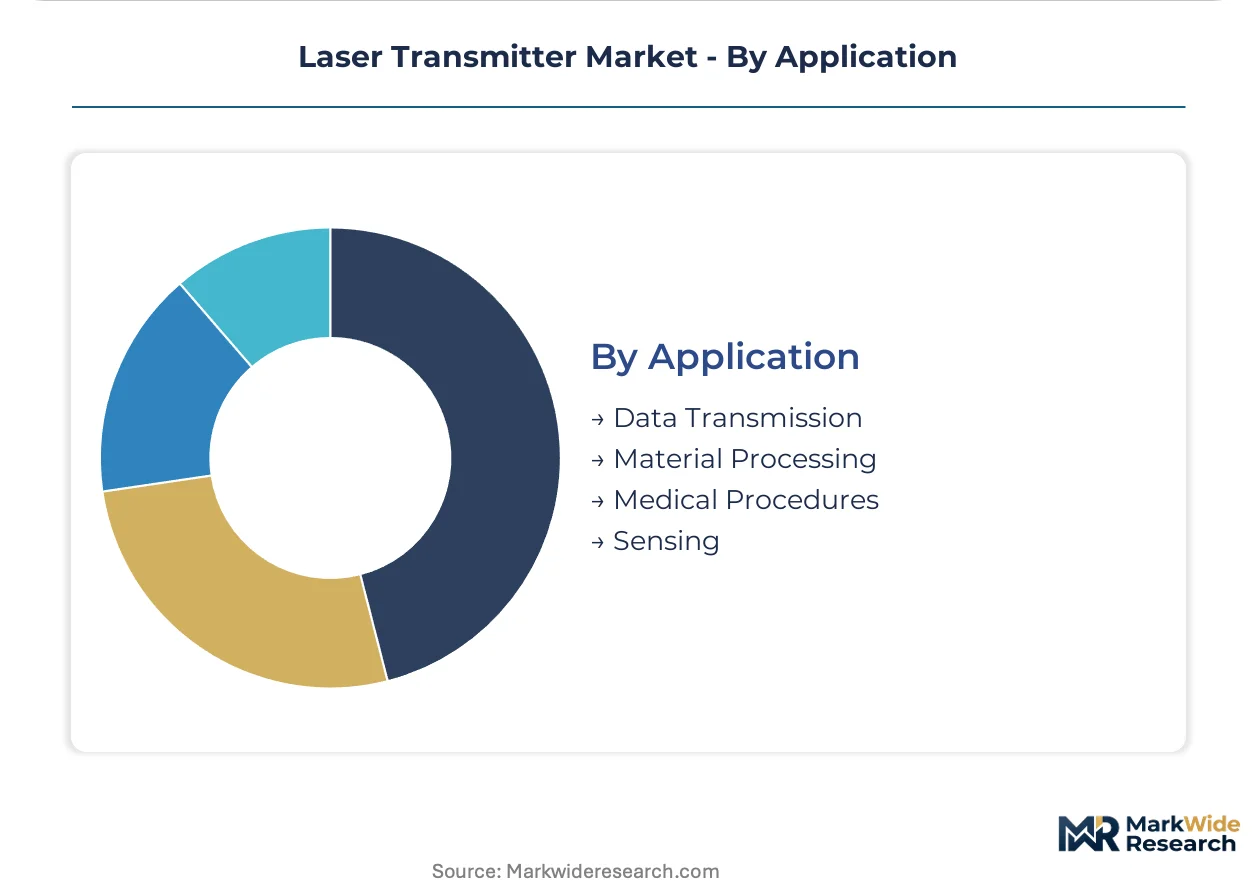
Application:
Distance-to-target requirements and material interaction physics dictate wavelength and power specification.
- Data Transmission:On-off keying and coherent modulation formats at 100 Gbps and 400 Gbps line rates demand linewidth stability below 100 kilohertz and side-mode suppression exceeding 40 decibels. Cloud hyperscaler data center interconnects in Virginia and Dublin specify these parameters for 80-kilometer unrepeated links.
- Material Processing:Reflective metal cutting of copper and aluminum requires 1-micrometer wavelength absorption characteristics that fiber lasers provide, displacing CO2 systems in Korean shipbuilding and Italian appliance manufacturing.
- Medical Procedures:Selective photothermolysis of vascular lesions or retinal tissue demands pulse duration control within millisecond precision.
- Sensing:Differential absorption LiDAR for atmospheric methane monitoring and coherent Doppler wind measurement rely on single-frequency seed lasers with frequency stability.
Material Processing generates the highest per-unit pricing. Sensing applications gain share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturers are relocating assembly operations to jurisdictions with streamlined laser equipment certification timelines, exploiting regulatory-arbitrage gaps between FDA 510(k) pathways and China's NMPA fast-track channels. This migration pattern concentrates component sourcing in established East Asian clusters while final integration shifts toward end-market proximity.
United States
Pentagon directed-energy weapons programs and counter-UAS procurement are consuming multi-kilowatt fiber laser transmitters at volumes unmatched by civilian applications. FDA device classifications impose 18-24 month clearance timelines for surgical laser systems, filtering supplier participation in healthcare verticals. Defense contractors in Arizona and Texas are expanding environmental stress screening facilities to meet compressed 18-month qualification cycles.
Germany
Automotive OEMs in Bavaria specify fiber laser cutting systems with automated nozzle changing for high-mix production, while Fraunhofer research institutes anchor photonics engineering talent. EU Green Deal carbon reduction mandates subsidize fiber laser adoption over CO2 systems in metal fabrication. Stuttgart and Munich precision manufacturing clusters consume ultraviolet transmitters for watchmaking component fabrication.
China
MIIT standards mandating real-time power monitoring and interlock redundancy exceed IEC 60825-1 baselines, forcing domestic recertification by 2026. NMPA testing protocols for imported medical laser systems fragment compliance documentation requirements. Yangtze River Delta manufacturing hubs in Shanghai and Suzhou drive volume for industrial material processing equipment.
Japan
Precision electronics manufacturing in Tokyo and Osaka consumes ultraviolet and deep-ultraviolet laser transmitters for lithography and wafer inspection. METI industrial policy supports domestic supply chain resilience for rare-earth-doped fiber architectures. Semiconductor fabrication clusters in Kyushu anchor demand for single-frequency seed lasers with frequency stability specifications.
South Korea
Shipbuilding yards in Ulsan and Busan deploy fiber lasers for reflective metal cutting of copper and aluminum, displacing legacy CO2 systems. MFDS medical device regulations align with international standards but maintain separate testing protocols for surgical equipment. Seoul Capital Area electronics manufacturers qualify 1550-nanometer transmitters for fiber-optic network expansion.
Laser Transmitter Market Competitive Landscape
Capacity expansion dominates the current landscape as manufacturers add cleanroom assembly lines to capture semiconductor-grade transmitter contracts. The vendor base organizes into three tiers: integrated photonics conglomerates with captive fiber-drawing facilities, specialized diode laser component suppliers, and regional system integrators serving maintenance markets. Strategic archetypes include defense-focused ruggedization specialists, telecom-hardened reliability players, and industrial power-scaling engineers. Vertical integration into rare-earth fiber production and geographic proximity to East Asian manufacturing clusters represent the dominant competitive moves.
Within the integrated photonics tier, Lumentum Operations LLC and IPG Photonics Corporation exemplify scale-driven positioning through their optical communications heritage and high-power fiber laser manufacturing footprints respectively. Focuslight Technologies Inc. occupies a specialist position at the upstream end of transmitter assembly chains, representing the diode laser component archetype that supplies downstream integrators.
| Leading Market Players |
|---|
| RPMC Lasers |
| ABB Ltd |
| Hawk Measurement Systems |
| Easy-Laser AB |
| Focuslight Technologies Inc. |
| Robert Bosch GmbH |
| Honeywell Process Solutions |
| Lumentum Operations LLC |
| IPG Photonics Corporation |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up defense contractors concentrate ownership of high-power fiber laser assembly capacity, tightening pricing discipline through captive environmental stress screening and multi-year Pentagon offtake agreements that insulate tier-one suppliers from spot-market volatility in rare-earth feedstock.
Pricing Analysis
Distributor margins of 15-25% separate OEM direct pricing from end-user acquisition costs in industrial laser systems, with contract-based long-term offtake dominating defense procurement while per-unit transactional sales persist in telecommunications diode markets. Price differentiation rests on FDA 510(k) certification tier and volume scale, with surgical laser transmitters commanding premiums over uncertified industrial units. Pricing pressure stems from Chinese export quota volatility in ytterbium-doped fiber preforms, compressing margins for non-integrated manufacturers. Defense contractors exhibit least price sensitivity due to fielding velocity priorities, while Asian fiber-optic network operators drive hardest bargain on 1310-nanometer diode volume.
Supply Chain Analysis
Workforce scarcity in German precision optics engineering and Japanese resonator cavity design constrains capacity expansion for semiconductor-grade transmitter assembly, forcing reliance on established clusters. Manufacturing concentrates in China, Germany, and Japan, with rare-earth refining anchored in Chinese facilities and precision polishing equipment sourced from German suppliers. The chain draws from neodymium and ytterbium feedstock, gallium arsenide substrates, and specialized optical coatings. Single-source vulnerability in Chinese rare-earth processing exposes fiber laser manufacturers to export restriction risk. Distribution runs through defense prime contractors, industrial system integrators, and telecom equipment OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where China's MIIT 2026 recertification mandate and Pentagon's compressed 18-month qualification cycles simultaneously expand replacement demand and consolidate supplier pools.
For Market Incumbents: Deepen backward integration into rare-earth fiber drawing to secure ytterbium-doped preform supply against Chinese export quota volatility. Expand captive environmental stress screening facilities in Arizona and Texas to capture Pentagon directed-energy contracts where fielding velocity now outweighs unit cost in source selection. Defend position by accelerating ISO 14644 Class 7 cleanroom certification timelines that delay new entrant revenue recognition.
For New Entrants and Emerging Players: The mid-tier pricing gap between IPG Photonics' premium fiber laser systems and commodity Chinese industrial units offers white-space entry through 1550-nanometer automotive LiDAR qualification in Germany and California. Target quantum key distribution infrastructure in Switzerland and China where specification categories sit outside traditional telecom standards. Pursue foundry partnerships with Fraunhofer institutes to access resonator cavity engineering talent concentrated in German research institutions.
For Investors and Strategic Acquirers: Valuations sit cheapest among diode laser component specialists supplying upstream transmitter assembly chains, particularly those with indium phosphide epitaxial growth capabilities. Long-term viability favors vendors with dual-use defense-civilian revenue streams that smooth procurement cycle volatility. Watch Pentagon program acceleration as inflection signal—counter-UAS and directed-energy weapons procurement velocity indicates demand durability across the analysis window.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare-Earth Fiber Production | Captive ytterbium-doped preform supply insulates against Chinese export quota volatility. |
| Environmental Stress Screening Facility Expansion | Arizona and Texas locations capture Pentagon compressed 18-month qualification cycles. |
| Automotive LiDAR Transmitter Qualification | 1550-nanometer fiber laser certification with German OEMs opens volume replacement contracts. |
| Quantum Key Distribution Source Development | Single-photon laser specifications for Swiss and Chinese national networks establish new category. |
| ISO 14644 Class 7 Cleanroom Certification | Semiconductor-grade assembly compliance extends lead time advantage over new entrants. |
Research Methodology
Direct dialogue with fiber laser system engineers, defense procurement officers, semiconductor fabrication managers, and telecommunications network planners grounded qualitative assessment, cross-referenced against SEC 10-K filings, Pentagon budget justification documents, MIIT standard drafts, and customs trade data for rare-earth compound imports. Bottom-up unit demand modeling across defense, industrial, and healthcare verticals triangulated with top-down market sizing from equipment manufacturer revenue disclosures.
Segment-level projections across fiber, diode, solid-state, and gas laser architectures incorporated power threshold, wavelength precision, and thermal management requirements throughout the forecast period. CAGRs derived from equipment replacement cycle analysis, defense program acceleration curves, and automotive LiDAR penetration assumptions. Quantum cascade technology adoption in infrared sensing and semiconductor lithography equipment capex trajectories provided industry-specific forecast inputs.
Caveats apply where rare-earth export policy shifts, FDA 510(k) timeline extensions, or quantum communication network deployment delays could materially shift the outlook. Material deviation in these triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optics
AR and VR Lens Market
Optics
Global Optical Lens Market
Optics
Global Semiconductor Lasers Market
Optics
Global Enhanced Vision System Market
Optics
Optical Lens for Mobile Phone Market
Optics
Fiber Optic Cable Market
Optics
Fiber Optic Amplifier Market
Optics
Photonics Sensor Market
Optics
EUV Pellicle Market
Optics
Fiber Optic Development Tools Market
Optics
Optical Liquid Level Sensor Market
Optics
Optical Profilometer Market
Optics
Smart Photochromic Lenses Market
Optics
MEMS Mirrors Market
Optics
Digital Holographic Microscopy Market
Optics
Anti Glare Film Market