
 Erbium Oxide Market | 2026-2036
Erbium Oxide Market Size, Share, and Industry Trends Forecast 2026-2036
Erbium Oxide Market Foresight
Photonic integration is reshaping amplifier architecture across long-haul and submarine cable systems. American Elements leverages vertical integration from rare earth separation to oxide finishing, sustaining supply security for North American photonics OEMs. Stanford Advanced Materials specializes in high-purity granule and pellet formats, competing on lot-to-lot consistency for laser crystal growers.
Erbium oxide is a pinkish rare earth sesquioxide with the chemical formula Er₂O₃, typically synthesized via oxalate precipitation and calcination at temperatures exceeding 800°C to achieve 99.9% purity for photonic applications. The powder segment anchors volume demand from glass and ceramic manufacturers seeking cost-effective colorants, while pellet and soluble compound formats command premium positioning in fiber preform doping where dissolution kinetics and thermal uniformity determine amplifier performance. Optical fiber application leads value capture, with telecommunications end users driving specification tightening around trace impurity thresholds.
China's SAMR enforces GB standards on rare earth oxide purity and export licensing, while REACH in Europe mandates full substance registration for erbium compounds imported above one-tonne thresholds, conditioning market access documentation. The US EPA oversees hazardous waste classification for rare earth processing byproducts under RCRA, influencing domestic refining economics. Stakeholders must monitor evolving dual-use export control classifications for high-purity rare earth materials as photonic systems intersect with defense communication networks.
Market Dynamics
Fiber-optic telecommunications infrastructure expansion is concentrating demand for erbium-doped fiber amplifiers in East Asian manufacturing clusters, while China's MIIT purity standards are tightening material certification requirements across the supply chain.
Growth Catalysts
- MIIT Purity Standards:China's Ministry of Industry and Information Technology mandates stricter rare earth oxide certification, forcing quality upgrades that favor established refiners with analytical capabilities.
- Submarine Cable Deployment:Transoceanic fiber projects require high-purity erbium oxide for ultra-low-loss amplifiers, creating sustained demand from cable system integrators.
- Jiangxi Refining Corridor:Concentrated rare earth processing infrastructure in China's Jiangxi province enables integrated supply chains from separation to oxide finishing.
Market Restraints
- Heavy Rare Earth Concentration:Erbium co-occurs with dysprosium and terbium in ionic clays, tying supply economics to politically sensitive heavy rare earth markets.
- REACH Registration Burden:ECHA mandates full substance documentation for erbium compounds imported above one-tonne thresholds, creating compliance friction for European buyers.
- Calcination Energy Costs:Achieving 99.9% purity requires sustained temperatures exceeding 800°C, exposing producers to volatile natural gas and electricity pricing.
Strategic Opportunities
- Space-Based Laser Communications:Satellite constellations deploying inter-satellite optical links require radiation-hardened erbium-doped amplifiers with specialized thermal specifications.
- Medical Laser Systems:Aesthetic and surgical laser OEMs are qualifying erbium-doped yttrium aluminum garnet crystals for precise tissue ablation applications.
- US IRA Critical Minerals Provisions:Inflation Reduction Act incentives for domestic rare earth processing are attracting capital toward North American separation and oxide finishing capacity.
Industry Challenges
- Analytical Metrology Shortage:ICP-MS operators capable of certifying parts-per-billion trace impurities in rare earth oxides command premium wages, constraining quality lab expansion.
- Lot-to-Lot Consistency:Fiber preform manufacturers reject material exhibiting thermal expansion coefficient variation, forcing suppliers to maintain tighter process control than commodity oxide markets require.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Erbium Oxide Market |
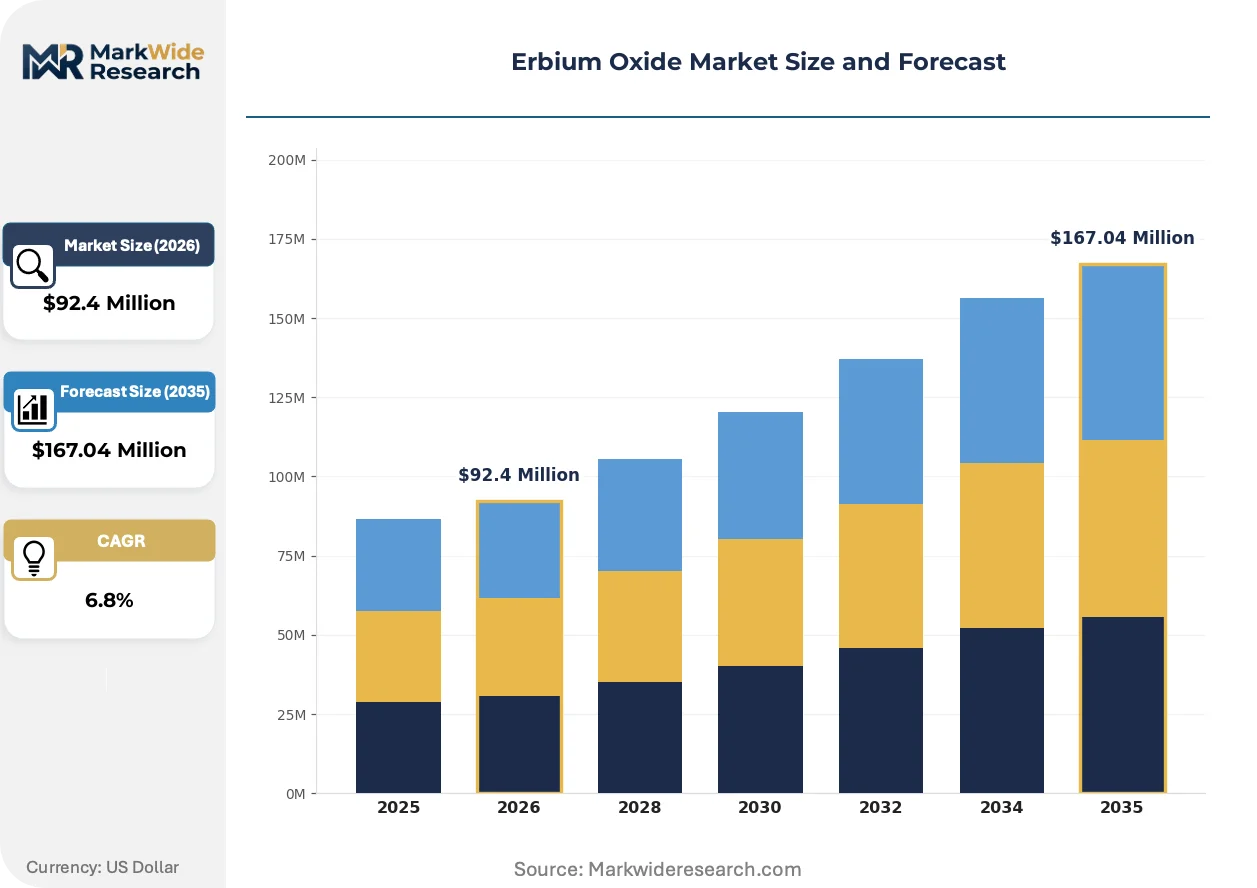
| Market Size in 2026 | $92.4 Million |
| Market Size in 2035 | $167.04 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powder, Granule, Pellet, Soluble Compound Application: Optical Fiber, Glass Coloring, Ceramic Glaze, Catalysts, Metallurgical Additive End User Industry: Telecommunications, Electronics Manufacturing, Chemical Processing, Construction Materials Packaging Type: Drums, Bags, Bottles, Bulk Containers |
| Companies Covered | American Elements, China Minmetals Rare Earth, Stanford Advanced Materials, Treibacher Industrie AG, Alfa Aesar, Ganzhou Qiandong Rare Earth Group, Alkane Resources, ESPI Metals, Chengdu Beyond Chemical, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Erbium Oxide Market Shifts & Advancements
Photonic integration is compressing amplifier form factors while tightening material specifications, with three developments reshaping how erbium oxide flows through the value chain.
Co-packaged optics architectures are collapsing discrete erbium-doped fiber amplifiers into silicon photonic substrates. Cloud hyperscalers deploying 800G transceivers are qualifying these integrated designs for intra-data center interconnects. This consolidation is rendering obsolete the standalone amplifier modules that previously dominated metro fiber deployments.
REACH authorization requirements for erbium compounds are expanding under ECHA's 2024 substance evaluation work program. Downstream users must now document full supply chain provenance from mine to oxide. European photonics OEMs are responding by qualifying dual-source supply arrangements and demanding batch-specific certificates of analysis.
Telecommunications equipment buyers are consolidating vendor relationships around suppliers offering integrated rare earth-to-oxide capabilities. Long-term offtake agreements with fixed pricing tiers are displacing spot market purchases for high-purity material. This preference shift is most visible in North American markets where supply security concerns have intensified following export licensing disruptions.
Erbium Oxide Market Segmentation
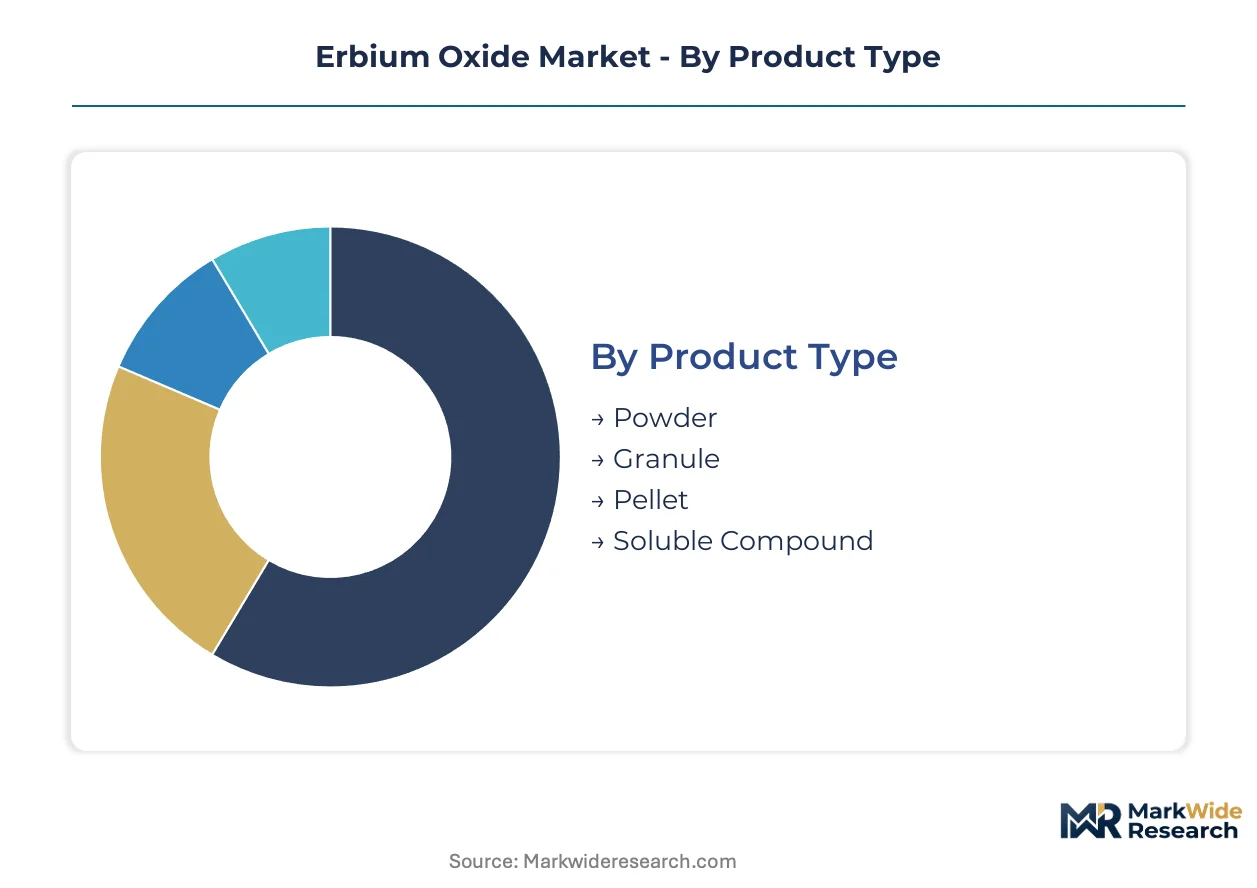
Erbium oxide specifications diverge sharply between commodity colorant applications and precision photonic systems. Material format and purity tier determine which end users can qualify suppliers, creating distinct competitive arenas with limited overlap.
Product Type:
Manufacturers select formats based on dissolution kinetics, thermal processing requirements, and contamination risk tolerance across downstream operations.
- Powder:Fine particulate erbium oxide with typical particle sizes below 10 microns serves glass and ceramic manufacturers seeking homogeneous dispersion in molten matrices. Jiangxi province's rare earth refining corridor channels substantial powder volumes toward construction materials producers who prioritize cost efficiency over ultra-high purity certification.
- Pellet:Pressed and sintered cylindrical forms eliminate dust contamination risks during fiber preform doping operations. Telecommunications equipment manufacturers in East Asian manufacturing clusters specify pellet formats where thermal uniformity during vapor-phase delivery directly determines amplifier gain flatness.
- Granule:Intermediate particle size offers handling convenience for metallurgical additive applications requiring controlled feed rates into molten metals.
- Soluble Compound:Nitrate and chloride derivatives enable aqueous processing routes for catalyst manufacturers and specialized chemical synthesis operations.
Established volume favors Powder; emerging adoption favors Pellet.
Application:
Technical requirements escalate from bulk colorant functions through precision photonic components.
- Optical Fiber:Erbium-doped fiber amplifiers demand 99.9% purity with parts-per-billion trace metal control. Transoceanic cable projects and submarine telecommunications infrastructure in the Pacific Rim consume high-purity material under multi-year supply agreements with fixed pricing tiers.
- Glass Coloring:Pinkish sesquioxide incorporation into decorative and architectural glass relies on lower purity grades where spectral absorption characteristics matter more than trace impurity thresholds.
- Ceramic Glaze:Surface coating applications exploit erbium's distinctive coloration for specialty tableware and artistic pottery production.
- Catalysts:Petrochemical and environmental remediation processes utilize erbium oxide as a promoter or support material in heterogeneous catalysis systems.
- Metallurgical Additive:High-temperature alloy modification employs erbium for grain refinement and oxidation resistance enhancement in aerospace-grade materials.
Value concentration centers on Optical Fiber; volume scale dominates Glass Coloring.
End User Industry:
Procurement sophistication varies from specification-driven OEMs to price-sensitive commodity buyers.
- Telecommunications:Equipment vendors and cable system integrators enforce stringent lot-to-lot consistency requirements with full supply chain provenance documentation. China's MIIT purity standards and REACH substance registration mandates shape supplier qualification protocols.
- Electronics Manufacturing:Laser crystal growers and photonic component fabricators compete for limited high-purity material output with specialized thermal expansion coefficient specifications.
- Chemical Processing:Catalyst producers and fine chemical manufacturers utilize soluble compound formats for process integration.
- Construction Materials:Glass and ceramic manufacturers represent the most price-sensitive demand segment with limited quality differentiation between suppliers.
Specification intensity peaks in Telecommunications; procurement flexibility characterizes Construction Materials.
Packaging Type:
Containment systems align with material reactivity, handling automation, and contamination prevention requirements.
- Drums:Steel or fiber containers protect powder and granule formats during international shipment and extended storage.
- Bags:Multi-layer polymer packaging serves lower-value applications where moisture exclusion remains the primary concern.
- Bottles:Laboratory-scale containment enables analytical reagent distribution and R&D sample provision.
- Bulk Containers:Intermediate bulk containers and tanker systems support integrated rare earth-to-oxide operations with direct pipeline transfer to downstream processing.
Standard logistics favor Drums; integrated supply chains favor Bulk Containers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Telecommunications OEMs and fiber preform manufacturers cluster procurement decisions around three dominant geographies where rare earth refining infrastructure intersects with photonics manufacturing ecosystems.
China
Jiangxi province's rare earth refining corridor processes the majority of global erbium oxide output for fiber amplifier production. MIIT purity standards and SAMR export licensing requirements condition material certification protocols for international buyers. Ganzhou and Xinyu host integrated separation-to-oxide facilities supplying East Asian telecommunications equipment vendors.
United States
Domestic demand concentrates among North American photonics OEMs seeking supply security for submarine cable and data center interconnect applications. EPA RCRA hazardous waste classifications and IRA critical minerals incentives are reshaping refining economics toward domestic oxide finishing capacity. California and Arizona host qualification laboratories for high-purity material acceptance testing.
Germany
European telecommunications infrastructure projects drive specification-grade procurement through REACH-registered supply channels. ECHA substance evaluation requirements and RoHS compliance frameworks enforce full supply chain provenance documentation. The Rhine-Ruhr industrial region maintains analytical metrology capabilities for parts-per-billion impurity certification.
Japan
Specialized laser crystal growers and optical component fabricators source premium-grade material for co-packaged photonic systems. METI industrial standards and JIS certification protocols govern material acceptance for telecommunications equipment exports. The Kansai region around Osaka retains precision ceramics processing expertise for amplifier substrate manufacturing.
South Korea
Domestic display and telecommunications equipment manufacturers are qualifying secondary supply sources beyond Chinese material flows. MFDS chemical substance registration and national strategic stockpile programs influence procurement security planning. The Seoul Capital Area hosts fiber preform drawing facilities serving Pacific submarine cable projects.
Erbium Oxide Market Competitive Landscape
Channel-controlling players compete with product-specialist players across distinct tier positions. The vendor base stratifies between integrated rare earth-to-oxide operators and focused high-purity finishers serving photonics OEMs. Two strategic archetypes dominate: backward-integrated miners with captive separation capacity, and analytical-capability specialists competing on lot-to-lot consistency. Capacity expansion and strategic offtake agreements represent the primary competitive moves reshaping supply relationships.
Among North American material suppliers, American Elements exemplifies the integrated archetype with rare earth separation through oxide finishing capabilities. Stanford Advanced Materials occupies a position within the high-purity specialist tier, competing on granule and pellet format consistency for laser crystal applications. Treibacher Industrie AG represents the European analytical-capability anchor, serving REACH-registered supply channels for telecommunications OEMs.
| Leading Market Players |
|---|
| American Elements |
| China Minmetals Rare Earth |
| Stanford Advanced Materials |
| Treibacher Industrie AG |
| Alfa Aesar |
| Ganzhou Qiandong Rare Earth Group |
| Alkane Resources |
| ESPI Metals |
| Chengdu Beyond Chemical |
| Others |
Supply & Pricing Matrix
Undercapacity in North American rare earth oxide finishing is forcing telecommunications OEMs toward premium pricing for supply security, while Jiangxi province's refining corridor maintains cost advantages through integrated separation-to-oxide operations. This geographic asymmetry between concentrated Asian supply and security-conscious Western buyers creates divergent pricing postures across purity tiers and contract structures.
Pricing Analysis
Cost-plus contracts indexed to natural gas and electricity benchmarks dominate high-purity erbium oxide procurement, with telecommunications equipment vendors locking in multi-year offtake agreements to secure 99.9% purity material. Price differentiation rests on trace impurity certification thresholds and lot-to-lot consistency guarantees rather than brand premiums. Cost compression in standard-grade powder formats is intensifying because construction materials buyers prioritize volume scale over analytical documentation. Fiber preform manufacturers exhibit the least price sensitivity, while glass colorant producers in Jiangxi's construction materials corridor drive the most aggressive spot-market negotiation.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for North American photonics OEMs seeking alternative sourcing. Production concentrates in China, Japan, and Germany, with Jiangxi province's ionic clay deposits and Ganzhou's separation infrastructure anchoring global oxide output. Raw material flows draw from heavy rare earth co-occurrence in southern Chinese deposits, xenotime mineral concentrates from Malaysian operations, and recycled magnet feedstocks from Japanese urban mining operations. Single-source vulnerability around ICP-MS analytical metrology constrains quality lab expansion. Distribution runs through integrated rare earth-to-oxide operators with direct pipeline transfer to fiber preform manufacturers, supplemented by drum-based international shipment for spot-market powder sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Certified analytical services and lot-specific documentation represent the fastest-expanding recurring-revenue layer, outpacing hardware margins as telecommunications OEMs demand full supply chain provenance under REACH and MIIT mandates.
For Market Incumbents: Pre-empt analytical capability shortages by acquiring ICP-MS operations in Arizona or California qualification hubs before wage inflation erodes service margins. Backward integration into rare earth separation capacity in North America defends against IRA incentive-driven domestic competitors. Co-packaged optics architectures threaten standalone amplifier module revenues, making thermal expansion coefficient specification control the critical defensive lever. For New Entrants and Emerging Players: Mid-market soluble compound formats for catalyst manufacturers in the Rhine-Ruhr region represent the most penetrable entry point, bypassing telecommunications certification barriers. South Korean fiber preform drawing facilities seeking secondary supply sources beyond Chinese material flows offer qualified demand without incumbent relationship lock-in. A qualification-laboratory partnership go-to-market angle accelerates acceptance testing timelines for regional photonics OEMs. For Investors and Strategic Acquirers: Capital is best deployed toward analytical-capability specialists with established ICP-MS operations and existing REACH registration documentation, as quality lab scarcity intensifies acquisition premiums. Long-term viability across the projection horizon hinges on positioning within submarine cable and space-based laser communication supply chains rather than commodity colorant markets. The signal to watch is MIIT export licensing disruption frequency, which would accelerate North American domestic capacity investment timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Rare Earth Separation | IRA critical minerals incentives reduce capital recovery periods for North American oxide finishing capacity. |
| Long-term Supply Agreement | Fixed pricing tiers with telecommunications OEMs mitigate natural gas cost volatility for calcination operations. |
| Analytical Laboratory Acquisition | ICP-MS capability scarcity commands premium positioning in fiber preform supplier qualification protocols. |
| Joint Venture with Jiangxi Refiners | Co-investment in Ganzhou separation infrastructure secures priority oxide allocation for submarine cable projects. |
| Green Manufacturing Transition | Renewable-powered calcination aligns with EU Green Deal requirements for REACH-registered supply channels. |
Research Methodology
Initial hypotheses were tested against primary input from rare earth separation plant managers, telecommunications equipment procurement leads, laser crystal grower R&D directors, and ICP-MS laboratory operations heads, then refined against customs trade data, MIIT certification registries, SEC 10-K filings from listed rare earth processors, and ECHA substance evaluation documentation. Bottom-up volume estimates from individual oxide finishing facilities were triangulated with top-down demand models derived from fiber amplifier deployment statistics and submarine cable project announcements.
Demand-supply-balance modeling across the analysis window incorporated purity tier segmentation, format type differentiation between powder and pellet outputs, end-use industry concentration in telecommunications versus construction materials, and regional production hub classification. CAGRs were derived from slope analysis of annual volume trajectories rather than single-point extrapolation. Forecast inputs included MIIT export licensing approval rates, IRA incentive disbursement timelines, and co-packaged optics adoption curves from hyperscaler transceiver qualification programs.
Practitioners should monitor heavy rare earth co-product pricing volatility, REACH authorization list expansion, and dual-use export control reclassification for early signals of forecast revision triggers. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Global Optical Measurement Market
Optical Components
Global Transparent Quartz Tube Market
Optical Components
Terbium Gallium Garnet Market
Optical Components
US Lithium Niobate Modulator Market
Optical Components
Coherent Optical Equipment Market
Optical Components
Electro-Optic Modulators Market
Optical Components
Digital Optical Transmitter Market
Optical Components
High Power Double-Clad Fiber Bragg Grating Market
Optical Components
Global Optical Connectivity Solutions Market
Optical Components
Optical Dome Market
Optical Components
Optical Transceiver Market
Optical Components
Photointerrupter Market
Optical Components
Europe Optical Film Market
Optical Components
Global Hybrid Photonic Integrated Circuit Market
Optical Components
Global Optical Fiber Preform Market
Optical Components
Passive Optical Component Market