
 Optical Communications Market | 2026-2036
Optical Communications Market Size, Share, and Industry Trends Forecast 2026-2036
Optical Communications Market Outlook
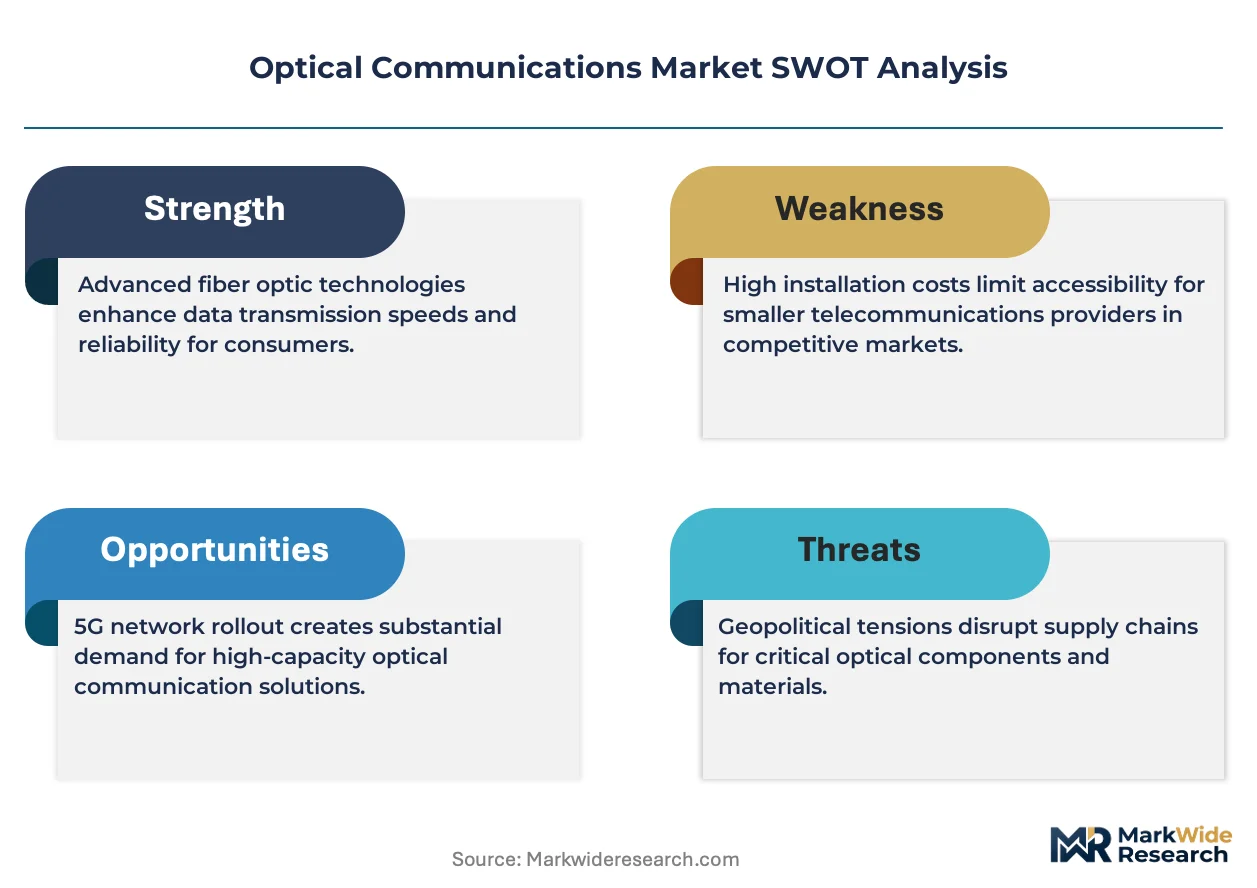
Silicon photonics integration is reshaping transceiver architecture by collapsing discrete components onto single chips. Ciena Corporation leverages coherent DSP technology to sustain leadership in long-haul wavelength systems. Huawei Technologies Co. Ltd. anchors supply for domestic 5G backhaul through captive photonics manufacturing. Corning Incorporated dominates specialty fiber production for data center interconnects.
Optical communications encompasses the transmission of information via light signals through fiber-optic media, typically operating at wavelengths between 1260 and 1625 nanometers with attenuation below 0.2 decibels per kilometer in single-mode fiber. These systems serve as the backbone for high-capacity telecommunications, cloud computing infrastructure, and enterprise networking by converting electrical data into modulated light pulses. Transceivers represent the most contested margin pool as 800G and 1.6T form factors command premium pricing from hyperscale buyers. Coherent optics extends reach and spectral efficiency, making it the fastest-growing technology segment for submarine and metro deployments. Fiber cables remain the mature volume base, with manufacturing scale determining cost competitiveness in access network tenders.
The Federal Communications Commission in the United States and the European Telecommunications Standards Institute shape product roadmaps through spectrum allocation and interface certification requirements. China's Ministry of Industry and Information Technology enforces domestic standards that influence supplier qualification for 5G optical transport. Stakeholders must monitor divergence between regional technical specifications as fragmentation in wavelength grid standards threatens interoperability across multinational networks.
Market Dynamics
Silicon photonics is collapsing discrete component architectures into single-chip transceivers, compressing cost curves and forcing legacy suppliers to retool manufacturing footprints or exit volume segments entirely.
Growth Catalysts
- AI-Driven Data Center Buildouts:Hyperscale operators in China are deploying 800G and 1.6T transceivers to support machine learning training clusters. Fiber port density requirements per rack have tripled since 2023.
- Open RAN Mandates:European Union interoperability requirements are accelerating demand for standardized optical interfaces across multi-vendor radio access networks.
- Submarine Cable Upgrades:Coherent DSP technology is extending unrepeatered reach across transoceanic routes, opening replacement cycles on aging Atlantic and Pacific systems.
Market Restraints
- Indium Phosphide Supply Concentration:High-performance laser chip production concentrates among Japanese and US specialty foundries, creating input bottlenecks during demand surges.
- REACH Compliance Costs:European chemical substance restrictions are raising qualification expenses for hermetic packaging materials used in submarine-grade transceivers.
- Copper Interconnect Substitution:Active electrical cables are capturing rack-scale connections under 3 meters, compressing addressable fiber volume in hyperscale facilities.
Strategic Opportunities
- India National Broadband Mission:Government-funded rural fiber-to-the-home deployment is creating tender volume for low-cost GPON optics at unprecedented scale.
- Coherent Pluggable Convergence:Integration of DSP and photonics in QSFP-DD form factors is collapsing the distinction between datacom and telecom transceiver supply chains.
- Edge Computing Micro-Data Centers:5G network densification is generating demand for industrial-temperature optical modules in cell tower baseband units.
Industry Challenges
- Coherent Algorithm Talent Scarcity:DSP firmware engineering expertise concentrates among a handful of specialists, inflating compensation and slowing product development cycles.
- Legacy SONET/SDH Integration:Incumbent carriers require backward-compatible optical transport solutions, forcing vendors to maintain obsolete product lines alongside coherent platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optical Communications Market |
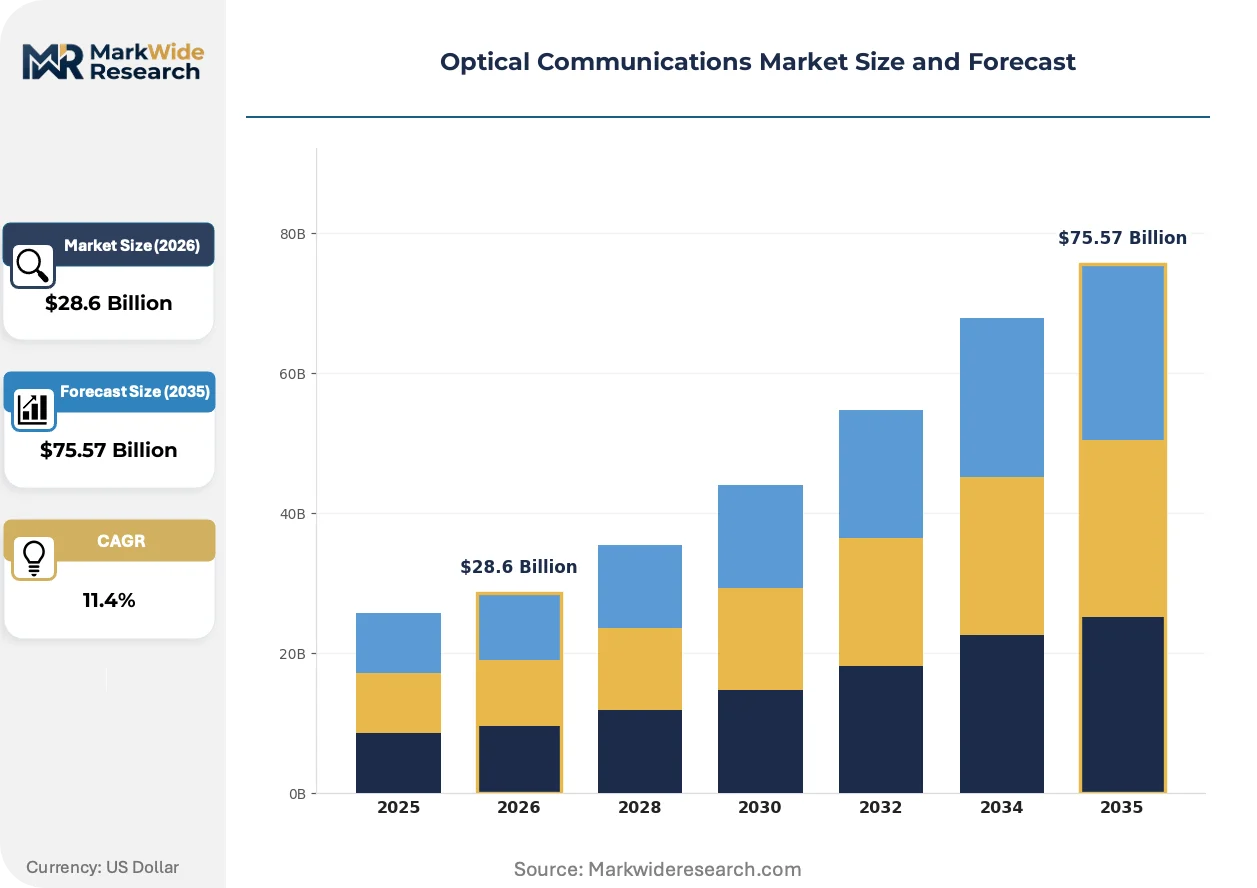
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $75.57 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Amplifiers, Transceivers, Fiber Cables, Modulators Technology: Wavelength Division Multiplexing, Coherent Optics, Free-Space Optics, Dense Wavelength Division Multiplexing End User: Telecommunications, Data Centers, Broadcasting, Research Institutions Application: Long-Haul Communication, Short-Haul Communication, Metro Networks, Access Networks |
| Companies Covered | Ciena Corporation, Cisco Systems, Inc., Huawei Technologies Co. Ltd., Lumentum Holdings Inc., Coherent Corp., Corning Incorporated, Infinera Corporation, Fujitsu, Sumitomo Electric Industries, Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optical Communications Market Strategic Shifts
Optical communications architecture is migrating from discrete component assemblies toward monolithic silicon photonics platforms, with implications spanning manufacturing economics, supplier power, and end-use application boundaries.
Pluggable coherent optics is migrating from standalone line card assemblies into router and switch faceplates. Cloud operators in North America are demanding 400ZR and 800ZR modules in QSFP-DD and OSFP form factors for direct router-to-router metro connectivity. This migration is collapsing the traditional boundary between packet networking and optical transport engineering teams within carrier procurement organizations.
The European Telecommunications Standards Institute's Open ZR+ interoperability specifications are mandating multi-vendor compatibility for high-baud-rate coherent modules. Equipment manufacturers must certify DSP and photonic subsystems against common test protocols before deployment in EU member state networks. Submarine system integrators face the tightest compliance timelines, as Open ZR+ qualification gates now precede cable landing station procurement decisions.
Hyperscale buyers are consolidating optical transceiver procurement through direct contracts with Asian ODMs, bypassing traditional systems vendor channels. Meta and Google now specify silicon photonics designs directly, sourcing finished modules from captive manufacturing partners. This behavior is most visible in Taiwan and China, where merchant DSP suppliers have established dedicated application engineering teams inside buyer facilities to compress development cycles.
Optical Communications Market Segmentation
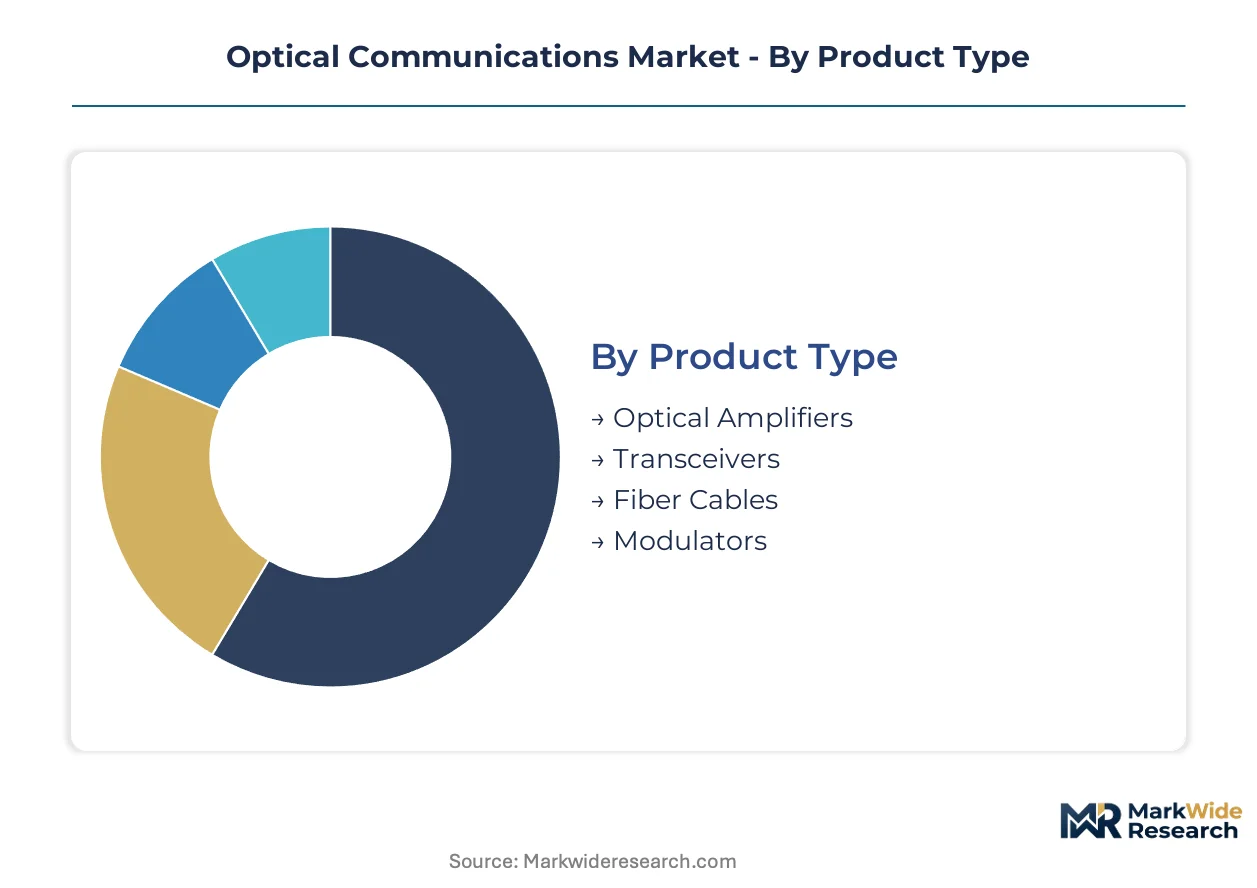
Segmentation in optical communications reveals how technology maturity, cost structure, and deployment geography create distinct margin pools. Buyers prioritize different specifications across submarine, metro, and access applications, fragmenting supplier strategies.
Product Type:
Mature commodity segments coexist with emerging high-integration formats, creating a bifurcated supplier landscape.
- Transceivers:Silicon photonics integration collapses lasers, modulators, and DSP onto single chips. Hyperscale data center operators in China are consolidating procurement through direct Asian ODM contracts for 800G and 1.6T form factors.
- Fiber Cables:Single-mode and specialty fiber variants deliver attenuation below 0.2 decibels per kilometer at 1260-1625 nanometer wavelengths. Manufacturing scale determines cost competitiveness in access network tenders across India National Broadband Mission deployments.
- Optical Amplifiers:Erbium-doped fiber amplifiers extend unrepeatered reach in submarine systems.
- Modulators:Lithium niobate and silicon photonic variants modulate light pulses for coherent transmission.
Transceivers retain volume leadership; coherent pluggable convergence in QSFP-DD form factors holds the steepest expansion curve.
Technology:
Cost tier separation distinguishes legacy volume deployments from premium coherent systems commanding specialized engineering.
- Coherent Optics:Digital signal processing algorithms extend spectral efficiency and transmission reach. Submarine cable upgrades across Atlantic and Pacific routes are accelerating replacement demand for coherent DSP-based line cards.
- Dense Wavelength Division Multiplexing:DWDM multiplexes multiple optical carrier signals onto single fiber through tight wavelength spacing. Metro networks in European Union member states are adopting Open ZR+ specifications to satisfy interoperability mandates.
- Wavelength Division Multiplexing:CWDM variants serve cost-sensitive access networks with wider channel spacing.
- Free-Space Optics:Laser-based atmospheric transmission bypasses fiber trenching in temporary or denied-access scenarios.
DWDM retains volume leadership; coherent optics holds the steepest expansion curve.
End User:
Customer type determines specification intensity, procurement centralization, and backward compatibility requirements.
- Data Centers:Hyperscale facilities demand 800G and 1.6T transceivers with silicon photonics architectures. Fiber port density requirements per rack have tripled since 2023 to support AI training cluster interconnects.
- Telecommunications:Incumbent carriers require coherent transport solutions maintaining backward compatibility with legacy SONET/SDH infrastructure. Open RAN mandates from European regulators are accelerating standardized optical interface procurement.
- Broadcasting:Media networks prioritize low-latency fiber links for live content distribution.
- Research Institutions:Scientific computing centers deploy specialty fiber for high-precision timing and synchronization.
Telecommunications retains volume leadership; data centers hold the steepest expansion curve.
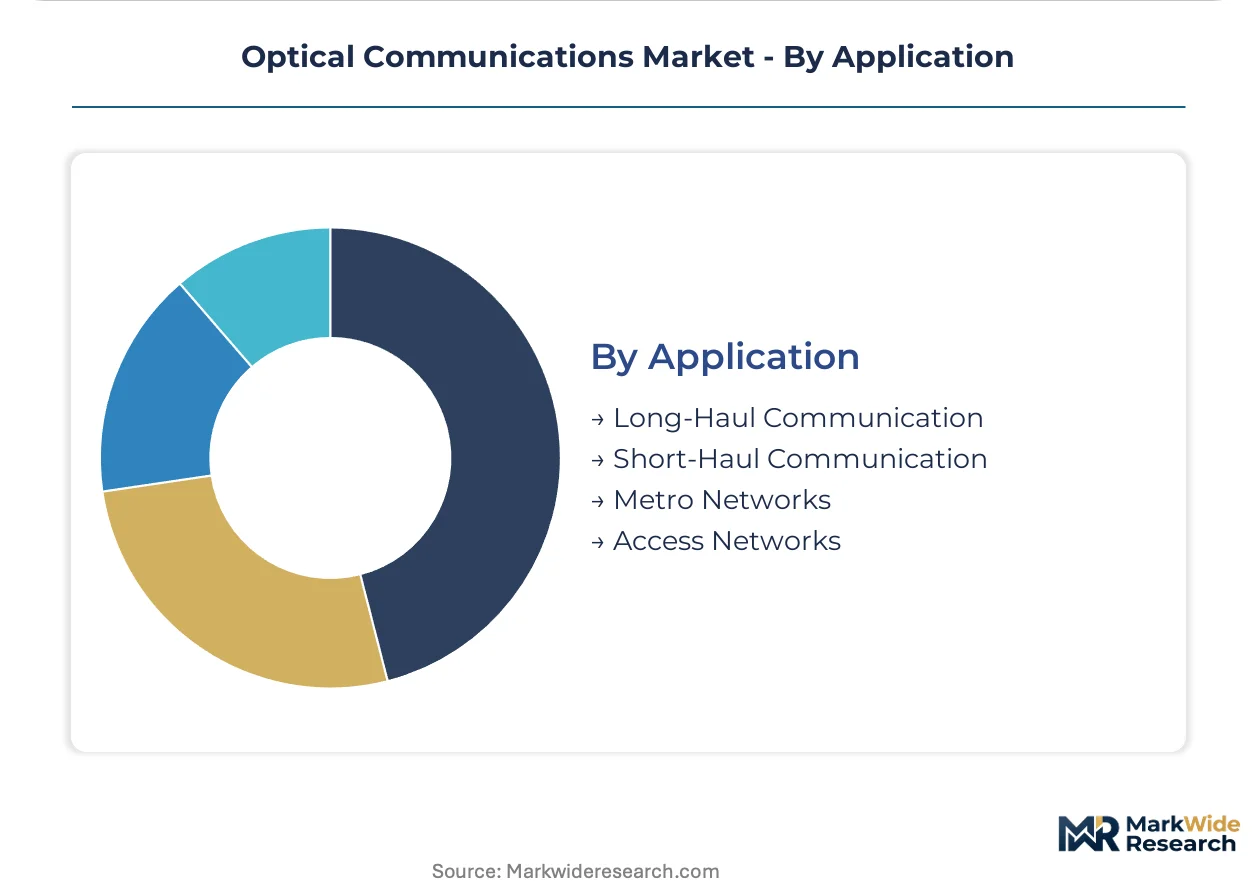
Application:
Reach requirements segment the market into distance-based tiers with distinct technology and margin profiles.
- Long-Haul Communication:Transoceanic and intercontinental routes deploy coherent optics with advanced modulation formats. Submarine system integrators face compressed qualification timelines as Open ZR+ certification gates now precede cable landing station decisions.
- Metro Networks:Urban aggregation rings connect data centers and central offices over 10-100 kilometer spans. Cloud operators in North America are demanding 400ZR and 800ZR pluggable modules for direct router-to-router connectivity.
- Short-Haul Communication:Data center interconnects and campus networks operate below 10 kilometers.
- Access Networks:Fiber-to-the-home deployments utilize GPON optics for cost-sensitive last-mile connectivity.
Access networks retain volume leadership; metro networks hold the steepest expansion curve.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese optical component exports flow directly to hyperscale data center operators in North America and Europe, bypassing traditional systems vendor channels. Taiwan-based ODMs serve as the primary manufacturing conduit for silicon photonics transceivers bound for global cloud infrastructure. Submarine cable landing stations on both sides of the Atlantic anchor coherent optics demand.
United States
Hyperscale cloud operators in Virginia and Oregon drive 800G transceiver procurement through direct Asian ODM contracts. The FCC shapes product roadmaps through spectrum allocation and interface certification requirements. Greater San Jose hosts merchant DSP suppliers maintaining dedicated application engineering teams inside buyer facilities.
China
Domestic cloud providers build hyperscale AI training facilities requiring massive fiber port density expansion. The Ministry of Industry and Information Technology enforces domestic standards influencing supplier qualification for 5G optical transport. Shenzhen and Shanghai anchor captive photonics manufacturing for 5G backhaul supply.
Germany
Industrial automation networks generate demand for industrial-temperature optical modules in manufacturing corridors. ETSI Open ZR+ interoperability specifications mandate multi-vendor compatibility for coherent modules deployed across EU member states. Munich and Berlin concentrate equipment manufacturer certification laboratories.
India
Government-funded rural fiber-to-the-home deployment creates tender volume for low-cost GPON optics at unprecedented scale. The Telecom Regulatory Authority of India oversees spectrum allocation affecting wireless backhaul optical transport requirements. Maharashtra and Karnataka host emerging domestic assembly operations for access network components.
Japan
Specialty foundries concentrate high-performance indium phosphide laser chip production serving global transceiver demand. METI industrial policy supports domestic photonics manufacturing scale. Yokohama and Osaka anchor submarine cable system integration facilities facing compressed Open ZR+ qualification timelines.
Optical Communications Market Competitive Environment
Channel-controlling players compete with product-specialist players across three distinct tiers. Consolidation pressure intensifies as silicon photonics integration collapses legacy component supply chains. Systems vendors with captive semiconductor capabilities occupy the premium tier, while merchant component suppliers and Asian ODMs populate volume segments. Competitive moves center on backward integration into photonic chip manufacturing and direct procurement relationships with hyperscale data center operators.
Among North American systems vendors, Ciena Corporation and Cisco Systems, Inc. exemplify the coherent DSP technology tier. Corning Incorporated represents the specialty fiber manufacturing archetype. Huawei Technologies Co. Ltd. occupies a position as a vertically integrated Asian systems vendor with captive photonics manufacturing. These three anchors illustrate how geographic origin and corporate structure map to competitive positioning across submarine, metro, and access network applications.
| Leading Market Players |
|---|
| Ciena Corporation |
| Cisco Systems, Inc. |
| Huawei Technologies Co. Ltd. |
| Lumentum Holdings Inc. |
| Coherent Corp. |
| Corning Incorporated |
| Infinera Corporation |
| Fujitsu |
| Sumitomo Electric Industries, Ltd. |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in Japanese indium phosphide foundries is compressing availability of high-performance laser chips while hyperscale buyers consolidate procurement through direct Asian ODM contracts. This utilization squeeze simultaneously elevates input costs for premium coherent transceivers and accelerates substitution toward silicon photonics architectures that bypass specialty foundry bottlenecks.
Pricing Analysis
The 800G-to-1.6T generation pricing gap widens substantially against legacy 400G and 100G tiers, with coherent DSP-enabled modules commanding substantial premiums over intensity-modulated alternatives. Contract-based long-term offtake structures dominate hyperscale procurement, though spot-market volatility persists for indium phosphide laser chips where volume scale and certification grade (Open ZR+ compliance) differentiate supplier tiers. Pricing pressure stems from active electrical cables capturing sub-3-meter rack connections, compressing fiber transceiver volumes in hyperscale facilities. Access network buyers exhibit highest price sensitivity, while submarine system integrators prioritize reliability and extended reach over unit cost.
Supply Chain Analysis
Extended payment terms from hyperscale cloud operators now reach 90-120 days, forcing Asian ODMs to utilize supply-chain finance facilities backed by Taiwanese banking consortiums. Manufacturing concentrates in Taiwan, China, and Japan, with the first two anchoring silicon photonics module assembly and the latter feeding indium phosphide laser chips and lithium niobate modulators. Supply chain risk centers on single-source vulnerability for high-baud-rate DSPs and coherent algorithm firmware. Distribution runs through direct procurement relationships with Meta, Google, and domestic Chinese cloud providers, bypassing traditional systems vendor channels entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Open ZR+ interoperability specifications are collapsing the traditional boundary between packet networking and optical transport procurement, creating platform-economics dynamics where ecosystem control determines margin capture.
For Market Incumbents: Pre-empt coherent pluggable convergence by accelerating backward integration into silicon photonics foundry capacity in Taiwan or China. Defend against hyperscale direct-ODM procurement by embedding application engineering teams inside buyer facilities, mirroring merchant DSP supplier tactics. Prioritize certification investment for ETSI Open ZR+ compliance ahead of EU cable landing station decisions. For New Entrants and Emerging Players: Build out captive supply of industrial-temperature optical modules for 5G edge computing micro-data centers, where incumbent carrier procurement remains fragmented and specification requirements are less stringent than hyperscale data center tiers. Target India's National Broadband Mission rural fiber tenders for low-cost GPON optics, leveraging domestic assembly partnerships in Maharashtra and Karnataka to satisfy local content preferences. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across silicon photonics manufacturing as 800G and 1.6T transceivers require advanced packaging capabilities. Long-term viability favors suppliers with captive photonic chip production or exclusive ODM relationships with hyperscale buyers. Acquisition target archetype: merchant DSP specialists with coherent algorithm talent pools. Signal to watch: Open ZR+ qualification timelines compressing from 18 months to sub-12 month cycles.| Strategic Initiative | Industry Significance |
|---|---|
| Silicon Photonics Foundry Investment | Captive manufacturing of 800G/1.6T transceivers reduces dependency on Taiwanese ODM pricing power. |
| Open ZR+ Certification Acceleration | ETSI compliance gates now precede submarine cable procurement decisions in EU member states. |
| Hyperscale Direct Procurement Relationship | Bypassing systems vendor channels captures margin pool from Meta and Google optical spend. |
| Coherent DSP Talent Acquisition | Firmware engineering scarcity in Greater San Jose inflates compensation and slows development cycles. |
| India Domestic Assembly Partnership | Maharashtra and Karnataka operations satisfy local content rules for National Broadband Mission tenders. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of SEC filings, hyperscaler capital expenditure disclosures, ETSI technical specifications, and customs trade data for optical component flows. Interviews with transceiver procurement managers at cloud operators, optical transport engineers at incumbent carriers, DSP firmware architects at merchant semiconductor suppliers, and submarine cable system integrators informed demand-side assumptions. Bottom-up modeling of 800G and 1.6T port shipments triangulates against top-down market value estimates derived from supplier revenue disclosures.
Forecast inputs include modeled adoption curves across product type, technology generation, end-user vertical, and application reach tiers. The analytical framework segments by coherent versus direct-detect architectures, silicon photonics versus indium phosphide laser sources, and hyperscale data center versus telecommunications carrier procurement patterns. CAGRs derive from shipment volume projections weighted by average selling price trajectories for each form factor generation, incorporating input from supply-side capacity announcements and demand-side capex guidance.
The forecast holds incumbent behavior within observed patterns; aggressive moves by vertically integrated Chinese systems vendors or merchant DSP specialists would shift outcomes substantially. Model assumptions incorporate observed qualification timelines for Open ZR+ interoperability, indium phosphide foundry utilization rates, and hyperscale direct-ODM procurement penetration. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Communication Chips & Hardware
Data Transmission Module Market
Communication Chips & Hardware
Transceiver Chip Market
Communication Chips & Hardware
4G Smart Device Chip Market
Communication Chips & Hardware
Global Narrowband IoT (NB IoT) Chipset Market
Communication Chips & Hardware
Semiconductor Device in Communication Industry Market
Communication Chips & Hardware
Global Hybrid Fiber Coaxial Market
Communication Chips & Hardware
APAC Semiconductor Device in Communication Industry Market
Communication Chips & Hardware
Nano GPS Chip Market
Communication Chips & Hardware
IPC Soc Chip Market
Communication Chips & Hardware
Global Wireless Gigabit Market
Communication Chips & Hardware
Global PCI Express Serial Communication Card Market
Communication Chips & Hardware
Time-Of-Flight Chip Market
Communication Chips & Hardware
Wireless Connectivity Chipset Market
Communication Chips & Hardware
Earphone Bluetooth Chip Market
Communication Chips & Hardware
Japan Digital Signal Processor Market
Communication Chips & Hardware
Bluetooth Audio Soc Chips Market