
 Mexico Extreme Ultraviolet Lithography (EUVL) Systems Market | 2026-2036
Mexico Extreme Ultraviolet Lithography (EUVL) Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Mexico Extreme Ultraviolet Lithography (EUVL) Systems Market Insights
Photoresist chemistry is rebalancing product economics as metal-oxide resists replace chemically amplified organic formulations for sub-7nm patterning fidelity. ASML Holding NV leverages its monopoly on EUV light source systems to sustain pricing power across Mexican foundry installations. ZEISS Group anchors the optical subsystem supply chain with its precision mirror assemblies, while Applied Materials, Inc. competes in adjacent deposition and etch tools that complement lithography clusters.
Extreme Ultraviolet Lithography (EUVL) Systems deploy 13.5nm wavelength light generated by laser-produced tin plasma, reflecting through multilayer-coated mirrors to pattern silicon wafers at resolutions below 3nm half-pitch for commercial semiconductor production. The technology requires vacuum chamber operation and extreme precision in thermal management to prevent wavefront distortion during exposure. Light Sources command the dominant value share due to source power scaling requirements, while Wafer Inspectors represent the fastest-growing product category as yield management intensifies at advanced nodes. Foundries absorb the majority of installed EUVL capacity, though Research Institutes are expanding procurement as Mexico's federal technology programs build domestic semiconductor workforce capabilities.
Mexico's Ministry of Economy coordinates industrial policy for semiconductor equipment imports, while Cofece reviews competition implications of concentrated lithography supply chains, and NOM standards govern electromagnetic compatibility for installed systems. Regulatory compliance with NOM-024 energy efficiency requirements shapes equipment selection criteria for Mexican fabs, and import tariff structures under USMCA provisions influence total cost of ownership calculations for EUVL system deployments. Stakeholders must monitor how federal semiconductor incentive program disbursement timelines affect capital commitment cycles relative to equipment lead times.
Market Dynamics
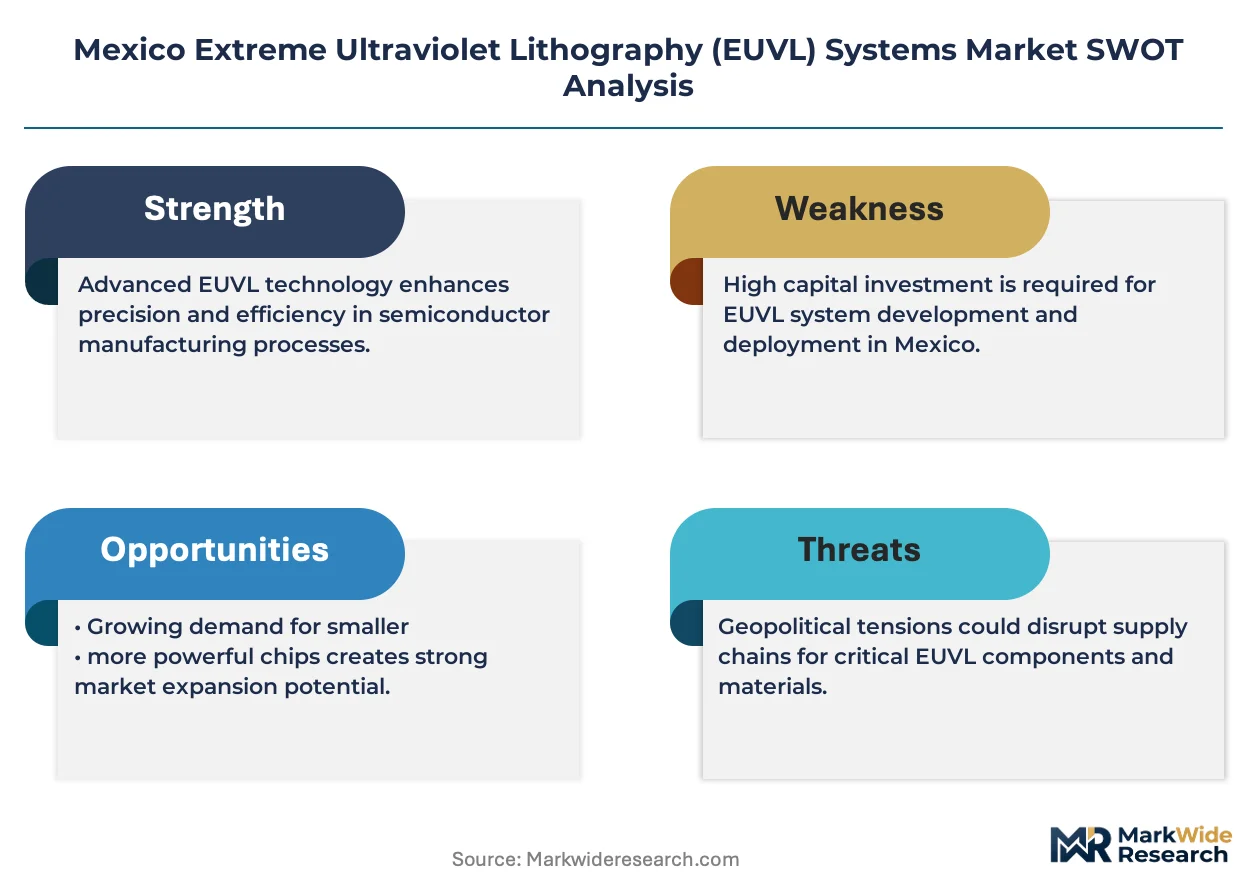
Laser-produced plasma EUV sources are concentrating capital deployment decisions around single-supplier dependencies, forcing Mexican foundries to negotiate multi-year service contracts before equipment delivery slots open.
Growth Catalysts
- Federal semiconductor incentives:Mexico's Ministry of Economy disbursement schedules under strategic electronics manufacturing programs are accelerating capital equipment import approvals for Baja California and Jalisco fabrication facilities.
- Advanced node migration:Sub-7nm patterning requirements at Guadalajara foundries are mandating EUVL adoption where deep ultraviolet multi-patterning reaches physical limits.
- USMCA tariff structures:Duty-free treatment for semiconductor production equipment under the trade agreement is lowering total cost of ownership calculations relative to Asian import alternatives.
Market Restraints
- Single-source lithography supply:Vacuum-compatible precision optics production concentrates in German and Dutch supplier bases, creating geopolitical exposure for Mexican fabs.
- Photoresist input volatility:Metal-oxide resist precursor chemicals face supply allocation constraints as foundry demand outpaces specialty chemical manufacturing capacity.
- NOM-024 compliance friction:Electromagnetic compatibility certification timelines for EUVL systems extend equipment commissioning schedules by four to six months.
Strategic Opportunities
- Tijuana corridor expansion:Underpenetrated back-end facilities in Baja California present retrofit opportunities for EUV-aware inspection and metrology tool integration.
- Research institute procurement:Federal technology workforce programs are creating non-foundry demand streams for lower-throughput EUV systems at domestic training centers.
- Deposition-etch cluster convergence:Adjacent process equipment integration with lithography cells offers bundled service contract possibilities for Applied Materials and Lam Research tool ecosystems.
Industry Challenges
- EUV-specific technician scarcity:Vacuum system maintenance and tin droplet generator calibration require specialized training pipelines that Mexican technical institutes have not yet scaled.
- Legacy DUV integration complexity:Hybrid fabs running both deep ultraviolet and extreme ultraviolet lines face workflow scheduling conflicts and contamination control protocol mismatches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mexico Extreme Ultraviolet Lithography (EUVL) Systems Market |
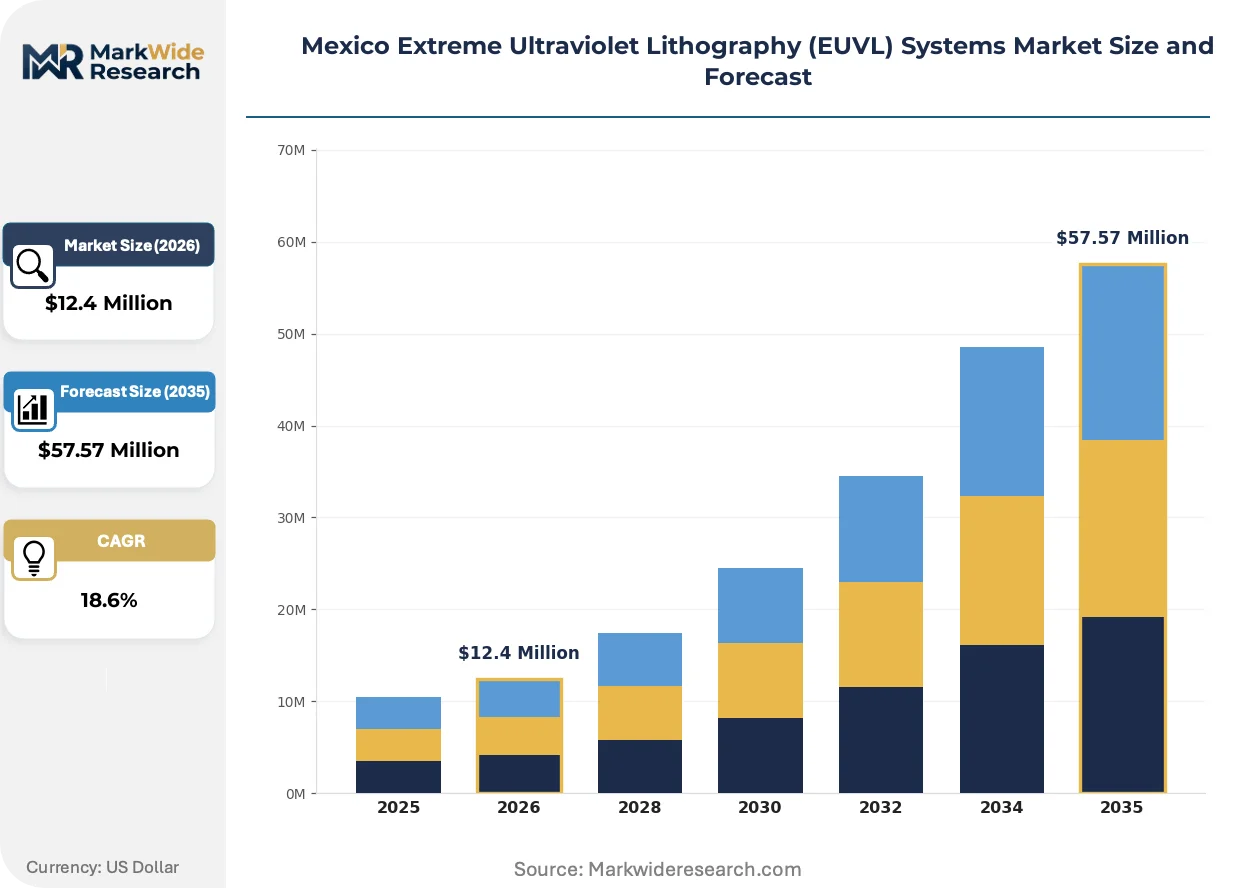
| Market Size in 2026 | $12.4 Million |
| Market Size in 2035 | $57.57 Million |
| CAGR (2026 – 2036) | 18.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Light Sources, Wafer Inspectors, Photomasks, Coating Equipment Technology: Optical Lithography, Electron Beam Lithography, Nanoimprint Lithography, Maskless Lithography Application: Semiconductor Manufacturing, Flat Panel Displays, MEMS Fabrication, Circuit Board Production End User: Foundries, Integrated Device Manufacturers, Research Institutes, Government Entities |
| Companies Covered | ASML Holding NV, KLA Corporation, ZEISS Group, Canon Inc., Nikon Corporation, TRUMPF, Applied Materials, Inc., Lasertec Corporation, AGC Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mexico Extreme Ultraviolet Lithography (EUVL) Systems Market Trends and Innovations
Photoresist chemistry transitions and source power scaling requirements are compressing equipment replacement cycles while rewriting procurement evaluation criteria for Mexican semiconductor facilities.
Metal-oxide resists are rewriting patterning economics for sub-7nm nodes. These formulations deliver improved line-edge roughness control compared to chemically amplified organic alternatives. Foundries in Guadalajara are adopting metal-oxide platforms for their first EUV production layers. The technology is rewriting yield management protocols by reducing defect density in critical dimension control.
NOM-024 energy efficiency mandates are reshaping equipment specification requirements for Mexican installations. The standard imposes standby power consumption limits that affect thermal management subsystem design. Lithography tool vendors must certify vacuum pump and cooling unit configurations separately from core exposure systems. Baja California fabs are responding by bundling energy compliance verification into pre-shipment acceptance testing.
Buyer concentration among integrated device manufacturers is consolidating procurement negotiation leverage. Three foundry operators now control effective EUV capacity allocation decisions for northern Mexico. Equipment vendors are responding with dedicated application engineering teams stationed in Tijuana and Guadalajara. This concentration is visible in extended payment term negotiations and priority service tier structures.
Mexico Extreme Ultraviolet Lithography (EUVL) Systems Market Segmentation
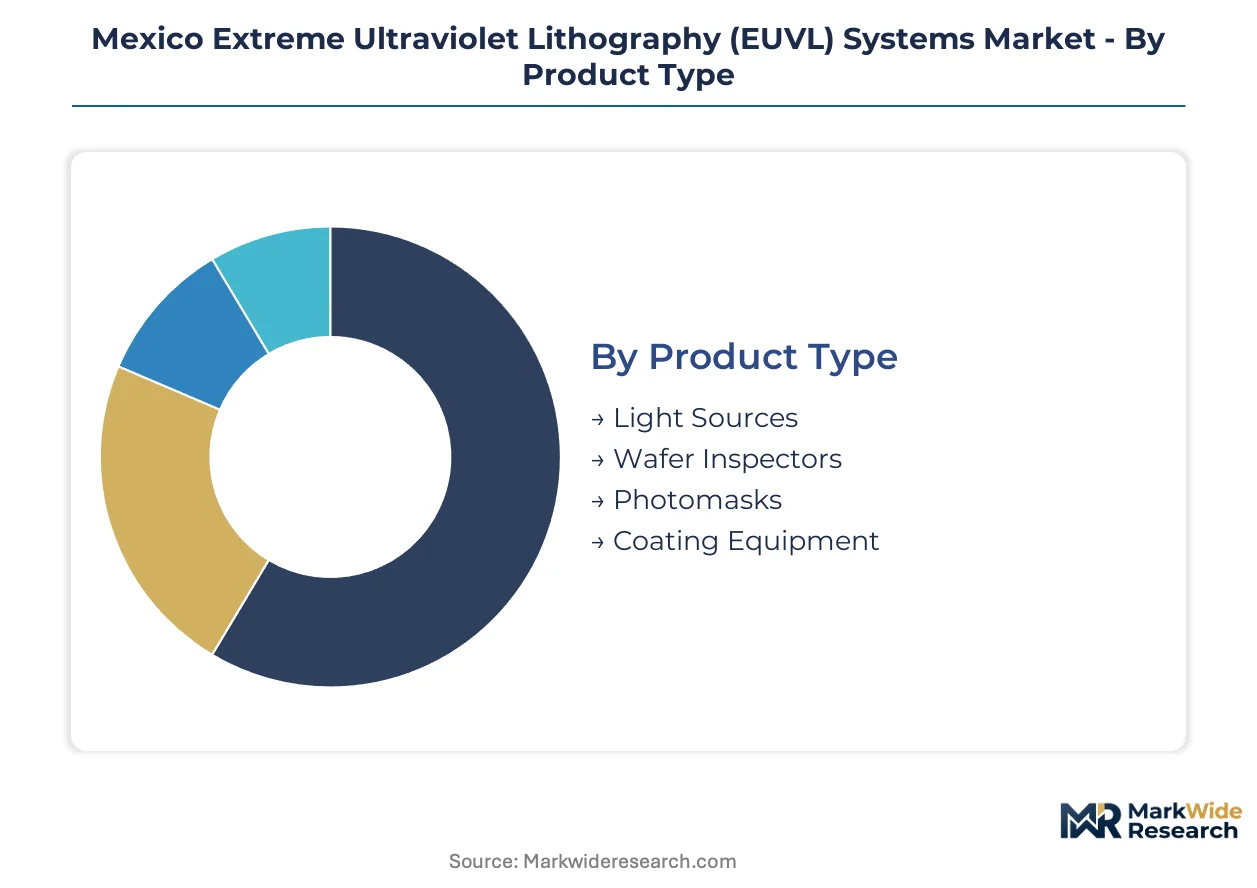
EUVL system procurement in Mexico fractures across equipment categories, patterning technologies, and customer archetypes. Each segmentation axis reveals distinct capital allocation priorities among Guadalajara foundries and Baja California fabrication clusters.
Product Type:
Power scaling requirements and yield management intensity differentiate equipment value tiers across Mexican installations.
- Light Sources:Laser-produced plasma systems generating 13.5nm wavelength light through tin droplet excitation dominate capital expenditure. Guadalajara foundries prioritize source power above 500W for high-volume manufacturing throughput. Single-supplier concentration forces Mexican fabs into multi-year service contracts before delivery slots open.
- Wafer Inspectors:Defect detection systems operating at sub-7nm sensitivity thresholds are expanding most quickly in Baja California. Tijuana facilities retrofit inspection capacity to manage yield loss from metal-oxide resist process windows. Equipment vendors station dedicated application engineering teams to support commissioning timelines.
- Photomasks:Multilayer-reflective reticles with molybdenum-silicon coating stacks pattern EUV exposure layers.
- Coating Equipment:Track systems for metal-oxide resist deposition and development integrate with lithography cluster workflows.
Mature deployment sits with Light Sources. Newer deployment is concentrated in Wafer Inspectors.
Technology:
Patterning physics and resolution limits separate commercially dominant methods from niche alternatives in Mexican fab planning.
- Optical Lithography:Reflective 13.5nm EUV systems with Zeiss multilayer mirror assemblies anchor production at advanced nodes. Baja California IDMs deploy optical EUV for sub-7nm logic layers where deep ultraviolet multi-patterning fails. Ministry of Economy incentive disbursements accelerate import approvals for these systems.
- Electron Beam Lithography:Direct-write systems using variable-shaped beam technology serve mask writing and prototyping applications. Research institutes in Mexico City procure lower-throughput configurations for federal workforce training programs. Patterning speed constraints limit fab-scale deployment.
- Nanoimprint Lithography:Mechanical patterning through template contact offers cost alternatives for non-critical layers.
- Maskless Lithography:Electron-beam and laser-based direct-write systems enable rapid prototyping without reticle fabrication.
Volume concentration favors Optical Lithography. Capability building concentrates in Electron Beam Lithography.
Application:
Device complexity and layer count requirements drive divergent EUV adoption timelines across Mexican manufacturing bases.
- Semiconductor Manufacturing:Logic and memory fabrication at sub-7nm nodes consumes the dominant share of installed EUV capacity. Guadalajara foundries pattern transistor and interconnect layers using metal-oxide resists for critical dimension control. NOM-024 energy efficiency mandates reshape thermal management subsystem specifications.
- Flat Panel Displays:Large-area patterning for OLED backplanes and driver integrated circuits adopts EUV for fine-pitch routing. Tijuana display assembly corridors source patterned substrates from adjacent semiconductor facilities. Panel size scaling challenges optical field stitching requirements.
- MEMS Fabrication:Microelectromechanical systems use EUV for sensor element definition at wafer-scale.
- Circuit Board Production:Advanced packaging interconnects explore EUV-aware lithography for redistribution layer patterning.
Capital intensity peaks in Semiconductor Manufacturing. Adoption momentum builds in Flat Panel Displays.
End User:
Procurement scale and technical capability requirements stratify customer segments across Mexico's northern industrial corridor.
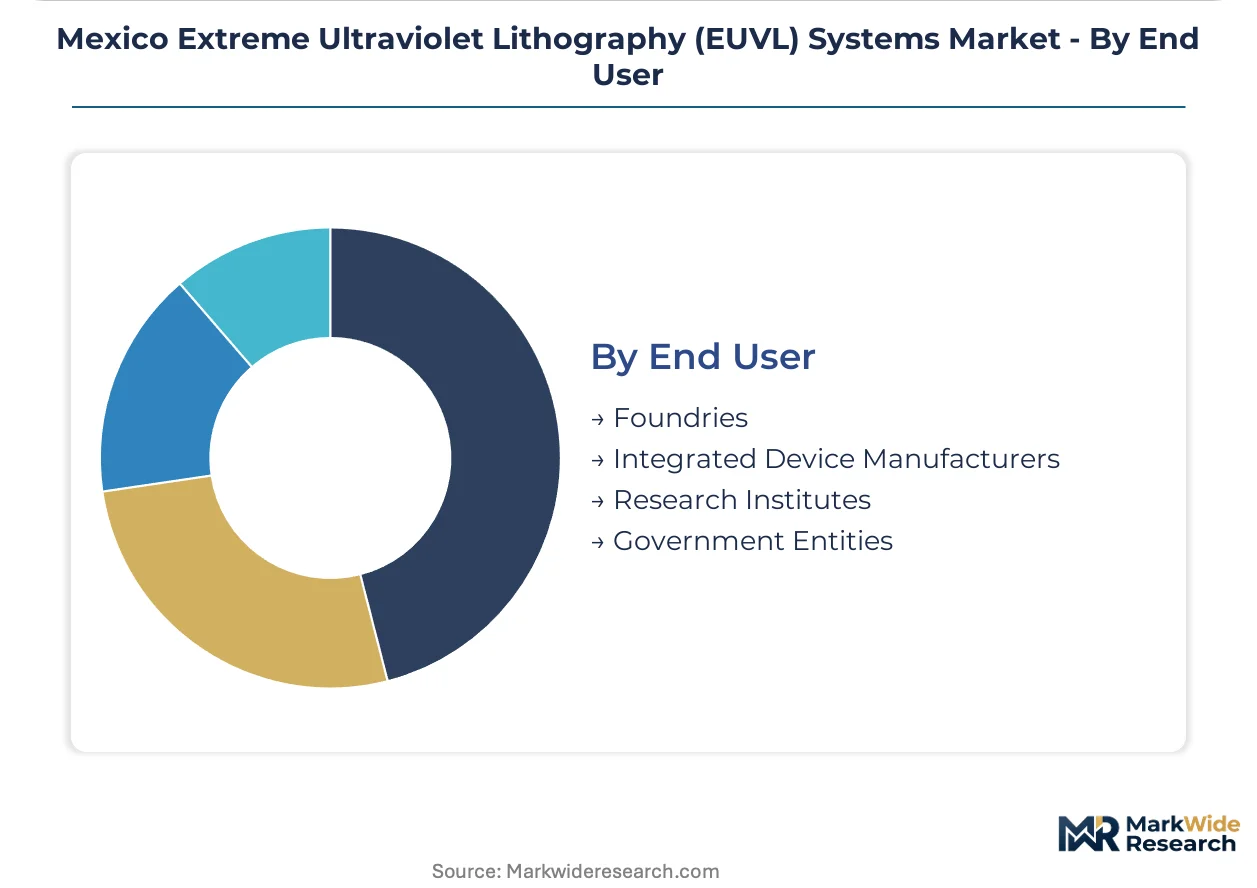
- Foundries:Merchant semiconductor manufacturers in Guadalajara absorb majority EUV capacity for advanced node production. Multi-year equipment delivery queues concentrate negotiation leverage among three dominant operators. Priority service tier structures reflect concentrated buyer power.
- Integrated Device Manufacturers:Captive fabrication facilities in Baja California deploy EUV for proprietary logic and memory products. USMCA tariff treatment lowers total cost of ownership relative to Asian import alternatives. Hybrid DUV-EUV workflows create contamination control protocol challenges.
- Research Institutes:Federal technology programs build domestic technician pipelines through lower-throughput system procurement.
- Government Entities:Defense and aerospace applications explore secure domestic patterning capabilities.
Volume leadership resides with Foundries. Capability expansion concentrates in Research Institutes.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates in northern Mexico's industrial corridor where Baja California and Jalisco host the dominant fabrication capacity. Federal incentive disbursement schedules under the Ministry of Economy's strategic programs are accelerating capital equipment import approvals for these clusters.
Baja California
Tijuana and Mexicali host integrated device manufacturers deploying EUVL for proprietary logic production. NOM-024 energy efficiency mandates reshape thermal management subsystem specifications for installed systems. The border industrial corridor benefits from USMCA tariff treatment that lowers total cost of ownership relative to Asian import alternatives.
Jalisco
Guadalajara's foundry cluster drives sub-7nm patterning requirements where deep ultraviolet multi-patterning reaches physical limits. Ministry of Economy disbursement schedules are accelerating capital equipment import approvals for advanced node migration. The Guadalajara metropolitan area concentrates merchant semiconductor manufacturing capacity and technician training pipelines.
Nuevo León
Monterrey's electronics assembly corridor generates demand for EUV-aware inspection and metrology tool integration. Cofece reviews competition implications of concentrated lithography supply chains affecting regional procurement. The state hosts expanding back-end facilities presenting retrofit opportunities for adjacent process equipment.
Mexico City Metropolitan Area
Research institutes in the capital procure lower-throughput EUV systems for federal workforce training programs. National electromagnetic compatibility standards govern equipment certification timelines extending commissioning schedules. The metropolitan zone anchors domestic semiconductor education infrastructure and policy coordination.
Mexico Extreme Ultraviolet Lithography (EUVL) Systems Market Competitive Landscape
Strategic partnerships dominate the current landscape as equipment vendors establish dedicated application engineering teams in Tijuana and Guadalajara. The vendor base concentrates around single-supplier dependencies in vacuum-compatible precision optics, creating tiered service contract structures. Three archetypes emerge: lithography system integrators, optical subsystem specialists, and adjacent process equipment providers. Multi-year service contracting and priority tier structures represent the dominant competitive moves.
Within the lithography integration tier, ASML Holding NV exemplifies the concentrated supply position that forces Mexican foundries into advance service commitments. Among optical subsystem specialists, ZEISS Group occupies a position reflecting German precision manufacturing heritage. At the adjacent equipment vector, Applied Materials, Inc. represents the deposition-etch cluster convergence opportunity for bundled service contracts.
| Leading Market Players |
|---|
| ASML Holding NV |
| KLA Corporation |
| ZEISS Group |
| Canon Inc. |
| Nikon Corporation |
| TRUMPF |
| Applied Materials, Inc. |
| Lasertec Corporation |
| AGC Inc. |
| Others |
Pricing and Supply Chain Analysis
Tin spot price volatility on the London Metal Exchange cascades through laser-produced plasma source manufacturing into three-tier pricing structures across premium, standard, and economy levels for Mexican foundry procurement. Equipment vendors translate raw material cost swings into service contract escalators that concentrate pricing power among ASML's installed base.
Pricing Analysis
High-volume foundry contracts sacrifice margin for delivery slot priority while research institute sales capture premium pricing for lower-throughput configurations. Price differentiation separates multiyear service bundling from bare equipment procurement, with NOM-024 compliance verification adding certification-tier premiums. Pricing pressure stems from single-source lithography dependencies forcing Mexican fabs into advance payment structures. Integrated device manufacturers in Baja California exhibit highest price sensitivity due to captive fab economics, whereas Guadalajara merchant foundries prioritize throughput guarantees over unit cost.
Supply Chain Analysis
Transpacific freight cost spikes from Rotterdam and Veldhoven extend equipment commissioning timelines and inflate total cost of ownership calculations for Mexican installations. Vacuum-compatible precision optics production concentrates in Germany and the Netherlands, while tin droplet generator subsystems source from Japanese specialty manufacturers. Single-source vulnerability in Zeiss multilayer mirror assemblies creates geopolitical exposure for Baja California fabs. Distribution runs through ASML's direct service organization with localized application engineering teams in Tijuana and Guadalajara.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Single-supplier concentration in lithography light sources is compressing viable vendor count and forcing consolidation among adjacent process equipment providers unable to bundle service contracts.
For Market Incumbents: Deploy multi-year service tier structures as the primary retention mechanism against emerging deposition-etch cluster convergence threats from Applied Materials and Lam Research. Backward integration into metal-oxide resist precursor supply channels reduces photoresist input volatility exposure. Priority capacity allocation for Guadalajara's three dominant foundry operators defends position against potential Nikon or Canon optical lithography revivals. For New Entrants and Emerging Players: Research institutes operating federal workforce training programs represent the most penetrable buyer archetype for lower-throughput EUV configurations. Electron beam lithography direct-write systems for mask writing applications face less entrenched supplier relationships than production optical lithography. A go-to-market angle emphasizing technician training partnerships with Jalisco's technical universities bypasses foundry procurement committee barriers. For Investors and Strategic Acquirers: The window for entry favors optical subsystem specialists with vacuum-compatible precision manufacturing capabilities before ASML completes vertical integration into mirror assembly production. Wafer inspection equipment vendors serving Baja California's retrofit demand offer acquisition targets with immediate revenue traction. Watch Cofece competition review outcomes for lithography supply chain concentration as the signal for regulatory-forced divestiture opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-year Service Contract Expansion | ASML locks Mexican foundries into priority maintenance tiers before competitor tool qualification. |
| Backward Integration into Photoresist Precursors | Equipment vendors secure metal-oxide resist chemical supply against specialty manufacturer allocation constraints. |
| Research Institute Partnership Program | Vendors build technician pipelines through Mexico City federal workforce training center placements. |
| Deposition-Etch Cluster Convergence | Applied Materials bundles adjacent process tools with lithography cell integration services. |
| NOM-024 Pre-Certification Investment | Zeiss and ASML reduce Mexican commissioning delays through standby power compliance pre-verification. |
Research Methodology
SEC filings from lithography equipment vendors, Mexican Ministry of Economy import records, and SEMI industry statistics formed the secondary backbone for market sizing validation. Primary interviews with fab operations directors, vacuum system maintenance technicians, photoresist procurement leads, and Cofece regulatory analysts combined with bottom-up and top-down triangulation to cross-check capacity installation timelines against federal incentive disbursement schedules.
Bottom-up modeling aggregated individual equipment delivery slots and service contract values across Guadalajara and Baja California fabrication facilities, while top-down analysis calibrated aggregate spending against Ministry of Economy capital import authorizations across the projection horizon. Segmentation dimensions included product type, patterning technology, application layer complexity, and end-user procurement scale. CAGRs derived from equipment replacement cycle compression and source power scaling roadmaps, with NOM-024 compliance friction and USMCA tariff treatment as industry-specific forecast modifiers.
Revisions become necessary when federal semiconductor incentive disbursement timelines shift, Cofece competition rulings alter supplier concentration, or photoresist precursor supply allocations tighten beyond current specialty chemical manufacturing capacity. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Global Optical Measurement Market
Optical Components
Fluorophore Market
Optical Components
Optical Film Market
Optical Components
Global Optical Connectivity Solutions Market
Optical Components
Global Optical Fiber Preform Market
Optical Components
Europe Eye Tracking Solutions Market
Optical Components
LGP (Light Guide Plate) for TV Market
Optical Components
North America Laser Diode Market
Optical Components
Optical Dome Market
Optical Components
North America Tunable Laser Market
Optical Components
Liquid Light Guides Market
Optical Components
Europe Tunable Laser Market
Optical Components
Erbium Oxide Market
Optical Components
Spatial Light Modulator Market
Optical Components
Waveguide Phase Shifter Market
Optical Components
Optical Isolator Market