
 Optical Isolator Market | 2026-2036
Optical Isolator Market Size, Share, and Industry Trends Forecast 2026-2036
Optical Isolator Market Intelligence
Aftermarket calibration and refurbishment revenue is narrowing as OEMs push integrated isolator-laser modules with sealed optical paths. Corning Optical Communications leverages its fused silica supply chain to dominate polarization-maintaining isolator substrates. Innolume GmbH sustains competitive positioning through in-house production of 980nm pump laser isolators for erbium-doped fiber amplifiers. Jiangxi Liansheng Technology Co., Ltd anchors cost-sensitive fiber optic isolator supply for Chinese telecommunications OEMs.
An optical isolator is a non-reciprocal magneto-optic device employing Faraday rotator crystals—typically terbium gallium garnet or yttrium iron garnet—biased by permanent magnets to rotate polarization by 45 degrees and block back-reflected light via polarizer-analyzer pairs. It protects laser diodes and amplifiers from optical feedback damage in high-power systems operating above 1W continuous-wave output. Fiber optic isolators lead product type demand due to their direct integration into telecom transceivers and submarine cable repeaters. Faraday isolators compete in scientific and defense applications requiring extreme extinction ratios above 40dB. Acousto-optic technology occupies niche ultrafast laser markets where tunable isolation bandwidth matters more than insertion loss.
The US FCC regulates optical power emissions in telecommunications equipment, while China's MIIT enforces GB standards for fiber optic component environmental testing. The EU F-Gas Regulation restricts sulfur hexafluoride and other greenhouse gases used in certain optical manufacturing processes, forcing crystal growers toward alternative etching chemistries. Stakeholders must monitor how REACH substance restrictions evolve for rare-earth dopants and whether India's BIS certification mandates create new compliance gates for imported isolator assemblies.
Market Dynamics
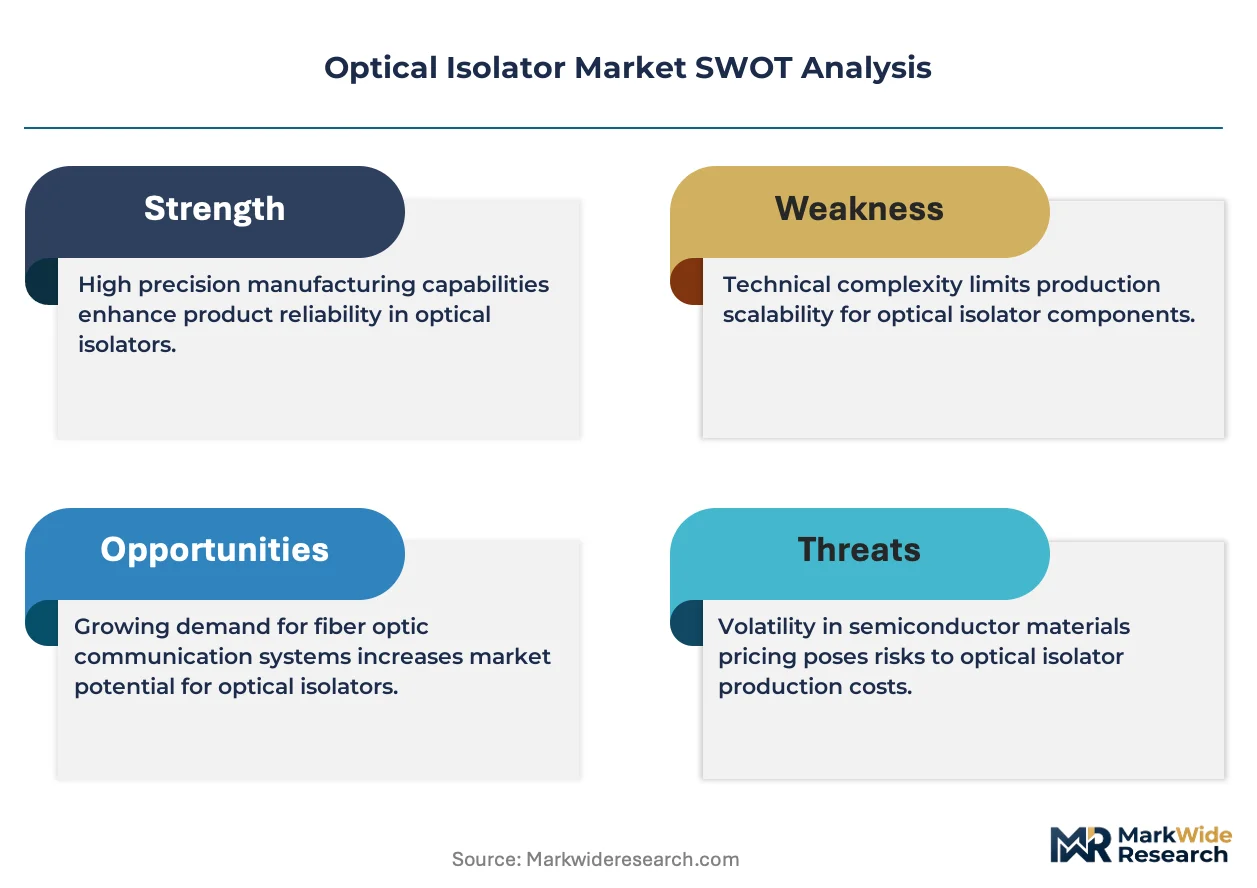
Telecommunications OEMs are consolidating optical isolator procurement around polarization-independent designs for 5G backhaul, compressing demand for legacy polarization-maintaining variants while China's MIIT fiber standards and the EU's F-Gas Regulation simultaneously reshape material compliance requirements for magneto-optic crystal supply chains.
Growth Catalysts
- 5G Infrastructure Deployment:Telecommunications carriers in China, the United States, and Germany are installing dense fiber networks requiring isolator-protected pump lasers for erbium-doped fiber amplifiers at every amplification node.
- Data Center Interconnect Scaling:Hyperscale cloud operators are consuming polarization-independent isolators in 400G and 800G coherent transceivers to suppress back-reflection in high-speed optical links.
- Submarine Cable Modernization:Transoceanic cable consortiums are replacing legacy repeaters with isolator-integrated amplifiers to extend unrepeatered span lengths across Pacific routes.
Market Restraints
- Rare-Earth Supply Concentration:Terbium and yttrium refining for Faraday rotator crystals concentrates in Chinese processing facilities, exposing non-Chinese isolator manufacturers to supply disruption risk.
- Permanent Magnet Cost Volatility:Neodymium-iron-boron magnet prices fluctuate with Chinese export quota policies, directly pressuring isolator bill-of-materials stability.
- Technical Performance Ceiling:Conventional terbium gallium garnet crystals face thermal depolarization limits above 10W continuous-wave power, constraining high-power fiber laser applications.
Strategic Opportunities
- Indian Telecom Buildout:India's BharatNet rural fiber initiative and private 5G spectrum auctions are creating fresh demand for cost-optimized isolator assemblies compliant with BIS certification mandates.
- Silicon Photonics Integration:Foundry partnerships between isolator specialists and silicon photonics platforms are enabling monolithic integration of non-reciprocal functions with CMOS-compatible processes.
- EU Green Deal Alignment:The F-Gas Regulation's phase-down of sulfur hexafluoride is forcing crystal etching process innovation, rewarding early movers with preferred supplier status under EU public procurement rules.
Industry Challenges
- Magneto-Optic Crystal Growth Expertise Scarcity:Czochralski growth of low-defect terbium gallium garnet boules requires decades of tacit knowledge concentrated at a handful of Japanese and Chinese crystal houses.
- REACH Compliance Documentation Burden:European manufacturers face escalating substance disclosure requirements for rare-earth dopants and permanent magnet coatings, extending new product qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optical Isolator Market |
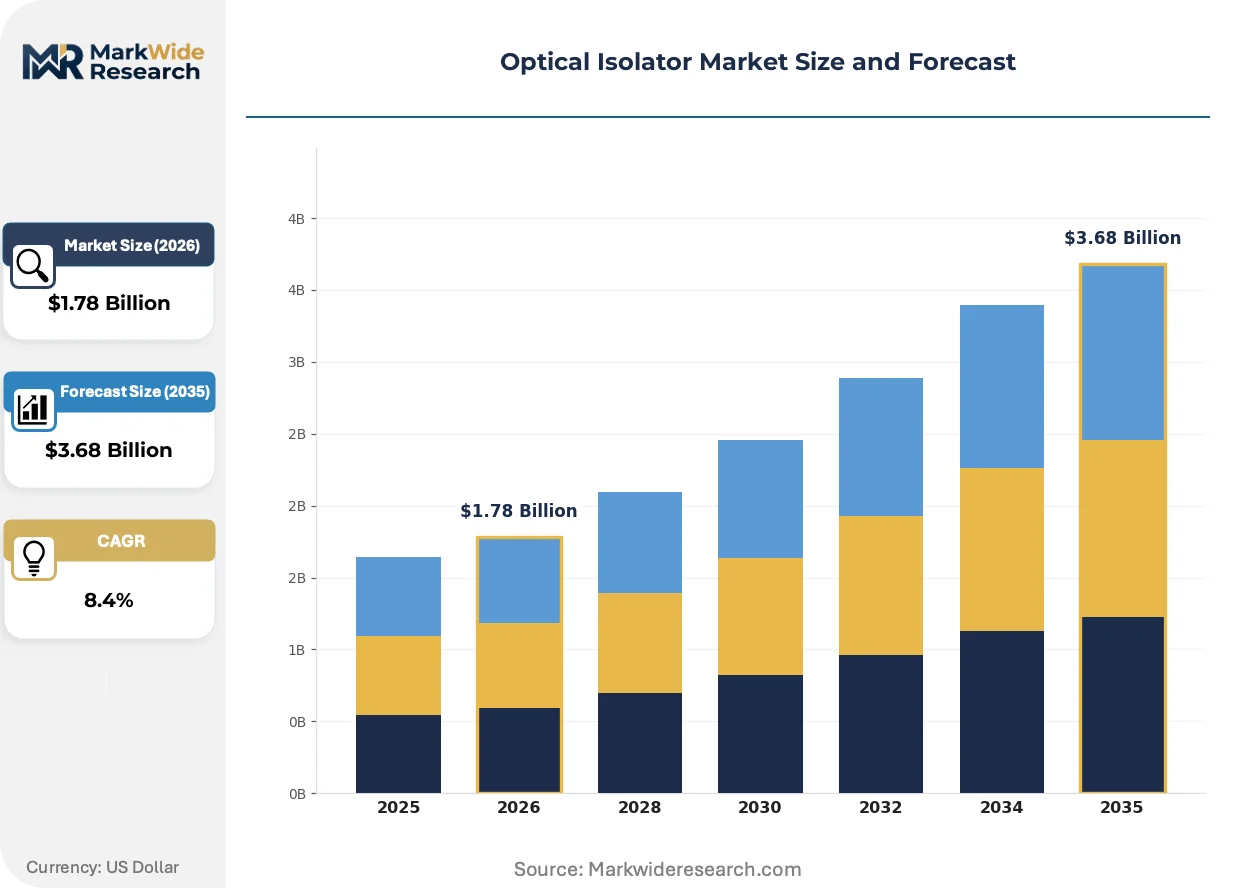
| Market Size in 2026 | $1.78 Billion |
| Market Size in 2035 | $3.68 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Faraday Isolators, Polarizing Isolators, Fiber Optic Isolators, Non-Polarizing Isolators End User: Telecommunications, Aerospace, Defense, Industrial Lasers Installation: Benchtop, Rack-Mounted, Integrated, OEM Technology: Fiber Optic Technology, Acousto-Optic Technology, Electro-Optic Technology, Bulk Optics Technology |
| Companies Covered | Gould Fiber Optics, Innolume GmbH, Corning Optical Communications, Maxphotonics Co. Ltd., Jiangxi Liansheng Technology Co., Ltd, Edmund Optics Inc., Newport Corporation, Advanced Fiber Resources, Electro-Optics Technology, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optical Isolator Market Strategic Shifts & Innovations
Photonic integration and regulatory chemistry restrictions are converging to transform how optical isolators are manufactured, specified, and procured across telecommunications and industrial laser end-uses.
Thin-film magneto-optic materials deposited directly onto semiconductor substrates are rendering obsolete discrete bulk-crystal isolator assemblies in silicon photonics transceivers. Intel and Cisco's optical networking divisions are qualifying these integrated isolators for 800G datacenter interconnects. The shift is compressing addressable market volume for traditional packaged isolators while expanding unit value capture for foundry-compatible magnetic thin-film processes.
China's MIIT revised GB/T standards for fiber optic component environmental testing in 2023, mandating extended temperature cycling and humidity exposure for isolators deployed in outdoor 5G infrastructure. Domestic manufacturers in Shenzhen and Wuhan have retooled qualification laboratories to meet these accelerated stress protocols. Foreign suppliers without local testing partnerships face extended certification delays for Chinese carrier procurement tenders.
Hyperscale data center operators are consolidating optical component purchasing through direct long-term agreements with isolator manufacturers, bypassing traditional distribution channels. Amazon Web Services and Microsoft Azure have established approved vendor lists with volume commitments spanning three-year horizons. This concentration is most visible in East Asian manufacturing clusters where isolator fabs co-locate with laser module integrators serving cloud infrastructure buildouts.
Optical Isolator Market Segmentation
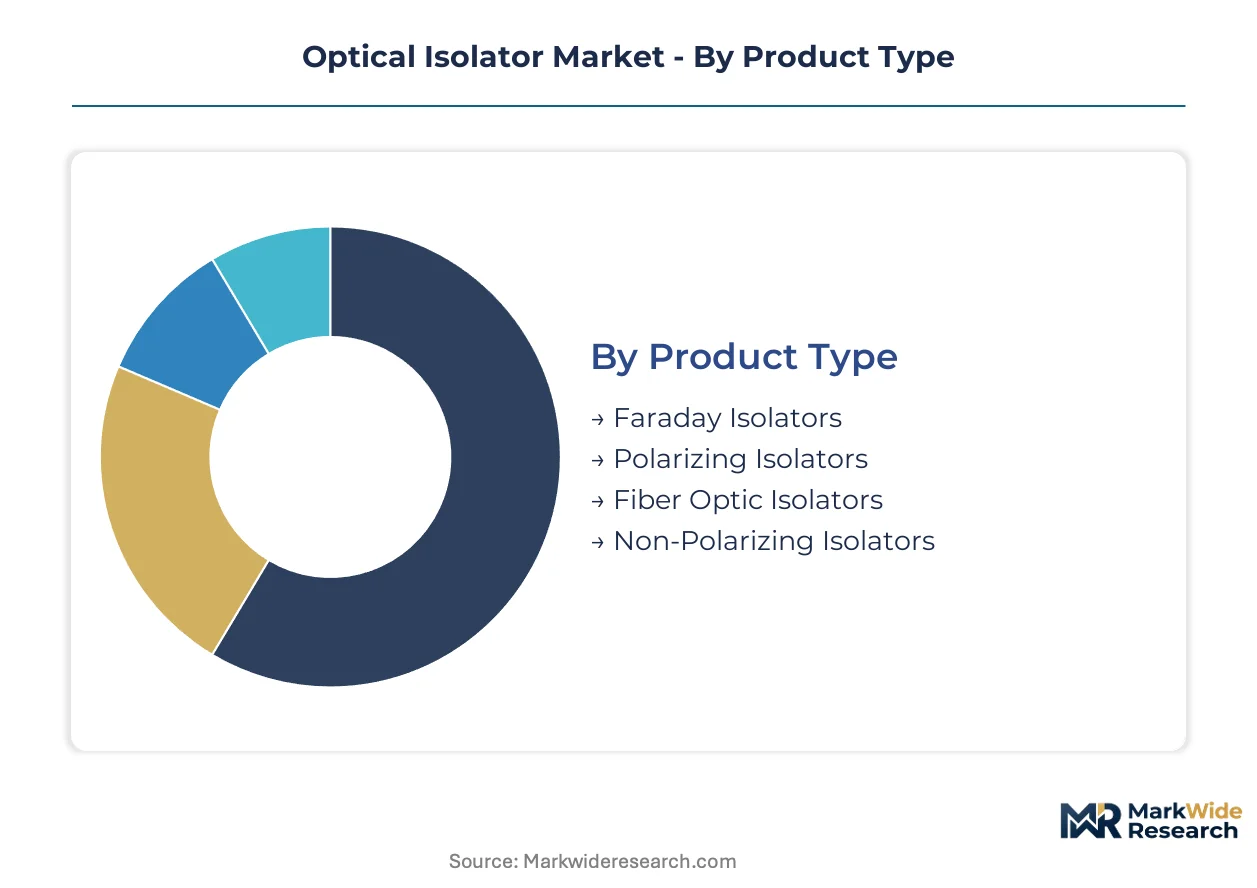
Optical isolator procurement patterns diverge sharply across product architectures and deployment contexts, with aftermarket service intensity varying from negligible in sealed OEM modules to substantial in scientific benchtop configurations. Understanding these segment boundaries clarifies where margin capture concentrates and where technical differentiation sustains pricing power.
Product Type:
After-sales calibration and refurbishment intensity runs highest in scientific-grade Faraday isolators, where polarization extinction ratio drift necessitates periodic realignment, and lowest in telecom fiber optic variants with sealed optical paths.
- Faraday Isolators:These devices employ terbium gallium garnet crystals in strong permanent magnetic fields to achieve polarization rotation with extinction ratios exceeding 40dB. Demand concentrates in German and Japanese scientific laser facilities where back-reflection protection safeguards delicate optical experiments. Thermal depolarization limits above 10W continuous-wave constrain adoption in emerging kilowatt-class industrial cutting systems.
- Fiber Optic Isolators:Direct fusion-splicing into telecom transceivers and submarine cable repeaters defines this segment's integration model. Shenzhen and Wuhan manufacturing clusters consume polarization-independent variants at scale for 5G backhaul infrastructure, with Chinese MIIT environmental testing standards dictating qualification protocols for outdoor deployment.
- Polarizing Isolators:Discrete polarizer-analyzer pairs deliver precise polarization control for laboratory instrumentation.
- Non-Polarizing Isolators:Wavelength-agnostic operation suits multi-channel dense wavelength division multiplexing systems.
By volume, fiber optic isolators lead. By growth pace, Faraday variants for scientific applications are climbing fastest.
End User:
Cost tier stratification separates premium aerospace qualification programs from price-sensitive telecommunications procurement, with defense applications occupying an intermediate position where ITAR compliance adds fixed certification overhead.
- Telecommunications:Carrier procurement of polarization-independent isolators for 5G fronthaul and data center interconnects dominates unit volume. Hyperscale cloud operators in the United States and Germany are consolidating purchasing through direct three-year volume agreements, bypassing traditional distribution channels entirely.
- Industrial Lasers:Fiber laser manufacturers require isolator protection above 1W continuous-wave to prevent catastrophic optical feedback damage. Chinese and German machine tool builders embed these components into cutting and welding heads, with thermal management limitations constraining power scaling beyond current crystal technology limits.
- Aerospace:Satellite optical communication terminals demand radiation-hardened isolator assemblies with extended qualification timelines.
- Defense:Directed energy and laser designation systems drive demand for extreme-environment isolator packaging.
Telecommunications commands absolute unit volume. Industrial lasers are expanding most quickly as fiber laser power scaling penetrates metal fabrication.
Installation:
Customer type fragmentation separates research laboratories with sporadic benchtop purchases from carrier procurement departments managing rack-mounted infrastructure at scale.
- Integrated:Monolithic embedding within laser diode packages or transceiver assemblies eliminates field serviceability entirely. Intel and Cisco optical networking divisions are qualifying thin-film magneto-optic isolators for 800G silicon photonics transceivers, displacing discrete packaged alternatives.
- OEM:Original equipment manufacturers specify isolator performance parameters for captive integration into laser systems and test instrumentation. Japanese and Chinese laser module integrators in East Asian manufacturing clusters source these components through co-located optical component fabs.
- Benchtop:Standalone isolators for laboratory reconfiguration and prototyping support flexible experimental setups.
- Rack-Mounted:Standardized 19-inch enclosures house isolator arrays in carrier central offices and data center fiber distribution frames.
Integrated installations dominate forward procurement commitments. Benchtop configurations retain highest margin per unit despite shrinking volume share.
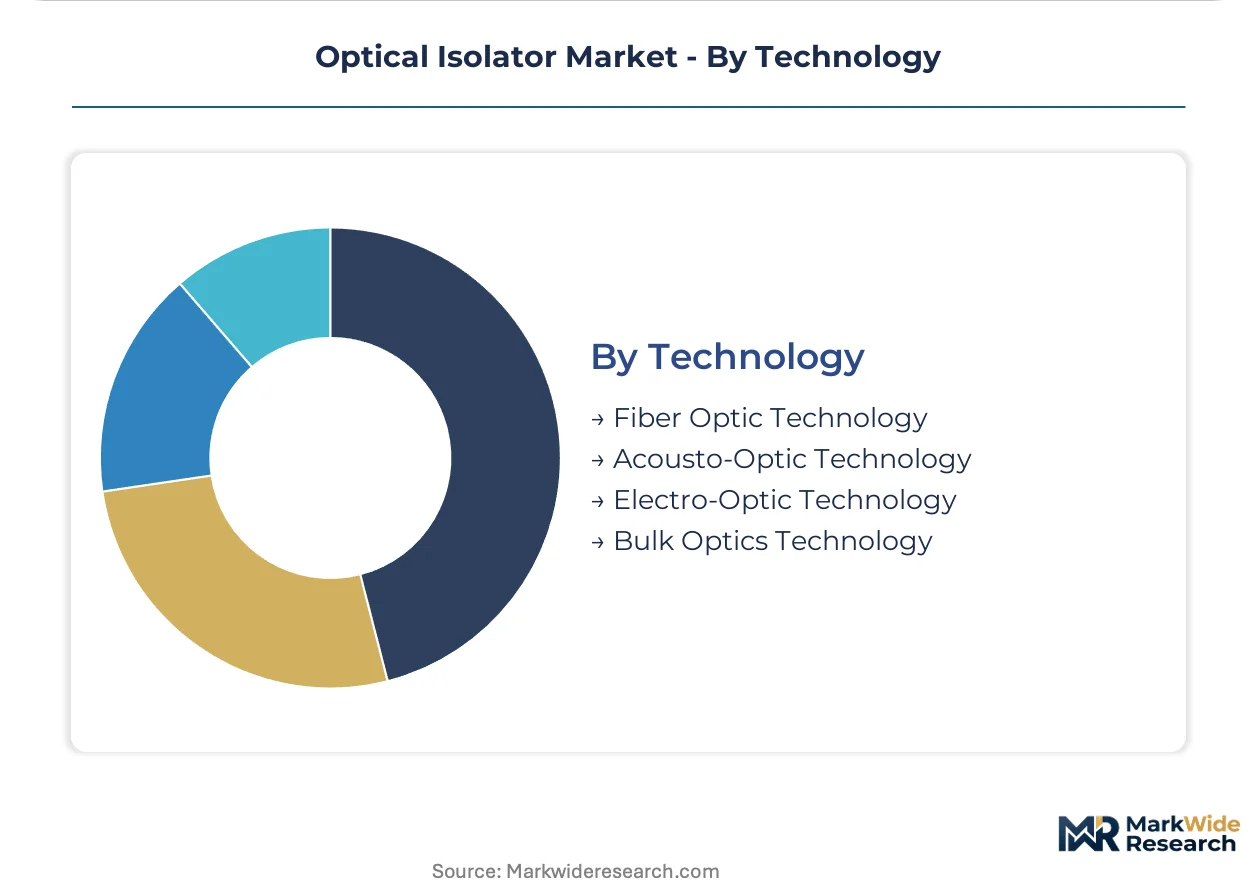
Technology:
Supply concentration in magneto-optic crystal growth expertise—concentrated at Japanese and Chinese crystal houses—shapes competitive dynamics across technology categories, with alternative approaches struggling to match Faraday rotation performance.
- Fiber Optic Technology:Polarization-independent designs using tapered fiber-rotator-fiber architectures enable direct splicing into telecom links. EU F-Gas Regulation restrictions on sulfur hexafluoride etching chemistries are forcing crystal process innovation among European suppliers seeking preferred procurement status.
- Acousto-Optic Technology:Tunable isolation bandwidth suits ultrafast laser applications where insertion loss tolerance enables spectral agility. Niche scientific instrument manufacturers in Germany and the United States deploy these devices for chirped-pulse amplification systems.
- Electro-Optic Technology:Electric-field modulation of birefringence offers switching speed advantages for specialized communication protocols.
- Bulk Optics Technology:Discrete free-space assemblies persist in high-power laser systems requiring thermal management inaccessible to fiber-coupled alternatives.
Fiber optic technology leads by installed base. Acousto-optic approaches are gaining share fastest in emerging ultrafast laser instrumentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across geographies. Indian carriers demand cost-optimized isolator assemblies for rural fiber buildouts, while German scientific laser facilities absorb premium Faraday isolator pricing for extreme extinction ratios. Chinese procurement sits between these poles, prioritizing volume scale with moderate performance tolerance.
United States
Hyperscale cloud operators drive polarization-independent isolator consumption for 400G and 800G coherent transceivers in data center interconnects. The FCC regulates optical power emissions in telecommunications equipment, constraining isolator specifications for carrier-grade deployment. Silicon Valley and Austin manufacturing clusters host isolator-laser module integrators serving AWS and Microsoft Azure procurement programs.
China
Telecommunications infrastructure buildouts for 5G backhaul consume polarization-independent isolators at massive scale. MIIT revised GB/T standards for fiber optic component environmental testing in 2023, mandating extended temperature cycling for outdoor deployment. Shenzhen and Wuhan optical component fabs co-locate with laser systems integrators, anchoring East Asian manufacturing gravity.
Germany
Scientific laser facilities and industrial machine tool builders generate concentrated demand for high-extinction-ratio Faraday isolators. The EU F-Gas Regulation restricts sulfur hexafluoride etching chemistries, forcing crystal process innovation among European suppliers. Munich and Stuttgart precision optics clusters host qualification laboratories serving both research and industrial laser OEMs.
India
BharatNet rural fiber initiative and private 5G spectrum auctions create fresh demand for cost-optimized isolator assemblies. BIS certification mandates establish compliance gates for imported isolator components, favoring domestic testing partnerships. Bengaluru and Hyderabad telecom equipment manufacturing corridors concentrate procurement for cost-sensitive carrier tenders.
Japan
Scientific instrumentation and submarine cable repeater refurbishment sustain demand for premium Faraday rotator crystals. METI industrial policy supports magneto-optic crystal growth expertise retention at specialized Japanese crystal houses. Yokohama and Osaka precision manufacturing districts maintain tacit knowledge in Czochralski growth of low-defect terbium gallium garnet boules.
Optical Isolator Market Key Industry Players
Capability concentration sits with one tier; scale advantage sits with another. The optical isolator market structures around three tiers: multinational fused silica suppliers with captive crystal supply chains, mid-cap specialists with vertical integration into magneto-optic materials, and regional assemblers competing on cost-optimized fiber optic variants. Strategic moves center on foundry partnerships for silicon photonics integration and qualification laboratory investments for MIIT and BIS certification compliance.
Among German precision optics specialists, Innolume GmbH exemplifies the mid-cap integrated model with in-house production capabilities. Corning Optical Communications occupies a position representing multinational substrate supply chain dominance. Jiangxi Liansheng Technology Co., Ltd anchors the cost-optimized tier for Chinese telecommunications OEM procurement. These three archetypes—integrated specialist, multinational materials supplier, and regional cost leader—capture distinct margin pools across the isolator value chain.
| Leading Market Players |
|---|
| Gould Fiber Optics |
| Innolume GmbH |
| Corning Optical Communications |
| Maxphotonics Co. Ltd. |
| Jiangxi Liansheng Technology Co., Ltd |
| Edmund Optics Inc. |
| Newport Corporation |
| Advanced Fiber Resources |
| Electro-Optics Technology, Inc. |
| Others |
Cost & Logistics Intelligence
Rare-earth export quota volatility from Chinese processing facilities determines both three-tier pricing spreads across premium Faraday isolators, standard fiber optic variants, and economy telecom assemblies, and the geographic clustering of crystal growth expertise in Japanese and Chinese specialist houses.
Pricing Analysis
Aftermarket calibration service contracts drive lifetime value in scientific-grade Faraday isolators where polarization extinction ratio drift necessitates periodic realignment, while sealed OEM modules eliminate this revenue stream entirely. Pricing stratifies across premium, standard, and economy tiers based on certification grade for MIIT environmental testing and volume scale commitments from hyperscale cloud operators. Cost compression in economy fiber optic isolators is intensifying because Chinese telecommunications OEMs consolidate procurement around polarization-independent designs. Indian carriers under BharatNet rural fiber initiatives exhibit highest price sensitivity, whereas German scientific laser facilities absorb premium positioning for extreme extinction ratios above 40dB.
Supply Chain Analysis
Export control restrictions on magneto-optic crystal growth technology limit technology transfer outside Japanese and Chinese specialist houses, concentrating tacit knowledge in Czochralski growth of low-defect terbium gallium garnet boules. Raw material dependencies center on terbium and yttrium refining capacity, neodymium-iron-boron permanent magnets, and fused silica substrate supply from Corning's captive operations. Single-source vulnerability runs through Chinese rare-earth processing dominance for Faraday rotator crystal feedstock. Distribution runs through direct long-term agreements between isolator manufacturers and hyperscale cloud operators, bypassing traditional component distribution channels entirely.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Thin-film magneto-optic integration with silicon photonics platforms is disrupting discrete packaged isolator demand, compressing addressable volume for legacy assemblies while expanding unit value capture for foundry-compatible processes.
For Market Incumbents: Harden supply chain resilience by securing captive terbium gallium garnet crystal supply through backward integration into Czochralski growth operations or exclusive offtake agreements with Japanese crystal houses. Accelerate qualification laboratory investments for MIIT GB/T environmental testing compliance to defend procurement access in Chinese carrier tenders against domestic competitors with localized certification partnerships.
For New Entrants and Emerging Players: Pursue white-space opportunities in Indian BIS-certified isolator assemblies for BharatNet rural fiber buildouts, where cost-optimized polarization-independent designs face limited qualified domestic competition. Target foundry partnerships with silicon photonics platforms as the most penetrable entry vector, offering thin-film magneto-optic deposition expertise for 800G datacenter interconnect transceivers.
For Investors and Strategic Acquirers: The market sits at a technology substitution phase that favors materials specialists with in-house crystal growth capabilities over pure-play assemblers exposed to silicon photonics displacement. Acquisition candidates should demonstrate established Czochralski growth expertise or exclusive supply relationships with terbium gallium garnet crystal houses. Monitor Intel and Cisco optical networking qualification timelines for integrated thin-film isolators as the critical inflection signal for traditional packaged isolator demand erosion.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Crystal Growth | Secures terbium gallium garnet supply against Chinese rare-earth export quota volatility. |
| MIIT Qualification Laboratory Investment | Enables accelerated certification for outdoor 5G infrastructure deployment in China. |
| Silicon Photonics Foundry Partnership | Positions thin-film isolators for 800G datacenter interconnect adoption by Intel and Cisco. |
| BIS Certification Partnership in India | Opens BharatNet rural fiber procurement to compliant isolator assemblies. |
| F-Gas Regulation Process Innovation | Grants preferred supplier status under EU public procurement rules for crystal etching. |
Research Approach
A spread of perspectives from telecommunications procurement officers at hyperscale cloud operators, laser systems integration engineers, magneto-optic crystal growth specialists, and regulatory compliance managers converged on the working assumptions. Primary fieldwork combined structured interviews with secondary validation through MIIT GB/T standard documentation, EU F-Gas Regulation compliance filings, FCC telecommunications equipment certifications, and customs trade data for rare-earth magnet and optical component flows. Bottom-up isolator unit demand estimates from 5G infrastructure deployment databases and top-down market sizing triangulated on convergent values.
Demand-supply balance modeling across the projection horizon incorporated telecommunications infrastructure capex cycles, data center interconnect scaling trajectories, and industrial fiber laser power scaling roadmaps. Segmentation dimensions included product architecture, end-use application, installation configuration, and technology platform. CAGRs derived from fitted growth curves applied to base-year estimates, with cross-checks against hyperscaler three-year volume commitment disclosures and submarine cable repeater refurbishment schedules.
Macroeconomic conditions sit as an overlay; deviation in telecommunications carrier capex cycles, rare-earth export quota policies, or silicon photonics adoption velocity would shift the trajectory. Forecasts reflect documented assumptions on 5G deployment pacing and cloud infrastructure expansion. Material shifts in EU F-Gas Regulation enforcement stringency or Chinese MIIT standard revision timing would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
North America Optical Film Market
Optical Components
Global Transparent Quartz Tube Market
Optical Components
US Lithium Niobate Modulator Market
Optical Components
Optical Film Market
Optical Components
Optical Modulators Market
Optical Components
Optical Encoder Market
Optical Components
Europe Tunable Laser Market
Optical Components
ROADM WSS Component Market
Optical Components
100G Optical Transceivers Market
Optical Components
Waveguide Phase Shifter Market
Optical Components
LAMEA Lithium Niobate Modulator Market
Optical Components
Low-E Glass Magnetron Sputtering Coating Line Market
Optical Components
North America Laser Diode Market
Optical Components
Optical Cross Connect Market
Optical Components
Optical Amplifier Market
Optical Components
Asia-Pacific Optical Film Market