
 Optical Sensor Market | 2026-2036
Optical Sensor Market Size, Share, and Industry Trends Forecast 2026-2036
Optical Sensor Market Analysis
Multi-source procurement for infrared emitters and photodetectors is repositioning supply relationships across the optical sensor value chain. ams-OSRAM AG leverages its vertically integrated III-V semiconductor fabrication to dominate high-performance emitter supply. Hamamatsu Photonics K.K. anchors premium photodetector production through proprietary avalanche photodiode technology. Texas Instruments Incorporated competes by extending its analog front-end portfolio into integrated optical sensing subsystems.
An optical sensor converts electromagnetic radiation into electrical signals through photoelectric effects, with responsivity measured in amperes per watt and spectral sensitivity spanning ultraviolet through infrared wavelengths. These devices enable position detection, ambient light measurement, and optical imaging in automated systems. Photodiodes and CCD sensors lead product type revenue due to their penetration in smartphone cameras and machine vision equipment. Digital sensor architectures are displacing analog interfaces in industrial automation as Industry 4.0 protocols demand direct digital output. Medical devices and automotive safety represent the fastest-expanding application segments, driven by pulse oximetry adoption and advanced driver-assistance mandates.
FDA device classification rules in the United States govern optical sensors embedded in diagnostic and patient monitoring equipment, while REACH and RoHS frameworks in Europe restrict hazardous substances in semiconductor packaging materials. Japan's METI promotes domestic optical component manufacturing through JIS standards alignment and clean energy technology subsidies. Stakeholders must monitor evolving cybersecurity requirements for connected sensors in smart home and telecommunications infrastructure as regulatory scope broadens beyond physical safety to data integrity assurance.
Market Dynamics
Automotive LiDAR mandates and industrial machine vision standardization are compressing development cycles while fragmenting procurement across multiple qualified suppliers.
Growth Catalysts
- EU F-Gas Regulation:Phase-down of hydrofluorocarbons in cooling systems for precision optics manufacturing is accelerating adoption of solid-state emitter technologies that eliminate refrigerant-dependent thermal management.
- Machine vision equipment:Quality inspection lines in electronics assembly are integrating multi-spectral photodiode arrays to detect sub-micron surface defects in semiconductor wafers.
- Munich-Jena corridor:Germany's precision optics cluster provides specialized thin-film deposition and lithography capabilities that shorten prototype-to-production timelines for next-generation sensors.
Market Restraints
- Indium gallium arsenide substrate costs:Near-infrared photodetector production depends on limited III-V wafer supply concentrated among Japanese and Taiwanese foundries.
- CE marking complexity:Medical device optical sensors face extended conformity assessment timelines under EU MDR, delaying market entry by 12-18 months versus previous directives.
- SiPM substitution threat:Silicon photomultipliers are capturing low-light detection applications previously served by avalanche photodiodes in medical imaging equipment.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for electronics manufacturing are attracting optical component assembly operations to serve domestic smartphone and automotive markets.
- Quantum sensing convergence:Integration of squeezed light sources with conventional photodetector architectures opens precision measurement applications in gravitational wave detection and atomic clocks.
- Direct-to-equipment-maker channels:Sensor vendors are bypassing traditional distribution by embedding calibration services into supply agreements with industrial automation OEMs.
Industry Challenges
- Multi-physics simulation expertise:Shortage of engineers capable of modeling opto-electro-thermal interactions in packaged sensor assemblies extends design validation cycles.
- ISO 26262 functional safety certification:Automotive LiDAR modules require ASIL-D compliance documentation that consumes 20-30% of total program engineering resources.
- Legacy analog infrastructure:Industrial facilities running 4-20mA control loops face capital-intensive retrofits to accommodate digital optical sensor outputs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optical Sensor Market |
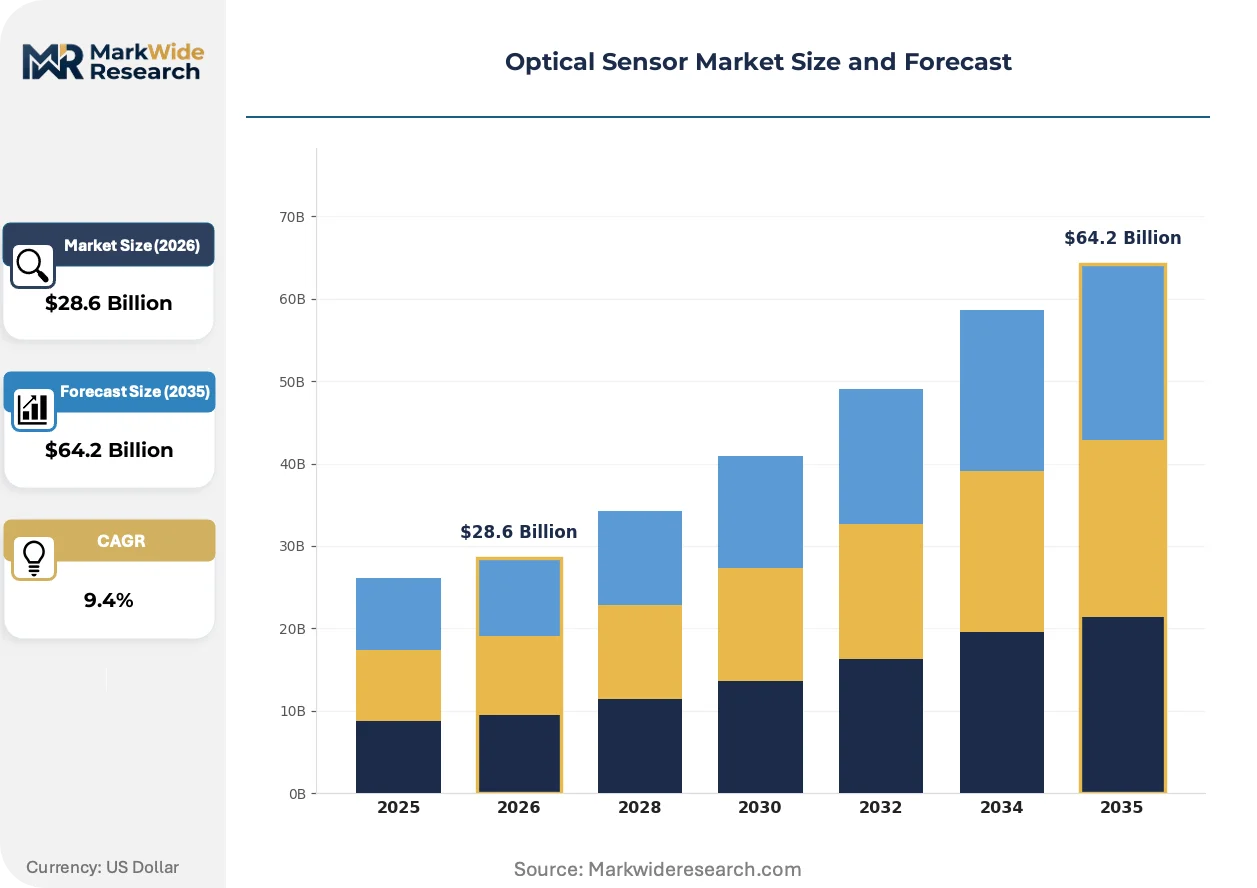
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $64.2 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Photoresistors, Photodiodes, Phototransistors, CCD Sensors Application: Consumer Electronics, Automotive Safety, Industrial Automation, Medical Devices Technology: Analog Sensors, Digital Sensors, Active Sensors, Passive Sensors End User: Aerospace, Defense, Telecommunications, Smart Homes |
| Companies Covered | ams-OSRAM AG, Hamamatsu Photonics K.K., ON Semiconductor Corp., STMicroelectronics N.V., ROHM Co., Ltd., Sony Group Corporation, Broadcom Inc., Texas Instruments Incorporated, Keyence Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optical Sensor Market Emerging Trajectories
Photonic integration and software-defined sensing architectures are dissolving traditional boundaries between component and subsystem suppliers.
Silicon photonics is modularizing optical transceiver design by embedding lasers, modulators, and detectors onto single CMOS-compatible substrates. Cloud hyperscalers are adopting co-packaged optics at the switch-ASIC interface to manage power density in data centers. This convergence is compressing the addressable market for discrete component vendors while expanding value capture by semiconductor foundries.
Japan's METI has aligned domestic JIS standards with IEC 62769 for field device integration, accelerating interoperability testing for optical sensors in process automation. Manufacturers must now certify against both national and international protocols before shipment, adding documentation overhead. The pharmaceutical and fine chemicals sectors are most affected, as batch records require traceable sensor calibration chains.
Specification consolidation among automotive Tier-1 suppliers is compressing the qualified vendor list for LiDAR photodetectors from fifteen to four dominant sources. Procurement teams now demand automotive SPICE Level 3 process evidence and on-site failure analysis capability as table stakes. This concentration is most visible in Germany's automotive supply chain, where KBA type-approval requirements reinforce supplier stickiness through validation cost amortization.
Optical Sensor Market Segmentation
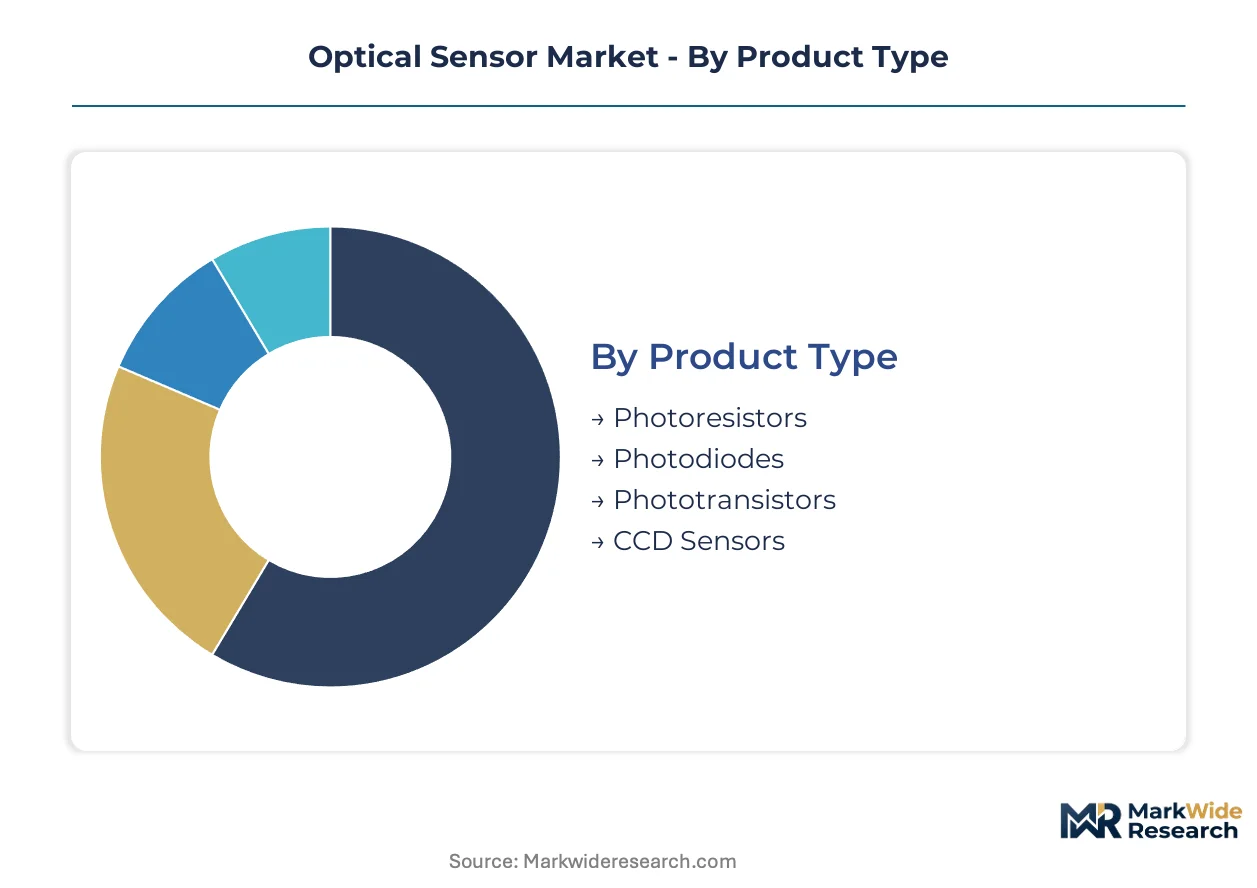
Optical sensor procurement patterns diverge sharply across technical specifications and deployment environments. Capital allocation decisions favor segments with proven reliability in safety-critical systems while emerging applications reshape supplier qualification criteria.
Product Type:
Photodiode arrays and CCD architectures demand the heaviest frontend investment in cleanroom fabrication and precision lithography equipment.
- Photodiodes:Silicon and III-V compound semiconductor junctions convert incident photons to photocurrent with quantum efficiency exceeding 80% in visible wavelengths. Automotive LiDAR modules in Germany's KBA-regulated supply chain specify avalanche photodiodes with sub-nanosecond response times for collision avoidance systems.
- CCD Sensors:Charge-coupled devices transfer photogenerated charge through sequential clocking across MOS capacitor arrays. Machine vision installations in Japan's precision manufacturing sector favor interline-transfer CCDs for their global shutter capability in high-speed inspection lines.
- Photoresistors:Cadmium sulfide thin-film devices exhibit photoconductive gain through trap-state modulation of carrier lifetime.
- Phototransistors:Bipolar junction structures integrate photodetection with internal current amplification for ambient light sensing in consumer displays.
Photodiodes absorb the bulk of installed capacity; CCD sensors are expanding most quickly in industrial imaging applications.
Application:
Volume concentration varies by certification burden, with medical and automotive segments requiring the most extensive compliance documentation.
- Automotive Safety:LiDAR, camera-based ADAS, and cabin monitoring systems integrate multi-spectral optical sensors under ISO 26262 functional safety mandates. EU type-approval processes through Germany's KBA enforce ASIL-D traceability for photodetectors used in autonomous emergency braking.
- Medical Devices:Pulse oximetry, endoscopic imaging, and optical coherence tomography demand biocompatible packaging and FDA 510(k) clearance. Blood glucose monitoring patches in the United States require IEC 60601-1-2 electromagnetic compatibility certification for home use.
- Consumer Electronics:Smartphone cameras and wearable fitness trackers drive high-volume procurement of compact CMOS image sensors.
- Industrial Automation:Position encoders, barcode scanners, and robotic guidance systems deploy photoelectric switches in factory floor environments.
Consumer electronics commands the highest unit volumes; automotive safety carries the steepest expansion trajectory as Level 3 autonomy approaches commercial deployment.
Technology:
Interface architecture determines system integration cost, with digital outputs eliminating analog-to-digital converter requirements.
- Digital Sensors:Integrated ADCs and serial communication protocols enable direct microcontroller attachment. Industry 4.0 deployments in Germany's Munich-Jena corridor specify IO-Link or EtherCAT-compatible optical sensors for real-time process data exchange.
- Active Sensors:Built-in LED or laser sources provide self-illumination for reflective or through-beam detection modes. Smart home occupancy systems in Japan's METI-subsidized deployments favor active infrared sensors for reliable detection independent of ambient lighting.
- Analog Sensors:Continuous voltage or current outputs persist in legacy 4-20mA industrial control loops.
- Passive Sensors:Ambient light-dependent resistors and photodiodes without onboard electronics serve cost-sensitive applications.
Analog sensors retain the largest installed base; digital sensors are gaining share fastest as retrofit cycles refresh aging fieldbus infrastructure.
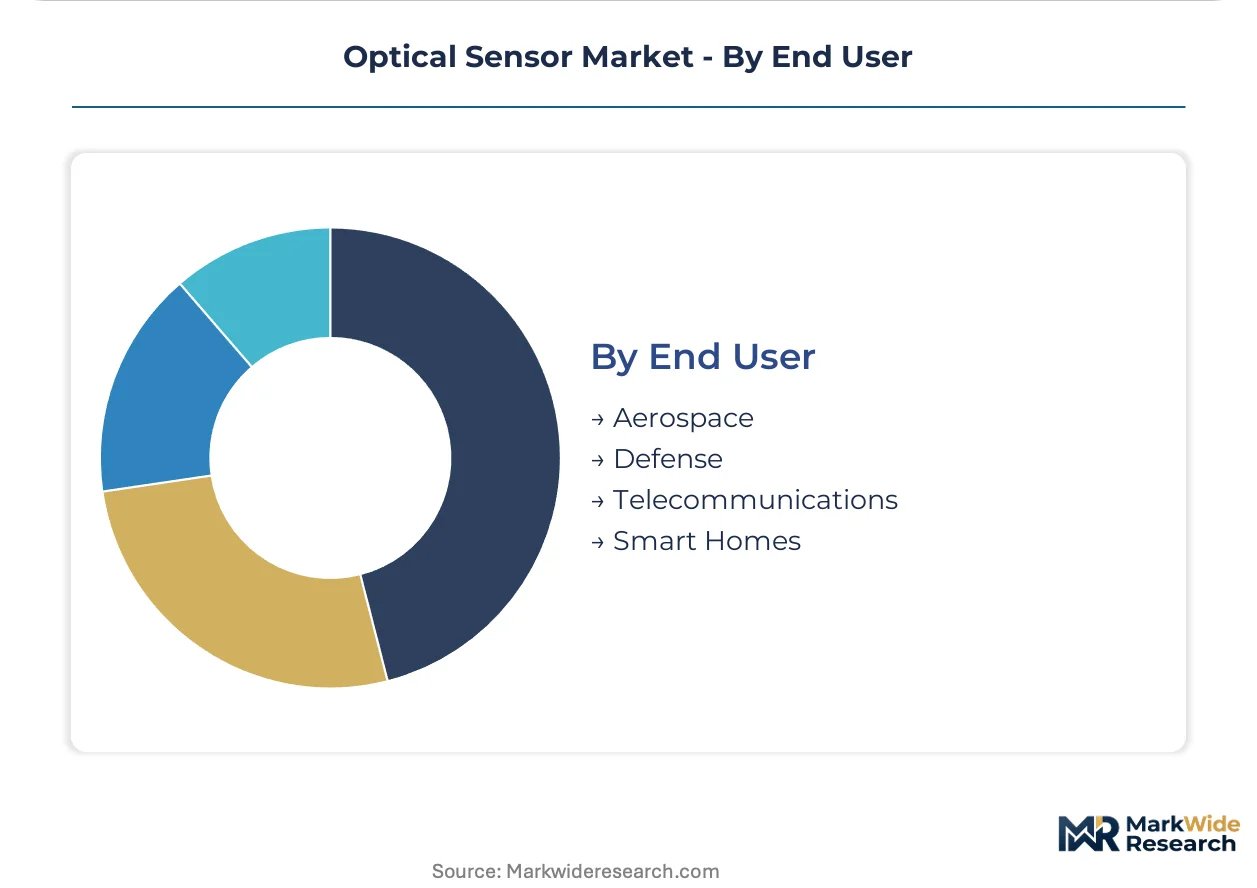
End User:
Procurement sophistication escalates with mission-criticality, from commercial specifications in telecommunications to hardened requirements in defense.
- Defense:Night vision goggles, laser rangefinders, and missile seeker heads specify InGaAs and mercury cadmium telluride detectors with cryogenic cooling. ITAR-controlled supply chains restrict foreign access to focal plane arrays above specified resolution thresholds.
- Aerospace:Star trackers, Earth observation payloads, and cockpit displays demand radiation-hardened photodetectors with qualification heritage from ESA or NASA programs.
- Telecommunications:Fiber optic transceivers and optical switches deploy InP-based photodetectors in data center interconnects.
- Smart Homes:Security cameras, environmental monitors, and voice-activated assistants integrate low-cost ambient light and proximity sensors.
Telecommunications consumes the greatest photodetector volume; defense applications command the highest unit prices and longest qualification cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Indium phosphide and gallium arsenide substrate production concentrates in Japan and Taiwan, anchoring the upstream photodetector supply chain. Germany's precision optics cluster and the United States' automotive safety corridor drive downstream integration demand.
United States
FDA device classification rules govern optical sensors in pulse oximetry and diagnostic imaging equipment, while NHTSA mandates accelerate LiDAR adoption for autonomous emergency braking. The FDA's 510(k) clearance pathways for home-use blood glucose monitors compress development timelines for wearable optical sensors.
Germany
KBA type-approval requirements enforce ASIL-D traceability for automotive LiDAR photodetectors used in Level 3 autonomy systems. The Munich-Jena corridor provides specialized thin-film deposition capabilities that shorten prototype-to-production cycles for next-generation avalanche photodiodes.
Japan
METI promotes domestic optical component manufacturing through JIS standards alignment and clean energy technology subsidies. Hamamatsu anchors premium photodetector production, while METI's alignment of JIS with IEC 62769 accelerates interoperability testing for process automation sensors.
China
MIIT's semiconductor self-sufficiency initiatives target domestic production of III-V compound photodetectors previously imported from Japanese foundries. Yangtze River Delta fabs are expanding InGaAs wafer capacity to serve fiber optic transceiver demand in data center interconnects.
India
PLI scheme production-linked incentives attract optical component assembly operations to serve domestic smartphone and automotive markets. Karnataka and Tamil Nadu electronics manufacturing clusters are qualifying suppliers for machine vision equipment in electronics assembly lines.
Optical Sensor Market Vendor Landscape
Capacity expansion dominates the current landscape as photodetector foundries add III-V wafer fabrication lines to address automotive LiDAR demand. The market structures around three tiers: vertically integrated semiconductor conglomerates with captive emitter supply, specialized photonics houses with proprietary avalanche photodiode technology, and analog semiconductor vendors extending into integrated optical sensing subsystems. Dominant competitive moves include strategic partnerships between sensor vendors and automotive Tier-1 suppliers, plus backward integration into epitaxial wafer growth to secure indium gallium arsenide substrate supply.
Among European-integrated semiconductor groups, ams-OSRAM AG and STMicroelectronics N.V. occupy positions spanning emitter fabrication through module assembly. Japanese specialists exemplify the premium photodetector tier, with Hamamatsu Photonics K.K. representing proprietary avalanche photodiode expertise. Texas Instruments Incorporated anchors the analog-front-end extension strategy, integrating optical sensing subsystems with established signal conditioning portfolios.
| Leading Market Players |
|---|
| ams-OSRAM AG |
| Hamamatsu Photonics K.K. |
| ON Semiconductor Corp. |
| STMicroelectronics N.V. |
| ROHM Co., Ltd. |
| Sony Group Corporation |
| Broadcom Inc. |
| Texas Instruments Incorporated |
| Keyence Corporation |
| Others |
Supply Flow & Price Mechanics
Silicon photonics integration is compressing photodetector module costs while concentrating fabrication among CMOS-compatible foundries in Taiwan and the United States. This technology transition simultaneously eliminates discrete component assembly steps and tightens supply control among semiconductor conglomerates with captive III-V epitaxy capabilities.
Pricing Analysis
Warranty and calibration service bundling separates automotive LiDAR photodetector pricing from unbundled industrial sensor procurement. Three-tier pricing structure across ASIL-D certified, industrial-grade, and consumer-tier products reflects ISO 26262 compliance investment and volume scale. Pricing pressure stems from silicon photomultiplier substitution in medical imaging, forcing avalanche photodiode vendors to absorb qualification cost amortization. Consumer electronics buyers exhibit highest price sensitivity; defense contractors accept longest lead times for ITAR-controlled InGaAs focal plane arrays.
Supply Chain Analysis
Indium phosphide and gallium arsenide substrate supply rests on Japanese and Taiwanese specialty foundries with limited III-V wafer expansion. German precision optics clusters and Chinese Yangtze River Delta fabs draw from this concentrated upstream, processing raw wafers into photodiode arrays and LiDAR modules. Single-source vulnerability in InGaAs substrate production exposes automotive and telecommunications segments to allocation risk during capacity constraints. Distribution runs through direct-to-OEM channels for automotive Tier-1 suppliers, bypassing traditional component distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where control over indium gallium arsenide epitaxy and avalanche photodiode fabrication determines margin capture. Players are pursuing backward integration into III-V wafer growth to secure substrate supply against Japanese and Taiwanese foundry concentration.
For Market Incumbents: Cement supply position by securing long-term indium gallium arsenide wafer offtake agreements with Japanese foundries before Chinese MIIT-subsidized domestic capacity reaches qualification. Expand Munich-Jena corridor cleanroom footprint to capture automotive LiDAR prototype-to-production acceleration. Silicon photomultiplier substitution in medical imaging demands accelerated R&D investment in single-photon avalanche diode performance to defend premium positioning. For New Entrants and Emerging Players: Automotive Tier-2 suppliers represent the most penetrable channel partner type for photodiode array vendors lacking ASIL-D heritage. Target India's PLI-subsidized electronics manufacturing clusters in Karnataka and Tamil Nadu for optical component assembly partnerships serving domestic smartphone and automotive markets. Machine vision equipment for electronics assembly lines offers white-space entry with lower certification burden than medical or automotive safety segments. For Investors and Strategic Acquirers: Exit pathways concentrate in acquisition by vertically integrated semiconductor conglomerates seeking III-V photodetector capabilities. Long-term viability favors targets with proprietary avalanche photodiode technology and established relationships with Germany's KBA type-approval ecosystem. Watch for silicon photomultiplier performance breakthroughs in LiDAR receiver sensitivity as the inflection signal threatening incumbent photodetector valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into III-V Epitaxy | Captive indium gallium arsenide wafer supply insulates against Japanese foundry allocation constraints. |
| Automotive SPICE Level 3 Certification | Process documentation satisfies Germany's KBA type-approval requirements for LiDAR photodetector qualification. |
| Direct-to-OEM Channel Development | Bypassing distributors captures calibration service revenue from industrial automation equipment makers. |
| Silicon Photonics Co-Packaging Partnership | Integration with hyperscaler switch-ASIC interfaces expands addressable market beyond discrete components. |
| India PLI Scheme Manufacturing Entry | Karnataka and Tamil Nadu assembly operations access domestic smartphone and automotive demand growth. |
Methodological Framework
SEC 10-K filings, ECHA REACH registration databases, and Japan METI industrial statistics formed the secondary backbone for supply chain mapping and regulatory timeline reconstruction. Primary interviews with automotive Tier-1 supplier procurement managers, biomedical engineers at FDA-registered device manufacturers, and cleanroom fabrication directors in Germany's Munich-Jena corridor validated capacity expansion plans and qualification bottlenecks. Bottom-up photodetector unit demand estimates from automotive LiDAR and medical imaging applications triangulated against top-down optical sensor market value projections.
Historical trendline analysis of photodiode array pricing and III-V wafer supply capacity informed the forecast framework across the analysis window. Segmentation modeling incorporated product type, application, interface technology, and end-user mission-criticality dimensions. CAGRs derived from shipment volume trajectories in smartphone cameras, machine vision equipment, and automotive safety systems, cross-referenced with capital expenditure disclosures from photodetector foundries.
Several conditions sit outside the modeled scope, including quantum sensing technology commercialization timelines and potential ITAR restriction modifications on InGaAs focal plane arrays. Forecasts reflect assumptions about automotive LiDAR adoption rates and EU MDR conformity assessment duration stability. A small set of named triggers warrants ongoing watch: silicon photomultiplier performance breakthroughs, Chinese MIIT domestic wafer capacity qualification, and F-Gas Regulation phase-down acceleration affecting precision optics thermal management.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
LGP (Light Guide Plate) for TV Market
Optical Components
CMP Polishing Machine Market
Optical Components
Mobile Optical Pluggable Market
Optical Components
Duplication Disc Market
Optical Components
Global Transparent Quartz Tube Market
Optical Components
Europe Tunable Laser Market
Optical Components
CW Fiber Amplifier Market
Optical Components
Optical Time-Domain Reflectometer Market
Optical Components
Raman Amplifier Market
Optical Components
Europe Eye Tracking Solutions Market
Optical Components
Asia Pacific Optical Sensors Market
Optical Components
Machine Vision Light Source Market
Optical Components
Terbium Gallium Garnet Market
Optical Components
Passive Optical Component Market
Optical Components
Infrared Filter Market
Optical Components
Global Mask Alignment Systems Market