
 IR Emitter and Receiver Market | 2026-2036
IR Emitter and Receiver Market Size, Share, and Industry Trends Forecast 2026-2036
IR Emitter and Receiver Market Foresight
Asset-light leasing models for cleanroom and epitaxial growth capacity are tilting competitive dynamics toward fabless designers with strong IP portfolios. Excelitas Technologies leverages captive crystal growth and vertical packaging to sustain margin control across defense and medical verticals. Hamamatsu Photonics anchors its position through deep vertical integration in compound semiconductor substrates. Texas Instruments competes by embedding infrared front-ends within broader sensor-fusion silicon platforms.
IR emitters and receivers are optoelectronic devices that convert electrical signals into infrared radiation and vice versa, typically operating at wavelengths from 700 nanometers to 1 millimeter using III-V semiconductor materials such as gallium arsenide or indium gallium arsenide. Their primary commercial purpose is enabling non-contact sensing, optical communication, and thermal detection across industrial and consumer systems. Photodetector segments command premium pricing in automotive LiDAR and spectroscopy where signal-to-noise thresholds are stringent. LED-based transmitter categories dominate volume in consumer remote control and home automation applications where cost sensitivity shapes procurement. Wireless infrared technology retains niche strength in secure short-range data transmission where electromagnetic interference must be avoided.
The FDA governs medical device applications of infrared emitters in pulse oximetry and thermal imaging, while the FCC regulates spectrum use for wireless infrared data links in commercial equipment. REACH and RoHS frameworks in Europe restrict hazardous substances in optoelectronic manufacturing, directly influencing material selection and supplier qualification. Japan's METI drives standardization through JIS certification for industrial infrared sensors. Stakeholders must monitor evolving automotive safety mandates and material compliance deadlines to align product roadmaps with certifiable specifications.
Market Dynamics
Automotive OEMs are consolidating infrared sensing architectures into unified domain controllers, compressing discrete component procurement while elevating performance requirements for integrated emitter-receiver modules.
Growth Catalysts
- EU F-Gas Regulation:Phase-down of fluorinated greenhouse gases accelerates replacement of legacy thermal imaging gases with solid-state IR alternatives in industrial leak detection systems.
- Indium gallium arsenide substrates:Extended-wavelength sensitivity in InGaAs photodiodes opens spectroscopy applications for pharmaceutical quality control and food safety screening.
- Germany's precision optoelectronics clusters:Concentrated supplier networks around Munich and Stuttgart reduce qualification cycles for automotive tier-1 infrared module sourcing.
Market Restraints
- Indium price volatility:Primary indium supply concentrates in Chinese smelter operations, creating input cost instability for InGaAs and ITO-coated emitter fabrication.
- Mercury cadmium telluride toxicity:REACH substance restrictions and RoHS exemptions under review threaten long-haul defense and space applications dependent on MCT detectors.
- Silicon photonics substitution:Integrated silicon photonic receivers for short-range LiDAR displace discrete III-V compound receivers in cost-sensitive consumer robotics.
Strategic Opportunities
- India's PLI scheme for electronics:Manufacturing incentives for semiconductor packaging attract IR module assembly capacity to serve domestic automotive and medical device demand.
- Hyperspectral imaging convergence:Fusion of IR emitter arrays with computational spectroscopy creates agricultural crop monitoring applications beyond traditional moisture sensing.
- Japan METI carbon neutrality roadmap:Energy efficiency mandates for industrial processes drive retrofit demand for non-contact thermal monitoring using IR thermopile arrays.
Industry Challenges
- Compound semiconductor process engineers:Talent scarcity in MOCVD epitaxy and wafer-level packaging constrains capacity expansion for automotive-qualified IR emitters.
- AEC-Q102 certification timelines:Extended qualification cycles for automotive photodetectors delay revenue recognition for new emitter-receiver product families.
- Multi-sensor fusion integration:Software complexity in synchronizing IR, visible, and radar data streams stretches OEM validation resources and extends design-win cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | IR Emitter and Receiver Market |
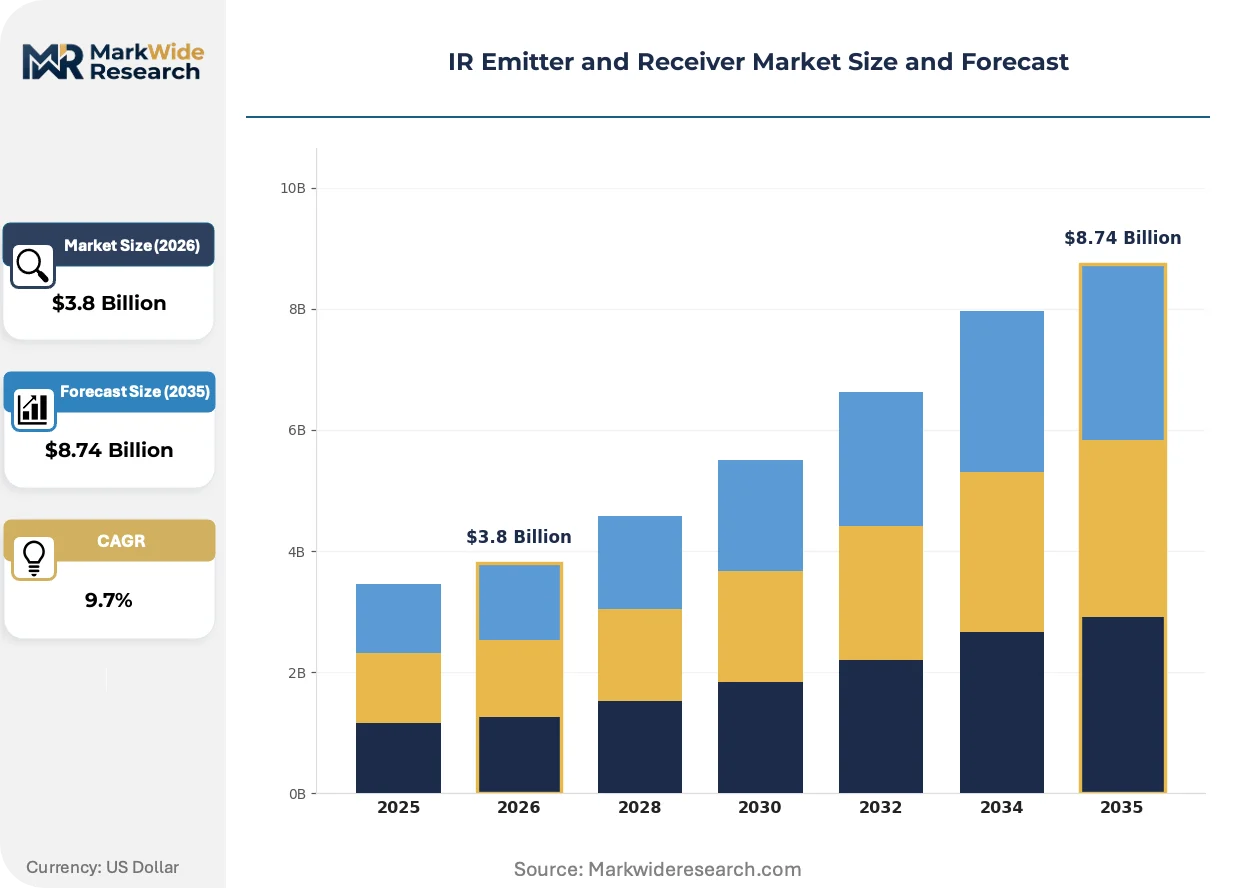
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.74 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: LED, Laser, Photodetector, Transmitter Technology: Analog, Digital, Wireless, Infrared End User: Consumer Electronics, Automotive, Industrial Automation, Security Systems Application: Remote Controls, Gesture Recognition, Data Transmission, Home Automation |
| Companies Covered | Excelitas Technologies, Texas Instruments, Hamamatsu Photonics, Murata Manufacturing, Honeywell International, FLIR Systems, Teledyne Technologies, OSRAM Opto Semiconductors, Leonardo DRS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
IR Emitter and Receiver Market Shifts & Advancements
Digital signal processing at the sensor edge is redefining performance benchmarks, with smart IR modules now embedding calibration algorithms that previously required host processor intervention.
Vertical-cavity surface-emitting laser arrays are digitizing depth-sensing architectures for cabin-monitoring and gesture-recognition systems. Tier-1 automotive suppliers are qualifying multi-junction VCSEL chips at 940 nanometers for driver attention tracking. This digitization is compressing the traditional separation between illumination source and image processing subsystems.
REACH substance restriction proposals on cadmium and lead in optoelectronics are forcing reformulation of quantum dot IR emitters and solder metallizations. Compound semiconductor foundries in Europe are accelerating lead-free die-attach process qualifications. Medical imaging OEMs face the steepest compliance timelines as MDR technical documentation requirements overlap with material transition deadlines.
Subscription-based sensor calibration services are displacing perpetual licensing for industrial IR thermography platforms. German machine builders now bundle predictive maintenance algorithms with emitter-receiver hardware through five-year service agreements. This model is most visible in steel and glass manufacturing verticals where continuous thermal monitoring prevents catastrophic line shutdowns.
IR Emitter and Receiver Market Segmentation
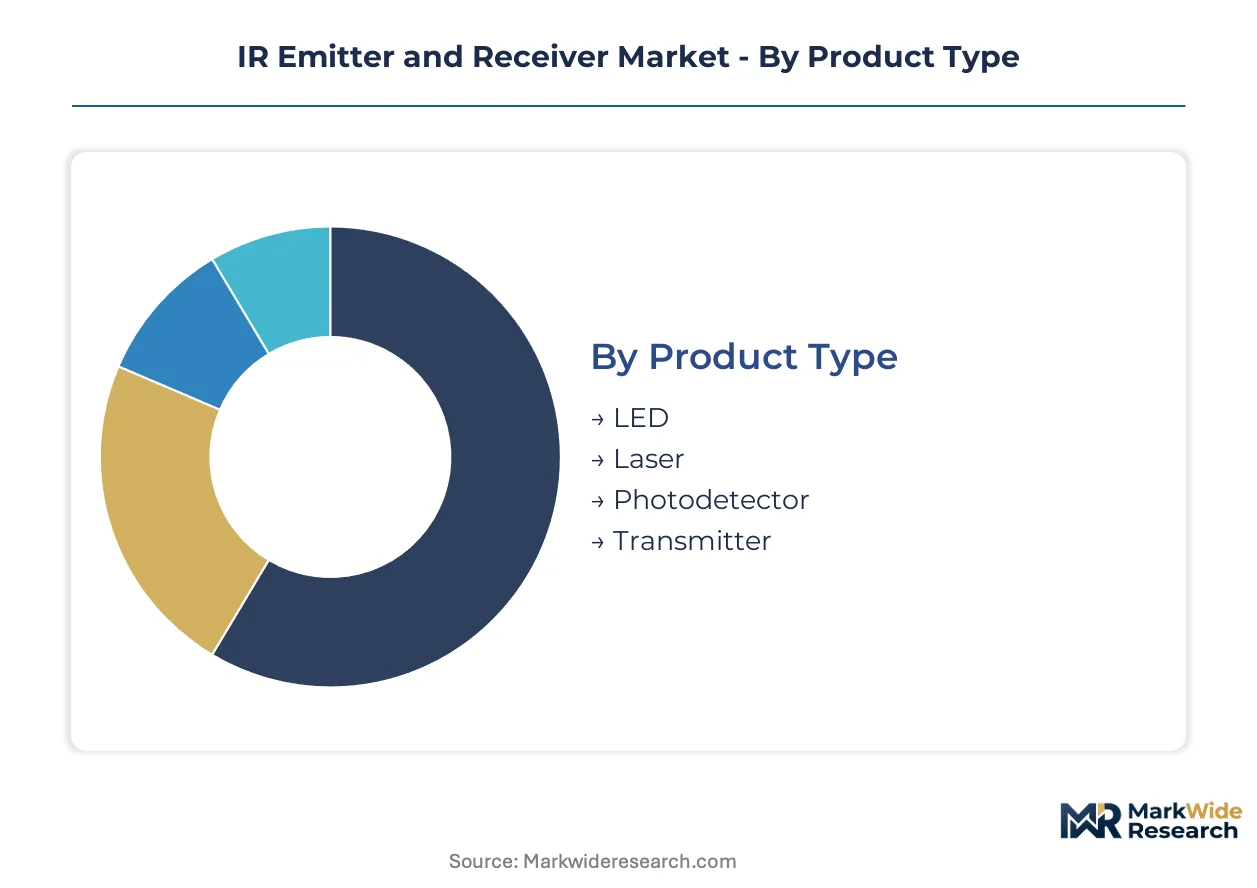
Segmentation in the IR emitter and receiver market reveals divergent procurement cycles across product architectures. LED-based transmitters turn over rapidly in consumer applications, while photodetectors for automotive LiDAR face extended qualification timelines that compress supplier margins.
Product Type:
Cycle times vary dramatically: LED emitters refresh annually in remote control manufacturing, whereas photodetectors for spectroscopy lock in design wins for multi-year programs.
- LED:Solid-state devices utilizing gallium arsenide substrates dominate volume production for short-range illumination. Demand concentrates in China and Mexico for television remote manufacturing, where cost-per-unit thresholds below five cents shape supplier selection.
- Photodetector:PIN and avalanche photodiodes convert infrared radiation into electrical signals with high quantum efficiency. Automotive LiDAR qualification in Germany and Japan drives premium pricing, though AEC-Q102 certification cycles extend eighteen to twenty-four months.
- Laser:Edge-emitting and VCSEL architectures enable precise beam steering for depth sensing.
- Transmitter:Integrated emitter-driver modules simplify system design for OEMs.
LED dominates installed base. Photodetector is where expansion concentrates.
Technology:
Cost tiers separate legacy analog implementations from digital architectures with embedded signal processing capabilities.
- Digital:Smart IR modules incorporate ADCs and calibration algorithms at the sensor edge, reducing host processor burden. Industrial automation in Japan's METI carbon neutrality programs drives retrofit demand for networked thermal monitoring arrays.
- Wireless:Infrared data links operate in unlicensed spectrum bands, avoiding electromagnetic interference in sensitive environments. Secure short-range transmission for military and medical applications in the United States sustains niche procurement despite Bluetooth substitution pressure.
- Analog:Continuous signal output suits simple proximity detection without processing overhead.
- Infrared:Wavelength-specific implementations span near-infrared through thermal bands.
Analog retains legacy volume. Digital is climbing the fastest.
End User:
Application maturity determines margin structure, with consumer electronics commoditized and automotive demanding reliability premiums.
- Automotive:Night-vision systems and cabin-monitoring modules integrate multi-junction VCSEL arrays at 940 nanometers. OEM consolidation around domain controllers in Germany elevates performance requirements for qualified emitter-receiver pairs.
- Industrial Automation:Non-contact temperature measurement and process monitoring deploy thermopile arrays and pyroelectric detectors. India's PLI scheme for electronics manufacturing attracts module assembly capacity serving domestic steel and glass production monitoring.
- Consumer Electronics:Smartphones, tablets, and wearables embed compact proximity sensors.
- Security Systems:Perimeter intrusion detection and surveillance illumination drive bulk infrared LED procurement.
Consumer Electronics dominates installed base. Automotive is gaining share fastest.
Application:
Volume concentration in mature use cases contrasts with emerging gesture and automation interfaces requiring new form factors.
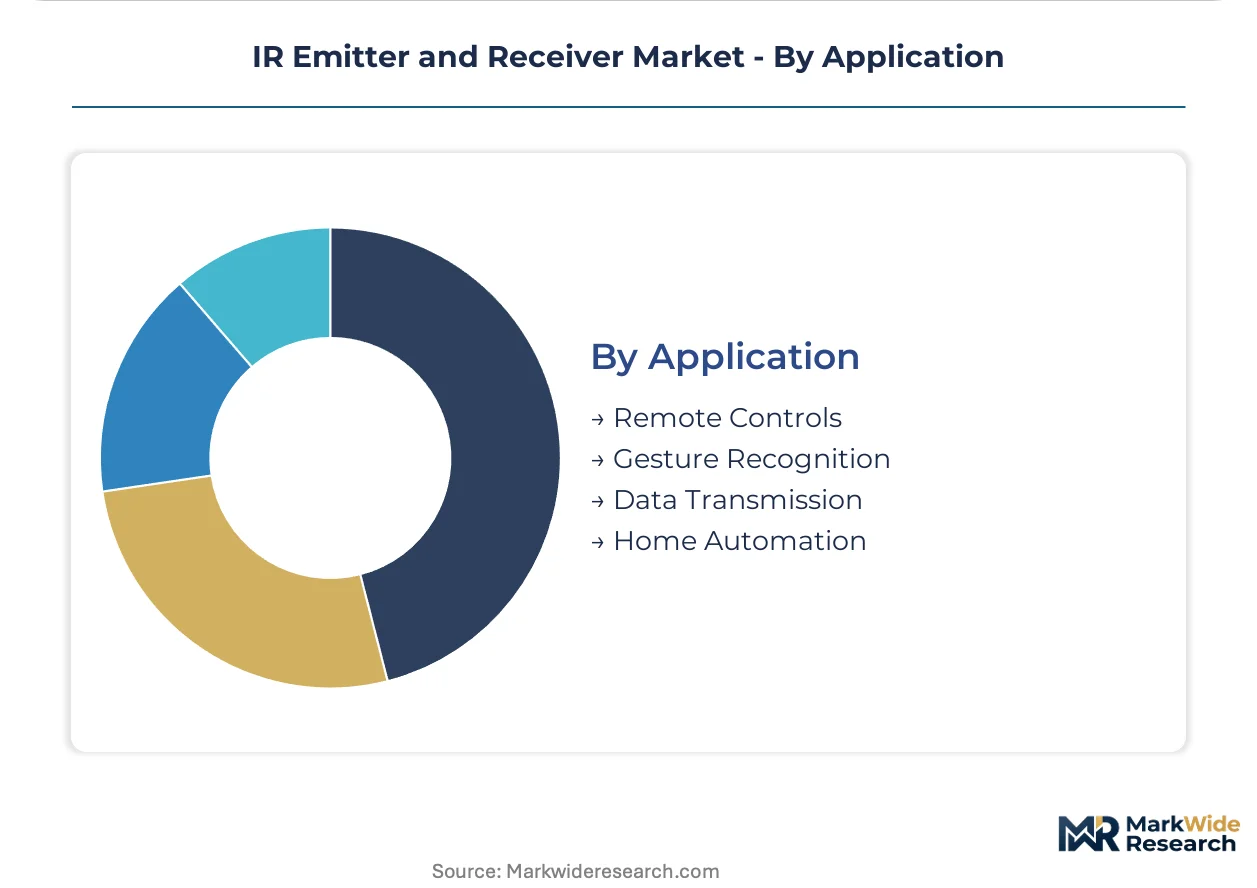
- Gesture Recognition:Time-of-flight and structured light systems interpret hand movements for touchless human-machine interfaces. Automotive tier-1 suppliers in Japan and Germany qualify multi-zone depth sensors for driver attention monitoring.
- Home Automation:Smart lighting, climate control, and occupancy sensing integrate passive infrared motion detectors. Subscription-based calibration services from German machine builders bundle predictive maintenance algorithms with thermopile hardware.
- Remote Controls:Line-of-sight infrared transmission persists in television and set-top box interfaces.
- Data Transmission:IrDA and similar protocols retain deployment in electromagnetic-sensitive environments.
Remote Controls dominates installed base. Gesture Recognition is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's PLI scheme for electronics manufacturing is attracting IR module assembly capacity to serve domestic automotive and medical device demand. Germany's precision optoelectronics clusters around Munich and Stuttgart reduce qualification cycles for automotive tier-1 sourcing. Japan's METI carbon neutrality roadmap drives retrofit demand for industrial thermal monitoring systems.
United States
Automotive OEMs in Detroit and Silicon Valley integrate multi-junction VCSEL arrays for driver attention monitoring systems. The FDA governs medical device applications in pulse oximetry and thermal imaging, while the FCC regulates spectrum use for wireless infrared data links. Defense contractors in Arizona and Massachusetts sustain procurement of mercury cadmium telluride detectors for thermal imaging despite REACH-aligned substance restrictions.
Germany
Machine builders in the Ruhr region bundle predictive maintenance algorithms with thermopile hardware through subscription-based service agreements. The EU F-Gas Regulation accelerates replacement of legacy thermal imaging gases with solid-state IR alternatives in industrial leak detection systems. Stuttgart's automotive tier-1 supplier networks elevate performance requirements for qualified emitter-receiver pairs as OEMs consolidate around domain controllers.
Japan
Industrial automation retrofit programs deploy networked thermal monitoring arrays to meet METI energy efficiency mandates for carbon neutrality. JIS certification standardizes industrial infrared sensor specifications, compressing supplier qualification timelines for domestic OEMs. Nagoya's precision manufacturing corridor concentrates demand for InGaAs photodiodes in pharmaceutical quality control applications.
China
Television remote manufacturing in Guangdong and Jiangsu provinces drives volume demand for gallium arsenide LED emitters below five-cent cost thresholds. Primary indium supply concentrates in Chinese smelter operations, creating input cost instability for InGaAs and ITO-coated emitter fabrication. Shenzhen's consumer electronics ecosystem compresses design cycles for compact proximity sensors in smartphones and wearables.
India
Steel and glass manufacturing verticals in Maharashtra and Gujarat deploy continuous thermal monitoring to prevent catastrophic production line shutdowns. The PLI scheme for electronics manufacturing attracts IR module assembly capacity to serve domestic automotive and medical device demand. Bangalore's medical device OEMs face overlapping compliance timelines from MDR technical documentation and REACH material transition deadlines.
IR Emitter and Receiver Market Competitive Landscape
Channel-controlling players compete with product-specialist players across distinct value capture tiers. Consolidation pressure intensifies as automotive OEMs compress discrete component procurement into unified domain controllers. Three archetypes dominate: vertically integrated compound semiconductor fabricators, fabless designers with strong IP portfolios, and diversified sensor-fusion platform vendors. Capacity expansion in epitaxial growth and strategic partnerships for AEC-Q102 certification acceleration represent the dominant competitive moves.
Among diversified technology conglomerates, Texas Instruments and Honeywell International exemplify platform-scale positioning, while Hamamatsu Photonics occupies a specialist tier in compound semiconductor substrates. Excelitas Technologies represents the vertically integrated archetype through captive crystal growth operations. These three anchors illustrate how competitive positioning stratifies between breadth-driven sensor fusion and depth-driven optoelectronic specialization.
| Leading Market Players |
|---|
| Excelitas Technologies |
| Texas Instruments |
| Hamamatsu Photonics |
| Murata Manufacturing |
| Honeywell International |
| FLIR Systems |
| Teledyne Technologies |
| OSRAM Opto Semiconductors |
| Leonardo DRS |
| Others |
Supply & Pricing Matrix
Indium price volatility from Chinese smelter concentration compresses margin spreads across InGaAs photodetector tiers while forcing supply chain restructuring toward alternative substrate sourcing and inventory buffer strategies.
Pricing Analysis
Certification level creates the primary spread between automotive AEC-Q102-qualified modules and consumer-grade emitters. Pricing stratifies across premium, standard, and economy tiers, with automotive photodetectors commanding reliability premiums while remote-control LEDs face cost compression below five-cent thresholds. Price differentiation reflects qualification timeline burdens and material compliance costs under REACH substance restrictions. Consumer electronics procurement teams exhibit highest price sensitivity, whereas defense contractors absorb premium pricing for mercury cadmium telluride detectors despite regulatory headwinds.
Supply Chain Analysis
Compound semiconductor foundries in Taiwan, Germany, and the United States hold captive epitaxial growth capacity for automotive-qualified emitters. Raw material dependencies center on gallium arsenide substrates, indium metal, and mercury cadmium telluride crystals. Single-source vulnerability concentrates in Chinese indium refining operations, creating input cost instability for InGaAs fabrication. Distribution runs through tier-1 automotive supplier networks in Stuttgart and Nagoya, with direct OEM relationships displacing traditional distributor channels in high-reliability segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Silicon photonics substitution for short-range LiDAR receivers threatens discrete III-V compound market share, requiring incumbents to defend through integration depth and certification moats.
For Market Incumbents: Build AEC-Q102 certification moats through captive epitaxial capacity and accelerated qualification pipelines. Backward integration into indium gallium arsenide substrate production reduces exposure to Chinese smelter volatility. Channel control through long-term automotive platform agreements locks out silicon photonics substitutes in safety-critical cabin-monitoring applications. For New Entrants and Emerging Players: India's underpenetrated medical device module assembly offers white-space entry under PLI manufacturing incentives. Agricultural hyperspectral imaging convergence creates application expansion beyond traditional moisture sensing. Target steel and glass manufacturing verticals in Maharashtra with subscription-calibration service bundling to bypass entrenched German machine builder relationships. For Investors and Strategic Acquirers: EU F-Gas Regulation phase-down deadlines reshape the acquisition landscape toward solid-state IR alternatives in industrial leak detection. Five-to-ten year viability favors fabless designers with strong IP portfolios over capital-intensive crystal growth operations. Monitor indium price trajectories and REACH cadmium restriction timelines as inflection signals for MCT-dependent defense asset repricing.| Strategic Initiative | Industry Significance |
|---|---|
| AEC-Q102 Certification Acceleration | Shortens eighteen-month automotive qualification cycles for new emitter-receiver families. |
| Lead-Free Die-Attach Process Qualification | Aligns compound semiconductor packaging with REACH substance restriction timelines. |
| Subscription-Based Calibration Services | German machine builders bundle predictive maintenance algorithms with thermopile hardware. |
| India PLI Module Assembly Investment | Captures domestic automotive and medical device demand under manufacturing incentives. |
| VCSEL Array Platform Standardization | Multi-junction 940nm chips consolidate driver attention monitoring architectures. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with automotive tier-1 procurement managers, compound semiconductor process engineers, medical device regulatory affairs leads, and industrial automation system integrators. Secondary validation drew from SEC 10-K filings, EU ECHA substance restriction proposals, METI carbon neutrality program disclosures, and customs trade data for indium and gallium arsenide flows. Bottom-up segment sizing triangulated against top-down industry association aggregates.
Calibration against historical capacity expansion patterns and regulatory compliance cost trajectories anchored projections across the analysis window. Segmentation dimensions modeled include product architecture, certification tier, end-use vertical, and regional production cluster. CAGRs derived from elasticity-adjusted demand curves incorporating automotive OEM platform consolidation and material substitution timelines. Industry-specific inputs encompassed AEC-Q102 qualification velocity and REACH substance restriction implementation schedules.
The forecast holds incumbent behavior within observed patterns; aggressive moves by silicon photonics foundries or Chinese indium traders would shift outcomes beyond modeled ranges. Quarterly review of automotive platform award announcements and EU regulatory exemption renewal decisions is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Sensors and Controls
Piezoelectric MEMS Resonators Market
Sensors and Controls
Thermistor Market
Sensors and Controls
Oxygen Gas Sensors Market
Sensors and Controls
Silicon-Based Fingerprint Sensors Market
Sensors and Controls
Timing Device Market
Sensors and Controls
Distributed Acoustic Sensing (DAS) Market
Sensors and Controls
Piezoelectric Materials Market
Sensors and Controls
RFID Reader Market
Sensors and Controls
Safety Laser Scanner Market
Sensors and Controls
Microsensor Market
Sensors and Controls
Digital Thermometer Market
Sensors and Controls
Asia-Pacific Electric Vehicle Sensor Market
Sensors and Controls
North America Turbomachinery Control Systems Market
Sensors and Controls
Wireless Sensor Tags Market
Sensors and Controls
Japan Digital Thermometer Market
Sensors and Controls
Pressure Transducer Market