
 Pancake Optical Module Market | 2026-2036
Pancake Optical Module Market Size, Share, and Industry Trends Forecast 2026-2036
Pancake Optical Module Market Insights
Premium-grade pancake optical modules with sub-20mm effective focal lengths is redrawing competitive boundaries in compact VR optics. Largan Precision leverages its lens molding expertise to anchor supply for next-generation headsets. Sony differentiates through proprietary stacked-lens architectures that sustain image fidelity at reduced thickness.
Pancake optical modules compress light paths through polarized beam splitters and quarter-wave plates to achieve sub-25mm form factors, replacing conventional Fresnel lens assemblies in head-mounted displays. High-speed product variants command margin pools as VR refresh rates climb toward 120Hz, while fiber optic technology leads data transmission applications where signal integrity outweighs cost sensitivity. Modular designs are gaining traction in automotive HUD prototyping, though telecommunication end users still dominate volume procurement for optical networking infrastructure.
FCC equipment authorization rules shape electromagnetic compatibility thresholds for consumer electronics deployment in the United States, while China's MIIT enforces GB standards on optical transmission performance for domestic VR supply chains. The EU's RoHS and REACH frameworks restrict hazardous substances in lens coatings and adhesive layers, forcing reformulation of polarizer films. Stakeholders must monitor how regional certification divergence affects module interchangeability across OEM programs.
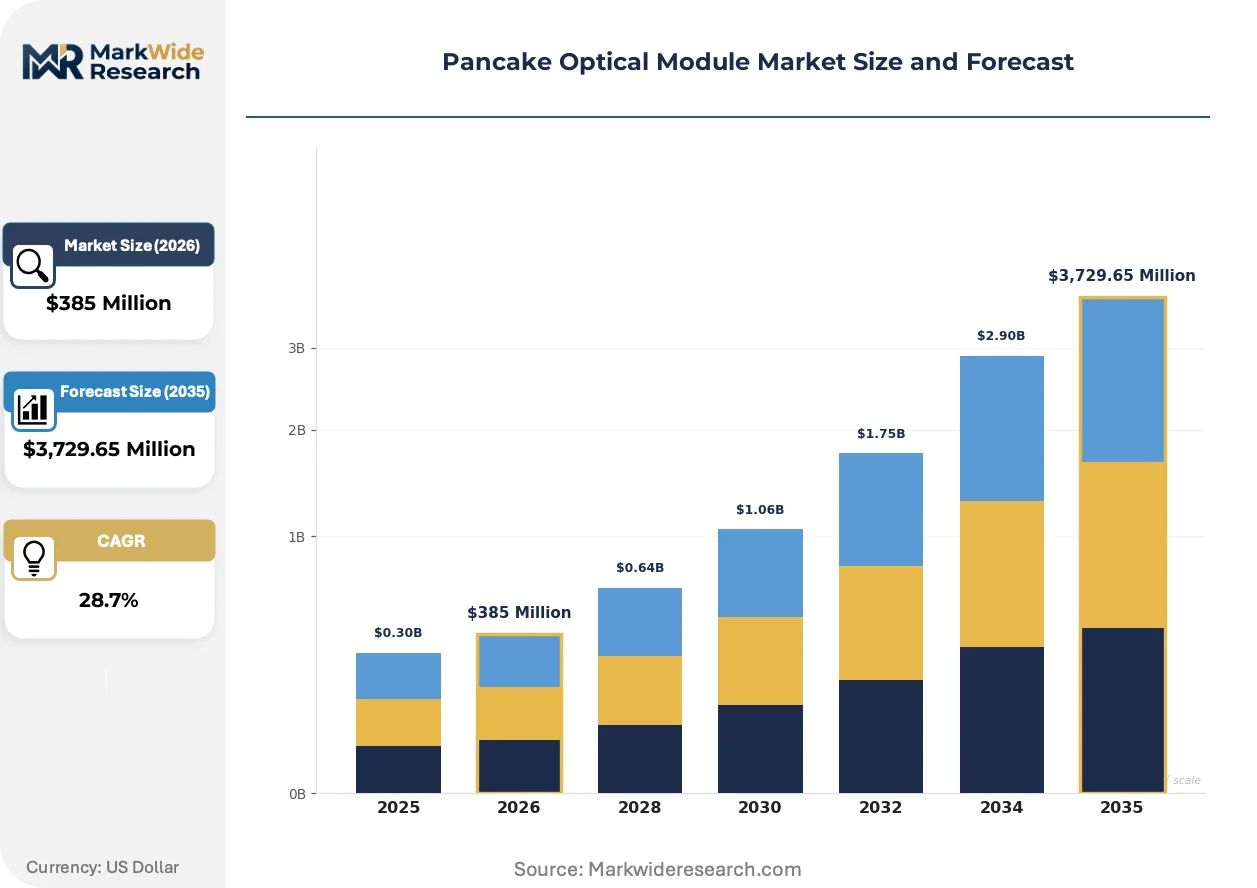
Market Dynamics
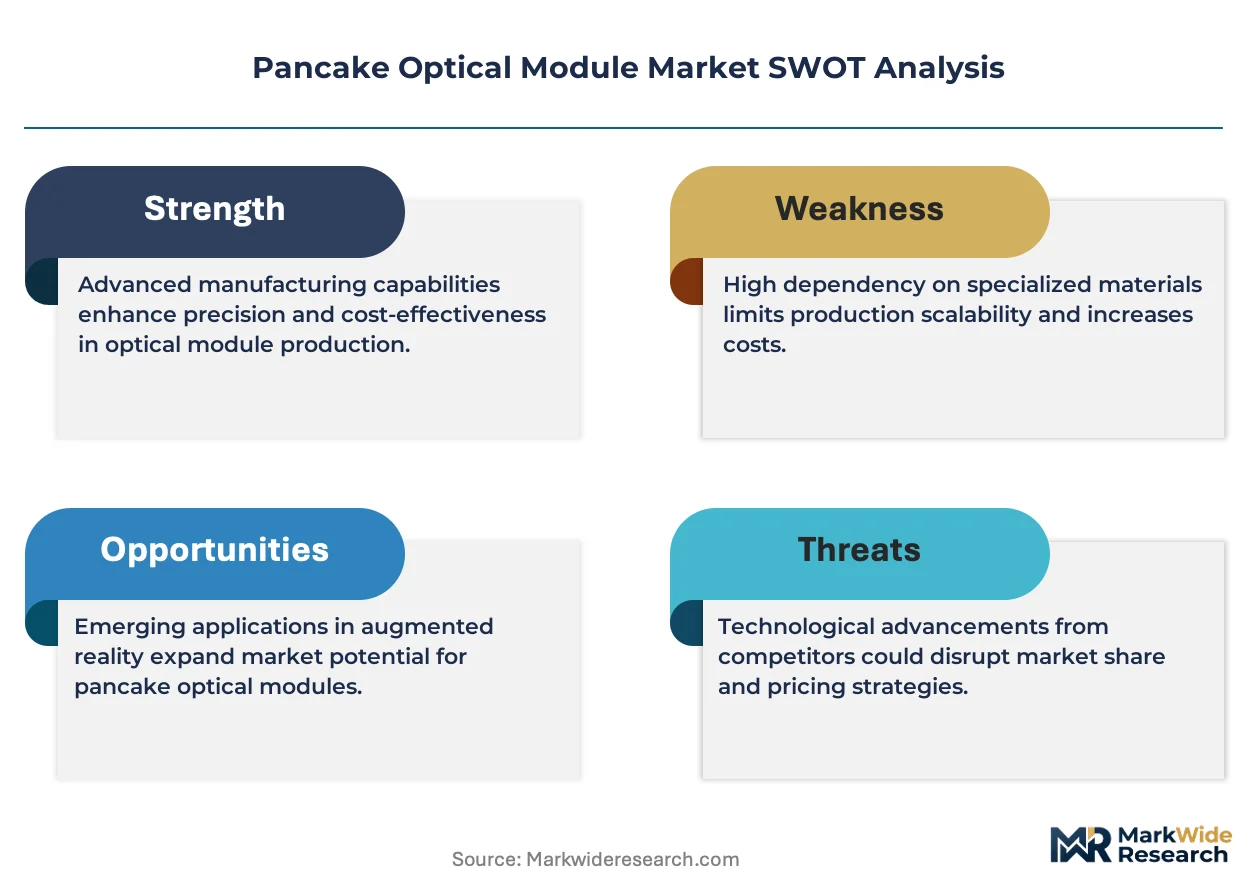
VR headset manufacturers are compressing optical stack thickness below 20mm, forcing module suppliers to reconfigure polarized beam splitter architectures and quarter-wave plate laminations at unprecedented yield rates.
Growth Catalysts
- MIIT GB Standards:China's tightened optical transmission performance mandates for domestic VR supply chains are accelerating qualification cycles for certified module suppliers.
- Fresnel Displacement:Polarized beam splitter assemblies are replacing conventional Fresnel lens architectures in head-mounted displays, opening retrofit opportunities across installed VR bases.
- Shenzhen Manufacturing Corridor:Demand concentration in this electronics cluster is pulling module assembly capacity toward integrated polarizer film and adhesive layer production.
Market Restraints
- Polarizer Film Supply Concentration:RoHS and REACH restrictions on hazardous substances in lens coatings have reduced qualified adhesive formulation suppliers to a handful of European and Asian specialty chemical producers.
- Quarter-Wave Plate Yield Volatility:Sub-micron thickness tolerances in retarder films generate scrap rates above 30% at current manufacturing scales.
- Fiber Optic Substitution:Data transmission applications requiring extreme signal integrity are bypassing pancake modules entirely for direct fiber coupling in high-end simulation systems.
Strategic Opportunities
- Automotive HUD Prototyping:Modular pancake designs are penetrating windshield projection systems as Tier 1 suppliers validate compact optical paths for augmented driving displays.
- 120Hz Refresh Rate Tier:High-speed product variants command margin pools as VR refresh specifications climb, separating performance-tier suppliers from commodity module assemblers.
- FCC Equipment Authorization Alignment:Electromagnetic compatibility thresholds for US consumer electronics deployment are creating certification arbitrage for pre-tested module platforms.
Industry Challenges
- Optical Metrology Talent Scarcity:Sub-20mm effective focal length characterization requires specialized interferometry expertise that module houses struggle to staff at volume.
- Stacked-Lens IP Licensing:Proprietary multi-element architectures from incumbent patent holders create royalty friction for new entrants designing competing thin-form-factor solutions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Pancake Optical Module Market |
| Market Size in 2026 | $385 Million |
| Market Size in 2035 | $3,729.65 Million |
| CAGR (2026 – 2036) | 28.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: High-Speed, Standard, Miniature, Modular Technology: Fiber Optic, Lenses, Sensors, Connectors End User: Telecommunication, Consumer Electronics, Automotive, Aerospace Application: Data Transmission, Imaging Systems, Signal Processing, Networking |
| Companies Covered | Largan Precision, Sunny Optical Technology, Hoya Corporation, Canon Inc., Goertek Inc., Meta, Apple, Samsung, Sony, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Pancake Optical Module Market Trends and Innovations
Optical path compression is redrawing module architecture, with polarized beam splitter configurations displacing refractive designs while regulatory frameworks fragment certification requirements across major VR markets.
Polarized beam splitter cubes with dielectric thin-film coatings are miniaturizing light paths through total internal reflection at 45-degree incidence angles. VR original equipment manufacturers in Shenzhen and Taipei are qualifying these stacks for 2024-2025 headset refreshes. The technology is miniaturizing form factors while maintaining optical efficiency above 85%.
REACH Annex XVII restrictions on halogenated flame retardants in optical adhesives are forcing reformulation of polarizer film bonding layers. European module suppliers are switching to silicone-based alternatives with 18-month validation timelines. Automotive HUD prototyping programs are most affected, as thermal cycling requirements exceed consumer VR specifications.
Buyers are consolidating procurement around vertically integrated module suppliers capable of in-house polarizer film lamination and quarter-wave plate retarder fabrication. Direct sourcing from lens molding houses is displacing merchant optical component distributors in North American and East Asian supply chains. This concentration is most visible in Meta's and ByteDance's supplier qualification pipelines.
Pancake Optical Module Market Segmentation
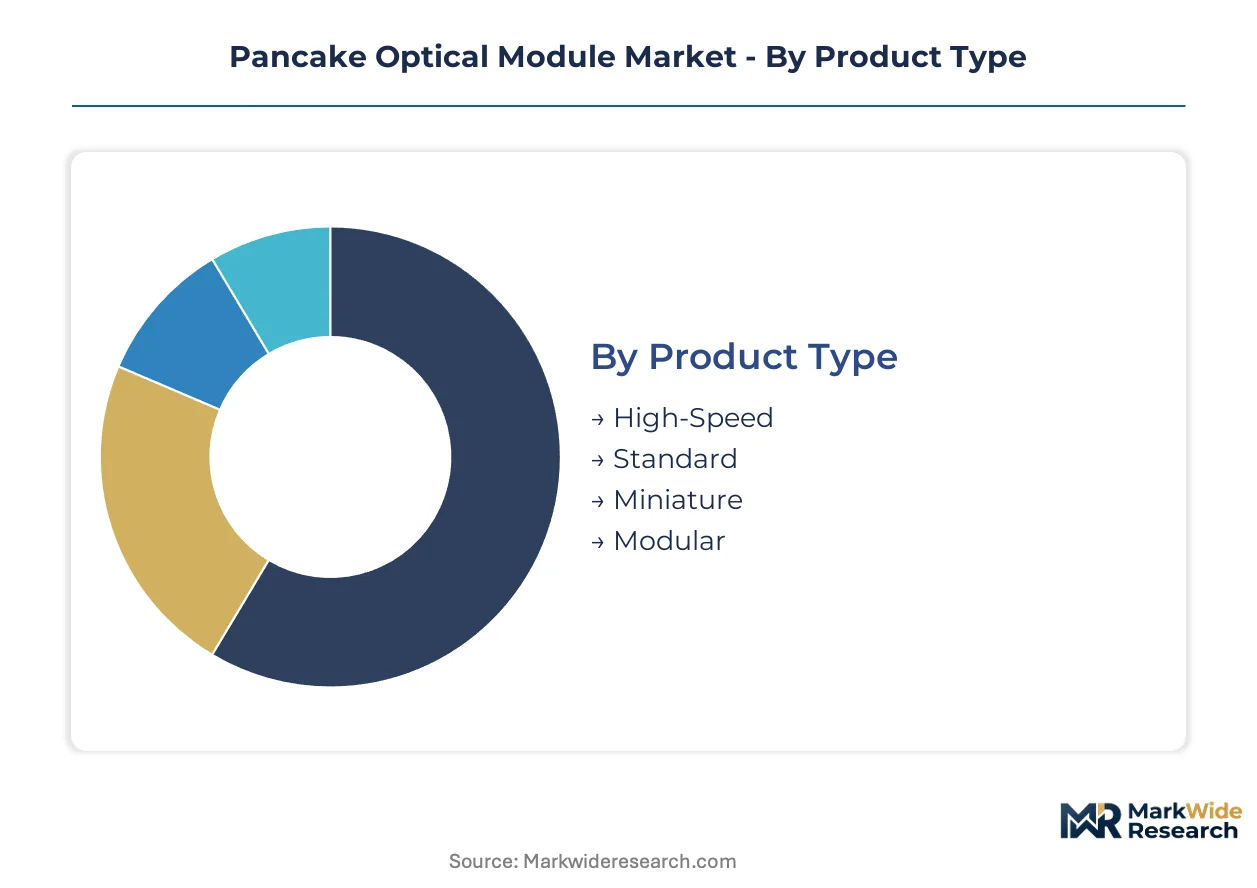
Segmentation in the pancake optical module market reveals how margin pools concentrate around performance tiers and application complexity. Suppliers configure production lines differently for consumer VR volumes versus aerospace qualification requirements.
Product Type:
Margin pools concentrate in high-speed variants where refresh rate specifications above 90Hz command premium positioning against standard modules.
- High-Speed:Engineered for 120Hz refresh rates with sub-20ms motion-to-photon latency. Meta and ByteDance procurement pipelines in Shenzhen are scaling orders for VR headset integration where thermal management challenges limit supplier qualification.
- Standard:Conventional 60-90Hz configurations serving installed base retrofits and cost-sensitive headset programs. Yield rates above 85% at Taiwanese lens molding houses sustain volume economics for mid-tier VR manufacturers.
- Miniature:Sub-15mm optical stacks for smart glasses and compact AR devices. Sony and Apple supplier ecosystems in Japan and California are validating these form factors for wearable deployment.
- Modular:Interchangeable polarizer film and quarter-wave plate assemblies enabling field serviceability. Automotive HUD prototyping programs in Stuttgart and Detroit favor this architecture for thermal cycling resilience.
The dominant share belongs to Standard modules, while High-Speed is closing the gap fastest as refresh specifications climb across flagship VR programs.
Technology:
Technology selection tracks application-specific tradeoffs between signal integrity requirements and form factor constraints.
- Fiber Optic:Direct light coupling for simulation systems demanding zero electromagnetic interference. High-end military training installations and medical imaging suites bypass pancake architectures entirely for pure fiber transmission paths.
- Lenses:Molded aspheric elements with dielectric coatings compressing optical paths through total internal reflection. Largan Precision and Chinese lens houses in Dongguan dominate polarized beam splitter cube supply for 2024-2025 headset refreshes.
- Sensors:Integrated photodetector arrays for eye-tracking and foveated rendering subsystems. Meta's Quest Pro and ByteDance's Pico 4 Enterprise integrate these modules for dynamic resolution scaling.
- Connectors:High-density electrical and optical interfaces linking pancake stacks to display driver boards. MIIT GB standards on optical transmission performance are tightening insertion loss specifications for domestic Chinese supply chains.
Lenses capture the dominant technology share, with Fiber Optic expanding most quickly in simulation and medical segments where signal purity outweighs cost sensitivity.
End User:
End user segmentation maps directly to certification burden and procurement scale, with automotive programs requiring the most extensive validation timelines.
- Telecommunication:Optical networking infrastructure demanding 99.999% reliability in data center interconnects. Huawei and ZTE procurement in Shenzhen concentrates volume for modular designs with field-replaceable polarizer assemblies.
- Consumer Electronics:VR headset manufacturers compressing stack thickness below 20mm for comfort-critical wearable deployment. FCC equipment authorization rules shape electromagnetic compatibility thresholds for US-bound products.
- Automotive:Tier 1 suppliers validating pancake architectures for windshield HUD projection. REACH Annex XVII restrictions on halogenated flame retardants in optical adhesives extend European validation cycles to 18 months.
- Aerospace:Military and commercial aviation applications requiring MIL-STD-810 environmental qualification. Vibration and altitude testing protocols eliminate most commercial module suppliers from this segment.
Consumer Electronics holds the dominant end user position, though Automotive is climbing the fastest as HUD prototyping accelerates across German and Japanese OEM programs.
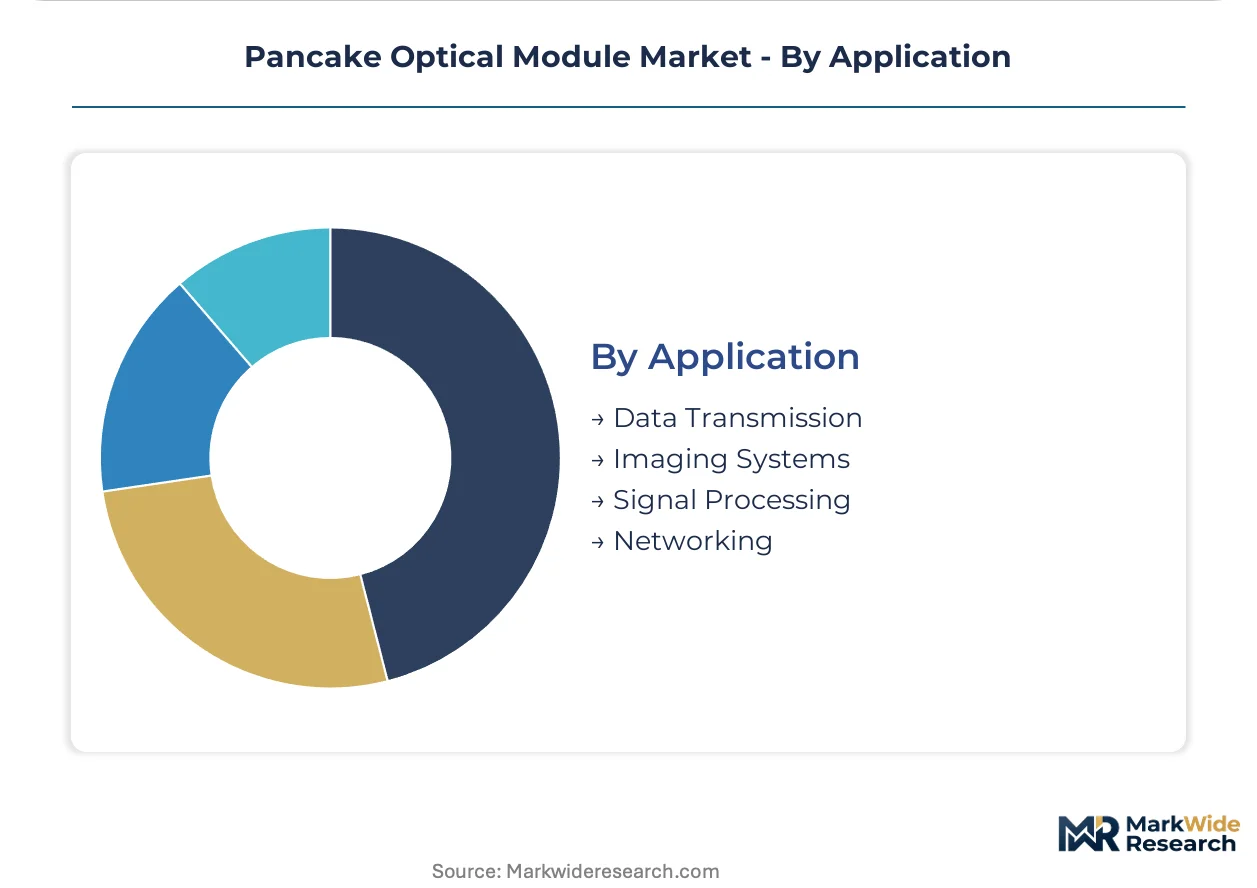
Application:
Application segmentation distinguishes between data-centric deployments where throughput dominates and imaging systems where optical fidelity is paramount.
- Data Transmission:High-bandwidth optical links in telecom switching and data center fabrics. Signal processing requirements above 400Gbps are pushing fiber optic substitution in the highest-performance installations.
- Imaging Systems:VR and AR displays where pancake modules replace Fresnel lens assemblies. Polarized beam splitter configurations achieve 85% optical efficiency while halving headset thickness.
- Signal Processing:Real-time optical computing and photonic integrated circuits. Laboratory deployments at MIT, TU Munich, and Tsinghua University are testing pancake-derived architectures for AI inference acceleration.
- Networking:Enterprise and carrier-grade optical transport equipment. Modular designs with standardized connector interfaces enable multi-vendor interoperability in heterogeneous network deployments.
Imaging Systems command the dominant application share, while Data Transmission is gaining share fastest as telecom infrastructure refresh cycles accelerate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export flows of pancake optical modules tilt heavily toward Asian manufacturing clusters, with import dependency concentrated in North American and European headset assembly operations. Trade balances reflect specialized lens molding capabilities that remain geographically sticky. Currency volatility and logistics costs are redirecting some procurement toward regional qualification programs.
China
MIIT GB standards on optical transmission performance are compressing supplier qualification timelines for domestic VR supply chains. Shenzhen's electronics manufacturing corridor anchors polarizer film lamination and quarter-wave plate fabrication for Meta and ByteDance procurement pipelines. Dongguan lens houses are scaling polarized beam splitter cube output for 2024-2025 headset refreshes.
United States
FCC equipment authorization rules shape electromagnetic compatibility thresholds for consumer electronics deployment, extending validation cycles for imported modules. Meta's Reality Labs and Apple supplier ecosystems in California are qualifying miniature sub-15mm optical stacks for wearable deployment. Seattle-area optical metrology firms are staffing interferometry expertise for sub-20mm effective focal length characterization.
Japan
METI industrial policy supports photonics R&D through public-private partnerships targeting next-generation display optics. Sony's supplier ecosystem in Kansai and Chubu regions validates proprietary stacked-lens architectures for compact VR form factors. Tokyo-based specialty chemical producers are reformulating silicone-based optical adhesives to meet REACH Annex XVII halogen restrictions.
Germany
ECHA REACH restrictions on halogenated flame retardants in optical adhesives extend automotive HUD validation cycles to 18 months. Stuttgart Tier 1 suppliers are prototyping modular pancake designs for windshield projection systems. Bavarian precision optics firms are supplying dielectric thin-film coating equipment to Asian beam splitter manufacturers.
South Korea
MFDS and national standards bodies are aligning optical performance certification with MIIT GB frameworks to ease cross-border component trade. Samsung Display supplier networks in Gyeonggi Province are qualifying high-speed 120Hz module variants for flagship VR programs. Busan-area materials firms are developing retarder films to address quarter-wave plate yield volatility.
Pancake Optical Module Market Competitive Landscape
Listed leaders compete with private specialists across capital access and R&D velocity, creating a tiered structure where scale advantages clash with niche technical depth. The vendor base concentrates around lens molding houses with captive polarizer lamination capabilities and diversified electronics conglomerates with vertical display supply chains. Three archetypes dominate: precision optics pure-plays, integrated headset OEMs, and diversified component conglomerates. Capacity expansion and strategic patent licensing represent the dominant competitive moves as effective focal length specifications tighten.
Among precision optics specialists, Largan Precision and Sunny Optical Technology exemplify the lens molding archetype with established supply relationships to major headset programs. Hoya Corporation anchors the Japanese contingent with heritage in optical materials and coating technologies. These three occupy positions across the premium and standard module tiers, with their geographic dispersion reflecting the regional fragmentation of VR OEM procurement.
| Leading Market Players |
|---|
| Largan Precision |
| Sunny Optical Technology |
| Hoya Corporation |
| Canon Inc. |
| Goertek Inc. |
| Meta |
| Apple |
| Samsung |
| Sony |
| Others |
Pricing and Supply Chain Analysis
Capacity utilization at Dongguan lens molding houses sits above 85% for standard module tiers, compressing price floors for mid-tier VR manufacturers while concentrating margin pools among suppliers with captive polarizer film lamination. This scale asymmetry forces merchant assemblers toward high-speed 120Hz variants where yield volatility and thermal management complexity sustain premium positioning.
Pricing Analysis
Industrial OEM buyers anchor a three-tier pricing structure across premium, standard, and economy levels in the pancake optical module market. Price differentiation hinges on refresh rate certification tiers and volume scale commitments, with high-speed variants commanding substantial premiums over 60-90Hz configurations. Cost compression in standard modules is intensifying because Dongguan lens houses are expanding molding capacity faster than qualification pipelines can absorb. Consumer VR headset manufacturers exhibit the highest price sensitivity, while aerospace and medical simulation buyers prioritize signal integrity over unit economics.
Supply Chain Analysis
Container availability constraints on the Shenzhen-Los Angeles trade lane are extending inbound logistics cycles for North American VR assembly operations. Module supply concentrates in China, Taiwan, and South Korea, with polarized beam splitter cubes and quarter-wave plate retarders forming critical input dependencies. Single-source vulnerability in European specialty chemical supply for REACH-compliant optical adhesives creates qualification bottlenecks for automotive HUD programs. Distribution runs through vertically integrated module suppliers capable of in-house polarizer lamination, displacing merchant optical component distributors in Meta's and ByteDance's procurement pipelines.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The pancake optical module market sits in early-cycle expansion as VR headset manufacturers compress optical stack thickness below 20mm, creating retrofit demand across installed bases and opening adjacent applications in automotive HUD systems.
For Market Incumbents: Fortify polarizer film lamination capabilities through backward integration into quarter-wave plate retarder fabrication, securing yield control as sub-micron thickness tolerances eliminate marginal suppliers. Patent licensing revenue from stacked-lens architectures provides defensive cash flow against emerging entrants with dielectric thin-film coating expertise. Capacity addition in Shenzhen's electronics corridor locks in proximity to Meta and ByteDance qualification pipelines. For New Entrants and Emerging Players: FCC equipment authorization fast-track programs create entry pathways for pre-tested module platforms targeting US-bound consumer electronics deployment. Automotive HUD prototyping in Stuttgart and Detroit offers the most penetrable white space, as 18-month REACH validation cycles deter incumbent VR suppliers from diversifying. A go-to-market angle anchored on modular field-serviceable designs addresses thermal cycling resilience requirements that Tier 1 suppliers prioritize over consumer VR specifications. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among precision optics pure-plays with captive lens molding and polarizer lamination capabilities, as headset OEMs consolidate procurement around vertically integrated suppliers. Long-term viability over a 5-10 year horizon rests on positioning for 120Hz refresh rate tier migration and automotive HUD qualification pipelines. The signal to monitor is quarter-wave plate yield rate improvement at Busan-area materials firms, as sustained progress above 70% would trigger incumbent capacity expansion and compress premium pricing windows.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Retarder Fabrication | Captive quarter-wave plate production at Largan Precision and Sunny Optical insulates margin pools from 30% scrap rate volatility. |
| REACH-Compliant Adhesive Reformulation | Silicone-based bonding layer validation at Tokyo specialty chemical producers unlocks 18-month European automotive HUD procurement cycles. |
| 120Hz High-Speed Module Qualification | Samsung Display supplier networks in Gyeonggi Province are scaling thermal management expertise for flagship VR refresh specifications. |
| Modular Field-Serviceable Design Adoption | Stuttgart Tier 1 suppliers favor interchangeable polarizer assemblies for windshield projection system thermal cycling resilience. |
| FCC Pre-Certification Platform Investment | Pre-tested module platforms reduce electromagnetic compatibility validation friction for US consumer electronics deployment. |
Research Methodology
Cross-validation between procurement director interviews at Shenzhen VR assembly operations and MIIT GB standards documentation anchors the qualitative findings in this study. Primary fieldwork engaged optical metrology specialists, lens molding house operations managers, and Tier 1 automotive supplier engineering leads alongside secondary validation through SEC filings of listed precision optics firms, customs records of polarizer film trade flows, and ECHA REACH Annex XVII regulatory updates. Bottom-up module shipment aggregation and top-down VR headset production estimates were triangulated to constrain forecast variance.
Sensitivity analysis across the projection horizon tested demand elasticity to refresh rate specification changes and regulatory timeline shifts in European adhesive qualification. Segmentation dimensions modeled include product performance tier, technology type, end-user industry, and regional manufacturing cluster. CAGRs were derived from installed base displacement curves for Fresnel lens architectures and adoption rate assumptions for automotive HUD prototyping. Industry-specific inputs incorporated quarter-wave plate yield improvement trajectories and polarizer film lamination capacity expansion schedules.
Decision-makers should treat outputs as directional under sustained VR headset volume growth and stable specialty chemical supply for optical adhesives; material deviation would warrant model refresh. Forecasts reflect assumptions of MIIT GB standard enforcement continuity and REACH Annex XVII restriction stability. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Global Optical Coating Equipment Market
Optical Components
Fiber Optic Plates (FOP) Market
Optical Components
Laser Photomask Market
Optical Components
Optical Component Tester Market
Optical Components
100G Optical Transceivers Market
Optical Components
Europe Optical Imaging Market
Optical Components
Fluorophore Market
Optical Components
Asia Pacific Optical Sensors Market
Optical Components
Global Hybrid Photonic Integrated Circuit Market
Optical Components
Package Shell for Optical Communication Modules Market
Optical Components
US Lithium Niobate Modulator Market
Optical Components
Flip-Chip VCSEL Market
Optical Components
Mexico Extreme Ultraviolet Lithography (EUVL) Systems Market
Optical Components
Global Mask Alignment Systems Market
Optical Components
Fogless Mirror Market
Optical Components
Lithium Niobate Modulator Market