
 Global Tunable Filter Market | 2026-2036
Global Tunable Filter Market Size, Share, and Industry Trends Forecast 2026-2036
Global Tunable Filter Market Outlook
Modular packaging of tunable filter subsystems is recalibrating how telecom equipment buyers evaluate total cost of ownership against discrete component sourcing. Analog Devices leverages its vertically integrated MEMS fabrication to sustain margin advantages across optical and RF filter lines. Qorvo anchors its position through dielectric technology leadership in aerospace-qualified RF filter modules. EXFO competes by specializing in test-grade tunable filters for network validation workflows.
A tunable filter is an electromagnetic or optical device whose passband or rejection band can be electronically or mechanically adjusted across a specified wavelength or frequency range, typically achieving linewidths below 0.1 nm in optical variants and insertion losses under 3 dB in RF implementations. Its primary purpose is to enable dynamic signal selection in environments where fixed-filter banks would require excessive hardware redundancy. Optical filters lead revenue contribution due to fiber optic network densification, while RF filters represent the fastest-expanding margin pool as mmWave spectrum allocations multiply base station filter counts. MEMS technology dominates unit volume through semiconductor-compatible batch fabrication, though liquid crystal approaches occupy premium niches in reconfigurable optical add-drop multiplexers.
FCC spectrum auction rules in the United States, CE marking under the EU Radio Equipment Directive, and MIIT equipment certification in China collectively constrain which filter technologies achieve commercial deployment in each geography. REACH substance restrictions and RoHS lead-free soldering mandates further shape material selection for European-bound products. Stakeholders must monitor pending 6G spectrum harmonization debates across the ITU-R framework to anticipate which filter architectures will secure regulatory pre-approval for next-generation infrastructure cycles.
Market Dynamics
The convergence of 5G mmWave densification and fiber optic network expansion is compressing filter procurement cycles from annual to quarterly rhythms, forcing component suppliers to accelerate qualification pipelines and modularize subsystem architectures.
Growth Catalysts
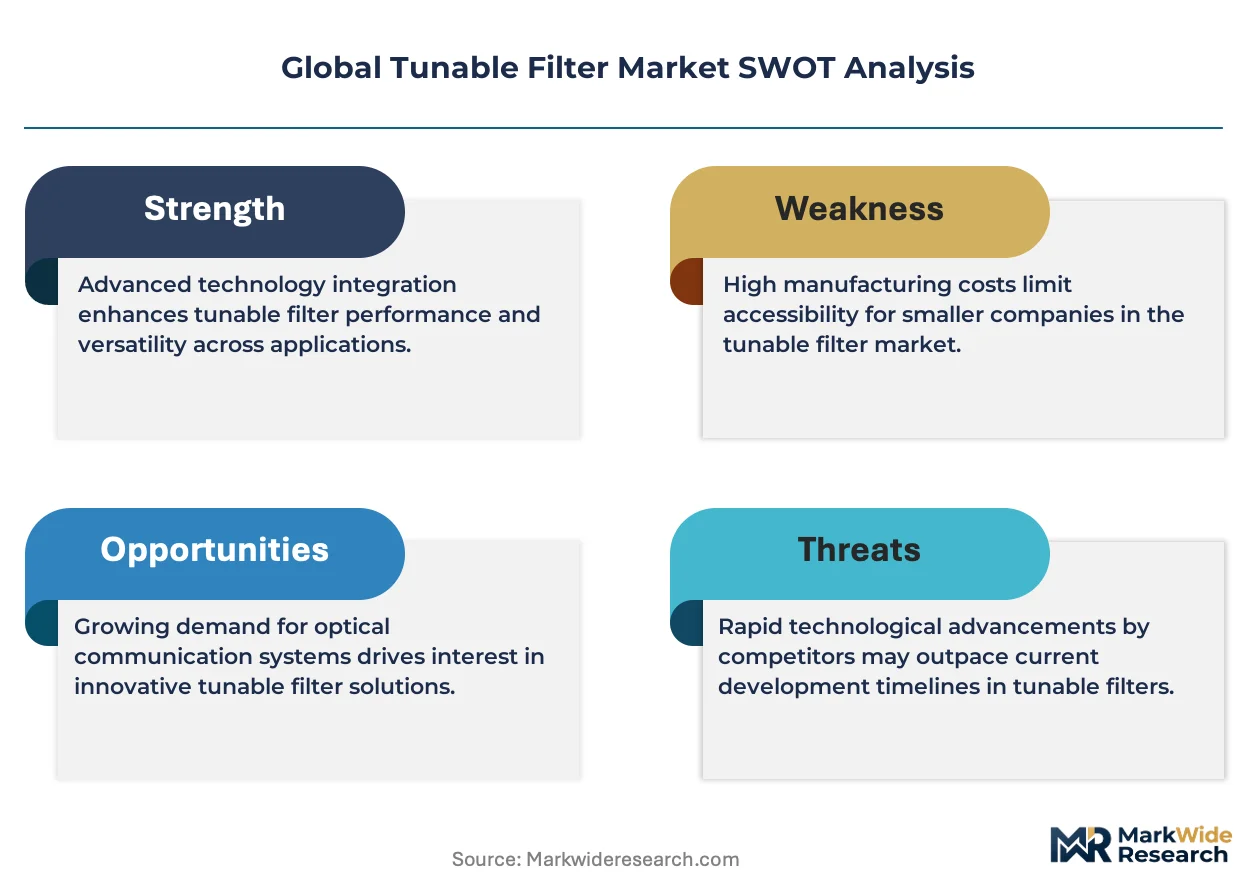
- MIIT Equipment Certification:China's accelerated 5G base station rollout under MIIT mandates is pulling demand for RF tunable filters through domestic OEM procurement channels.
- Data Center Buildouts:Hyperscale facilities in Singapore and Ashburn are deploying reconfigurable optical add-drop multiplexers requiring liquid crystal tunable filters for dynamic wavelength management.
- Semiconductor Batch Fabrication:MEMS-compatible foundry processes are collapsing unit economics for tunable filter production, enabling volume scaling previously restricted to fixed-filter technologies.
Market Restraints
- Indium Phosphide Substrate Costs:Optical filter fabrication depends on constrained III-V semiconductor supply, with InP wafer pricing volatility passing through to module gross margins.
- REACH Substance Restrictions:ECHA-mandated limitations on cadmium and lead in optical coatings are forcing reformulation of long-life thin-film stacks, extending qualification timelines.
- Dielectric Resonator Substitution:Fixed-frequency ceramic filters from Murata and TDK are capturing sub-6 GHz 5G slots where tuning range exceeds actual operational requirements.
Strategic Opportunities
- India PLI Scheme:Production-linked incentives for telecom equipment manufacturing are attracting filter subsystem assembly to Chennai and Pune industrial corridors.
- 6G Spectrum Harmonization:ITU-R preparatory studies on sub-THz bands are creating design-win windows for filters covering 100-300 GHz experimental allocations.
- Test-Grade Channel Expansion:Network validation workflows are fragmenting filter procurement between production-grade and instrumentation-grade suppliers, opening specialized distribution paths.
Industry Challenges
- MEMS Process Engineering Talent:Foundry-scale MEMS fabrication requires rare cross-training in semiconductor processing and RF/optical design, with compensation inflation in Hsinchu and Dresden.
- Multi-Standard Certification Overlap:Filters serving both FCC Part 27 and CE Radio Equipment Directive must satisfy divergent spurious emission test protocols, duplicating validation expenditure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Tunable Filter Market |
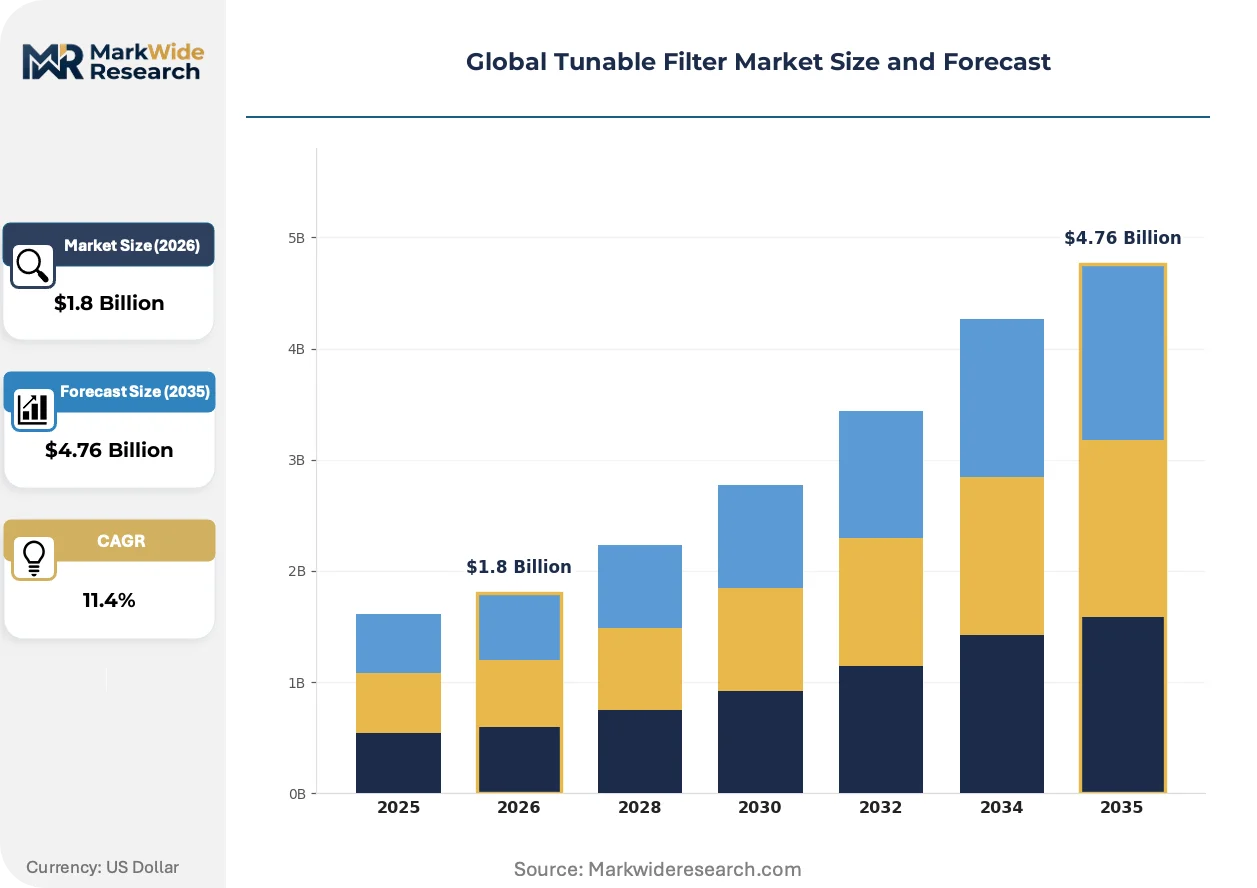
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $4.76 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Optical Filters, Acoustic Filters, Digital Filters, RF Filters Technology: MEMS, Liquid Crystal, Optical Coating, Dielectric End User: Telecommunications, Consumer Electronics, Medical Devices, Aerospace Application: Signal Processing, Environmental Monitoring, Spectroscopy, Optical Imaging |
| Companies Covered | Analog Devices, EXFO, Dover Corporation, Smiths Interconnect, DiCon Fiberoptics, Coleman Microwave Company, Qorvo, Murata Manufacturing, Netcom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Tunable Filter Market Strategic Shifts
Automation of filter calibration and tuning is compressing manufacturing variance while regulatory pressure on material content is forcing coating chemistry reinvention. Buyer procurement patterns are simultaneously fragmenting across application-specific qualification tracks.
MEMS-actuated optical filter assemblies are automating wavelength alignment previously requiring manual interferometric adjustment. Telecommunications equipment OEMs in Japan and South Korea are adopting these modules for coherent transceiver manufacturing lines. This automation is compressing final test cycle times from hours to minutes while reducing yield-scrappage from misalignment drift.
REACH Annex XVII restrictions on perfluorinated compounds are prohibiting legacy anti-reflection coatings in European-bound optical filters. Manufacturers are reformulating with magnesium fluoride and silicon dioxide nanolaminates, sacrificing some durability for compliance. Medical imaging and aerospace filter segments are absorbing the highest qualification costs due to extended lifetime requirements.
Telecom operators are unbundling filter procurement from transceiver subsystem contracts, creating direct component sourcing relationships previously mediated by module integrators. This disintermediation is fragmenting volume concentration across distributor and direct channels. The shift is most visible in Germany and the United Kingdom, where Deutsche Telekom and BT Group have established approved vendor lists for tunable optical components.
Global Tunable Filter Market Segmentation
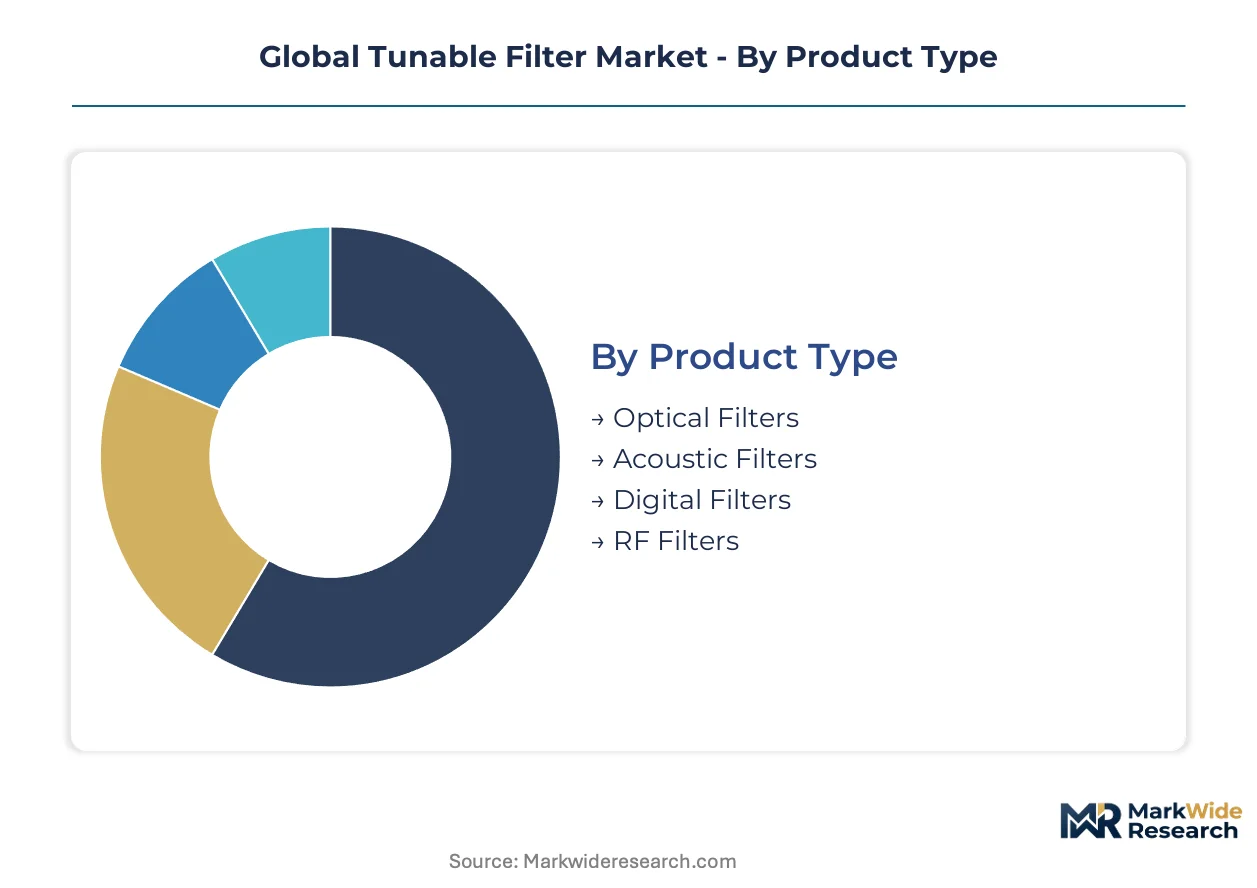
Tunable filter procurement splits sharply across certification regimes. MIIT equipment certification in China governs RF variants for 5G infrastructure, while CE marking under the EU Radio Equipment Directive constrains optical coating chemistries. Buyers must map segment selection to destination-market approval pathways.
Product Type:
Optical filters face REACH Annex XVII substance restrictions on perfluorinated compounds, while RF filters navigate FCC Part 27 spurious emission protocols in the United States. Acoustic and digital variants operate under lighter regulatory burdens, concentrating in consumer electronics where self-certification suffices.
- Optical Filters:These devices achieve linewidths below 0.1 nm through thin-film interference structures. Fiber optic network densification in Germany and Japan pulls demand for reconfigurable optical add-drop multiplexers, though InP wafer cost volatility compresses module margins.
- RF Filters:Insertion losses under 3 dB characterize these electromagnetic variants across tunable passbands. China's accelerated 5G base station rollout under MIIT mandates drives procurement through domestic OEM channels, with mmWave spectrum allocations multiplying base station filter counts.
- Acoustic Filters:Surface acoustic wave architectures dominate smartphone front-end modules. South Korean and Taiwanese consumer electronics manufacturers integrate these for sub-6 GHz filtering where space constraints override tuning range requirements.
- Digital Filters:FPGA-implemented algorithms enable software-defined filtering without analog components. Test equipment manufacturers in the United States embed these for flexible signal analysis workflows.
Leading the category by volume: Optical Filters. Growing fastest: RF Filters.
Technology:
Cost tier stratification separates MEMS batch-fabricated units from liquid crystal premium positioning. Dielectric and optical coating approaches occupy intermediate tiers based on performance-to-price ratios.
- MEMS:Semiconductor-compatible foundry processes enable volume scaling previously restricted to fixed-filter technologies. Hsinchu and Dresden foundries supply telecommunications OEMs in Japan and South Korea with actuated optical assemblies, automating wavelength alignment that previously required manual interferometric adjustment.
- Liquid Crystal:Electric-field modulation of birefringence enables microsecond-scale reconfiguration. Hyperscale data centers in Singapore and Ashburn deploy these for dynamic wavelength management in reconfigurable optical add-drop multiplexers, absorbing premium pricing for operational flexibility.
- Optical Coating:Thin-film interference stacks deposited via ion-beam sputtering deliver fixed-center tunable bandwidth products. REACH-mandated reformulation with magnesium fluoride and silicon dioxide nanolaminates extends European qualification timelines.
- Dielectric:Ceramic resonator technologies anchor aerospace-qualified modules where temperature stability exceeds tuning range priority. Qorvo leverages dielectric leadership in this segment for military and satellite communications.
MEMS dominates unit economics. Liquid Crystal commands the steepest expansion trajectory in revenue per unit.
End User:
Application-specific qualification tracks fragment procurement patterns across customer types. Medical and aerospace segments absorb extended validation cycles, while telecommunications compresss timelines to quarterly rhythms.
- Telecommunications:Equipment OEMs unbundle filter procurement from transceiver subsystem contracts. Deutsche Telekom and BT Group in Germany and the United Kingdom maintain approved vendor lists for tunable optical components, disintermediating traditional module integrators.
- Medical Devices:Imaging systems require extended-lifetime thin-film stacks. ECHA-mandated coating reformulations hit this segment hardest due to durability requirements for endoscopic and ophthalmic applications.
- Consumer Electronics:Smartphone manufacturers prioritize acoustic filter integration for front-end modules. South Korean and Chinese handset OEMs drive volume through specifications emphasizing size over tuning range.
- Aerospace:Satellite and military communications demand temperature-stable dielectric modules. FCC and CE dual certification requirements duplicate validation expenditure for suppliers serving both United States and European defense contractors.
Telecommunications generates the highest absolute demand. Medical Devices shows the fastest margin expansion as qualification barriers limit supplier entry.
Application:
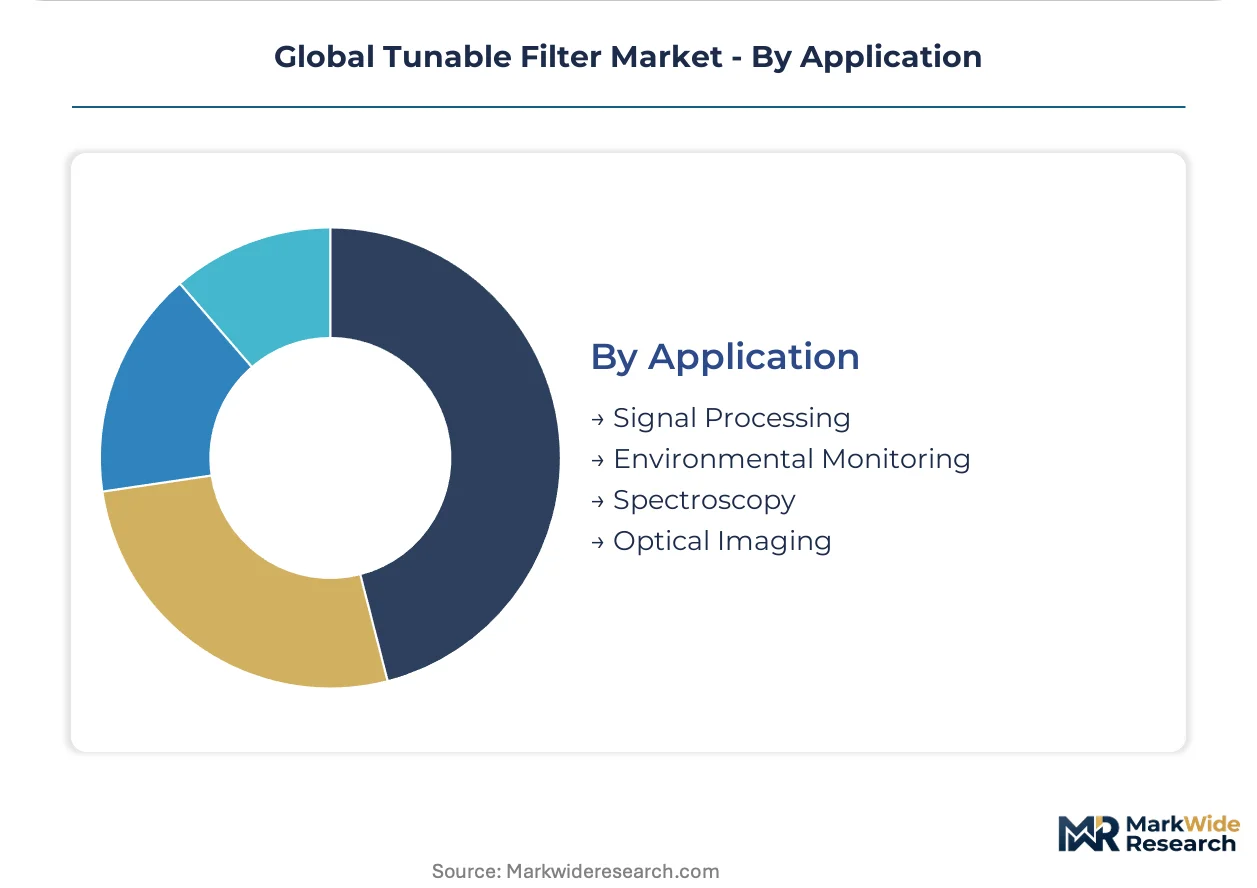
Signal processing applications concentrate in high-volume telecommunications infrastructure. Environmental monitoring and spectroscopy occupy specialized instrumentation niches with fragmented procurement.
- Signal Processing:Dynamic channel selection in 5G base stations and coherent optical transceivers. China's MIIT-certified deployment timeline compresss supplier qualification windows to quarterly cycles.
- Spectroscopy:Laboratory and portable analytical instruments require narrow-linewidth optical filtering. German and Swiss precision instrument manufacturers source test-grade variants for Raman and fluorescence applications.
- Environmental Monitoring:Atmospheric sensing networks deploy tunable filters for gas detection at specific absorption lines. European Green Deal monitoring initiatives in France and the Netherlands stimulate demand for compliant optical assemblies.
- Optical Imaging:Machine vision and medical imaging systems integrate tunable bandwidth selection. FDA and CE-MDR dual certification requirements shape supplier strategies for United States and European medical device markets.
Signal Processing leads by procurement volume. Environmental Monitoring is climbing the fastest as climate monitoring networks expand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production concentrates in East Asian semiconductor foundries while consumption splits between Chinese infrastructure buildouts and European regulatory-compliant deployments. The United States anchors aerospace and test equipment demand. Germany and Japan sustain precision optical manufacturing ecosystems.
China
MIIT-mandated 5G base station rollouts pull RF tunable filter procurement through domestic OEM channels. GB standards certification and dual carbon goals constrain material selection for European-bound exports. Hsinchu-trained engineering talent clusters in Shanghai and Shenzhen, where MEMS foundries automate wavelength alignment for coherent transceiver lines.
United States
FCC Part 27 spurious emission protocols govern mmWave filter deployment for 5G densification. FDA certification requirements shape medical imaging filter specifications for endoscopic and ophthalmic applications. Boston and Austin host test-grade filter specialists serving network validation workflows for hyperscale data centers.
Germany
REACH Annex XVII restrictions on perfluorinated compounds force magnesium fluoride coating reformulations for optical filter stacks. CE marking under the Radio Equipment Directive constrains RF variants for telecommunications infrastructure. Dresden foundries supply MEMS-actuated assemblies to Japanese and South Korean OEMs, compressing final test cycles from hours to minutes.
Japan
METI industrial policy supports domestic coherent transceiver manufacturing, pulling demand for reconfigurable optical add-drop multiplexers. JIS standards govern precision thin-film deposition for extended-lifetime medical imaging applications. Nagoya and Osaka clusters integrate liquid crystal tunable filters for dynamic wavelength management in fiber optic networks.
South Korea
MFDS certification requirements intersect with CE-MDR alignment for medical device filter exports to European markets. Consumer electronics manufacturers in Suwon and Seoul prioritize acoustic filter integration for smartphone front-end modules. Domestic OEMs compress procurement cycles to quarterly rhythms under pressure from 5G infrastructure deployment timelines.
Global Tunable Filter Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across technology tiers. Semiconductor-grade MEMS fabricators leverage batch processing economies against liquid crystal premium-positioned players. Three archetypes dominate: vertically integrated component suppliers, test-grade instrumentation specialists, and aerospace-qualified module providers. Capacity expansion and strategic partnerships constitute the primary competitive vectors, with foundry-scale investments in Hsinchu and Dresden reshaping cost structures.
Among diversified electronics conglomerates, Analog Devices and Murata Manufacturing exemplify scale-driven integration across optical and RF filter lines. Qorvo anchors the aerospace-qualified tier through dielectric technology positioning. EXFO occupies the test-grade instrumentation niche, serving network validation workflows. These three represent distinct competitive archetypes rather than overlapping market positions.
| Leading Market Players |
|---|
| Analog Devices |
| EXFO |
| Dover Corporation |
| Smiths Interconnect |
| DiCon Fiberoptics |
| Coleman Microwave Company |
| Qorvo |
| Murata Manufacturing |
| Netcom |
| Others |
Value Chain & Pricing Dynamics
Indium phosphide wafer pricing volatility cascades through optical filter module margins, compressing gross margins at the premium tier while MEMS batch-fabrication economies in Hsinchu and Dresden sustain cost-down trajectories for RF variants. Buyers in telecommunications equipment OEMs unbundle component procurement from subsystem contracts, fragmenting volume concentration and amplifying price negotiation leverage against discrete suppliers.
Pricing Analysis
Margin tightening in optical filter tiers reflects InP substrate cost pass-through and REACH-mandated coating reformulation expenses. Three-tier pricing structure across aerospace-qualified, telecommunications-grade, and test-instrumentation levels separates certification-burdened medical imaging variants from consumer-facing acoustic filters. Cost-down pressure on standard-grade RF modules accelerates because dielectric resonator substitution from Murata and TDK captures sub-6 GHz slots where tuning range exceeds operational requirements. Telecommunications OEMs exhibit highest price sensitivity due to quarterly procurement rhythms, while medical device manufacturers absorb premium pricing for extended-lifetime thin-film durability.
Supply Chain Analysis
Dual-sourcing mandates from Deutsche Telekom and BT Group force qualification of secondary MEMS foundries beyond Hsinchu and Dresden clusters. Geographic supply concentration centers on Taiwan, Germany, and China, with Shanghai and Shenzhen MEMS facilities automating wavelength alignment for coherent transceiver lines. Raw material dependencies draw from constrained III-V semiconductor supply, perfluorinated compound coating chemistries, and ceramic resonator substrates. Single-source vulnerability persists around InP wafer supply from consolidated III-V substrate manufacturers. Distribution runs through direct component sourcing relationships that disintermediate traditional module integrators in Germany and the United Kingdom.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive MEMS foundry capacity determines margin sustainability against fabless competitors. Control over semiconductor-compatible batch fabrication emerges as the decisive upstream lever separating sustainable profitability from margin erosion.
For Market Incumbents: Anchor aerospace-qualified positioning through dielectric technology investment against MEMS substitution threats in temperature-stable satellite applications. Deepen in-house production of MEMS actuation assemblies to defend margin position against fabless entrants exploiting Hsinchu foundry access. Prioritize CE marking and FDA dual certification investment to maintain medical imaging filter pricing power as REACH reformulation costs hit competitors hardest. For New Entrants and Emerging Players: India's PLI scheme for telecom equipment manufacturing opens a window for filter subsystem assembly in Chennai and Pune industrial corridors, bypassing incumbent concentration in East Asian foundries. Target test-grade instrumentation segments where EXFO's specialized positioning leaves fragmentation opportunity for network validation workflow suppliers. Pursue direct OEM qualification relationships with hyperscale data center operators in Singapore and Ashburn seeking liquid crystal tunable filters for dynamic wavelength management. For Investors and Strategic Acquirers: ITU-R preparatory studies on sub-THz 6G spectrum harmonization are the leading indicator that experimental 100-300 GHz filter architectures will secure design-win windows ahead of infrastructure deployment cycles. Long-term viability across the projection horizon favors acquisition targets with vertically integrated MEMS fabrication capabilities spanning optical and RF filter lines. Monitor MIIT equipment certification timeline acceleration as the signal for Chinese domestic OEM procurement channel consolidation that would elevate strategic value of certified suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| MEMS Foundry Capacity Expansion | Hsinchu and Dresden investments compress unit economics for batch-fabricated optical assemblies serving Japanese OEMs. |
| REACH-Compliant Coating Reformulation | Magnesium fluoride nanolaminate qualification extends European market access for medical imaging filter suppliers. |
| Direct OEM Procurement Relationships | Deutsche Telekom and BT Group approved vendor lists disintermediate module integrators in telecommunications infrastructure. |
| 6G Sub-THz Filter Architecture Development | ITU-R spectrum harmonization studies create design-win windows for experimental 100-300 GHz implementations. |
| India PLI Scheme Manufacturing Localization | Chennai and Pune assembly corridors attract filter subsystem production for telecom equipment export qualification. |
Study Parameters
Independent corroboration across telecommunications equipment OEM procurement officers, MEMS foundry process engineers, regulatory affairs specialists managing CE marking and MIIT certification, and test-grade instrumentation product managers underwrites the qualitative findings. Primary interviews with these stakeholders combined with secondary validation from FCC spectrum auction records, ECHA REACH restriction updates, MIIT equipment certification databases, and SEC filings from diversified filter manufacturers establish demand-side and supply-side triangulation. Bottom-up unit economics modeling and top-down market sizing reconciliation anchor quantitative outputs.
Comparable-period anchoring to historical 5G deployment cycles and fiber optic network densification trajectories calibrates growth assumptions across the projection horizon. Segmentation dimensions span product type, technology platform, end-user vertical, and application with additional modeling of certification-regime clusters that constrain commercial deployment geography. CAGRs derive from fitted adoption curves calibrated to infrastructure procurement rhythms. Key forecast inputs include MIIT-mandated base station rollout timelines and hyperscale data center capex disclosures from Singapore and Ashburn operators.
The model assumes a particular technology adoption path; alternative pathways for liquid crystal reconfigurable optical add-drop multiplexers versus MEMS-actuated assemblies would alter the outlook. Forecasts reflect assumptions around REACH substance restriction enforcement timelines and 6G spectrum harmonization outcomes. Deviation in InP wafer supply consolidation or III-V semiconductor pricing volatility would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
Waveguide Phase Shifter Market
Optical Components
Global Optical Coating Equipment Market
Optical Components
US Optical Sensors Market
Optical Components
Optical Transmitter Market
Optical Components
Diode Laser Module Market
Optical Components
Optical Amplifier Market
Optical Components
China Lithium Niobate Modulator Market
Optical Components
3-7mm Galvo Scanner Market
Optical Components
Global Electrochromic Glass and Devices Market
Optical Components
Display Optical Film Market
Optical Components
Japan Lithium Niobate Modulator Market
Optical Components
Global Diffractive Optical Elements Market
Optical Components
Optical Time-Domain Reflectometer Market
Optical Components
Optical Sensor Market
Optical Components
Global Fiber Bragg Grating Amplifier Market
Optical Components
Global Mask Alignment Systems Market