
 Optical Dome Market | 2026-2036
Optical Dome Market Size, Share, and Industry Trends Forecast 2026-2036
Optical Dome Market Insights
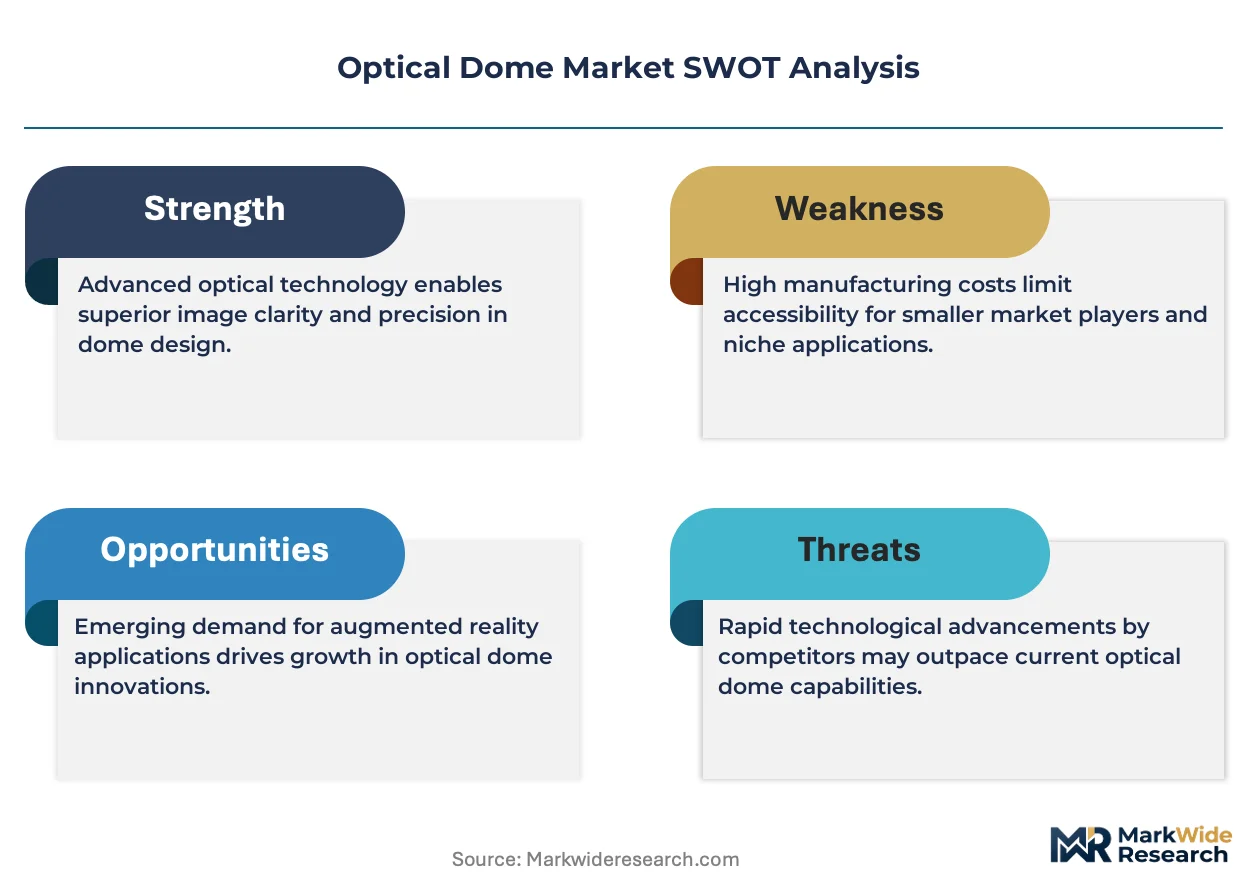
ISO 10110 surface imperfection tolerances and MIL-PRF-13830B scratch-dig specifications are bifurcating supplier eligibility between defense-qualified and commercial-grade manufacturers. Sherlan Optics leverages in-house grinding and polishing capabilities to sustain long-lead military contracts. Ecoptik specializes in UV-grade fused silica domes for semiconductor inspection tools. VY Optoelectrics anchors high-volume plastic optic production for automotive surround-view cameras.
An optical dome is a hemispherical or hyper-hemispherical transparent enclosure, typically manufactured from sapphire, fused silica, or optical-grade ceramics, that protects sensitive electro-optical payloads while preserving transmission across ultraviolet through infrared wavebands. Multi-layer anti-reflection coatings and diamond-turned surfaces achieve better than 99% transmission in critical defense and aerospace bands. Glass material segments dominate defense procurement where environmental hardness requirements exclude polymer alternatives, while plastic formulations grow fastest in automotive LiDAR and consumer electronics where cost scaling and molded aspheric geometries offset thermal limitations. Coated product categories capture premium margin pools because deposition chamber throughput constraints limit qualified supply.
FDA device regulations govern optical dome integration into surgical imaging and diagnostic equipment, while FAA airworthiness directives shape material traceability and fatigue testing protocols for airborne electro-optical systems. EASA certification requirements for unmanned aircraft systems are tightening optical payload environmental qualification standards across European supply chains. Stakeholders must monitor how dual-use export control expansions affect cross-border sapphire substrate sourcing and coating technology transfers.
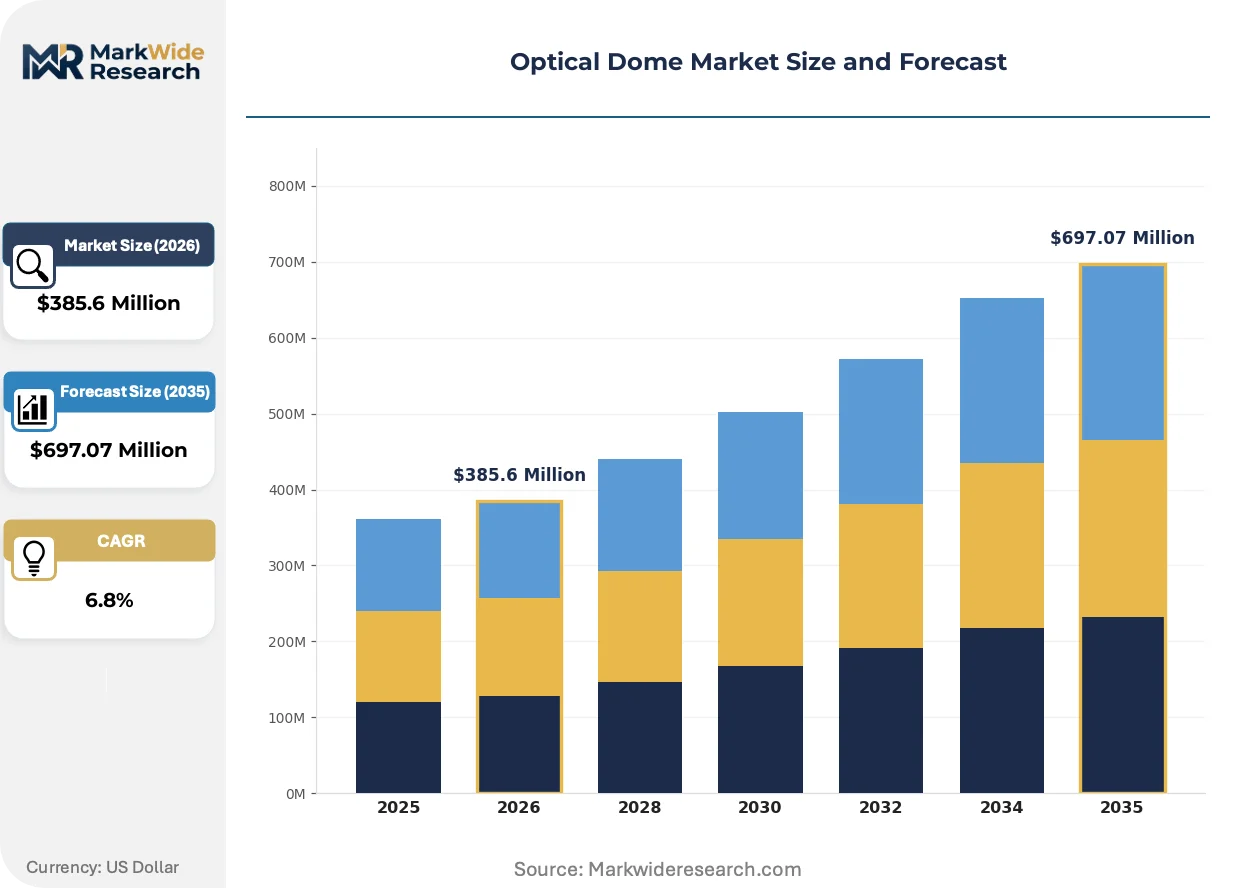
Market Dynamics
Defense procurement programs across NATO member states are expanding optical sensor deployments on unmanned aerial platforms, creating sustained demand for sapphire and fused silica domes with MIL-PRF-13830B qualification while compressing supplier lead times.
Growth Catalysts
- NATO unmanned platform expansion:Member states are accelerating electro-optical payload integration on surveillance drones, requiring hemispherical enclosures with thermal shock resistance for extended mission profiles.
- Fused silica UV transmission advances:Semiconductor lithography tools demand sub-nanometer surface roughness domes for 193nm and 248nm inspection wavelengths, pulling volume from specialty optics houses.
- Japan METI sovereign supply chain funding:Domestic security budgets underwrite captive electro-optical manufacturing capabilities, reducing import dependency for aerospace-qualified sapphire substrates.
Market Restraints
- Single-source sapphire boule concentration:Kyocera and Rubicon dominate high-purity crystal growth, creating supply vulnerability for defense-qualified material traceable to ITAR-compliant origins.
- Deposition chamber throughput limits:Multi-layer anti-reflection coating capacity constrains qualified supply, extending lead times for 99%-plus transmission specifications beyond eighteen months.
- Plastic thermal ceiling:Polycarbonate and acrylic formulations cannot survive hypersonic skin temperatures, excluding polymer alternatives from missile seeker and reentry vehicle applications.
Strategic Opportunities
- India PLI scheme optical component incentives:Production-linked subsidies for defense and aerospace manufacturing are attracting coating equipment investments to Bangalore and Hyderabad industrial corridors.
- Automotive LiDAR molded aspherics:Plastic optic producers are capturing surround-view camera volumes through injection-molded dome geometries impossible in ground glass or ceramics.
- EASA UAS environmental qualification tightening:Unmanned aircraft system certification standards are mandating extended temperature cycling and vibration testing, favoring suppliers with in-house metrology and environmental chambers.
Industry Challenges
- Master optician workforce attrition:Precision grinding and polishing expertise concentrates among technicians with twenty-plus years experience, with limited apprenticeship pipeline replenishment in Germany and the United States.
- Dual-use export control navigation:ITAR and EAR classification uncertainties delay sapphire substrate and coating technology transfers, requiring dedicated compliance personnel for cross-border transactions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Optical Dome Market |
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $697.07 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Layer, Multi-Layer, Coated, Uncoated Material: Glass, Plastic, Acrylite, Ceramics End User: Aerospace, Defense, Telecommunications, Automotive Application: Optical Sensors, Lenses, Camera Systems, Protective Covers |
| Companies Covered | Sherlan Optics, Ecoptik, VY Optoelectronics, Shanghai Optics, Optimax Systems, Rayotek, UQG Optics, CNGEIR, Borisun Optics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Optical Dome Market Trends and Innovations
Material science advances and regulatory tightening are reshaping competitive positioning across defense, aerospace, and industrial inspection verticals, with coating capabilities and environmental qualification protocols emerging as primary differentiation vectors.
Diamond-turned aspheric surfaces on sapphire substrates are achieving sub-micron form accuracy for infrared imaging systems. Missile seeker manufacturers in the United States and Germany are adopting these geometries to reduce spherical aberration without additional corrective optics. This precision manufacturing capability is bifurcating supplier tiers between defense-qualified houses with in-house diamond turning and commercial-grade competitors dependent on subcontracted finishing.
EU AI Act risk classification frameworks are extending to autonomous surveillance platforms carrying electro-optical payloads. EASA certification requirements now mandate algorithmic transparency documentation for target recognition systems protected by optical domes, forcing integrators to maintain material traceability records from boule growth through final assembly. European unmanned aircraft system OEMs are responding by consolidating supplier bases to qualified vendors with established quality management systems.
Hypersonic vehicle programs are compressing thermal protection system development cycles, pulling optical dome qualification timelines from thirty-six months to eighteen months. Prime contractors in the United States are unbundling environmental testing from manufacturing, awarding separate contracts to specialized metrology houses with arc-jet and plasma wind tunnel access. This disaggregation is most visible in the Colorado and Maryland aerospace clusters, where defense agencies fund shared qualification infrastructure.
Optical Dome Market Segmentation
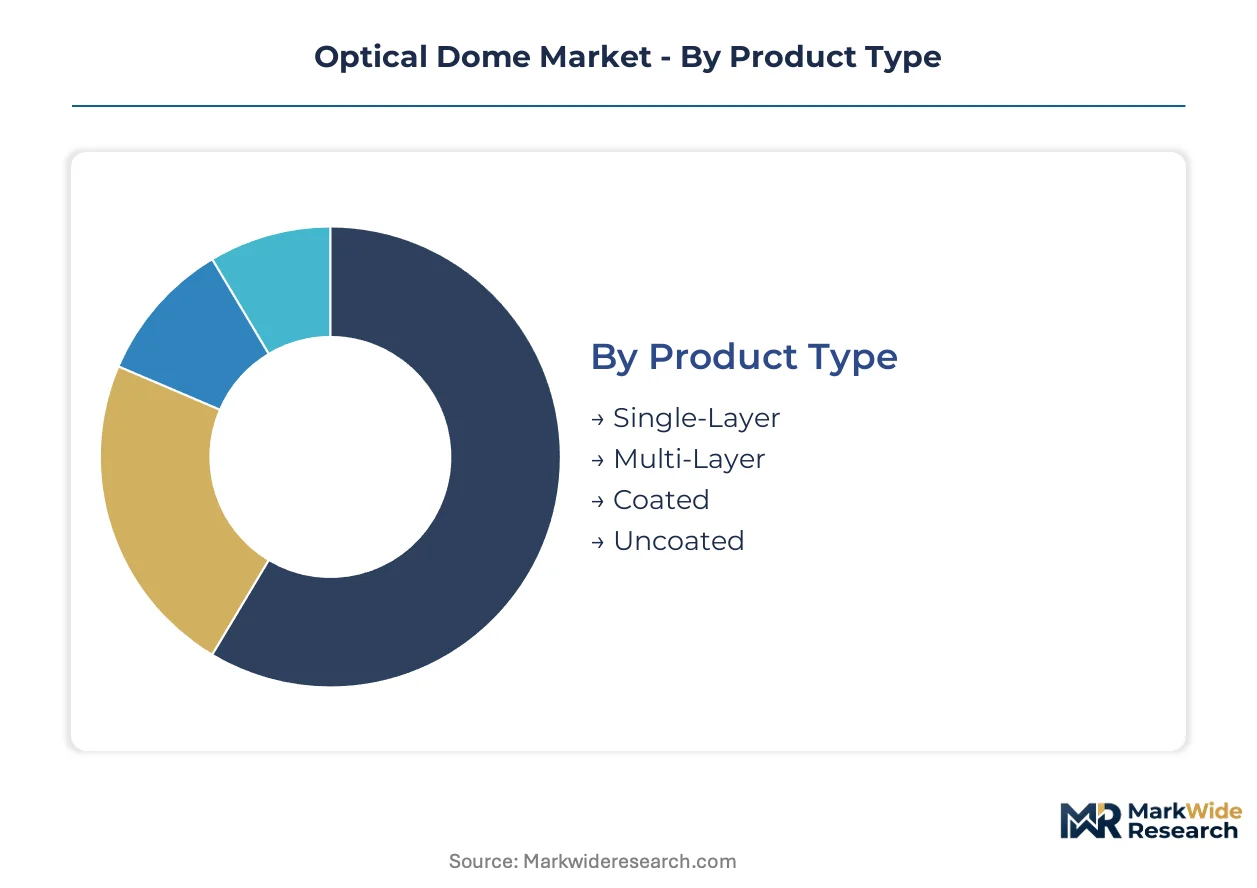
Optical dome segmentation reveals how material science, coating complexity, and end-use environmental requirements partition margin pools across defense, aerospace, and industrial verticals. Procurement patterns diverge sharply between ITAR-qualified military specifications and commercial-grade automotive volumes.
Product Type:
Coated product variants command premium margin pools because physical vapor deposition capacity constraints limit qualified supply and extend delivery timelines.
- Single-Layer:Basic anti-reflection coatings reduce surface reflection losses in visible and near-infrared bands. Automotive surround-view cameras in Germany and Japan absorb volume where cost sensitivity outweighs transmission efficiency requirements.
- Multi-Layer:Broadband anti-reflection stacks achieve better than 99% transmission across ultraviolet through infrared wavebands. Defense procurement programs in the United States specify these for missile seeker and unmanned aerial platform payloads where thermal shock resistance and transmission efficiency are non-negotiable.
- Coated:Deposition chamber throughput limits create eighteen-month lead times for qualified supply. MIL-PRF-13830B qualification requirements bifurcate supplier eligibility between defense-grade and commercial manufacturers.
- Uncoated:Ground and polished substrates without thin-film treatment serve cost-constrained applications. Plastic optic producers in Asia-Pacific automotive supply chains favor these for molded aspheric geometries where coating adhesion challenges persist.
The dominant share belongs to Multi-Layer, while Coated variants are closing the gap fastest as environmental qualification standards tighten across NATO defense procurement.
Material:
Glass formulations absorb the largest volume share, though ceramics and engineered plastics are carving out distinct application niches based on thermal performance ceilings.
- Glass:Sapphire and fused silica variants dominate environmental hardness requirements. Fused silica UV transmission advances at 193nm and 248nm wavelengths pull volume into semiconductor lithography inspection tools.
- Plastic:Polycarbonate and acrylic formulations enable injection-molded aspheric geometries impossible in ground glass. Automotive LiDAR surround-view cameras in Japan and Germany specify these where thermal limitations exclude hypersonic applications.
- Acrylite:Specialized acrylic grades offer improved impact resistance over standard polycarbonate. Consumer electronics manufacturers specify these for handheld imaging devices where weight reduction trumps thermal performance.
- Ceramics:Optical-grade ceramic substrates survive thermal shock thresholds exceeding 1500°C. Hypersonic vehicle programs in the United States specify these for reentry vehicle optical windows where sapphire alternatives fail.
Glass retains the dominant position by revenue, though Plastic is expanding most quickly in automotive LiDAR where molded complexity offsets thermal constraints.
End User:
Defense and aerospace verticals concentrate procurement value despite smaller unit volumes, while automotive scales through high-volume plastic optic programs.
- Aerospace:FAA airworthiness directives mandate material traceability and fatigue testing protocols. EASA certification requirements for unmanned aircraft systems tighten environmental qualification standards across European supply chains.
- Defense:NATO member states expand electro-optical payload integration on surveillance drones. ITAR and EAR classification uncertainties delay sapphire substrate and coating technology transfers, requiring dedicated compliance personnel.
- Telecommunications:Fiber optic network infrastructure demands precision optical components for signal conditioning. 5G backhaul expansion in Germany and Japan sustains demand for UV-grade fused silica domes.
- Automotive:LiDAR sensor integration for autonomous driving functions drives molded plastic optic volumes. Surround-view camera programs specify injection-molded dome geometries with sub-millimeter dimensional tolerances.
Defense captures the dominant revenue share, while Automotive is climbing the fastest as ADAS sensor penetration accelerates across German and Japanese OEM platforms.
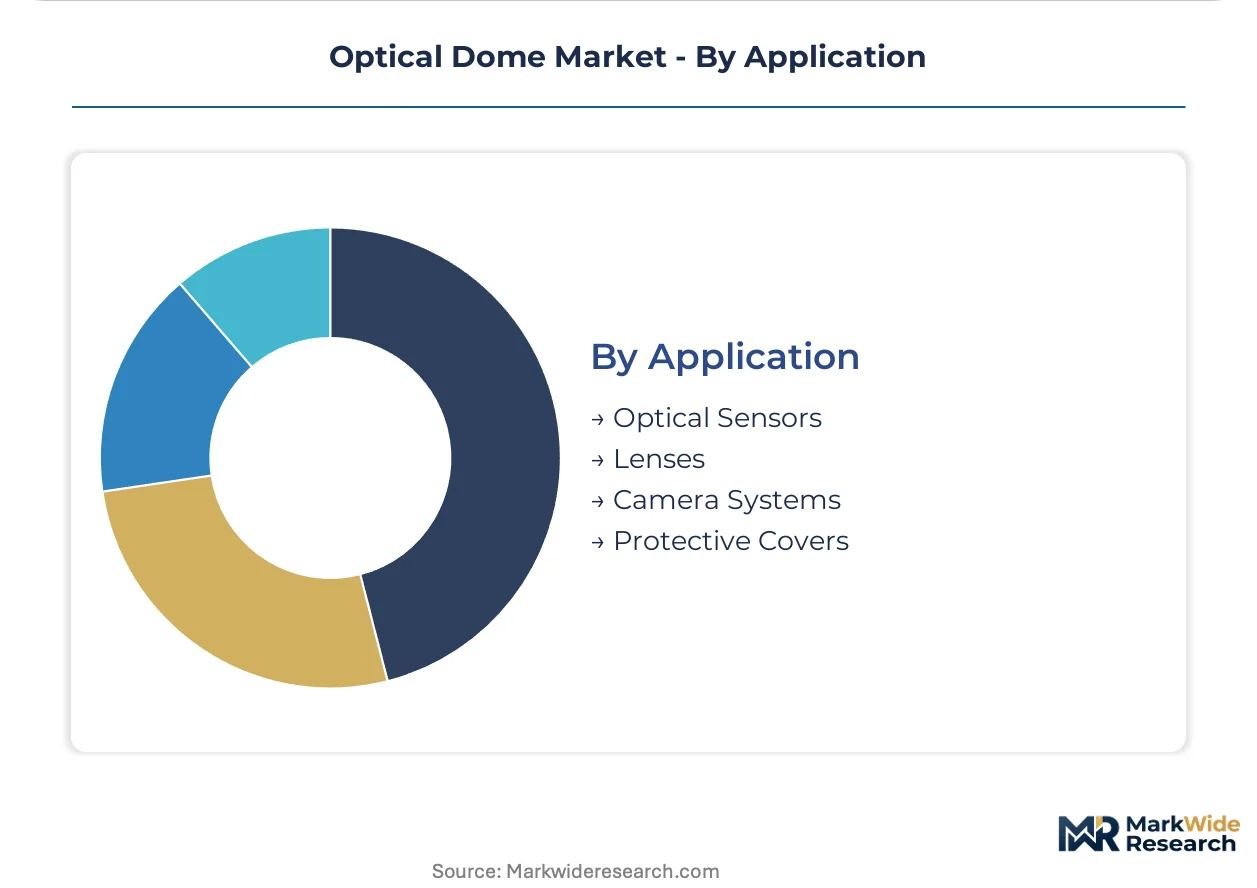
Application:
Camera Systems and Optical Sensors partition the market between imaging payloads and non-imaging detection functions, with specification intensity varying by end-use criticality.
- Optical Sensors:Non-imaging detection systems for missile warning and laser rangefinding applications. Diamond-turned aspheric surfaces on sapphire substrates achieve sub-micron form accuracy for infrared imaging systems in the United States.
- Lenses:Corrective optical elements requiring precise centering within dome enclosures. Semiconductor lithography tools demand sub-nanometer surface roughness specifications at 193nm inspection wavelengths.
- Camera Systems:Imaging payloads for surveillance, reconnaissance, and autonomous navigation. EU AI Act risk classification frameworks extend algorithmic transparency documentation requirements to target recognition systems protected by optical domes.
- Protective Covers:Environmental sealing without optical transmission requirements. Industrial automation and marine applications specify these where mechanical protection outweighs waveband performance.
Camera Systems holds the dominant application share, while Optical Sensors is gaining share fastest as hypersonic and directed-energy programs multiply sensor deployment density.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Defense procurement incentives and sovereign supply chain funding are redrawing geographic production footprints across NATO member states and allied economies. National security budgets now underwrite captive electro-optical manufacturing capabilities that previously relied on cross-border sourcing.
United States
Hypersonic vehicle programs and missile seeker modernization drive sapphire substrate demand. FAA airworthiness directives mandate material traceability for airborne electro-optical systems. Colorado and Maryland aerospace clusters host shared qualification infrastructure funded by defense agencies.
Germany
Surveillance drone payload integration expands across Bundeswehr procurement channels. EASA unmanned aircraft system certification tightens environmental qualification standards. Bavarian precision optics houses concentrate diamond-turning capabilities for infrared imaging systems.
Japan
METI sovereign supply chain funding reduces import dependency for aerospace-qualified sapphire. Automotive LiDAR sensor penetration accelerates molded plastic optic volumes. Nagoya industrial corridor anchors injection-molded dome production for surround-view camera programs.
India
PLI scheme production-linked subsidies attract coating equipment investments to defense manufacturing corridors. DGFT dual-use export classifications complicate technology transfer timelines. Bangalore and Hyderabad industrial clusters consolidate metrology and environmental testing capabilities.
Optical Dome Market Competitive Landscape
Player mix skews toward defense-qualified specialists with in-house grinding and polishing capabilities. The supplier base stratifies between ITAR-compliant houses sustaining long-lead military contracts and commercial-grade competitors serving cost-sensitive automotive volumes. Three archetypes dominate: precision optics houses with captive finishing, specialty coating providers constrained by deposition chamber throughput, and plastic optic producers leveraging molded aspheric geometries. Competitive moves center on backward integration into sapphire boule sourcing and unbundling environmental testing from manufacturing operations.
Within the defense-qualified tier, Sherlan Optics and Ecoptik occupy positions exemplifying divergent specialization vectors. Sherlan Optics represents the vertically integrated precision house archetype, while Ecoptik exemplifies wavelength-specific specialists. VY Optoelectrics anchors the high-volume plastic optic segment. Shanghai Optics and Optimax Systems sit within mid-tier commercial fabrication. Rayotek, UQG Optics, CNGEIR, and Borisun Optics populate the specialist coating and substrate finishing layer.
| Leading Market Players |
|---|
| Sherlan Optics |
| Ecoptik |
| VY Optoelectronics |
| Shanghai Optics |
| Optimax Systems |
| Rayotek |
| UQG Optics |
| CNGEIR |
| Borisun Optics |
| Others |
Pricing and Supply Chain Analysis
MIL-PRF-13830B qualification requirements simultaneously gate supplier eligibility and stratify price tiers across defense and commercial optical dome procurement. This certification bifurcation creates parallel supply ecosystems where ITAR-compliant houses command sustained premiums while commercial-grade competitors absorb volume-driven cost compression.
Pricing Analysis
Certification level creates the primary spread between defense-qualified and commercial-grade supply tiers. Three-tier pricing structure across premium, standard, and economy levels reflects MIL-PRF-13830B qualification status, deposition chamber capacity access, and in-house diamond-turning capabilities. Cost compression in automotive plastic optics is intensifying because injection-molded dome producers compete on sub-millimeter dimensional tolerances. Commercial automotive buyers exhibit highest price sensitivity, while hypersonic vehicle prime contractors prioritize transmission efficiency and thermal shock resistance over unit economics.
Supply Chain Analysis
Eighteen-month lead times for multi-layer anti-reflection coatings signal deposition chamber throughput constraints across qualified supply tiers. High-purity sapphire boule production concentrates in Japan and the United States, with Kyocera and Rubicon anchoring crystal growth capacity. Supply chains draw from fused silica precursors, specialty coating materials, and precision grinding equipment. Single-source vulnerability in ITAR-traceable sapphire substrates exposes defense procurement to export control disruption. Distribution runs through prime contractor consolidation, direct OEM supply agreements, and specialty optics distributors serving industrial inspection verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Hypersonic vehicle program acceleration and EASA unmanned aircraft certification tightening are reshaping competitive positioning across defense and aerospace verticals. These regulatory and technological inflections compress qualification timelines while elevating environmental testing capabilities as differentiation vectors.
For Market Incumbents: Fortify captive sapphire substrate sourcing through backward integration into boule growth or long-term offtake agreements with Kyocera and Rubicon. Expand in-house environmental testing capacity including arc-jet and plasma wind tunnel access to capture unbundled qualification contracts from prime contractors in Colorado and Maryland aerospace clusters. Master optician workforce attrition in Germany and the United States threatens precision grinding and polishing throughput.
For New Entrants and Emerging Players: Lead with automotive LiDAR molded aspheric geometries where injection-molded plastic optics displace ground glass in surround-view camera programs. Target Japan and Germany OEM supply chains where ADAS sensor penetration accelerates volume absorption. Establish coating equipment investments in India's Bangalore and Hyderabad corridors to capture PLI scheme production-linked subsidies for defense manufacturing.
For Investors and Strategic Acquirers: EASA UAS environmental qualification tightening reshapes the acquisition landscape toward suppliers with established quality management systems and in-house metrology capabilities. Five-to-ten year viability favors precision optics houses with captive finishing and diamond-turning equipment over coating-dependent subcontractors. Monitor ITAR and EAR classification expansion as signal for cross-border technology transfer friction and captive supply chain premiumization.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sapphire Boule Sourcing | Reduces ITAR-traceable material dependency and secures long-lead defense contract fulfillment. |
| In-House Environmental Testing Capacity Expansion | Captures unbundled qualification contracts from hypersonic vehicle prime contractors in U.S. clusters. |
| Coating Equipment Investment in India PLI Corridors | Accesses production-linked subsidies while positioning for defense and aerospace manufacturing growth. |
| Diamond-Turning Capability Acquisition | Enables sub-micron form accuracy for infrared imaging systems and missile seeker applications. |
| Automotive LiDAR Molded Aspheric Program Launch | Penetrates Japan and Germany OEM supply chains with injection-molded geometries impossible in ceramics. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across defense procurement officers, precision optics manufacturing executives, semiconductor lithography equipment engineers, and automotive Tier 1 supplier procurement leads. Secondary validation drew from FAA airworthiness directive filings, EASA unmanned aircraft system certification documentation, METI sovereign supply chain funding announcements, and India PLI scheme policy circulars. Bottom-up volume modeling triangulated against top-down defense budget allocation analysis.
Across the analysis window, segmentation dimensions included material formulation, coating complexity tier, end-use vertical, and geographic regulatory cluster. CAGRs were derived from weighted scenario modeling across defense procurement program timelines and automotive ADAS sensor penetration curves. Hypersonic vehicle program acceleration and EU AI Act risk classification frameworks served as demand-side inflection inputs.
Underlying assumptions cover sustained NATO unmanned platform expansion and stable dual-use export control classifications, with deviation risk concentrated in ITAR reclassification events and master optician workforce attrition. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Optical Components
North America Laser Diode Market
Optical Components
CVD Sic Ring Market
Optical Components
Europe Lithium Niobate Modulator Market
Optical Components
Optical Modulators Market
Optical Components
Prism Coupler Market
Optical Components
Erbium-Doped Fiber Amplifier Market
Optical Components
Faraday Rotator Market
Optical Components
Optical Component Tester Market
Optical Components
Infrared Filter Market
Optical Components
Objective Lens Market
Optical Components
Nonlinear Optical Crystals Market
Optical Components
Asia-Pacific Optical Film Market
Optical Components
Diode Laser Module Market
Optical Components
Fogless Mirror Market
Optical Components
Global Optical Measurement Market
Optical Components
Silicon Photonics Market