
 Coating Binders Market | 2026-2036
Coating Binders Market Size, Share, and Industry Trends Forecast 2026-2036
Coating Binders Market Intelligence
The EU's REACH framework, focused on restricting volatile organic compounds, is consolidating the supply base around producers with advanced water-based and high-solids technologies. BASF SE leverages its extensive R&D infrastructure to develop compliant formulations for demanding automotive and industrial applications. Arkema specializes in high-performance acrylic and vinyl binders, targeting the protective coatings and wood finishes segments. Dow Chemical Company sustains its market position through massive production scale and a diversified product portfolio.
Coating binders are polymeric resins that form a continuous film upon drying, binding pigments, extenders, and other additives together within a coating formulation. Their primary function is to provide critical properties like adhesion to the substrate, durability, and resistance to environmental factors like moisture, chemicals, and UV radiation. Acrylic binders command a significant share due to their versatility in architectural applications. Epoxy and polyurethane binders represent high-performance categories, essential for demanding protective and automotive OEM coatings.
Compliance with regulations from the US Environmental Protection Agency (EPA) and the European Chemicals Agency (ECHA) is non-negotiable for market access in key Western markets. These bodies enforce strict limits on VOCs and hazardous air pollutants, shaping product development priorities toward greener chemistries. Future investment decisions will hinge on balancing the performance requirements of end-users with the escalating costs of regulatory compliance and sustainable material sourcing.
Market Dynamics
The central dynamic shaping the coating binders market is the regulatory-driven transition toward low-VOC and environmentally sustainable formulations. This pressure from bodies like the EU's ECHA and the US EPA is forcing a technological pivot away from traditional solvent-borne systems, concentrating market power with producers of advanced water-based, high-solids, and powder coating binders.
Growth Catalysts
- Sustainable Construction Mandates:Policies under the EU Green Deal and similar initiatives promote the use of low-impact building materials, directly stimulating demand for water-based acrylic binders used in certified green architectural paints and coatings.
- Automotive Sector Expansion:Growth in automotive production within India and Mexico necessitates sophisticated OEM and refinish coatings, increasing consumption of high-performance polyurethane and epoxy binders that offer superior durability and chemical resistance.
- Bio-Based Formulations:The development of binders from renewable sources like plant oils and starches is creating a new product category. These bio-based binders help coating manufacturers meet corporate sustainability targets and appeal to environmentally conscious consumers.
Market Restraints
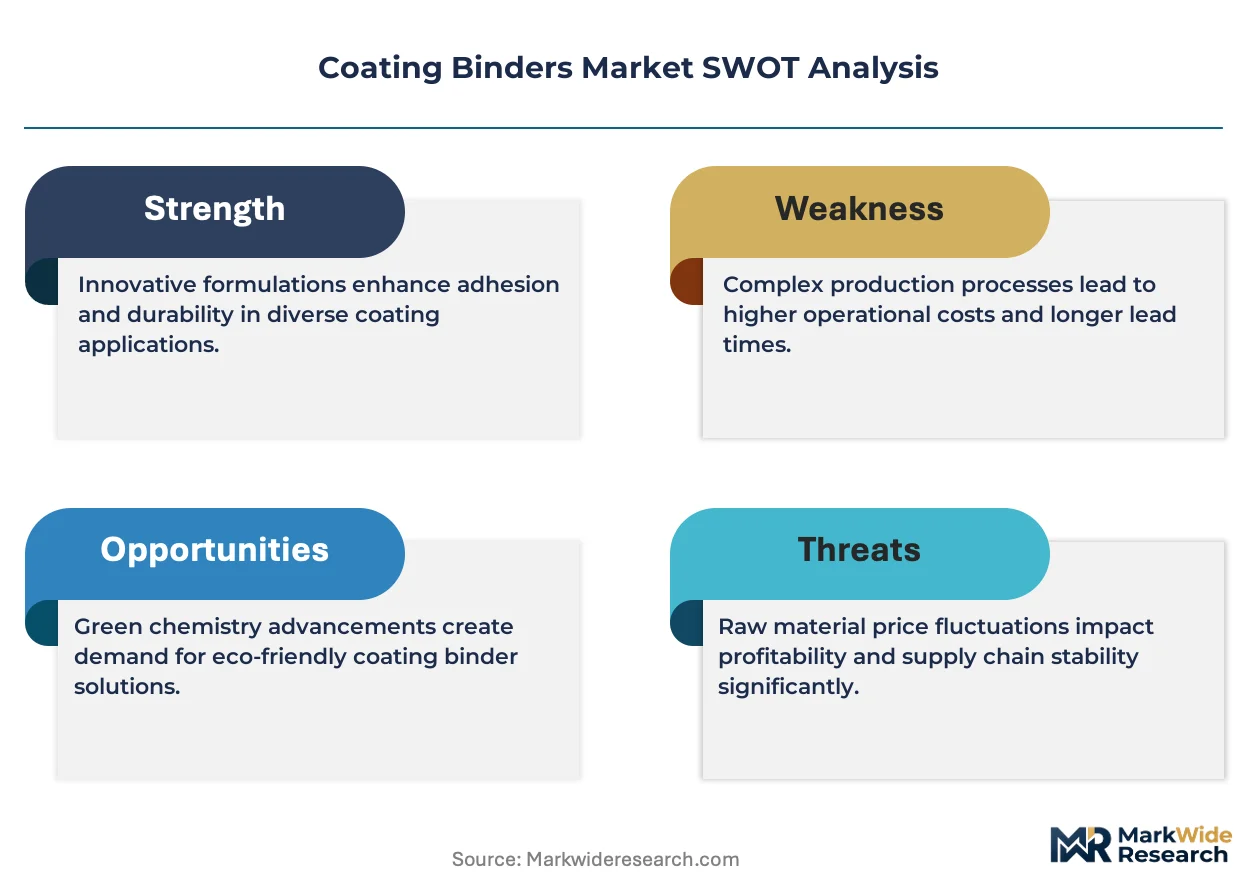
- Raw Material Price Volatility:The market is subject to price fluctuations of petrochemical feedstocks, such as acrylic monomers and epoxy resins. This volatility creates margin pressure for binder manufacturers and uncertainty for downstream coating formulators.
- Performance Gaps in Greener Tech:Certain water-based binder formulations still exhibit performance limitations, such as slower curing times or reduced hardness, compared to solvent-borne counterparts, hindering their adoption in demanding industrial and protective applications.
- Regulatory Compliance Costs:The continuous evolution of VOC regulations, including those from the US EPA, requires significant R&D investment for reformulation and extensive testing for recertification, posing a substantial financial burden.
Strategic Opportunities
- Functional and Smart Coatings:There is a significant opportunity in developing binders for functional coatings, such as self-healing systems for automotive clear coats or antimicrobial binders for coatings used in hospitals and public transportation.
- Infrastructure Investment in Africa:Large-scale infrastructure projects across several African nations are creating nascent demand for protective coatings for steel and concrete, opening new geographic markets for epoxy and polyurethane binder systems.
- Nanotechnology Integration:Incorporating nanoparticles like nanosilica or carbon nanotubes into binder matrices offers a pathway to create next-generation coatings with enhanced properties such as extreme scratch resistance, UV stability, and conductivity.
Industry Challenges
- Sustainable Feedstock Scalability:A primary operational challenge is securing a consistent, large-scale supply of high-quality bio-based or recycled raw materials, as their supply chains are less mature and more fragmented than those for conventional petrochemicals.
- Formulation Expertise Scarcity:The industry faces a shortage of polymer chemists and technical specialists with the skills to develop high-performance water-based systems that replicate the application properties and durability of solvent-based incumbents.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Coating Binders Market |
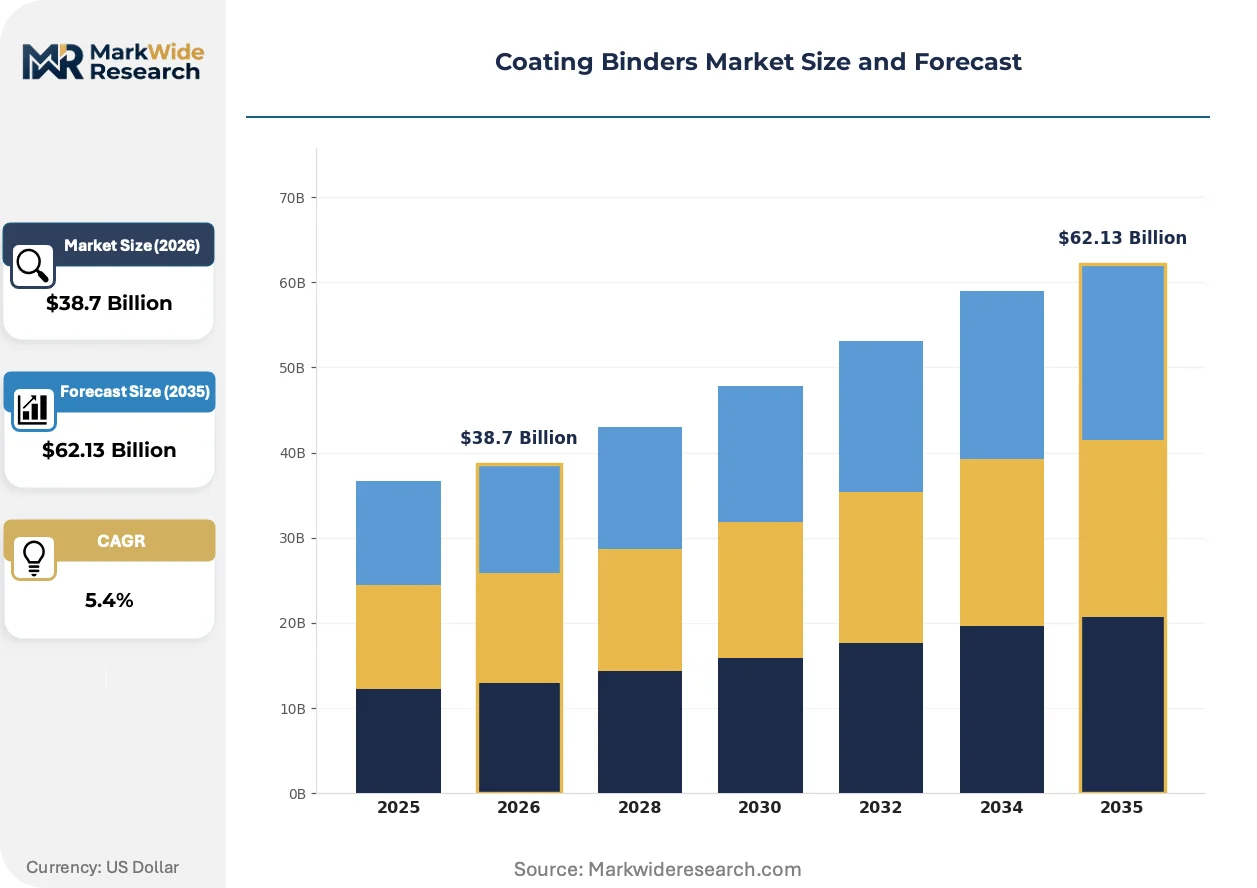
| Market Size in 2026 | $38.7 Billion |
| Market Size in 2035 | $62.13 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Binder Type: Acrylic, Epoxy, Polyurethane, Alkyd, Polysiloxane, Vinyl Application: Architectural, Protective Coatings, Automotive OEMs, Wood Finishes, Marine, Aerospace End User Industry: Construction, Transportation Equipment, Furniture Manufacturing, Shipbuilding, Aircraft Production, Electronics Assembly Packaging Type: Drums, Pails, Bulk Containers, Carboys, Totes, Intermediate Bulk Containers |
| Companies Covered | Arkema, Trinseo, BASF SE, OMNOVA Solutions Inc., Synthomer PLC, Dow Chemical Company, Wacker Chemie AG, Dairen Chemical Corporation, Celanese Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Coating Binders Market Strategic Shifts & Innovations
Innovation in the coating binders market is driven by a fundamental push toward sustainability without compromising performance. This compels a shift in polymer science, focusing on developing novel binder architectures that reduce environmental impact while meeting the increasingly stringent demands of industrial and architectural end-users.
Ultraviolet (UV) and Electron Beam (EB) curable binder systems are polymers that polymerize almost instantly when exposed to high-intensity light. Industries such as electronics manufacturing and graphic arts are rapidly adopting these systems to increase production throughput. This technology is rewriting the operational model for high-volume finishing lines by nearly eliminating drying time and VOC emissions, which cuts energy consumption and factory footprint.
China's stringent environmental regulations, particularly the MEE's standards limiting VOC content in industrial products, are forcing a rapid market transformation. This policy directly accelerates the phase-out of traditional solvent-borne technologies across numerous manufacturing sectors. The nation's vast furniture and construction industries are most affected, creating a massive and urgent demand for compliant water-based and powder coating binder technologies.
A notable shift in buyer behavior is the growing requirement for life-cycle transparency through instruments like Environmental Product Declarations (EPDs). This disrupts procurement processes historically based on technical data sheets and price, compelling binder suppliers to invest in life-cycle assessment. This trend is particularly advanced in Northern Europe's architectural segment, where green building schemes make EPDs a key factor in material specification.
Coating Binders Market Segmentation
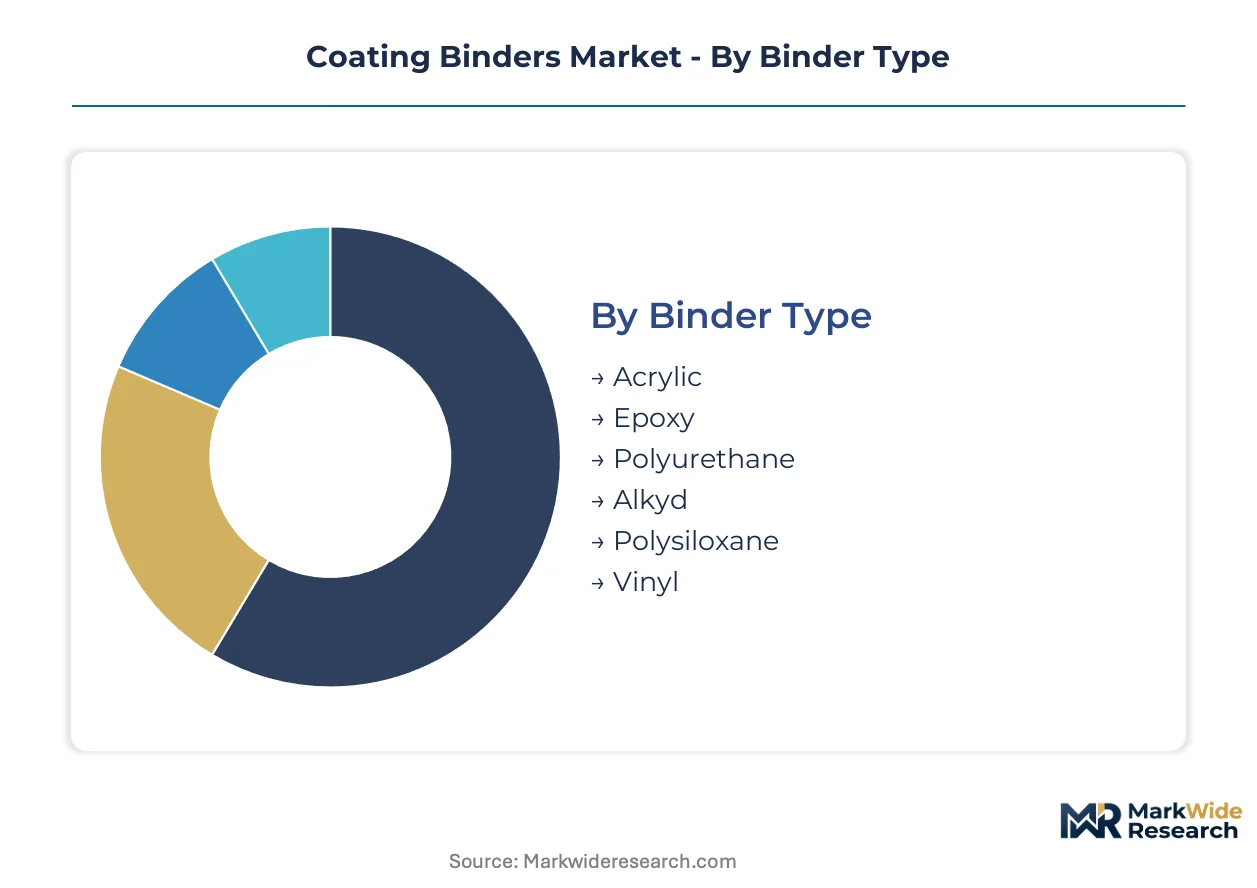
The coating binders market exhibits diverse segmentation, reflecting varied end-user requirements and technological advancements across different applications. Understanding these distinct segments provides clarity on demand drivers, technological preferences, and competitive dynamics within the industry.
Binder Type:
The market's volume is largely dictated by commodity binders, while premium formulations capture specialized performance niches.
- Acrylic:These versatile polymers form films with excellent UV and weather resistance, making them ideal for exterior durability. Demand concentrates heavily in architectural coatings for new construction and renovation projects across China and India.
- Epoxy:Known for their exceptional adhesion, chemical resistance, and mechanical strength, epoxy binders are critical for protective coatings. Industrial applications, particularly in infrastructure and manufacturing facilities, drive significant consumption.
- Polyurethane:These high-performance binders provide superior hardness, flexibility, and abrasion resistance for demanding automotive OEM and refinish coatings.
- Alkyd:Traditional alkyd resins offer good adhesion and cost-effectiveness, finding use in general industrial and decorative paints.
- Polysiloxane:Offering extreme weatherability and corrosion protection, polysiloxane binders are increasingly specified for infrastructure and marine applications.
- Vinyl:Vinyl binders deliver excellent chemical resistance and flexibility, making them suitable for packaging and coil coatings.
Today's leader: Acrylic. Tomorrow's challenger: Polysiloxane.
Application:
The market stratifies by the performance demands of specific coating applications, each requiring tailored binder chemistries.
- Architectural:This segment represents the largest volume market, encompassing interior and exterior paints for residential and commercial buildings. Sustainable construction mandates in Europe and North America directly stimulate demand.
- Automotive OEMs:Coatings for original equipment manufacturers require binders with stringent performance for durability, aesthetics, and resistance to environmental factors. Growth in vehicle production in Mexico and India boosts this sector.
- Protective Coatings:These applications demand binders offering superior corrosion, chemical, and abrasion resistance for steel structures and industrial equipment.
- Wood Finishes:Binders for wood coatings provide aesthetic appeal, scratch resistance, and protection for furniture and flooring.
- Marine:Harsh saltwater environments necessitate binders with exceptional corrosion and UV resistance for ship hulls and offshore platforms.
- Aerospace:Lightweight, high-performance binders are essential for aircraft coatings, offering protection and aerodynamic efficiency.
Architectural applications hold the largest share, while Aerospace coatings are climbing the fastest.
End User Industry:
Demand for coating binders originates from various industrial sectors, each with unique performance and regulatory requirements.
- Construction:This industry is the primary consumer of coating binders, especially for architectural and protective coatings in new builds and maintenance. Urbanization in Asia-Pacific countries fuels this demand.
- Transportation Equipment:Manufacturers in this sector, including automotive and rail, require high-performance binders for durable and aesthetic finishes. Regulatory demands for low-VOC solutions are significant.
- Furniture Manufacturing:This sector uses binders for wood and metal finishes, focusing on aesthetics, durability, and low-VOC compliance.
- Shipbuilding:Marine coatings for vessels require binders that withstand extreme conditions, including salt spray and UV radiation.
- Aircraft Production:High-performance binders are critical for aerospace coatings, providing protection, weight reduction, and fuel efficiency.
- Electronics Assembly:Specialty binders are employed for protective and insulating coatings in electronic components.
The Construction sector maintains the largest consumption, with Aircraft Production showing the steepest expansion trajectory.
Packaging Type:
Logistics and operational efficiency determine the preferred packaging types for coating binders across the value chain.
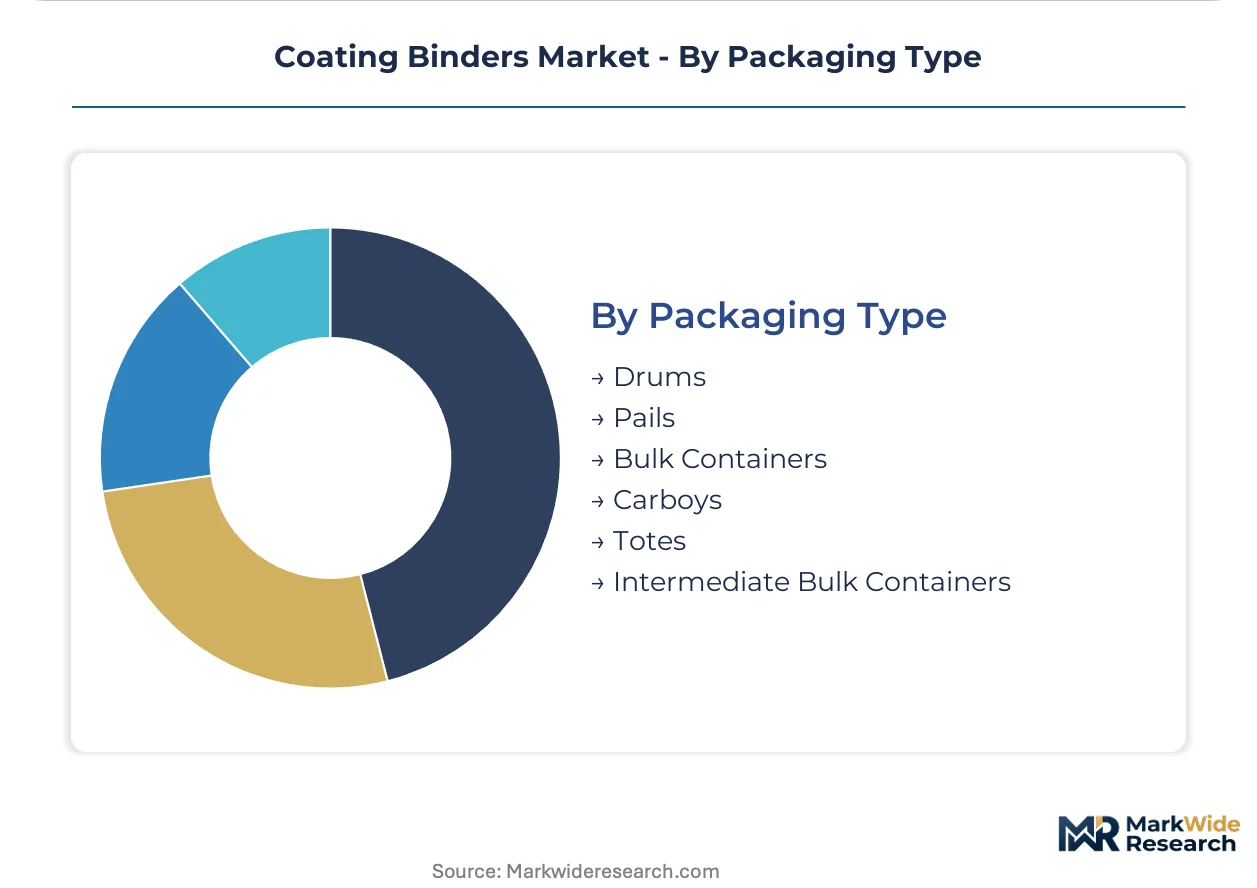
- Drums:These standard industrial containers are widely used for shipping and storing various volumes of coating binders, offering versatility for different customer scales. Their robust construction ensures product integrity during transit.
- Bulk Containers:Large-volume industrial users often opt for bulk containers to minimize packaging waste and reduce logistics costs. These are prevalent in high-throughput manufacturing operations.
- Pails:Smaller-volume applications and specialized formulations frequently utilize pails for convenient handling and batch control.
- Carboys:Designed for chemical resistance, carboys are employed for transporting specific high-purity or corrosive binder formulations.
- Totes:Reusable and stackable, totes offer an efficient solution for mid-volume distribution and internal material handling.
- Intermediate Bulk Containers:IBCs provide a cost-effective and environmentally friendly option for transporting and storing moderate quantities of binders.
Drums remain the most common packaging, while Intermediate Bulk Containers are gaining share fastest for efficiency.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global talent pool in polymer chemistry and materials science anchors regional growth in the coating binders market. Specialized R&D hubs across Germany, the United States, and China drive innovation in sustainable formulations. These centers provide the expertise necessary for developing advanced low-VOC and high-performance binder systems.
China
Consumption intensifies within China's advanced manufacturing and construction industrial clusters. The MEE's stringent environmental standards limiting VOC content in industrial products force rapid market transformation. The Yangtze River Delta region, with its vast furniture and construction industries, experiences urgent demand for compliant water-based and powder coating binder technologies.
Germany
European demand for high-performance binders stems from the demanding automotive OEM and industrial applications. The EU's REACH framework, enforced by ECHA, strictly limits volatile organic compounds, accelerating the shift to water-based formulations. Bavaria's automotive sector actively adopts compliant formulations for demanding vehicle finishes, leveraging extensive R&D.
United States
The United States experiences robust demand from architectural and protective coatings sectors. US EPA regulations on VOCs and hazardous air pollutants shape product development priorities toward greener chemistries. Chemical production hubs along the Gulf Coast invest significantly in R&D for reformulation and extensive testing for recertification.
India
Growth in automotive production and large-scale infrastructure projects necessitates sophisticated coating binders. India's Bureau of Indian Standards (BIS) promotes quality and environmental compliance in industrial products. Chennai's automotive manufacturing cluster drives increasing consumption of high-performance polyurethane and epoxy binders for superior durability.
Mexico
Mexico's expanding automotive sector and ongoing construction projects fuel demand for specialized coating systems. Environmental regulations from SEMARNAT influence product development toward low-VOC solutions. The Bajío region, a prominent automotive industry hub, requires sophisticated OEM and refinish coatings with superior durability and chemical resistance.
Coating Binders Market Key Industry Players
Diversified conglomerates compete with focused pure-play specialists, creating a tiered market structure for coating binders. This landscape features established chemical giants alongside innovative niche players specializing in sustainable technologies. Strategic archetypes include large-scale commodity producers, high-performance solution providers, and regional specialists. Dominant competitive moves center on R&D investment in low-VOC formulations and strategic partnerships to expand market reach.
At the scale-driven end, Dow Chemical Company and BASF SE exemplify the market presence of global chemical giants, leveraging extensive production capabilities across diverse binder chemistries. Arkema represents a specialized European player, focusing its expertise on high-performance acrylic and vinyl binders for targeted applications. These entities anchor distinct segments, from commodity volumes to specialized, performance-driven solutions.
| Leading Market Players |
|---|
| Arkema |
| Trinseo |
| BASF SE |
| OMNOVA Solutions Inc. |
| Synthomer PLC |
| Dow Chemical Company |
| Wacker Chemie AG |
| Dairen Chemical Corporation |
| Celanese Corporation |
Cost & Logistics Intelligence
Premium performance coating binders, such as polysiloxanes and specialized polyurethanes, exhibit distinct pricing and supply chain structures compared to commodity acrylics. Their higher value reflects advanced R&D and stringent performance specifications, influencing dedicated supply networks.
Pricing Analysis
Bundled technical support and formulation services often accompany premium coating binders, differentiating their pricing from unbundled commodity sales. The dominant pricing structure involves contract-based long-term offtake for industrial customers and per-unit transactional sales for architectural segments, with price differentiation stemming from performance tiers and regulatory compliance. Pricing softness reflects raw material price volatility for petrochemical feedstocks. Architectural coatings buyers exhibit the highest price sensitivity, while automotive OEM and aerospace customers prioritize performance.
Supply Chain Analysis
Dual-sourcing requirements are increasingly common for critical binder systems, mitigating risks for major coating manufacturers. Supply concentration for key binder chemistries is observed in China for commodity acrylics, Germany for specialized polyurethanes, and the United States for advanced epoxy resins. The industry sources from petrochemical feedstocks like acrylic monomers and epoxy resins, alongside emerging bio-based inputs, making commodity price volatility a structural supply chain risk. Downstream distribution involves direct sales for large industrial OEMs and specialized distributor networks for smaller formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The coating binders market is evolving into a late-cycle quality story, driven by a pronounced demand-shift toward premium specifications for durability and environmental compliance. End-users increasingly prioritize high-performance, low-VOC formulations over traditional options.
For Market Incumbents:To counter regulatory pressure on VOCs and performance gaps in greener technologies, incumbents must intensify R&D investment in advanced water-based and UV-curable binder systems. Securing long-term supply agreements for sustainable raw materials, like plant oils, reinforces their position. Investing in robust certification processes, such as Environmental Product Declarations (EPDs), will differentiate offerings in Northern European architectural segments. This dual focus on innovation and certified sustainability protects market share against emerging technologies.
For New Entrants and Emerging Players:The EU Green Deal in Europe opens a window for new entrants specializing in bio-based and low-VOC coating binder formulations. White-space targets include developing functional coatings, such as antimicrobial binders for healthcare settings, and self-healing systems for demanding industrial applications. Focusing on life-cycle transparency through Environmental Product Declarations provides a strong go-to-market angle for green building schemes. Targeting sustainable construction mandates offers a penetrable segment for innovative players.
For Investors and Strategic Acquirers:Asymmetric upside sits with investors targeting agile mid-cap companies pioneering sustainable binder technologies for the long term. Acquisition targets should be niche specialists in UV/EB curable systems or advanced bio-based chemistry, offering proprietary formulations. These firms possess critical intellectual property and formulation expertise for future market demands. The signal to watch is the successful scaling of sustainable feedstock supply chains, indicating broader market readiness for green chemistries.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Advanced Water-Based R&D | Develops compliant formulations for demanding automotive and industrial applications under ECHA regulations. |
| Secure Bio-Based Raw Material Partnerships | Addresses supply chain scalability challenges for plant oil and starch-derived binders, meeting corporate sustainability targets. |
| Expand UV/EB Curable Capacity | Capitalizes on growing adoption in electronics manufacturing and graphic arts, nearly eliminating VOC emissions. |
| Develop Functional Coating Binders | Creates high-value products like self-healing or antimicrobial systems for hospitals and public transportation. |
| Pursue Environmental Product Declaration (EPD) Certification | Meets life-cycle transparency requirements, particularly for architectural segments in Northern Europe. |
Research Approach
Multiple input streams—primary interviews, secondary research, and market intelligence reports—were reconciled to construct a robust market view. Primary engagement involved R&D directors, procurement leads at coating manufacturers, and regulatory affairs specialists. Secondary validation drew from industry association reports and government regulatory filings from the US EPA and EU ECHA. This approach ensured comprehensive bottom-up and top-down triangulation of market data.
Historical trends were cross-referenced with expert panel input to project market trajectories across the analysis window. The analytical framework modeled segmentation dimensions including binder type, application, end-user industry, and regional regulatory adherence. Compound Annual Growth Rates were derived from an iterative process of supply-demand balancing. Industry-specific forecast inputs included raw material price forecasts and global construction spending outlooks.
Revisions become necessary when significant regulatory shifts or unexpected petrochemical feedstock availability issues materialize. Forecasts reflect current market assumptions regarding environmental mandates and technological adoption rates. Deviation in global economic growth or regulatory enforcement would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Intumescent Fire Retardant Coating Market
Coatings
North America Concrete Floor Coatings Market
Coatings
Mexico Protective Coatings Market
Coatings
Tablet Coatings Market
Coatings
Global Anti-Reflective Coatings Market
Coatings
Can Coatings Market
Coatings
FEVE Fluoropolymer Coatings Market
Coatings
2K Coatings Market
Coatings
Global Industrial Floor Coatings Market
Coatings
Waterproof Coating Market
Coatings
High Build Rust Stabilizer with Reinforced Glass Flake Coating Market
Coatings
Electrical Appliance Coatings Market
Coatings
United Kingdom Automotive OEM Coatings Market
Coatings
Global Flat Glass Coatings Market
Coatings
Metallic Powder Coating Market
Coatings
Self-Healing Coatings Market