
 Global Flat Glass Coatings Market | 2026-2036
Global Flat Glass Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
Global Flat Glass Coatings Market Foresight
Buyer concentration among large-scale architectural developers is expanding as mega-projects consolidate procurement volumes across multiple tower complexes. Ferro leverages its pigment technology leadership to supply color-stable formulations for facade glass. Sherwin-Williams Company anchors North American distribution through its contractor-direct channel network. Arkema competes on fluoropolymer chemistry for durable exterior coatings.
Flat glass coatings comprise thin functional layers applied to glass substrates through processes such as magnetron sputtering or sol-gel deposition, modifying optical, thermal, or mechanical properties for specific end-use performance. These coatings typically range from nanometers to micrometers in thickness and serve to control solar heat gain, enhance visible light transmission, or enable self-cleaning surfaces in building and transportation applications. Low emissivity and solar control categories dominate current volume as building codes tighten thermal performance mandates across temperate climates. Sputtering and physical vapor deposition technologies capture premium margin pools due to precision thickness control and multi-layer stack capability for advanced optical performance.
FDA oversight applies to coatings in food-contact display applications, while EPA regulations govern volatile organic compound emissions during coating application and curing processes. REACH compliance in Europe restricts certain heavy metal pigments and mandates substance registration for imported coated glass products. The EU Green Deal's renovation wave targets accelerate specification of high-performance thermal insulation coatings in existing building retrofits. Stakeholders must monitor evolving carbon-border adjustment mechanisms and building performance standards to align product certification with regional compliance timelines.
Market Dynamics
The EU Green Deal's renovation wave and the F-Gas Regulation are compressing specification cycles for thermal insulation coatings, forcing coating suppliers to accelerate certification timelines while developers consolidate procurement across multi-tower complexes.
Growth Catalysts
- EU Green Deal renovation mandates:The regulation accelerates retrofit specifications for high-performance thermal insulation coatings across existing building stock in temperate European climates.
- Magnetron sputtering technology:This deposition process enables precision multi-layer optical stacks that meet tightening solar heat gain coefficient requirements in commercial facades.
- China commercial construction corridor:Mega-project developers in Shanghai, Beijing, and Shenzhen are consolidating procurement volumes for solar control glazing across integrated tower complexes.
Market Restraints
- Fluoropolymer feedstock concentration:Specialty fluorinated precursors for durable exterior coatings face supply concentration among limited Japanese and German chemical suppliers.
- REACH substance registration costs:The ECHA framework imposes escalating compliance burdens on imported coated glass products containing restricted heavy metal pigments.
- Silica aerogel substitution threat:Advanced translucent insulation materials are capturing niche specifications previously reserved for coated glazing in high-performance envelopes.
Strategic Opportunities
- India building efficiency codes:The BIS energy conservation building code creates specification pull for low-emissivity coatings in Mumbai, Delhi, and Bangalore commercial developments.
- Self-cleaning photocatalytic convergence:Titanium dioxide nanocoatings combined with hydrophilic surface engineering are opening maintenance-reduction specifications for transportation glazing.
- Direct-to-developer digital channels:Specification platforms are disintermediating traditional distributor networks for large-scale architectural procurement decisions.
Industry Challenges
- Multi-layer stack process control:Sputtering operations require nanometer-scale thickness uniformity across architectural glass formats exceeding six meters.
- Cross-border carbon certification:The EU Carbon Border Adjustment Mechanism creates documentation complexity for coated glass imports from energy-intensive production origins.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Flat Glass Coatings Market |
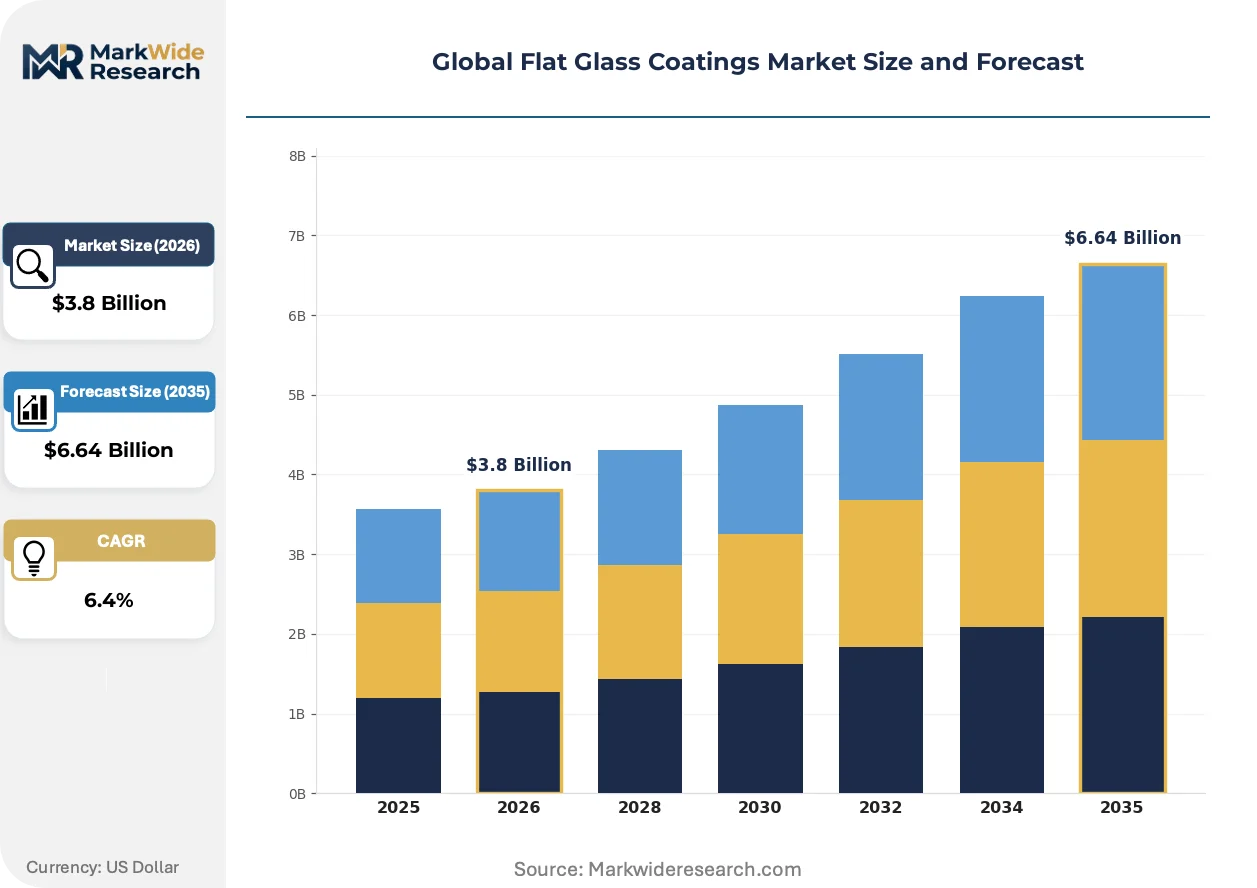
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.64 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Anti-Reflective, Self-Cleaning, Solar Control, Low Emissivity, Decorative, Thermal Insulation Coating Technology: Physical Vapor Deposition, Chemical Vapor Deposition, Sputtering, Sol-Gel Process, Spray Coating, Dip Coating Application: Architectural Glass, Automotive Glass, Electronics Display, Solar Panels, Furniture Glass, Lighting Fixtures End User Industry: Building Contractors, Automakers, Consumer Electronics, Renewable Energy Providers, Furniture Manufacturers, Lighting Companies |
| Companies Covered | Ferro, Sherwin-Williams Company, Arkema, Nippon Paint, Vitro, Fenzi, Hesse GmbH & Co. KG, 3M Company, PPG Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Flat Glass Coatings Market Shifts & Advancements
Electrochromic and thermochromic active coatings are transitioning from aerospace and automotive origins into commercial architectural specifications, reshaping how building envelopes respond to dynamic environmental conditions.
Magnetron sputtering is expanding into large-area architectural substrates as equipment manufacturers scale deposition chambers beyond six-meter glass formats. Tower developers in the United Arab Emirates and Singapore are specifying dynamic solar control stacks that modulate visible light transmission across diurnal cycles. This precision coating architecture is compressing the performance gap between static and active glazing systems.
The EPA's volatile organic compound emission standards for coating application and curing processes are tightening solvent-based formulation viability in North American manufacturing. Formulators are accelerating waterborne and UV-curable platform development to maintain market access. Transportation glazing suppliers serving the US market are reconfiguring curing infrastructure to comply with state-level air quality implementation plans.
Architectural specification decisions are migrating earlier into project development cycles as developers model whole-building energy performance during schematic design phases. Coatings suppliers are embedding thermal simulation capabilities into pre-construction technical support to secure placement before competitive bidding opens. This front-loaded engagement pattern is most pronounced in German and Dutch commercial developments pursuing passive house certification thresholds.
Global Flat Glass Coatings Market Segmentation
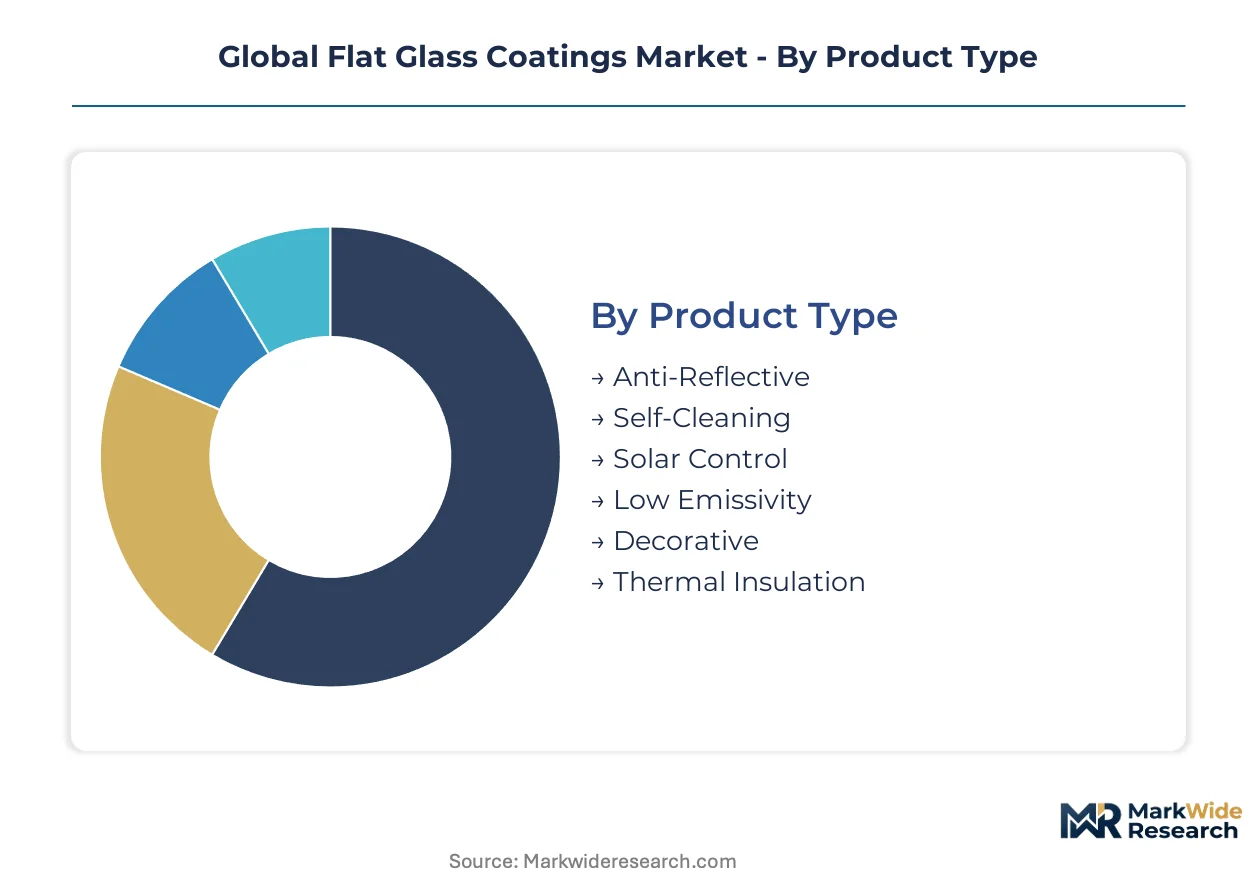
Flat glass coatings serve divergent performance requirements across building envelopes, transportation, and consumer electronics, necessitating precise segmentation to align thermal, optical, and mechanical specifications with end-use validation protocols. Each category reflects distinct procurement patterns, from bulk architectural tenders to precision electronics contracts.
Product Type:
Customization intensity varies sharply across this category, with thermal performance coatings commanding project-specific engineering while decorative formulations permit greater standardization.
- Low Emissivity:Multi-layer silver or metal oxide stacks deposited via magnetron sputtering reduce thermal emissivity below 0.15, enabling compliance with Germany's EnEV building energy standards and passive house certification thresholds across Dutch commercial developments.
- Solar Control:Spectrally selective coatings filter infrared radiation while maintaining visible light transmission, consolidating procurement volumes among Shanghai and Shenzhen mega-project developers pursuing LEED-equivalent ratings.
- Anti-Reflective:Nanostructured silica or magnesium fluoride layers minimize surface reflectance below 2% for museum display cases and high-end electronics.
- Self-Cleaning:Titanium dioxide photocatalytic surfaces decompose organic contaminants under UV exposure, reducing maintenance cycles for transportation glazing.
- Decorative:Pigmented or fritted coatings enable aesthetic differentiation in interior partitions and branded retail facades.
- Thermal Insulation:Advanced multi-layer stacks targeting U-values below 0.8 W/m²K for Nordic climate envelopes.
Leading the category by volume: Low Emissivity. Growing fastest: Solar Control.
Coating Technology:
Capital intensity and deposition precision create distinct margin tiers, with vacuum-based methods capturing premium architectural specifications versus atmospheric processes serving cost-sensitive applications.
- Sputtering:Magnetron sputtering achieves nanometer-scale thickness control across six-meter glass formats, anchoring production lines serving UAE and Singapore tower developments with dynamic solar control requirements.
- Physical Vapor Deposition:Electron beam evaporation deposits high-purity metal oxides for electronics display coatings requiring optical uniformity across sub-millimeter pixel densities.
- Chemical Vapor Deposition:Atmospheric pressure CVD enables inline production of silicon oxide barriers for solar panel encapsulation.
- Sol-Gel Process:Liquid-phase deposition suits small-batch decorative and anti-reflective coatings with lower capital barriers.
- Spray Coating:Robotic spray systems apply organic-inorganic hybrids for automotive windscreen rain-repellent treatments.
- Dip Coating:Immersion processes coat complex lighting fixture geometries with uniform thin films.
Highest volume share: Sputtering. Steepest expansion trajectory: Physical Vapor Deposition.
Application:
Specification authority migrates across value chain nodes, with architectural developers consolidating procurement while electronics OEMs retain direct coating supplier relationships.
- Architectural Glass:Curtain wall and fenestration systems drive specification of low-emissivity and solar control stacks, with EU Green Deal renovation mandates accelerating retrofit volumes across German and French building stock.
- Automotive Glass:Windshield and sidelite coatings integrate rain-sensing, heads-up display compatibility, and thermal comfort functions, with NHTSA optical clarity standards governing North American homologation.
- Electronics Display:Cover glass for smartphones and tablets demands anti-reflective and anti-fingerprint surface engineering.
- Solar Panels:Anti-reflective coatings maximize photon capture efficiency in photovoltaic modules.
- Furniture Glass:Tempered tabletops and shelving utilize decorative and protective treatments.
- Lighting Fixtures:Diffusion and reflector coatings optimize LED luminaire efficacy.
Dominant application by revenue: Architectural Glass. Climbing the fastest: Electronics Display.
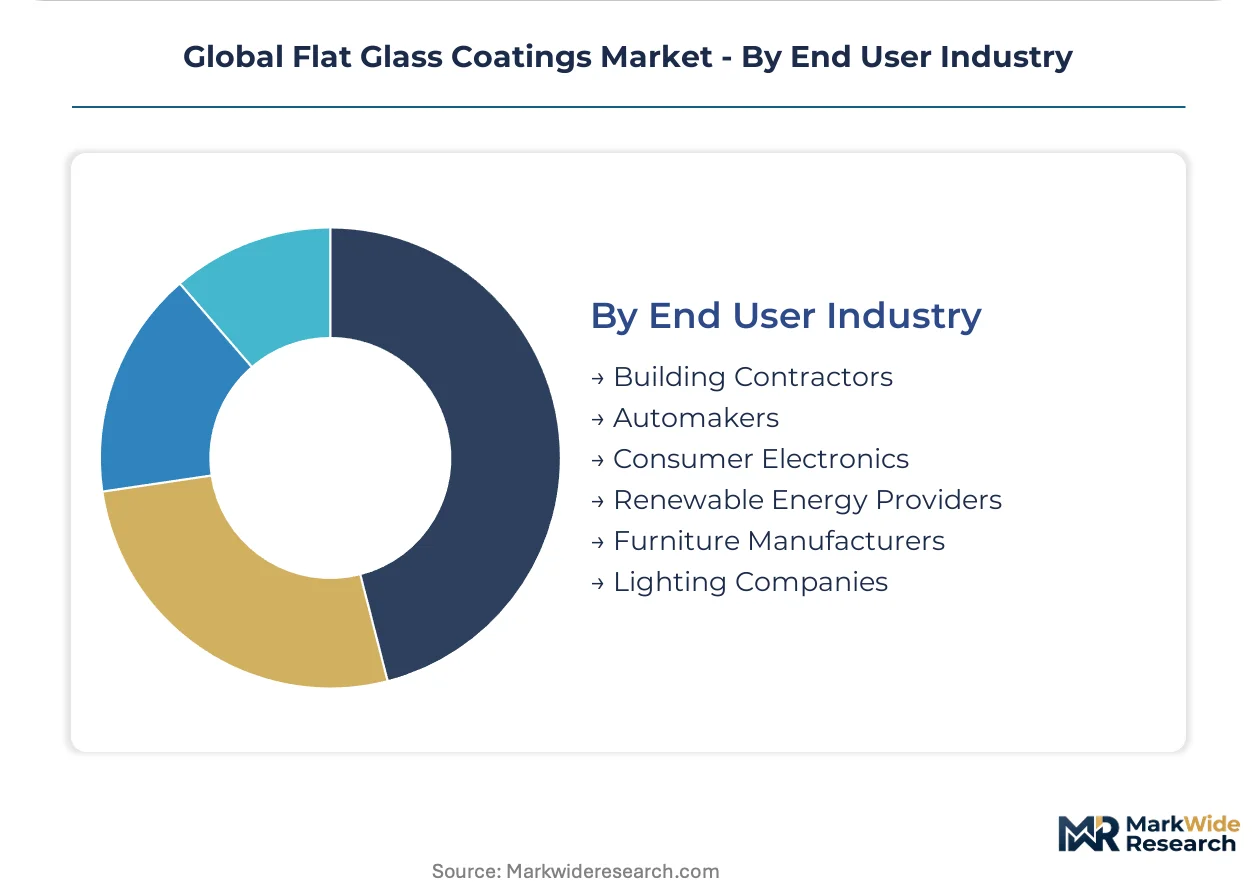
End User Industry:
Procurement scale and technical sophistication diverge, with building contractors negotiating multi-tower volumes while furniture manufacturers purchase on spot markets.
- Building Contractors:Mega-project developers in China, India, and the UAE consolidate glazing procurement across integrated tower complexes, compressing supplier margins through volume concentration.
- Automakers:Tier-1 glass suppliers specify coatings during platform development cycles, with EPA VOC emission standards constraining North American curing process selection.
- Consumer Electronics:Display panel manufacturers source cover glass coatings directly, bypassing traditional distribution.
- Renewable Energy Providers:Utility-scale solar developers specify anti-reflective performance warranties spanning 25-year module lifetimes.
- Furniture Manufacturers:Regional producers procure decorative coatings through distributor networks.
- Lighting Companies:LED fixture assemblers specify optical coatings for thermal management and beam control.
Largest procurement scale: Building Contractors. Gaining share fastest: Consumer Electronics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China concentrates procurement volumes for solar control glazing among mega-project developers in Shanghai, Beijing, and Shenzhen. The EU Green Deal renovation wave and F-Gas Regulation are compressing specification cycles across temperate European climates.
China
Commercial construction corridors in Shanghai, Beijing, and Shenzhen drive consolidated procurement for solar control glazing across integrated tower complexes. MEE dual carbon goals tighten building envelope performance benchmarks for new developments. Yangtze River Delta fabricators scale magnetron sputtering capacity to serve domestic mega-project demand.
Germany
EnEV building energy standards mandate low-emissivity coatings for passive house certification thresholds across commercial retrofits. EU Green Deal renovation wave targets accelerate specification of high-performance thermal insulation coatings in existing building stock. Bavaria and North Rhine-Westphalia cluster glazing suppliers serving Dutch and Austrian export markets.
United States
EPA volatile organic compound emission standards constrain solvent-based formulation viability in North American manufacturing. State-level air quality implementation plans in California and the Northeast tighten curing process requirements for transportation glazing. Pacific Northwest and Southeast construction corridors specify solar control stacks for LEED-equivalent commercial developments.
India
BIS energy conservation building code creates specification pull for low-emissivity coatings in Mumbai, Delhi, and Bangalore commercial developments. PLI scheme incentives support domestic manufacturing scale-up for energy-efficient building materials. Maharashtra and Gujarat host emerging coating application facilities serving western India construction markets.
United Arab Emirates
Tower developers in Dubai and Abu Dhabi specify dynamic solar control stacks that modulate visible light transmission across diurnal cycles. MOHAP building efficiency guidelines align with international green certification frameworks for mega-project envelopes. Dubai production facilities import sputtered coated glass for facade integration across Gulf Cooperation Council developments.
Global Flat Glass Coatings Market Competitive Landscape
German and Japanese producers anchor the premium tier through precision sputtering equipment and fluoropolymer chemistry; Chinese fabricators hold volume positions in solar control glazing for domestic mega-projects. The vendor base stratifies across three tiers: multinational chemical conglomerates with integrated pigment-to-coating pipelines, regional specialists in magnetron sputtering technology, and emerging Asian producers scaling atmospheric deposition methods. Strategic archetypes include technology licensors leveraging patent portfolios, backward-integrated pigment suppliers controlling color-stable formulation inputs, and distributor-anchored brands with contractor-direct channel networks. Dominant competitive moves center on certification acceleration to meet compressed EU Green Deal timelines and capacity expansion in six-meter glass format sputtering chambers.
Within the multinational chemical tier, Ferro and Arkema exemplify pigment-to-coating integration strategies. Ferro leverages color-stable formulation leadership for facade glass specifications. Arkema competes on fluoropolymer chemistry for durable exterior applications. Sherwin-Williams Company anchors North American distribution through its contractor-direct channel network, representing the distributor-anchored archetype.
| Leading Market Players |
|---|
| Ferro |
| Sherwin-Williams Company |
| Arkema |
| Nippon Paint |
| Vitro |
| Fenzi |
| Hesse GmbH & Co. KG |
| 3M Company |
| PPG Industries |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap specialists across Germany and Italy anchor supply discipline through conservative leverage policies, translating into sticky contract pricing that resists spot-market volatility even as fluoropolymer feedstock costs fluctuate. Their ownership structure insulates procurement decisions from quarterly earnings pressure, enabling long-term offtake agreements with Japanese precursor suppliers that stabilize coating formulation costs for facade glass specifications.
Pricing Analysis
Volume concentration in Chinese solar control glazing compresses margins at the standard tier, while sputtered multi-layer stacks for UAE tower developments capture premium pricing through performance certification. Price differentiation hinges on magnetron deposition precision and EU Green Deal compliance tier, with REACH-registered formulations commanding substantial premiums over import-dependent alternatives. Cost compression in decorative coatings is intensifying because atmospheric deposition methods face overcapacity in Asian markets. Mega-project developers exhibit lowest price sensitivity due to whole-building energy modeling requirements, whereas furniture manufacturers negotiate aggressively on spot purchases.
Supply Chain Analysis
Regional distribution centers in Rotterdam and Singapore coordinate hub-and-spoke patterns for architectural glass coatings, consolidating shipments from German and Japanese production clusters before final-mile delivery to tower construction sites. Manufacturing gravity centers on China, Germany, and Japan, with Yangtze River Delta fabricators scaling six-meter sputtering chambers for domestic mega-project demand. Specialty fluorinated precursors draw from limited Japanese and German chemical suppliers, creating single-source vulnerability for durable exterior formulations. Distribution runs through contractor-direct channels in North America and specification-platform intermediaries in European retrofit markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
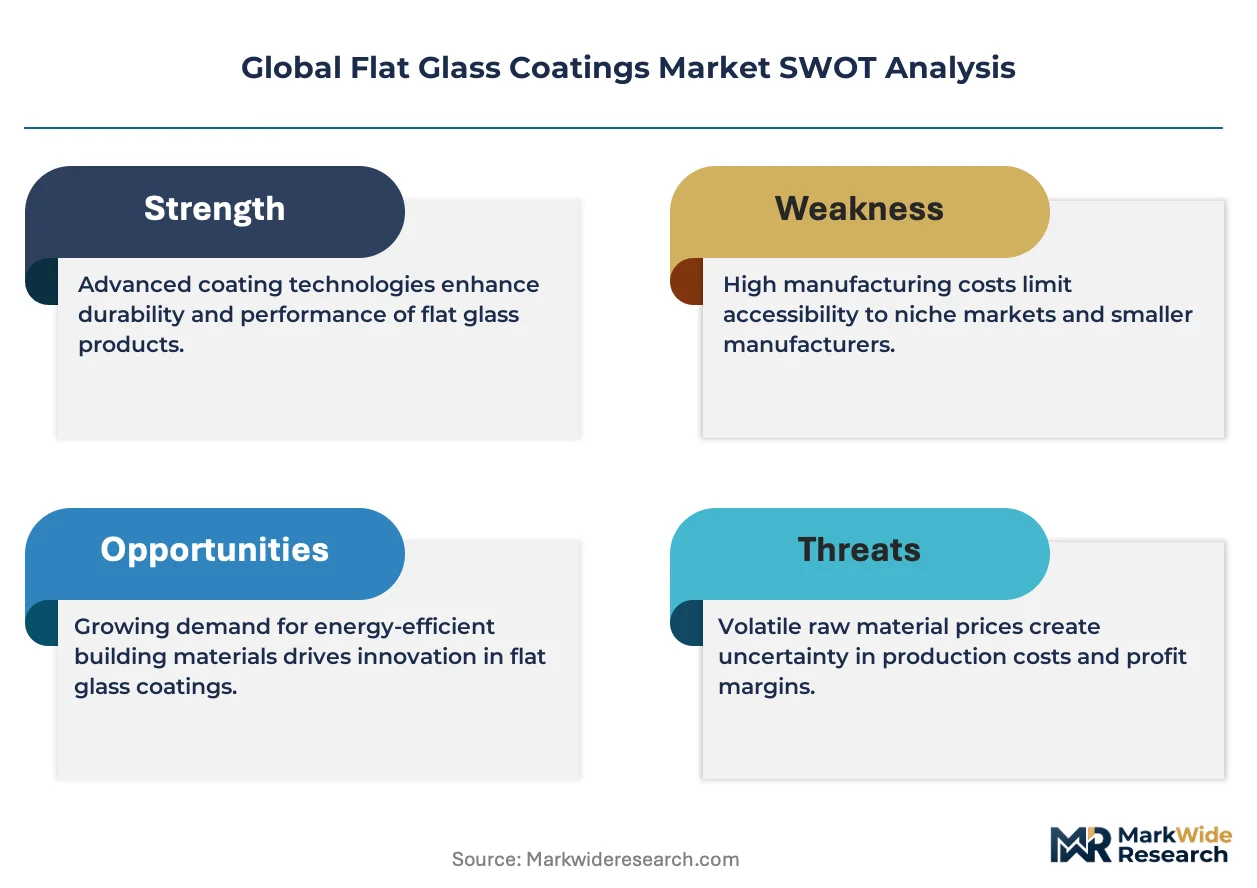
Flat glass coatings function as a cost-of-compliance market where REACH substance registration and EU Green Deal certification timelines erect formidable barriers against non-compliant competitors, entrenching incumbents with established ECHA dossiers and validated thermal performance data.
For Market Incumbents: Cement certification leadership by accelerating dual-carbon validation for Chinese export volumes ahead of tightening EU Carbon Border Adjustment Mechanism documentation requirements. Deepen backward integration into color-stable pigment production to neutralize Ferro's formulation advantages in facade glass specifications. Prioritize capacity expansion in six-meter sputtering formats serving UAE and Singapore tower developments where procurement consolidation favors qualified suppliers with proven deposition uniformity. For New Entrants and Emerging Players: Begin with India's BIS energy conservation building code corridor, where domestic manufacturing incentives under the PLI scheme reduce import dependency and specification pull for low-emissivity coatings outpaces established supply. Target Mumbai and Bangalore commercial developments through direct-to-developer digital channels that disintermediate traditional distributor networks. Emphasize waterborne formulation platforms that preempt EPA VOC compliance constraints affecting solvent-based competitors in North American transportation glazing. For Investors and Strategic Acquirers: First-mover magnetron sputtering equipment orders for sub-1.0 W/m²K thermal insulation stacks are the leading indicator that Nordic climate envelope specifications are tightening faster than incumbent capacity expansion. Position for five-to-ten year viability by acquiring regional specialists with validated ECHA registrations and existing six-meter deposition capabilities rather than greenfield atmospheric deposition plays. Monitor BIS code implementation velocity in Maharashtra and Gujarat as the signal for Indian market entry timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluoropolymer Precursors | Captive supply of Japanese and German specialty chemicals reduces feedstock vulnerability for exterior durability formulations. |
| Capacity Expansion in Six-Meter Sputtering Chambers | UAE and Singapore tower developers specify dynamic solar control stacks requiring nanometer uniformity across architectural glass formats. |
| REACH Acceleration for EU Green Deal Timelines | ECHA substance registration ahead of renovation wave mandates secures specification access in German and Dutch passive house retrofits. |
| Waterborne Platform Development | EPA VOC emission standards in California and Northeast states constrain solvent-based curing infrastructure for transportation glazing suppliers. |
| Direct-to-Developer Digital Channel Launch | Specification platforms disintermediate traditional distribution for mega-project procurement decisions in China and India commercial corridors. |
Research Methodology
Multi-period observation of magnetron sputtering capacity additions, EU Green Deal renovation permit filings, and BIS code adoption rates anchored the trend analysis, supplemented by interviews with plant managers at Yangtze River Delta fabricators, procurement leads at UAE tower developers, technical R&D directors at pigment suppliers, and channel partners in North American contractor-direct networks. Secondary validation drew from ECHA substance registration databases, SEC 10-K filings of coating suppliers, customs and trade data for fluoropolymer precursor flows, and ACC industry reports. Bottom-up project pipeline enumeration triangulated against top-down macroeconomic construction forecasts to isolate coating-specific demand drivers.
Segment-weighting across product type, coating technology, application, and end-user industry dimensions informed volume and value allocation throughout the projection horizon. Low-emissivity and solar control categories received differential weighting based on building code implementation schedules in temperate climates. Sputtering and physical vapor deposition technologies were modeled separately from atmospheric processes to capture margin tier divergence. CAGRs derived from equipment order backlogs, renovation wave target trajectories, and mega-project procurement cycle analysis rather than extrapolation of historical growth rates. Carbon border adjustment mechanism implementation timelines and F-Gas Regulation phase-down schedules served as scenario modifiers for European demand trajectories.
Underlying measurement precision varies by segment; architectural glass and automotive applications carry tighter precision than furniture and lighting fixture categories due to more consolidated procurement data availability. Forecasts reflect documented assumptions regarding EU Green Deal enforcement intensity, MEE dual carbon goal implementation pace, and fluoropolymer precursor supply continuity. Silica aerogel substitution velocity in high-performance envelopes and cross-border carbon certification documentation complexity represent specific risk factors that could materially revise demand projections. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Coating Market
Coatings
Marking Coatings Market
Coatings
Antifouling Coatings Market
Coatings
Germany Protective Coatings Market
Coatings
Conductive Polymer Coatings Market
Coatings
Electrical Appliance Coatings Market
Coatings
2K Protective Coatings Market
Coatings
Ultraviolet (UV) Coatings Market
Coatings
Cold Gas Spray Coating Market
Coatings
North America Anti-Friction Coatings Market
Coatings
Global PET Film Coated Steel Coil Market
Coatings
Tablet and Pellet Coating Systems Market
Coatings
Breathable Antimicrobial Coatings Market
Coatings
US Industrial Coatings Market
Coatings
Silicone Coating Market
Coatings
Conductive Coatings Market