
 Montelukast Intermediate Market | 2026-2036
Montelukast Intermediate Market Size, Share, and Industry Trends Forecast 2026-2036
Montelukast Intermediate Market Outlook
Buyer concentration among generic pharmaceutical manufacturers is recalibrating as patent expirations fragment procurement across mid-size formulators. Neuland Laboratories Ltd. anchors high-purity custom synthesis capabilities for leukotriene antagonist precursors. Morepen Laboratories Ltd. leverages backward integration into advanced intermediates to control cost structures. Jubilant Life Sciences Ltd. dominates North American supply relationships through FDA-audited facilities.
Montelukast intermediates comprise chiral synthetic precursors—specifically the methylindole and cyclopropylacetic acid fragments—that enable stereoselective assembly of the leukotriene receptor antagonist. These molecules require controlled crystallization and enantiomeric purity exceeding 99.5% to meet pharmacopeial specifications for downstream API integration. Active Pharmaceutical Ingredients command the dominant value share as manufacturers seek to internalize regulatory dossier control, while Contract Manufacturers represent the fastest-growing end-user channel as Big Pharma outsources non-core synthesis. Direct Sales channels capture premium pricing for validated batches, whereas distributor networks serve spot-market procurement for smaller formulators.
FDA's Drug Master File requirements and India's CDSCO Schedule M standards collectively elevate barrier thresholds for new intermediate suppliers seeking commercial scale. The EPA's pharmaceutical effluent guidelines and REACH's Substance of Very High Concern protocols further constrain solvent recovery and waste discharge economics across manufacturing sites. EMA's revised ICH Q7 guidelines on good manufacturing practice for APIs are tightening audit frequencies for intermediate producers supplying European formulation facilities. Stakeholders must monitor regulatory divergence between FDA and EMA inspection protocols to anticipate compliance cost trajectories.
Market Dynamics
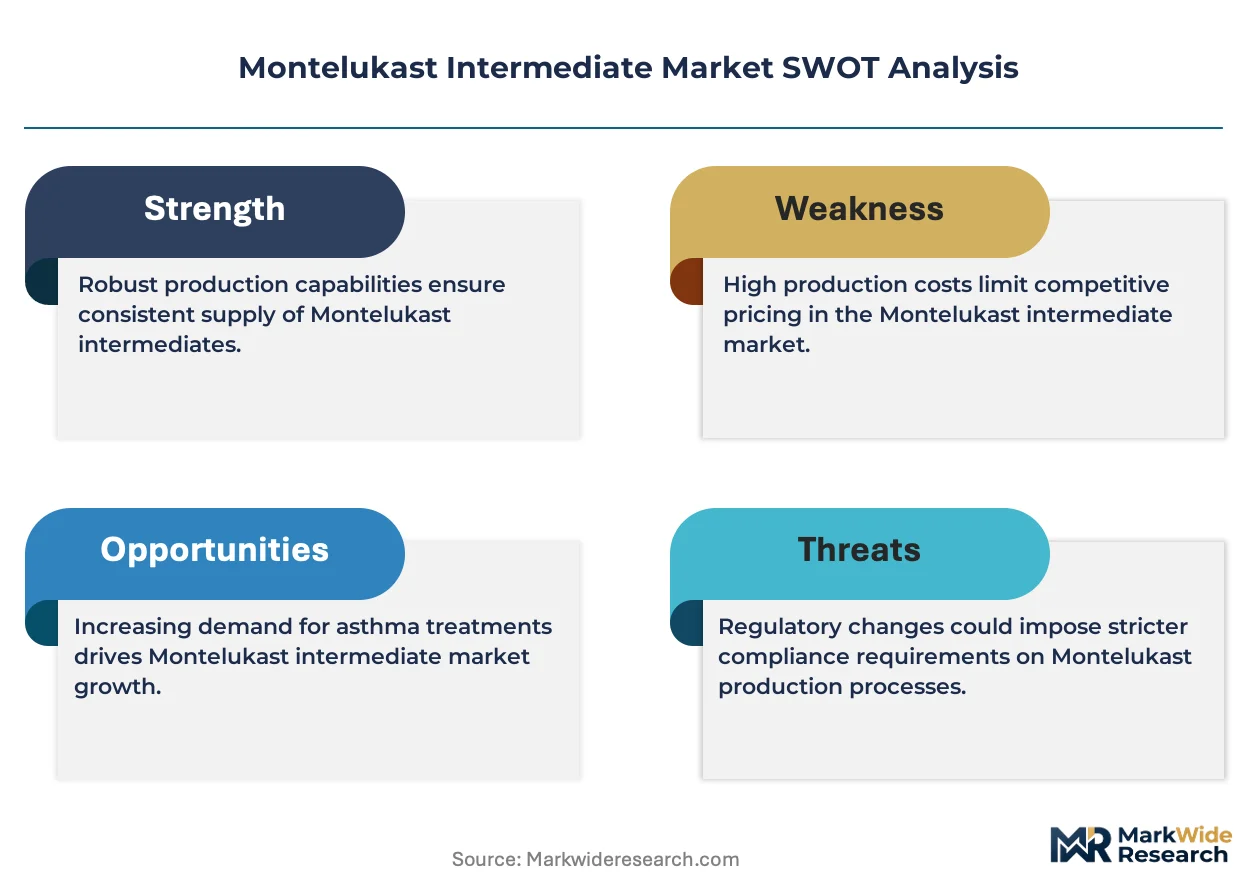
Patent cliff dynamics are fragmenting procurement authority across mid-size generic formulators, eroding the volume leverage historically concentrated among originator-aligned suppliers and forcing intermediate producers to reconfigure their customer segmentation and validation batch economics.
Growth Catalysts
- India's PLI scheme for APIs:The production-linked incentive framework is subsidizing capital expenditure for domestic intermediate manufacturing, compressing cost structures for export-oriented suppliers.
- Leukotriene antagonist demand:Respiratory therapeutic expansion in emerging markets is sustaining volume requirements for methylindole and cyclopropylacetic acid precursors.
- FDA-audited facility proliferation:Regulatory validation capacity in Telangana and Maharashtra is shortening qualification timelines for North American supply contracts.
Market Restraints
- Solvent cost volatility:Dichloromethane and acetonitrile price swings are compressing margin predictability for crystallization-intensive synthesis steps.
- Enantiomeric purity thresholds:The 99.5% specification ceiling for chiral intermediates is elevating rejection rates and batch failure costs.
- EPA pharmaceutical effluent guidelines:Wastewater discharge constraints are mandating captive recovery infrastructure that raises fixed cost intensity.
Strategic Opportunities
- CDMO channel expansion:Big Pharma outsourcing of non-core synthesis is creating dedicated demand streams for validated intermediate batches.
- REACH SVHC compliance services:European substance registration complexity is enabling premium positioning for dossier-complete suppliers.
- Continuous flow chemistry:Process intensification technologies are opening throughput advantages for early adopters in high-volume precursor segments.
Industry Challenges
- Chiral synthesis expertise scarcity:Stereoselective catalysis competency gaps are constraining workforce scalability for asymmetric hydrogenation steps.
- ICH Q7 audit frequency compression:EMA inspection interval tightening is diverting technical resources from production to compliance documentation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Montelukast Intermediate Market |
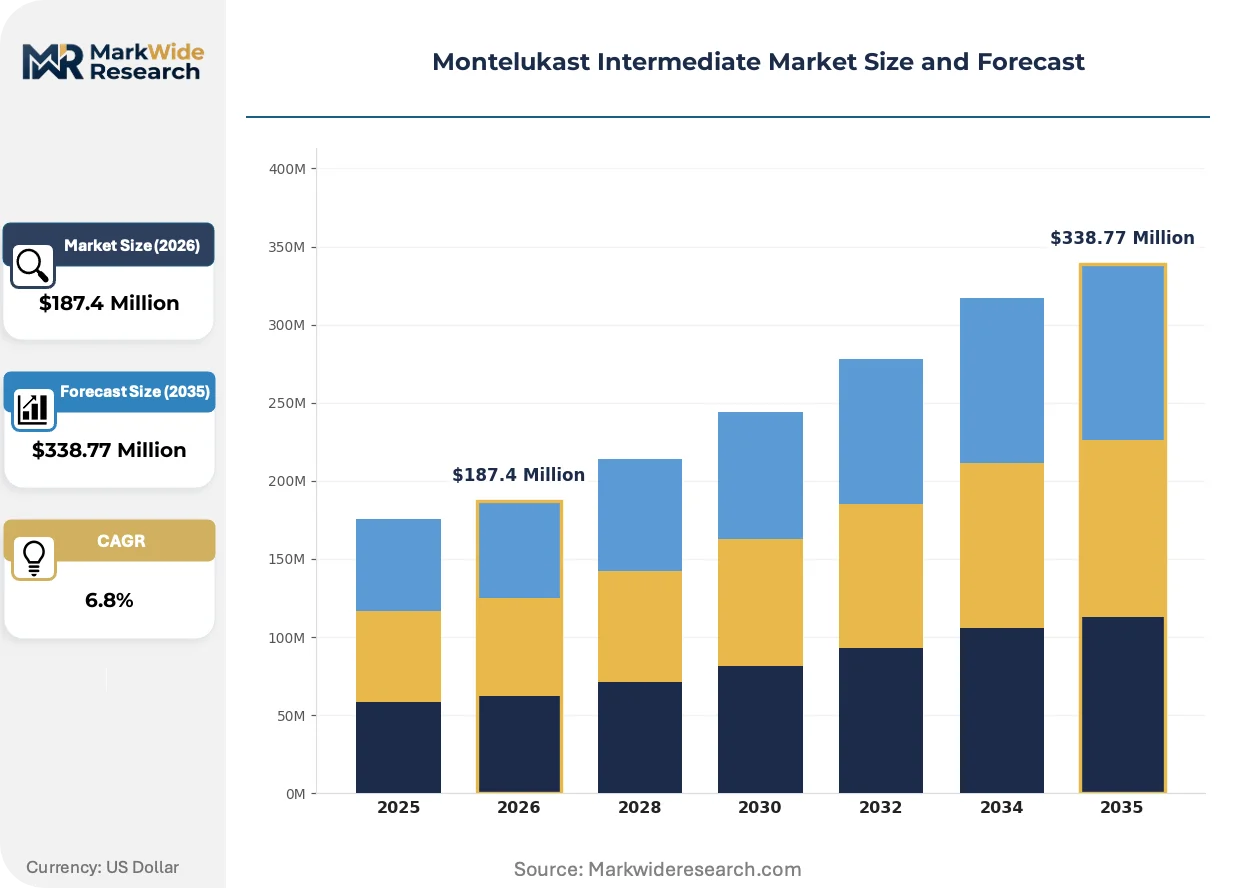
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Intermediates, Active Pharmaceutical Ingredients, Raw Materials, Chemical Precursors Application: Pharmaceutical Manufacturing, Research & Development, Quality Control, Regulatory Testing End User: Pharmaceutical Companies, Contract Manufacturers, Research Institutions, Biotech Firms Distribution Channel: Direct Sales, Online Sales, Wholesalers, Distributors |
| Companies Covered | Neuland Laboratories Ltd., Morepen Laboratories Ltd., Navin Fluorine International Ltd., Jubilant Life Sciences Ltd., Teva Pharmaceutical Industries Ltd., Ortin Laboratories Ltd., Manus Aktteva Biopharma, VIVAN Life Sciences, Divis Laboratories Ltd., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Montelukast Intermediate Market Strategic Shifts
Process analytical technology and regulatory data integrity requirements are converging to reshape how intermediate producers validate batch consistency and manage quality documentation across distributed manufacturing networks.
Continuous manufacturing platforms are integrating real-time release testing protocols into montelukast precursor synthesis lines. Mid-size API manufacturers are adopting these systems to reduce in-process inventory holding and accelerate batch turnover. The technology is integrating quality assurance functions directly into production workflows, compressing the traditional separation between manufacturing and analytical laboratories.
REACH authorization requirements for Substances of Very High Concern are forcing solvent substitution programs across European supply chains. Manufacturers are reformulating crystallization protocols to eliminate chlorinated hydrocarbons from standard operating procedures. Intermediate producers serving EMA-regulated formulation facilities are responding by revalidating entire synthetic routes under revised environmental compliance frameworks.
Buyer consolidation among generic pharmaceutical distributors is compressing supplier qualification cycles and elevating documentation requirements. Direct sales channels are displacing spot-market procurement for validated intermediate grades as formulators seek regulatory dossier continuity. This concentration is most visible in North American supply relationships, where FDA Drug Master File completeness has become a non-negotiable vendor selection criterion.
Montelukast Intermediate Market Segmentation
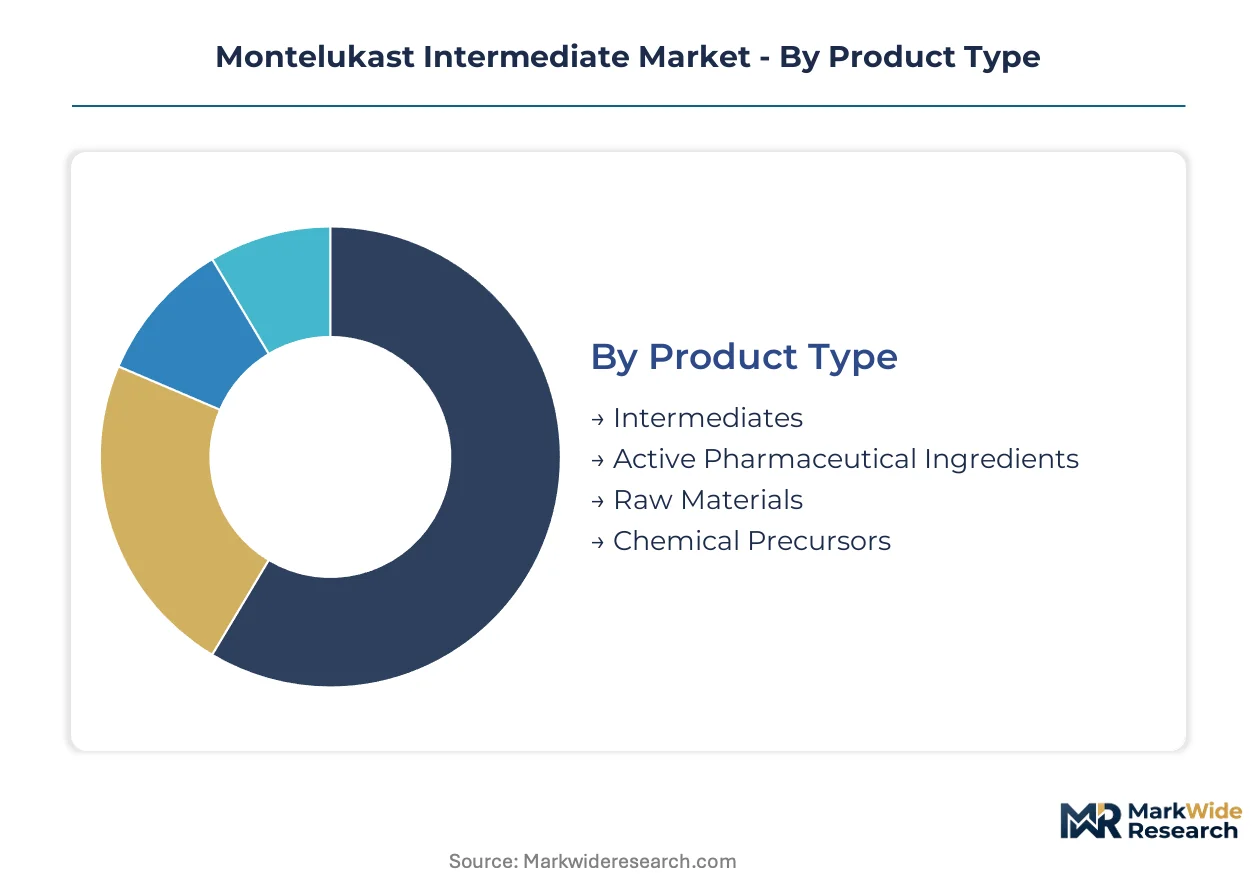
Segmentation in montelukast intermediates reveals how value pools concentrate across regulatory validation tiers and synthesis complexity levels. Each dimension exposes different margin structures and customer loyalty patterns that shape supplier strategy.
Product Type:
Standardization intensity varies sharply across this category, with commoditized inputs at one pole and dossier-controlled specialties at the other.
- Active Pharmaceutical Ingredients:These high-purity finished inputs command premium positioning through pharmacopeial certification and regulatory filing completeness. Indian manufacturers in Telangana and Maharashtra are internalizing API production to capture margin previously lost to European traders, driven by CDSCO Schedule M compliance cost advantages.
- Intermediates:Chiral synthetic precursors—specifically methylindole and cyclopropylacetic acid fragments—require stereoselective assembly and enantiomeric purity exceeding 99.5%. Demand concentrates among generic formulators seeking backward integration into regulated supply chains, constrained by solvent recovery infrastructure requirements.
- Chemical Precursors:Bulk starting materials for multi-step synthesis routes.
- Raw Materials:Unprocessed feedstocks subject to commodity pricing dynamics.
Most installed capacity flows through Intermediates. Expansion is steepest in Active Pharmaceutical Ingredients.
Application:
Volume concentration tracks regulatory burden intensity, with commercial manufacturing absorbing the bulk of validated batch output.
- Pharmaceutical Manufacturing:Commercial-scale synthesis of montelukast sodium for tablet and chewable formulations dominates volume absorption. Maharashtra and Telangana API clusters process the majority of Indian output, driven by FDA audit readiness and PLI scheme capital subsidies.
- Research & Development:Early-stage process development and route scouting for improved stereoselectivity.
- Quality Control:Analytical reference standard production and stability testing protocols.
- Regulatory Testing:Forced degradation studies and impurity profiling for dossier submission.
Pharmaceutical Manufacturing captures the dominant share of qualified supplier relationships. R&D applications are climbing fastest as manufacturers pursue continuous flow chemistry adoption.
End User:
Customer scale and regulatory sophistication create distinct service requirements across this dimension.
- Contract Manufacturers:CDMOs represent the fastest-expanding demand channel as Big Pharma outsources non-core synthesis. These buyers require validated batch documentation and FDA Drug Master File completeness, sourcing heavily from Telangana facilities with shortened North American qualification timelines.
- Pharmaceutical Companies:Integrated generic formulators seeking captive supply security and margin control.
- Research Institutions:Academic and government labs requiring small-batch chiral intermediates for method development.
- Biotech Firms:Emerging therapeutic developers exploring leukotriene pathway modulation.
Pharmaceutical Companies retain the largest committed volume. Contract Manufacturers are gaining share fastest through outsourcing acceleration.
Distribution Channel:
Channel selection reflects buyer scale and regulatory risk tolerance, with direct relationships commanding premium positioning.
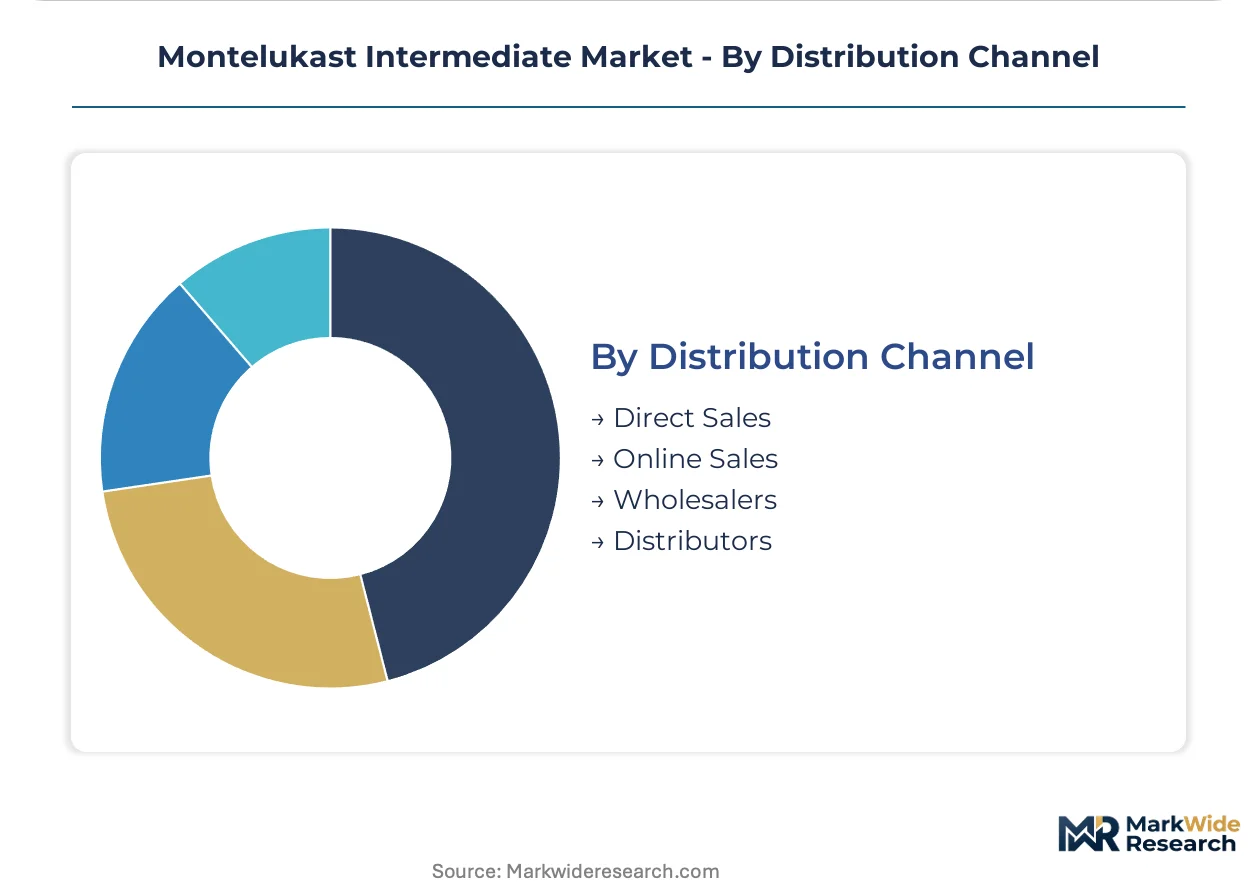
- Direct Sales:Validated batch procurement for large formulators and CDMOs requiring regulatory dossier continuity. FDA Drug Master File completeness has become a non-negotiable selection criterion in North American supply relationships, compressing spot-market participation.
- Distributors:Fragmented spot-market access for smaller formulators with less stringent documentation needs.
- Wholesalers:Inventory pooling for standardized intermediate grades.
- Online Sales:Catalog procurement for research-grade materials and analytical standards.
Direct Sales channels handle the majority of commercial-grade volume. Distributor networks are expanding fastest to serve mid-size generic formulators emerging from patent cliff fragmentation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chiral synthesis expertise clusters in India and China anchor global intermediate supply, with regulatory validation capacity concentrating in Telangana and Maharashtra. European REACH compliance requirements and US FDA audit standards filter supplier participation across geographies.
India
Generic pharmaceutical manufacturers drive methylindole and cyclopropylacetic acid precursor demand as patent cliffs expand the formulator base. CDSCO Schedule M standards and the PLI scheme for APIs subsidize capital expenditure for domestic intermediate manufacturing. Telangana and Maharashtra host FDA-audited facility clusters that compress North American qualification timelines for export-oriented suppliers.
China
Bulk chemical precursor production and multi-step synthesis capabilities support downstream chiral intermediate requirements for global leukotriene antagonist supply. NMPA GMP standards and environmental compliance protocols under MEE oversight constrain solvent recovery economics. Zhejiang and Jiangsu provinces concentrate crystallization-intensive manufacturing with enantiomeric purification infrastructure.
United States
CDMO outsourcing of non-core synthesis creates dedicated demand streams for validated intermediate batches with complete Drug Master File documentation. FDA inspection protocols and EPA pharmaceutical effluent guidelines elevate barrier thresholds for new supplier qualification. New Jersey and Massachusetts clusters process commercial-scale procurement for North American generic formulation facilities.
Germany
REACH Substance of Very High Concern protocols and EMA ICH Q7 guideline enforcement drive solvent substitution programs across European supply chains. ECHA authorization requirements force reformulation of crystallization protocols to eliminate chlorinated hydrocarbons. Bavaria and North Rhine-Westphalia host dossier-complete suppliers serving EMA-regulated formulation facilities with shortened audit cycles.
Switzerland
Swissmedic regulatory standards and precision chemical manufacturing heritage support high-purity chiral intermediate production for premium therapeutic segments. Dual quality system compliance with both EMA and FDA requirements enables cross-Atlantic supply relationships. Basel-region clusters integrate continuous flow chemistry platforms for process intensification in precursor synthesis.
Montelukast Intermediate Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists for procurement relationships with generic formulators and CDMOs. Market structure fragments across three validation tiers: FDA-audited exporters, domestic-scale suppliers, and research-grade batch producers. Strategic archetypes include backward-integrated API manufacturers, custom synthesis specialists, and distributor-linked traders. Capacity expansion in Telangana and Maharashtra and REACH dossier completion for European access represent dominant competitive moves.
Among India-based specialists, Neuland Laboratories Ltd. and Morepen Laboratories Ltd. exemplify the custom synthesis archetype serving leukotriene antagonist precursor demand. Jubilant Life Sciences Ltd. occupies a position representing North American supply relationship concentration through regulatory validation infrastructure. These three entities anchor distinct strategic vectors: chiral purity capability, backward integration economics, and trans-Atlantic dossier completeness.
| Leading Market Players |
|---|
| Neuland Laboratories Ltd. |
| Morepen Laboratories Ltd. |
| Navin Fluorine International Ltd. |
| Jubilant Life Sciences Ltd. |
| Teva Pharmaceutical Industries Ltd. |
| Ortin Laboratories Ltd. |
| Manus Aktteva Biopharma |
| VIVAN Life Sciences |
| Divis Laboratories Ltd. |
| Others |
Value Chain & Pricing Dynamics
Dichloromethane and acetonitrile feedstock volatility cascades through crystallization-intensive synthesis steps, compressing margin predictability for Indian and Chinese manufacturers while fragmenting procurement authority among mid-size generic formulators seeking validated batch economics.
Pricing Analysis
Regulatory dossier bundling separates validated intermediate grades from spot-market chemical precursors. Premium-mid-economy pricing differentiation tracks enantiomeric purity thresholds and FDA Drug Master File completeness, with CDMOs absorbing cost compression for guaranteed supply security. Generic formulators exhibit highest price sensitivity, whereas originator-aligned buyers prioritize batch validation continuity over unit economics.
Supply Chain Analysis
Freight cost differentials between Telangana-Maharashtra clusters and North American formulation facilities favor direct sales channels over distributor networks. Supply concentration rests on India, China, and Switzerland for chiral synthesis expertise, with methylindole and cyclopropylacetic acid fragments drawing from petrochemical and fine chemical feedstocks. Single-source vulnerability around FDA-audited facility capacity constrains supply elasticity. Distribution runs through validated batch procurement for large formulators and CDMOs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story as leukotriene antagonist demand shifts toward 99.5% enantiomeric purity specifications that only dossier-complete suppliers can reliably deliver.
For Market Incumbents: Extend regulatory validation infrastructure into continuous flow chemistry platforms to defend against process intensification disruptors. Deepen backward integration into solvent recovery systems to offset EPA effluent guideline compliance costs. Prioritize Telangana capacity expansion to compress North American qualification timelines for CDMO procurement relationships.
For New Entrants and Emerging Players: India's PLI scheme for APIs opens a window for capital-efficient entry into methylindole precursor manufacturing with subsidized equipment depreciation. Target research-grade chiral intermediates for academic and biotech method development buyers before scaling into commercial validation tiers. Lead with REACH SVHC compliance services to differentiate in European supply relationships.
For Investors and Strategic Acquirers: Roll-up economics work for FDA-audited custom synthesis specialists because patent cliff fragmentation is multiplying mid-size formulator procurement relationships beyond single-supplier capacity. Focus acquisition screening on Telangana and Maharashtra facilities with shortened North American qualification timelines. Monitor EMA ICH Q7 audit frequency compression as a signal for compliance cost inflection and vendor consolidation acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Continuous Flow Chemistry Adoption | Process intensification reduces solvent inventory holding for crystallization-intensive chiral synthesis steps. |
| REACH SVHC Compliance Investment | Dossier completion enables premium positioning for European leukotriene antagonist formulation supply. |
| FDA Drug Master File Expansion | Regulatory filing completeness has become non-negotiable for North American CDMO procurement relationships. |
| Backward Integration into Solvent Recovery | Captive infrastructure offsets EPA pharmaceutical effluent guideline compliance cost intensity. |
| PLI Scheme Capacity Buildout | Indian capital subsidies compress cost structures for export-oriented methylindole precursor manufacturing. |
Study Parameters
Multiple input streams — regulatory filing databases, customs trade records, and manufacturing capacity registries — were reconciled with primary interviews involving API plant managers, CDMO procurement leads, regulatory affairs directors at generic formulators, and fine chemical distribution channel partners. Secondary validation drew from FDA Drug Master File listings, EMA inspection reports, CDSCO Schedule M compliance records, and Indian PLI scheme beneficiary disclosures. Bottom-up facility capacity aggregation and top-down therapeutic demand estimation were cross-checked for triangulation integrity.
Data-stream reconciliation across product type, application, end user, and distribution channel dimensions generated volume and value estimates over the projection horizon. CAGRs were derived from regression analysis against patent expiration timelines and respiratory therapeutic expansion trajectories. Industry-specific forecast inputs incorporated leukotriene antagonist prescription volume patterns and chiral synthesis technology adoption curves.
Revisions become necessary when regulatory audit protocol divergence, solvent feedstock price shocks, or continuous flow chemistry disruption materialize beyond modeled assumptions. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Chemical Intermediates
Global Chemical Intermediates Market
Chemical Intermediates
Acetamide MEA Market
Chemical Intermediates
API Intermediate Market
Chemical Intermediates
Potential Hydrogen (Ph) Adjusters Market
Chemical Intermediates
Grignard Reagents Market
Chemical Intermediates
Nutrition Chemicals Market
Chemical Intermediates
Tetrahydrocurcumin Reagent Market
Chemical Intermediates
Hydroxyisobutyric Acid Market
Chemical Intermediates
Tertiary Amines Market
Chemical Intermediates
Polyamide Intermediate Chemicals Market
Chemical Intermediates
Molybdenum Disulfide (MoS2) Market
Chemical Intermediates
Ethylene Urea Market
Chemical Intermediates
1, 3, 5-Triazine Market
Chemical Intermediates
Octenylsuccinate Market
Chemical Intermediates
Phosphate Chemical Reagents Market
Chemical Intermediates
Glycidyl Methacrylate Market