
 FEVE Fluoropolymer Coatings Market | 2026-2036
FEVE Fluoropolymer Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
FEVE Fluoropolymer Coatings Market Foresight
Waterborne resin chemistry is tilting the FEVE coatings technology stack away from solvent-borne systems in high-VOC jurisdictions. Daikin Industries leverages its fluoropolymer monomer captive supply to dominate premium architectural specifications in East Asia. PPG Industries anchors North American demand through spec-grade coil coating partnerships with major metal fabricators. Sherwin-Williams competes on distribution density, sustaining channel control across fragmented contractor networks.
FEVE fluoropolymer coatings consist of fluoroethylene-vinyl ether copolymers that cure into thin films with gloss retention exceeding conventional PVDF systems, typically applied at 25-40 micrometres dry film thickness to deliver 30-year colour stability on aluminium and steel substrates. Architectural coatings occupy the largest value pool given lifecycle cost advantages in curtain wall and cladding applications, while liquid formulations lead volume due to spray-applied field flexibility on complex geometries. Powder coatings represent the fastest-growing form segment as electrostatic application lines expand at OEM metal coating facilities seeking zero-VOC compliance.
Japan's METI enforces Industrial Standards (JIS) for exterior coating durability that effectively mandate fluoropolymer-grade performance on public buildings. China's MEE implements GB 30981 and successive VOC limits that force reformulation toward compliant FEVE chemistries. The EU REACH framework restricts certain fluorinated precursor substances, reshaping raw material sourcing for European-formulated products. Stakeholders must monitor regulatory divergence between Asian VOC phase-down schedules and European PFAS restriction proposals to anticipate formulation lock-in risks.
Market Dynamics
Waterborne resin chemistry is compressing the solvent-borne FEVE coatings segment as China's MEE tightens GB 30981 VOC ceilings and Japan's METI extends JIS durability mandates to public infrastructure refurbishment.
Growth Catalysts
- MEE VOC Phase-Down:China's GB standards force reformulation toward compliant FEVE chemistries, accelerating solvent-to-waterborne conversions across Guangdong and Jiangsu coating clusters.
- Curtain Wall Lifecycle Economics:30-year weathering warranties on aluminium substrates displace polyurethane alternatives in coastal Chinese mega-infrastructure specifications.
- Japan's Aging Commercial Stock:Architectural facade refurbishment across Tokyo and Osaka commercial districts concentrates solvent-based FEVE demand for field-applied recoating flexibility.
Market Restraints
- Fluoromonomer Supply Concentration:Captive fluoropolymer feedstock production concentrates among Japanese chemical conglomerates, creating input cost volatility for non-integrated formulators.
- EU REACH Precursor Restrictions:ECHA scrutiny of fluorinated building blocks reshapes raw material sourcing for European-formulated FEVE products, extending qualification timelines.
- PVDF Substitution Threat:Kynar-grade coatings retain cost advantages in coil-applied aluminium specifications where dry-film thickness tolerance permits thicker deposition.
Strategic Opportunities
- India's Coastal Infrastructure:Underpenetrated FEVE specification in Mumbai and Chennai port facilities creates openings for corrosion-resistant cladding warranties exceeding conventional epoxy-polyester systems.
- Powder FEVE Expansion:Electrostatic application line investments at OEM metal coating facilities unlock zero-VOC compliance without sacrificing fluoropolymer-grade weathering performance.
- Dual Carbon Policy Tailwinds:China's national carbon neutrality targets accelerate low-VOC coating procurement mandates across state-owned construction enterprises.
Industry Challenges
- Formulation Chemist Scarcity:Fluoropolymer resin synthesis expertise concentrates among aging technical workforces in Osaka and Shanghai, constraining R&D expansion at mid-tier coating houses.
- Qualification Protocol Complexity:JIS K 5659 and GB/T 9755 accelerated weathering certification cycles extend 18-24 months, delaying product commercialization for reformulated waterborne systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | FEVE Fluoropolymer Coatings Market |
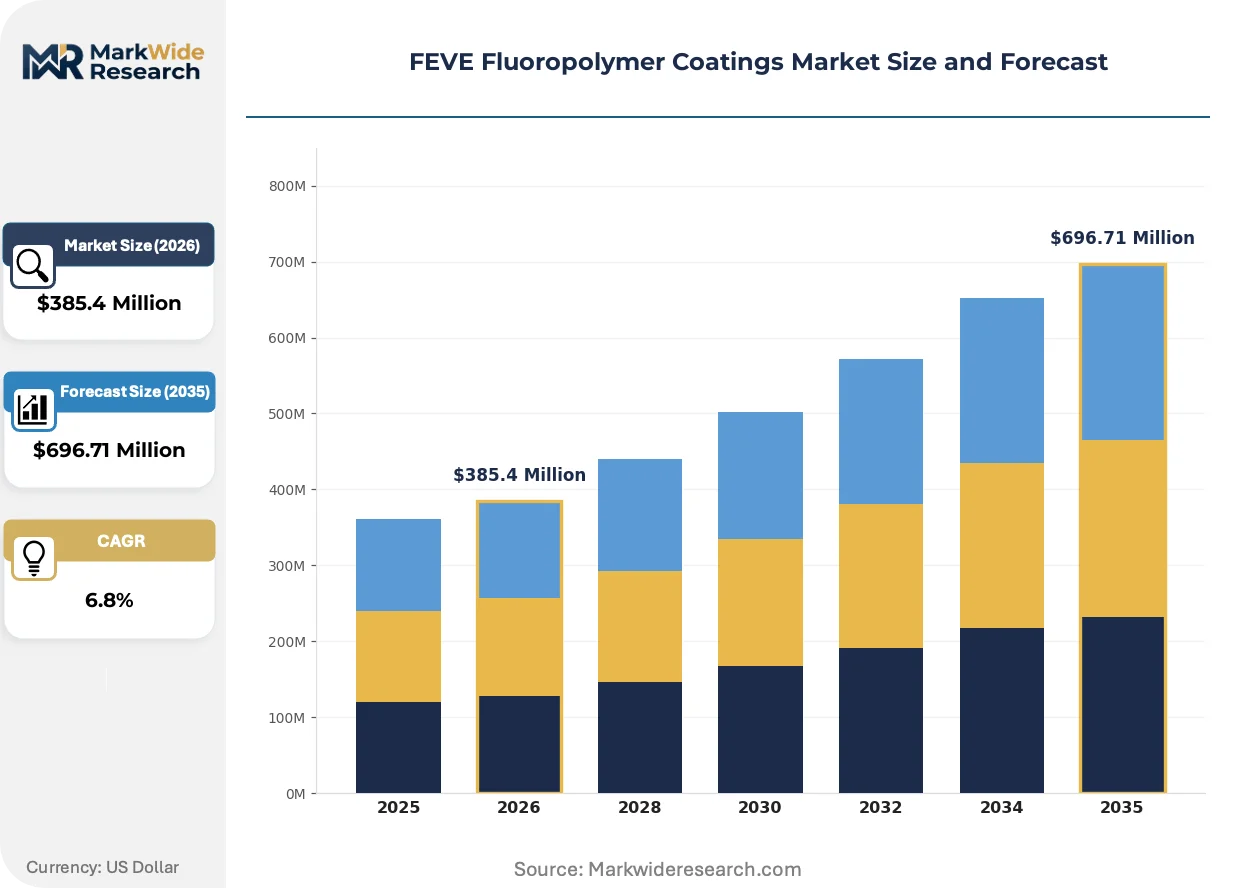
| Market Size in 2026 | $385.4 Million |
| Market Size in 2035 | $696.71 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Architectural Coatings, Industrial Coatings, Automotive Coatings, Marine Coatings End User: Construction, Aerospace, Automotive, Electronics Application: Protective Coatings, Decorative Coatings, Aerospace Coatings, Electrical Insulators Form: Liquid, Powder, Film, Granular |
| Companies Covered | Daikin Industries, AGC, PPG Industries, Tnemec, Kansai Paint, AkzoNobel, KCC Corporation, Zhejiang Zhongxin Fluoride Material, Sherwin-Williams, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
FEVE Fluoropolymer Coatings Market Shifts & Advancements
FEVE coatings technology is bifurcating between ultra-durable architectural specifications and compliant industrial formulations as regulatory chemistry constraints tighten across East Asian manufacturing clusters.
Hybrid waterborne-fluoropolymer resin systems are rendering obsolete conventional solvent-borne FEVE in high-VOC jurisdictions. Japanese and Chinese architectural specifiers now mandate these chemistries for public building refurbishments. The shift compresses solvent-based product lines to niche field-repair applications where spray equipment compatibility lags.
REACH restrictions on per- and polyfluoroalkyl substance precursors are forcing European formulators to qualify alternative fluorinated building blocks. ECHA regulatory scrutiny extends substance evaluation timelines by 12-18 months. Powder coating segments respond fastest, leveraging existing electrostatic lines to bypass liquid formulation compliance burdens.
Certificate-driven procurement now dominates Chinese state-owned construction tenders, with GB/T environmental labels displacing price-only vendor selection. Tier-one contractors in Beijing and Shenzhen bundle coating warranties into design-build contracts. This consolidation concentrates specification authority among certified applicator networks with documented 30-year performance track records.
FEVE Fluoropolymer Coatings Market Segmentation
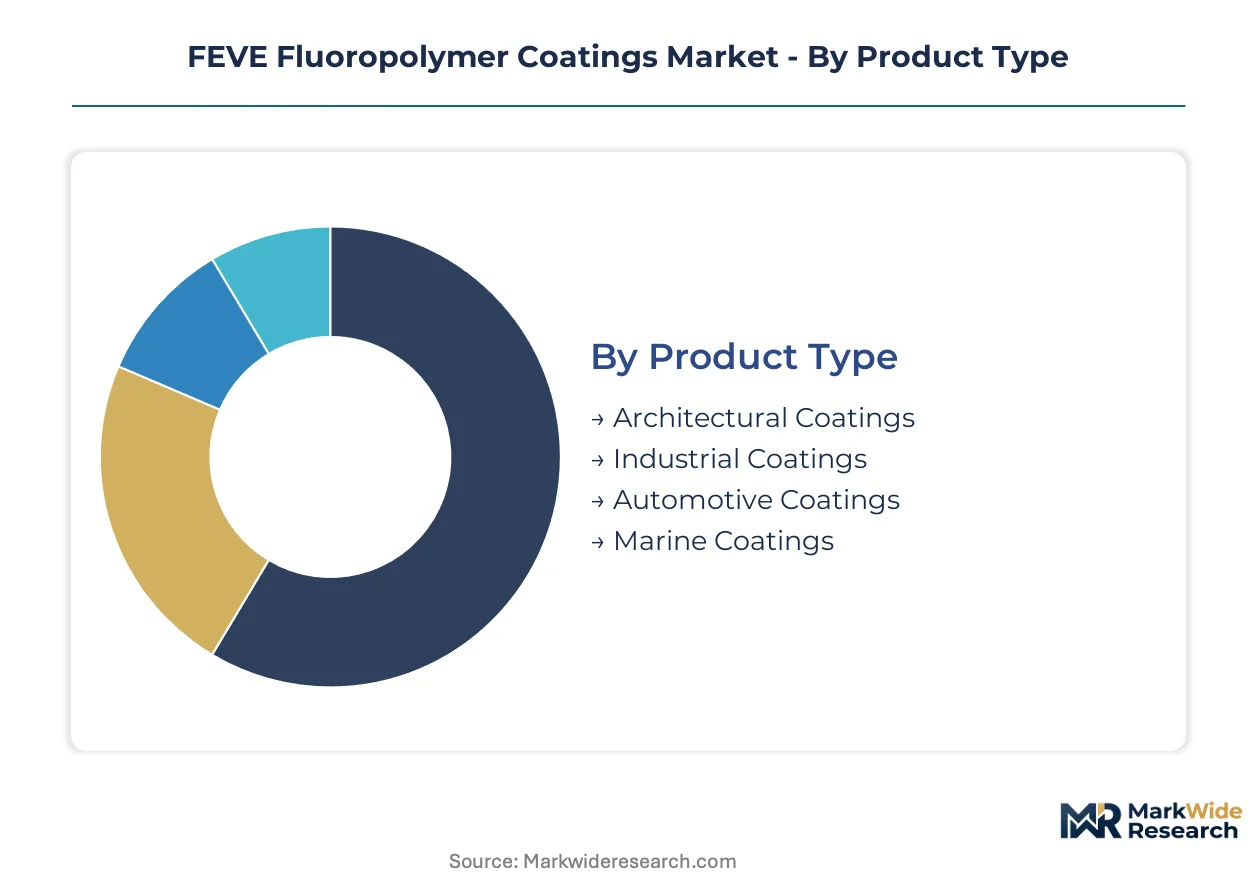
FEVE fluoropolymer coatings segment along four critical dimensions that determine specification pathways, procurement economics, and technical qualification requirements. Product type and form classifications drive formulation chemistry decisions, while end-user and application segments dictate performance warranty structures and certification protocols.
Product Type:
After-sales service intensity varies sharply across product type segments, with architectural specifications demanding multi-decade warranty support and industrial applications requiring rapid technical response for line interruptions.
- Architectural Coatings:These formulations cure into thin films at 25-40 micrometres dry film thickness, delivering 30-year colour stability on aluminium curtain walls and steel cladding. Demand concentrates in coastal Chinese provinces where mega-infrastructure projects mandate extended weathering warranties that displace polyurethane alternatives.
- Industrial Coatings:Heavy-duty FEVE systems protect chemical processing equipment and infrastructure against aggressive corrosion environments. Procurement in Japan's aging industrial zones emphasizes field-applied recoating flexibility for maintenance turnarounds.
- Automotive Coatings:Premium automotive exterior finishes leverage FEVE gloss retention for luxury vehicle segments.
- Marine Coatings:Corrosion-resistant formulations serve offshore platforms and vessel superstructures in salt-laden environments.
By volume, architectural coatings lead. By growth pace, industrial coatings are ahead as refurbishment cycles accelerate across East Asian manufacturing belts.
End User:
Cost tier stratification separates specification-grade construction procurement from price-sensitive electronics applications, with aerospace occupying a premium certification tier above automotive volume contracts.
- Construction:Public building tenders in China and Japan now bundle coating warranties into design-build contracts, concentrating authority among certified applicator networks with documented performance track records.
- Aerospace:Exterior aircraft finishes demand extreme UV resistance and gloss retention through high-altitude thermal cycling. Qualification protocols extend 18-24 months for reformulated systems seeking JIS or GB certification.
- Automotive:OEM metal coating facilities invest in electrostatic application lines for zero-VOC compliance without sacrificing fluoropolymer-grade weathering performance.
- Electronics:Thin-film FEVE applications serve precision equipment housings requiring chemical resistance.
Construction commands the largest value pool. Aerospace exhibits the steepest expansion trajectory as next-generation aircraft production ramps.
Application:
Application segmentation reflects functional performance hierarchies rather than substrate differences, with protective specifications prioritizing corrosion resistance and decorative segments emphasizing aesthetic durability.
- Protective Coatings:Heavy-duty FEVE systems deliver barrier protection against salt spray, chemical splash, and industrial atmospheres. Demand clusters at Mumbai and Chennai port facilities where corrosion-resistant cladding warranties exceed conventional epoxy-polyester system lifespans.
- Decorative Coatings:High-gloss architectural finishes maintain colour fidelity through decades of UV exposure. Tokyo and Osaka commercial districts drive solvent-based FEVE demand for field-applied recoating flexibility on complex facade geometries.
- Aerospace Coatings:Exterior aircraft applications combine weight minimization with extreme durability.
- Electrical Insulators:FEVE films provide dielectric protection in high-voltage equipment.
Protective coatings dominate volume. Decorative coatings are climbing fastest as refurbishment cycles shorten across aging East Asian commercial stock.
Form:
Supply concentration in fluoromonomer production shapes form segment economics, with liquid formulations benefiting from established distribution networks and powder systems requiring captive resin synthesis capabilities.
- Liquid:Spray-applied liquid FEVE dominates field flexibility for complex geometries and on-site recoating. China's MEE VOC phase-down under GB 30981 accelerates solvent-to-waterborne conversions across Guangdong and Jiangsu coating clusters.
- Powder:Electrostatic application enables zero-VOC compliance at OEM metal coating facilities. The segment expands most quickly as electrostatic line investments bypass liquid formulation compliance burdens.
- Film:Pre-formed FEVE films serve specialized lamination applications.
- Granular:Solid resin forms support compounding and masterbatch operations.
Liquid formulations lead by volume. Powder coatings gain share fastest as regulatory chemistry constraints tighten across East Asian manufacturing clusters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Japanese fluoropolymer resin producers supply premium architectural coating specifications to coastal Chinese infrastructure projects and Southeast Asian refurbishment markets. Trade corridors connect Osaka-based monomer synthesis to Guangdong coating compounders and Singaporean specification houses.
China
MEE enforcement of GB 30981 VOC ceilings forces solvent-to-waterborne conversions across Guangdong and Jiangsu coating clusters. Dual carbon policy targets accelerate low-VOC procurement mandates at state-owned construction enterprises. Mega-infrastructure specifications in Shenzhen and Shanghai mandate 30-year weathering warranties on aluminium curtain walls.
Japan
METI extends JIS K 5659 durability mandates to public building refurbishments across Tokyo and Osaka commercial districts. Aging facade stock drives solvent-based FEVE demand for field-applied recoating flexibility. Daikin Industries anchors captive fluoromonomer supply from Osaka technical centers.
United States
EPA industrial coating regulations and state-level VOC limits in California shape reformulation requirements for architectural specifications. PPG Industries anchors North American demand through spec-grade coil coating partnerships with metal fabricators. Gulf Coast petrochemical corridors supply fluorinated feedstocks to Midwest OEM coating facilities.
Germany
ECHA REACH scrutiny of fluorinated precursor substances extends substance evaluation timelines for European-formulated products. Industrial coating demand clusters in North Rhine-Westphalia and Baden-Württemberg manufacturing belts. AkzoNobel operates specification-grade production serving Central European architectural refurbishment.
India
BIS certification requirements and coastal corrosion environments drive specification-grade procurement at Mumbai and Chennai port facilities. Underpenetrated FEVE warranties exceed conventional epoxy-polyester system lifespans in salt-laden atmospheres. Western and Southern industrial corridors attract technical partnership investments from East Asian resin suppliers.
FEVE Fluoropolymer Coatings Market Competitive Landscape
On the supply side, the industry is bifurcated between captive fluoromonomer producers and formulation-dependent coating houses. Japanese chemical conglomerates concentrate upstream resin synthesis, while North American and European players compete on specification-grade application expertise and distribution density. Three archetypes dominate: integrated monomer-to-coating conglomerates, specification-focused architectural specialists, and regional distribution-anchored formulators. Competitive moves center on electrostatic powder line investments for zero-VOC compliance and strategic partnerships with certified applicator networks.
Within the integrated conglomerate tier, Daikin Industries and AGC exemplify captive supply chain control from fluoropolymer monomer through premium architectural specifications. PPG Industries occupies a position among North American specification-grade specialists, while Kansai Paint and KCC Corporation represent East Asian formulation houses competing on JIS-certified durability guarantees. Chinese participants including Zhejiang Zhongxin Fluoride Material sit within the regional feedstock-to-formulation expansion archetype.
| Leading Market Players |
|---|
| Daikin Industries |
| AGC |
| PPG Industries |
| Tnemec |
| Kansai Paint |
| AkzoNobel |
| KCC Corporation |
| Zhejiang Zhongxin Fluoride Material |
| Sherwin-Williams |
| Others |
Supply & Pricing Matrix
Single-source fluoromonomer dependency in Japanese resin synthesis determines both the premium-to-economy pricing spread across architectural specifications and the geographic clustering of formulation capacity around Osaka and Shanghai technical centers. This concentration forces non-integrated coating houses to absorb input volatility while integrated conglomerates capture margin through captive supply.
Pricing Analysis
Waterborne-to-solvent pricing gaps separate current-generation compliant formulations from prior-generation high-VOC systems facing regulatory phase-down. Three-tier pricing structure across premium JIS-certified architectural grades, standard industrial specifications, and economy coil-coating tiers reflects certification investment and fluoropolymer resin purity. Cost compression in solvent-borne segments is intensifying because China's MEE enforcement accelerates conversion timelines. Construction procurement teams at state-owned enterprises exhibit lowest price sensitivity given bundled warranty requirements, while fragmented metal fabricators in Jiangsu province remain most cost-conscious.
Supply Chain Analysis
Japan's export-control scrutiny of fluorinated precursor technologies limits cross-border flows of proprietary resin synthesis know-how, constraining capacity expansion outside established technical centers. Fluoropolymer feedstock production concentrates in Japan, China, and South Korea, with formulation compounding clustering in Guangdong and Jiangsu provinces. Raw material dependencies center on vinyl ether monomers, fluorinated solvents, and specialized cross-linking agents. Single-source vulnerability runs through Daikin's captive monomer supply to premium architectural specifications. Distribution runs through certified applicator networks that bundle technical service with product procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FEVE coatings market sits at a cyclical recovery phase driven by China's post-pandemic infrastructure stimulus accelerating mega-project specifications.
For Market Incumbents: Harden specification-grade positioning through backward integration into fluoromonomer production or exclusive supply agreements with Japanese resin producers, defending against PVDF substitution in coil-applied segments. Deepen JIS K 5659 certification portfolios to lock out mid-tier competitors facing 18-24 month qualification barriers. For New Entrants and Emerging Players: Build out powder FEVE production lines serving OEM metal coating facilities in India's underpenetrated Western and Southern industrial corridors, where electrostatic application enables zero-VOC compliance without legacy solvent-borne infrastructure. Target Mumbai and Chennai port facility refurbishments with corrosion-resistant cladding warranties exceeding epoxy-polyester system lifespans. For Investors and Strategic Acquirers: The market sits at an early-expansion phase that favors integrated resin-to-coating conglomerates with captive fluoropolymer supply and established certification track records. Long-term viability hinges on regulatory chemistry adaptation capacity across the next decade. Acquisition focus should center on Japanese or Chinese formulation houses with documented 30-year performance warranties. The signal to watch is MEE enforcement intensity accelerating solvent-to-waterborne conversion timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Fluoromonomer Production | Captive resin supply insulates margin volatility from Japanese chemical conglomerate pricing power. |
| Electrostatic Powder Line Investment | Zero-VOC compliance at OEM facilities bypasses GB 30981 liquid formulation burdens. |
| JIS K 5659 Certification Acceleration | 18-24 month qualification cycles create defensive moats against reformulated waterborne competitors. |
| Certified Applicator Network Partnership | Beijing and Shenzhen design-build contractors bundle warranties into state-owned tenders. |
| India Coastal Infrastructure Technical Partnership | Mumbai and Chennai port facilities seek corrosion-resistant warranties exceeding conventional systems. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with plant managers at Guangdong coating clusters, procurement leads at Japanese metal fabricators, technical R&D directors at Osaka resin synthesis facilities, and certified applicator network heads in Beijing and Shenzhen. Secondary validation drew from MEE regulatory filings, METI JIS standard documentation, customs trade data on fluorinated feedstock flows, and SEC disclosures from listed coating conglomerates. Bottom-up volume estimates from individual facility outputs were triangulated against top-down demand projections from construction tender databases.
Calibration against historical price realization data and certification timeline records anchored growth projections across the modeling period. Segmentation dimensions modeled include product type tier, form classification, end-use industry vertical, and regional regulatory cluster. CAGRs were derived from slope analysis of segment-specific volume trajectories. Key forecast inputs incorporated MEE enforcement intensity scenarios and JIS mandate expansion timelines for public building refurbishment.
The forecast holds incumbent behavior within observed patterns; aggressive capacity expansion by Chinese state-owned chemical enterprises or accelerated ECHA REACH restrictions on fluorinated precursors would shift outcomes. Material shifts in China's dual carbon policy implementation or METI durability mandate scope would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Conductive Polymer Coatings Market
Coatings
Coating Agents for Synthetic Leather Market
Coatings
Mexico Floor Coatings Market
Coatings
Yacht Coatings Market
Coatings
Glazes Market
Coatings
Rail Coatings Market
Coatings
Germany Automotive OEM Coatings Market
Coatings
North America Anti-Friction Coatings Market
Coatings
Global Solar Panel Coatings Market
Coatings
Waterproof Coating Market
Coatings
Dispersion Coating Market
Coatings
Hull Coatings Market
Coatings
Chemical Resistant Coatings Market
Coatings
North America Concrete Floor Coatings Market
Coatings
Automotive Conformal Coatings Market
Coatings
Hard Coating Market