
 2K Coatings Market | 2026-2036
2K Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
2K Coatings Market Outlook
High-performance polyurethane specifications are redrawing procurement standards across transportation and industrial end uses. PPG Industries leverages its automotive OEM relationships to sustain premium positioning in North American assembly plants. AkzoNobel anchors European marine demand through specialized corrosion-protection systems. Jotun differentiates via geographic dominance in Middle Eastern and Southeast Asian project markets.
Two-component coatings combine a base resin with a hardener that crosslinks upon mixing, delivering cured films with superior chemical resistance, hardness, and durability under aggressive thermal and mechanical loads. The formulation requires precise mix ratios, pot-life management, and controlled application conditions to achieve specified performance. Polyurethane and epoxy formulations command the deepest margin pools due to their critical role in automotive clearcoats and heavy-industrial corrosion protection. Water-based systems are gaining fastest among formulation categories as manufacturers reformulate to meet tightening VOC ceilings without sacrificing cure speed. Automotive application volumes lead in absolute terms, though aerospace specifications carry the highest per-liter value due to certification burdens and performance thresholds.
EPA VOC rules, REACH registration requirements, and China's MEE emission standards collectively determine which chemistries remain commercially viable in each major production jurisdiction. Compliance costs favor suppliers with captive resin synthesis and in-house toxicology testing capabilities rather than formulation-only operations. Stakeholders must monitor regulatory divergence between jurisdictions, as diverging hazard classifications threaten to fragment product portfolios and complicate scale economics.
Market Dynamics
VOC compliance deadlines across Germany, Japan, and the United States are forcing simultaneous solvent-to-water conversions while polyurethane specifications harden in automotive clearcoat contracts. This regulatory-technical squeeze is compressing formulation flexibility and rewarding captive resin capabilities.
Growth Catalysts
- REACH registration thresholds:Tier-1 suppliers with pre-registered dossiers capture reformulation contracts from smaller competitors lacking ECHA-compliant toxicology data. German OEMs now mandate REACH-compliant base coats in supplier scorecards.
- Automotive lightweighting:Carbon-fiber reinforced plastics in electric vehicle body panels require specialized 2K polyurethane adhesion promoters. Japanese battery-electric platforms specify these systems for structural bonding durability.
- China's industrial coastal corridor:Manufacturing clusters in Jiangsu and Guangdong provinces concentrate demand for high-solids epoxy tank linings. MEE emission enforcement accelerates specification upgrades in petrochemical storage facilities.
Market Restraints
- Isocyanate feedstock volatility:MDI and TDI pricing swings tied to benzene derivatives compress margin visibility for polyurethane formulators. European suppliers face additional ETS carbon cost pass-through.
- South Korean monomer concentration:Three producers control majority regional supply of aliphatic isocyanates for automotive refinish. Any unplanned outage cascades through Asian coating supply chains within weeks.
- Epoxy-amine pot-life limitations:Two-hour working windows restrict application scale in marine and infrastructure projects. Contractors in humid subtropical climates face accelerated viscosity rise and waste.
Strategic Opportunities
- India's PLI-linked auto component expansion:Domestic electric vehicle manufacturing under the Production Linked Incentive scheme creates demand for localized 2K coating capacity. BIS certification requirements favor early entrants with testing infrastructure.
- UV-curable waterborne hybrids:Convergence of ultraviolet initiation with low-VOC water carriers enables single-pass automotive refinish with near-zero flash-off time. Repair shops in Japanese urban centers pilot these systems for throughput gains.
- Industrial IoT-enabled coating monitoring:Embedded pot-life sensors and automated mix-ratio verification reduce application defects in aerospace MRO facilities. Channel partners in Germany bundle hardware with coating supply contracts.
Industry Challenges
- Formulation chemist scarcity:Crosslinking kinetics expertise for polyurethane-epoxy hybrids commands premium compensation. German technical universities report insufficient polymer science enrollment to replace retiring specialists.
- AS9100D certification timelines:Aerospace coating approvals require 18-24 month qualification cycles with airframe OEMs. Smaller suppliers lack capital to sustain R&D through extended validation without revenue.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | 2K Coatings Market |
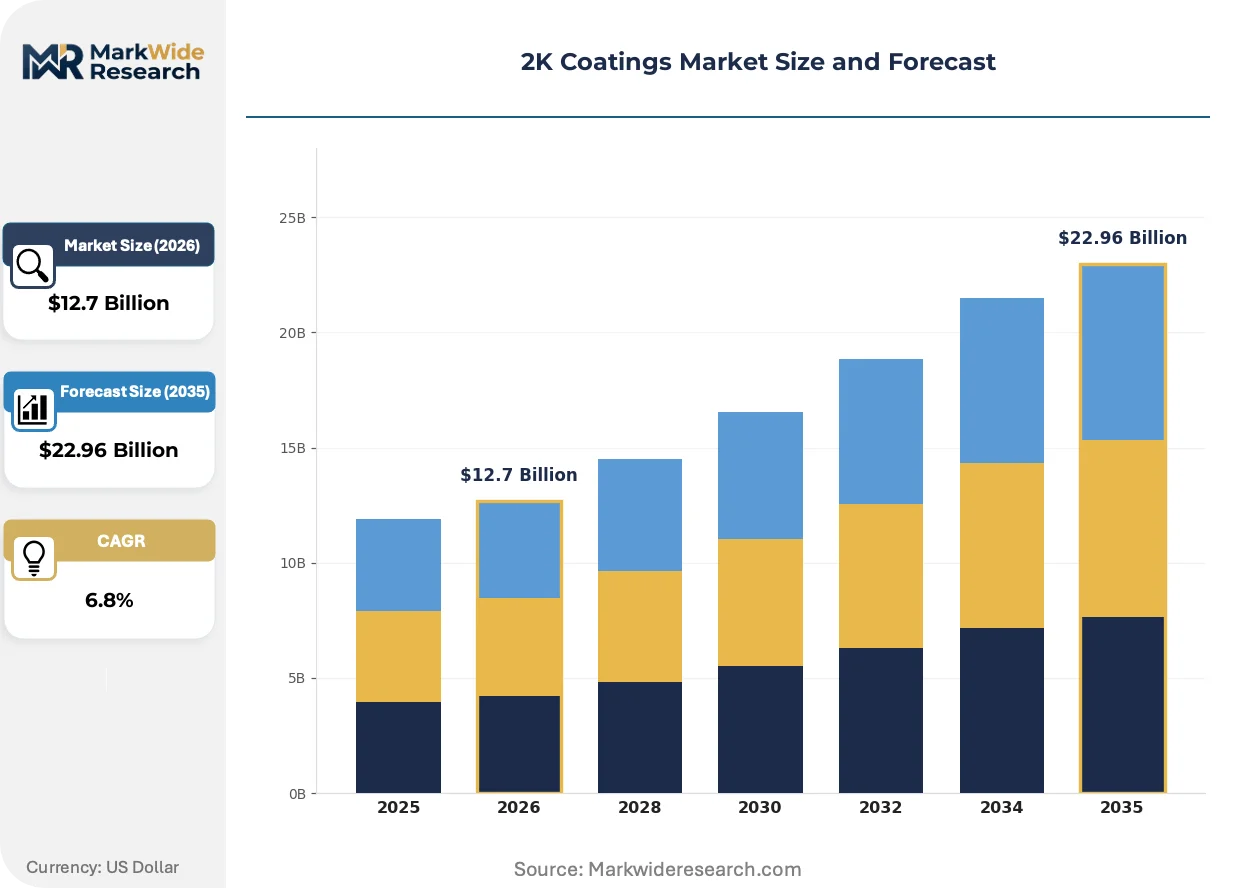
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $22.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Acrylic, Polyurethane, Epoxy, Polyester Application: Automotive, Marine, Aerospace, Industrial End User: OEMs, Aftermarket Providers, Manufacturers, Contractors Formulation: Water-Based, Solvent-Based, High Solids, Powder |
| Companies Covered | AkzoNobel N.V., PPG Industries, Inc., The Sherwin-Williams Company, Jotun A/S, Hempel A/S, BASF SE, Axalta Coating Systems, RPM International Inc., Sika AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
2K Coatings Market Strategic Shifts
Waterborne polyurethane technology is fragmenting application methodologies across automotive and industrial segments. Three distinct vectors are reshaping competitive requirements: chemistry evolution, regulatory harmonization pressure, and buyer consolidation in specification authority.
Polyaspartic aliphatic polyurea is fragmenting floor coating and infrastructure maintenance schedules. These rapid-cure systems achieve full chemical resistance within hours versus days for conventional epoxies. Facility maintenance managers in US manufacturing plants are specifying polyaspartic topcoats to compress downtime windows. The technology is fragmenting traditional epoxy-polyurethane layering protocols into single-coat specifications.
EPA VOC rules and China's MEE standards are diverging on allowable solvent content thresholds, complicating unified product portfolios. US automotive refinish regulations now permit higher exempt solvent volumes than Shanghai enforcement zones. Formulators serving multinational OEMs must maintain parallel SKUs or sacrifice margin on lowest-common-denominator waterborne systems. Marine coating specifications for China-flagged vessels face stricter GB standard compliance than comparable EU-registered tonnage.
Consolidated fleet operators are centralizing coating procurement through approved vendor lists with technical audit requirements. Large US commercial vehicle leasing companies now mandate supplier factory audits and batch traceability. Independent body shops lose direct purchasing autonomy as regional distributor networks capture specification influence. This concentration is most visible in German automotive refinish, where multi-shop chains negotiate system-wide supply agreements with single-source coating houses.
2K Coatings Market Segmentation
2K coatings demand fragments across distinct technical specifications and procurement channels. Each segment category channels through different sales architectures—direct OEM supply, distributor networks, or project-based contracting—shaping margin capture and formulation requirements.
Product Type:
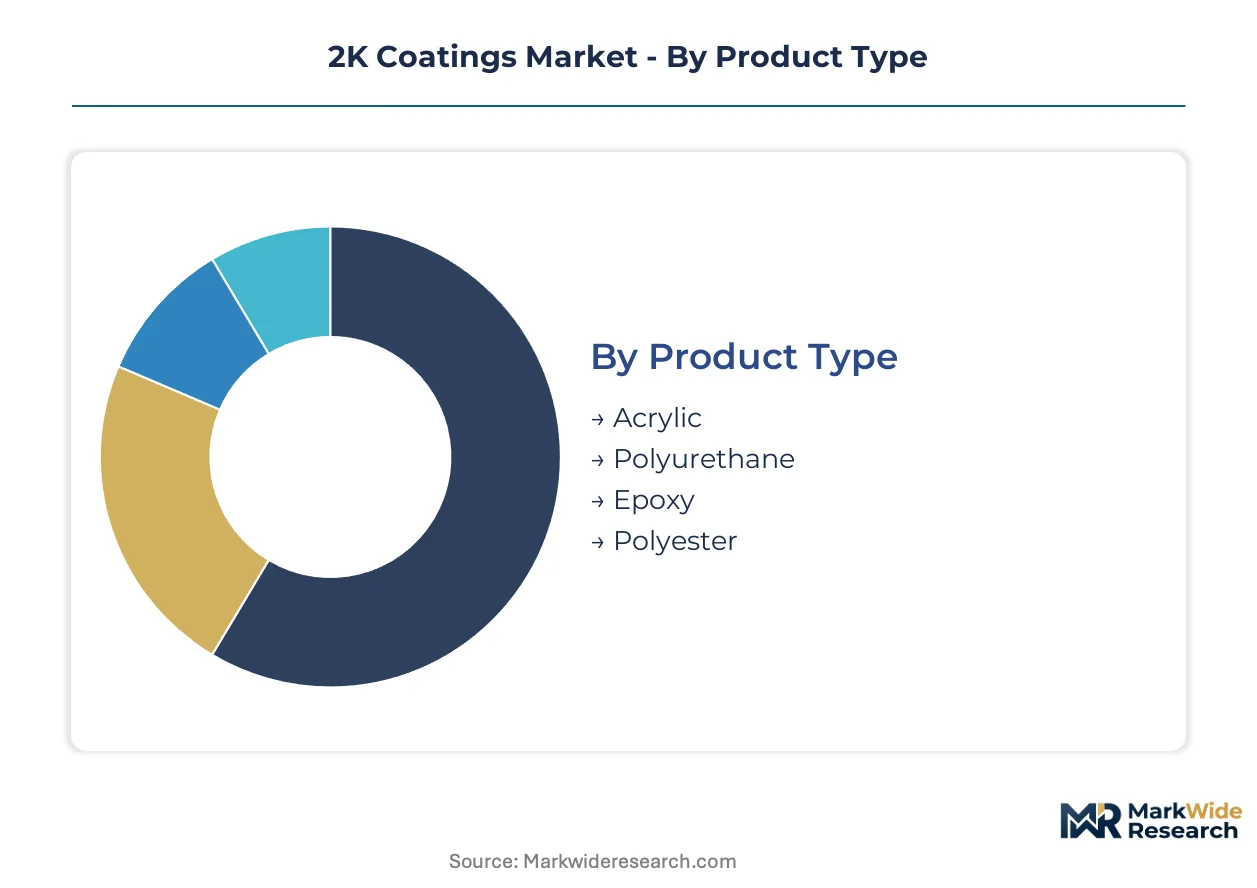
Channel mix varies sharply by chemistry: polyurethane and epoxy flow predominantly through direct OEM and industrial supply agreements, while acrylic and polyester reach markets via broader distributor and refinish channels.
- Polyurethane:Aliphatic and aromatic isocyanate crosslinkers deliver exceptional UV stability and abrasion resistance for automotive clearcoats. German and Japanese OEMs specify these systems for electric vehicle structural panels requiring adhesion to carbon-fiber reinforced plastics. REACH registration burdens favor suppliers with captive isocyanate production.
- Epoxy:Amine-cured systems provide chemical resistance for tank linings and marine protective coatings. Demand concentrates in China's Jiangsu and Guangdong petrochemical corridors where MEE emission enforcement accelerates high-solids upgrades. Two-hour pot-life constraints limit contractor scale in humid subtropical applications.
- Acrylic:Thermosetting acrylic-urethane hybrids serve automotive refinish and industrial maintenance through distributor networks. Faster dry times appeal to high-throughput collision repair operations.
- Polyester:Saturated and unsaturated formulations target industrial equipment and infrastructure protective coatings. Lower raw material costs support economy-tier positioning in emerging market manufacturing.
Polyurethane dominates installed base value. Epoxy is where expansion concentrates in industrial corrosion protection.
Application:
Cost tier stratification separates specification-driven aerospace and automotive from price-sensitive industrial maintenance and marine project work.
- Automotive:OEM clearcoats and structural adhesives command premium pricing through direct supply relationships. Japanese battery-electric platforms specify 2K polyurethane for carbon-fiber bonding durability. EPA VOC rules and REACH compliance compress formulation flexibility for multinational suppliers.
- Aerospace:AS9100D-certified systems for commercial and defense airframes carry the highest per-liter value due to 18-24 month qualification cycles. German and US MRO facilities drive demand for embedded IoT monitoring of pot-life and mix ratios.
- Marine:Protective and antifouling coatings for commercial vessels face divergent regulatory pressures—China's GB standards enforce stricter limits than EU-registered tonnage. AkzoNobel anchors European demand through specialized corrosion-protection systems.
- Industrial:Manufacturing equipment, storage tanks, and infrastructure maintenance represent volume-driven procurement through regional distributors. Polyaspartic polyurea is displacing traditional epoxy-polyurethane layering for rapid-cure floor coatings in US manufacturing plants.
Automotive dominates installed base. Aerospace is where margin expansion concentrates.
End User:
Customer type determines contract structure—OEMs negotiate system-wide supply agreements while contractors purchase through distributor tiers.
- OEMs:German automotive manufacturers mandate REACH-compliant base coats in supplier scorecards, consolidating procurement through approved vendor lists with technical audit requirements. Direct supply relationships lock in formulation specifications for multi-year platform cycles.
- Aftermarket Providers:US commercial vehicle leasing companies and German multi-shop refinish chains capture specification influence from independent body shops. Regional distributor networks bundle coating supply with technical support and color-matching services.
- Manufacturers:Industrial equipment producers source through procurement consortia, prioritizing batch traceability and factory audit compliance over technical differentiation.
- Contractors:Marine and infrastructure project contractors face epoxy-amine pot-life limitations that restrict application scale. Humid subtropical climates accelerate viscosity rise, driving waste and labor cost pressure.
OEMs dominate installed base. Aftermarket Providers is where channel consolidation concentrates.
Formulation:
Maturity curves separate established solvent-based systems from rapidly reformulating waterborne and high-solids alternatives.
- Water-Based:Polyurethane dispersions and epoxy emulsions gain fastest among categories as manufacturers reformulate for tightening VOC ceilings without sacrificing cure speed. Japanese urban repair shops pilot UV-curable waterborne hybrids for near-zero flash-off time.
- Solvent-Based:Conventional systems retain share in automotive refinish where US regulations permit higher exempt solvent volumes than Shanghai enforcement zones. Formulators maintain parallel SKUs or sacrifice margin on lowest-common-denominator alternatives.
- High Solids:Reduced solvent content epoxies and polyurethanes satisfy MEE emission standards in China's industrial coastal corridor. Petrochemical storage facilities in Jiangsu and Guangdong drive specification upgrades.
- Powder:Thermosetting 2K powder coatings serve industrial equipment and architectural applications through electrostatic application. Limited heat-sensitive substrate compatibility constrains automotive penetration.
Solvent-Based dominates installed base. Water-Based is where regulatory-driven replacement concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Isocyanate feedstock production clusters in Germany, South Korea, and the United States determine formulation cost structures across major demand centers. Regulatory divergence between EPA, REACH, and MEE frameworks forces parallel product SKUs rather than unified portfolios. Each geography presents distinct specification pressures and procurement consolidation patterns.
United States
Commercial vehicle fleet operators centralize coating procurement through approved vendor lists with factory audit mandates. EPA VOC rules permit higher exempt solvent volumes than Asian enforcement zones, preserving solvent-based refinish share. Gulf Coast petrochemical corridors supply MDI feedstock to polyurethane formulators serving automotive OEM assembly plants.
Germany
Automotive OEMs mandate REACH-compliant base coats in supplier scorecards, consolidating direct supply relationships. ECHA registration thresholds capture reformulation contracts from smaller competitors lacking toxicology dossiers. Bavarian technical universities face polymer science enrollment shortfalls as formulation chemists retire.
China
Manufacturing clusters in Jiangsu and Guangdong provinces concentrate demand for high-solids epoxy tank linings. MEE emission enforcement accelerates specification upgrades in petrochemical storage facilities. GB standards for China-flagged vessels enforce stricter limits than comparable EU-registered tonnage.
Japan
Battery-electric platforms specify 2K polyurethane adhesion promoters for carbon-fiber reinforced plastic body panels. METI industrial standards shape qualification requirements for automotive clearcoat suppliers. Urban repair shops pilot UV-curable waterborne hybrids for near-zero flash-off throughput gains.
India
Production Linked Incentive scheme subsidies for domestic electric vehicle manufacturing create demand for localized 2K coating capacity. BIS certification requirements favor early entrants with testing infrastructure. Maharashtra and Gujarat industrial corridors attract formulation investments from multinational suppliers.
2K Coatings Market Competitive Environment
Concentration sits with diversified chemical conglomerates and specialized coating houses that control captive resin synthesis. The vendor base separates into three tiers: integrated resin-to-coating manufacturers, formulation specialists with regional distribution depth, and project-based marine contractors. Scale advantages accrue to suppliers with in-house toxicology testing and multi-jurisdiction regulatory dossiers. Competitive dynamics center on REACH registration capture and automotive OEM direct supply lock-ins.
Within the integrated chemical tier, BASF SE and AkzoNobel N.V. exemplify archetypes with upstream isocyanate or resin capabilities that buffer feedstock volatility. PPG Industries, Inc. occupies a position among North American automotive OEM specialists with assembly plant direct supply relationships. Jotun A/S anchors the project-based marine and protective coating segment through geographic concentration in Middle Eastern and Southeast Asian markets. These three patterns—captive feedstock, OEM direct supply, and regional project dominance—define competitive positioning across formulation categories.
| Leading Market Players |
|---|
| AkzoNobel N.V. |
| PPG Industries, Inc. |
| The Sherwin-Williams Company |
| Jotun A/S |
| Hempel A/S |
| BASF SE |
| Axalta Coating Systems |
| RPM International Inc. |
| Sika AG |
| Others |
Value Chain & Pricing Dynamics
Sixty-to-ninety-day isocyanate inventory cycles in European polyurethane formulators compress margin visibility when benzene derivative feedstock costs spike, concentrating pricing power with BASF and Covestro where captive MDI production buffers volatility. REACH registration compliance costs and ETS carbon pass-throughs amplify tier separation between integrated resin manufacturers and formulation-only operators.
Pricing Analysis
EPA VOC rules and REACH registration thresholds dictate the pricing tier structure across automotive and industrial segments. Three-tier pricing stratifies across AS9100D-certified aerospace systems, REACH-compliant automotive OEM grades, and economy-tier industrial maintenance coatings. Price differentiation hinges on certification burden and captive resin synthesis. Cost compression in solvent-based refinish intensifies as waterborne reformulation sacrifices margin for compliance. Aftermarket collision repair shops exhibit highest price sensitivity; aerospace MRO facilities show lowest due to qualification lock-in.
Supply Chain Analysis
Forty-five-day epoxy resin lead times from South Korean and Chinese petrochemical hubs constrain just-in-time formulation for marine and infrastructure contractors. Isocyanate supply draws from German, South Korean, and US Gulf Coast production clusters. Raw material dependencies center on MDI, TDI, and specialty amine hardeners. Single-source vulnerability in aliphatic isocyanates for automotive refinish threatens Asian coating supply chains. Distribution runs through direct OEM supply agreements for polyurethane clearcoats and regional distributor networks for industrial maintenance grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as waterborne polyurethane penetration in automotive OEM clearcoats accelerates specification upgrades ahead of regulatory deadlines.
For Market Incumbents: Shield formulation margins by deepening captive isocyanate production in Germany and South Korea against feedstock volatility from benzene derivative swings. Lock in multi-year automotive OEM direct supply agreements before REACH registration thresholds consolidate procurement further. Prioritize AS9100D certification investment to capture aerospace MRO demand for IoT-enabled pot-life monitoring systems. For New Entrants and Emerging Players: Anchor in India's PLI-linked electric vehicle component corridor where BIS certification requirements favor early entrants with localized testing infrastructure. Target waterborne UV-curable hybrids for Japanese urban repair shops seeking near-zero flash-off throughput gains. Pursue project-based marine contracting in Middle Eastern and Southeast Asian markets where geographic specialization outweighs scale disadvantages. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because REACH dossier ownership and automotive OEM qualification cycles create durable moats against formulation-only competitors. Target acquisition archetypes include mid-cap specialists with captive resin synthesis and multi-jurisdiction toxicology testing capabilities. Watch for isocyanate feedstock price stabilization as inflection signal for margin expansion in polyurethane formulations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Isocyanate Synthesis | Captive MDI production buffers BASF and Covestro against benzene derivative volatility in European markets. |
| REACH Dossier Expansion | ECHA-compliant toxicology data captures reformulation contracts from smaller competitors lacking registration infrastructure. |
| UV-Curable Waterborne Hybrid Launch | Japanese urban repair shops pilot these systems for automotive refinish throughput gains under METI standards. |
| India PLI-Linked Capacity Buildout | Maharashtra and Gujarat industrial corridors attract formulation investments serving domestic electric vehicle manufacturing. |
| Industrial IoT Sensor Bundling | German channel partners embed pot-life monitoring hardware with coating supply contracts for aerospace MRO facilities. |
Study Parameters
Cross-validation between primary interviews with automotive OEM procurement directors, marine coating contractors, and industrial maintenance managers and secondary sources including customs trade data, ACC and Cefic industry reports, and SEC 10-K filings anchors the qualitative findings. Bottom-up triangulation across formulation chemists at technical universities and distributor network partners validates supply chain concentration patterns. Top-down reconciliation with petrochemical capacity databases ensures feedstock demand alignment.
Sensitivity analysis across benzene derivative price bands and regulatory compliance cost scenarios tests forecast robustness over the projection horizon. Segmentation modeling incorporates chemistry type, application end-use, formulation category, and regional regulatory cluster dimensions. CAGRs derive from volume-demand buildups by automotive platform, industrial project pipeline, and marine fleet specification trends. Forecast inputs include isocyanate production capacity utilization and MEE enforcement intensity in China's Jiangsu and Guangdong corridors.
Decision-makers should treat outputs as directional under sustained REACH registration thresholds and EPA VOC compliance timelines; material deviation in isocyanate feedstock availability or regulatory harmonization would warrant model refresh. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Water Based Enamel Market
Coatings
Global UV-Cured Coatings Market
Coatings
Egypt Automotive OEM Coatings Market
Coatings
Technical Coil Coatings Market
Coatings
Extrusion Coating Market
Coatings
Polysiloxane Coatings Market
Coatings
Transportation Coating Market
Coatings
Global Diamond Coatings Market
Coatings
Marine Coatings Market
Coatings
Global Low Friction Coatings Market
Coatings
Global Mirror Coatings Market
Coatings
Anti-Microbial Coatings Market
Coatings
Intumescent Fire Retardant Coating Market
Coatings
Marine Anti Fouling Coatings Market
Coatings
Cool Roof Coatings Market
Coatings
US Protective Coatings Market