
 Wood Adhesives and Binders Market | 2026-2036
Wood Adhesives and Binders Market Size, Share, and Industry Trends Forecast 2026-2036
Wood Adhesives and Binders Market Analysis
Mass timber construction is reorganizing demand patterns as commercial builders displace traditional residential renovators as the dominant buyer archetype. Henkel AG & Co. KGaA leverages its water-based polyurethane portfolio to anchor supply relationships with European glulam fabricators. H.B. Fuller Company sustains R&D intensity in hot-melt reactive systems for automated panel lines. Dow Inc. competes through backward integration into petrochemical feedstocks that stabilize epoxy resin costs.
Wood adhesives and binders comprise formulated polymer systems—typically urethane, phenolic, amino, or emulsion resins—engineered to bond lignocellulosic substrates under controlled temperature, pressure, and moisture conditions, with bond-line durability measured by ASTM D1183 cyclic boil protocols. Their primary purpose is to transfer structural loads across joint interfaces in engineered wood products while resisting hydrolytic degradation. PVA emulsions dominate furniture assembly due to their room-temperature cure and cost position, though phenol-formaldehyde retains margin pools in exterior-grade plywood where weather resistance commands specification premiums. Water-based technology leads volume across flooring and cabinet applications as solvent-based formulations face VOC restrictions, while reactive hot-melt systems represent the fastest-growing technology segment in automated mass timber production.
EPA TSCA Title VI formaldehyde standards and the EU REACH regulation constrain amino resin formulations, forcing reformulation investments and shifting specification authority toward certified low-emission systems. Germany's DIBt approval process and California Air Resources Board labeling requirements create divergent compliance pathways that fragment product portfolios. Stakeholders must monitor evolving building codes for tall mass timber structures and decide whether to absorb certification costs or cede specification control to third-party testing houses.
Market Dynamics
Mass timber construction is displacing light-frame residential applications as the dominant demand anchor, forcing adhesive formulators to engineer high-strength thermoset systems capable of meeting structural timber bond-line durability requirements under cyclic loading conditions.
Growth Catalysts
- EPA TSCA Title VI formaldehyde standards:The emission caps are accelerating reformulation investments toward certified low-emission amino resin systems. Panel manufacturers must achieve third-party certification to access specification-driven commercial construction channels.
- Cross-laminated timber (CLT) fabrication:European glulam producers are expanding production capacity for multi-story residential and commercial structures. Adhesive suppliers with DIBt-approved systems capture specification authority in engineered wood clusters.
- Water-based polyurethane chemistry:Advances in moisture-cure formulations enable room-temperature processing with exterior-grade durability. Flooring and cabinet manufacturers adopt these systems to eliminate solvent-based VOC compliance costs.
Market Restraints
- Petrochemical feedstock volatility:Epoxy and polyurethane resin costs fluctuate with propylene and benzene derivative pricing. Dow Inc. mitigates exposure through captive ethylene oxide production.
- Phenol supply concentration:Global phenol production clusters in the US Gulf Coast and Northeast Asia. Disruptions at integrated cumene-phenol complexes cascade into phenolic resin cost instability for exterior plywood manufacturers.
- Cure temperature limitations of PVA emulsions:Polyvinyl acetate adhesives fail at sustained temperatures above 60°C. This thermal ceiling excludes furniture assembly applications requiring heat resistance for kitchen and bathroom environments.
Strategic Opportunities
- Tall mass timber building codes:The International Building Code's Type IV-HT construction classification permits timber structures up to 18 stories. Code adoption across US states creates specification demand for structural adhesive systems with ASTM D7247 fire-performance ratings.
- Reactive hot-melt automation:Robotic dispensing systems for mass timber panel lines enable precise adhesive metering and reduced waste. Equipment suppliers and adhesive formulators are co-developing integrated production cells.
- EU Green Deal embodied carbon accounting:Lifecycle assessment requirements for construction materials favor bio-based binder formulations. Suppliers with EPD-verified low-carbon adhesives access green public procurement tenders in Germany and France.
Industry Challenges
- Adhesive formulation chemist scarcity:Specialized expertise in phenol-formaldehyde condensation kinetics and polyurethane prepolymer design concentrates at legacy European and North American firms. Emerging market producers struggle to replicate tacit knowledge in cure rheology control.
- Multi-jurisdiction certification timelines:Simultaneous pursuit of DIBt approval, CARB Phase 2 compliance, and EPA TSCA Title VI certification extends product launch cycles. Testing house backlogs delay market entry for reformulated low-emission systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wood Adhesives and Binders Market |
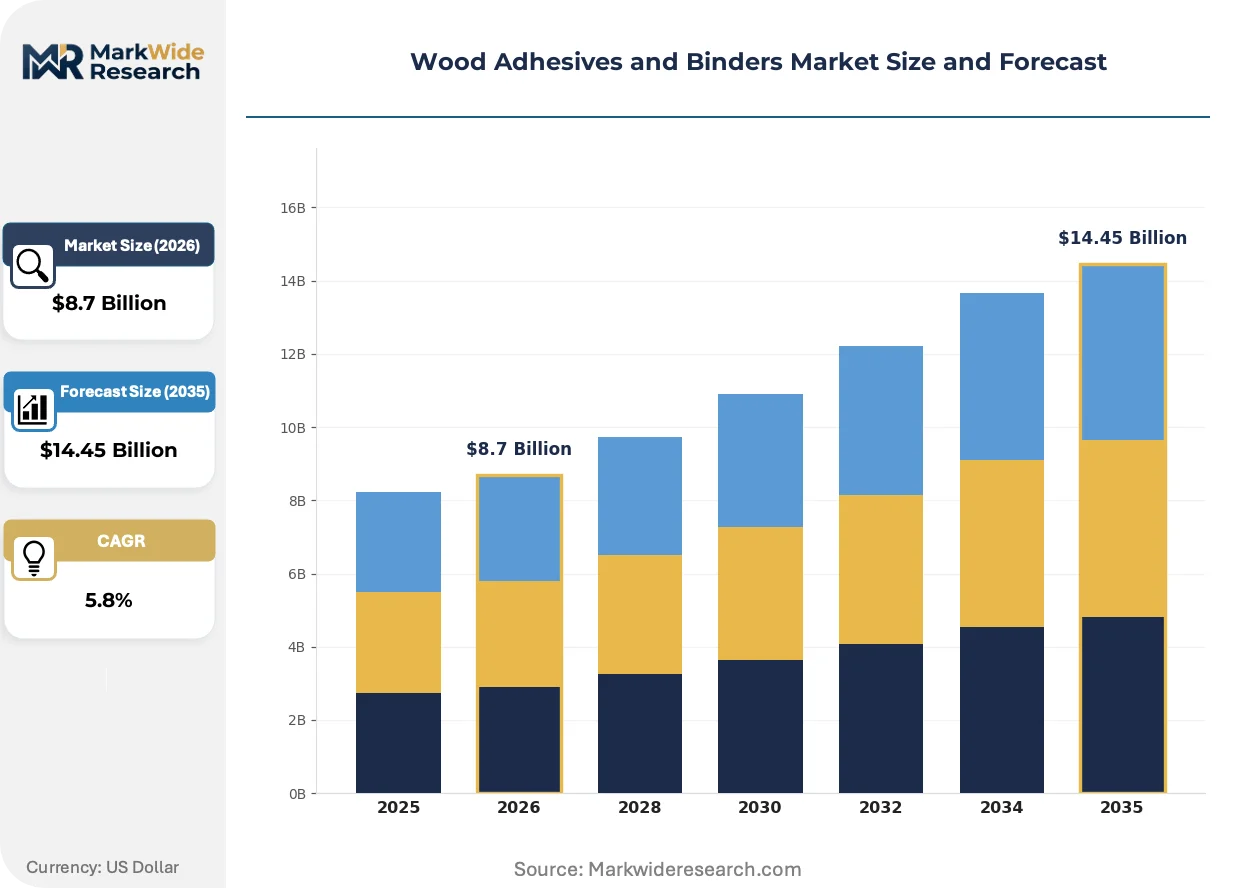
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $14.45 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: PVA, Urea-Formaldehyde, Phenol-Formaldehyde, Epoxy Application: Furniture, Cabinets, Flooring, Plywood End User: Construction, Furniture Manufacturing, Interior Design, Packaging Technology: Hot Melt, Water-Based, Solvent-Based, Reactive |
| Companies Covered | Henkel AG & Co. KGaA, H.B. Fuller Company, 3M Company, Ashland Inc., BASF SE, Huntsman Corporation, Dow Inc., Avery Dennison Corporation, Bostik, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wood Adhesives and Binders Market Emerging Trajectories
Formulation chemistry is pivoting toward reactive systems that cure under ambient moisture conditions, eliminating energy-intensive hot-press cycles while meeting structural performance thresholds for engineered wood products.
Hybrid polyurethane-polyurea prepolymer systems are decomposing the traditional separation between structural and non-structural adhesive categories. Mass timber fabricators in Austria and Canada adopt single-component moisture-cure formulations for both CLT face bonding and glulam finger jointing. This convergence compresses supplier qualification requirements and reduces inventory complexity for multi-product manufacturers.
REACH Annex XVII restrictions on formaldehyde-releasing substances are tightening permissible emission levels for amino resins used in particleboard and MDF production. The regulation forces European panel manufacturers toward phenol-formaldehyde and isocyanate-based alternatives despite higher raw material costs. Germany's engineered wood cluster around Baden-Württemberg exhibits the fastest reformulation velocity due to DIBt enforcement intensity.
Commercial builders are consolidating specification authority previously dispersed among residential contractors and furniture manufacturers. Mass timber general contractors in Seattle, Vancouver, and Oslo now mandate adhesive performance data packages including cyclic boil durability and creep resistance metrics. This concentration elevates technical service capabilities as a competitive discriminator among formulation suppliers.
Wood Adhesives and Binders Market Segmentation
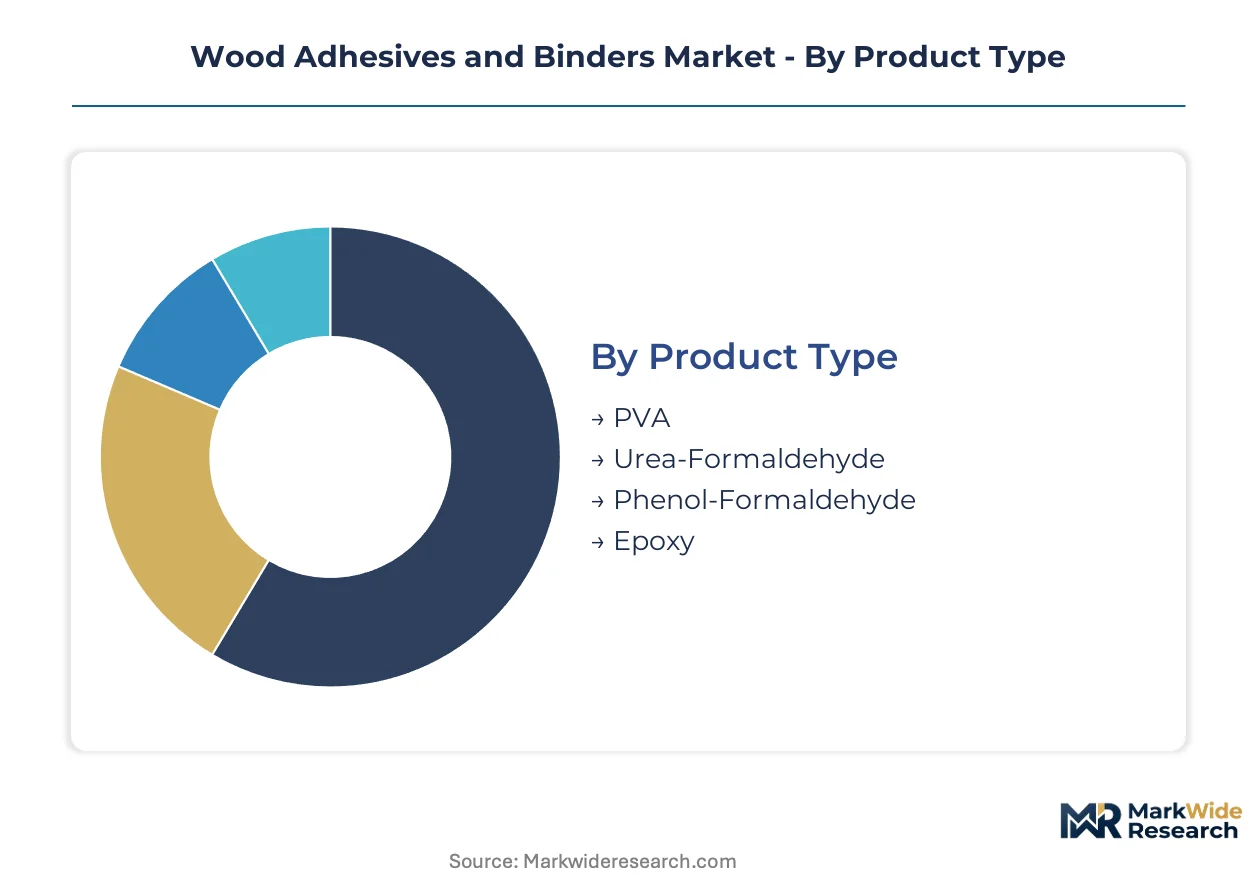
Adhesive selection in engineered wood markets hinges on cure chemistry, emission profiles, and automation compatibility. Segmentation reveals where specification authority concentrates and which chemistries face displacement pressure from regulatory tightening and manufacturing technology shifts.
Product Type:
Urea-formaldehyde and PVA emulsions face acute substitution pressure as EPA TSCA Title VI and REACH Annex XVII tighten emission caps and thermal performance thresholds.
- PVA:Polyvinyl acetate emulsions cure at ambient temperature through water evaporation, enabling rapid furniture assembly without heated presses. Demand concentrates in cabinet and millwork fabrication across North American residential construction, though the 60°C thermal ceiling excludes kitchen and bathroom applications requiring sustained heat resistance.
- Urea-Formaldehyde:Amino resin systems bond particleboard and MDF through acid-catalyzed condensation, offering cost-efficient interior-grade performance. German panel manufacturers in Baden-Württemberg are accelerating reformulation toward low-emission variants as DIBt enforcement intensifies and third-party certification becomes mandatory for commercial specification.
- Phenol-Formaldehyde:Thermosetting resins deliver exterior-grade durability through irreversible cross-linking chemistry, commanding specification premiums in marine and structural plywood applications despite higher raw material costs tied to phenol supply concentration.
- Epoxy:Two-component systems provide exceptional moisture resistance and gap-filling capability for specialty laminated beams and repair applications, though petrochemical feedstock volatility constrains cost competitiveness at volume.
PVA retains volume leadership in furniture assembly; phenol-formaldehyde holds the steepest expansion curve as mass timber specifications displace amino resin demand.
Application:
Cost tier stratification separates commodity interior applications from premium structural specifications requiring certified durability testing.
- Furniture:Assembly operations prioritize rapid handling strength and invisible glue lines, driving PVA and hot-melt adoption in residential and office furniture production across Vietnam and Poland manufacturing clusters.
- Cabinets:Moisture-cure polyurethane systems are displacing solvent-based contact cements as California Air Resources Board labeling requirements propagate through North American supply chains.
- Flooring:Water-based polyurethane adhesives dominate engineered wood plank installation, eliminating VOC compliance costs while meeting ASTM D3498 shear strength requirements for residential and commercial substrates.
- Plywood:Exterior-grade panels specify phenol-formaldehyde or melamine-urea hybrid systems for cyclic boil durability, with procurement concentrating among Southeast Asian veneer mills serving Japanese and Australian export markets.
Furniture commands absolute volume; flooring applications are climbing the fastest as renovation activity and moisture-cure formulation advances converge.
End User:
Customer type determines specification complexity, with mass timber general contractors demanding performance data packages that residential renovators rarely require.
- Construction:Commercial builders specify structural adhesives with ASTM D7247 fire-performance ratings and cyclic boil durability metrics, consolidating procurement authority previously dispersed among residential contractors.
- Furniture Manufacturing:Assembly plants prioritize room-temperature cure speed and sandability, maintaining PVA dominance despite thermal performance limitations in heat-exposed environments.
- Interior Design:Custom millwork and architectural woodwork demand aesthetic-grade bonding with minimal squeeze-out, favoring low-viscosity water-based systems for visible joint applications.
- Packaging:Corrugated pallet and crate manufacturers utilize cost-optimized starch and dextrin adhesives for non-structural applications with minimal durability requirements.
Construction anchors revenue concentration; furniture manufacturing maintains the broadest installed base across geographic markets.
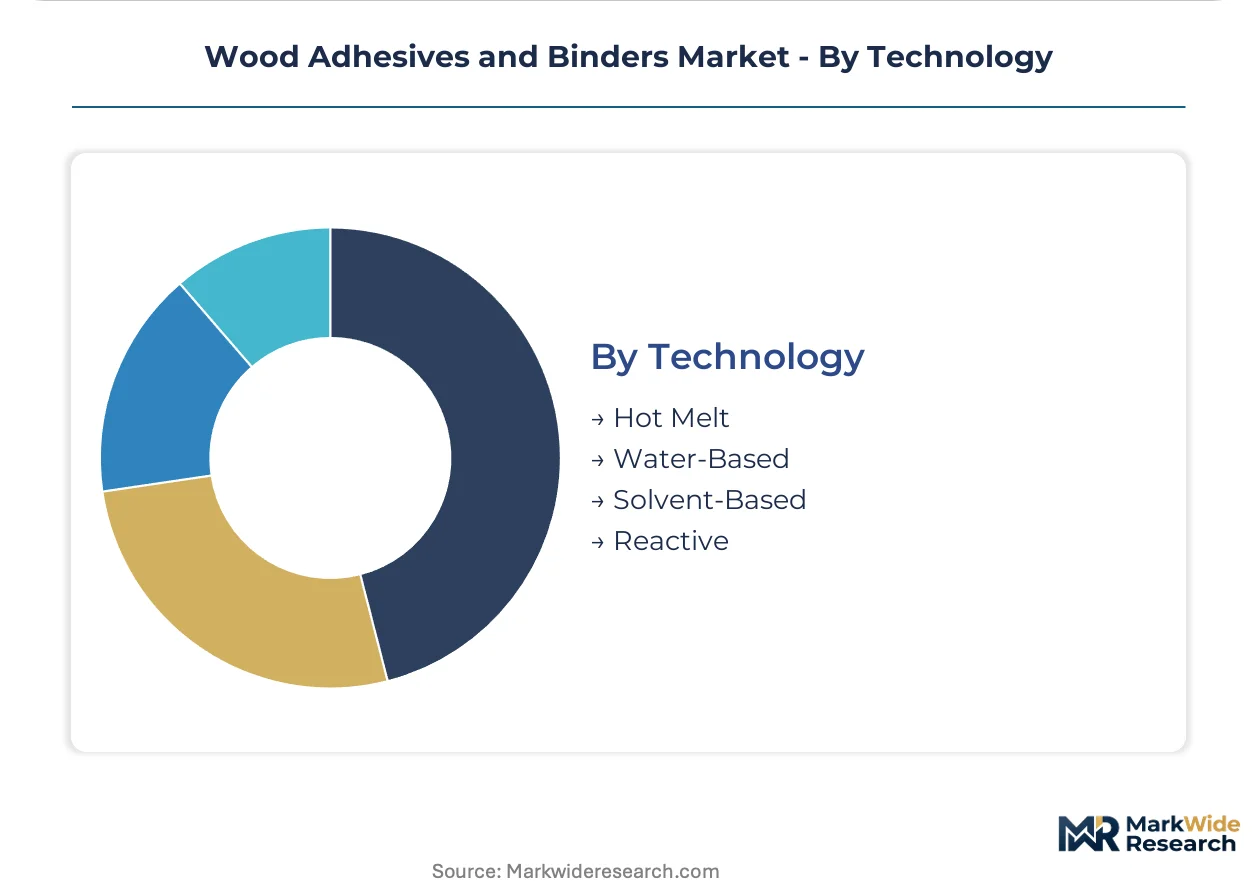
Technology:
Manufacturing automation intensity separates segments, with robotic mass timber lines demanding precise metering and rapid green-strength development.
- Hot Melt:Reactive polyurethane hot-melts cure through ambient moisture exposure, enabling automated dispensing in CLT and glulam production lines without heated press cycles.
- Water-Based:Emulsion systems eliminate solvent VOC compliance burdens, dominating flooring and cabinet applications where room-temperature processing and cleanup convenience outweigh cure speed limitations.
- Solvent-Based:Contact cements and neoprene systems face regulatory phase-out across European and North American jurisdictions, retreating to specialty applications where substrate compatibility constraints persist.
- Reactive:Two-component epoxy and polyurethane systems deliver structural performance thresholds for engineered wood products, requiring precise mix ratio control that automated metering equipment enables at production scale.
Water-based technology maintains volume leadership; reactive systems are gaining share fastest as mass timber automation penetrates European and North American fabrication facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German adhesive formulators export moisture-cure polyurethane systems to Canadian mass timber fabricators, establishing a transatlantic trade corridor anchored by DIBt certification authority and North American code adoption.
United States
Seattle and Portland mass timber contractors consolidate specification authority for structural adhesives with ASTM D7247 fire-performance ratings. EPA TSCA Title VI formaldehyde emission caps force California and Pacific Northwest panel manufacturers toward third-party certification. Production clusters in Oregon and Washington state supply cross-laminated timber to commercial builders across the western states.
Germany
Baden-Württemberg's engineered wood cluster drives the fastest reformulation velocity toward low-emission amino resin systems. DIBt approval requirements exceed baseline EU REACH Annex XVII standards, creating a compliance moat for domestic adhesive suppliers. Stuttgart-area glulam fabricators expand capacity for multi-story residential structures across German-speaking Europe.
Canada
Vancouver mass timber general contractors mandate adhesive performance data packages including cyclic boil durability metrics. British Columbia building code amendments permit timber structures up to 12 stories, stimulating demand for structural thermoset systems. Quebec's engineered wood sector supplies CLT panels to US Northeast commercial construction markets.
China
Guangdong and Jiangsu province plywood mills consume phenol-formaldehyde resins for exterior-grade veneer production serving Japanese and Australian export markets. The country's national environmental regulator enforces stricter VOC emission standards for wood panel manufacturing. Zhejiang furniture manufacturing clusters maintain PVA emulsion demand for cabinet and millwork assembly.
Japan
Osaka and Nagoya metropolitan area construction firms specify JIS-compliant structural adhesives for seismic-resistant engineered wood systems. METI building energy codes favor mass timber for mid-rise commercial structures in dense urban zones. Hokkaido timber processors supply laminated beams to domestic and South Korean infrastructure projects.
Wood Adhesives and Binders Market Vendor Landscape
Player mix skews toward diversified chemical conglomerates with captive resin production and specialized adhesive formulators serving engineered wood niches. Market structure exhibits tiered concentration, with top-tier suppliers controlling structural certification pathways and mid-tier players competing on furniture and interior applications. Three archetypes dominate: petrochemical-integrated resin producers, European formulation specialists with DIBt authority, and Asian cost-optimized emulsion suppliers. Capacity expansion and technology licensing represent the primary competitive vectors as automation penetrates mass timber fabrication.
Among European formulation specialists, Henkel AG & Co. KGaA and H.B. Fuller Company exemplify the certification-driven tier, occupying positions anchored by regulatory approval depth and technical service infrastructure. Dow Inc. represents the petrochemical-integrated archetype with upstream control over epoxy and polyurethane feedstock costs. These three entities illustrate how competitive positioning stratifies across structural versus non-structural application domains.
| Leading Market Players |
|---|
| Henkel AG & Co. KGaA |
| H.B. Fuller Company |
| 3M Company |
| Ashland Inc. |
| BASF SE |
| Huntsman Corporation |
| Dow Inc. |
| Avery Dennison Corporation |
| Bostik |
| Others |
Supply Flow & Price Mechanics
Long-term offtake agreements between phenol-formaldehyde resin suppliers and Southeast Asian plywood mills lock in feedstock access and price visibility eighteen to twenty-four months forward, insulating integrated producers from benzene derivative volatility while exposing non-integrated formulators to spot market swings.
Pricing Analysis
The technology-generation pricing gap between solvent-based legacy systems and water-based reactive formulations has compressed as EPA TSCA Title VI compliance costs equalize procurement economics. Three-tier pricing structure across premium structural certification, standard industrial grade, and economy furniture assembly tiers dominates transaction structures, with DIBt-approved systems commanding fifteen to twenty percent premiums over baseline REACH-compliant alternatives. Cost compression in amino resin segments is intensifying because European panel manufacturers absorb reformulation investments without passing through to buyers. Furniture manufacturers exhibit highest price sensitivity due to thin assembly margins, while mass timber general contractors prioritize performance data packages over per-kilogram unit costs.
Supply Chain Analysis
Inventory cycles for phenol and methanol feedstocks extend to eight weeks at European formulators, creating lead-time vulnerability when Gulf Coast petrochemical complexes experience unplanned outages. Supply concentrates in the United States, Germany, and China, with phenol production anchored in Texas and Louisiana integrated cumene complexes, polyurethane prepolymer synthesis clustering in Baden-Württemberg, and Guangdong province hosting emulsion resin capacity for Asian furniture manufacturing. Raw material dependencies on benzene derivatives, formaldehyde, and isocyanate systems expose formulators to commodity price volatility and regulatory restriction cascades. Single-source vulnerability concentrates in phenol supply, where three Gulf Coast producers serve North American structural plywood demand. Distribution runs through direct technical service relationships for mass timber accounts and chemical distributor networks for furniture and cabinet segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Mass timber construction represents a high-growth disruption as the International Building Code's Type IV-HT classification redefines structural adhesive performance requirements, with regulatory adoption across US states creating specification velocity that outpaces traditional furniture and residential renovation demand cycles.
For Market Incumbents: Compound certification depth in structural thermoset systems to defend margin pools against emerging polyurethane specialists, prioritizing DIBt and EPA TSCA Title VI approval maintenance as the priority lever while expanding captive phenol-formaldehyde resin capacity in Texas and Louisiana to mitigate feedstock cost volatility from Gulf Coast supply concentration. For New Entrants and Emerging Players: CARB Phase 2 fast-track certification offers entry pathway into California mass timber specification chains, with white-space concentration in moisture-cure polyurethane systems for automated CLT production lines serving Pacific Northwest commercial builders and Vancouver general contractors demanding cyclic boil durability data packages. For Investors and Strategic Acquirers: Capital is best deployed toward European formulation specialists with DIBt authority and established technical service infrastructure serving Baden-Württemberg glulam fabricators, as long-term viability across the analysis window hinges on regulatory approval depth rather than volume scale alone. The signal to watch is adoption velocity of Type IV-HT building codes across US state legislatures.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Phenol Resin Production | Gulf Coast captive supply secures feedstock cost stability against benzene derivative volatility. |
| DIBt Certification Fast-Track Investment | German approval authority unlocks specification access across European mass timber clusters. |
| Reactive Hot-Melt Automation Partnership | Robotic dispensing integration with CLT panel lines reduces adhesive waste and labor intensity. |
| Low-Emission Amino Resin Reformulation | REACH Annex XVII compliance maintains particleboard market access against phenolic substitution. |
| Technical Service Infrastructure Expansion | Seattle and Vancouver presence captures mass timber contractor specification authority consolidation. |
Methodological Framework
Operator-level perspectives from adhesive formulation chemists, mass timber production engineers, panel manufacturing procurement leads, and DIBt certification auditors anchored the qualitative base, cross-referenced with secondary validation from EPA TSCA Title VI compliance databases, EU REACH Annex XVII substance restriction filings, customs trade data for phenol-formaldehyde resin flows, and SEC 10-K disclosures from petrochemical-integrated suppliers. Bottom-up volume estimates from individual production facilities and top-down demand modeling from construction activity indices were triangulated to reconcile segmentation outputs.
Sensitivity analysis across feedstock cost scenarios, regulatory adoption timelines, and automation penetration rates tested forecast robustness across the projection horizon. Segmentation dimensions modeled include adhesive chemistry type, cure technology platform, application durability grade, end-user specification complexity, and regional regulatory cluster. CAGRs were derived from slope-intercept fitting of annual volume estimates against construction output indices and engineered wood product capacity expansion schedules, with phenol pricing volatility and mass timber building code adoption velocity as primary forecast inputs.
The analysis sits within stated boundaries; outcomes outside sustained Type IV-HT code adoption, stable phenol supply from Gulf Coast complexes, or continued DIBt enforcement intensity would require recalibration. Forecasts reflect documented assumptions about regulatory trajectory and feedstock cost structures. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Adhesives & Sealants
South America Construction Adhesives Market
Adhesives & Sealants
Asia-Pacific Contact Adhesives Market
Adhesives & Sealants
North America Human Fibrin Glue Market
Adhesives & Sealants
Middle East and Africa Human Fibrin Glue Market
Adhesives & Sealants
Rubber-Based Adhesives Market
Adhesives & Sealants
Global Emulsion Adhesives Market
Adhesives & Sealants
Anaerobic Adhesives and Sealants Market
Adhesives & Sealants
Europe Hot-Melt Adhesives Market
Adhesives & Sealants
Melamine Formaldehyde (MF) Market
Adhesives & Sealants
Global Adhesion Barrier Market
Adhesives & Sealants
Adhesives and Sealants for Handheld Devices Market
Adhesives & Sealants
Middle East and Africa Adhesives Market
Adhesives & Sealants
North America Reactive Adhesives Market
Adhesives & Sealants
Carpet Adhesive Market
Adhesives & Sealants
Global Electrically Conductive Adhesives Market
Adhesives & Sealants
Roofing Adhesive Market